
 Drug Free Depression Treatment Market | 2026-2036
Drug Free Depression Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Free Depression Treatment Market Foresight
Multi-source procurement of neuromodulation hardware is decoupling from single-vendor hospital contracts. NeuroStar Advanced Therapy leverages its installed base of TMS systems to sustain recurring revenue from maintenance protocols. Brainsway Ltd. differentiates through deep TMS coil designs that occupy specialized niches in obsessive-compulsive and addiction comorbidities.
Drug free depression treatment encompasses non-pharmacological interventions including transcranial magnetic stimulation, electroconvulsive therapy alternatives, behavioral conditioning protocols, and micronutrient supplementation regimens administered through clinical or digital channels. Therapeutic devices command premium positioning due to capital intensity and regulatory clearance requirements, while mobile apps within the delivery mode segment attract venture funding despite unresolved reimbursement pathways. Behavioral therapy retains structural dominance in volume terms, though cognitive therapy demonstrates faster uptake among employer-sponsored mental health programs seeking measurable return-on-investment metrics.
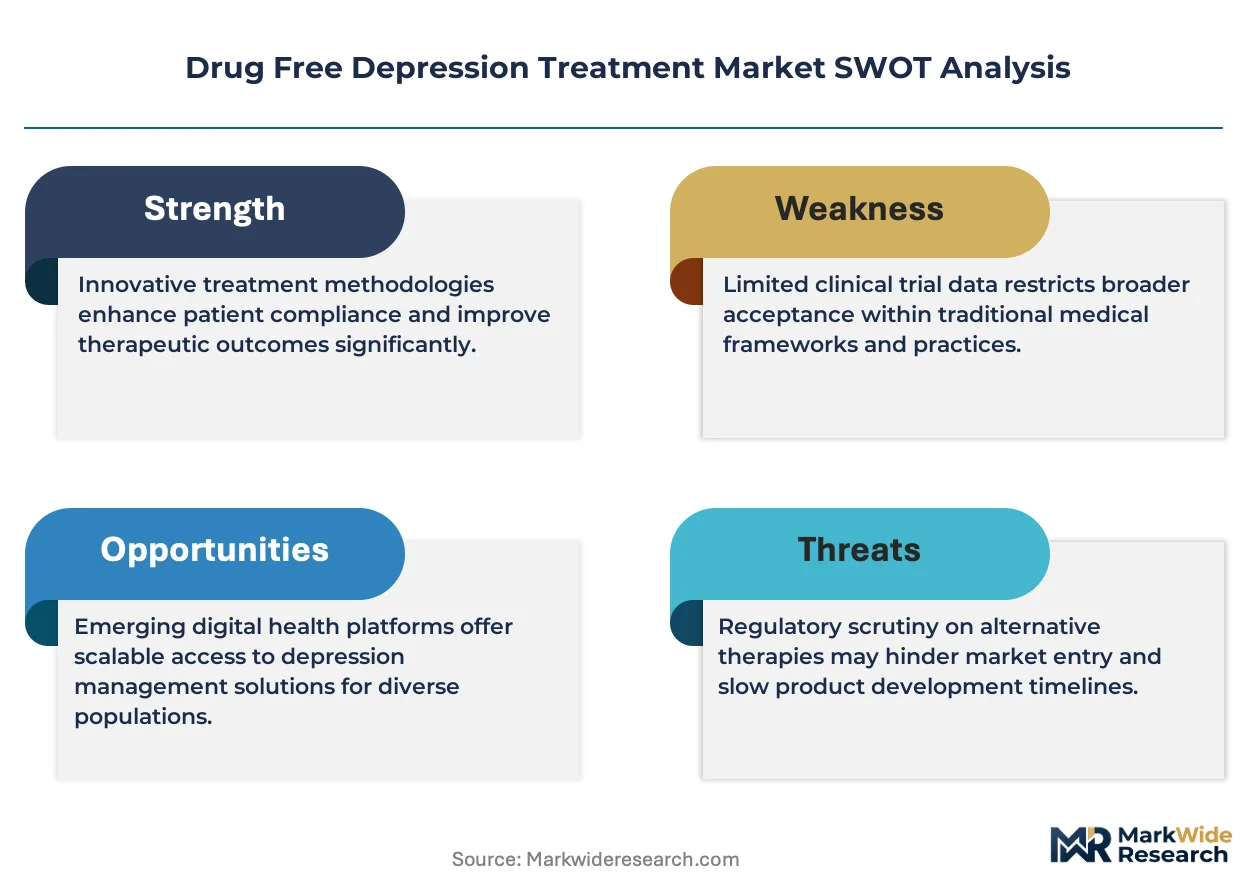
FDA breakthrough device designations and HIPAA compliance frameworks shape product development timelines and channel economics for device manufacturers and digital health platforms. The Centers for Medicare & Medicaid Services national coverage determinations for repetitive TMS directly influence provider adoption thresholds and capital expenditure decisions. Stakeholders must monitor evolving FDA guidance for software-as-a-medical-device classifications that could recategorize certain digital therapeutic offerings and trigger new clinical evidence requirements.
Market Dynamics
Reimbursement maturation for transcranial magnetic stimulation is restructuring provider economics, shifting capital deployment from hospital-centric installations toward ambulatory clinic networks and specialized mental health facilities.
Growth Catalysts
- FDA Breakthrough Device Pathway:Expedited market access for neuromodulation systems compresses commercialization timelines from 36 months to 18 months for qualifying depression interventions.
- Employer Mental Health ROI Mandates:Large self-insured employers in the United States now require measurable outcome metrics for behavioral health vendor selection, accelerating cognitive therapy platform procurement.
- Deep Coil Engineering:Specialized TMS coil architectures targeting obsessive-compulsive and addiction comorbidities expand addressable patient populations beyond major depressive disorder monotherapy.
Market Restraints
- Capital Intensity Thresholds:TMS system acquisition costs exceeding $75,000 per unit restrict independent psychiatric practice participation to hospital-affiliated networks with equipment leasing infrastructure.
- Single-Vendor Service Lock-In:Proprietary maintenance protocols and coil calibration requirements tether providers to original equipment manufacturers, limiting competitive hardware substitution.
- Digital Therapeutic Reimbursement Gaps:CMS national coverage determinations exclude most software-as-a-medical-device depression interventions from fee-for-service billing codes.
Strategic Opportunities
- Software-as-a-Medical-Device Reclassification:Pending FDA guidance on digital therapeutic evidence standards creates first-mover advantage for platforms with existing randomized controlled trial portfolios.
- Behavioral-Digital Convergence:Integration of synchronous telehealth coaching with asynchronous cognitive behavioral therapy modules addresses workforce shortage constraints in rural United States markets.
- HIPAA-Compliant Cloud Infrastructure:Federated data architectures enabling multi-site clinical trial recruitment while preserving patient privacy controls unlock pharmaceutical partnership revenue streams.
Industry Challenges
- Psychiatric Device Specialist Scarcity:Fellowship-trained interventional psychiatrists capable of TMS protocol optimization remain concentrated in academic medical centers, constraining scalable provider network expansion.
- Legacy EHR Integration Friction:Proprietary data formats from established neuromodulation systems require custom API development for seamless electronic health record connectivity, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Free Depression Treatment Market |
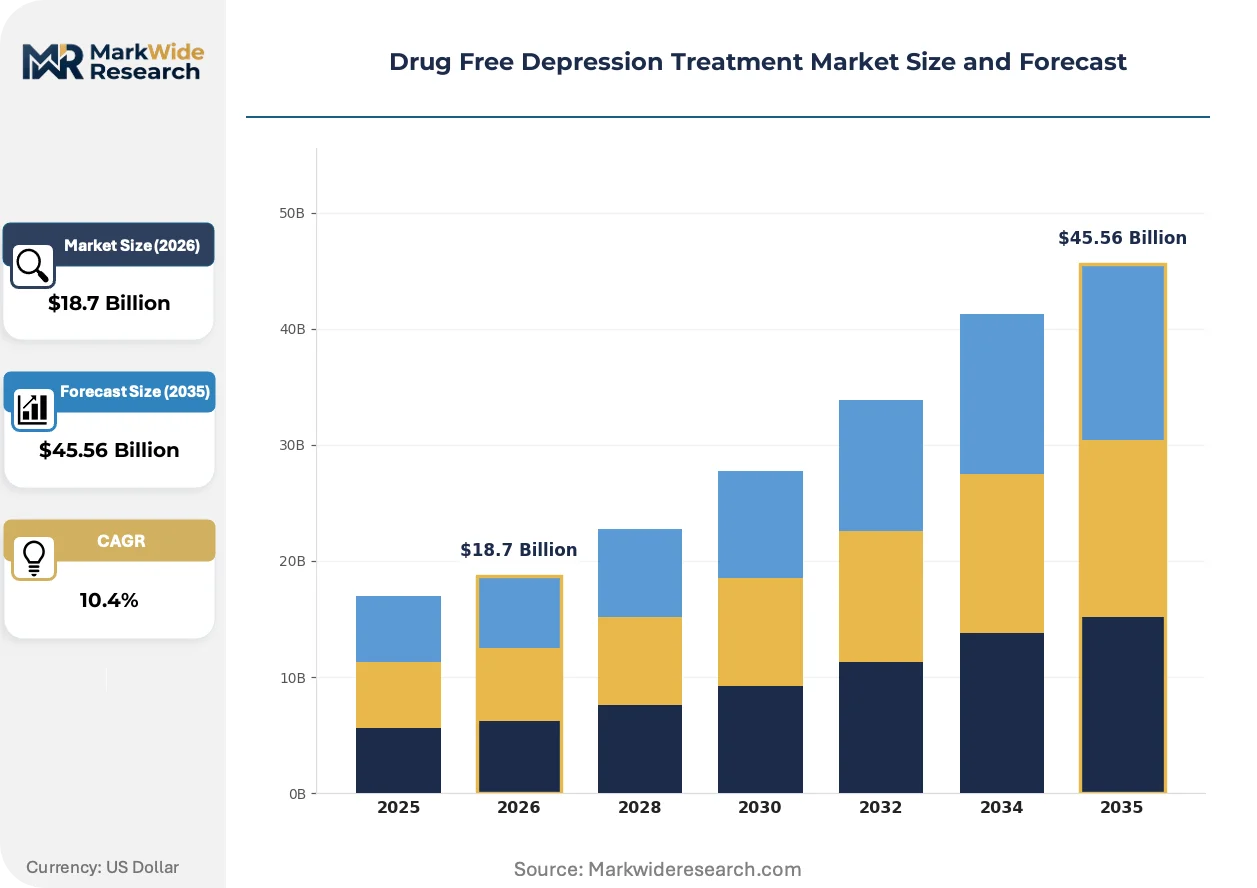
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $45.56 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutic Devices, Behavioral Therapy, Cognitive Therapy, Nutritional Approaches Delivery Mode: Online Therapy, In-Person Sessions, Mobile Apps, Workshops End User: Individuals, Healthcare Providers, Wellness Centers, Employers Solution: Self-Help Programs, Group Support, Consulting Services, Coaching |
| Companies Covered | NeuroStar Advanced Therapy, Magstim Company Limited, TMS NeuroHealth Centers, Inc., Brainsway Ltd., Fisher Wallace Laboratories, Psious, Cleveland Clinic, Mayo Clinic, McLean Hospital, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Free Depression Treatment Market Shifts & Advancements
Digital therapeutic platforms are fragmenting traditional care delivery hierarchies, while hardware manufacturers pursue vertical integration into software ecosystems to capture recurring revenue streams previously dominated by pure-play digital health vendors.
Closed-loop neuromodulation systems incorporating real-time EEG biomarker feedback are decentralizing depression treatment from institutional settings toward home-based administration. Psychiatric practices with established TMS infrastructure are piloting take-home device protocols for maintenance therapy phases. This decentralization is compressing the addressable market for clinic-based maintenance sessions while expanding total patient touchpoints per episode of care.
The FDA's evolving software-as-a-medical-device classification framework is recategorizing previously unregulated cognitive behavioral therapy apps as prescription-required interventions. Device manufacturers with existing 510(k) clearance infrastructure are acquiring digital therapeutic assets to preempt compliance-driven market exits by venture-funded competitors. European regulators through the MDR are simultaneously tightening clinical evidence requirements for CE-marked mental health applications, creating transatlantic regulatory convergence pressure.
Self-insured employers are unbundling mental health benefits from traditional insurance carve-outs, contracting directly with digital therapeutic platforms and specialized neuromodulation clinic networks. Third-party administrators are losing intermediation power as large employers in the United States establish direct credentialing relationships with TMS providers. This channel compression is most visible in technology sector employers with concentrated coastal workforces and established on-site wellness infrastructure.
Drug Free Depression Treatment Market Segmentation
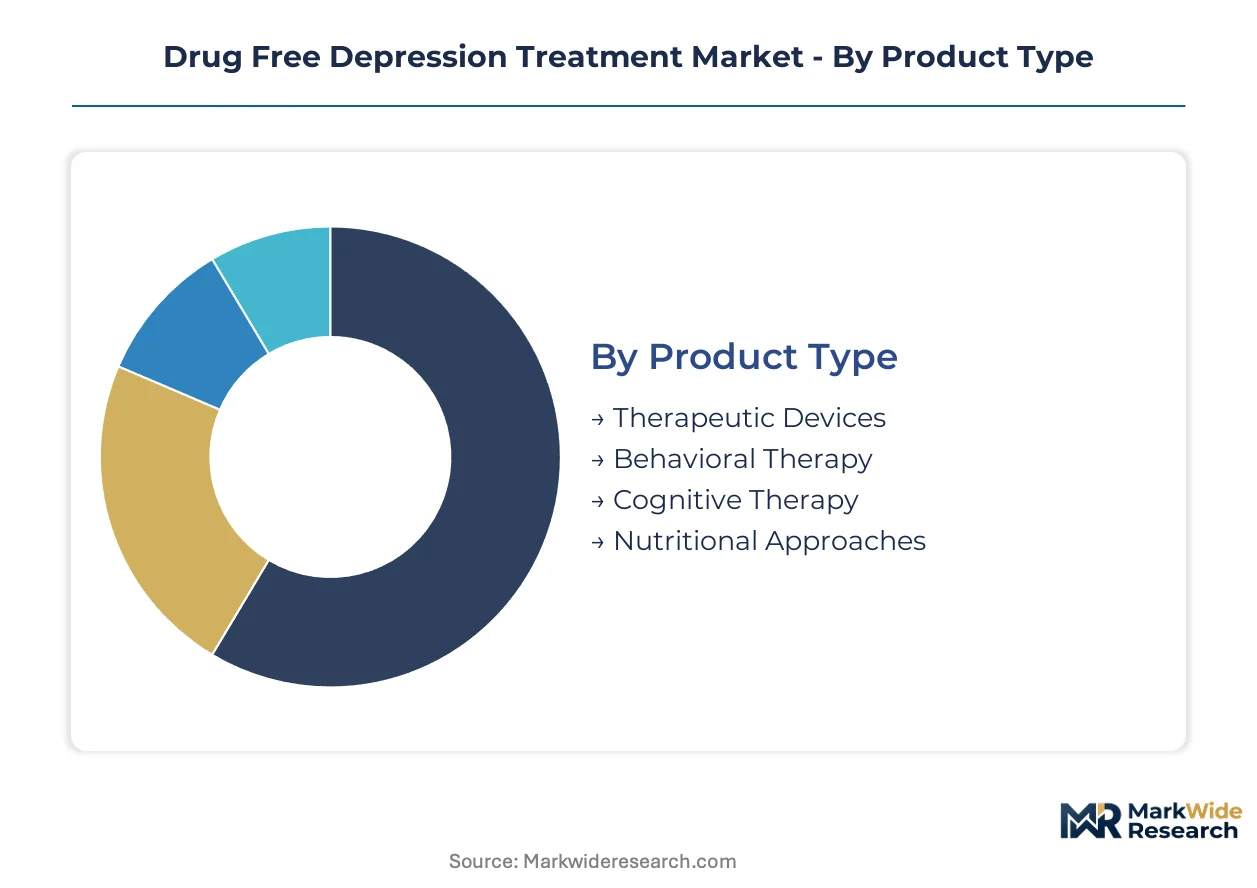
Segmentation in the drug free depression treatment market reveals distinct capital deployment patterns and reimbursement dynamics. Therapeutic devices command premium positioning due to FDA clearance requirements, while digital delivery modes attract venture funding despite unresolved payment pathways.
Product Type:
Supply concentration clusters around capital-intensive therapeutic devices, with manufacturing capabilities concentrated among established neuromodulation system producers.
- Therapeutic Devices:Transcranial magnetic stimulation and electroconvulsive therapy alternatives require FDA 510(k) or breakthrough device clearance. United States hospital networks and ambulatory surgery centers concentrate procurement, driven by CMS national coverage determinations for repetitive TMS.
- Behavioral Therapy:Protocols encompassing behavioral conditioning and exposure therapy retain structural volume dominance. Employer-sponsored mental health programs in the United States accelerate procurement, seeking measurable return-on-investment metrics for vendor selection.
- Cognitive Therapy:Structured cognitive behavioral interventions delivered through clinical or digital channels.
- Nutritional Approaches:Micronutrient supplementation regimens administered through clinical or retail channels.
Therapeutic devices absorb the bulk of installed capacity; cognitive therapy is expanding most quickly.
Delivery Mode:
Cost tier differentiation separates capital-intensive in-person modalities from scalable digital platforms, with reimbursement maturity determining provider economics.
- Online Therapy:Synchronous telehealth platforms enable remote cognitive behavioral therapy delivery. Rural United States markets concentrate demand, addressing workforce shortage constraints through behavioral-digital convergence.
- In-Person Sessions:Clinic-based therapeutic administration requires physical infrastructure and trained specialist presence.
- Mobile Apps:Asynchronous cognitive behavioral therapy modules and mood tracking tools. Large self-insured employers in the United States pilot direct contracting, bypassing traditional insurance intermediaries.
- Workshops:Group-based therapeutic education and skill-building sessions.
In-person sessions absorb the bulk of installed capacity; mobile apps are gaining share fastest.
End User:
Application dynamics vary sharply across customer types, with employer procurement patterns diverging from traditional healthcare reimbursement pathways.
- Individuals:Direct-pay consumers accessing therapeutic services through retail or digital channels.
- Healthcare Providers:Psychiatric practices and hospital systems deploying neuromodulation hardware and therapeutic protocols. Academic medical centers in the United States concentrate fellowship-trained interventional psychiatrists capable of TMS optimization.
- Wellness Centers:Non-clinical facilities offering complementary mental health services.
- Employers:Large self-insured organizations unbundling mental health benefits from traditional insurance carve-outs. Technology sector employers with coastal workforces establish direct credentialing relationships with TMS providers.
Healthcare providers absorb the bulk of installed capacity; employers are climbing the fastest.
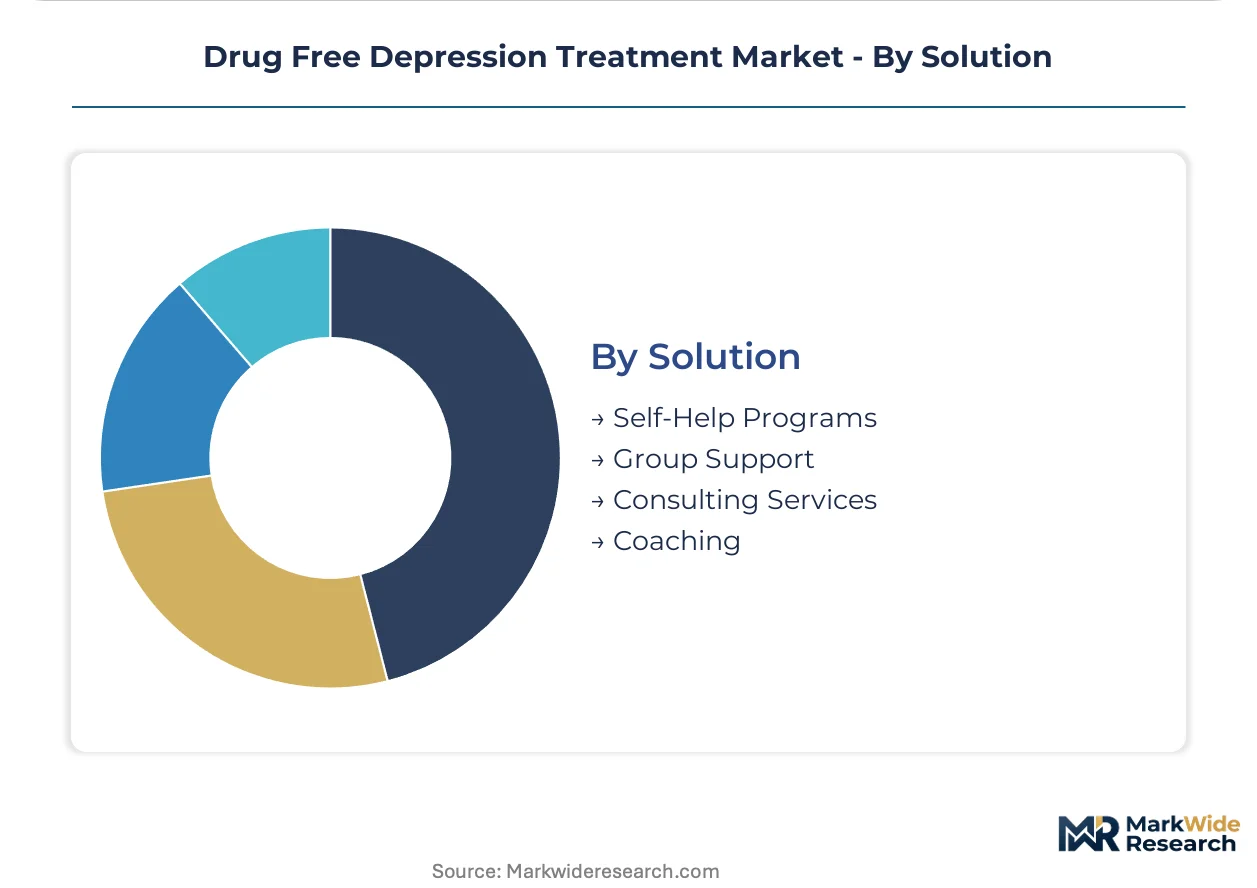
Solution:
Customer type stratification separates institutional procurement of consulting services from individual adoption of self-directed programs.
- Self-Help Programs:Structured therapeutic curricula for individual completion without professional guidance.
- Group Support:Peer-facilitated therapeutic communities and mutual aid structures.
- Consulting Services:Organizational mental health program design and implementation. United States employers contract directly with specialized neuromodulation clinic networks for workforce mental health benefits.
- Coaching:Goal-oriented therapeutic support delivered through synchronous telehealth or in-person sessions.
Consulting services absorb the bulk of installed capacity; coaching shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium brine deposits in Chile's Atacama Desert and hard-rock spodumene mines in Western Australia anchor the upstream material flows for neuromodulation device manufacturing. These raw material localities concentrate the geography of supply for precision-engineered TMS coil assemblies and stimulation electronics.
United States
Employer self-insurance mandates and mature CMS reimbursement codes for repetitive TMS concentrate demand among large technology sector employers. FDA breakthrough device designations accelerate commercialization timelines for qualifying neuromodulation systems. Academic medical centers in Boston and the San Francisco Bay Area house fellowship-trained interventional psychiatrists capable of protocol optimization.
Germany
Industrial automation capabilities in precision coil winding and medical device assembly sustain manufacturing competitiveness for European-market TMS hardware. EU MDR tightening of clinical evidence requirements for CE-marked mental health applications creates transatlantic regulatory convergence pressure. The Baden-Württemberg medical technology cluster around Stuttgart hosts specialized component suppliers for stimulation electronics.
Japan
Aging demographics and workforce mental health policy reforms expand addressable patient populations for non-pharmacological depression interventions. PMDA regulatory frameworks for software-as-a-medical-device classifications shape product development timelines for digital therapeutic platforms. The Kanto region around Tokyo concentrates psychiatric research institutions and hospital networks piloting closed-loop neuromodulation protocols.
United Kingdom
NHS long-term plan commitments to expanding talking therapies access create procurement opportunities for cognitive behavioral therapy platforms. MHRA post-Brexit regulatory autonomy enables divergence from EU MDR timelines for certain device classifications. The London-Southeast corridor attracts venture funding for digital mental health startups despite unresolved reimbursement pathways.
Israel
Defense sector technology transfer and academic research commercialization infrastructure support deep coil engineering innovation for specialized psychiatric applications. Ministry of Health digital health sandbox programs enable rapid clinical validation for software-as-a-medical-device interventions. The Tel Aviv metropolitan area concentrates startup activity in EEG biomarker integration for closed-loop stimulation systems.
Drug Free Depression Treatment Market Competitive Landscape
Global majors compete with regional champions across regulatory clearance infrastructure and installed base maintenance revenue. The market structure concentrates around three tiers: established neuromodulation hardware manufacturers with FDA 510(k) portfolios, digital therapeutic platforms pursuing software-as-a-medical-device reclassification, and academic medical center spin-outs commercializing research protocols. Strategic archetypes include capital-intensive device incumbents defending service lock-in, venture-funded digital health challengers seeking employer direct contracts, and vertically integrated clinic networks capturing patient touchpoints. Dominant competitive moves span M&A activity targeting digital therapeutic assets and capacity expansion into ambulatory clinic networks.
Among device manufacturers, NeuroStar Advanced Therapy and Brainsway Ltd. exemplify contrasting coil architecture strategies, with the former leveraging installed base scale for recurring maintenance revenue and the latter occupying specialized niches through deep stimulation designs. Magstim Company Limited anchors the UK-European manufacturing vector. These three entities represent the hardware-centric competitive tier, distinct from digital-first challengers and institutional clinic networks.
| Leading Market Players |
|---|
| NeuroStar Advanced Therapy |
| Magstim Company Limited |
| TMS NeuroHealth Centers, Inc. |
| Brainsway Ltd. |
| Fisher Wallace Laboratories |
| Psious |
| Cleveland Clinic |
| Mayo Clinic |
| McLean Hospital |
| Others |
Supply & Pricing Matrix
Employer direct-contracting mandates for mental health benefits are forcing device manufacturers to unbundle maintenance protocols from hardware acquisition, compressing upfront capital commitments while extending recurring revenue capture through service tiering.
Pricing Analysis
Warranty and coil calibration bundling distinguishes premium neuromodulation system tiers from standard configurations with à la carte service pricing. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated systems with full maintenance inclusion from entry-level hardware with limited technical support. Price differentiation rests on certification tier—breakthrough-designated devices command substantial premiums over 510(k)-cleared alternatives—and geographic service density, with urban corridor deployments absorbing lower per-unit field service costs. Pricing pressure stems from ambulatory clinic network expansion demanding volume discounts for multi-site procurement. Independent psychiatric practices exhibit highest price sensitivity due to capital constraints, while hospital-affiliated networks with equipment leasing infrastructure demonstrate lowest sensitivity.
Supply Chain Analysis
Refurbishment and coil remanufacturing flows concentrate in Germany and the United States, where precision coil winding capabilities and FDA-registered device servicing infrastructure anchor aftermarket revenue streams. Raw material dependencies draw from Chilean lithium brine deposits for stimulation electronics, Western Australian spodumene for precision-machined components, and Japanese rare-earth processing for magnetic coil assemblies. Single-source vulnerability runs through specialized TMS coil manufacturers with proprietary geometries, exposing providers to extended lead times during demand surges. Distribution runs through hospital procurement consortia and ambulatory surgery center networks, with direct-to-employer contracting emerging as a parallel channel for clinic network operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA software-as-a-medical-device reclassification timelines erect substantial compliance moats, advantaging incumbent device manufacturers with existing 510(k) clearance infrastructure over venture-funded digital challengers lacking randomized controlled trial portfolios.
For Market Incumbents: Lock in maintenance protocol exclusivity through proprietary coil calibration architectures that tether providers to original equipment manufacturer service networks. Expand backward integration into precision coil winding capabilities to neutralize supply disruption risks from specialized component vendors. Prioritize acquisition of digital therapeutic assets with existing clinical evidence packages to preempt FDA reclassification-driven market exits by software competitors. For New Entrants and Emerging Players: Enter via rural United States markets where workforce shortages in psychiatric specialties create demand for behavioral-digital convergence platforms integrating synchronous telehealth coaching with asynchronous cognitive behavioral therapy modules. Target employer direct-contracting channels in technology sector coastal workforces, bypassing traditional insurance intermediaries that exclude most digital therapeutics from fee-for-service billing. Pursue Ministry of Health digital health sandbox programs in Israel for rapid clinical validation of EEG biomarker-integrated closed-loop systems. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated clinic network operators given employer benefit unbundling trends and direct credentialing relationship formation. Long-term viability across the analysis window favors assets combining FDA-cleared hardware infrastructure with software companion development capabilities. Monitor CMS national coverage determination expansion signals for digital therapeutic billing codes as inflection indicators for platform revenue model sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Expedited 18-month commercialization timelines compress competitive entry windows for neuromodulation systems. |
| Hospital System Partnership | Academic medical center affiliations concentrate fellowship-trained interventional psychiatrists capable of protocol optimization. |
| Software Companion Development | Digital therapeutic integration captures recurring revenue streams previously dominated by pure-play health vendors. |
| Reimbursement Strategy | CMS national coverage determination alignment directly influences provider adoption thresholds and capital expenditure decisions. |
| CE Marking Pathway | EU MDR clinical evidence requirements create transatlantic regulatory convergence pressure for trial portfolio depth. |
Research Methodology
FDA 510(k) and breakthrough device filings, CMS national coverage determinations, and ClinicalTrials.gov registries formed the secondary backbone for regulatory pathway mapping and competitive positioning assessment. Primary interviews with interventional psychiatrists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers validated installed base estimates and procurement decision criteria. Triangulation across bottom-up neuromodulation system shipment tracking and top-down healthcare expenditure allocation produced volume and value estimates.
Bottom-up modeling of TMS system installations by provider type and geographic cluster anchored the analytical lens, cross-referenced against top-down employer mental health benefit spend allocation. Segmentation dimensions spanned product type, delivery mode, end user archetype, and solution configuration across the projection horizon. CAGRs derived from provider capacity expansion plans, reimbursement maturation trajectories, and digital therapeutic adoption curves. Forecast inputs incorporated FDA guidance timeline scenarios for software-as-a-medical-device reclassification and CMS coverage determination expansion patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA software reclassification acceleration or CMS digital therapeutic exclusion persistence. Practitioners should monitor employer direct-contracting volume growth and closed-loop neuromodulation home-use protocol adoption for early signals of care delivery decentralization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Addiction Treatment
Alcohol Use Disorder Treatment Market
Addiction Treatment
Opioid Induced Constipation Treatment Market
Addiction Treatment
Smokeless Tobacco Treatment Market
Addiction Treatment
Opioid Withdrawal Treatment Market
Addiction Treatment
Methadone Market
Addiction Treatment
US Mental Health and Addiction Treatment Centers Market
Addiction Treatment
Cocaine Intoxication Treatment Market
Addiction Treatment
Opioid Use Disorder (OUD) Market
Addiction Treatment
Nicotine De-Addiction Products Market
Addiction Treatment
Opioid Use Disorder Treatment Market
Addiction Treatment
Global Substance Use Disorder Treatment Market
Addiction Treatment
Global Addiction Treatment Market
Addiction Treatment
US Ketamine Clinics Market
Addiction Treatment
Substance Abuse Treatment Market