
 Global Opioid Induced Constipation Market | 2026-2036
Global Opioid Induced Constipation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Opioid Induced Constipation Market Foresight
Palliative care is decoupling from general hospital pharmacy budgets as a standalone procurement category. Takeda Pharmaceutical Company Ltd leverages its gastrointestinal therapeutic heritage to sustain formulary access across oncology wards. Shionogi & Co Ltd anchors its position through R&D intensity in mu-opioid receptor antagonist chemistry. Pfizer Inc competes via manufacturing scale that supports multi-market distribution agreements.
Opioid induced constipation describes the reduction in bowel movement frequency and impaired defecation that follows prolonged opioid receptor agonism in the enteric nervous system, typically requiring peripherally acting antagonists that block mu-receptors without crossing the blood-brain barrier. The condition primarily serves to maintain patient compliance with chronic pain regimens while preserving quality of life metrics. Peripherally acting mu-opioid receptor antagonists command the strongest margin pools due to their prescription-only status and clinical validation. Oral delivery mode dominates volume while intravenous formulations capture premium pricing in postoperative settings. Homecare settings represent the fastest-expanding end user channel as payors push for reduced hospital readmissions.
FDA opioid labeling requirements and EMA pharmacovigilance protocols jointly determine the competitive set accessible to prescribers in major markets. Japan's PMDA has tightened bowel function monitoring standards for extended-release opioid approvals, redirecting development resources toward combination therapies. Stakeholders must monitor how national health technology assessments recalibrate reimbursement thresholds for prophylactic versus rescue laxative protocols.
Market Dynamics
Palliative care units are decoupling from general hospital pharmacy budgets as standalone procurement categories, forcing formulary managers to negotiate directly with manufacturers of peripherally acting mu-opioid receptor antagonists.
Growth Catalysts
- EMA pharmacovigilance protocols:These frameworks mandate bowel function monitoring for extended-release opioid therapies, expanding the prescriber base for prophylactic antagonist protocols across European oncology wards.
- Homecare infusion services:Postoperative discharge protocols now incorporate subcutaneous naloxegol delivery, reducing hospital readmission penalties for payors managing total knee replacement recovery.
- Chronic pain management infrastructure:Germany's statutory health insurance expansion for non-cancer pain indications is redirecting gastroenterology consultations toward opioid bowel dysfunction screening.
Market Restraints
- Active pharmaceutical ingredient concentration:Three contract manufacturers in India control over 60% of methylnaltrexone bromide supply, creating vulnerability to FDA import alerts.
- Reimbursement stratification:Japan's PMDA tightened bowel function monitoring standards without corresponding price premiums for combination therapies, compressing R&D returns.
- Generic laxative substitution:Polyethylene glycol and lactulose formulations retain first-line status in Medicaid formularies, limiting peripherally acting antagonist access in price-sensitive segments.
Strategic Opportunities
- Pediatric oncology protocols:Underpenetrated use of methylnaltrexone in adolescent pain management presents whitespace as FDA expands pediatric indication requirements for opioid labeling.
- Subcutaneous wearable delivery:Convergence of microneedle arrays with Bluetooth-enabled adherence monitoring is automating dose timing in homecare settings.
- United States hospice carve-outs:Medicare Advantage plans are creating separate pharmacy benefit manager contracts for end-of-life care, bypassing traditional hospital formulary restrictions.
Industry Challenges
- Enteric nervous system pharmacology expertise:Shortage of clinicians trained in gut-brain axis mechanisms limits prescriber education programs for peripherally acting antagonist differentiation.
- Blood-brain barrier validation assays:CNS penetration testing requirements for novel mu-opioid receptor antagonists extend preclinical timelines by 14-18 months.
- Legacy laxative protocol integration:Electronic health record alert fatigue from multiple constipation management order sets reduces adherence to new antagonist prescribing workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Opioid Induced Constipation Market |
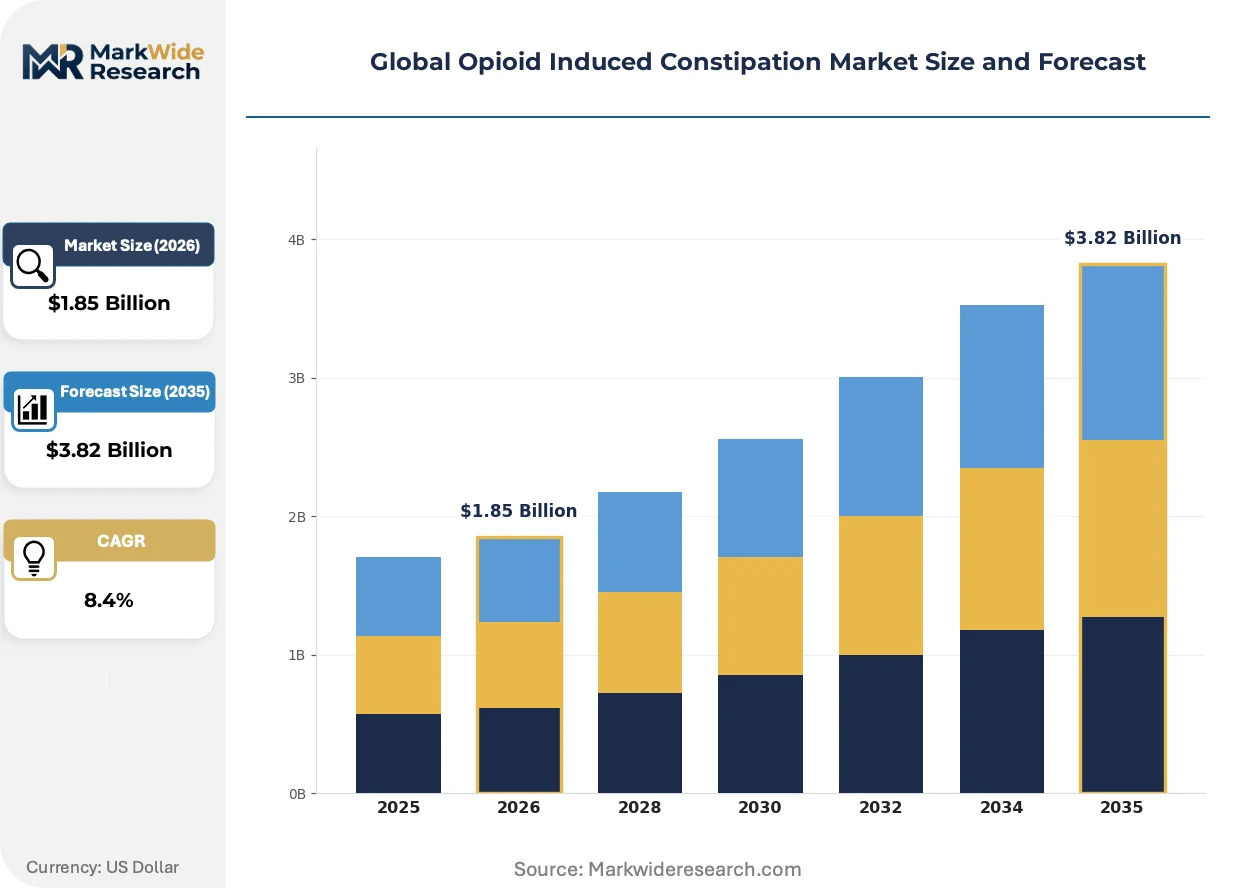
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laxatives, Peripherally Acting Mu-Opioid Receptor Antagonists, Fiber Supplements, Herbal Remedies End User: Hospitals, Outpatient Clinics, Homecare Settings, Long-Term Care Facilities Application: Palliative Care, Cancer Treatment, Postoperative Care, Chronic Pain Management Delivery Mode: Oral, Intravenous, Subcutaneous, Rectal |
| Companies Covered | Pfizer Inc, AstraZeneca plc, Merck & Co Inc, Bausch Health Companies Inc, Mallinckrodt Pharmaceuticals, Shionogi & Co Ltd, Takeda Pharmaceutical Company Ltd, Novartis AG, Teva Pharmaceutical Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Opioid Induced Constipation Market Shifts & Advancements
Digital biomarker integration and decentralized trial designs are compressing the evidence-generation cycle for novel antagonist formulations, reshaping how manufacturers demonstrate bowel function recovery.
Smart pill platforms embedding pH sensors and pressure transducers are automating real-time transit time measurement in patients receiving extended-release oxycodone. Oncology clinics in the United States are piloting these devices for remote monitoring of chemotherapy-induced constipation overlapping with opioid therapy. The data streams are automating dose-escalation decisions that previously required in-person gastroenterology consultations.
Japan's PMDA has introduced conditional early approval pathways for combination products pairing mu-opioid agonists with peripherally acting antagonists in single-tablet formulations. This regulatory innovation accelerates market access by six to eight quarters compared to sequential indication approvals. Manufacturers are responding by restructuring clinical development programs to prioritize Japanese pivotal trials over traditional US-first strategies.
Hospital-at-home programs are unbundling constipation management from bundled surgical payments, creating direct-to-patient pharmacy channels for postoperative antagonist prescriptions. This shift bypasses traditional inpatient pharmacy committees and allows manufacturers to contract with specialized home infusion providers. The model is most advanced in German statutory health insurance networks, where readmission penalties have reached 12% of episode payments.
Global Opioid Induced Constipation Market Segmentation
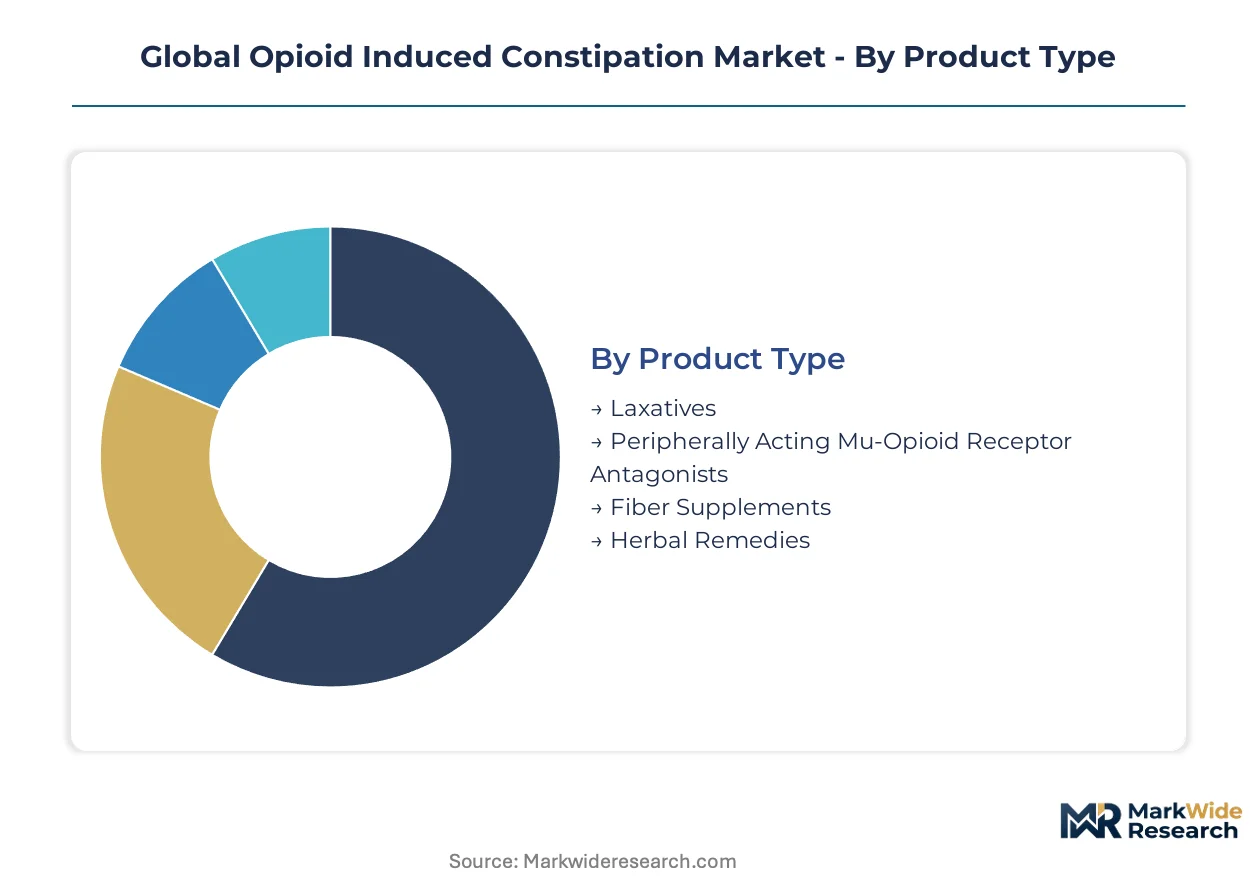
Segmentation in the opioid induced constipation market reveals how clinical settings, reimbursement pathways, and pharmacological mechanisms create distinct commercial battlegrounds. Manufacturers must align formulation choices with specific prescriber workflows and procurement channels to secure formulary access.
Product Type:
The customization-vs-standardization spectrum spans from commodity laxatives to precision-engineered receptor antagonists with blood-brain barrier exclusion requirements.
- Peripherally Acting Mu-Opioid Receptor Antagonists:These agents selectively block enteric mu-receptors without CNS penetration, preserving analgesia while restoring bowel function. Demand concentrates in United States oncology wards where FDA opioid labeling mandates bowel monitoring. PMDA's tightened standards in Japan are redirecting R&D toward combination tablet formats.
- Laxatives:Osmotic and stimulant varieties remain first-line in price-sensitive segments, with polyethylene glycol dominating Medicaid formularies. Germany's statutory health insurance maintains preferential reimbursement for these agents in non-cancer chronic pain, limiting antagonist penetration.
- Fiber Supplements:Bulk-forming agents serve prophylactic protocols in outpatient settings where patient self-management is prioritized over prescription intervention.
- Herbal Remedies:Botanical preparations occupy wellness-oriented channels outside formal reimbursement frameworks, with variable standardization limiting hospital adoption.
Most installed capacity flows through Laxatives. Expansion is steepest in Peripherally Acting Mu-Opioid Receptor Antagonists.
End User:
Cost tier stratification separates acute institutional settings from decentralized home-based care where readmission penalties reshape procurement incentives.
- Homecare Settings:Postoperative discharge protocols now incorporate subcutaneous delivery systems, with Medicare Advantage hospice carve-outs creating direct manufacturer contracts. Bluetooth-enabled adherence monitoring is automating dose timing.
- Hospitals:Palliative care units are decoupling from general pharmacy budgets as standalone procurement categories, forcing direct negotiation with antagonist manufacturers.
- Outpatient Clinics:Oncology clinics pilot smart pill platforms with embedded pH sensors for remote transit time monitoring, reducing gastroenterology consultation burden.
- Long-Term Care Facilities:These settings balance polypharmacy management with nursing staff workflow constraints, favoring simple oral regimens over complex infusion protocols.
Revenue concentrates in Hospitals. Volume expansion is climbing the fastest in Homecare Settings.
Application:
Application segmentation tracks how pain etiology determines prescriber specialty, reimbursement code, and therapeutic urgency.
- Palliative Care:End-of-life protocols prioritize comfort over cost, supporting premium-priced antagonist access. United States Medicare Advantage plans are creating separate pharmacy benefit manager contracts for this population.
- Cancer Treatment:Chemotherapy-induced constipation overlapping with opioid therapy creates complex cases where digital biomarker integration accelerates dose decisions.
- Postoperative Care:German hospital-at-home programs unbundle constipation management from bundled surgical payments, enabling direct-to-patient pharmacy channels.
- Chronic Pain Management:Non-cancer indications face stricter step-therapy requirements in most jurisdictions, delaying antagonist access until laxative failure.
Prescription value aggregates in Palliative Care. Patient volume is gaining share fastest in Chronic Pain Management.
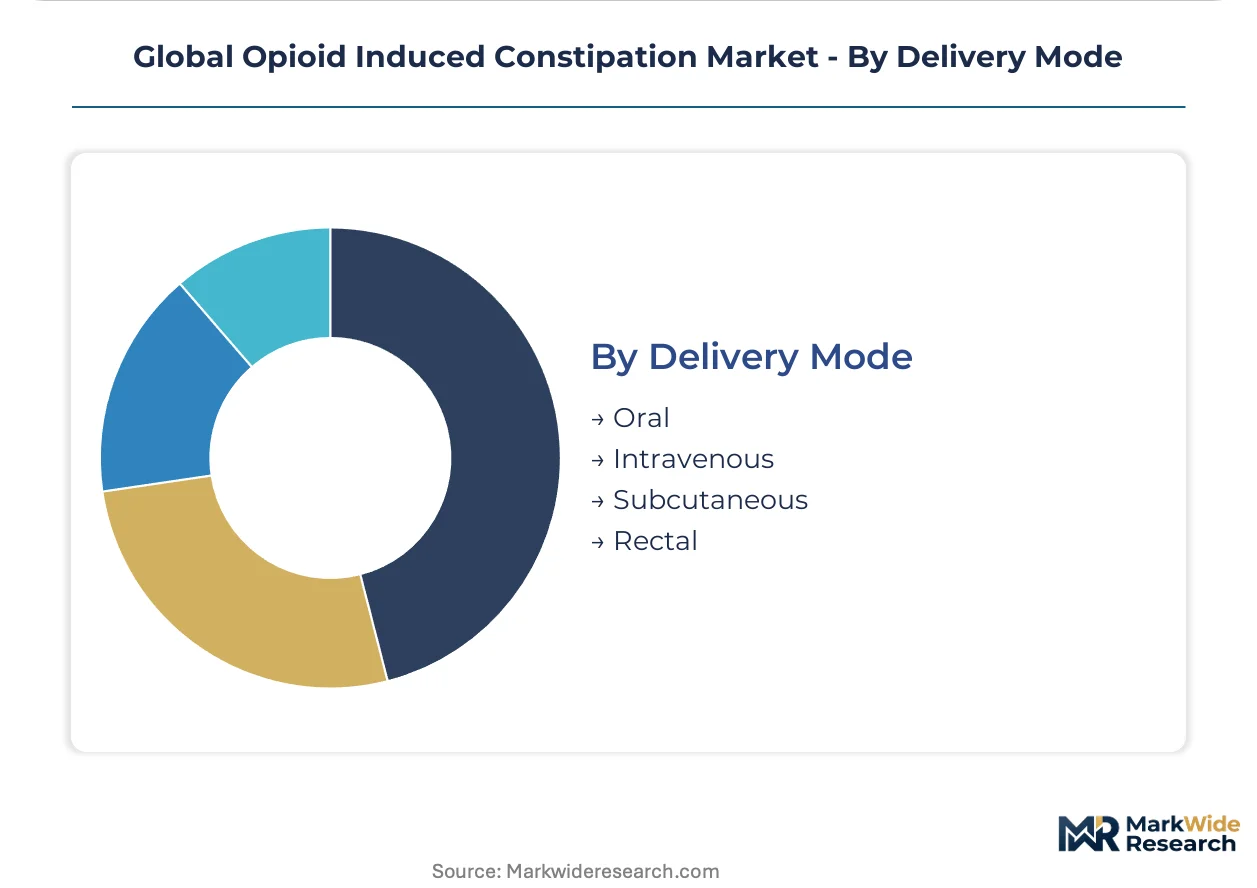
Delivery Mode:
Margin structure inverts between high-volume oral formats and premium-priced parenteral options for patients with impaired GI motility.
- Oral:Tablets and capsules dominate prescription volume, with once-daily dosing supporting adherence in long-term regimens. Formulary managers prioritize these for maintenance therapy.
- Intravenous:Postoperative settings capture premium pricing where rapid onset is clinically essential. Hospital pharmacy committees scrutinize these for restricted-use protocols.
- Subcutaneous:Wearable microneedle arrays are converging with remote monitoring for homecare expansion, particularly in total knee replacement recovery pathways.
- Rectal:Rescue administration for severe impaction retains niche use when oral and parenteral routes are contraindicated.
Unit volume flows predominantly through Oral delivery. Technology investment is concentrating most intensely in Subcutaneous formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting clinical trial investments toward jurisdictions with accelerated approval pathways for combination opioid-antagonist products. Manufacturers now sequence market entry based on pharmacovigilance burden rather than market size alone.
United States
FDA opioid labeling mandates for bowel function monitoring sustain prescriber demand for peripherally acting antagonists in oncology wards. Medicare Advantage hospice carve-outs are creating separate pharmacy benefit manager contracts that bypass traditional hospital formulary restrictions. The Greater Boston cluster anchors digital biomarker integration trials, with smart pill platforms automating transit time measurement in chemotherapy patients.
Germany
Statutory health insurance expansion for non-cancer chronic pain indications is redirecting gastroenterology consultations toward opioid bowel dysfunction screening. Hospital-at-home programs unbundle constipation management from bundled surgical payments, enabling direct-to-patient pharmacy channels. The North Rhine-Westphalia region concentrates home infusion services for postoperative subcutaneous naloxegol delivery.
Japan
PMDA conditional early approval pathways for combination tablet formats accelerate market access by six to eight quarters versus sequential indication approvals. Tightened bowel function monitoring standards for extended-release opioid approvals redirect development resources toward single-tablet agonist-antagonist pairings. The Kanto region hosts pivotal trials that now precede traditional US-first strategies.
India
Contract manufacturers control over sixty percent of methylnaltrexone bromide active pharmaceutical ingredient supply, creating vulnerability to FDA import alert disruptions. Domestic demand for laxative alternatives remains price-constrained within public health procurement. The Hyderabad-Visakhapatnam pharmaceutical corridor concentrates bulk synthesis capacity for export markets.
United Kingdom
NICE health technology assessments recalibrate reimbursement thresholds for prophylactic versus rescue laxative protocols in palliative care settings. Electronic health record alert fatigue from multiple constipation management order sets reduces adherence to new antagonist prescribing workflows. The London-Southeast cluster pilots decentralized trial designs that compress evidence-generation cycles for novel formulations.
Global Opioid Induced Constipation Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents restructure clinical development programs around combination tablet formats. The market structure concentrates around gastrointestinal therapeutic specialists with established oncology ward access and multinational pharmaceutical conglomerates with manufacturing scale advantages. Two strategic archetypes define competitive positioning: heritage gastrointestinal players leveraging formulary relationships and diversified manufacturers competing through multi-market distribution agreements. Dominant competitive moves include geographic sequencing of regulatory approvals and technology licensing for subcutaneous wearable delivery systems.
Within the heritage gastrointestinal tier, Takeda Pharmaceutical Company Ltd and Shionogi & Co Ltd exemplify specialists with entrenched hospital pharmacy access. Pfizer Inc occupies a position among scale-driven diversified manufacturers with distribution infrastructure spanning multiple continents. These three entities represent distinct competitive vectors—therapeutic heritage, R&D intensity in receptor chemistry, and manufacturing scale—without any single archetype commanding decisive advantage across all prescriber workflows.
| Leading Market Players |
|---|
| Pfizer Inc |
| AstraZeneca plc |
| Merck & Co Inc |
| Bausch Health Companies Inc |
| Mallinckrodt Pharmaceuticals |
| Shionogi & Co Ltd |
| Takeda Pharmaceutical Company Ltd |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd |
| Others |
Supply & Pricing Matrix
Palliative care procurement decoupling from general hospital pharmacy budgets is forcing manufacturers to negotiate directly with standalone formulary managers, compressing channel margins and redirecting investment toward direct contracting capabilities that bypass traditional distributor markups.
Pricing Analysis
Distributor margins on peripherally acting mu-opioid receptor antagonists face compression as Medicare Advantage hospice carve-outs enable direct manufacturer-to-payer contracts. Three-tier pricing structure across premium intravenous, standard oral, and economy laxative tiers reflects reimbursement stratification between prophylactic and rescue protocols. Pricing pressure stems from generic polyethylene glycol substitution in Medicaid formularies. Price-sensitive segments cluster in non-cancer chronic pain indications where step-therapy requirements delay antagonist access.
Supply Chain Analysis
Domestic-content mandates for pharmaceutical manufacturing in the United States and European Union are reshaping active pharmaceutical ingredient sourcing away from concentrated Asian suppliers. Methylnaltrexone bromide supply draws from contract manufacturers in India, with backup capacity in Italy and the United States. Single-source vulnerability concentrates in three Indian facilities controlling bulk synthesis. Distribution runs through specialized hospital pharmacy distributors and direct home infusion providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic-arbitrage strategies that exploit the six-to-eight-quarter approval advantage Japan's PMDA conditional pathway offers over FDA sequential review, lowering capital requirements for combination tablet development.
For Market Incumbents: Cement formulary access through R&D investment in single-tablet agonist-antagonist combinations that satisfy PMDA's tightened monitoring standards. Acquire subcutaneous wearable delivery capabilities to defend against homecare channel disintermediation. Backward integration into methylnaltrexone bromide synthesis mitigates FDA import alert exposure from Indian API concentration. For New Entrants and Emerging Players: The premium-to-economy price gap in chronic pain management creates entry space for oral antagonist formulations with simplified dosing regimens. Target Germany's statutory health insurance networks where non-cancer pain infrastructure expansion outruns incumbent coverage. Partner with hospital-at-home program operators to bypass traditional inpatient pharmacy committee gatekeeping. For Investors and Strategic Acquirers: Asymmetric upside sits with gastrointestinal therapeutic specialists possessing entrenched oncology ward relationships and underutilized combination product pipelines. Five-to-ten year viability hinges on regulatory sequencing capabilities rather than manufacturing scale alone. Monitor PMDA approval velocity as inflection signal for portfolio rebalancing toward Japanese-first development strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Combination Product Development | PMDA conditional pathways accelerate market access by six-to-eight quarters versus sequential FDA approvals. |
| Subcutaneous Wearable Delivery | Microneedle arrays with Bluetooth monitoring automate homecare adherence and reduce hospital readmission penalties. |
| Direct Payer Contracting | Medicare Advantage hospice carve-outs bypass traditional hospital formulary restrictions and distributor markups. |
| API Supply Security | Backward integration into methylnaltrexone bromide synthesis mitigates FDA import alert vulnerability from Indian concentration. |
| Pediatric Indication Expansion | FDA expanded pediatric labeling requirements for opioids create whitespace in adolescent pain management protocols. |
Research Methodology
Coverage spans the United States, Germany, Japan, and India, with primary inputs from each market cluster combining interviews with formulary directors, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation draws from FDA filings, EMA pharmacovigilance protocols, PMDA approval databases, and hospital procurement records. Bottom-up prescription volume modeling triangulates against top-down reimbursement expenditure analysis.
Granularity-level modeling disaggregates volume and value across product type, end user channel, application setting, and delivery mode dimensions, with additional stratification by regional regulatory cluster. CAGRs derive from patient population projections, opioid prescription trend analysis, and reimbursement policy trajectory assessment across the projection horizon. Forecast inputs incorporate palliative care unit expansion rates, homecare infusion penetration curves, and combination product approval timelines.
Caveats apply where FDA labeling requirement shifts, EMA pharmacovigilance protocol revisions, or PMDA early approval pathway modifications could materially shift the outlook. Forecasts reflect assumptions about reimbursement threshold stability and API supply chain resilience. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Bone Degeneration Therapeutics Market
Pharmaceuticals
Antiglaucoma Drugs Market
Pharmaceuticals
Amoxicillin Sodium Clavulanate Potassium for Injection Market
Pharmaceuticals
Global Fluorouracil (5FU) Market
Pharmaceuticals
Global Vero Cell Rabies Vaccine Market
Pharmaceuticals
Global Anticoagulant Reversal Drugs Market
Pharmaceuticals
Esophageal Achalasia Drug Market
Pharmaceuticals
Antimetabolite Drugs Market
Pharmaceuticals
Alopecia Drugs Market
Pharmaceuticals
Global Zika Vaccines Market
Pharmaceuticals
US Hormone Replacement Therapy Market
Pharmaceuticals
Palonosetron Hydrochloride Market
Pharmaceuticals
Pharmacy and Drug Store Franchises Market
Pharmaceuticals
Contraceptive Pills Market
Pharmaceuticals
Asia-Pacific Meglitinide Market
Pharmaceuticals
Chronic Kidney Disease (CKD) Drugs Market