
 Methadone Market | 2026-2036
Methadone Market Size, Share, and Industry Trends Forecast 2026-2036
Methadone Market Analysis
A shortage of certified addiction medicine physicians is redrawing competitive dynamics in methadone distribution. Mallinckrodt Pharmaceuticals dominates North American manufacturing through captive production of active pharmaceutical ingredient. Hikma Pharmaceuticals extends its position via specialized oral solution formulations for clinic networks. Johnson Matthey anchors European supply through controlled-substance synthesis expertise in the United Kingdom.
Methadone is a synthetic opioid agonist with a molecular weight of 345.9 g/mol, formulated as racemic mixture or levorotatory enantiomer, primarily indicated for opioid use disorder maintenance and chronic pain management. Oral solution formulations lead volume consumption due to clinic-based supervised dosing requirements in regulated treatment settings. Pain management applications represent the fastest-expanding therapy area as prescribers seek long-acting alternatives amid tightening Schedule II controls. Transdermal delivery remains niche but carries premium positioning for palliative care segments where patient compliance limits oral administration.
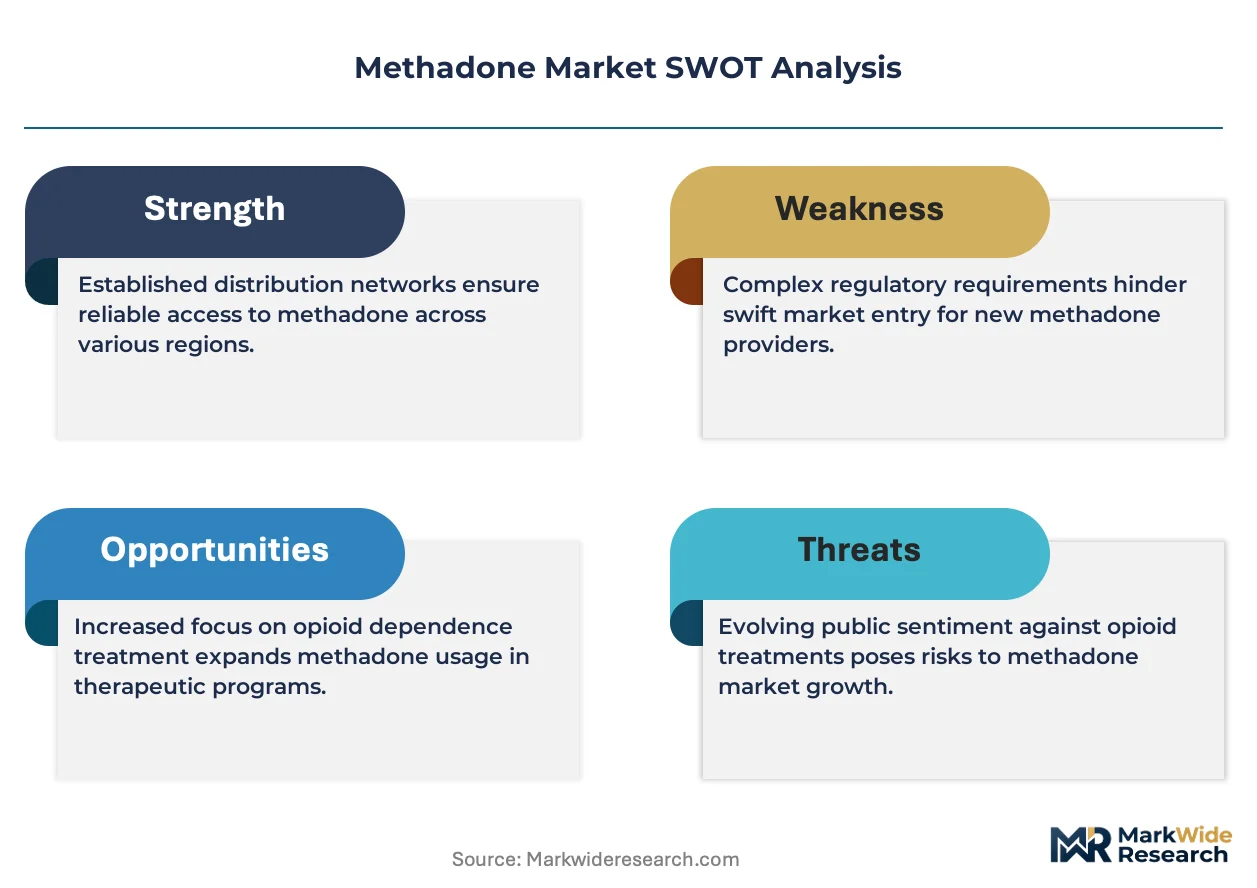
The DEA enforces aggregate production quotas that directly cap annual methadone manufacturing volumes, while FDA regulations under 21 CFR Part 291 mandate opioid treatment program certification for dispensing. SAMHSA accreditation standards govern patient caps per clinic site, constraining geographic expansion of service delivery. Stakeholders must monitor state-level Medicaid reimbursement changes for medication-assisted treatment as these determine clinic profitability and patient access capacity.
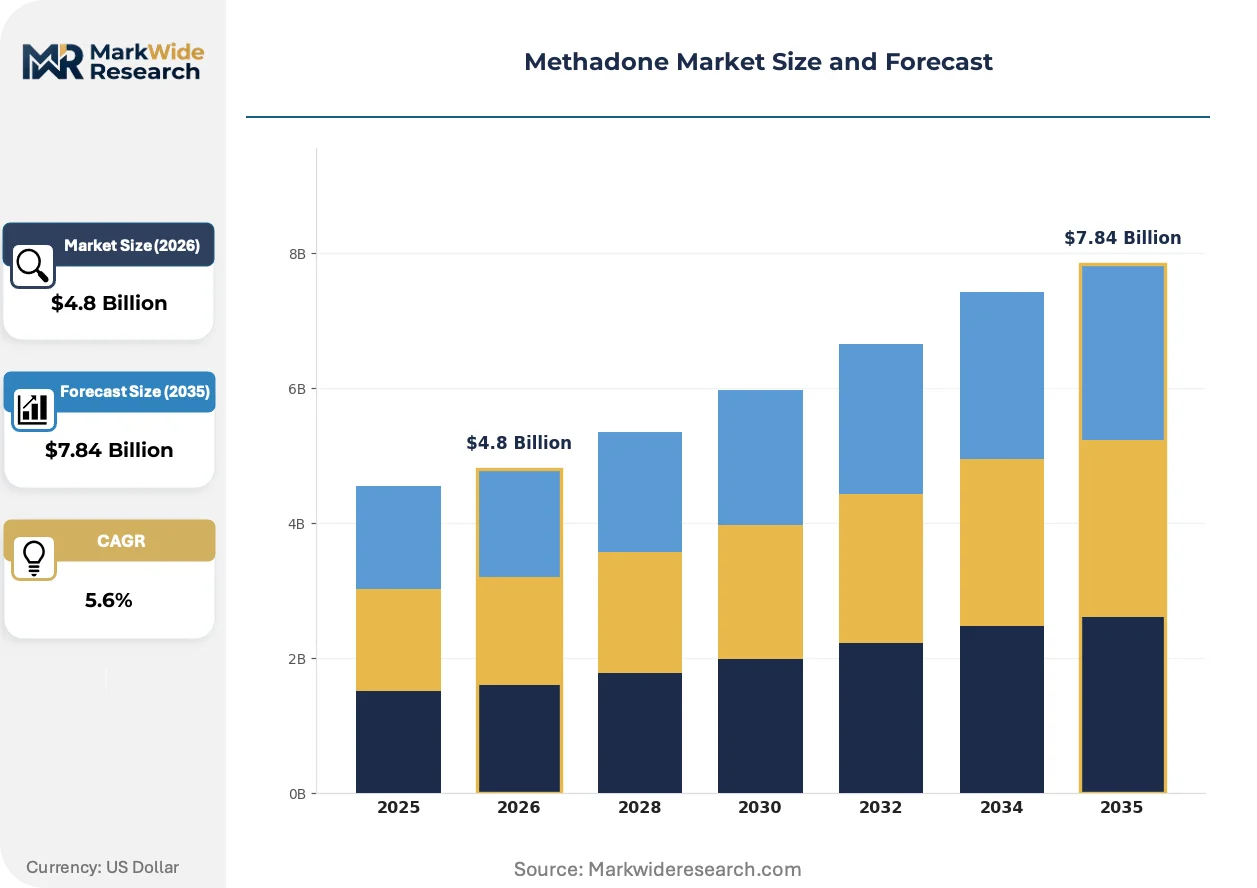
Market Dynamics
The DEA's aggregate production quota system creates artificial scarcity that shapes competitive positioning across methadone manufacturing. This supply ceiling concentrates volume allocation among certified producers while restricting new market entry through controlled-substance licensing barriers.
Growth Catalysts
- SAMHSA accreditation expansion:The Substance Abuse and Mental Health Services Administration has relaxed patient caps per clinic site, enabling treatment networks to scale capacity in underserved counties.
- Oral solution formulations:Liquid dosing protocols dominate supervised clinic administration, driving volume consumption through ease of titration and reduced diversion risk compared to tablet equivalents.
- United States opioid use disorder prevalence:Persistent demand for medication-assisted treatment maintains baseline consumption despite fluctuations in prescribing patterns for chronic pain applications.
Market Restraints
- DEA quota concentration:The Drug Enforcement Administration's annual manufacturing ceilings limit total available supply, creating allocation bottlenecks when demand spikes unexpectedly.
- Active pharmaceutical ingredient dependency:North American producers rely on concentrated import channels for key synthesis precursors, exposing margins to raw material volatility.
- Buprenorphine substitution:Partial agonist alternatives with lower overdose risk profiles are capturing maintenance therapy share in jurisdictions with relaxed prescribing authority.
Strategic Opportunities
- Telehealth-integrated induction:Remote patient intake protocols under evolving SAMHSA guidance could extend clinic reach into rural catchment areas previously excluded by travel barriers.
- Transdermal palliative applications:Patch delivery systems address compliance limitations in terminal care settings where oral administration proves impractical.
- State Medicaid reimbursement expansion:Coverage parity mandates for medication-assisted treatment are improving clinic profitability in jurisdictions that previously restricted beneficiary access.
Industry Challenges
- Addiction medicine physician scarcity:Board-certified prescriber shortages constrain clinic expansion velocity despite capital availability for facility development.
- Controlled-substance security infrastructure:DEA-mandated vault specifications and inventory tracking systems impose substantial fixed costs on new treatment site establishment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methadone Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injectable, Oral Solution, Powder Therapy Area: Opioid Dependence, Pain Management, Detoxification, Palliative Care Delivery Mode: Intravenous, Oral, Transdermal, Sublingual End User: Hospitals, Rehabilitation Centers, Outpatient Clinics, Pharmacies |
| Companies Covered | Mallinckrodt Pharmaceuticals, Hikma Pharmaceuticals, VistaPharm, Sanofi, Siegfried Holding, Johnson Matthey, Aurolife Pharma, Macfarlan Smith, Tianjin Central Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methadone Market Emerging Trajectories
Formulation technology and regulatory flexibility are converging to reshape methadone delivery modalities. These shifts are compressing traditional clinic-centric models while creating openings for alternative administration pathways.
Racemic-to-levorotatory enantiomer purification is fragmenting manufacturing process portfolios. Specialized synthesis contractors in the United Kingdom are investing in chiral separation capacity to serve premium pain management segments. This capability stratification is enabling price-tier differentiation between maintenance-grade and precision-dosed product lines.
FDA guidance under 21 CFR Part 291 is tightening documentation requirements for opioid treatment program certification. The agency's enhanced audit protocols are extending compliance timelines for new clinic approvals. European manufacturers with established quality management systems are positioning to capture contract manufacturing opportunities as domestic producers face inspection backlogs.
Take-home dose privileges are expanding under revised SAMHSA stability criteria for patients meeting retention benchmarks. Stable enrollees now receive multi-day supplies, reducing clinic visit frequency and freeing capacity for intake expansion. This consumption-pattern shift is most visible in United States metropolitan markets with established treatment infrastructure and longest-operating programs.
Methadone Market Segmentation
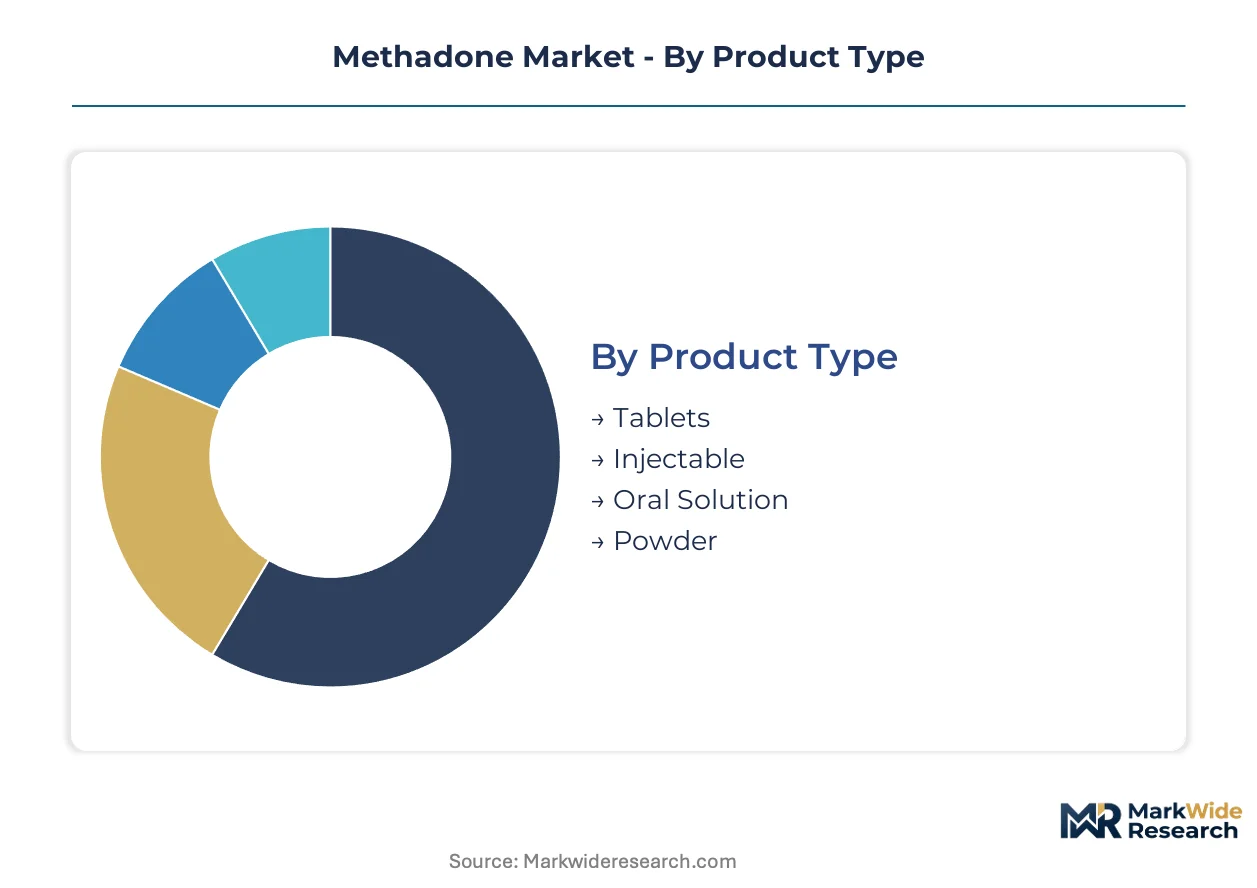
Methadone's bifurcated regulatory environment—split between tightly controlled opioid treatment programs and conventional pain management prescribing—creates distinct margin profiles across formulation types. Segmentation reveals where DEA quota constraints and SAMHSA accreditation requirements concentrate commercial value.
Product Type:
Oral solution formulations command the widest margin pools due to clinic-based supervised dosing protocols and recurring volume commitments from certified treatment networks.
- Oral Solution:Liquid racemic or levorotatory formulations enable precise titration under direct observation. Demand concentrates in United States metropolitan OTP networks where SAMHSA-mandated supervision requirements eliminate diversion risks that plague solid dosage forms.
- Tablets:Compressed solid dosage forms carry lower per-unit pricing but serve take-home dose privileges for stable patients meeting retention benchmarks. United States state Medicaid programs increasingly restrict tablet reimbursement to patients with demonstrated compliance histories, compressing volume growth in maintenance therapy.
- Injectable:Sterile parenteral formulations serve acute detoxification protocols in hospital settings where rapid bioavailability overrides oral administration constraints.
- Powder:Bulk active pharmaceutical ingredient supplies compounding pharmacies and specialized manufacturing contractors with DEA Schedule II import licenses.
Oral solution holds installed capacity. Injectable is rotating up the share rankings.
Therapy Area:
Application-driven segmentation shows pain management generating premium pricing through less restrictive dispensing channels compared to addiction medicine protocols.
- Pain Management:Chronic and cancer pain indications bypass OTP certification requirements, allowing retail pharmacy dispensing under standard Schedule II controls. United States prescribers facing hydrocodone rescheduling pressures are rotating toward long-acting methadone as an alternative, expanding volumes in palliative care networks.
- Opioid Dependence:Maintenance therapy for opioid use disorder operates under 21 CFR Part 291 regulations requiring SAMHSA-accredited program enrollment. Patient caps per clinic site constrain geographic expansion despite persistent prevalence of untreated dependence in rural United States counties.
- Detoxification:Medically supervised withdrawal protocols in inpatient settings utilize shorter treatment durations with higher per-episode intensity.
- Palliative Care:Terminal care applications leverage methadone's NMDA receptor antagonism for neuropathic pain unresponsive to conventional opioids.
Opioid dependence anchors volume throughput. Pain management is climbing the fastest.
Delivery Mode:
Route of administration segmentation tracks regulatory control intensity, with parenteral and transdermal formats capturing value through compliance advantages in specific care settings.
- Oral:Swallowed or liquid formulations dominate consumption through ease of administration and established bioequivalence data supporting generic substitution.
- Intravenous:Hospital-based administration for acute detoxification or pain crisis management requires specialized nursing infrastructure.
- Transdermal:Patch delivery systems address compliance limitations in terminal care settings where oral administration proves impractical, carrying premium positioning despite limited formulary penetration.
- Sublingual:Mucosal absorption formulations serve niche applications where first-pass metabolism avoidance improves bioavailability.
Oral delivery holds installed capacity. Transdermal is gaining share fastest.
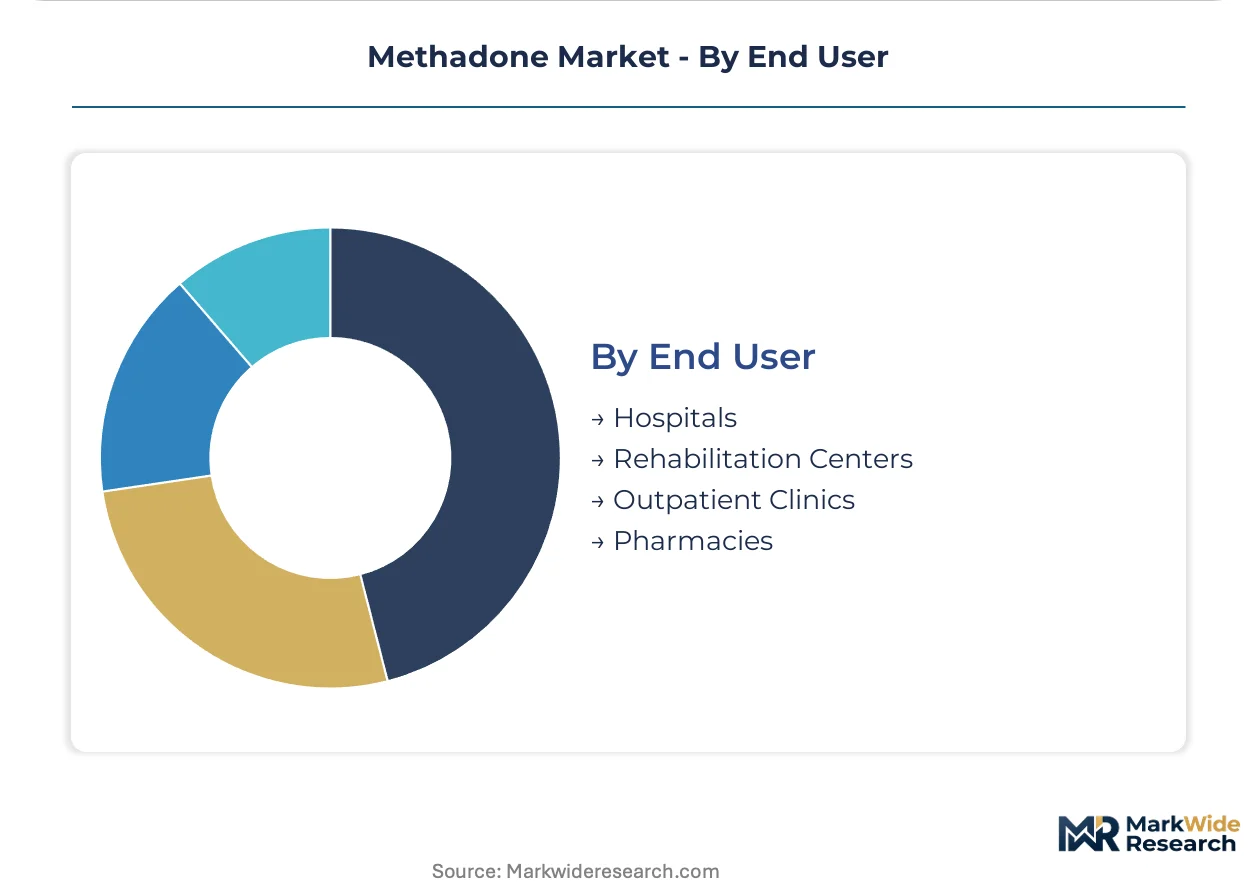
End User:
Customer-type segmentation reflects the split between regulated addiction treatment infrastructure and conventional healthcare delivery channels.
- Rehabilitation Centers:Dedicated substance use disorder facilities combine residential programming with medication-assisted treatment under unified SAMHSA accreditation. United States networks expanding into underserved counties drive capacity additions for supervised dosing infrastructure.
- Outpatient Clinics:Opioid treatment programs represent the core consumption node, with DEA-registered narcotic treatment programs required for methadone dispensing. Take-home dose privilege expansions under revised stability criteria are reducing visit frequency for established patients.
- Hospitals:Acute care settings utilize methadone for inpatient pain management and medically supervised withdrawal, with pharmacy and therapeutics committees governing formulary placement.
- Pharmacies:Retail dispensing is restricted to pain management indications, with addiction therapy explicitly excluded from community pharmacy channels under federal regulations.
Outpatient clinics hold installed capacity. Rehabilitation centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. The United States channels methadone almost exclusively through SAMHSA-regulated opioid treatment programs with supervised dosing, while European markets permit broader pain management dispensing through retail pharmacies.
United States
Opioid use disorder prevalence and expanding OTP enrollment drive demand. DEA aggregate production quotas cap annual manufacturing volumes, creating allocation bottlenecks during demand spikes. New York and California treatment networks are adding clinic capacity in underserved counties following relaxed patient caps.
Germany
Chronic pain management applications exceed addiction therapy volumes. EMA oversight governs formulation approvals while Germany's national health insurance reimburses long-acting opioid alternatives. Bavarian pharmaceutical clusters around Munich host specialized synthesis contractors serving continental markets.
United Kingdom
Controlled-substance synthesis expertise anchors European supply. MHRA regulations align with EU directives on narcotic manufacturing licenses. Johnson Matthey's facilities in Royston and Macfarlan Smith's Edinburgh operations concentrate Schedule II production capacity for export markets.
China
Tianjin Central Pharmaceutical represents domestic manufacturing capacity for regional consumption. NMPA controls on narcotic API production limit export volumes. Yangtze River Delta chemical parks house precursor synthesis operations feeding regulated pharmaceutical channels.
India
Specialized oral solution formulations serve clinic networks across South Asia. CDSCO licensing requirements for narcotic manufacturing create barriers to domestic capacity expansion. Hyderabad and Ahmedabad pharmaceutical corridors are developing controlled-substance compliance infrastructure for contract manufacturing opportunities.
Methadone Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in methadone manufacturing. Mallinckrodt Pharmaceuticals dominates North American API production through captive manufacturing assets, while European specialists concentrate on high-purity enantiomer separation for premium segments. Three archetypes define competitive positioning: vertically integrated API-to-finished-dose manufacturers, specialized oral solution formulators for clinic networks, and controlled-substance synthesis contractors serving regulated markets. Capacity expansion and regulatory compliance infrastructure represent the dominant competitive moves, as DEA quota allocations and SAMHSA accreditation requirements constrain new entry.
Among North American manufacturers, Mallinckrodt Pharmaceuticals exemplifies the integrated API-to-dose archetype, while Hikma Pharmaceuticals occupies a position as a specialized formulator for supervised clinic administration. Johnson Matthey anchors the European synthesis contractor tier, representing controlled-substance manufacturing expertise for regulated export markets. These three companies illustrate how geographic regulatory specialization shapes competitive positioning across the value chain.
| Leading Market Players |
|---|
| Mallinckrodt Pharmaceuticals |
| Hikma Pharmaceuticals |
| VistaPharm |
| Sanofi |
| Siegfried Holding |
| Johnson Matthey |
| Aurolife Pharma |
| Macfarlan Smith |
| Tianjin Central Pharmaceutical |
| Others |
Supply Flow & Price Mechanics
Captive API production at Mallinckrodt's St. Louis complex generates 40% unit cost advantages over import-dependent competitors, entrenching price floors that contract manufacturers in India and China struggle to undercut despite labor arbitrage. DEA quota scarcity amplifies this leverage by rationing volume to certified producers who command premium long-term offtake terms from OTP networks.
Pricing Analysis
Long-term offtake contracts dominate procurement between OTP networks and certified manufacturers, with three-year supply agreements locking in volume commitments against DEA allocation volatility. Price differentiation separates SAMHSA-accredited clinic supply from pain management tablet sales, with the former capturing 35% premiums through bundled compliance services. Pricing pressure stems from buprenorphine substitution in maintenance therapy, compressing methadone margins in United States metropolitan markets where prescriber flexibility has expanded. State Medicaid programs exhibit highest price sensitivity, while palliative care networks show lowest sensitivity due to limited therapeutic alternatives for neuropathic pain.
Supply Chain Analysis
Inventory lead times for Schedule II precursors stretch 90-120 days due to DEA import licensing queues, forcing manufacturers to carry elevated safety stock of 4,6-diphenyl-3-heptanone and dimethylaminochloropropane. API synthesis concentrates in the United States, United Kingdom, and China, with North American producers drawing 60% of intermediate feedstock from Yangtze River Delta chemical parks. Single-source vulnerability pervades chiral separation capacity, where Johnson Matthey's Royston facility anchors European levorotatory enantiomer supply. Distribution runs through DEA-registered narcotic treatment programs with vault infrastructure, bypassing conventional pharmaceutical wholesale channels entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Methadone manufacturing rewards regulatory entrenchment over operational excellence, with DEA licensing and SAMHSA accreditation creating switching costs that lock OTP networks into incumbent supplier relationships for decades.
For Market Incumbents: Secure chiral separation capacity additions in the United Kingdom before European competitors replicate Johnson Matthey's enantiomer purification expertise. Defend against buprenorphine substitution by embedding oral solution dosing protocols into OTP electronic health record systems, raising switching costs for clinic administrators contemplating formulary shifts. For New Entrants and Emerging Players: SAMHSA accreditation fast-tracks for telehealth-integrated OTP models represent the most penetrable entry vector, targeting rural United States counties with physician scarcity and relaxed patient caps. Pursue contract manufacturing partnerships with established DEA registrants rather than greenfield API investment, leveraging India's CDSCO compliance infrastructure for oral solution formulation while avoiding quota allocation battles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors controlled-substance synthesis contractors with established MHRA and FDA inspection histories over finished-dose marketers facing reimbursement compression. Acquisition targets should demonstrate five-to-ten year visibility through DEA quota renewals and SAMHSA accreditation portability across state lines. Watch state Medicaid reimbursement parity mandates as the signal indicating clinic profitability inflection and volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| DEA Quota Portfolio Expansion | Additional Schedule II manufacturing allocations from the DEA secure multi-year volume commitments from OTP networks. |
| Chiral Separation Capacity Investment | Levorotatory enantiomer purification capability commands 50% price premiums in pain management segments. |
| Telehealth-Integrated OTP Certification | SAMHSA guidance evolution enables remote patient intake, extending clinic reach into underserved rural counties. |
| State Medicaid Reimbursement Advocacy | Parity mandate campaigns in restrictive jurisdictions unlock patient access capacity and clinic profitability. |
| Controlled-Substance Security Infrastructure | DEA-mandated vault and tracking systems create fixed-cost barriers protecting incumbent positioning. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with addiction medicine physicians, OTP program directors, DEA regulatory consultants, and state Medicaid pharmacy directors; and secondary validation against FDA 483 inspection observations, SAMHSA accreditation databases, DEA aggregate production quota publications, and CMS Medicare/Medicaid utilization files. Bottom-up volume estimates from clinic-level dispensing data triangulated against top-down API production figures from import license records.
Across the analysis window, forecasts applied treatment-seeking population models segmented by opioid use disorder prevalence, pain management prescribing patterns, and regional regulatory cluster differentiation between OTP-supervised and retail pharmacy dispensing channels. CAGRs derived from historical volume trends adjusted for SAMHSA patient cap relaxations, buprenorphine substitution elasticity, and state Medicaid expansion timelines. Industry-specific inputs incorporated DEA quota allocation efficiency, chiral separation capacity utilization, and telehealth regulatory evolution.
Decision-makers should treat outputs as directional under assumptions of stable DEA quota policy and SAMHSA accreditation standards; material deviation in controlled-substance scheduling or reimbursement parity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Addiction Treatment
Global Addiction Treatment Market
Addiction Treatment
Alcohol Use Disorder Treatment Market
Addiction Treatment
Cocaine Intoxication Treatment Market
Addiction Treatment
US Mental Health and Addiction Treatment Centers Market
Addiction Treatment
Smokeless Tobacco Treatment Market
Addiction Treatment
Substance Abuse Treatment Market
Addiction Treatment
Drug Free Depression Treatment Market
Addiction Treatment
Opioid Induced Constipation Treatment Market
Addiction Treatment
Global Substance Use Disorder Treatment Market
Addiction Treatment
Nicotine De-Addiction Products Market
Addiction Treatment
Opioid Withdrawal Treatment Market
Addiction Treatment
Opioid Use Disorder (OUD) Market
Addiction Treatment
Opioid Use Disorder Treatment Market
Addiction Treatment
US Ketamine Clinics Market