
 Fluorapatite Market | 2026-2036
Fluorapatite Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorapatite Market Intelligence
Purity requirements for specialized applications versus bulk agricultural use is recalibrating the market's pricing structure. Major producers like OCP Group leverage vast phosphate rock reserves to control commodity-grade supply for fertilizers. The Mosaic Company competes on logistical strength and distribution networks across the Americas. In contrast, ICL Group Ltd. differentiates through its focus on specialty phosphate products for industrial and food-grade segments.
Fluorapatite is a hard, crystalline phosphate mineral with the chemical formula Ca5(PO4)3F. It serves as the primary industrial ore for producing phosphoric acid and elemental phosphorus. The fertilizer application, utilizing natural fluorapatite, constitutes the largest segment by volume for agricultural output. Higher-margin opportunities exist in technical and industrial grade materials for specialized uses in ceramics and glass manufacturing, where color and purity are critical.
Market access and production costs are shaped by stringent environmental regulations governing phosphate mining and processing, such as those enforced by the US EPA and China's MEE. In Europe, ECHA's REACH framework imposes strict registration and evaluation requirements on chemical substances, impacting imports and sales. Future profitability depends on producers' ability to manage compliance costs while meeting sustained agricultural demand for phosphate-based nutrients.
Market Dynamics
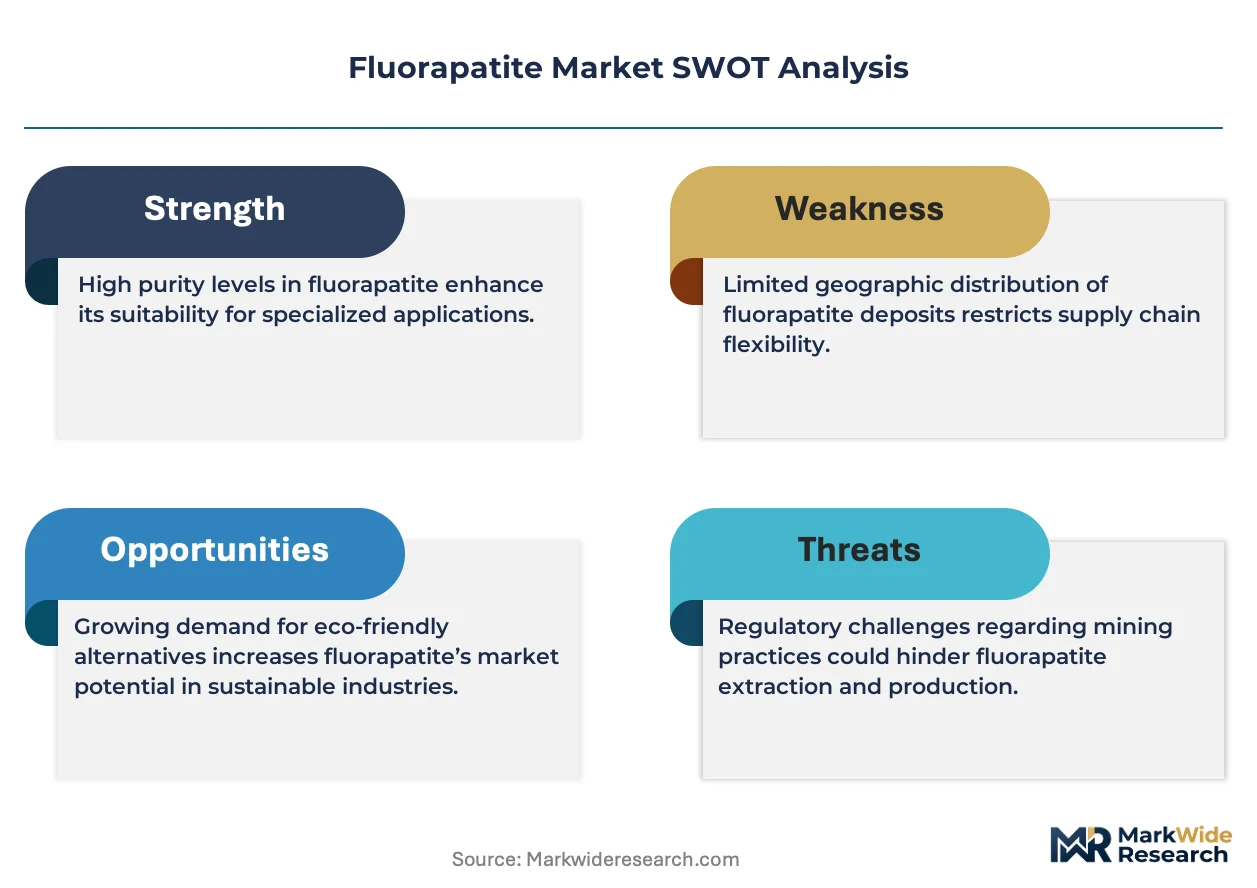
The fluorapatite market's structure is defined by the dual pressures of meeting immense agricultural demand for phosphate fertilizers and satisfying stringent purity specifications for industrial uses. Environmental regulations governing mining and processing, such as those from the US EPA, are increasing operational costs globally.
Growth Catalysts
- Agricultural Intensification:Persistent demand for phosphate fertilizers to support crop yields and ensure food security in populous regions of Asia and Africa acts as the primary volume driver for commodity-grade fluorapatite.
- Industrial Applications:The use of high-purity fluorapatite in the manufacturing of ceramics, specialty glass, and certain metal treatments provides higher-margin growth avenues beyond the dominant agricultural sector.
- Phosphoric Acid Production:As the principal ore for phosphoric acid, fluorapatite demand is directly tied to expansion in the broader chemical industry, including its use in food additives and detergents.
Market Restraints
- Environmental Regulations:Strict regulations on phosphate mining, such as water usage limits and land reclamation mandates enforced by China's MEE, increase compliance costs and can restrict production volumes.
- Geographic Concentration:The world's high-grade phosphate rock reserves are concentrated in a few countries, including Morocco and China, creating potential price volatility and supply chain risks for importing nations.
- Heavy Metal Contamination:Naturally occurring heavy metals like cadmium in some phosphate rock deposits require costly purification steps to meet safety standards for fertilizers and food-grade products, particularly in Europe.
Strategic Opportunities
- Circular Economy Integration:Developing technologies to recover and recycle phosphorus from wastewater, sewage sludge, and agricultural runoff offers a long-term opportunity to supplement mined fluorapatite and create a circular nutrient economy.
- Specialty Fertilizer Formulations:There is an opportunity to develop enhanced-efficiency fertilizers using purified fluorapatite that offer controlled nutrient release, reducing environmental impact and commanding premium prices.
- Biomaterial Applications:Research into using fluorapatite derivatives in biomedical applications, such as dental enamels and bone graft substitutes, represents a high-value frontier for highly purified material.
Industry Challenges
- Capital-Intensive Mining:The substantial capital investment required to develop new phosphate mines and construct beneficiation plants presents a high barrier to entry and constrains rapid supply expansion.
- Logistical Complexity:Managing the global transportation of a bulk commodity from mine sites to agricultural markets involves significant logistical costs and vulnerability to shipping disruptions.
- Compliance with Chemical Frameworks:Navigating the complex registration and authorization processes of chemical regulations like the EU's REACH for imports creates significant administrative and testing burdens for producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorapatite Market |
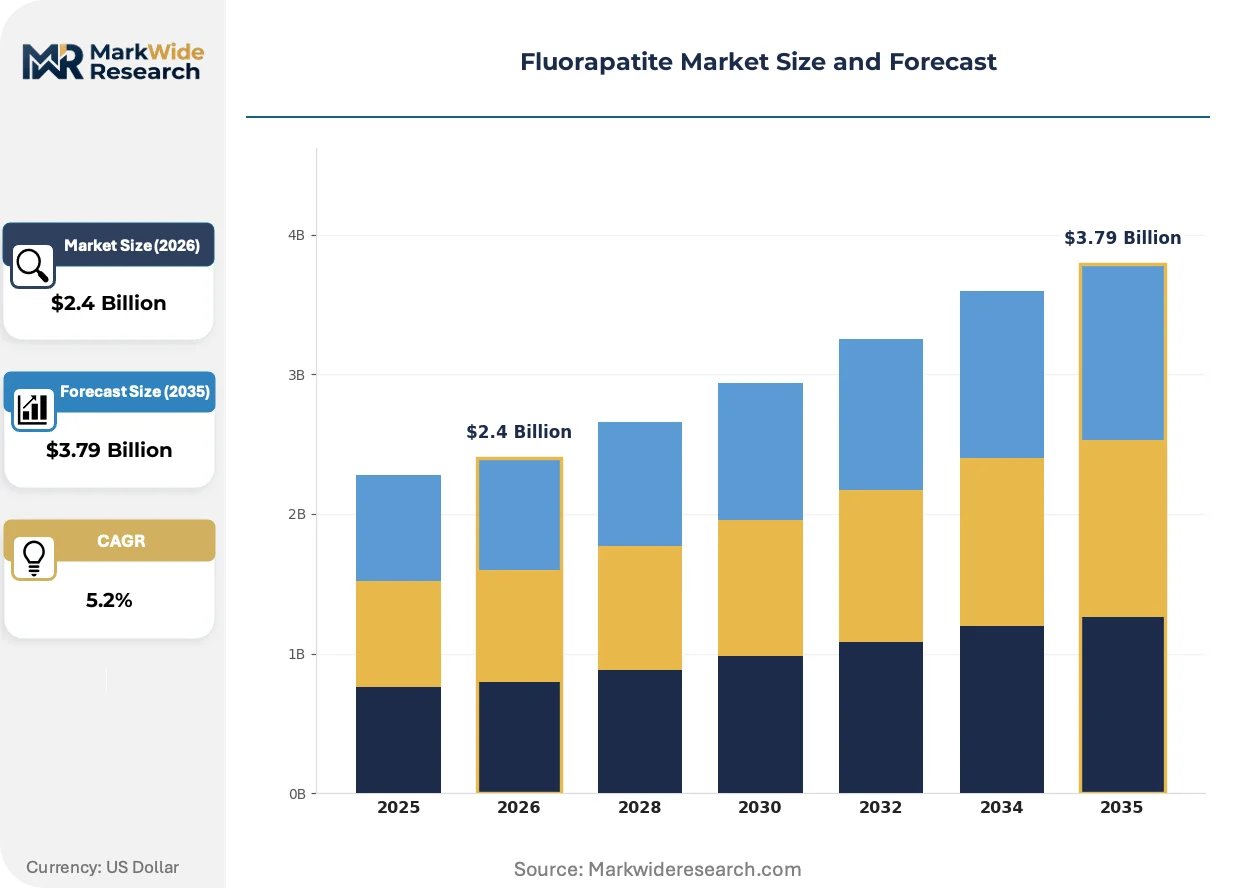
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Fluorapatite, Synthetic Fluorapatite, Fluorapatite Powder, Fluorapatite Granules Application: Ceramics, Fertilizers, Glass Manufacturing, Metallurgy End User: Agriculture, Construction, Electronics, Pharmaceuticals Grade: Technical Grade, Industrial Grade, Food Grade, Research Grade |
| Companies Covered | PhosAgro, Yuntianhua Group, The Mosaic Company, ICL Group Ltd., Maaden - Saudi Arabian Mining Company, OCP Group, Jordan Phosphate Mines Company, China Minmetals Corporation, Nutrien Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorapatite Market Strategic Shifts & Innovations
Technical advancements in ore processing are creating a clearer distinction between commodity and specialty grades. These innovations are occurring alongside evolving regulatory landscapes that prioritize material purity and supply chain transparency, particularly for products destined for agricultural and food-related applications.
Advanced beneficiation techniques, including multi-stage flotation and selective chemical leaching, are critical for removing impurities from raw phosphate ore. Manufacturers of technical-grade materials for ceramics and electronics rely on these processes to achieve stringent purity and color specifications. This technology, originally developed for niche industrial segments, is expanding into the production of premium fertilizers with lower concentrations of undesirable elements like cadmium.
The European Union's chemical safety framework, REACH, mandates extensive documentation for substances imported or manufactured in large quantities. This regulation forces non-EU fluorapatite producers to invest in comprehensive testing and data generation to prove material safety, directly affecting market access. The fertilizer segment is particularly impacted, as regulations on cadmium levels in phosphate fertilizers drive demand for purer, pre-qualified raw materials.
A notable shift in buying behavior is the increasing demand for traceability from farm to fork. This forces fertilizer manufacturers to provide documentation on the origin and composition of their raw materials, including fluorapatite. The trend is most pronounced in North American and European food systems, where retailers and food processors pass down sustainability and safety requirements to their agricultural suppliers.
Fluorapatite Market Segmentation
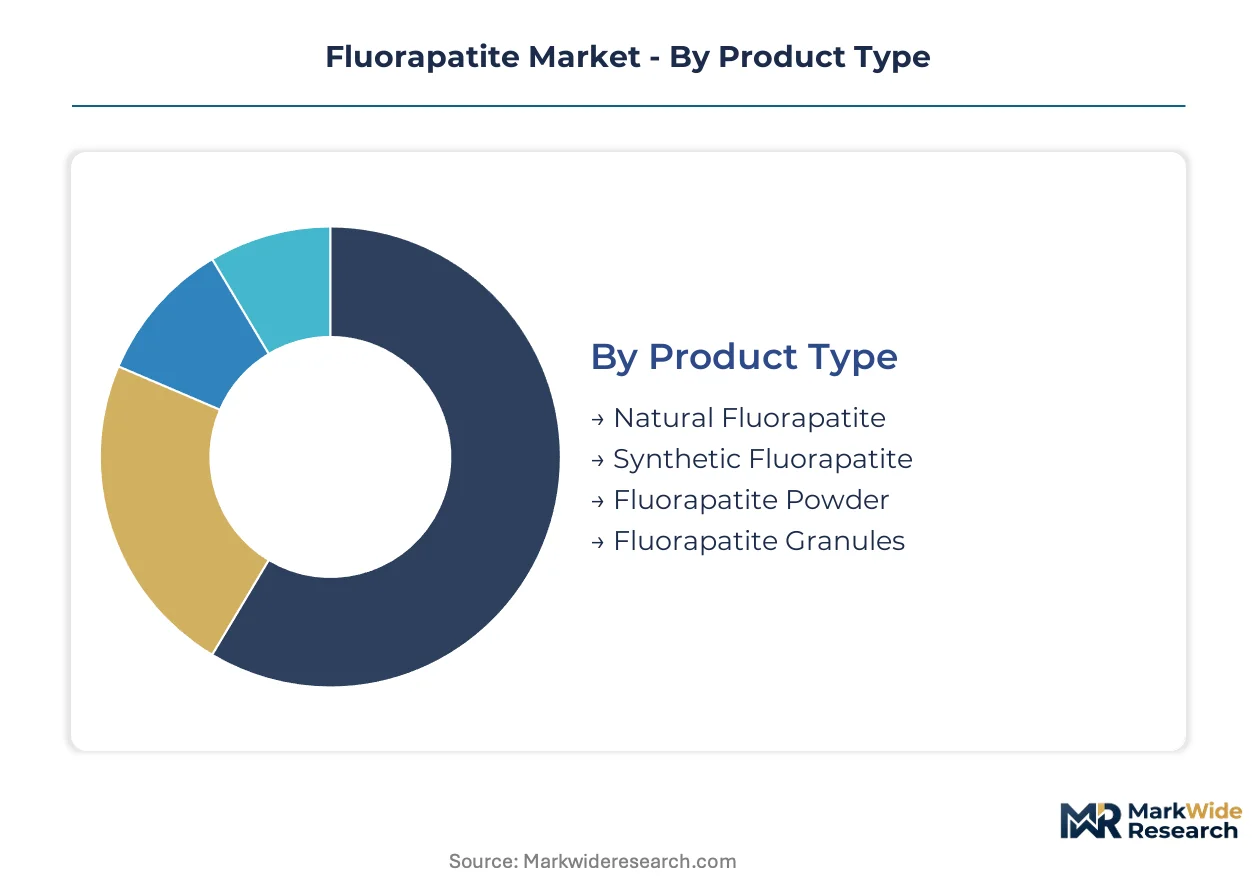
Segmentation of the fluorapatite market reveals distinct value propositions and regulatory compliance requirements across its various forms and applications. Understanding these segments is crucial for producers to align product offerings with specific industrial needs and market demands. The market's structure reflects diverse purity standards and end-use functionalities.
Product Type:
The product type segmentation highlights varying regulatory approval burdens, particularly for materials destined for sensitive applications like food and pharmaceuticals.
- Natural Fluorapatite:This mineral is directly mined and processed from phosphate rock, serving as the primary source for global phosphoric acid production. Demand concentrates in agricultural regions like China and India, driven by the immense need for phosphate fertilizers.
- Synthetic Fluorapatite:Manufactured under controlled laboratory conditions, this form offers superior purity and consistent crystalline structure compared to its natural counterpart. Its high-purity characteristics make it suitable for specialized applications in biomedical research and advanced material science.
- Fluorapatite Powder:This processed form is used across various industries, including ceramics and dental materials, requiring specific particle sizes for optimal performance.
- Fluorapatite Granules:Primarily utilized in the fertilizer sector, these granules ensure controlled nutrient release and ease of application in large-scale agricultural operations.
Leading the category by volume: Natural Fluorapatite. Growing fastest: Synthetic Fluorapatite.
Application:
Application segmentation reveals the diverse utility of fluorapatite, from high-volume agricultural inputs to niche industrial processes requiring specialized material properties.
- Ceramics:High-purity fluorapatite is critical in ceramic manufacturing for its thermal stability and unique optical properties, contributing to specialized technical ceramics. Demand in this segment focuses on material consistency and color neutrality.
- Fertilizers:This segment represents the largest volume consumption of fluorapatite, where the mineral is processed into phosphoric acid for nutrient-rich crop amendments. Persistent demand from Asia and Africa for food security drives this segment.
- Glass Manufacturing:Fluorapatite contributes to specialized glass formulations, enhancing properties like optical clarity and chemical resistance in high-performance glass products.
- Metallurgy:Used as a fluxing agent or in specific alloying processes, fluorapatite assists in refining metals and improving material characteristics in metallurgical operations.
The fertilizer application commands the largest share, while metallurgy applications are expanding due to their specialized requirements.
End User:
The end-user segmentation delineates distinct customer bases, each with specific requirements for fluorapatite's purity, form, and supply chain reliability.
- Agriculture:Farmers and large-scale agricultural enterprises constitute the primary end-users, relying on fluorapatite-derived fertilizers to enhance soil fertility and crop yields. This sector's demand is directly linked to global food production trends.
- Construction:Fluorapatite can be incorporated into certain construction materials for properties such as fire resistance or as a component in specialized cements.
- Electronics:High-purity fluorapatite finds use in advanced electronic components, such as phosphors in displays or as a dielectric material in sensitive devices.
- Pharmaceuticals:This high-value segment utilizes ultra-pure fluorapatite in biomedical applications, including bone substitutes and dental materials, where biocompatibility and precise chemical composition are paramount. Strict regulatory standards, such as those from the US FDA, govern material use.
Agriculture accounts for the bulk of consumption, with electronics and pharmaceuticals driving innovation in high-purity material requirements.
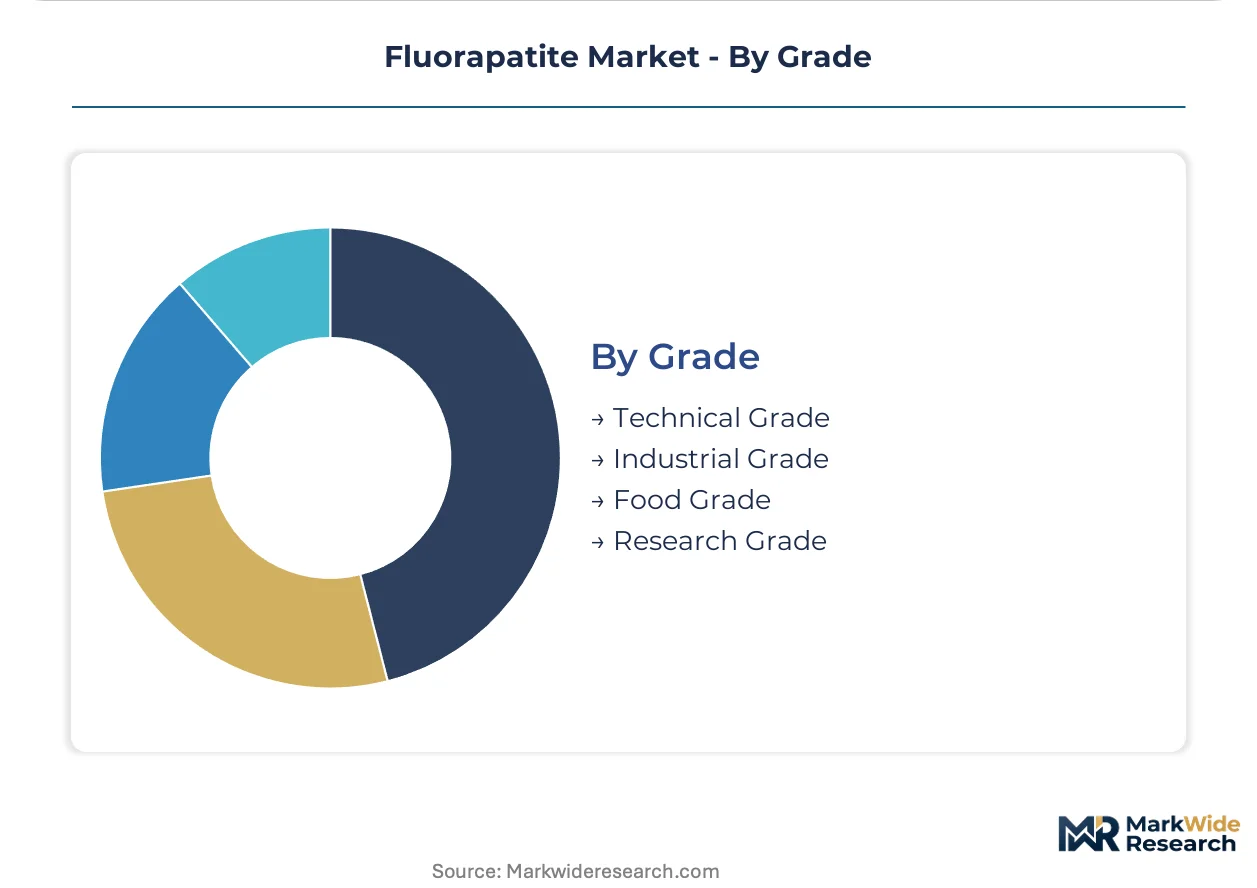
Grade:
Grade differentiation underscores the varying purity and processing demands across the fluorapatite market, influencing both production costs and market value.
- Technical Grade:Used in specialized industrial applications such as advanced ceramics and electronics, this grade requires precise chemical composition and particle size distribution. Manufacturers prioritize consistency and performance characteristics over sheer volume.
- Industrial Grade:This grade serves broad industrial applications, including general chemical manufacturing and certain metallurgical processes, where purity requirements are less stringent than for specialized uses.
- Food Grade:This segment demands the highest purity fluorapatite, free from heavy metal contaminants like cadmium, for use in food additives and supplements. Compliance with regulations from bodies like the EU's EFSA is essential for market access.
- Research Grade:Characterized by exceptional purity and precise specifications, this grade is exclusively used in scientific research and laboratory development for advanced material studies.
Industrial grade fluorapatite forms a foundational commodity, while research grade materials command premium pricing for scientific advancements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai, a key industrial hub, significantly influences the global fluorapatite market through its extensive chemical manufacturing and agricultural demand. China's central role in both mining and downstream fertilizer production establishes it as a primary driver. This concentration shapes global supply dynamics and pricing structures.
China
China's vast agricultural sector drives substantial demand for phosphate fertilizers, making it a critical consumer of fluorapatite. The Ministry of Ecology and Environment (MEE) enforces stringent environmental regulations on phosphate mining and processing. Industrial clusters in Sichuan and Yunnan provinces concentrate large-scale fluorapatite mining and phosphoric acid production for domestic and export markets.
Morocco
Morocco commands significant global fluorapatite supply due to its immense phosphate rock reserves, primarily serving the fertilizer industry. The country's regulatory framework supports large-scale mining operations and export-oriented processing. The OCP Group, centered in Khouribga, leverages these reserves to control a substantial portion of the world's commodity-grade supply.
United States
Agricultural demand for phosphate fertilizers across the Midwest states sustains a consistent need for fluorapatite imports and domestic production. The US Environmental Protection Agency (EPA) regulates phosphate mining and processing, influencing operational costs and material purity. Florida's Bone Valley region remains a key area for phosphate rock extraction and fertilizer manufacturing operations.
India
India's rapidly expanding agricultural sector and food security initiatives fuel substantial fluorapatite consumption for fertilizer production. The Fertilizer Control Order (FCO) sets quality standards for phosphate fertilizers, impacting raw material sourcing. Gujarat and Maharashtra host major fertilizer complexes, processing imported and domestic fluorapatite into agricultural inputs.
Fluorapatite Market Key Industry Players
Premium-margin players sit above commodity-margin players across the fluorapatite market, driven by varying purity requirements and application specificities. The market structure exhibits a tiered consolidation, with a few large integrated producers dominating bulk supply. Strategic archetypes include resource-rich vertically integrated giants and specialized processors focusing on high-purity materials. Dominant competitive moves involve capacity expansion in key mining regions and strategic partnerships for downstream processing.
On the premium-tier vector, ICL Group Ltd. exemplifies a focus on specialty phosphate products, serving industrial and food-grade segments where purity and consistent chemical composition are paramount. The Mosaic Company, an American corporation, competes on logistical strength and extensive distribution networks across the Americas, primarily for commodity-grade fertilizers destined for large-scale agricultural operations. OCP Group, a Moroccan state-owned enterprise, anchors the global commodity-grade supply through its vast phosphate rock reserves and integrated operations, controlling a significant portion of the primary raw material for phosphoric acid production.
| Leading Market Players |
|---|
| PhosAgro |
| Yuntianhua Group |
| The Mosaic Company |
| ICL Group Ltd. |
| Maaden - Saudi Arabian Mining Company |
| OCP Group |
| Jordan Phosphate Mines Company |
| China Minmetals Corporation |
| Nutrien Ltd. |
| Others |
Cost & Logistics Intelligence
Skilled labor concentrations in phosphate mining regions, particularly Morocco and China, create distinct labor-cost differentials influencing pricing spreads across commodity and specialty fluorapatite grades. These regional structures contribute to the market's tiered pricing dynamics.
Pricing Analysis
Yield-based pricing anchors commodity-grade fluorapatite, where its value is tied directly to agricultural output and fertilizer efficacy. The market primarily operates on a commodity spot and long-term contract-based offtake model. Price differentiation stems from stringent purity requirements for food-grade and pharmaceutical applications, contrasting with volume scale for agricultural use. Pricing softness affects industrial grade materials due to vast reserves, while specialty grades command premium pricing. Agricultural end-users exhibit the highest price sensitivity, whereas the pharmaceuticals sector shows the least.
Supply Chain Analysis
Reverse logistics for fluorapatite primarily involves managing byproducts from phosphoric acid production, though direct material returns are minimal due to its commodity nature. Global supply concentration centers on Morocco, China, and the United States, which possess significant phosphate rock reserves. The entire supply chain relies on the consistent extraction and processing of this primary raw material. Regulatory restrictions, particularly regarding heavy metal content like cadmium, pose a significant supply chain risk for European imports. Distribution runs through bulk shipping networks from mining regions to agricultural and industrial processing hubs globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fluorapatite market is fundamentally a cost-of-compliance story, where stringent environmental regulations and purity standards dictate market access and profitability. The EU's REACH framework, for instance, creates a significant barrier-to-entry moat for non-compliant producers.
For Market Incumbents:Hedge against increasing regulatory pressure and commodity price volatility by investing in advanced beneficiation technologies to reduce impurities like cadmium. Diversify end-use applications beyond bulk fertilizers into higher-margin technical and food-grade segments. Vertical integration into specialty processing provides greater control over material quality and market access. This strategy mitigates the threat of stricter cadmium contamination limits in key agricultural markets.
For New Entrants and Emerging Players:Advanced phosphorus recovery technologies from wastewater and sewage sludge offer a technology-first wedge for new entrants. Target underpenetrated biomaterial applications, such as dental enamels and bone graft substitutes, which require ultra-high purity materials. The most penetrable segment remains high-purity synthetic fluorapatite for niche medical uses. A strong go-to-market angle involves collaboration with research institutions and specialized medical device manufacturers.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized fluorapatite processors given their ability to meet stringent purity requirements and command premium pricing. The market's long-term viability remains strong, driven by persistent demand for food security and high-tech industrial applications. Acquisition targets should focus on companies with proprietary purification technologies and established market access in food-grade or biomedical segments. Investors should monitor increased M&A activity in the specialty phosphate sector as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Morocco | Secures raw material supply for OCP Group and stabilizes global commodity prices. |
| Advanced Beneficiation Technology Investment | Enables production of high-purity fluorapatite for ICL Group Ltd.'s specialty segments. |
| Phosphorus Recovery from Wastewater | Supports circular economy goals and reduces reliance on mined phosphate rock. |
| Compliance Certification (REACH/FDA) | Ensures market access for fluorapatite products in European and US markets. |
| R&D Partnership for Biomaterials | Unlocks new high-value applications for synthetic fluorapatite in medical devices. |
Research Approach
Independent corroboration across US EPA reports, China MEE disclosures, and ECHA REACH documentation underwrites the qualitative findings derived from extensive primary interviews. This approach combined insights from mine operators, fertilizer manufacturers, specialty chemical producers, and agricultural procurement managers. Bottom-up data collection from industry participants was triangulated with top-down market sizing and validation from regulatory bodies. This method ensured robust data integrity.
The forecast window was anchored to multiple historical reference periods, establishing baseline market performance and growth trajectories. The analytical framework modeled segmentation dimensions: product type, application, end-user, grade, and regional production capacity. Compound Annual Growth Rates were extrapolated from historical growth rates and projected market dynamics. Phosphate rock extraction volumes and global fertilizer consumption trends served as key forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen geopolitical shifts impacting trade routes or rapid technological breakthroughs in phosphorus recycling. Forecasts reflect assumptions regarding regulatory stability and agricultural demand patterns across the analysis window. Practitioners should monitor major policy changes and new extraction technologies for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
LAMEA Astrology Market
Others
Manometers Market
Others
Calcined Petroleum Coke Market
Others
Global Surface Analysis Market
Others
Spend Analytics Market
Others
Android STB and TV Market
Others
Signal Transformer Market
Others
Global Tobacco Market
Others
One-Way Degassing Valve Market
Others
Folding Screen Mobile Phone Market
Others
Global Platform Trolley Market
Others
Space Power Supply Market
Others
Augmented Shopping Market
Others
Cremation Furnace Market
Others
Dried Egg Market
Others
Edible Insects for Animal Feed Market