
 Asia-Pacific IVD Regulatory Affairs Outsourcing Market | 2026-2036
Asia-Pacific IVD Regulatory Affairs Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
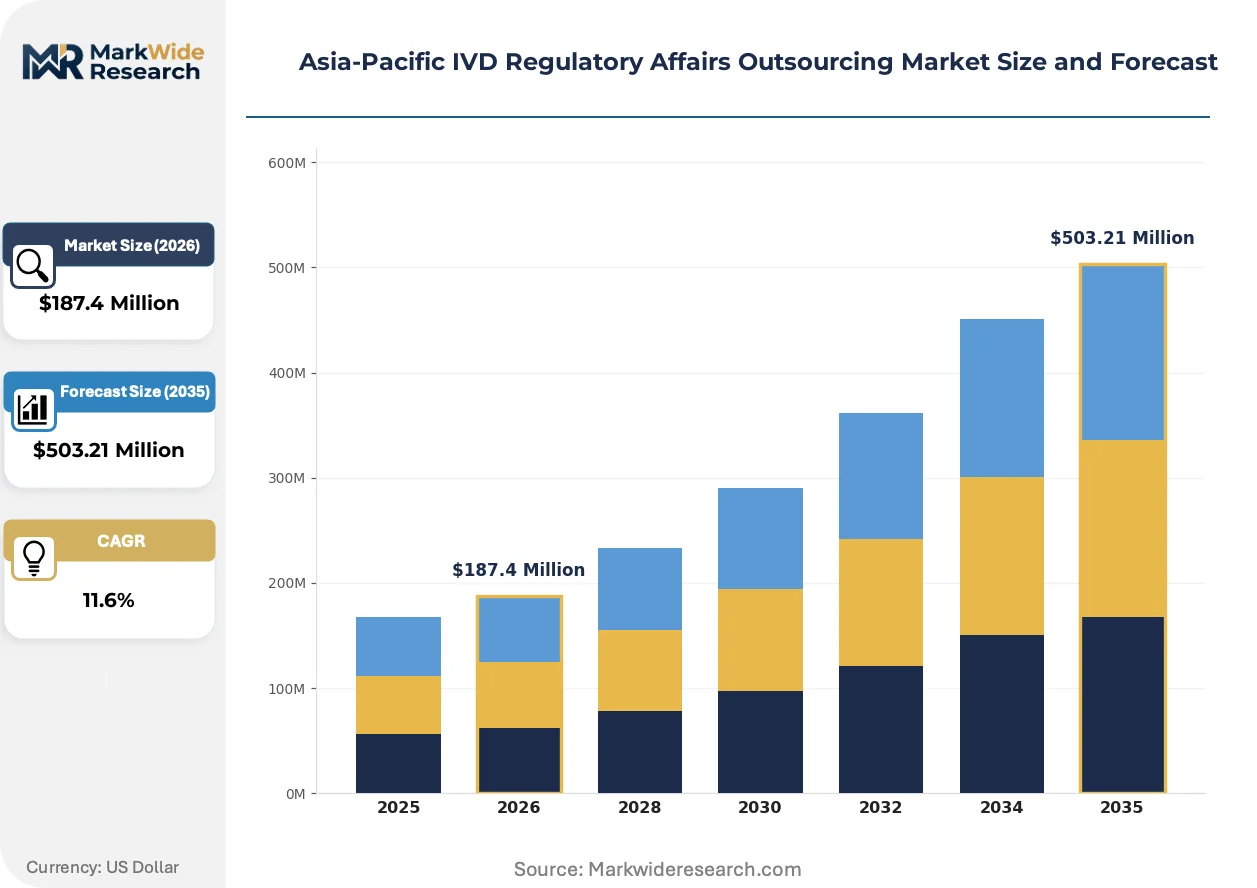
Asia-Pacific IVD Regulatory Affairs Outsourcing Market Outlook
ISO 13485 certification cycles are reorganizing competitive standing across the Asia-Pacific IVD regulatory outsourcing landscape, forcing service providers to demonstrate quality management system mastery before securing pharmaceutical company contracts. Charles River Laboratories leverages its established footprint in toxicology and regulatory consulting to anchor complex submission portfolios across Japan and Australia. WuXi AppTec competes through integrated laboratory-to-filing workflows that compress development timelines for domestic Chinese manufacturers. ICON PLC differentiates via therapeutic-area specialization in oncology diagnostics, where PMDA and TGA evidentiary standards converge.
Asia-Pacific IVD regulatory affairs outsourcing encompasses the delegation of compliance strategy, dossier preparation, quality system maintenance, and authority negotiation to third-party specialists who bridge linguistic, technical, and procedural gaps between manufacturers and national regulators. The practice requires mastery of device classification protocols, clinical performance study designs, and post-market surveillance reporting formats that vary across jurisdictions. Regulatory submission services command disproportionate margin pools as NMPA and CDSCO expand requirements for local clinical data in Class II and III diagnostic approvals. Quality assurance segments sustain steadier retainer relationships with medical device manufacturers who must maintain ISO 13485 and MDSAP certifications across multiple production sites. Consulting engagements for diagnostic laboratories are accelerating fastest as hospital networks and reference labs develop in-house IVD portfolios and confront unfamiliar regulatory terrain.
Japan's PMDA, China's NMPA, and India's CDSCO each enforce distinct evidentiary standards for IVD registration, creating fragmented compliance burdens that drive pharmaceutical companies and biotechnology firms toward specialized outsourcing partners with multi-jurisdictional capabilities. Australia's TGA alignment with EU MDR through its own therapeutic goods framework adds another certification layer for manufacturers targeting trans-Tasman markets. Stakeholders must monitor convergence between ASEAN harmonization initiatives and national sovereignty over clinical data requirements, as this tension will determine whether regional outsourcing platforms can achieve scale or remain trapped in country-specific service configurations.
Market Dynamics
CDSCO and NMPA are synchronously tightening local clinical evidence mandates for Class II and III diagnostic registrations, forcing domestic manufacturers across India and China to outsource complex dossier preparation rather than build captive regulatory capabilities.
Growth Catalysts
- CDSCO Local Clinical Data Mandates:India's tightened evidentiary requirements for IVD approvals are compelling domestic manufacturers to engage specialized regulatory partners capable of designing India-specific clinical performance studies and navigating authority negotiations.
- Biotechnology Firm Expansion:Southeast Asian biotech companies developing in-house IVD portfolios are accelerating their reliance on external regulatory submission services as they confront unfamiliar compliance terrain across multiple jurisdictions.
- ISO 13485 Certification Pressure:Quality management system mastery has become a non-negotiable contract threshold, with service providers reorganizing competitive standing through accelerated certification cycles and MDSAP scope expansion.
Market Restraints
- Regulatory Fragmentation Across ASEAN:Persistent divergence between national sovereignty over clinical data requirements and harmonization initiatives traps outsourcing platforms in country-specific service configurations, limiting scale economies.
- Specialized Talent Scarcity:The shallow pool of professionals fluent in both technical diagnostic science and multi-jurisdictional regulatory prose concentrates expertise in high-cost metropolitan hubs across Shanghai, Mumbai, and Tokyo.
- Prolonged Certification Timelines:PMDA and TGA evidentiary review cycles for novel oncology diagnostics extend engagement durations, compressing working capital efficiency for mid-sized service providers.
Strategic Opportunities
- Hospital Network Laboratory Vertical:Diagnostic laboratories within hospital networks across Thailand and Vietnam are developing proprietary IVD portfolios, creating demand for first-time regulatory navigation services from outsourcing specialists.
- Post-Market Surveillance Outsourcing:NMPA and CDSCO expansion of vigilance reporting requirements opens retainer-based revenue streams for quality assurance segments capable of managing multi-site ISO 13485 maintenance.
- TGA-EU MDR Alignment:Australia's therapeutic goods framework convergence with European standards enables regulatory service providers to leverage existing EU dossier structures for trans-Tasman market entry, reducing marginal preparation costs.
Industry Challenges
- Multi-Jurisdictional Dossier Complexity:Regulatory professionals must simultaneously master PMDA's pharmaceutical-informed review culture, NMPA's GB standards alignment, and CDSCO's evolving classification protocols, stretching training investments.
- Legacy Quality System Integration:Domestic Chinese and Indian manufacturers often operate entrenched production documentation practices that conflict with MDSAP audit expectations, requiring intensive remediation before certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific IVD Regulatory Affairs Outsourcing Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Compliance, Regulatory Submission, Quality Assurance End User: Diagnostic Laboratories, Pharmaceutical Companies, Medical Device Manufacturers, Biotechnology Firms Delivery Model: Onshore, Offshore, Hybrid, Outsourced Engagement Type: Project-Based, Retainer, Time & Materials, Dedicated Team |
| Companies Covered | Charles River Laboratories, ICON PLC, WuXi AppTec, Indegene, Tilleke & Gibbins International Ltd., EMERGO by UL, Freyr, MakroCare, SeerPharma, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific IVD Regulatory Affairs Outsourcing Market Strategic Shifts
Regulatory technology deployment and authority digitalization are compressing submission preparation cycles while simultaneously elevating data integrity standards across the Asia-Pacific IVD compliance landscape.
Artificial intelligence-enabled regulatory intelligence platforms are bifurcating the competitive landscape between high-volume submission factories and boutique therapeutic-area specialists. Large service providers deploy natural language processing to automate predicate device searches and adverse event signal detection across PMDA and NMPA databases. Mid-tier domestic Chinese CROs without comparable technology infrastructure are retreating toward commodity dossier formatting, ceding complex oncology and companion diagnostic portfolios to technology-enabled competitors.
NMPA's 2024 implementation of electronic submission gateways and real-time query response protocols is compressing review timelines for well-prepared applications while accelerating rejection cycles for deficient filings. Domestic Chinese manufacturers with established regulatory affairs partnerships are reallocating resources toward clinical trial design rather than administrative navigation. Foreign manufacturers without local regulatory presence face escalating barriers to direct authority engagement, reinforcing demand for outsourced in-country representation.
Diagnostic developers across South Korea and Australia are unbundling regulatory strategy from full-service CRO relationships, engaging specialized regulatory boutiques for initial classification and pathway selection before transferring execution to larger providers. This disintermediation reflects procurement sophistication among mid-cap biotechnology firms seeking to optimize fee structures across the development continuum. The trend concentrates in oncology diagnostics where PMDA and TGA evidentiary convergence enables modular service procurement without sacrificing submission quality.
Asia-Pacific IVD Regulatory Affairs Outsourcing Market Segmentation
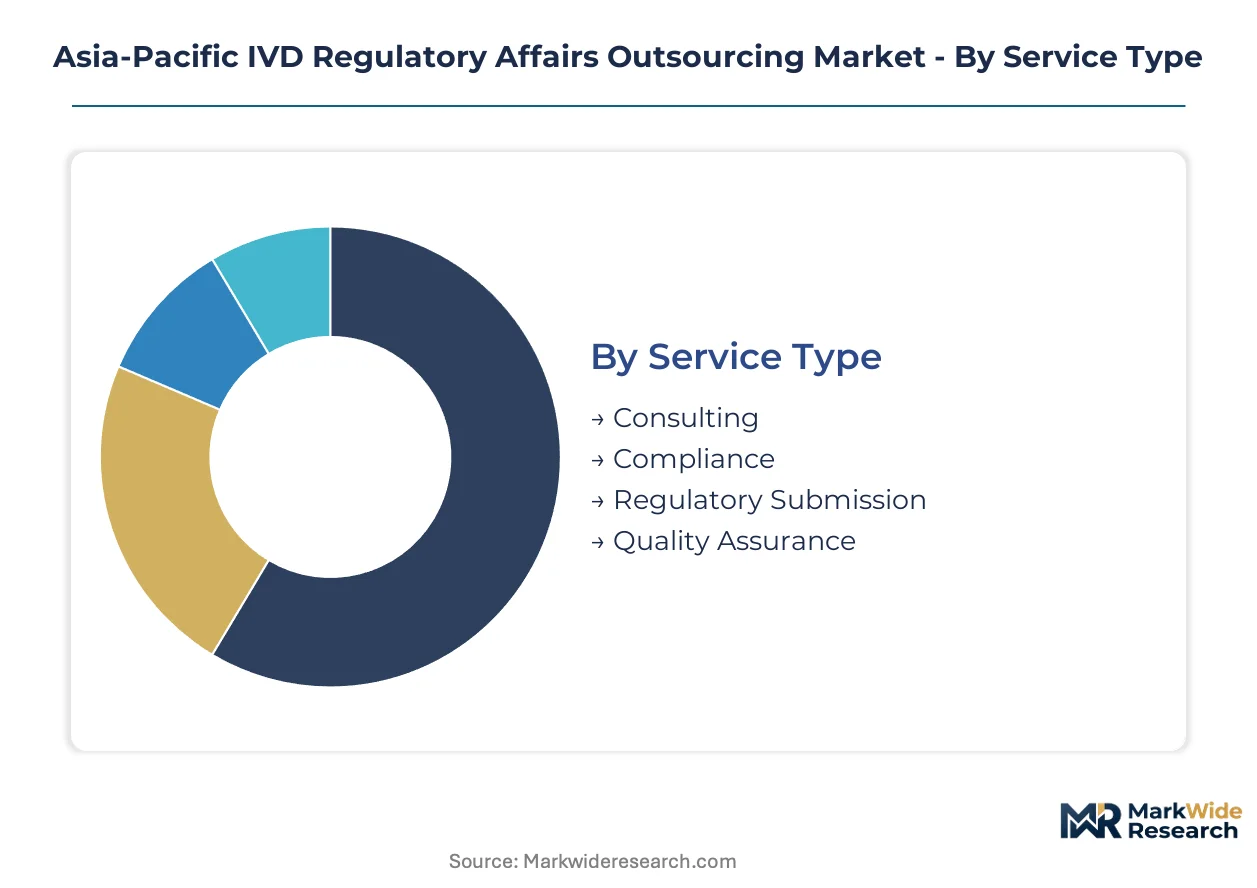
Segmentation in the Asia-Pacific IVD regulatory affairs outsourcing market reveals how service specialization aligns with divergent compliance burdens across NMPA, CDSCO, and PMDA jurisdictions. Each dimension captures distinct procurement patterns that separate high-margin advisory work from commoditized documentation support.
Service Type:
Regulatory differentiation across PMDA's pharmaceutical-informed review culture, NMPA's GB standards alignment, and CDSCO's evolving classification protocols creates tiered margin structures within each service category.
- Regulatory Submission:Complex dossier preparation for Class II and III diagnostic approvals commands premium pricing as NMPA and CDSCO expand local clinical data mandates. Demand concentrates among domestic Chinese and Indian manufacturers seeking outsourced expertise to navigate multi-market approval pathways rather than build captive regulatory capabilities.
- Quality Assurance:ISO 13485 certification maintenance and MDSAP scope expansion sustain steadier retainer relationships with medical device manufacturers operating multiple production sites. Hospital networks across Thailand and Vietnam developing proprietary IVD portfolios drive emerging demand for first-time quality system implementation.
- Consulting:Strategic pathway selection and classification advisory for novel oncology diagnostics and companion diagnostics.
- Compliance:Ongoing vigilance reporting and post-market surveillance management for multi-site operations.
Established volume favors Quality Assurance; emerging adoption favors Regulatory Submission.
End User:
Customer type determines contract duration and procurement sophistication, with biotechnology firms disaggregating regulatory strategy from full-service CRO relationships.
- Biotechnology Firms:Southeast Asian biotech companies developing in-house IVD portfolios accelerate reliance on external regulatory submission services as they confront unfamiliar compliance terrain across multiple jurisdictions. Modular procurement of initial classification and pathway selection reflects growing sophistication among mid-cap developers.
- Diagnostic Laboratories:Hospital networks and reference labs across Thailand and Vietnam developing proprietary IVD portfolios create demand for first-time regulatory navigation services. This segment is climbing the fastest as laboratory medicine groups expand beyond reagent supply into instrument and software registration.
- Medical Device Manufacturers:Established producers seeking multi-jurisdictional ISO 13485 maintenance and MDSAP certification.
- Pharmaceutical Companies:Drug developers extending into companion diagnostics requiring therapeutic-area regulatory specialization.
Procurement maturity separates Biotechnology Firms from Diagnostic Laboratories; contract scale differentiates Medical Device Manufacturers from Pharmaceutical Companies.
Delivery Model:
Geographic deployment of regulatory personnel shapes cost structures and authority engagement effectiveness across fragmented Asia-Pacific compliance environments.
- Hybrid:Blended onshore-offshore teams balance cost efficiency with mandatory in-country representation for NMPA and CDSCO authority negotiations. Domestic Chinese manufacturers with established regulatory partnerships leverage hybrid structures to reallocate resources toward clinical trial design.
- Onshore:Full in-country presence enables direct PMDA and TGA engagement but concentrates expertise in high-cost metropolitan hubs across Shanghai, Mumbai, and Tokyo.
- Offshore:Remote documentation preparation and dossier formatting from lower-cost locations.
- Outsourced:Complete delegation to third-party specialists with end-to-end accountability.
Cost optimization favors Offshore; regulatory effectiveness favors Onshore; Hybrid captures expanding share.
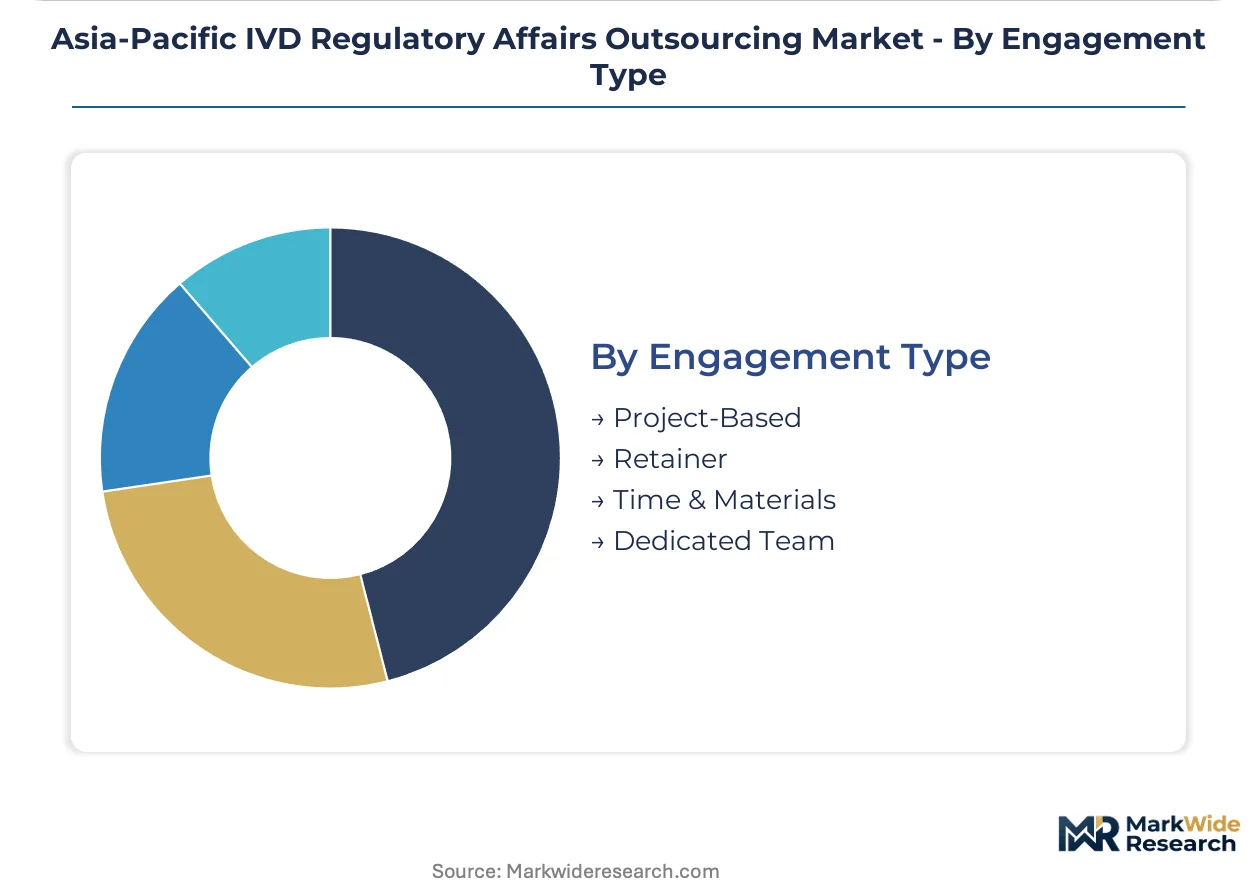
Engagement Type:
Contract structure reflects uncertainty in certification timelines and the shift from administrative navigation toward clinical evidence generation.
- Retainer:Steady monthly fees for ongoing quality system maintenance and post-market surveillance reporting as NMPA and CDSCO expand vigilance requirements. Medical device manufacturers with multi-site ISO 13485 certification needs favor this structure for budget predictability.
- Project-Based:Fixed-scope engagements for discrete submission milestones suit biotechnology firms with defined development timelines.
- Dedicated Team:Embedded personnel for complex multi-jurisdictional portfolios.
- Time & Materials:Flexible billing for unpredictable remediation and authority query response.
Revenue stability favors Retainer; flexibility favors Project-Based; complexity favors Dedicated Team.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO's tightened clinical evidence mandates and NMPA's electronic submission gateways are redrawing procurement patterns across the Asia-Pacific IVD regulatory outsourcing landscape. Domestic manufacturers in India and China now face steeper compliance burdens that favor external specialist engagement over captive capability building. Service providers with multi-jurisdictional footprints capture disproportionate contract flow as biotechnology firms expand across Southeast Asia.
India
Domestic diagnostic manufacturers confront CDSCO's expanded local clinical data requirements for Class II and III device registrations. The regulator's 2024 evidentiary protocols compel outsourcing of India-specific clinical performance study design and authority negotiation. Mumbai and Bangalore clusters concentrate regulatory service demand as biotech firms develop companion diagnostic portfolios.
China
NMPA's real-time query response protocols and GB standards alignment create bifurcated outcomes for prepared versus deficient submissions. Shanghai-based service providers leverage hybrid onshore-offshore teams to compress development timelines for domestic manufacturers. The Yangtze River Delta anchors the highest concentration of regulatory technology deployment and electronic dossier preparation capacity.
Japan
PMDA's pharmaceutical-informed review culture demands specialized expertise in oncology diagnostic evidentiary standards. Tokyo's regulatory consulting clusters serve foreign manufacturers seeking direct authority engagement without establishing captive Japanese regulatory affairs functions. The convergence of PMDA and TGA standards for companion diagnostics enables modular service procurement from regional specialists.
Australia
TGA's therapeutic goods framework alignment with EU MDR standards allows regulatory service providers to repurpose existing European dossier structures for trans-Tasman market entry. Sydney and Melbourne clusters attract outsourcing demand from Asia-Pacific manufacturers seeking streamlined certification for English-speaking markets. The regulator's vigilance reporting expansion sustains retainer-based revenue for quality assurance segments.
South Korea
MFDS evidentiary standards for novel diagnostics drive demand for specialized regulatory pathway selection before execution handoff to larger CROs. Seoul Capital Area biotechnology firms disaggregate regulatory strategy from full-service relationships, engaging boutiques for initial classification. Domestic manufacturers developing in-house IVD portfolios accelerate first-time regulatory navigation service procurement.
Asia-Pacific IVD Regulatory Affairs Outsourcing Market Competitive Environment
Player mix skews toward integrated CROs with regulatory consulting arms and specialized quality assurance boutiques. Market structure concentrates around three archetypes: global laboratory services firms with regulatory submission capabilities, Asia-Pacific-native CROs with authority relationship depth, and regulatory technology-enabled documentation specialists. Consolidation pressure favors providers with multi-jurisdictional ISO 13485 certification maintenance capacity. Strategic moves center on M&A to capture hospital network laboratory verticals and technology licensing to automate predicate device searches.
Within the integrated laboratory services tier, Charles River Laboratories anchors complex submission portfolios across Japan and Australia through its toxicology and regulatory consulting footprint. WuXi AppTec occupies a position exemplifying laboratory-to-filing workflow integration that compresses timelines for domestic Chinese manufacturers. ICON PLC represents therapeutic-area specialization in oncology diagnostics where PMDA and TGA evidentiary standards converge. These three entities illustrate how geographic origin and service architecture shape competitive positioning without determining specific market share outcomes.
| Leading Market Players |
|---|
| Charles River Laboratories |
| ICON PLC |
| WuXi AppTec |
| Indegene |
| Tilleke & Gibbins International Ltd. |
| EMERGO by UL |
| Freyr |
| MakroCare |
| SeerPharma |
| Others |
Value Chain & Pricing Dynamics
Ninety-to-one-hundred-twenty-day dossier preparation cycles concentrate regulatory talent in Shanghai, Mumbai, and Tokyo metropolitan hubs, compressing margin structures for mid-tier providers while amplifying pricing power for multi-jurisdictional specialists with established NMPA and CDSCO authority relationships.
Pricing Analysis
Cost-plus contracts with annual labor indexation dominate retainer-based quality assurance engagements, while project-based regulatory submission work commands premium pricing tied to certification complexity and therapeutic area specialization. Price differentiation separates ISO 13485-certified MDSAP specialists from commodity documentation providers, with oncology diagnostic expertise capturing the widest spreads. Pricing pressure stems from NMPA's electronic submission gateways accelerating rejection cycles for deficient filings, forcing providers to absorb remediation costs. Biotechnology firms exhibit highest price sensitivity for initial classification advisory, while pharmaceutical companies pay least attention to fee structures for companion diagnostic portfolios.
Supply Chain Analysis
Shanghai-Singapore regulatory talent corridors constitute the primary chokepoint for multi-jurisdictional service delivery, with authority negotiation capabilities bottlenecking through limited Mandarin-fluent professionals with PMDA exposure. Service delivery draws from India for clinical performance study design, China for GB standards alignment, and Japan for pharmaceutical-informed review culture. Raw material dependencies include regulatory technology platforms, predicate device databases, and adverse event signal detection systems. Single-source vulnerability concentrates in hybrid onshore-offshore team architectures where in-country representation cannot be replicated remotely. Distribution runs through direct pharmaceutical company procurement teams, biotechnology firm development alliances, and hospital network laboratory verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates formidable switching costs—manufacturers cannot readily transfer partially completed NMPA or CDSCO submissions without losing authority relationship continuity and dossier preparation momentum.
For Market Incumbents: Consolidate multi-jurisdictional ISO 13485 certification maintenance capacity through targeted capability acquisition in Vietnam and Thailand hospital network laboratory verticals. Deepen vertical integration into regulatory technology platforms to automate predicate device searches and compress dossier preparation timelines. Threat of AI-enabled documentation specialists commoditizing formatting work makes technology infrastructure the priority lever for margin defense. For New Entrants and Emerging Players: Lead with specialized oncology diagnostic advisory for South Korean biotechnology firms disaggregating regulatory strategy from full-service CRO relationships. Hospital network laboratories across Thailand and Vietnam developing proprietary IVD portfolios represent the most penetrable segment, with first-time quality system implementation demand outpacing established provider capacity. Go-to-market angle should emphasize modular pathway selection engagements before execution handoff. For Investors and Strategic Acquirers: Carve-out targets emerge from global laboratory services firms seeking to divest non-core regulatory consulting arms lacking therapeutic-area depth. Long-term viability favors providers with demonstrated PMDA-TGA evidentiary convergence capabilities and established NMPA electronic submission gateway proficiency. Signal to watch is CDSCO implementation of ASEAN harmonization protocols, which would revalue country-specific service configurations toward regional platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Platform Acquisition | Automates predicate device searches across NMPA and PMDA databases, compressing preparation timelines for complex oncology submissions. |
| Hospital Network Laboratory Vertical Expansion | Captures first-time ISO 13485 implementation demand from Thailand and Vietnam diagnostic laboratories developing proprietary IVD portfolios. |
| Multi-Jurisdictional Certification Maintenance | Secures retainer-based revenue stability as CDSCO and NMPA expand post-market surveillance reporting requirements across multiple production sites. |
| Therapeutic-Area Specialization Deepening | Builds defensible positioning in companion diagnostics where PMDA and TGA evidentiary standards converge, enabling premium pricing. |
| Hybrid Delivery Model Infrastructure | Balances cost efficiency through offshore documentation preparation with mandatory in-country representation for NMPA authority negotiations. |
Study Parameters
The analysis maps regulatory submission services, quality assurance, consulting, and compliance segments, each validated through regulatory affairs directors, biotechnology firm development executives, hospital laboratory medicine group leaders, and medical device manufacturer quality system managers. Primary interview findings triangulated against NMPA electronic submission gateway protocols, CDSCO clinical evidence guidelines, PMDA review culture documentation, and TGA therapeutic goods framework alignment with EU MDR. Bottom-up service provider capacity assessments and top-down procurement pattern analysis converged through cross-validation.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include service type, end user category, delivery model architecture, and engagement structure. CAGRs derived from regulatory filing volume trajectories, certification maintenance contract renewal rates, and biotechnology firm IVD portfolio expansion patterns. Forecast inputs incorporated NMPA real-time query response protocol adoption curves and CDSCO local clinical data mandate implementation timelines.
Forecasts assume regulatory continuity in NMPA, CDSCO, and PMDA evidentiary standards; material policy shifts toward ASEAN harmonization or divergent clinical data requirements would necessitate re-modeling. Scenario boundaries exclude black-swan regulatory discontinuities and technology disruption beyond natural language processing automation currently deployed. Practitioners should keep alternative scenarios live as ASEAN harmonization initiatives and national sovereignty tensions over clinical data requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Wood Stoves Market
Others
Over the Top Devices and Services Market
Others
Electrical Calibration Equipment Market
Others
Palatants Market
Others
Europe Meditation Market
Others
Global Cosmetovigilance Market
Others
Europe Transportation Management Systems Market
Others
Cellular-Connected Laptops Market
Others
Android STB and TV Market
Others
Thiamethoxam Market
Others
Global Maritime Freight Transport Market
Others
Computer on Module Market
Others
Digital Media Adaptor (DMA) Market
Others
Reinforcement Geosynthetics Market
Others
Asia Pacific Automotive LED Lighting Market
Others
Asia-Pacific Telecom Transformers Market