
 Global Pharmacy Inventory Management Software Solutions and Cabinets Market | 2026-2036
Global Pharmacy Inventory Management Software Solutions and Cabinets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmacy Inventory Management Software Solutions and Cabinets Market Foresight
Buyer concentration across hospital pharmacy chains is pivoting toward integrated health systems that centralize procurement for dozens of facilities. Omnicell Inc. leverages its automated dispensing cabinet portfolio to anchor relationships with large IDNs seeking enterprise-wide medication management. McKesson Corporation sustains competitive positioning through its distribution scale and cloud-based inventory platforms that connect retail and hospital pharmacies. ARxIUM differentiates via robotic dispensing systems that integrate with existing enterprise resource planning infrastructure.
Pharmacy inventory management software solutions and cabinets comprise automated hardware units with barcode verification, weight-based dispensing, and temperature-controlled storage alongside software platforms that track lot numbers, expiration dates, and controlled-substance chain-of-custody. These systems eliminate manual counting errors, reduce diversion risk, and ensure compliance with serialization requirements through real-time data capture at the point of dispensing. Automated dispensing cabinets occupy the largest margin pool as hospitals prioritize patient safety investments, while cloud-based deployment segments expand fastest as pharmacy chains seek to reduce on-premise IT overhead and enable remote inventory visibility across distributed sites. Medication tracking systems represent a concentrated growth vector where regulatory pressure for end-to-end traceability intersects with opioid stewardship programs.
The US FDA's Drug Supply Chain Security Act and the EU's Falsified Medicines Directive impose unit-level traceability requirements that directly shape software functionality specifications and cabinet integration standards. HIPAA in the United States and GDPR in Europe constrain how patient-specific dispensing data flows between inventory platforms and clinical systems, creating compliance-driven demand for encrypted, access-controlled architectures. Stakeholders must monitor how interoperability mandates from ONC and evolving EU MDR device classification rules for automated dispensing systems reshape vendor qualification criteria and procurement timelines.
Market Dynamics
Hospital pharmacy chains are consolidating procurement authority into integrated delivery networks, forcing vendors to architect enterprise-scale medication management platforms rather than site-specific installations.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Unit-level serialization mandates compel pharmacies to deploy track-and-trace infrastructure, directly expanding software and cabinet upgrade cycles across United States hospital systems.
- Robotic dispensing integration:Automated dispensing cabinets with barcode verification and weight-based sensing reduce medication errors in high-acuity settings, accelerating replacement of manual inventory workflows.
- Japan's aging demographic:Chronic disease burdens strain pharmaceutical distribution networks, driving adoption of temperature-controlled storage and automated retrieval systems in Tokyo and Osaka hospital clusters.
Market Restraints
- Capital intensity:Automated dispensing cabinets with enterprise software integration require substantial upfront investment, constraining adoption among independent community pharmacies and smaller regional hospitals.
- Semiconductor supply concentration:Microcontroller and sensor shortages concentrated in East Asian fabrication facilities create lead time volatility for cabinet manufacturers dependent on just-in-time component delivery.
- GDP data portability constraints:European Union privacy regulations restrict cross-border transfer of patient-specific dispensing records, complicating cloud-based inventory visibility for multinational pharmacy chains operating across Germany, France, and Italy.
Strategic Opportunities
- India's hospital modernization:Government health infrastructure investments and private hospital expansion in Mumbai, Delhi, and Bangalore create demand for automated dispensing systems in tier-2 and tier-3 cities.
- AI-driven demand forecasting:Machine learning algorithms predicting medication utilization patterns are converging with inventory platforms, enabling predictive restocking and waste reduction in oncology and antimicrobial stewardship programs.
- EU Falsified Medicines Directive:Verification system mandates for prescription medicines create compliance-driven demand for serialized inventory tracking and authentication hardware across German, French, and Spanish pharmacy networks.
Industry Challenges
- Interoperability architecture gaps:Pharmacy inventory platforms must integrate with heterogeneous electronic health record systems, enterprise resource planning software, and bedside medication administration records, extending implementation timelines.
- Controlled-substance custody documentation:Opioid stewardship programs and DEA diversion monitoring requirements impose rigorous chain-of-custody protocols, demanding specialized software modules and staff training workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmacy Inventory Management Software Solutions and Cabinets Market |
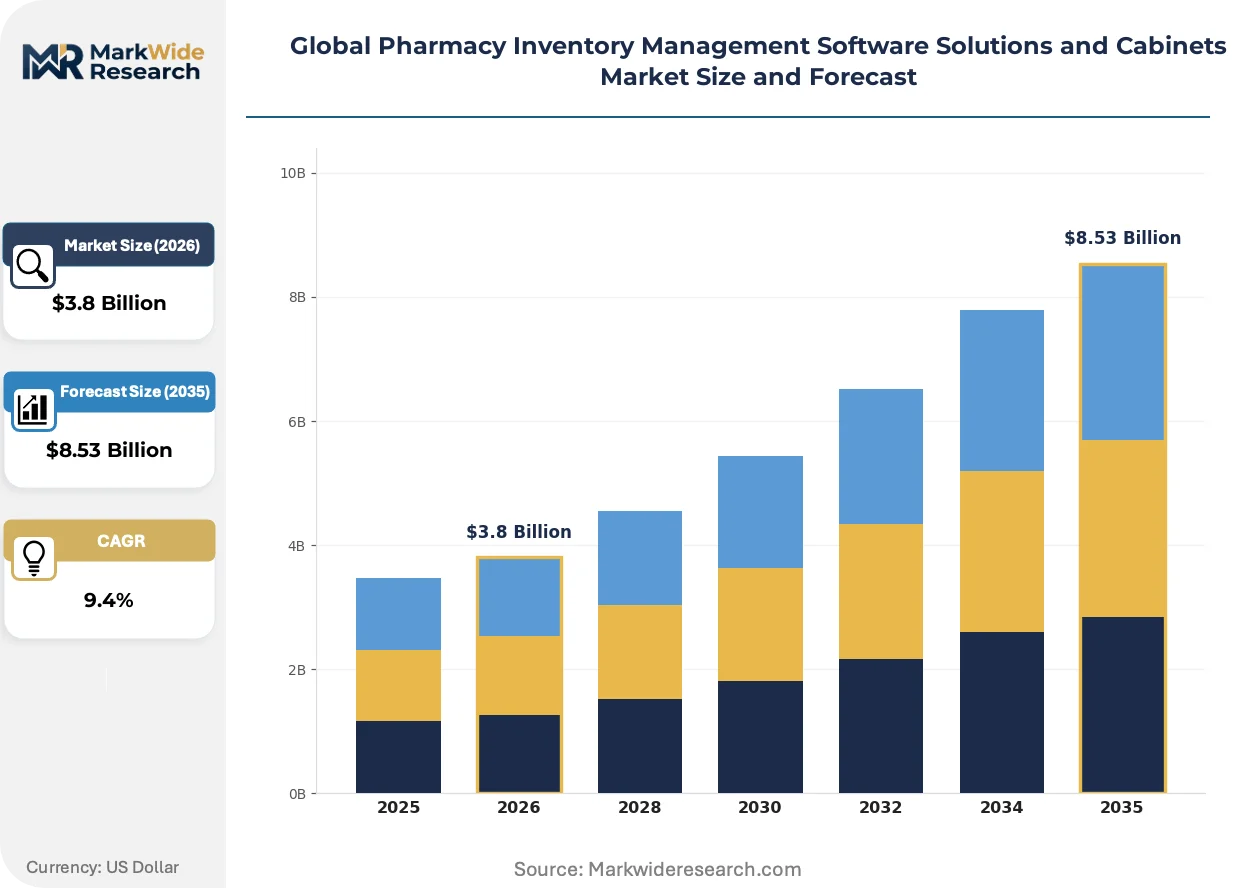
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inventory Management Software, Automated Dispensing Cabinets, Medication Tracking Systems, Stock Optimization Tools Deployment: Cloud-based, On-premise, Hybrid, SaaS, Hosted Application: Pharmacy Operations, Medication Reconciliation, Supply Chain Management, Regulatory Compliance End User: Retail Pharmacies, Hospital Pharmacies, Clinical Pharmacies, Long-term Care Facilities |
| Companies Covered | Omnicell Inc., McKesson Corporation, Becton Dickinson and Company, ARxIUM, Swisslog Healthcare, Cerner Corporation, Cardinal Health Inc., Liberty Software Inc., DATASCAN-DCS Pharmacy Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmacy Inventory Management Software Solutions and Cabinets Market Shifts & Advancements
Cloud-native deployment architectures and artificial intelligence capabilities are restructuring how pharmacy chains manage distributed inventory, compressing the traditional on-premise software upgrade cycle.
Radio-frequency identification tagging is converging with automated dispensing cabinet infrastructure to enable real-time location tracking of high-value biologics and controlled substances. Large academic medical centers in the United States are piloting RFID-enabled cabinets that automatically reconcile physical inventory against dispensing records. This convergence is compressing manual audit cycles from weekly to continuous, reducing labor overhead and diversion risk simultaneously.
The European Union's Medical Device Regulation reclassifies automated dispensing systems with patient-specific dosing capabilities as Class IIa medical devices, imposing clinical evaluation and post-market surveillance obligations on cabinet manufacturers. German notified bodies are processing certification applications with extended review timelines. Hospital procurement teams in France and Italy are prioritizing MDR-compliant vendors, reshaping competitive qualification criteria ahead of transition deadlines.
Subscription-based software licensing is displacing perpetual license purchases across United States pharmacy chains, unbundling hardware from software refresh cycles. Large integrated delivery networks negotiate enterprise agreements spanning dozens of facilities, consolidating vendor relationships. This shift concentrates purchasing leverage with procurement departments rather than individual pharmacy directors, favoring vendors with demonstrated multi-site deployment capabilities.
Global Pharmacy Inventory Management Software Solutions and Cabinets Market Segmentation
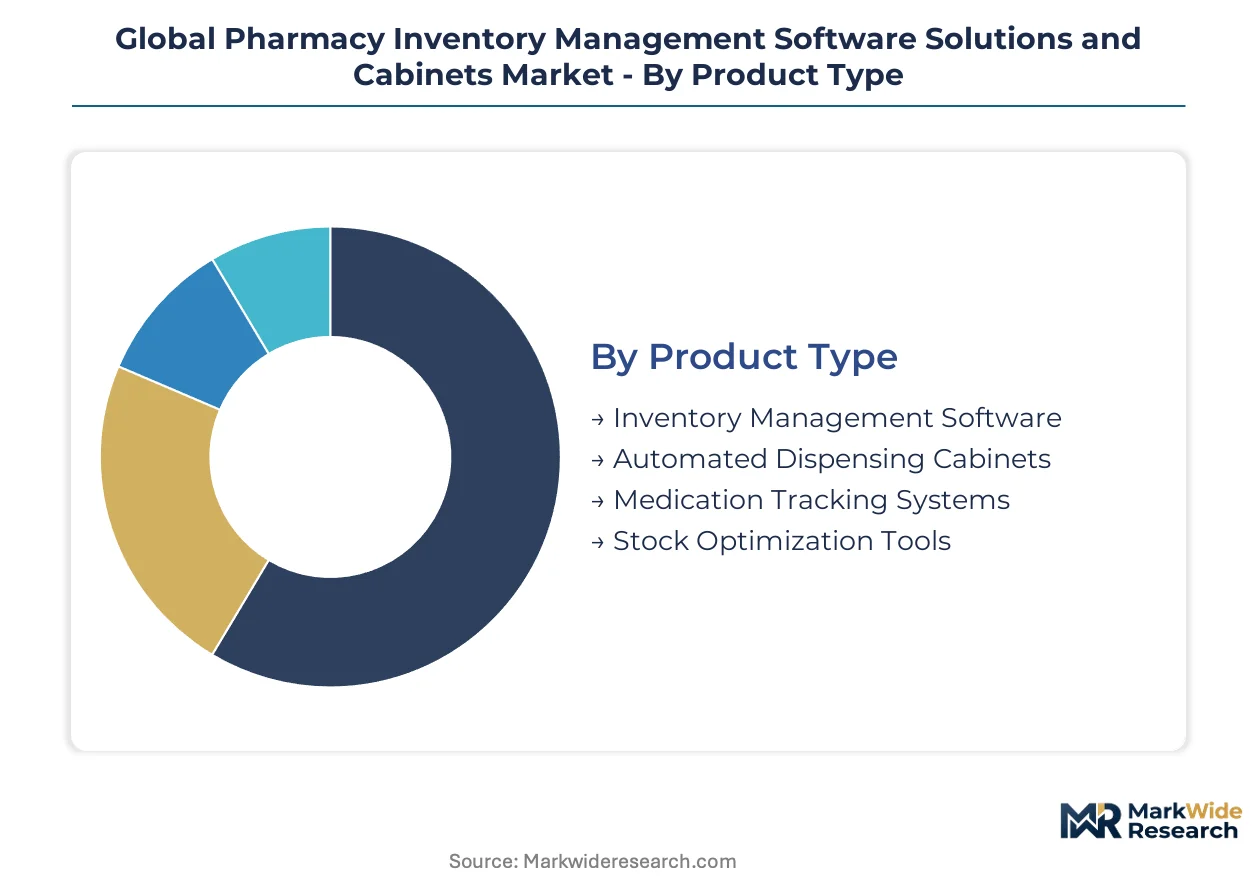
Pharmacy inventory management systems fragment across hardware-software boundaries and deployment architectures, with each segment demanding distinct integration capabilities and compliance postures. Understanding these divisions reveals where capital concentrates and where cloud-native architectures are displacing legacy infrastructure.
Product Type:
Customization intensity varies sharply across this category, from configurable software modules to purpose-built cabinet hardware requiring site-specific installation.
- Automated Dispensing Cabinets:Hardware units integrate barcode verification, weight-based sensing, and biometric access controls for high-acuity hospital settings. Demand clusters in United States integrated delivery networks modernizing medication safety infrastructure under FDA track-and-trace mandates.
- Inventory Management Software:Platforms orchestrate lot tracking, expiration monitoring, and controlled-substance chain-of-custody documentation across distributed pharmacy sites. Hospital chains in Germany and Japan prioritize enterprise-scale deployments that centralize visibility across dozens of facilities.
- Medication Tracking Systems:Specialized modules address serialization compliance and diversion monitoring for opioid stewardship programs.
- Stock Optimization Tools:Demand forecasting algorithms reduce waste in oncology and antimicrobial inventory pools.
Leading the category by volume: Automated Dispensing Cabinets. Expanding most quickly: Inventory Management Software.
Deployment:
Cost tier stratification drives procurement decisions, with capital expenditure constraints favoring subscription models over perpetual licenses.
- Cloud-based:Remote-hosted platforms eliminate on-premise server infrastructure and enable real-time inventory visibility across geographically dispersed pharmacy networks. United States retail chains and European hospital systems accelerate migration to reduce IT overhead and satisfy GDPR data residency requirements through regional cloud instances.
- SaaS:Subscription licensing unbundles software refresh cycles from hardware replacement, concentrating purchasing leverage with enterprise procurement departments negotiating multi-facility agreements.
- Hybrid:Mixed architectures preserve sensitive controlled-substance data on-premise while pushing analytics workloads to cloud environments.
- On-premise:Legacy installations persist where air-gapped security protocols dominate military or research hospital settings.
- Hosted:Third-party managed infrastructure appeals to mid-size pharmacy chains lacking internal IT capacity.
Commanding procurement volume: Cloud-based deployment. Steepest expansion trajectory: SaaS licensing models.
Application:
End-use workflow integration determines functional specifications, with regulatory compliance modules commanding premium pricing against operational efficiency tools.
- Regulatory Compliance:Software modules enforce FDA Drug Supply Chain Security Act serialization requirements and EU Falsified Medicines Directive verification protocols. United States hospital pharmacies and German retail networks deploy these systems to avoid supply chain exclusion and penalty exposure.
- Pharmacy Operations:Core dispensing workflow automation reduces manual counting errors and accelerates prescription fulfillment in high-volume retail settings.
- Medication Reconciliation:Admission-discharge-transfer tracking ensures accurate medication histories across care transitions.
- Supply Chain Management:Procurement optimization tools align inventory levels with utilization patterns across multi-site health systems.
Dominating by deployment scale: Pharmacy Operations. Gaining share fastest: Regulatory Compliance.
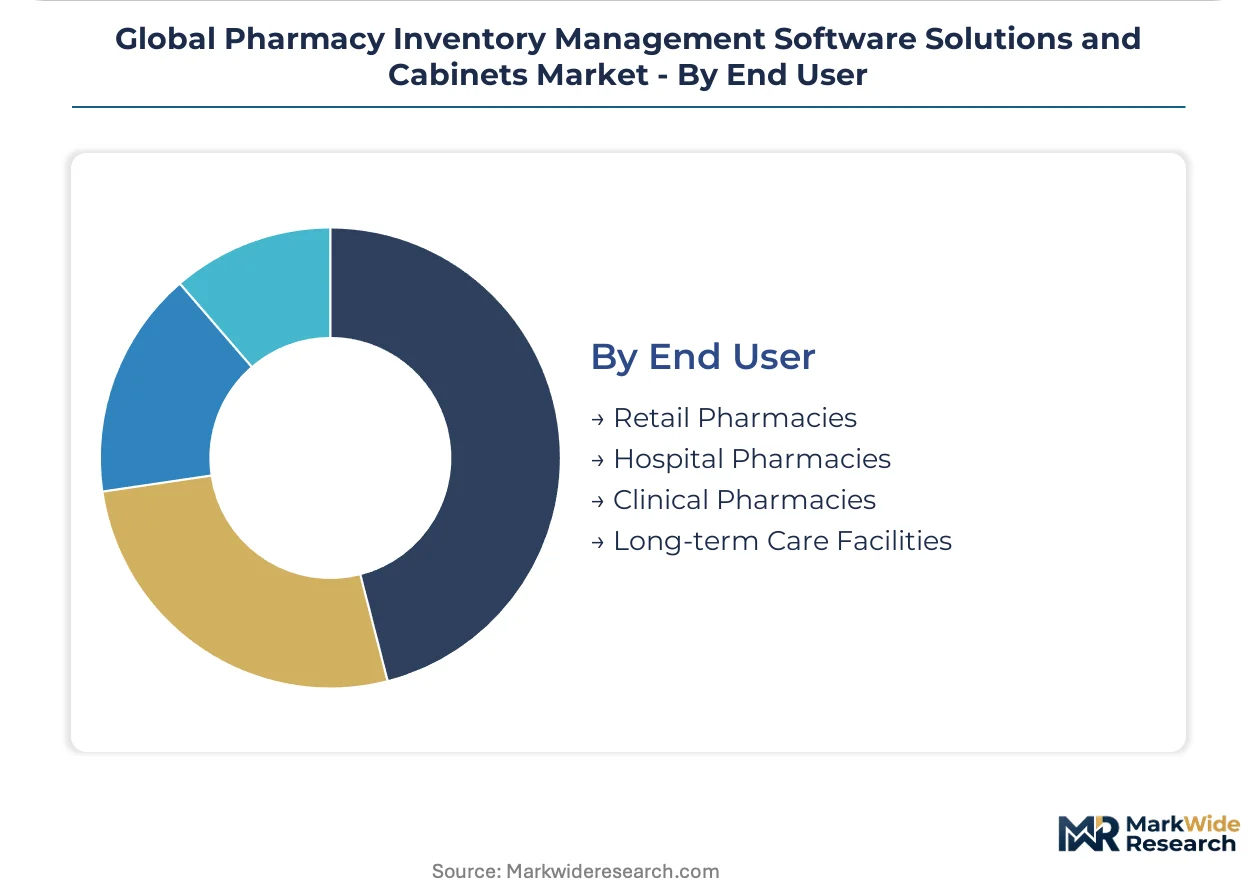
End User:
Customer type dictates system complexity, with hospital pharmacies requiring enterprise integration against retail pharmacies prioritizing standalone efficiency.
- Hospital Pharmacies:Integrated delivery networks demand automated dispensing cabinets with EHR interoperability and enterprise resource planning connectivity. United States academic medical centers and Tokyo hospital clusters drive specification standards for patient safety investments.
- Retail Pharmacies:Chain drugstores prioritize cloud-based inventory platforms that centralize procurement and reduce shrinkage across thousands of locations.
- Clinical Pharmacies:Specialty medication hubs require temperature-controlled storage integration for biologics and limited distribution drugs.
- Long-term Care Facilities:Simplified dispensing workflows address medication pass efficiency in nursing home and assisted living environments.
Leading by revenue concentration: Hospital Pharmacies. Climbing the fastest: Clinical Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement concentration in the United States, Germany, and Japan absorbs the majority of automated dispensing cabinet shipments, while cloud-based software deployments accelerate across distributed pharmacy networks in secondary markets.
United States
Integrated delivery networks centralize purchasing for dozens of facilities, demanding enterprise-scale medication management platforms. FDA Drug Supply Chain Security Act serialization mandates compel hospital pharmacies to upgrade track-and-trace infrastructure. Academic medical centers in Boston and the Research Triangle pilot RFID-enabled cabinets for continuous inventory reconciliation.
Germany
Hospital pharmacy chains prioritize MDR-compliant automated dispensing systems ahead of regulatory transition deadlines. The EU Falsified Medicines Directive verification requirements reshape procurement specifications for retail and hospital networks. Industrial clusters in Munich and Stuttgart concentrate cabinet manufacturing and notified body certification activity.
Japan
Tokyo and Osaka hospital clusters deploy temperature-controlled storage and automated retrieval systems to manage chronic disease medication volumes. METI infrastructure investments support pharmacy automation adoption in aging demographic regions. PMDA guidance on medical device software influences vendor qualification timelines for cabinet installations.
India
Private hospital expansion in Mumbai, Delhi, and Bangalore creates demand for automated dispensing systems in tier-2 and tier-3 cities. CDSCO medical device regulations align with international standards, streamlining import pathways for cabinet manufacturers. Government health infrastructure investments under Ayushman Bharat accelerate public hospital modernization programs.
United Kingdom
NHS pharmacy consolidation drives centralized procurement of inventory management platforms across hospital trusts. GDPR data residency requirements favor regional cloud deployments over cross-border hosting arrangements. London and Manchester academic medical centers lead adoption of AI-driven demand forecasting modules for oncology and antimicrobial stewardship.
Global Pharmacy Inventory Management Software Solutions and Cabinets Market Competitive Landscape
United States producers anchor the enterprise software tier; European specialists hold regulatory compliance positioning. Market structure concentrates around integrated hardware-software vendors serving hospital IDNs, with mid-size SaaS providers capturing retail pharmacy chains. Three archetypes dominate: automated cabinet manufacturers with EHR integration capabilities, cloud-native inventory platform vendors, and robotic dispensing specialists with ERP connectivity. Competitive moves center on enterprise agreement consolidation and MDR certification acceleration ahead of European deadlines.
Within the integrated systems tier, Omnicell Inc. and McKesson Corporation represent the scale-driven archetype, anchoring relationships with large IDNs through automated dispensing cabinet portfolios and distribution infrastructure. ARxIUM occupies a position among robotic dispensing specialists, exemplifying vendors that integrate with existing enterprise resource planning infrastructure. These three companies collectively illustrate how competitive positioning splits between hardware-anchored relationships and software-centric platform strategies.
| Leading Market Players |
|---|
| Omnicell Inc. |
| McKesson Corporation |
| Becton Dickinson and Company |
| ARxIUM |
| Swisslog Healthcare |
| Cerner Corporation |
| Cardinal Health Inc. |
| Liberty Software Inc. |
| DATASCAN-DCS Pharmacy Inc. |
| Others |
Supply & Pricing Matrix
Integrated delivery network procurement consolidation across United States hospital systems is forcing cabinet manufacturers to absorb customization costs while maintaining enterprise-scale software pricing, compressing margins on hardware-integrated deployments and accelerating subscription-based SaaS migration to preserve recurring revenue streams.
Pricing Analysis
High-volume automated dispensing cabinet shipments to hospital chains operate on thin hardware margins while software licensing commands premium recurring revenue. Three-tier pricing structure across enterprise, mid-tier, and standalone installations reflects EHR integration depth and FDA compliance certification levels. Pricing pressure stems from IDN purchasing leverage consolidating vendor relationships across dozens of facilities. Independent community pharmacies exhibit highest price sensitivity, constraining adoption of capital-intensive cabinet systems.
Supply Chain Analysis
Specialized engineering talent shortages in German and Japanese precision manufacturing regions constrain cabinet production scaling for MDR-certified systems. Microcontroller and sensor supply draws from Taiwan, South Korea, and select United States fabrication facilities, with barcode verification modules and biometric access components sourced from concentrated East Asian electronics clusters. Single-source vulnerability in semiconductor supply creates lead time volatility for cabinet manufacturers. Distribution runs through authorized medical device distributors with hospital GPO contracting relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native deployment architectures are displacing legacy on-premise pharmacy inventory platforms, with AI-driven demand forecasting modules replacing static replenishment algorithms across United States and European health systems.
For Market Incumbents: Acquire cloud-native SaaS capabilities to counter pure-play software entrants targeting mid-size pharmacy chains. Defensive consolidation requires MDR certification acceleration ahead of European deadlines and backward integration into sensor manufacturing to reduce semiconductor supply exposure. Threat from robotic dispensing specialists with ERP connectivity demands enterprise agreement lock-in through multi-site deployment capabilities.
For New Entrants and Emerging Players: Tier-2 and tier-3 cities in India's private hospital expansion represent underserved buyer archetypes with limited incumbent penetration. White-space targets include temperature-controlled storage integration for clinical pharmacies handling biologics and AI-driven waste reduction modules for oncology stewardship programs. Go-to-market angle should emphasize rapid deployment without legacy EHR integration complexity.
For Investors and Strategic Acquirers: The window for entry favors SaaS-native inventory platforms with demonstrated multi-site scalability over hardware-dependent cabinet manufacturers. Long-term viability rests on recurring revenue concentration and regulatory compliance moats. Acquisition target archetype: cloud-based platforms with GDPR-compliant regional cloud instances. Signal to watch is FDA track-and-trace mandate enforcement intensity accelerating replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Acceleration | German notified body queue positioning secures European hospital procurement eligibility ahead of transition deadlines. |
| Cloud-Native Platform Migration | Remote-hosted architectures satisfy GDPR data residency requirements through regional European cloud instances. |
| AI Demand Forecasting Integration | Machine learning modules reduce oncology and antimicrobial inventory waste for United States academic medical centers. |
| RFID Cabinet Deployment | Real-time biologics tracking compresses manual audit cycles from weekly to continuous in high-acuity settings. |
| Enterprise Agreement Consolidation | Multi-facility SaaS licensing concentrates purchasing leverage with IDN procurement departments. |
Research Methodology
Independent corroboration across hospital pharmacy directors, biomedical equipment procurement managers, and GPO contracts specialists underwrites the qualitative findings, validated against FDA Drug Supply Chain Security Act implementation timelines, EU MDR transition guidance documents, and hospital capital expenditure databases. Bottom-up facility-level adoption modeling triangulates with top-down market sizing from automated dispensing cabinet shipment records and cloud software licensing disclosures.
Comparable-period anchoring to historical FDA mandate compliance cycles and European medical device regulation transitions structured the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user facility type, application workflow, and regional regulatory cluster. CAGRs derive from facility penetration rates cross-referenced with software subscription pricing trajectories and hardware replacement cycles, incorporating semiconductor supply lead time volatility and IDN consolidation patterns as industry-specific forecast inputs.
Revisions become necessary when FDA enforcement intensity deviates from modeled timelines, EU MDR transition deadlines shift, or semiconductor supply concentration triggers sustained lead time disruption. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Post-Acute Transition Care Coordination Platform Market
Healthcare IT
Cancer Patient Registry Software Market
Healthcare IT
Anatomic Pathology Track and Trace Solutions Market
Healthcare IT
Global Electronic Trial Master File (ETMF) Market
Healthcare IT
US Practice Management Systems Market
Healthcare IT
Asia-Pacific Revenue Cycle Management Market
Healthcare IT
E-Prescribing Systems Market
Healthcare IT
Global Patient Intake Software Market
Healthcare IT
Hospital Capacity Management Solutions Market
Healthcare IT
Healthcare IT Provider Market
Healthcare IT
Global Personal Health Records Software Market
Healthcare IT
US Dental Clearing Houses Market
Healthcare IT
Healthcare Ediscovery Market
Healthcare IT
Prior Authorization Software Market
Healthcare IT
Clinical Communication and Collaboration Market
Healthcare IT
Pharmaceutical Software Market