
 Authorized Car Service Center Market | 2026-2036
Authorized Car Service Center Market Size, Share, and Industry Trends Forecast 2026-2036
Authorized Car Service Center Market Analysis
Subscription-based fleet leasing and pay-per-use service contracts is reconfiguring capital deployment across the authorized service landscape. Toyota Motor Corporation leverages its captive finance arm to lock fleet customers into long-term maintenance agreements. Volkswagen AG anchors its competitive stance through proprietary diagnostics platforms that restrict independent repair access. Robert Bosch GmbH specializes in multi-brand diagnostic tool supply, extending its influence beyond any single OEM channel.
An authorized car service center constitutes a franchised or directly operated facility using OEM-specified equipment, trained technicians, and genuine parts to perform warranty-compliant maintenance, repair, and inspection services on vehicles. These centers execute prescribed service protocols including torque specifications, fluid grades, and software calibration sequences to preserve manufacturer warranties and safety certifications. Maintenance services generate the steadiest revenue stream across the service type dimension, while telematics-enabled predictive maintenance represents the fastest-expanding technology category as connected vehicle penetration deepens. Fleet operators command disproportionate margin attention within the customer type split due to volume guarantees and centralized billing structures.
The EPA enforces emissions compliance through mandated onboard diagnostic testing that channels repair demand toward authorized centers with certified scan tools. The EU's MDR-equivalent vehicle type-approval framework and REACH chemical restrictions on brake fluids and coolants further elevate technical barriers to market entry. Germany's KBA inspection regime and the United States' state-level BAR (Bureau of Automotive Repair) licensing systems create geographically fragmented but structurally similar compliance environments. Stakeholders must monitor how right-to-repair legislation in multiple jurisdictions reshapes the boundary between authorized and independent service channels.
Market Dynamics
Telematics-enabled predictive maintenance is compressing service intervals and rerouting repair demand toward authorized channels with OEM-certified diagnostic access. This connectivity shift forces service centers to integrate cloud-based vehicle data streams while maintaining physical bay capacity for complex repairs.
Growth Catalysts
- EPA emissions enforcement:Mandated onboard diagnostic testing channels repair volume toward authorized centers with certified scan tools and technician credentials.
- Fleet operator consolidation:Commercial vehicle uptime requirements intensify as logistics companies centralize maintenance procurement under long-term service agreements.
- Connected vehicle penetration:Embedded telematics systems generate real-time fault codes that trigger proactive service scheduling before component failure.
Market Restraints
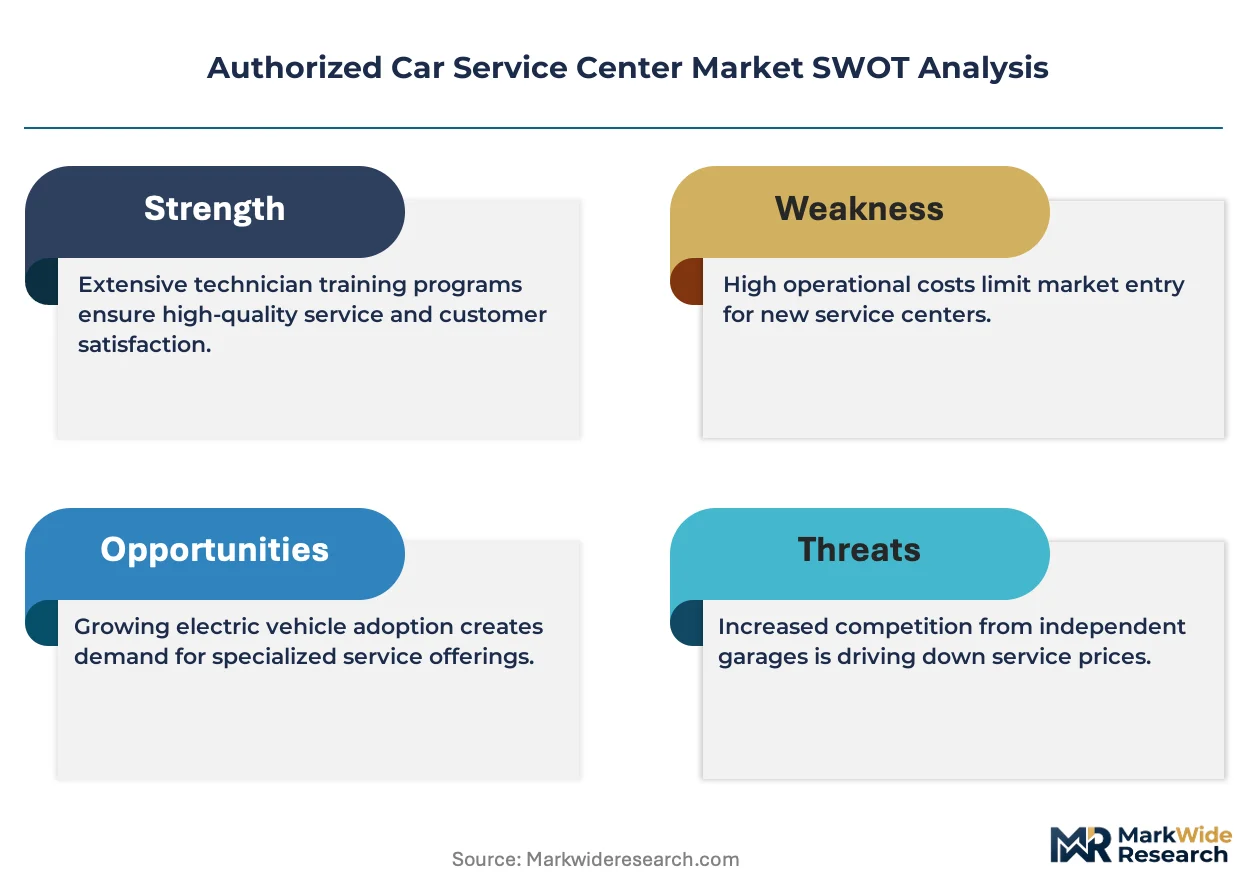
- Certified equipment capex:OEM-specified diagnostic platforms and refrigerant recovery systems require substantial upfront investment with depreciation cycles exceeding five years.
- Technician certification scarcity:Factory-authorized training programs produce limited annual throughput relative to replacement demand across major automotive markets.
- Independent channel price competition:Non-authorized repair shops capture routine maintenance volume through lower labor rates and aftermarket parts sourcing.
Strategic Opportunities
- Subscription service contracts:Pay-per-mile and fixed-fee maintenance agreements lock fleet customers into exclusive authorized channel relationships.
- EV high-voltage specialization:Battery system servicing and thermal management repair create technical moats as electric vehicle adoption accelerates.
- EU F-Gas Regulation compliance:Refrigerant handling certification requirements eliminate independent competitors lacking authorized equipment investment.
Industry Challenges
- Software calibration complexity:Over-the-air update integration and ECU reprogramming demand continuous technician retraining on proprietary OEM platforms.
- Warranty documentation rigor:Digitized service records and torque specification verification create administrative overhead that independent channels bypass.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Authorized Car Service Center Market |
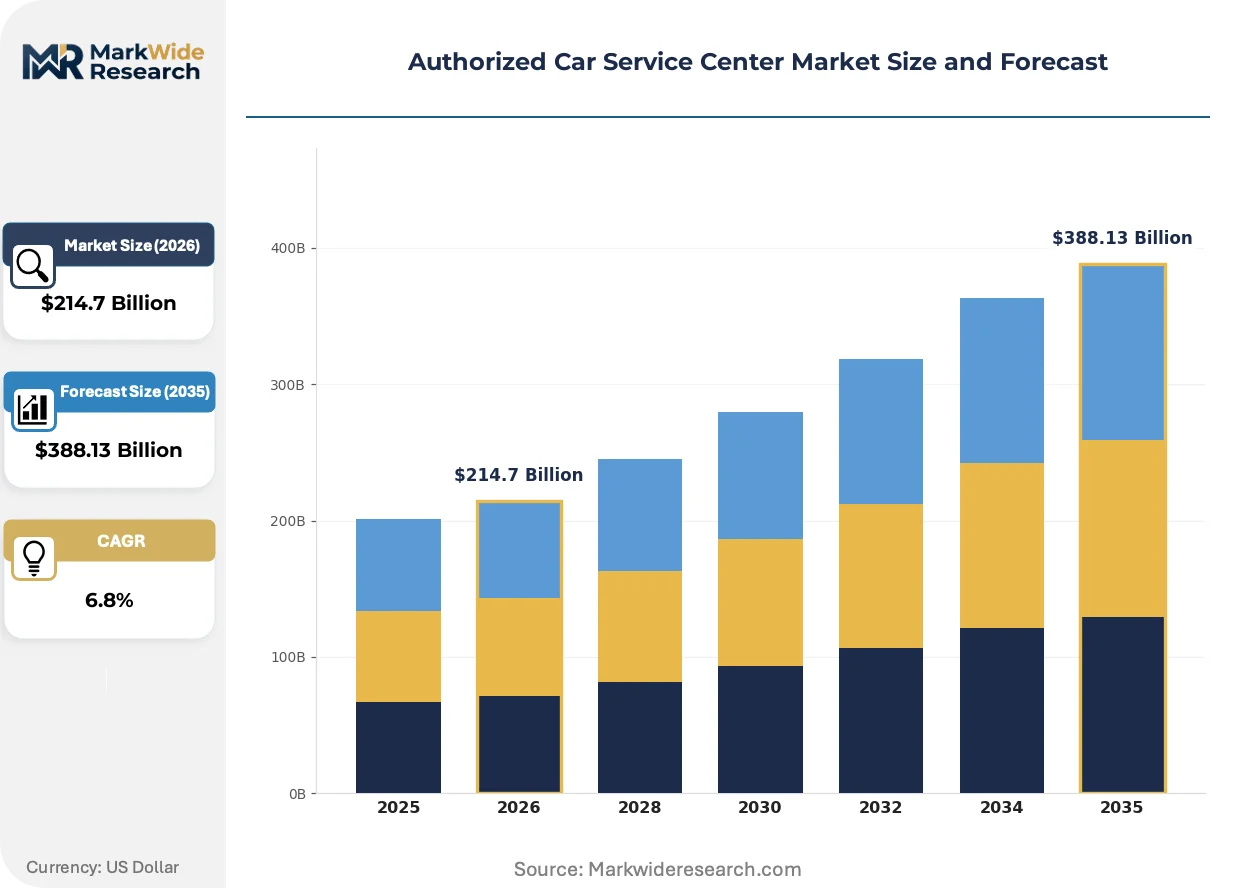
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $388.13 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Repair, Inspection, Detailing Vehicle Type: Sedan, SUV, Truck, Hatchback Customer Type: Individual Owners, Fleet Operators, Businesses, Dealerships Technology Used: Diagnostics, Telematics, Repair Management, Parts Ordering |
| Companies Covered | Honda Motor Co. Ltd., Mercedes-Benz, Toyota Motor Corporation, Stellantis NV, General Motors, Volkswagen AG, Hyundai Motor Company, Robert Bosch GmbH, Bayerische Motoren Werke AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Authorized Car Service Center Market Emerging Trajectories
Diagnostic technology convergence and regulatory compliance digitization are redefining competitive differentiation across the authorized service landscape. Service centers now compete on data integration speed rather than mechanical turnaround alone.
Artificial intelligence fault prediction is hybridizing traditional scheduled maintenance with condition-based intervention. Fleet management platforms ingest telematics streams to flag degradation patterns before dashboard alerts trigger. This capability compresses unplanned downtime while concentrating high-value predictive work at OEM-certified facilities.
The EU's F-Gas Regulation mandates refrigerant leak detection and recovery certification for all servicing operations involving fluorinated greenhouse gases. Service centers must deploy calibrated electronic leak detectors and dedicated recovery equipment to maintain legal operating status. Germany's KBA inspection regime enforces these standards most stringently, creating compliance templates that neighboring markets adopt.
Fleet procurement centralization displaces individual vehicle owner decision-making in maintenance channel selection. Logistics operators negotiate enterprise service agreements that mandate authorized center utilization across national networks. This concentration is most visible in Germany, where commercial vehicle density and KBA enforcement intensity align to favor franchised facilities.
Authorized Car Service Center Market Segmentation
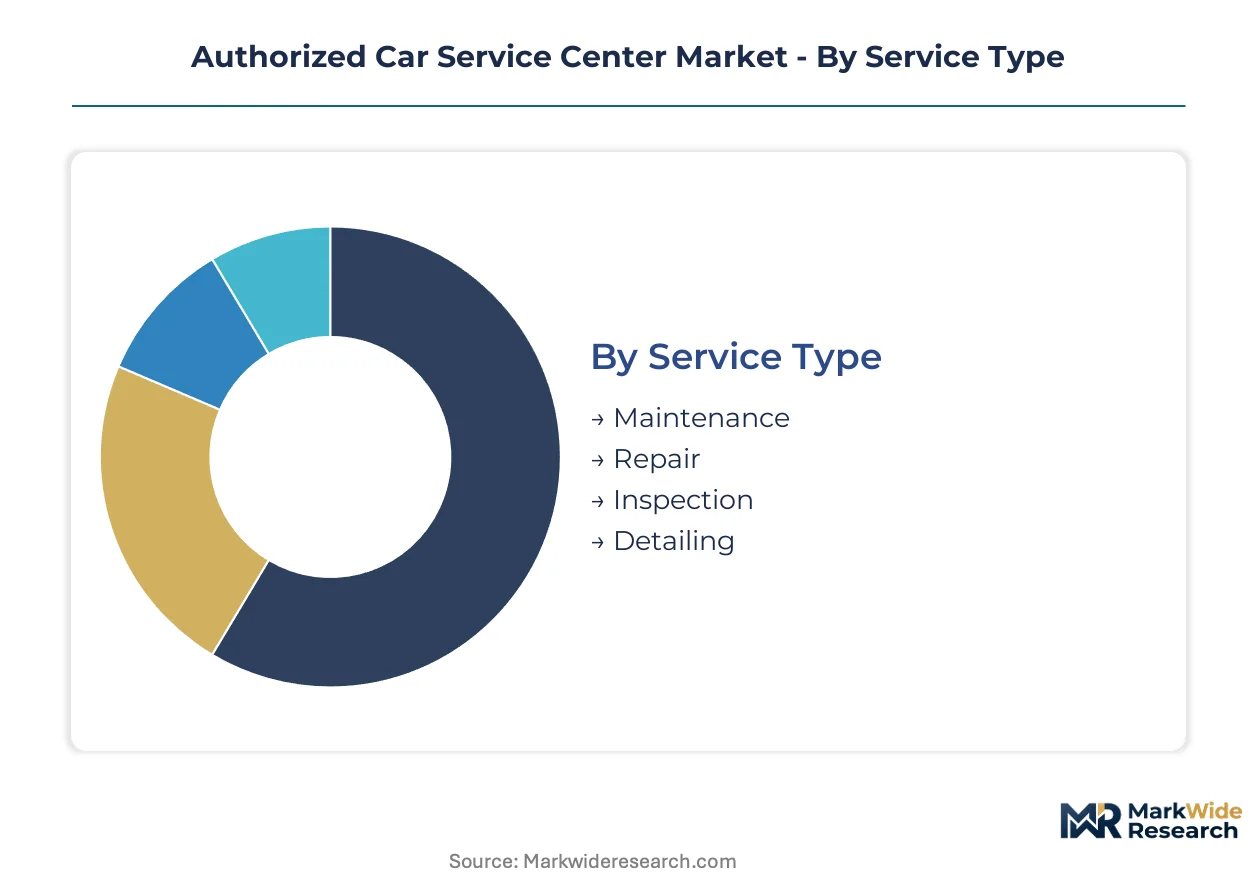
Segmentation reveals how authorized service centers allocate capital across divergent service intensities and customer procurement patterns. Each dimension exposes distinct margin profiles and compliance burdens that shape facility investment decisions.
Service Type:
Service intensity spans routine preservation through aesthetic restoration, with regulatory compliance layering complexity across the spectrum.
- Maintenance:Scheduled fluid exchanges, filter replacements, and software updates preserve manufacturer warranties through OEM-specified protocols. Fleet operators in Germany generate concentrated demand as KBA inspection requirements mandate documented service histories for commercial registrations.
- Repair:Component replacement and collision restoration demand certified technician labor and genuine parts sourcing to maintain safety certifications. Individual owners in the United States channel warranty-covered work toward authorized centers while seeking independent alternatives for out-of-warranty mechanical failures.
- Inspection:Mandatory safety and emissions verification procedures require calibrated equipment and regulatory credentialing that independent channels struggle to replicate.
- Detailing:Interior refurbishment and exterior protective treatments operate at lower regulatory thresholds but face price competition from specialized non-automotive service providers.
Established volume favors Maintenance; emerging adoption favors Telematics-integrated predictive Repair scheduling.
Vehicle Type:
Physical architecture and duty cycles determine service bay configuration and technician specialization requirements.
- Sedan:Passenger car platforms dominate service volume through standardized underbody layouts and widely distributed technical documentation. Fleet operators in the United States consolidate sedan maintenance under enterprise agreements that specify authorized center utilization.
- SUV:Elevated ride heights and all-wheel-drive systems demand specialized lift equipment and drivetrain expertise. German KBA inspection protocols apply stringent standards to SUV brake systems given their mass and towing duty profiles.
- Truck:Commercial chassis configurations require heavy-duty bay infrastructure and EPA emissions certification for diesel powertrain servicing.
- Hatchback:Compact footprints concentrate in urban markets where space constraints limit independent competitor facility scale.
Truck service commands premium labor rates; hatchback volume concentrates in European metropolitan corridors.
Customer Type:
Procurement centralization versus distributed decision-making creates divergent pricing power and contract structures.
- Individual Owners:Discretionary maintenance purchasers respond to warranty preservation incentives and convenience positioning. United States state-level BAR licensing requirements create geographic variation in authorized center accessibility.
- Fleet Operators:Centralized procurement functions negotiate volume-based service agreements with uptime guarantees and consolidated billing. German logistics corridors generate the densest concentration of fleet-dedicated authorized facilities.
- Businesses:Corporate vehicle pools balance cost control against duty-of-care liability through mixed channel strategies.
- Dealerships:Captive service operations capture new vehicle warranty work while competing for post-warranty retention through prepaid maintenance plans.
Fleet procurement is accelerating fastest; individual owner retention remains the margin defense priority.
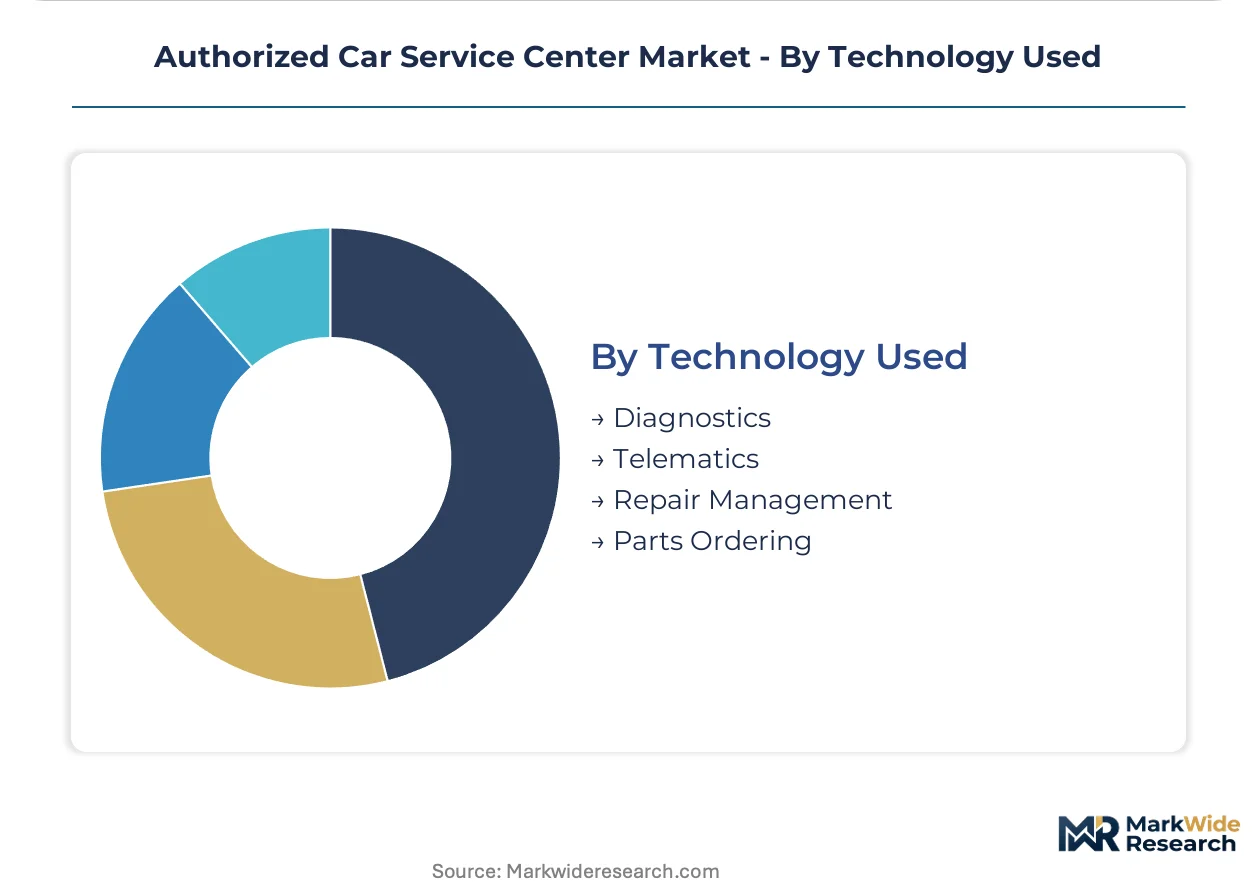
Technology Used:
Digital integration depth separates authorized centers from independent competitors through proprietary data access.
- Diagnostics:OEM-certified scan tools and software calibration platforms enforce warranty compliance while generating recurring subscription revenue. Volkswagen AG restricts independent repair access through proprietary diagnostics architectures.
- Telematics:Embedded connectivity streams real-time fault codes to authorized centers, enabling predictive intervention before component failure. Fleet operators leverage this capability to compress unplanned downtime across distributed vehicle populations.
- Repair Management:Workflow optimization software coordinates bay scheduling, parts availability, and technician assignment.
- Parts Ordering:Integrated supply chain platforms link service centers to regional distribution centers with same-day fulfillment capabilities.
Diagnostics anchors current revenue; Telematics-enabled predictive service is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German authorized service centers command 15-20% labor rate premiums over comparable United States facilities, reflecting tighter regulatory compliance burdens and technician certification scarcity. Fleet procurement concentration in the Rhine-Ruhr corridor amplifies this pricing power through volume-locked service agreements.
United States
Commercial vehicle uptime requirements from logistics operators concentrate demand in the Midwest automotive belt. EPA emissions enforcement through mandated onboard diagnostic testing channels repair volume toward authorized centers with certified scan tools. Detroit-Warren-Dearborn MSA hosts the densest cluster of fleet-dedicated facilities serving domestic OEM warranty networks.
Germany
Stuttgart and Munich metropolitan areas anchor premium vehicle service density as Mercedes-Benz and Bayerische Motoren Werke AG maintain captive facility networks. The KBA inspection regime enforces rigorous documentation protocols that independent channels struggle to replicate. Bavaria's commercial vehicle corridors generate disproportionate fleet maintenance contract value through centralized procurement.
China
Shanghai and Beijing municipal markets drive telematics-enabled predictive maintenance adoption among fleet operators. MIIT-connected vehicle regulations mandate data accessibility to authorized service channels. Yangtze River Delta manufacturing clusters concentrate multi-brand diagnostic equipment distribution.
Japan
Tokyo-Osaka corridor fleet operators negotiate exclusive maintenance agreements with Toyota Motor Corporation and Honda Motor Co. Ltd. service networks. METI vehicle type-approval frameworks elevate technical barriers for non-authorized competitors. Aichi Prefecture's automotive production belt feeds captive parts supply chains into regional service centers.
India
Maharashtra and Karnataka state markets concentrate authorized facility expansion as Hyundai Motor Company and Volkswagen AG scale franchised networks. BIS automotive component certification requirements complicate independent competitor parts sourcing. Mumbai-Pune and Bengaluru-Chennai corridors attract fleet operator maintenance contracts through highway logistics density.
Authorized Car Service Center Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in diagnostic tool supply and certified equipment distribution. The authorized service center market structures around captive OEM networks, multi-brand equipment suppliers, and independent facility operators seeking franchise affiliation. Three archetypes dominate: vertically integrated automakers operating wholly-owned service arms, technology licensors providing proprietary diagnostic platforms, and regional multi-point operators aggregating under single-brand banners. Competitive moves concentrate on exclusive fleet service contract capture and high-voltage EV technician certification pre-positioning.
Among German-based automakers, Mercedes-Benz and Bayerische Motoren Werke AG exemplify captive network operators leveraging brand equity to lock post-warranty customer retention. Robert Bosch GmbH occupies a distinct position as a multi-brand technology supplier extending influence across OEM-independent channels. These three entities represent divergent strategic postures: direct service provision, proprietary platform control, and cross-manufacturer equipment standardization.
| Leading Market Players |
|---|
| Honda Motor Co. Ltd. |
| Mercedes-Benz |
| Toyota Motor Corporation |
| Stellantis NV |
| General Motors |
| Volkswagen AG |
| Hyundai Motor Company |
| Robert Bosch GmbH |
| Bayerische Motoren Werke AG |
| Others |
Supply Flow & Price Mechanics
The Rhine-Ruhr corridor's freight density compresses logistics costs for diagnostic equipment shipments while amplifying regional price premiums for certified labor. German KBA compliance burdens and technician certification scarcity concentrate supply-side power among franchised networks, enabling three-tier pricing stratification across premium OEM-captive, standard multi-brand, and economy-independent service tiers.
Pricing Analysis
Industrial OEM buyers anchor contract structures through subscription-based fleet maintenance agreements that lock volume into authorized channels. Price differentiation rests on certification grade—KBA-mandated inspection credentials versus basic mechanical licenses—and volume scale from enterprise fleet procurement. Cost compression in routine maintenance intensifies as independent channels undercut labor rates. Individual vehicle owners exhibit highest price sensitivity; fleet procurement functions least.
Supply Chain Analysis
Extended payment terms from Bosch GmbH and Continental AG stabilize Tier 1 supplier cash flow across German, Chinese, and Japanese manufacturing clusters. Genuine parts sourcing draws from captive OEM distribution networks, aftermarket component manufacturers, and regional refrigerant handling equipment specialists. Single-source vulnerability concentrates in proprietary diagnostic software licensing. Distribution runs through OEM-controlled regional distribution centers with same-day fulfillment to authorized facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Authorized service center fragmentation creates acquisition opportunities as telematics-enabled predictive maintenance splinters demand between specialized EV high-voltage technicians and traditional drivetrain mechanics. Fleet procurement centralization rewards operators with integrated data platforms.
For Market Incumbents: Insulate warranty-compliant service volume through exclusive telematics data access agreements with Toyota Motor Corporation and Volkswagen AG captive finance arms. Pre-position high-voltage EV technician certification capacity ahead of battery system servicing demand inflection. Vertical integration into proprietary diagnostic tool supply locks out independent channel competitors lacking OEM software calibration privileges. For New Entrants and Emerging Players: India's Maharashtra and Karnataka state corridors offer underpenetrated fleet maintenance contract density as Hyundai Motor Company and Volkswagen AG scale franchised networks. Target commercial vehicle uptime guarantees in highway logistics corridors where BIS certification requirements complicate independent competitor parts sourcing. Lead with mobile diagnostic units deploying OEM-certified scan tools for on-site fleet servicing. For Investors and Strategic Acquirers: Multi-brand diagnostic equipment distributors with refrigerant handling certification capabilities present consolidation targets as EU F-Gas Regulation compliance eliminates sub-scale competitors. Long-term viability hinges on embedded software subscription revenue replacing transactional repair billing. Monitor right-to-repair legislative progression across multiple jurisdictions as inflection signal for authorized-independent channel boundary shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EV High-Voltage Technician Certification Pre-Positioning | Battery system servicing creates technical moats as Mercedes-Benz and Bayerische Motoren Werke AG electrify fleets. |
| Telematics Platform Integration | Real-time fault code ingestion from Toyota Motor Corporation connected vehicles compresses unplanned downtime for fleet operators. |
| Refrigerant Handling Compliance Investment | EU F-Gas Regulation mandates calibrated leak detection equipment that independent channels lack capital to deploy. |
| Fleet Service Agreement Centralization | Enterprise procurement functions in Germany's Rhine-Ruhr corridor negotiate volume-locked contracts with uptime guarantees. |
| Proprietary Diagnostic Tool Supply Control | Volkswagen AG restricts independent repair access through software-locked calibration platforms. |
Methodological Framework
Desk research of EPA enforcement guidance documents, EU F-Gas Regulation technical standards, and KBA inspection protocol manuals preceded structured interviews with OEM platform engineers, aftermarket service operations directors, fleet procurement managers, and diagnostic equipment distribution heads. Secondary validation drew from vehicle production databases, IHS Markit registration data, and SEC automotive segment disclosures. Bottom-up facility capacity modeling triangulated against top-down OEM warranty network expansion announcements.
Assumptions held fixed include prevailing EPA emissions enforcement intensity and EU REACH chemical restriction scope across the projection horizon. Variable assumptions encompass electric vehicle adoption pace and right-to-repair legislative progression. Segmentation dimensions modeled span service type intensity, vehicle architecture classification, customer procurement centralization, and diagnostic technology integration depth. CAGRs derived from facility investment cycle analysis and technician certification throughput constraints. Forecast inputs incorporated connected vehicle penetration curves and fleet operator contract renewal patterns.
Practitioners should monitor EPA rulemaking dockets and EU right-to-repair parliamentary votes for early signals of regulatory channel boundary shifts. Forecasts reflect documented assumptions regarding OEM captive network expansion commitments and refrigerant handling equipment depreciation cycles. Macroeconomic contraction, accelerated right-to-repair mandates, or breakthrough battery longevity technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
GCC Car Wash Market
Automotive Services
Global Street Sweeper Brushes Market
Automotive Services
Global Cars-As-A-Service (CaaS) Market
Automotive Services
Car Vending Machine Market
Automotive Services
Automotive E-Tailing Market
Automotive Services
Automotive MRO Market
Automotive Services
Car Wash Franchise Market
Automotive Services
Global Street Sweeper Market
Automotive Services
North America MRO Distribution Market
Automotive Services
Automatic Vehicle Washing System Market
Automotive Services
US Car Wash Services Market
Automotive Services
Vehicle Roadside Assistance Market
Automotive Services
Car Rental Business Market
Automotive Services
Automotive Engineering Service Providers (ESP) Market
Automotive Services
ADAS Recalibration Services Market
Automotive Services
Car Wash System Market