
 Germany Induction Hobs Market | 2026-2036
Germany Induction Hobs Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Induction Hobs Market Foresight
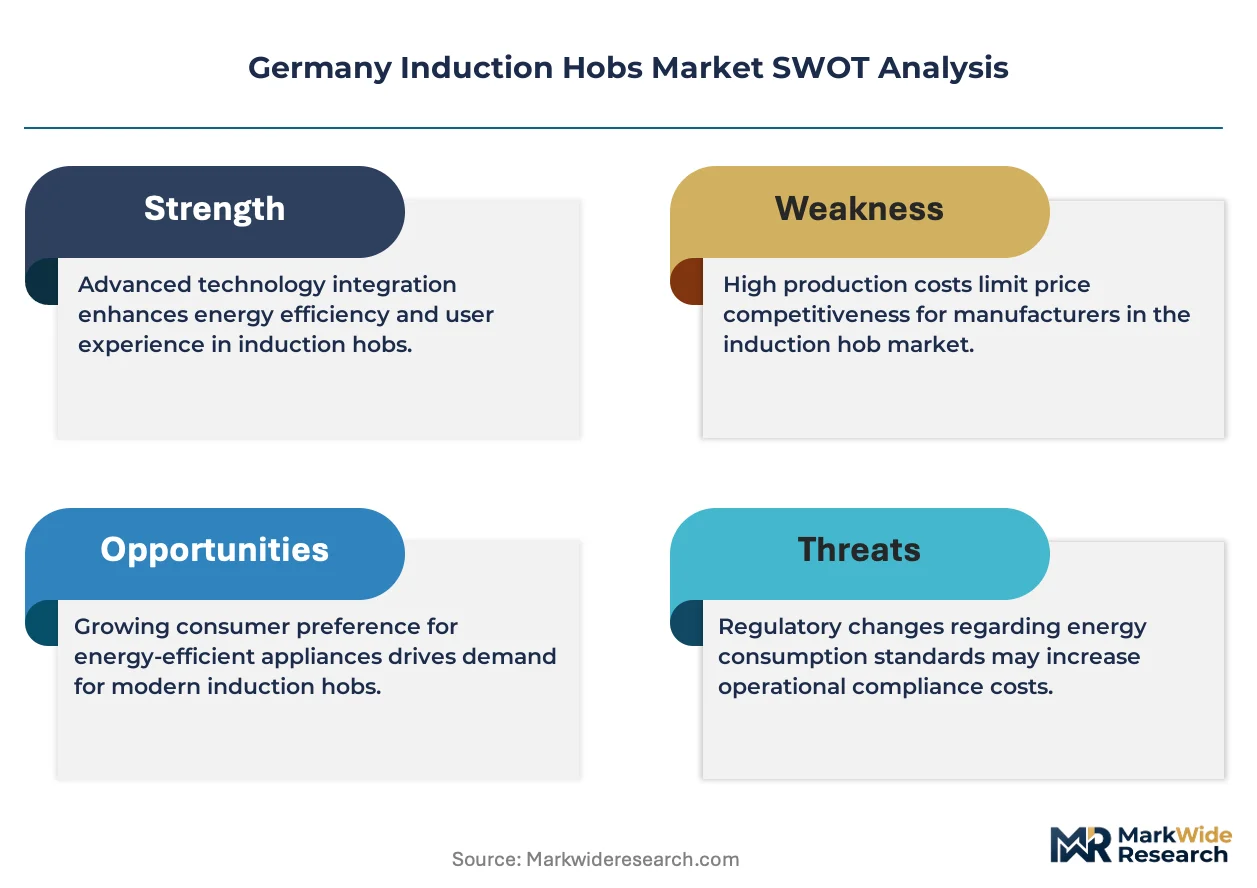
The EU Ecodesign Directive is realigning the cost-of-entry calculus for induction hob manufacturers targeting Germany. BSH Hausgeräte GmbH leverages its captive manufacturing base in Bavaria to sustain price competitiveness against imports. Miele & Cie. KG anchors the premium segment through precision coil engineering and extended warranty programs. Electrolux AB competes on modular bridge-zone configurations that appeal to open-plan kitchen designers.
Germany induction hobs are electric cooking appliances employing copper coil assemblies beneath ceramic glass surfaces to generate oscillating magnetic fields that heat ferromagnetic cookware directly, achieving thermal efficiencies exceeding 90%. Built-in variants dominate German kitchen renovations due to seamless countertop integration, while bridge-zone technology captures growing share among consumers seeking flexible cooking zones for oversized pans. Professional chefs and hospitality operators gravitate toward booster-function models that deliver rapid heat escalation for commercial throughput demands.
KBA efficiency benchmarks and CE marking requirements shape product development timelines and testing expenditures for manufacturers distributing within Germany. The country's national energy regulator enforces standby power limits that favor semiconductor-based control systems over legacy relay architectures. Stakeholders must monitor amendments to the EU F-Gas Regulation and evolving MEPS tiers to anticipate compliance-driven redesign cycles and sourcing shifts in coil and inverter components.
Market Dynamics
EU Ecodesign Directive efficiency thresholds are compressing product development cycles and forcing coil and inverter redesigns across German manufacturing bases, while Bavarian and North Rhine-Westphalian housing stock modernization concentrates demand geographically.
Growth Catalysts
- KBA efficiency benchmarks:The national energy regulator enforces standby power limits that favor semiconductor-based control systems over legacy relay architectures, accelerating component upgrades.
- Bridge-zone technology:Modular configurations appeal to open-plan kitchen designers seeking flexible cooking zones for oversized pans and griddles.
- Urban residential renovation:Kitchen modernization in Munich, Hamburg, and Cologne drives built-in induction hob replacement cycles.
Market Restraints
- Copper coil cost volatility:Raw material price swings in electromagnetic component supply chains compress manufacturer margins unpredictably.
- Ferromagnetic cookware dependency:Consumer reluctance to replace aluminum or glass cookware creates adoption friction among price-sensitive households.
- EU F-Gas Regulation amendments:Evolving compliance timelines force premature redesign cycles in semiconductor cooling systems.
Strategic Opportunities
- Booster-function commercialization:Rapid heat escalation capabilities target professional chefs and hospitality operators seeking throughput advantages.
- Baden-Württemberg underpenetration:Stuttgart and Karlsruhe housing markets lag Bavaria in renovation intensity, offering expansion headroom.
- CE marking harmonization:Streamlined testing protocols reduce certification expenditures for multi-country European distribution.
Industry Challenges
- Electromagnetic compatibility certification:CE marking requirements and KBA testing protocols extend product launch timelines by four to six months.
- Legacy relay architecture phase-out:Semiconductor control system integration demands firmware engineering capabilities scarce in traditional appliance engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Induction Hobs Market |
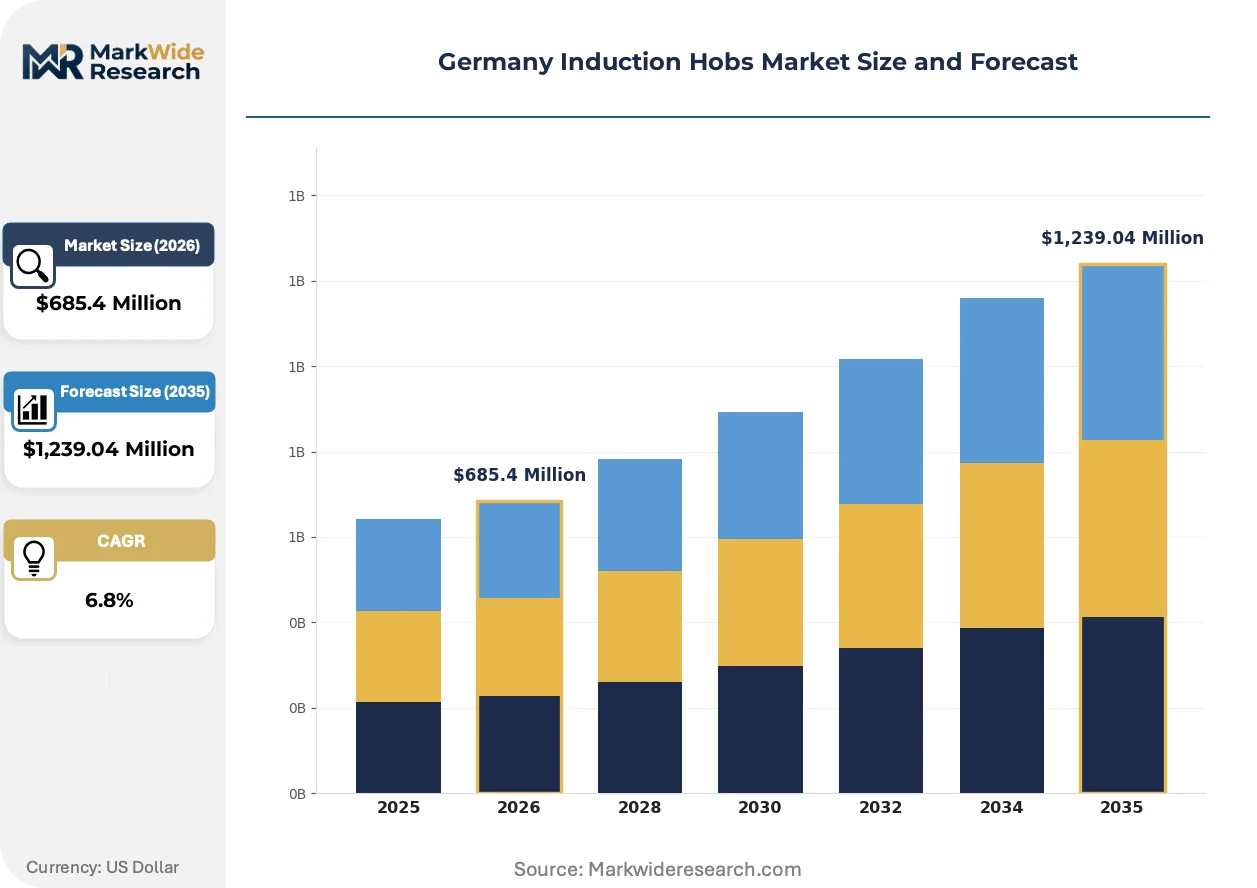
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Built-in, Freestanding, Portable, Slide-in Technology: Single Coil, Double Coil, Bridge Zone, Booster Function Application: Residential Kitchens, Commercial Catering, Food Trucks, Culinary Schools End User: Homeowners, Professional Chefs, Hospitality Operators, Event Caterers |
| Companies Covered | Electrolux AB, Arçelik, BSH Hausgeräte GmbH, Panasonic Corporation, LG Electronics, Samsung Electronics, Miele & Cie. KG, SMEG S.p.A., Whirlpool Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Induction Hobs Market Shifts & Advancements
Induction hob engineering is pivoting from standalone cooking appliances toward integrated kitchen ecosystem components, with magnetic field precision, energy recovery systems, and connectivity modules reshaping competitive differentiation.
Induction coil assemblies are converging with Internet of Things connectivity modules to enable remote diagnostics and energy consumption monitoring. High-end residential developers in Berlin and Frankfurt specify these connected configurations for smart home integration. This convergence is compressing warranty cost structures while opening recurring software service revenue streams.
The EU F-Gas Regulation is tightening refrigerant and cooling system requirements for inverter components used in high-power induction circuits. Manufacturers must redesign thermal management architectures to maintain CE marking compliance. Bavarian production facilities face the steepest compliance cost adjustments given their concentration of high-wattage professional-grade output.
Certification-driven procurement now dominates German kitchen renovation contracts, with architects and interior designers specifying CE-marked and KBA-certified units exclusively. Traditional retail channels lose share to trade-direct specifications. This preference shift is most visible in Munich's luxury residential tower developments and Hamburg's waterfront regeneration projects.
Germany Induction Hobs Market Segmentation
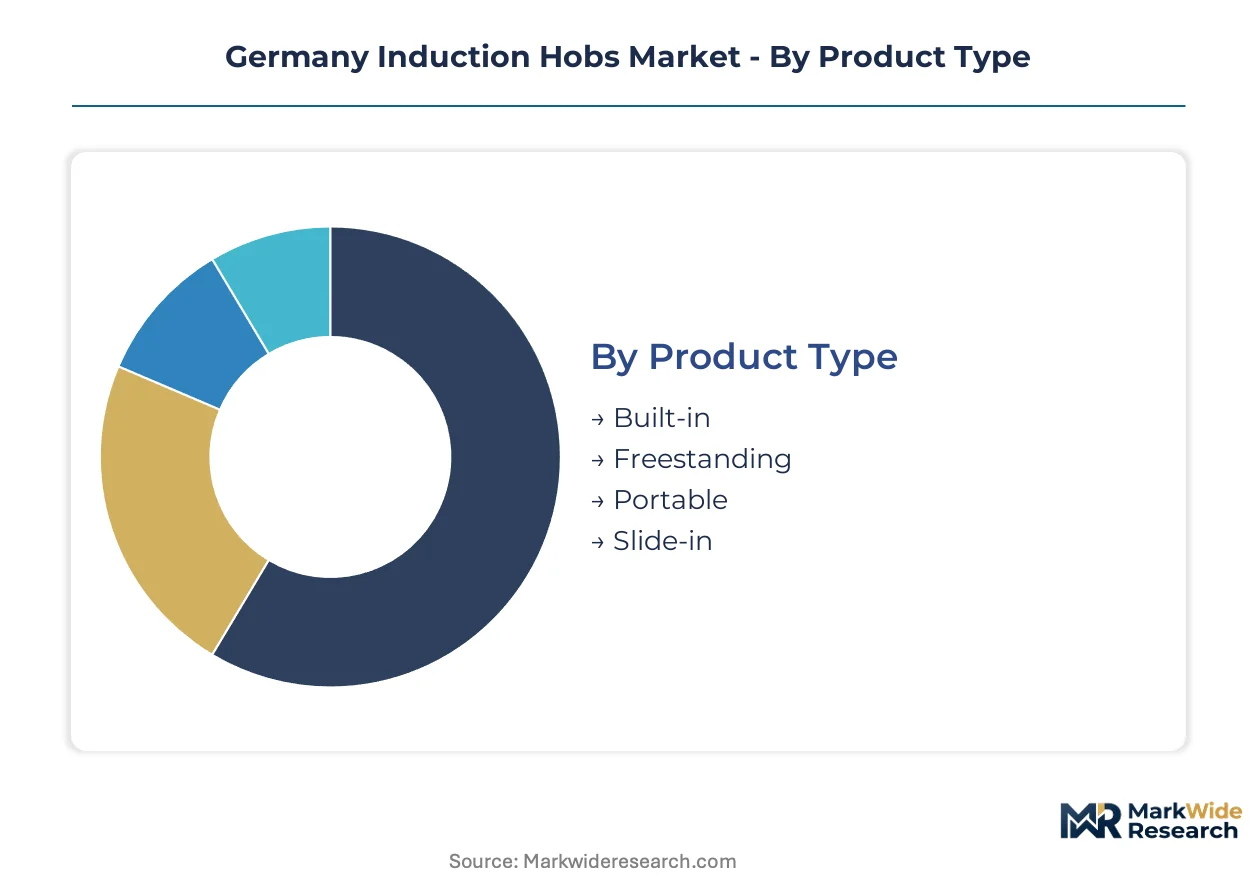
Induction hob purchasing decisions in Germany diverge sharply across installation constraints, cooking intensity requirements, and regulatory exposure. Segment boundaries reflect distinct margin structures and certification burdens that reshape manufacturer prioritization.
Product Type:
Installation permanence and countertop integration depth separate buyer willingness-to-pay across German kitchen renovation markets.
- Built-in:These units embed flush beneath stone or composite countertops through cutout integration, requiring certified electrical installation. Bavarian and North Rhine-Westphalian housing stock modernization concentrates demand here, driven by seamless aesthetic requirements in premium urban renovations.
- Freestanding:Self-contained units with integrated ovens or storage modules suit rental properties where permanent modification is restricted. Demand clusters in Berlin's tenant-heavy districts where lease terms prohibit built-in appliance installation.
- Portable:Compact single-zone units with plug-and-play operation target supplemental cooking needs and temporary kitchen setups. Student housing cooperatives in university cities specify these for cost-controlled dormitory retrofits.
- Slide-in:Range-style configurations bridge countertop gaps with finished side panels, appealing to kitchen island installations. Hamburg waterfront regeneration projects specify these for open-plan entertaining spaces requiring visual continuity from multiple angles.
Built-in leads volumes today; portable is gaining share fastest.
Technology:
Magnetic field configuration sophistication determines thermal response speed and multi-vessel flexibility, with KBA efficiency benchmarks favoring advanced inverter architectures.
- Single Coil:One copper coil assembly beneath each cooking zone delivers standard heat output through fixed-position vessels. Budget-conscious homeowners in eastern German states select these for basic replacement cycles where bridge-zone flexibility is unnecessary.
- Double Coil:Nested coil arrangements expand effective heating diameter to accommodate oversized pans without cold spots. Family households in Stuttgart's suburban expansion zones prioritize these for batch cooking efficiency.
- Bridge Zone:Adjacent coil pairs synchronize through shared inverter control to create elongated cooking surfaces for griddles and fish poachers. Open-plan kitchen designers in Frankfurt luxury towers specify these configurations exclusively.
- Booster Function:Temporary power surge protocols deliver rapid heat escalation for commercial throughput demands. Professional chefs in Munich's Michelin-rated establishments require these for sauce reduction timing precision.
Single coil dominates installed base; bridge zone climbs the fastest.
Application:
Duty cycle intensity and regulatory inspection frequency create divergent procurement specifications across German end-use environments.
- Residential Kitchens:Standard-duty installations with intermittent daily use patterns and homeowner-operated maintenance. Urban renovation waves in Cologne and Düsseldorf drive replacement demand as post-war housing stock reaches end-of-life.
- Commercial Catering:High-throughput operations requiring continuous-duty ratings and accelerated thermal recovery. Bavarian hospitality clusters specify booster-equipped bridge zones for banquet service efficiency.
- Food Trucks:Mobile installations demanding compact footprints, vibration resistance, and generator-compatible power draws. Berlin's street food corridor operators favor portable and slide-in configurations for regulatory compliance flexibility.
- Culinary Schools:Training environments requiring durable surfaces, precise temperature control demonstration, and standardized safety protocols. Baden-Württemberg vocational institutes procure double-coil units for curriculum standardization.
Residential kitchens anchor volume; food trucks show steepest expansion trajectory.
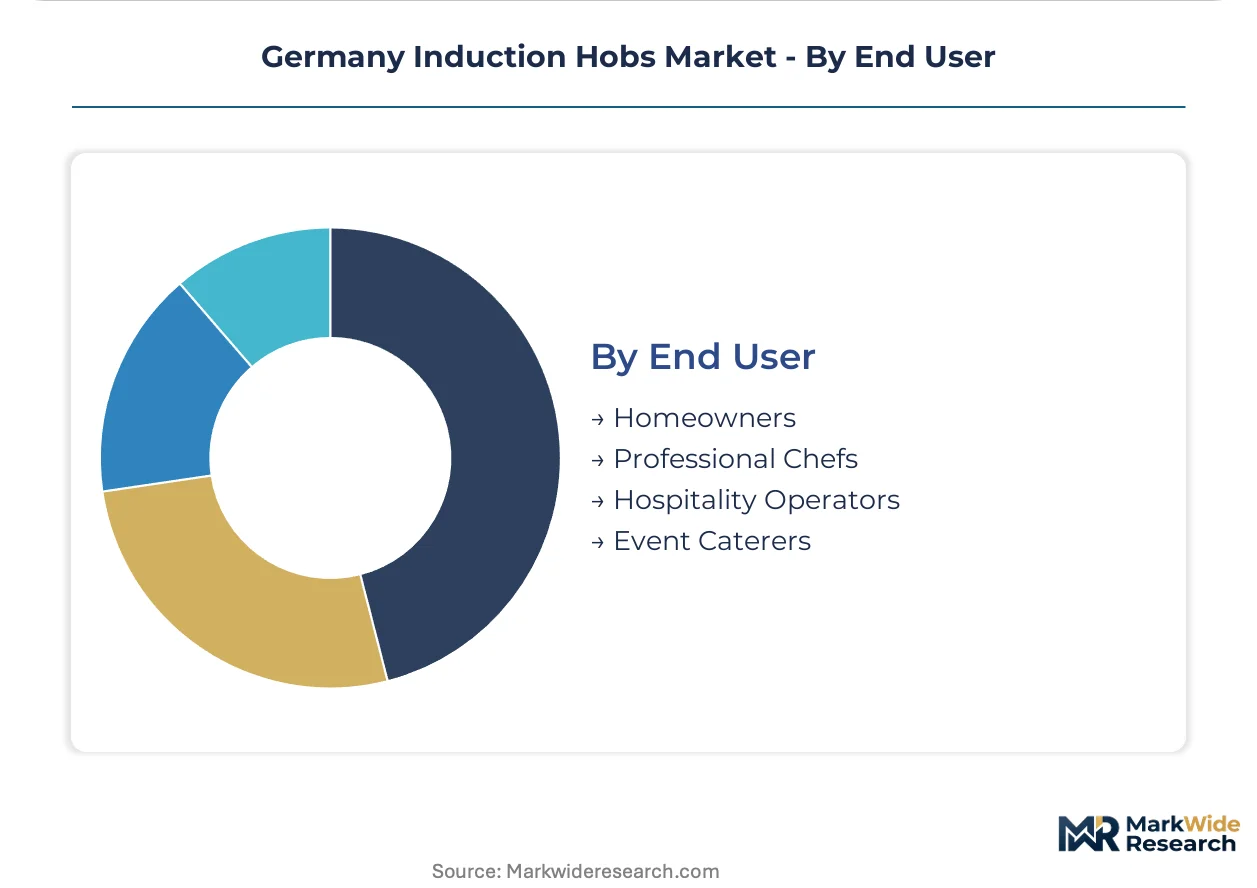
End User:
Technical sophistication and total cost-of-ownership sensitivity fragment procurement authority across German distribution channels.
- Homeowners:Individual purchasers prioritizing aesthetic integration, warranty length, and energy label visibility. Direct retail and kitchen studio channels capture this segment through specification consulting.
- Professional Chefs:Technique-driven users demanding instantaneous heat modulation and vessel-agnostic field distribution. Munich and Hamburg fine-dining clusters drive specification toward booster-function bridge zones.
- Hospitality Operators:Procurement departments optimizing for total lifecycle cost, service network density, and CE marking documentation completeness. Hotel chains standardize on built-in configurations across property portfolios.
- Event Caterers:Mobile operators requiring rapid deployment, generator compatibility, and damage-resistant surfaces. Temporary kitchen rental firms in Berlin and Frankfurt stock portable and slide-in inventories.
Homeowners command the largest share; hospitality operators are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's induction hob industry traces its manufacturing lineage to Bavaria's post-war appliance industrialization, where captive production infrastructure established the foundation for today's coil and inverter engineering clusters.
Bavaria
Munich and Nuremberg housing renovations drive built-in induction hob specifications, with luxury residential towers requiring seamless countertop integration. KBA efficiency benchmarks enforce standby power limits that favor semiconductor control architectures over legacy relays. Ingolstadt's appliance engineering corridor hosts captive manufacturing facilities serving domestic and export markets.
North Rhine-Westphalia
Cologne and Düsseldorf post-war housing stock modernization accelerates replacement cycles for energy-efficient cooking appliances. CE marking requirements and electromagnetic compatibility testing protocols shape procurement specifications for kitchen renovation contracts. The Ruhr industrial belt maintains component supply relationships for copper coil and ceramic glass assemblies.
Baden-Württemberg
Stuttgart and Karlsruhe housing markets lag Bavaria in renovation intensity, creating expansion headroom for bridge-zone and booster-function configurations. The EU Ecodesign Directive pushes manufacturers toward higher efficiency thresholds that reshape product development timelines. Mannheim's vocational institutes standardize on double-coil units for culinary training curricula.
Hamburg
Waterfront regeneration projects specify slide-in range configurations for open-plan entertaining spaces requiring visual continuity from multiple angles. The EU F-Gas Regulation amendments force thermal management redesigns in inverter cooling systems. HafenCity development clusters drive trade-direct procurement channels over traditional retail.
Berlin
Tenant-heavy districts favor freestanding and portable induction configurations where lease terms prohibit permanent kitchen modification. Street food corridor operators demand generator-compatible power draws and regulatory compliance flexibility. Smart home integration specifications in luxury residential towers compress warranty cost structures through connected diagnostics.
Germany Induction Hobs Market Competitive Landscape
The competitive structure tilts toward diversified appliance conglomerates with captive European manufacturing footprints. Tiered positioning separates premium precision-engineering specialists from scale-driven mass-market suppliers. Three archetypes dominate: integrated home appliance groups with backward component control, precision-engineering specialists commanding warranty premiums, and Asian electronics conglomerates competing on modular connectivity features. Consolidation pressure manifests through strategic partnerships for coil sourcing and geographic expansion into underpenetrated eastern German states.
Among European-anchored appliance groups, BSH Hausgeräte GmbH exemplifies the vertically integrated archetype through Bavarian production concentration, while Miele & Cie. KG occupies the premium-engineering tier with extended warranty positioning. Electrolux AB represents the modular-configuration specialist competing on bridge-zone flexibility for open-plan kitchen specifications.
| Leading Market Players |
|---|
| Electrolux AB |
| Arçelik |
| BSH Hausgeräte GmbH |
| Panasonic Corporation |
| LG Electronics |
| Samsung Electronics |
| Miele & Cie. KG |
| SMEG S.p.A. |
| Whirlpool Corporation |
| Others |
Supply & Pricing Matrix
The EU Ecodesign Directive's escalating efficiency thresholds gate qualified component supply for German induction hob manufacturers, restricting premium-tier pricing access to those with captive coil engineering capabilities and semiconductor control system integration. Bavarian producers leverage backward integration into copper coil assemblies to defend margin structures against import price competition, while North Rhine-Westphalian assemblers absorb certification-driven cost compression through ceramic glass sourcing scale.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates German distribution, with CE marking grade and KBA certification status as primary price differentiation drivers. Cost compression in the economy tier intensifies because Asian electronics conglomerates flood modular single-coil configurations through direct online channels. Homeowners in tenant-heavy Berlin districts exhibit highest price sensitivity, while Munich luxury residential developers show least sensitivity to premium positioning for bridge-zone and booster-function specifications.
Supply Chain Analysis
Workforce availability constraints in Bavaria's Ingolstadt engineering corridor and North Rhine-Westphalia's Ruhr industrial belt tether coil and inverter production to these regions despite eastern Germany's lower labor costs. German manufacturing draws from Chinese ceramic glass substrates, Chilean copper cathodes, and Taiwanese semiconductor components. Single-source vulnerability in IGBT inverter modules creates procurement risk given EU F-Gas Regulation compliance deadlines. Distribution runs through trade-direct specification channels serving kitchen renovation contractors, bypassing traditional retail for built-in configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German induction hob procurement functions as a geographic-arbitrage play between Bavaria's engineering density and Baden-Württemberg's underpenetrated renovation markets, with KBA efficiency enforcement creating compliance cost differentials that favor incumbent manufacturing footprints.
For Market Incumbents: Deepen captive supply of semiconductor control systems to offset relay architecture phase-out costs and defend against Asian modular competitors. Expand bridge-zone engineering capacity in Bavaria to capture Hamburg waterfront regeneration specifications. Prioritize firmware engineering recruitment given scarcity in traditional appliance teams.
For New Entrants and Emerging Players: Kitchen studio partnerships offer fastest channel access for specification influence in Munich and Frankfurt luxury towers. Target Stuttgart and Karlsruhe housing markets where renovation intensity lags Bavaria. Lead with portable and slide-in configurations for Berlin's tenant-heavy districts where permanent installation is restricted.
For Investors and Strategic Acquirers: Roll-up economics work for precision coil engineering specialists because KBA certification requirements create fragmented vendor bases with high switching costs for OEM customers. Five-to-ten year viability hinges on EU F-Gas Regulation compliance capabilities in thermal management. Monitor amendments to MEPS tiers as inflection indicator for redesign cycle intensity and component sourcing shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coil Manufacturing | Captive copper coil production insulates BSH and Miele from raw material volatility while accelerating KBA certification timelines. |
| Bridge-Zone Technology Licensing | Electrolux's modular configurations command specification premiums in Hamburg and Frankfurt open-plan kitchen developments. |
| Semiconductor Control System Migration | Replacement of relay architectures with firmware-driven inverters satisfies national energy regulator standby power limits. |
| Baden-Württemberg Distribution Expansion | Stuttgart and Karlsruhe housing stock modernization offers headroom for double-coil and booster-function penetration. |
| Connected Diagnostics Platform Launch | IoT-enabled remote monitoring compresses warranty costs for Berlin luxury residential towers while opening software revenue streams. |
Research Methodology
Multiple input streams — primary interviews with appliance engineering directors, kitchen studio specification consultants, and KBA certification officers, alongside secondary validation through BSI technical documentation, EU Ecodesign Directive amendment tracking, and customs trade data — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations captured coil sourcing strategies, inverter thermal management redesign timelines, and trade-direct channel shift dynamics. Secondary sources included CE marking registration databases, Bavarian economic development agency manufacturing surveys, and North Rhine-Westphalian housing renovation permit filings.
Data-stream reconciliation anchored volume and value outputs to segmentation dimensions spanning installation type, coil configuration technology, application intensity, and end-user procurement authority across the projection horizon. CAGRs derived from housing stock age profiles, renovation cycle frequencies, and efficiency regulation compliance cost curves. Industry-specific forecast inputs incorporated copper price volatility scenarios and EU F-Gas Regulation amendment timelines for semiconductor cooling system redesigns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MEPS tier escalations, raw material supply disruptions, and electromagnetic compatibility certification backlog durations. Forecasts reflect documented assumptions regarding renovation intensity persistence in Bavaria and North Rhine-Westphalia. Material deviation in KBA efficiency benchmark amendments or Chilean copper export restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Global Residential Robotic Vacuum Cleaner Market
Household Items
Europe & UK Nonstick Cookware Market
Household Items
Europe Electric Cordless Lawn and Garden Tools Market
Household Items
Smart Bath Heater Market
Household Items
Pet Fur Remover Market
Household Items
Cutlery Market
Household Items
Hand Dryer Market
Household Items
Portable Car Vacuum Market
Household Items
Chest Freezers Market
Household Items
UK Digital Showers Market
Household Items
Mexico Cookware Market
Household Items
Permanent Marker Market
Household Items
Cutlery Steel Market
Household Items
Replacement Sheets Market
Household Items
United States Barbeque Grill Market
Household Items
North America Liquid Hand Soap Market