
 Pocket Tissues Market | 2026-2036
Pocket Tissues Market Size, Share, and Industry Trends Forecast 2026-2036
Pocket Tissues Market Analytics
Bamboo pulp is restructuring cost structures across the pocket tissues supply chain as mills diversify from virgin wood fiber. Georgia-Pacific leverages its integrated pulp network to stabilize input costs across North American production. Essity anchors European manufacturing with concentrated R&D spending on thin-gauge, high-tensile sheet formats. Kimberly-Clark competes through proprietary embossing technology that extends brand recognition in the premium pouch segment.
Pocket tissues are portable, multi-ply cellulose sheets, typically two to four layers bonded through mechanical pressing, designed for personal hygiene, makeup removal, and surface wiping in transit or confined spaces. The antibacterial product type commands margin premiums in hospital and hotel end-use channels where infection control protocols elevate specification requirements. Eco-friendly variants, incorporating recycled fibers or plant-based packaging, represent the fastest-growing segment as procurement policies at Sofidel Group's commercial clients harden sustainability clauses. Standard pocket packs dominate volume through convenience store and supermarket distribution, though refill formats gain traction in Japanese household subscriptions.
The US EPA regulates pulp bleaching effluent under Cluster Rules, while the EU Ecolabel and FSC chain-of-custody certification shape product access to European retail shelves. Japan's METI enforces quality labeling standards that differentiate pharmaceutical-grade moist tissues from cosmetic wipes, segmenting compliance burdens. Stakeholders must monitor cellulose futures volatility and emerging state-level packaging extended producer responsibility laws as these forces compound sourcing decisions.
Market Dynamics
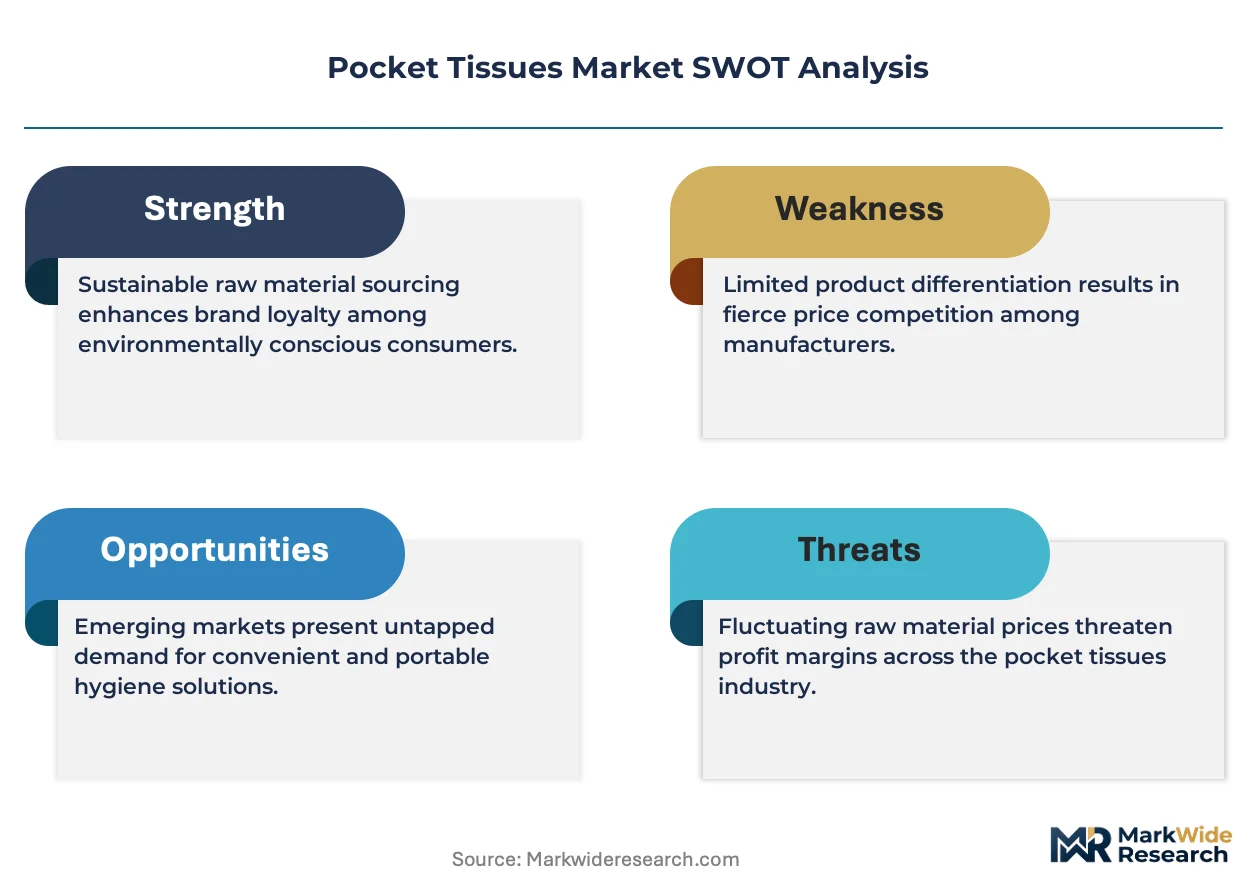
The EU Green Deal's single-use plastics directive is forcing pulp converters toward FSC-certified sourcing and biodegradable film laminates, compressing legacy supply chains while opening premium positioning for compliant manufacturers.
Growth Catalysts
- EU Ecolabel penetration:Retailers in Germany and France now mandate chain-of-custody certification for shelf placement, pulling volume toward verified sustainable suppliers.
- Travel and hospitality procurement:Hotel amenity programs are expanding antibacterial and moist tissue specifications as infection control protocols harden across airport lounges and boutique properties.
- Japan's compact urban lifestyles:METI labeling standards and dense metropolitan transit patterns sustain premium pocket pack consumption through convenience-oriented household subscriptions.
Market Restraints
- Cellulose futures volatility:Hardwood pulp price swings destabilize converter margins, particularly for non-integrated mills dependent on spot market purchasing.
- Supply concentration in Nordic regions:Bleached softwood kraft pulp production clusters in Sweden and Finland, creating geographic vulnerability to energy cost shocks and transport disruptions.
- Technical limitation in wet-strength chemistry:Current temporary wet-strength resins degrade inconsistently in municipal composting streams, limiting biodegradability claims.
Strategic Opportunities
- Underpenetrated Indian urban transit:Metro system expansion in Mumbai, Delhi, and Bangalore creates distribution nodes for single-serve hygiene products targeting commuter density.
- Pharmaceutical-grade moist tissue segment:PMDA and METI regulatory differentiation between cosmetic wipes and sanitary products opens margin-rich hospital and eldercare channels.
- Refill format innovation:Japanese subscription services are pioneering compact refill cartridges that reduce packaging waste while locking in recurring revenue streams.
Industry Challenges
- Certification timeline compression:FSC and EU Ecolabel audit cycles lag behind retailer sustainability deadlines, forcing converters to carry dual-certified inventory.
- Biodegradable film integration:PLA and PHA-based packaging requires heat-sealing equipment retrofits that strain mid-capitalization producer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pocket Tissues Market |
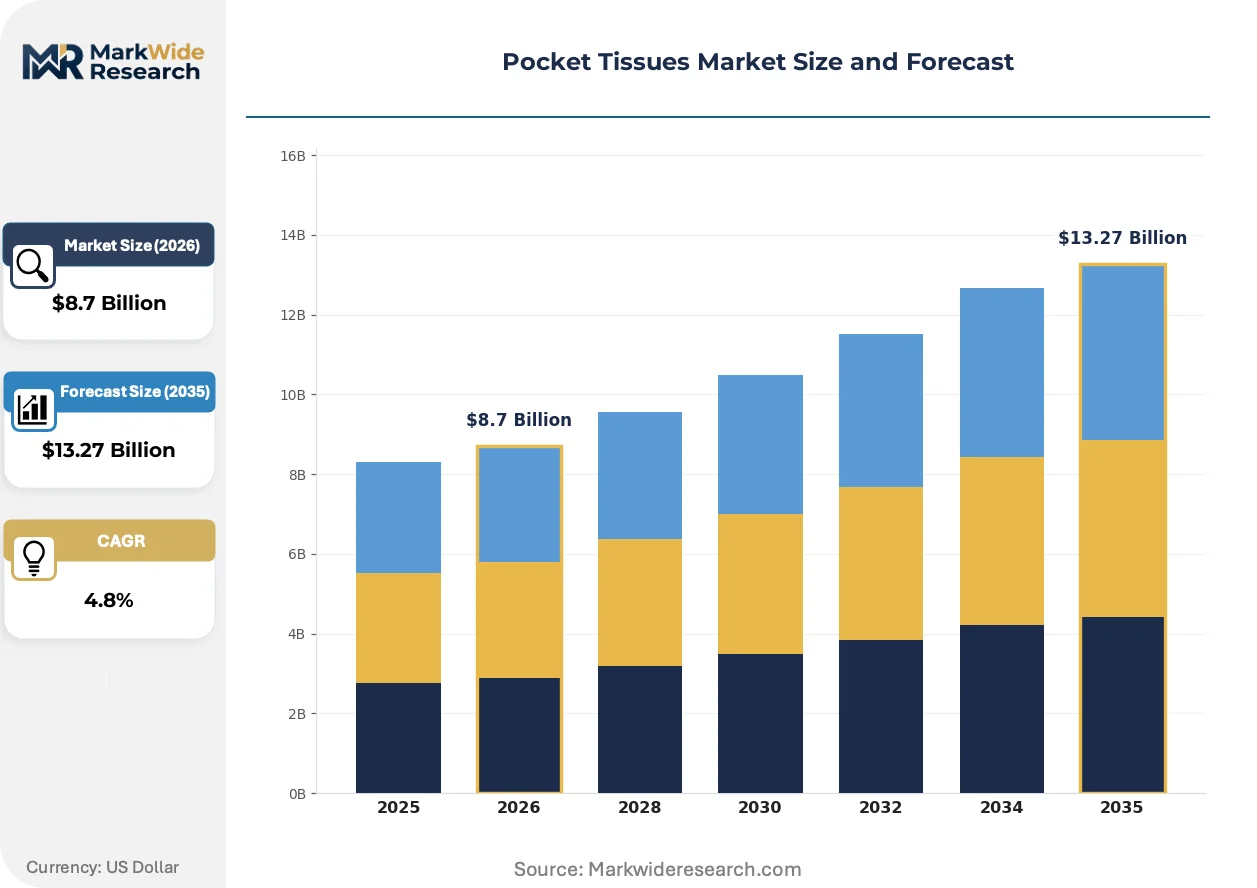
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Antibacterial, Moist, Eco-friendly Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Drugstores End User: Households, Offices, Hospitals, Hotels Packaging Type: Boxed, Pouch, Pocket Pack, Refill |
| Companies Covered | Georgia-Pacific, Sinar Mas, Essity, Hengan, CMPC, Kimberly-Clark, Sofidel Group, First Quality Tissue, Procter & Gamble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pocket Tissues Market Evolving Landscape
Material science advances and regulatory stringency are converging to redefine product architecture and supply chain accountability across the pocket tissues value chain.
Bamboo pulp fiber processing is rewriting cost structures and sustainability credentials simultaneously. Mills in Sichuan and Zhejiang provinces are commissioning dedicated bamboo dissolving pulp lines that reduce water intensity versus hardwood kraft cooking. Hospitality procurement teams in Singapore and Hong Kong are fast-tracking supplier qualification for bamboo-based amenity programs. The technology is compressing the premium pricing gap between virgin wood fiber and alternative cellulose sources.
REACH chemical registration requirements are tightening restrictions on formaldehyde-based wet-strength resins used in moist tissue formulations. The European Chemicals Agency's 2023 substance evaluation roadmap has accelerated converter migration to glyoxal and polyamide-amine-epichlorohydrin alternatives. Pharmaceutical-grade moist tissue producers face reformulation costs that disproportionately burden small-batch contract manufacturers serving hospital networks.
Buyer concentration among consolidated retail banners is compressing supplier negotiation leverage. Carrefour and Auchan in France, Aeon and Seven & I in Japan, and Target in the United States are consolidating category management into centralized sustainability-scorecard frameworks. Regional converters must now submit Scope 3 emissions data to maintain listing status. The shift is most visible in Western European mass retail, where private-label penetration in pocket tissues exceeds branded volume.
Pocket Tissues Market Segmentation
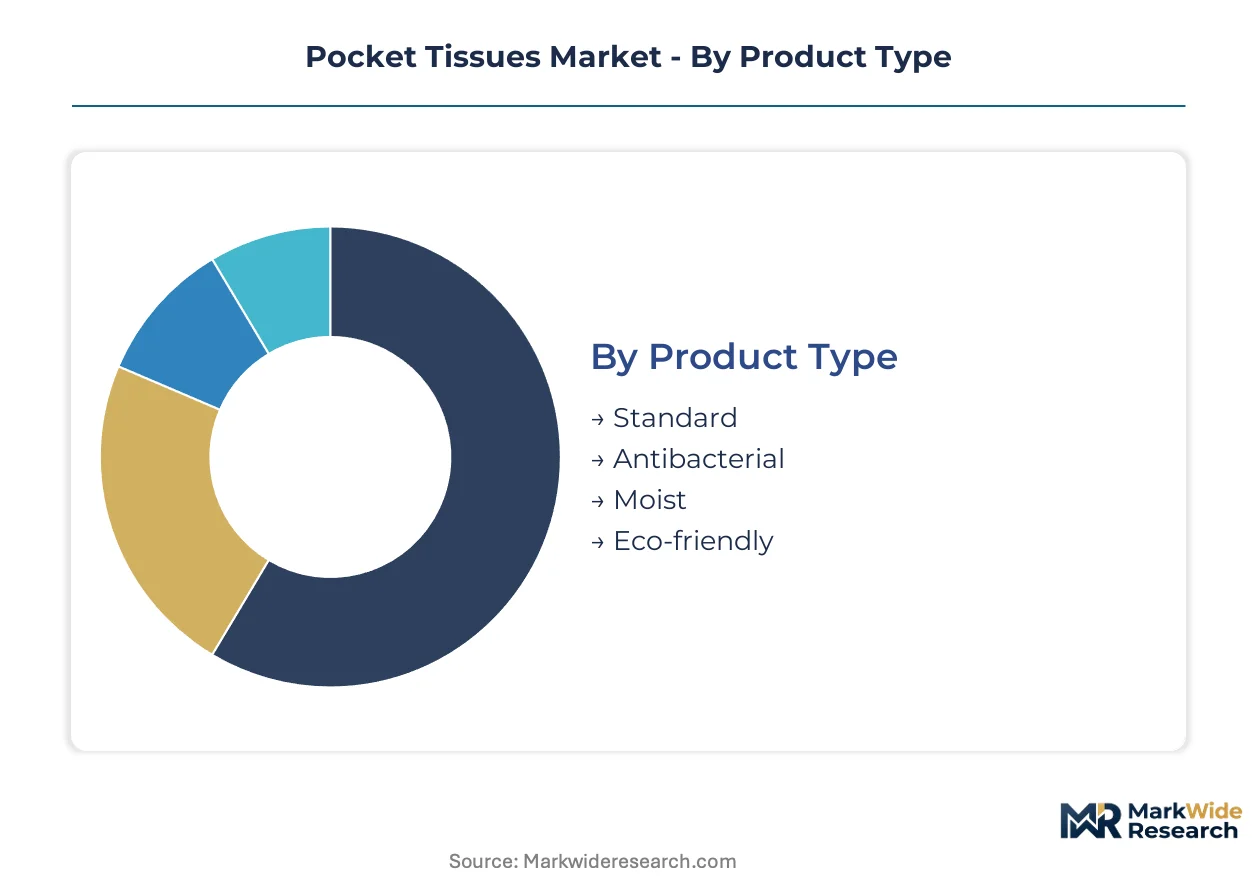
Pocket tissues serve discrete use cases ranging from emergency transit hygiene to pharmaceutical-grade infection control, making product architecture and channel strategy inseparable. Segment boundaries blur as hospitality procurement teams bundle antibacterial and eco-friendly specifications into single amenity contracts.
Product Type:
Standalone functional differentiation drives tiered pricing and regulatory classification across the four product architectures.
- Standard:Two-to-four-ply dry cellulose sheets bonded through mechanical pressing without chemical additives. Convenience store networks in Japan and Germany move the highest unit volumes through impulse-purchase placement near checkout terminals.
- Antibacterial:Sheets impregnated with benzalkonium chloride or triclosan alternatives meeting hospital-grade disinfection protocols. Infection control procurement at airport lounges and boutique hotels commands margin premiums above standard formats.
- Moist:Pre-moistened tissues utilizing temporary wet-strength resins for durability during surface wiping. METI and PMDA labeling standards in Japan segment these between cosmetic and pharmaceutical classifications.
- Eco-friendly:Bamboo pulp or recycled fiber content paired with biodegradable film laminates. FSC-certified sourcing requirements under the EU Green Deal are compressing legacy supply chains toward this architecture.
Standard leads volumes today; eco-friendly is gaining share fastest.
Distribution Channel:
Channel concentration shapes working capital requirements and shelf-life risk exposure for converters.
- Online Retail:Subscription services and bulk direct-to-consumer shipments. Japanese household refill programs pioneered this channel, locking recurring revenue through compact cartridge delivery.
- Supermarkets:Mass-volume placement with centralized sustainability-scorecard compliance. Carrefour and Auchan in France now mandate Scope 3 emissions data for listing maintenance.
- Convenience Stores:Impulse-purchase dominance through high-traffic transit nodes. Metro system expansion in Mumbai, Delhi, and Bangalore creates new distribution density for single-serve formats.
- Drugstores:Pharmaceutical-grade moist tissue placement alongside regulated sanitary products. Hospital network procurement channels converge here with eldercare institutional buyers.
Supermarkets anchor volume throughput; online retail is climbing the fastest.
End User:
User-type segmentation governs specification intensity and certification burden.
- Households:Volume consumption through convenience-oriented purchasing patterns. Dense metropolitan transit patterns in Japan sustain premium pocket pack subscriptions.
- Offices:Bulk procurement with standardized amenity programs. Corporate sustainability policies are hardening recycled fiber and plastic-free packaging requirements.
- Hospitals:Infection control protocols elevate antibacterial and pharmaceutical-grade moist tissue specifications. Reformulation costs for REACH-compliant wet-strength resins disproportionately burden small-batch contract manufacturers.
- Hotels:Guest amenity programs bundling multiple product types into unified sustainability clauses. Sofidel Group and comparable hospitality suppliers now require FSC chain-of-custody verification.
Households dominate absolute consumption; hospitals show the steepest specification escalation.
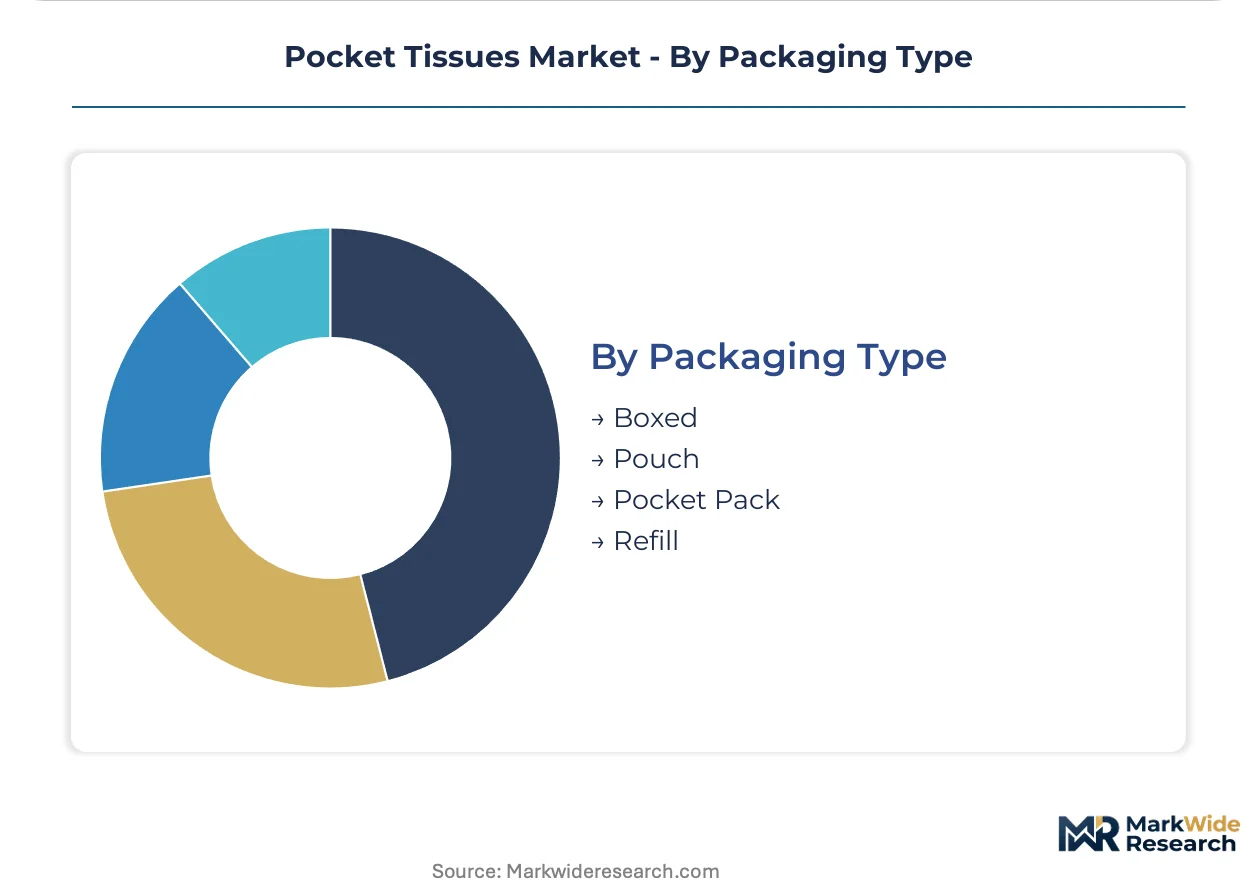
Packaging Type:
Format innovation is redefining waste reduction and replenishment economics.
- Boxed:Rigid cardboard housing for countertop placement in offices and hotel bathrooms. Standard format for bulk institutional procurement with minimal differentiation.
- Pouch:Flexible film packaging for travel and transit use. Kimberly-Clark's proprietary embossing technology extends brand recognition in this premium segment.
- Pocket Pack:Ultra-compact 6-to-10-sheet formats designed for garment storage. METI labeling standards and compact urban lifestyles in Japan sustain category premiumization.
- Refill:Cartridge-based replenishment systems reducing per-use packaging mass. Japanese subscription services are pioneering this architecture with locked-in recurring revenue mechanics.
Pocket pack leads unit shipments; refill formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's metropolitan transit corridors and premium retail infrastructure anchor the highest per-capita pocket tissue consumption worldwide. Dense urban populations in Tokyo and Osaka sustain compact-format demand through convenience-oriented purchasing patterns. The report examines five critical national markets where regulatory frameworks and distribution density shape competitive positioning.
Japan
Compact urban lifestyles in Tokyo and Osaka sustain premium pocket pack consumption through subscription-based household replenishment. METI labeling standards differentiate pharmaceutical-grade moist tissues from cosmetic wipes, segmenting compliance burdens across hospital and retail channels. Convenience store networks in the Kanto region move the highest unit volumes through impulse-purchase placement near transit terminals.
Germany
Retailers in Berlin and Munich now mandate EU Ecolabel chain-of-custody certification for shelf placement, pulling volume toward verified sustainable suppliers. The EU Green Deal's single-use plastics directive pressures converters toward FSC-certified pulp and biodegradable film laminates. Bleached softwood kraft pulp production clusters in Hamburg and surrounding Nordic supply corridors create geographic vulnerability to energy cost shocks.
United States
Georgia-Pacific leverages integrated pulp networks to stabilize input costs across North American production facilities in the Southeast. The US EPA regulates pulp bleaching effluent under Cluster Rules, shaping mill compliance investments. Target and comparable mass retailers consolidate category management into centralized sustainability-scorecard frameworks requiring Scope 3 emissions data submission.
China
Mills in Sichuan and Zhejiang provinces commission dedicated bamboo dissolving pulp lines that reduce water intensity versus hardwood kraft cooking. The country's dual carbon goals accelerate converter migration toward alternative cellulose sources. Metro system expansion in Shanghai and Beijing creates distribution nodes for single-serve hygiene products targeting commuter density.
India
Underpenetrated urban transit corridors in Mumbai, Delhi, and Bangalore present distribution opportunities for pocket tissue formats targeting commuter density. The BIS quality certification framework governs sanitary product standards, though enforcement remains fragmented across states. Convenience retail expansion along metro corridors in Maharashtra and Karnataka establishes new points of sale for impulse-purchase categories.
Pocket Tissues Market Competitive Landscape
Global majors compete with regional champions across integrated pulp supply chains and proprietary embossing technologies. The market exhibits tiered consolidation with scale-driven multinationals, mid-cap regional specialists, and private-label contract manufacturers occupying distinct competitive positions. Strategic archetypes include vertically integrated pulp-to-retail operators, technology-differentiated premium brands, and sustainability-certified niche suppliers. Dominant competitive moves center on backward integration into pulp assets and heat-sealing equipment retrofits for biodegradable film compliance.
Among North American integrated producers, Georgia-Pacific and Kimberly-Clark occupy positions exemplifying scale-driven pulp network leverage and proprietary embossing technology differentiation respectively. European specialists Essity and Sofidel Group represent the sustainability-certified tier, with the latter anchoring hospitality procurement channels through FSC chain-of-custody verification. Asia-Pacific regional champions Hengan and Sinar Mas sit within the bamboo pulp diversification archetype, reflecting alternative fiber sourcing strategies emerging from Sichuan and Indonesian production bases.
| Leading Market Players |
|---|
| Georgia-Pacific |
| Sinar Mas |
| Essity |
| Hengan |
| CMPC |
| Kimberly-Clark |
| Sofidel Group |
| First Quality Tissue |
| Procter & Gamble |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap converters in Zhejiang and Sichuan provinces anchor supply-side discipline through captive bamboo pulp operations, compressing cost variability and enabling aggressive pricing against Nordic softwood-dependent competitors serving EU Ecolabel mandates.
Pricing Analysis
Hardwood pulp futures pass through to converter pricing within one to two contract cycles, with non-integrated mills bearing margin compression during spot market spikes. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified eco-friendly variants from commodity standard packs and private-label economy tiers. Pricing pressure stems from buyer concentration at Carrefour, Aeon, and Target, whose sustainability-scorecard compliance costs disproportionately burden small-batch producers. Household subscribers through Japanese refill services show lowest price sensitivity; Indian convenience retail channels exhibit highest elasticity to per-unit packaging costs.
Supply Chain Analysis
Direct-to-hospitality channels handle infection-control specification demand through contracted long-term offtake agreements with Sofidel Group and comparable amenity suppliers. Geographic supply concentration centers on Sweden and Finland for bleached softwood kraft pulp, Sichuan and Zhejiang for bamboo dissolving pulp, and Indonesia for tropical hardwood alternatives. Raw material dependencies include cellulose fiber, temporary wet-strength resins, and PLA-based biodegradable films. Single-source vulnerability in Nordic energy-intensive pulp production creates exposure to electricity cost shocks. Distribution runs through consolidated retail banners in Western Europe, convenience store networks in Japanese transit corridors, and emerging metro-linked nodes in Indian urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's single-use plastics directive compounds regulatory compliance costs into competitive moats, with FSC chain-of-custody certification now a table-stakes requirement for European retail access.
For Market Incumbents: Deepen backward integration into bamboo pulp assets in Sichuan and Zhejiang to offset Nordic softwood cost volatility and anchor eco-friendly tier margins. Secure dual FSC-EU Ecolabel certification ahead of retailer deadline compression to lock out mid-cap competitors dependent on audit cycle lag. Prioritize heat-sealing equipment retrofits for PLA film compatibility before biodegradable packaging mandates harden. For New Entrants and Emerging Players: Launch via Indian metro corridor convenience retail to exploit underpenetrated commuter hygiene demand in Mumbai, Delhi, and Bangalore. Target pharmaceutical-grade moist tissue segments where PMDA and METI regulatory differentiation creates margin-rich hospital and eldercare channels underserved by commodity converters. Pursue white-label manufacturing partnerships with hospitality procurement teams bundling antibacterial and sustainability specifications. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap regional converters with FSC pre-certification and bamboo pulp sourcing relationships already established. Long-term viability favors suppliers with locked-in Japanese subscription revenue mechanics and refill format IP. Watch cellulose futures backwardation as inflection signal for margin expansion opportunity in non-integrated converter acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| FSC Chain-of-Custody Certification | EU Ecolabel and retailer scorecard mandates now require verified sustainable sourcing for shelf placement. |
| Bamboo Pulp Capacity Expansion | Sichuan and Zhejiang mills reduce water intensity versus hardwood kraft while compressing premium pricing gaps. |
| Refill Format Innovation | Japanese subscription services pioneer compact cartridges that reduce packaging waste and lock recurring revenue. |
| Biodegradable Film Integration | PLA and PHA packaging requires heat-sealing retrofits that strain mid-cap balance sheets but open premium positioning. |
| Pharmaceutical-Grade Moist Tissue Development | PMDA and METI regulatory differentiation opens margin-rich hospital and eldercare procurement channels. |
Research Methodology
Bottom-up household consumption modeling reconciled against top-down pulp production tracking forms the analytical core of this study. Primary interviews with category buyers at Carrefour and Aeon, hospitality procurement managers at Sofidel Group, plant managers at Sichuan bamboo pulp mills, and METI regulatory affairs specialists combined with secondary validation from customs trade data, FSC chain-of-custody databases, EU Ecolabel registries, and cellulose futures exchange records. Triangulation across these sources calibrated volume estimates and pricing elasticity assumptions.
Historical trendline analysis of per-capita pocket tissue consumption across Japanese metropolitan transit corridors, German retail sustainability-scorecard adoption curves, and Indian metro system expansion timelines informed projection mechanics. Segmentation dimensions modeled include product type, distribution channel, end user, and packaging format across the analysis window. CAGRs derived from elasticity-adjusted demand curves incorporating regulatory compliance cost pass-through and alternative fiber substitution rates. Forecast inputs included pulp price volatility scenarios and retailer consolidation patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under cellulose futures spike conditions or accelerated EU packaging extended producer responsibility implementation. Periodic stress-testing of base assumptions is recommended given regulatory timeline uncertainty and emerging state-level sustainability mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Global Nap Pod Market
Household Items
Toilet Rim Blocks Market
Household Items
Soap Tablet Market
Household Items
Range Hood Cleaning Service Market
Household Items
Collapsible Water Bottle Market
Household Items
Sanitary Napkin Vending Machine Market
Household Items
Disposable Cutlery Market
Household Items
Washing Machine Cleaner Market
Household Items
Cast Iron Cookware Market
Household Items
Laundry Detergent Sheets Market
Household Items
Waterless Aroma Diffuser Market
Household Items
Toilet Brush Market
Household Items
Europe Hand Dryers Market
Household Items
Italy Digital Showers Market
Household Items
Global Disposable Toilet Seat Covers Market
Household Items
Portable Iron Market