
 Folded Tissues Market | 2026-2036
Folded Tissues Market Size, Share, and Industry Trends Forecast 2026-2036
Folded Tissues Market Insights
Scandinavian pulp-to-tissue supply chains is realigning around tighter environmental certification standards and shorter logistics loops. Essity Aktiebolag leverages its integrated pulp operations in Sweden to sustain cost-advantaged virgin fiber output for premium facial tissue lines. Kimberly-Clark Corporation anchors North American institutional demand through direct distribution contracts with hospital systems and foodservice operators.
Folded tissues are single-use cellulose-based wiping products manufactured through creping, embossing, and folding processes to achieve specified ply counts, absorbency rates, and dispensing compatibility. They serve hygiene, spill management, and skin-contact applications across consumer and professional settings. Facial tissues and paper towels lead volume, with facial tissues commanding higher per-unit margins in branded retail channels while paper towels dominate commercial and hospitality procurement through wholesale distribution. Recycled paper and bamboo materials are gaining structural traction as virgin pulp cost volatility and ESG procurement mandates reshape material sourcing.
EPA guidelines govern recycled content claims in the United States, while REACH and EU Green Deal frameworks restrict chemical additives and mandate carbon disclosure across European tissue supply chains. FDA oversight applies to tissues marketed with antimicrobial or medical-grade claims, creating compliance thresholds for healthcare channel entry. Stakeholders must monitor evolving ECHA substance restrictions and retailer-specific sustainability scorecards that increasingly determine shelf access and contract eligibility.
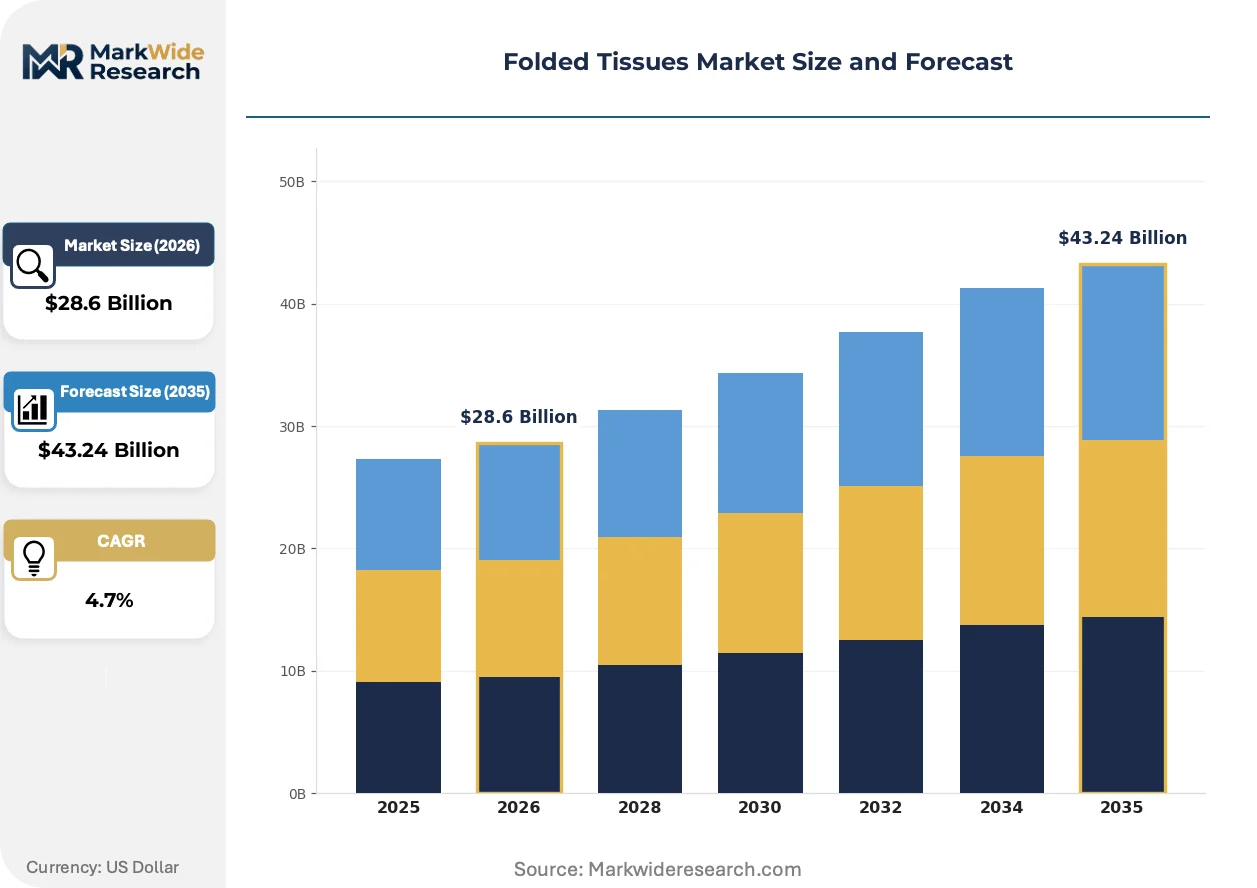
Market Dynamics
EU Green Deal carbon disclosure mandates and F-Gas Regulation phase-downs are restructuring fiber sourcing economics, forcing converters to decouple from long-haul pulp supply chains and regionalize production around certified sustainable feedstocks.
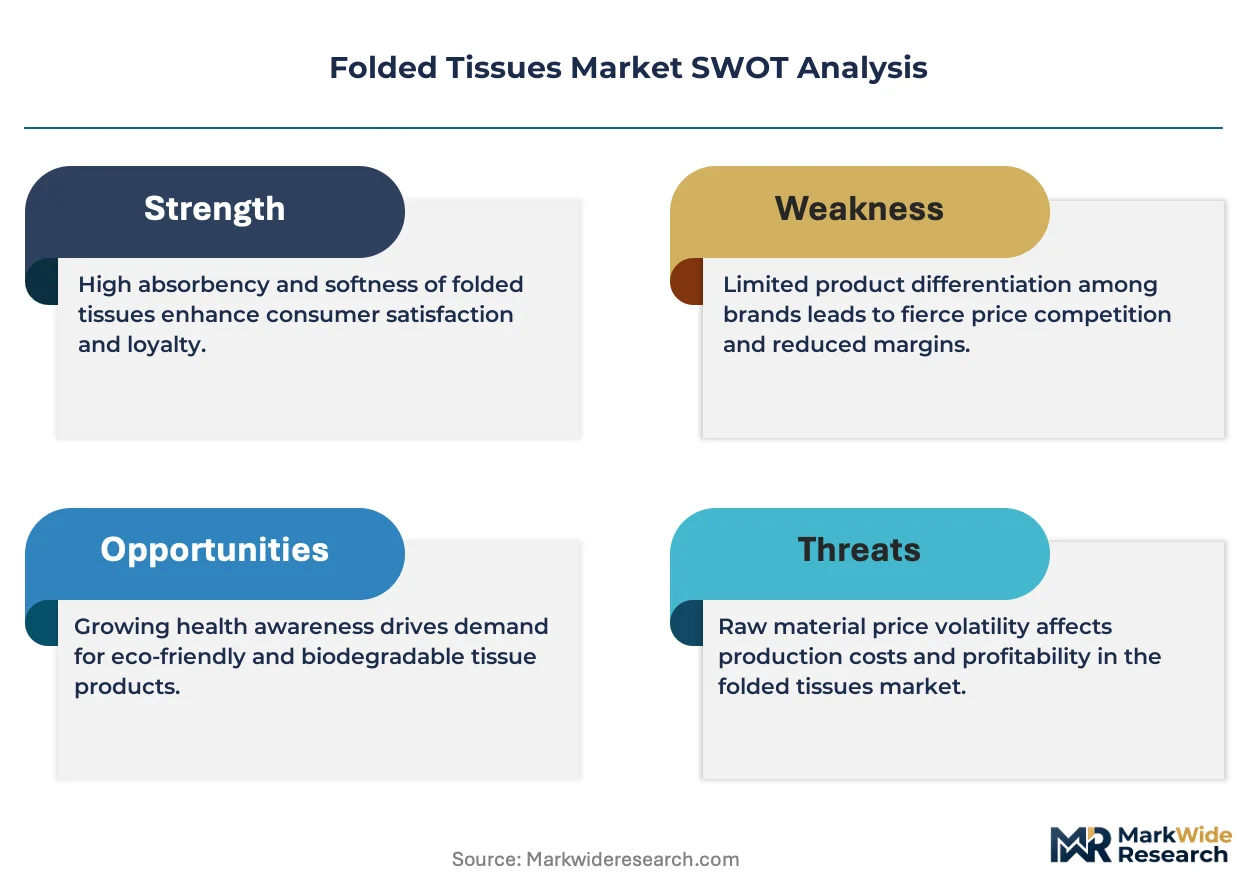
Growth Catalysts
- Healthcare infection control protocols:Hospital systems in Germany and France are mandating single-use folded tissues in patient-contact zones, expanding institutional procurement volumes beyond traditional janitorial supply contracts.
- REACH chemical restriction enforcement:ECHA substance restrictions on formaldehyde-based wet-strength agents are accelerating migration to enzymatic bonding technologies in European tissue converting.
- Bamboo fiber cultivation expansion:Plantation development in Sichuan Province is absorbing virgin pulp cost volatility by providing mechanically processed alternative fibers for mid-tier facial tissue lines.
Market Restraints
- Scandinavian pulp supply concentration:Integrated Nordic producers control 60% of European bleached softwood kraft supply, creating feedstock bottleneck risk for independent converters.
- Natural gas price volatility:Drying and creping operations remain energy-intensive; German tissue mills face margin compression from grid-dependent thermal costs.
- Competing nonwoven substrates:Spunlace wipes in foodservice and industrial cleaning applications are capturing spill-management volume from multi-fold paper towels.
Strategic Opportunities
- CSRD-aligned carbon accounting services:Tissue converters can bundle Scope 3 disclosure documentation with bulk supply contracts to capture ESG-mandated procurement budgets.
- Compostable certification pathways:OK Compost INDUSTRIAL and HOME labels unlock municipal and corporate zero-waste program eligibility in France and Benelux markets.
- Direct-to-facility distribution platforms:Bypassing wholesale janitorial distributors through contracted logistics partnerships with hospital group purchasing organizations reduces working capital cycles.
Industry Challenges
- Skilled creping technician scarcity:Yankee dryer operation and coating chemistry expertise is retiring faster than vocational programs replenish qualified personnel.
- Multi-standard certification overlap:Simultaneous pursuit of EU Ecolabel, Nordic Swan, and Blue Angel creates conflicting technical specifications and testing cost duplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Folded Tissues Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Tissues, Toilet Tissues, Paper Towels, Napkins Application: Residential, Commercial, Healthcare, Hospitality Distribution Channel: Supermarkets, Online Retailers, Drugstores, Wholesale Material: Recycled Paper, Virgin Pulp, Bamboo, Others |
| Companies Covered | Kimberly-Clark Corporation, Essity Aktiebolag, Asia Pulp & Paper Group PT, SOFIDEL Group, Georgia-Pacific LLC, Napco National, Wepa Hygieneprodukte GmbH, Cascades USA, Inc., Metsa Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Folded Tissues Market Trends and Innovations
Active investment in enzymatic debonding, through-air drying retrofits, and blockchain-tracked fiber provenance is compressing legacy asset lifecycles and redefining premium positioning beyond ply count and embossing patterns.
Bamboo-pulp hybrid formulations are absorbing price volatility in virgin softwood markets while meeting Nordic Swan chemical restrictions. Quick-service restaurant chains in the Netherlands and Belgium are piloting these substrates for napkin and dispenser-towel applications. The structural consequence is margin compression for unbleached recycled furnish producers unable to match softness performance at equivalent carbon intensity claims.
The EU F-Gas Regulation phase-down is eliminating hydrofluorocarbon-based through-air drying assistance in tissue machines, compelling converters to adopt infrared or microwave drying augmentation. German engineering firms are retrofitting existing Yankee hoods with electric booster systems. Tissue grades requiring high bulk-to-basis-weight ratios face capital-intensive reconfiguration or output reduction.
Healthcare procurement consolidation is compressing supplier rosters and unbundling after-sales technical service from product supply. French hospital group purchasing organizations now mandate on-site dispenser compatibility audits and usage analytics reporting as contract preconditions. This behavioral shift concentrates volume with converters possessing integrated field service capabilities and IoT-enabled consumption monitoring infrastructure.
Folded Tissues Market Segmentation
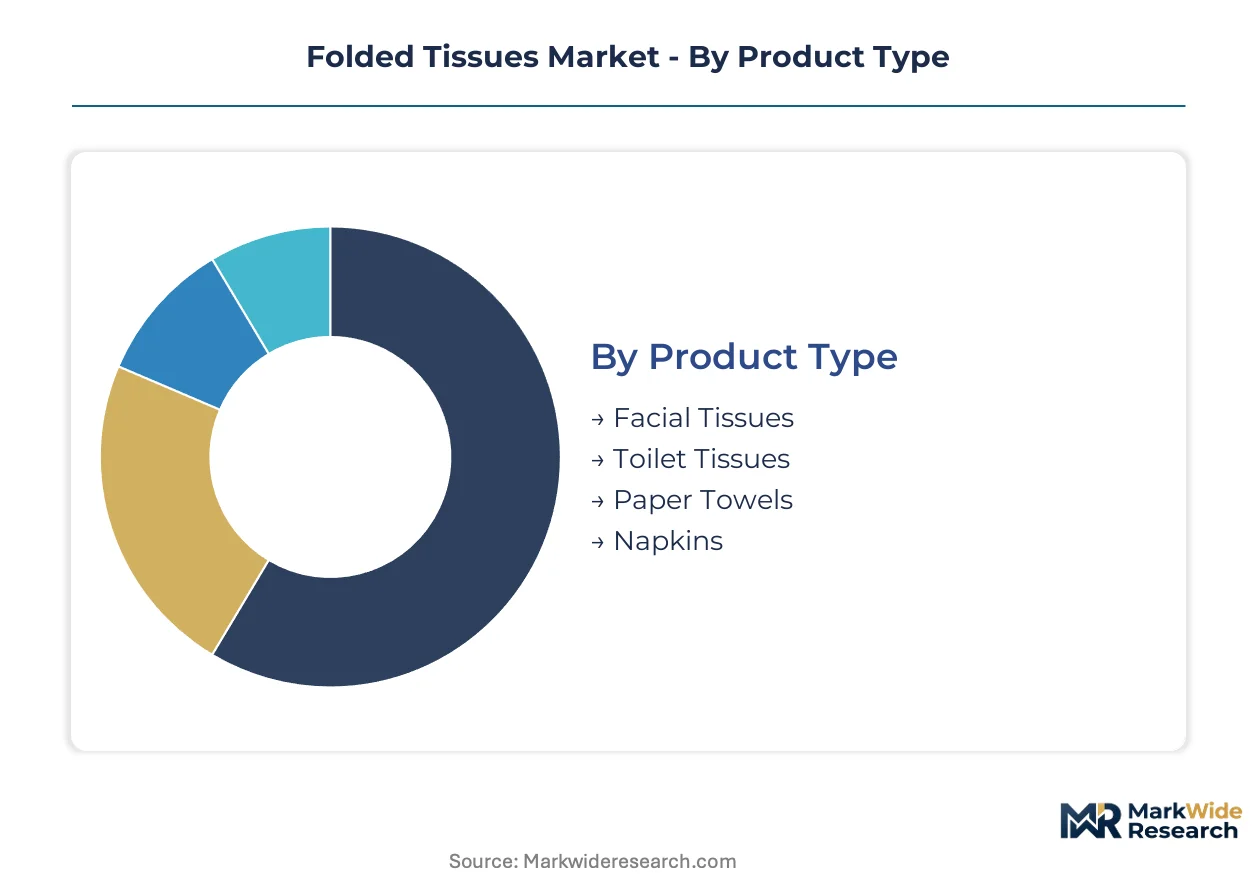
Folded tissue procurement patterns diverge sharply across end-use contexts. Healthcare buyers prioritize infection control specifications while hospitality operators optimize for dispenser compatibility and unit economics. Understanding these fault lines reveals where margin pools concentrate and which material innovations gain commercial traction.
Product Type:
Cost tier separates mass-market volume from premium margin capture.
- Facial Tissues:Softwood-dominant creped sheets with lotion or aloe additives for skin-contact applications. German drugstore chains and French pharmacy networks drive branded premium lines where Nordic Swan certification commands shelf placement.
- Paper Towels:Higher basis-weight multi-ply constructions optimized for absorbency and wet strength. Quick-service restaurant chains in the Netherlands and Belgium absorb volume through dispenser-system contracts that lock in proprietary fold formats.
- Toilet Tissues:Rolled and folded formats for institutional washrooms, with jumbo rolls dominating high-traffic commercial installations.
- Napkins:Lower ply-count disposable wiping products for foodservice table settings, with recycled furnish gaining share in corporate catering procurement.
Volume sits with paper towels; growth tilts toward facial tissues.
Application:
Customer type dictates specification intensity and contract structure.
- Healthcare:FDA-regulated single-use tissues for patient-contact zones with mandatory sterility documentation. French hospital group purchasing organizations now require on-site dispenser audits and usage analytics as contract preconditions.
- Commercial:Janitorial supply contracts covering office buildings, retail centers, and educational facilities where bulk procurement and logistics reliability outweigh softness performance.
- Residential:Branded retail consumption through supermarkets and online channels, with subscription models capturing recurring purchase behavior in urban markets.
- Hospitality:Property-branded amenity programs where embossing customization and compact dispenser formats support premium positioning.
Contract value concentrates in healthcare; expansion accelerates fastest in hospitality.
Distribution Channel:
Geography determines channel efficiency and working capital requirements.
- Supermarkets:High-velocity retail environments where shelf space allocation follows Nielsen velocity data and retailer sustainability scorecards. German REWE and EDEKA chains enforce EU Green Deal-aligned carbon disclosure for own-label tissue listings.
- Wholesale:Institutional procurement through janitorial distributors serving facility management contractors. Direct-to-facility platforms are bypassing these intermediaries in French and Belgian hospital networks.
- Online Retailers:Subscription and bulk-purchase platforms capturing pantry-loading behavior and corporate reorder automation.
- Drugstores:Premium facial tissue placement with pharmacy-adjacent health positioning and travel-format impulse purchases.
Supermarkets anchor volume; online channels are climbing the fastest.
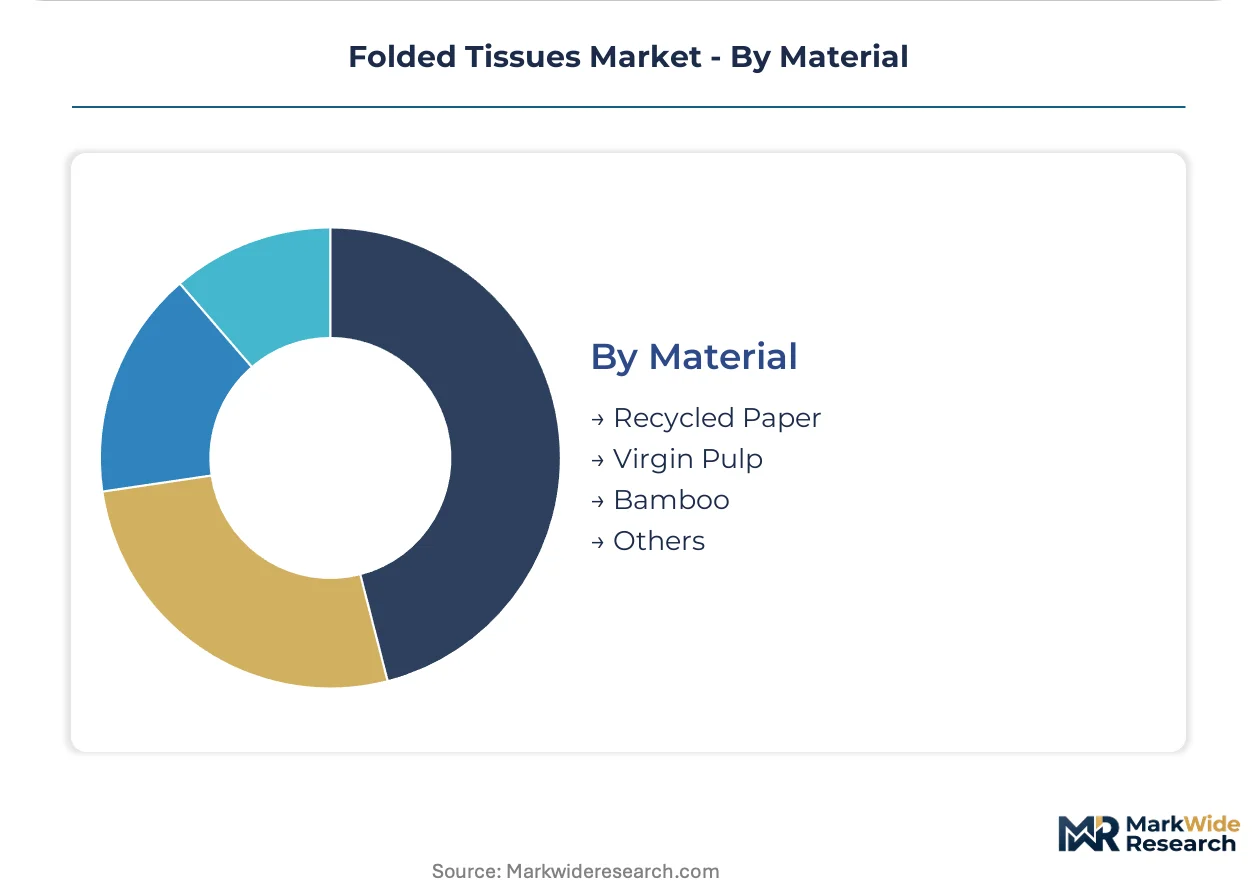
Material:
Supply concentration and ESG compliance reshape sourcing economics.
- Virgin Pulp:Bleached softwood kraft from Scandinavian integrated producers delivering premium softness and strength. Nordic supply concentration creates feedstock bottleneck risk for independent European converters.
- Recycled Paper:Post-consumer furnish governed by EPA recycled content claims in the United States and EU Ecolabel thresholds. REACH chemical restrictions on formaldehyde-based wet-strength agents limit performance parity with virgin grades.
- Bamboo:Mechanically processed alternative fiber from Sichuan Province plantations absorbing virgin pulp price volatility. Quick-service restaurant pilots in the Netherlands validate compostable certification pathways.
- Others:Emerging agricultural residues and textile fiber blends in early-stage commercialization for specialized industrial wiping applications.
Virgin pulp dominates current volume; bamboo and recycled furnish are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scandinavian bleached softwood kraft supply anchors European tissue manufacturing, while Sichuan bamboo plantations and integrated pulp-to-tissue complexes in Germany reshape feedstock economics across the value chain.
Germany
Hospital group purchasing organizations in North Rhine-Westphalia mandate single-use folded tissues for infection control protocols, expanding institutional procurement volumes. The EU Green Deal carbon disclosure requirements pressure Wepa Hygieneprodukte GmbH and SOFIDEL Group facilities to regionalize around certified sustainable feedstocks. Düsseldorf and Mannheim converting clusters serve pan-European institutional buyers through direct distribution contracts.
United States
FDA-regulated healthcare procurement and EPA recycled content claims govern tissue supply to hospital systems and foodservice operators. Kimberly-Clark Corporation anchors institutional demand through direct distribution contracts with hospital networks. Georgia-Pacific LLC operates large-scale converting capacity in the Southeast serving quick-service restaurant chains through dispenser-system lock-in contracts.
Sweden
Integrated pulp operations deliver cost-advantaged virgin fiber output for premium facial tissue lines serving Nordic and continental European retail channels. Essity Aktiebolag leverages captive softwood kraft supply to sustain margin capture in branded segments. Stockholm and Gothenburg production clusters face feedstock bottleneck risk as independent converters compete for residual Scandinavian pulp availability.
China
Sichuan Province bamboo plantation development absorbs virgin pulp price volatility for mid-tier facial tissue formulations. Asia Pulp & Paper Group PT and domestic converters pilot mechanically processed alternative fibers for quick-service restaurant napkin applications. Yangtze River Delta tissue mills face dual carbon goals pressure to decouple from coal-dependent drying operations.
France
French hospital group purchasing organizations mandate on-site dispenser compatibility audits and usage analytics reporting as contract preconditions. REACH chemical restrictions on formaldehyde-based wet-strength agents accelerate migration to enzymatic bonding technologies in converting operations. Lille and Lyon industrial zones concentrate tissue finishing capacity serving Benelux and domestic healthcare procurement.
Folded Tissues Market Competitive Landscape
Global majors compete with regional champions across fiber integration and healthcare channel access, producing a tiered structure where scale-driven volume players, pulp-integrated specialists, and sustainability-certified niche operators coexist. Three archetypes dominate: integrated pulp-to-tissue conglomerates controlling feedstock economics, regional converters leveraging proximity to institutional buyers, and alternative-fiber pioneers capturing ESG-mandated procurement budgets. Competitive moves center on M&A for dispenser-system lock-in contracts and backward integration into certified sustainable fiber sourcing.
Within the integrated pulp-to-tissue tier, Essity Aktiebolag and Metsa Group exemplify Scandinavian feedstock control strategies, while Kimberly-Clark Corporation occupies a position anchoring North American institutional demand through healthcare and foodservice direct distribution. Wepa Hygieneprodukte GmbH represents the regional champion archetype, leveraging German manufacturing proximity to serve EU institutional procurement subject to EU Green Deal carbon disclosure mandates.
| Leading Market Players |
|---|
| Kimberly-Clark Corporation |
| Essity Aktiebolag |
| Asia Pulp & Paper Group PT |
| SOFIDEL Group |
| Georgia-Pacific LLC |
| Napco National |
| Wepa Hygieneprodukte GmbH |
| Cascades USA, Inc. |
| Metsa Group |
| Others |
Pricing and Supply Chain Analysis
French hospital group purchasing organizations concentrate procurement volumes through direct distribution contracts, locking in contract-based long-term offtake pricing that bundles dispenser-system compatibility audits and usage analytics reporting with tissue supply.
Pricing Analysis
After-sales technical service unbundling from product supply is reshaping contract structures across European healthcare procurement. Three-tier pricing structure across premium, standard, and economy levels separates Nordic Swan-certified facial tissues from standard institutional grades and unbleached recycled furnish. Price differentiation hinges on certification grade and volume scale, with branded retail channels capturing premium positioning while bulk janitorial contracts face cost compression from natural gas price volatility in German drying operations. Quick-service restaurant chains in the Netherlands and Belgium exhibit highest price sensitivity due to dispenser-system lock-in contracts, while hospital systems prioritize infection control specifications over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Scandinavian bleached softwood kraft supply, where integrated Nordic producers control the majority of European feedstock. Raw material dependencies center on virgin pulp from Sweden, bamboo fiber from Sichuan Province, and post-consumer recycled furnish governed by EPA and EU Ecolabel thresholds. Tariff exposure on Chinese bamboo pulp imports and regulatory restriction under REACH chemical limitations create structural risk for independent converters. Distribution runs through direct-to-facility platforms bypassing wholesale janitorial distributors in French and Belgian hospital networks, while supermarkets and online retailers anchor consumer-facing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The folded tissues market is transitioning from mechanical creping to enzymatic bonding technologies as REACH chemical restrictions eliminate formaldehyde-based wet-strength agents from European supply chains.
For Market Incumbents: Cement pulp integration advantages through captive softwood kraft supply in Scandinavia and backward integration into Sichuan bamboo plantation partnerships. Invest in IoT-enabled consumption monitoring infrastructure to meet French hospital group purchasing organization contract preconditions and defend against dispenser-system disintermediation by direct-to-facility platforms. For New Entrants and Emerging Players: Enter via compostable certification pathways targeting municipal and corporate zero-waste programs in France and Benelux markets. Capture ESG-mandated procurement budgets through OK Compost INDUSTRIAL and HOME labels, leveraging mechanically processed bamboo fiber to absorb virgin pulp price volatility in mid-tier facial tissue segments. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional converters with integrated field service capabilities in Germany and France. Long-term viability centers on CSRD-aligned carbon accounting service bundling and Scope 3 disclosure documentation capabilities. Monitor EU F-Gas Regulation phase-down timelines as inflection indicator for capital-intensive Yankee dryer retrofit requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Bonding Technology Adoption | ECHA REACH restrictions on formaldehyde-based wet-strength agents accelerate migration from legacy mechanical creping processes. |
| Backward Integration into Certified Fiber Sourcing | EU Green Deal carbon disclosure mandates reward converters controlling Nordic Swan-certified pulp supply chains. |
| Direct-to-Facility Distribution Platform Launch | French hospital group purchasing organizations now mandate bypassing wholesale janitorial distributors for contract eligibility. |
| Compostable Certification Investment | OK Compost INDUSTRIAL and HOME labels unlock municipal zero-waste program procurement in Benelux markets. |
| IoT-Enabled Consumption Monitoring Infrastructure | Usage analytics reporting is now a contract precondition for healthcare channel access in France. |
Research Methodology
Trade publications, customs records, and EU regulatory filings formed the secondary backbone of this analysis, cross-referenced against primary interviews with tissue converting plant managers, hospital procurement directors, janitorial distribution channel partners, and sustainability certification auditors. Bottom-up volume modeling triangulated against top-down macroeconomic indicators ensured segment-level consistency across product type, application, and material dimensions.
Historical trendline analysis established baseline growth trajectories across the projection horizon, with CAGR derivation incorporating fiber cost volatility indices, energy price scenarios, and regulatory compliance cost curves. Segmentation modeling captured product type, end-use application, distribution channel, and material composition variations. Industry-specific forecast inputs included Scandinavian pulp supply concentration metrics and EU F-Gas Regulation phase-down implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under natural gas price volatility and REACH chemical restriction enforcement scenarios. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Neck Pillows Market
Household Items
Stainless Steel Toilet Paper Dispenser Market
Household Items
Water Purifier Market
Household Items
India Digital Showers Market
Household Items
Germany Digital Showers Market
Household Items
Hand Wash Station Market
Household Items
Commercial Locker Market
Household Items
Electric Brooms Market
Household Items
HEPA Vacuum Cleaners Market
Household Items
Europe Handheld Vacuum Cleaners Market
Household Items
Dishwasher Detergent Market
Household Items
Washing Capsules Market
Household Items
Luxury Massage Chair Market
Household Items
MENA POU Water Purifiers Market
Household Items
Netherlands Cookware Market
Household Items
Facial Tissue Paper Market