
 Italy Digital Showers Market | 2026-2036
Italy Digital Showers Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Digital Showers Market Insights
Brass valve assemblies is consolidating around thermostatic digital cartridges in Italy's digital showers supply chain, reducing component counts and improving temperature precision. BTicino leverages its Legrand Group parent infrastructure to dominate smart-home integration channels. Grohe sustains engineering leadership through its German-Italian cross-border R&D footprint. Roca Sanitario anchors Mediterranean distribution with manufacturing scale at its Barcelona and Italian facilities.
Italy Digital Showers encompass electronically controlled water delivery systems integrating thermostatic mixing, digital user interfaces, and network connectivity for personalized temperature, flow, and duration programming. These systems employ ceramic disc cartridges rated for 500,000 cycles, pressure-balanced sensors, and IPX4-minimum electronic enclosures to ensure safety and longevity in wet environments. Smart showers command premium positioning through app-enabled scheduling and water-usage analytics, while hospitality retrofit installations represent the fastest-expanding revenue pool as hotel operators modernize bathrooms without full plumbing replacement. Touch control interfaces retain the largest installed base among control methods, though voice control is gaining traction in luxury residential new-builds.
Italy's Ministry of Economic Development enforces EU Ecodesign regulations on water consumption limits, while CE marking mandates electromagnetic compatibility for connected shower electronics. The EU F-Gas Regulation indirectly shapes component sourcing for any refrigerant-based heat pump integrations. Italy's national building code, alongside regional energy efficiency incentives from Lombardy and Veneto, steers specification toward low-flow digital systems in public and commercial construction. Stakeholders must track evolving EU Cyber Resilience Act requirements for connected bathroom devices and assess whether voice-control modules will trigger additional data governance obligations.
Market Dynamics
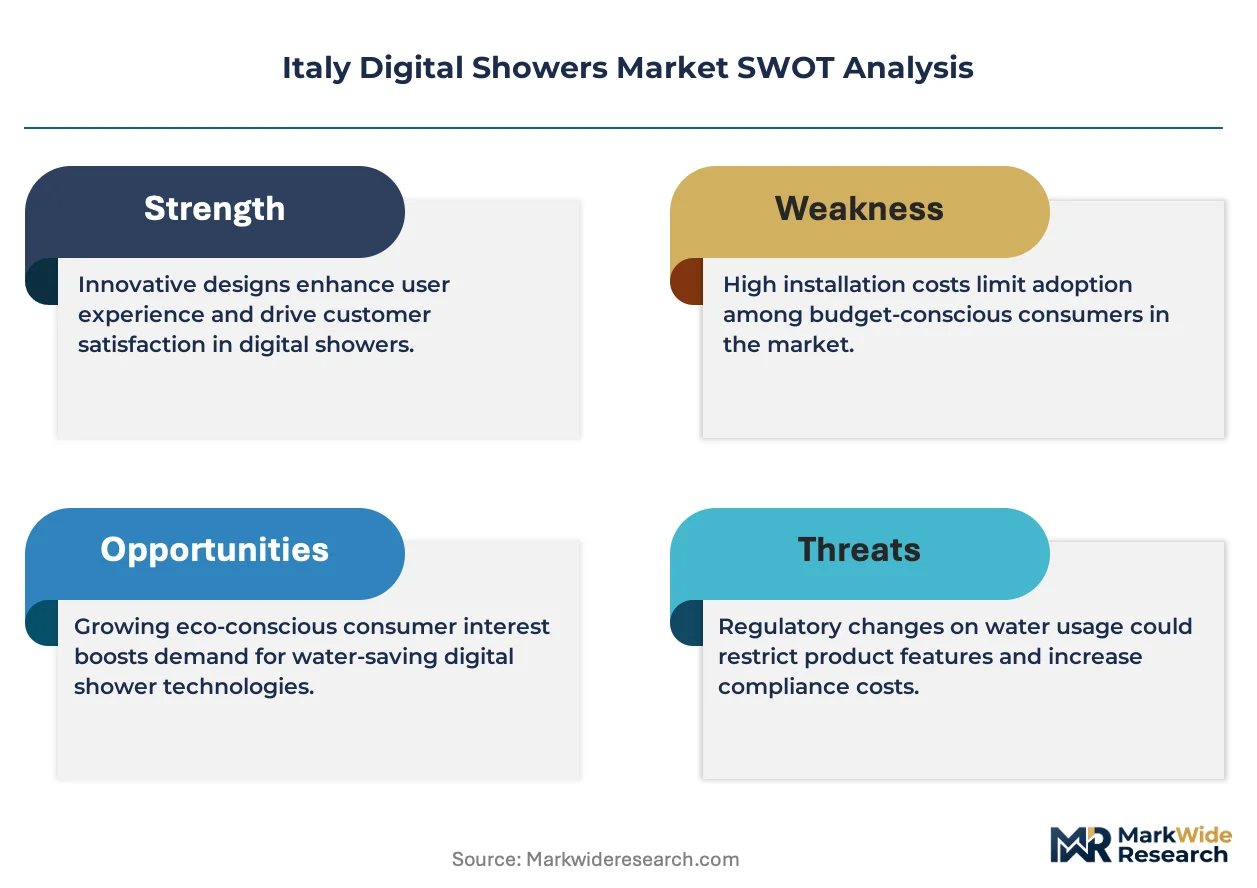
The Italy Digital Showers Market is being fundamentally restructured by EU Ecodesign water-efficiency mandates that are forcing rapid obsolescence of conventional thermostatic hardware while creating asymmetric compliance burdens across domestic versus import supply chains.
Growth Catalysts
- EU Ecodesign Directive:Mandatory water consumption limits for bathroom fixtures are compelling hotel operators and residential developers across Lombardy and Veneto to specify digital shower systems with flow-rate monitoring and automatic shut-off capabilities.
- Thermostatic digital cartridges:Brass valve assembly consolidation around single-cartridge architectures is reducing installation complexity and maintenance intervals, accelerating hospitality retrofit timelines in Rome's boutique hotel sector.
- Regional energy efficiency incentives:Lombardy's building renovation subsidies and Veneto's green construction tax credits are steering public procurement toward low-flow digital systems in commercial and institutional builds.
Market Restraints
- Ceramic disc cartridge supply concentration:Sourcing dependency on German and Swiss precision manufacturers creates input cost volatility and extended lead times for Italian assemblers during demand spikes.
- IPX4 enclosure certification friction:CE marking requirements for electromagnetic compatibility impose testing timeline delays of 4-6 months on connected shower electronics, compressing product launch windows.
- Conventional thermostatic mixer substitution:Lower-cost Italian-manufactured mechanical valves retain installed base in secondary residential markets and price-sensitive renovation segments across southern regions.
Strategic Opportunities
- Sicily and Apulia underpenetration:Southern Italy's lagging smart-home adoption rates present first-mover expansion potential for digital shower distributors establishing regional service networks.
- Voice-control module integration:Convergence of shower electronics with Alexa and Google Home ecosystems is opening premium positioning in Milan's luxury residential new-build pipeline.
- EU Cyber Resilience Act preparation:Early compliance architecture for connected bathroom device security standards will differentiate specification-grade suppliers ahead of mandatory certification phases.
Industry Challenges
- Embedded systems firmware talent scarcity:Shortage of engineers with wet-environment IoT development experience is constraining R&D velocity for touch-interface and app-connectivity modules.
- Legacy plumbing infrastructure integration:Retrofit installations in Rome's historic building stock require custom manifold adaptations, driving project cost overruns and contractor qualification bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Digital Showers Market |
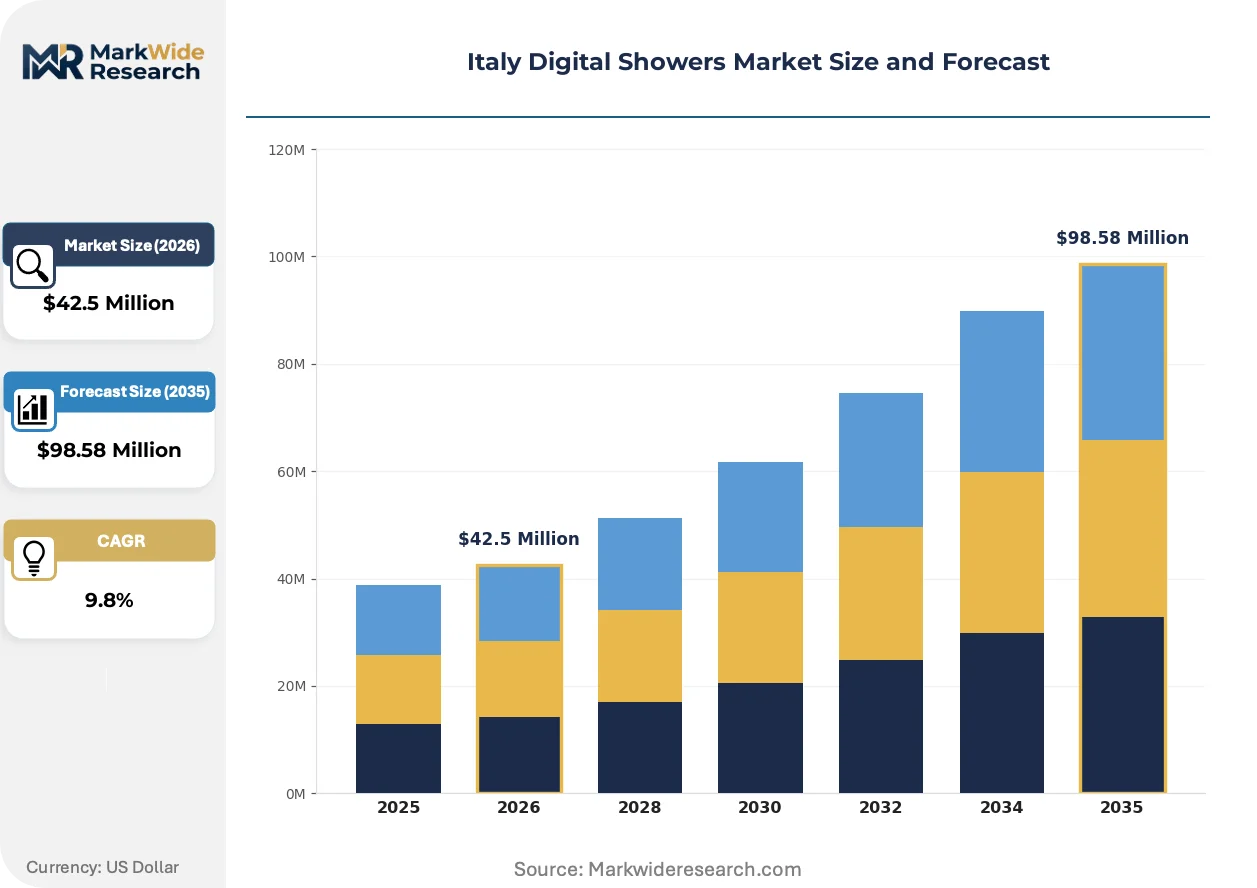
| Market Size in 2026 | $42.5 Million |
| Market Size in 2035 | $98.58 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Smart Showers, Hybrid Showers, Wireless Showers, Electric Showers Control Method: App Control, Voice Control, Touch Control, Remote Control End User Segment: Residential, Commercial, Hospitality, Healthcare Installation Type: New Installations, Retrofit, Standard Installations, Luxury Installations |
| Companies Covered | BTicino, Roca Sanitario, Aqualisa Products Limited, Kohler Co., TOTO Ltd., LIXIL Corporation, Dornbracht Deutschland GmbH & Co. KG, Grohe, Aquaelite, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Digital Showers Market Trends and Innovations
Digital shower architecture is undergoing rapid modularization as connectivity requirements and water-efficiency mandates force redesign of core hydraulic and electronic subsystems. Three distinct trajectories are reshaping competitive positioning and procurement patterns.
Mesh-networked valve control is decentralizing system architecture across Italy's hospitality retrofit sector. Traditional centralized mixing units are yielding to distributed sensor arrays that enable zonal temperature management. Luxury hotel operators in Tuscany are piloting these configurations to reduce guest complaint resolution times. This topology is decentralizing maintenance workflows and compressing response service level agreements.
EU F-Gas Regulation compliance is redirecting heat pump integration strategies for digital shower systems with refrigerant-based water heating. Manufacturers are accelerating R&D into CO2-based alternatives and solid-state heating elements to preempt supply chain disruption. Connected shower electronics with integrated heat pump control modules face the most acute sourcing pressure and are responding with dual-vendor qualification programs.
Water-usage analytics bundling is altering procurement patterns among Milan's high-end residential developers. Specification decisions increasingly hinge on tenant-facing consumption dashboards rather than hardware aesthetics alone. Digital shower vendors are unbundling software subscriptions from hardware sales to capture recurring revenue. This behavioral shift is most visible in Lombardy's certified green building developments where sustainability reporting mandates drive amenity selection criteria.
Italy Digital Showers Market Segmentation
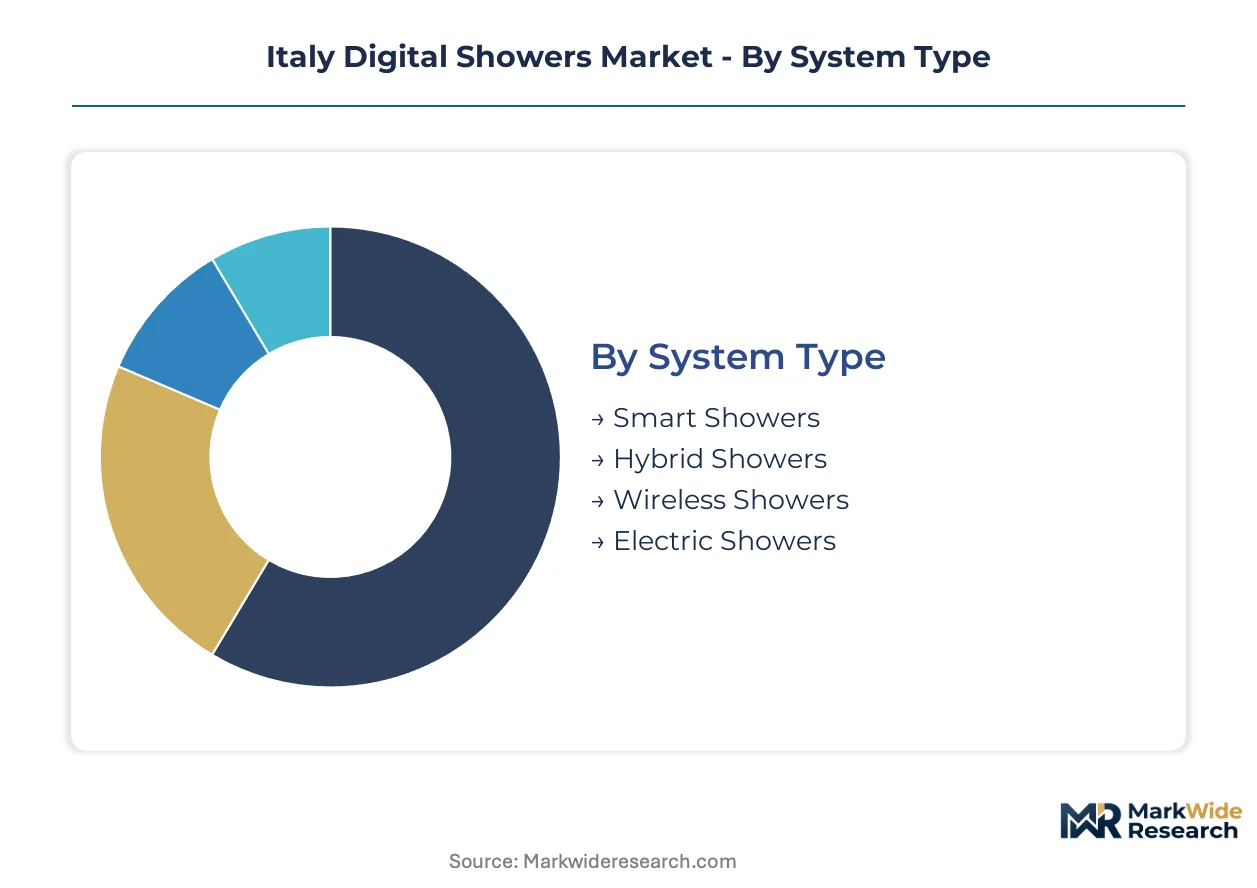
Segmentation in Italy's digital showers market exposes how EU Ecodesign compliance costs and hospitality retrofit complexity concentrate demand across specific system architectures and control interfaces. Procurement patterns diverge sharply between Milan's certified green residential towers and Rome's historic boutique hotel renovations.
System Type:
Supply concentration in thermostatic digital cartridge manufacturing favors integrated system architectures that reduce component vendor count and simplify CE marking pathways.
- Smart Showers:Fully networked systems integrate app connectivity, water-usage analytics, and heat pump control modules. Demand concentrates in Lombardy's certified green building developments where sustainability reporting mandates drive amenity selection. CE marking timelines for electromagnetic compatibility compress product launch windows by 4-6 months.
- Hybrid Showers:Dual-mode units combine digital thermostatic precision with manual override capability. Rome's boutique hospitality sector specifies these for guest-facing installations where technology reliability concerns persist. Reduced firmware complexity accelerates procurement cycles.
- Wireless Showers:Battery-powered valve control eliminates hardwired connectivity requirements.
- Electric Showers:Integrated heating element systems serve retrofit applications with limited hot water infrastructure.
Today's leader: Smart Showers. Tomorrow's challenger: Hybrid Showers.
Control Method:
Cost tier stratification separates premium voice-enabled installations from standard touch interfaces across Italy's residential new-build pipeline.
- Touch Control:Capacitive glass interfaces retain the largest installed base across Italian digital shower deployments. Milan's high-end residential developers specify these for reliability in wet environments. IPX4 enclosure certification requirements impose testing cost burdens that favor established suppliers.
- Voice Control:Alexa and Google Home ecosystem integration commands premium positioning. Luxury residential new-builds in Lombardy pilot these for smart-home convergence. EU Cyber Resilience Act preparation requirements add compliance architecture costs.
- App Control:Smartphone-mediated programming enables scheduling and consumption monitoring.
- Remote Control:Dedicated hardware interfaces serve accessibility-focused installations.
Touch Control dominates volume. Voice Control climbs the fastest in specification value.
End User Segment:
Application-driven demand fragmentation creates distinct procurement workflows between institutional healthcare tenders and hospitality retrofit projects.
- Hospitality:Boutique hotel operators across Tuscany and Rome drive the steepest expansion trajectory for digital shower retrofits without full plumbing replacement. Mesh-networked valve control pilots reduce guest complaint resolution times. Custom manifold adaptations for historic building stock inflate project costs.
- Residential:High-end new-build developments in Milan anchor specification-grade demand. Water-usage analytics bundling increasingly influences procurement decisions over hardware aesthetics alone.
- Commercial:Office and institutional installations prioritize flow-rate monitoring for regulatory compliance.
- Healthcare:Hospital and aged-care facilities specify anti-scald precision and accessibility controls.
Hospitality captures specification premium. Residential scales volume.
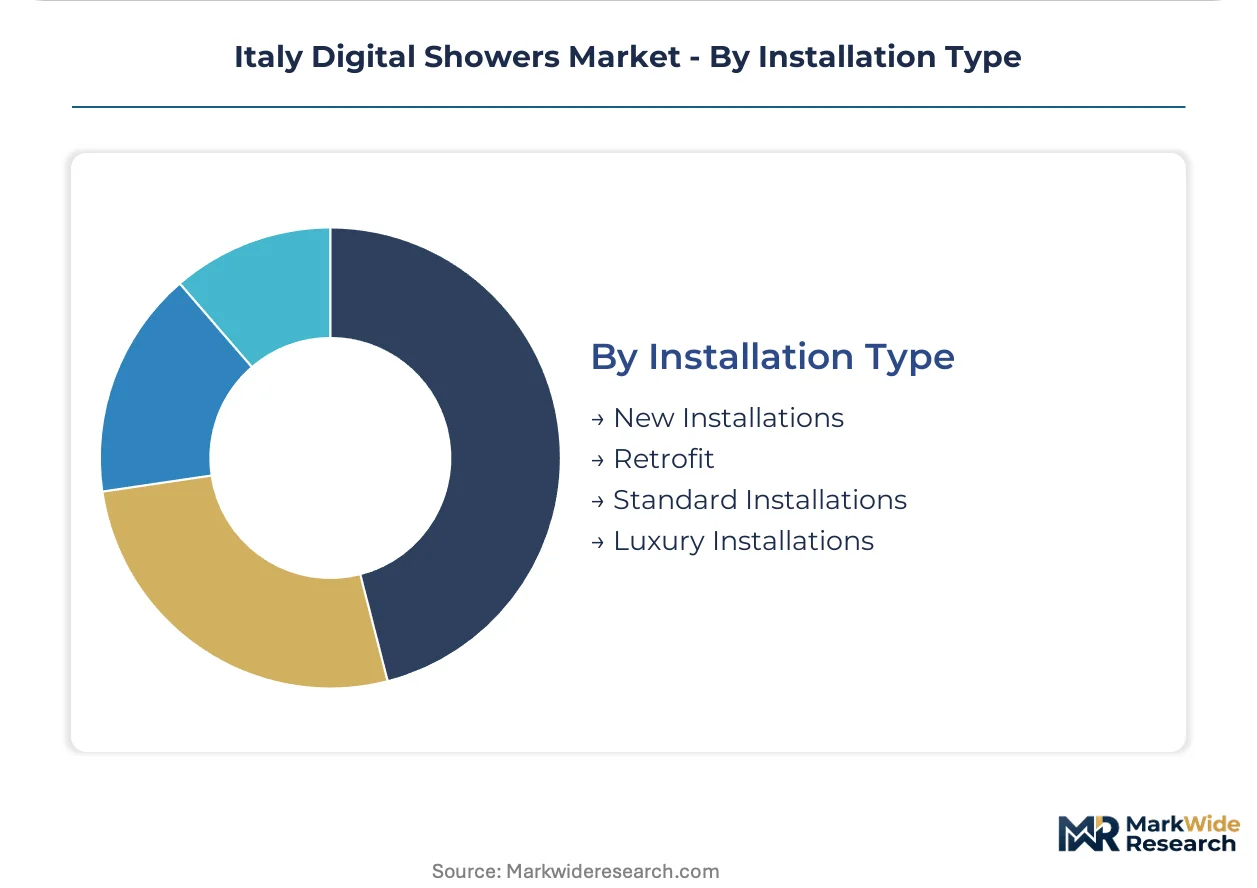
Installation Type:
Geography determines installation complexity, with Rome's historic center imposing custom engineering requirements absent from Lombardy's greenfield developments.
- Retrofit:Existing infrastructure upgrades concentrate in Rome's historic building stock and Venice's constrained plumbing environments. Regional energy efficiency incentives from Lombardy and Veneto steer public procurement toward low-flow digital systems. Contractor qualification bottlenecks extend project timelines.
- New Installations:Greenfield residential and commercial builds in Milan's expanding districts enable optimized digital-first plumbing design. Thermostatic digital cartridge consolidation reduces installation complexity and maintenance intervals.
- Standard Installations:Mid-market residential replacements compete with conventional thermostatic mixer substitution.
- Luxury Installations:Bespoke configurations serve ultra-premium residential and flagship hospitality projects.
New Installations optimize margin. Retrofit expands addressable market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milan's high-end residential developments and Rome's boutique hospitality renovations concentrate Italy's digital showers demand. Regional energy efficiency incentives from Lombardy and Veneto steer public procurement toward low-flow digital systems. Historic building stock constraints in central Italy create distinct installation complexity versus greenfield opportunities in the north.
Lombardy
Milan's certified green building developments anchor specification-grade demand for smart showers with water-usage analytics. Lombardy's building renovation subsidies accelerate hospitality retrofit timelines. Thermostatic digital cartridge consolidation reduces installation complexity across the region's commercial construction pipeline.
Lazio
Rome's boutique hotel sector drives hybrid shower specifications balancing digital precision with manual override reliability. Italy's Ministry of Economic Development enforces EU Ecodesign water consumption limits on bathroom fixture procurement. Custom manifold adaptations for historic building stock inflate project costs and extend contractor qualification timelines.
Veneto
Veneto's green construction tax credits steer institutional builds toward mesh-networked valve control systems. CE marking requirements for electromagnetic compatibility impose testing delays on connected shower electronics. Padua and Verona cluster hospitality retrofit activity as regional tourism operators modernize guest bathrooms.
Tuscany
Luxury hotel chains across Tuscany expand digital shower installations as guest experience differentiation intensifies. EU F-Gas Regulation compliance redirects heat pump integration strategies for refrigerant-based water heating. Florence and Siena concentrate boutique property renovation demand requiring zonal temperature management pilots.
Sicily
Southern Italy's lagging smart-home adoption rates present first-mover expansion potential for regional service network establishment. Conventional thermostatic mixer substitution retains installed base in price-sensitive renovation segments. Palermo and Catania residential markets remain underpenetrated relative to northern benchmarks.
Italy Digital Showers Market Competitive Landscape
Smart-home integration partnerships dominate the current landscape as suppliers converge shower electronics with broader building automation ecosystems. The vendor base stratifies across three tiers: multinational plumbing conglomerates with captive distribution, electrical component specialists leveraging parent infrastructure, and regional fabricators serving retrofit niches. Technology licensing and portfolio diversification represent the primary competitive vectors as players respond to EU Cyber Resilience Act preparation requirements.
Within the multinational tier, Grohe and Roca Sanitario exemplify divergent geographic anchoring strategies. Grohe leverages its German-Italian cross-border R&D footprint for engineering positioning, while Roca Sanitario anchors Mediterranean distribution through manufacturing scale at its Barcelona and Italian facilities. BTicino occupies a distinct position as an electrical specialist exploiting Legrand Group parent infrastructure to dominate smart-home integration channels. These three represent the archetype spectrum: cross-border R&D leadership, regional manufacturing scale, and electrical-systems integration.
| Leading Market Players |
|---|
| BTicino |
| Roca Sanitario |
| Aqualisa Products Limited |
| Kohler Co. |
| TOTO Ltd. |
| LIXIL Corporation |
| Dornbracht Deutschland GmbH & Co. KG |
| Grohe |
| Aquaelite |
| Others |
Pricing and Supply Chain Analysis
Captive cartridge manufacturing by German and Swiss precision suppliers anchors both supply security and pricing power for Italian digital shower assemblers, creating asymmetric cost pass-through advantages for integrated multinationals over regional fabricators. This consolidation pattern concentrates margin capture upstream while forcing downstream players to absorb ceramic disc volatility through inventory buffers or specification downgrades.
Pricing Analysis
Input-cost pass-through from ceramic disc cartridges and IPX4-certified electronic enclosures runs through three-tier pricing structure across premium, standard, and economy levels. Certification grade and after-sales service bundling separate specification-grade hospitality installations from residential retrofits. Pricing pressure stems from conventional thermostatic mixer substitution in southern Italian renovation markets. Residential developers in Sicily and Apulia exhibit highest price sensitivity, while Lombardy green building projects prioritize water-usage analytics over unit cost.
Supply Chain Analysis
EU Ecodesign local-content requirements are reshaping sourcing patterns toward qualified European component vendors and away from opportunistic Asian electronics suppliers. Manufacturing concentrates in Germany, Switzerland, and Italy for precision hydraulic components, with Barcelona anchoring Roca Sanitario's Mediterranean distribution scale. Brass valve assemblies, ceramic disc cartridges, and thermostatic sensors constitute critical input dependencies. Single-source vulnerability in German ceramic disc manufacturing creates supply chain risk. Distribution runs through plumbing merchant networks and electrical wholesale channels serving hospitality retrofit contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's digital showers market represents a late-cycle quality story as EU Ecodesign mandates displace conventional hardware and concentrate procurement among specification-grade suppliers capable of compliance architecture and connected-device security.
For Market Incumbents: Anticipate margin compression from embedded systems firmware talent scarcity by securing captive engineering pipelines through Milan and Turin technical university partnerships. Consolidate thermostatic digital cartridge supply positions through dual-vendor qualification programs reducing German and Swiss sourcing concentration. Defend hospitality retrofit share against hybrid shower challengers by accelerating mesh-networked valve control pilots in Tuscany boutique properties. For New Entrants and Emerging Players: Begin with Sicily and Apulia's underpenetrated residential renovation markets where conventional thermostatic mixer substitution retains installed base and price-sensitive buyers lack smart-home integration alternatives. Establish regional service networks ahead of multinational distributor expansion. Pursue voice-control module integration as the go-to-market angle for Milan luxury new-build specifications where Alexa and Google Home convergence commands premium positioning. For Investors and Strategic Acquirers: Roll-up economics work for electrical component specialists with Legrand Group-style parent infrastructure because smart-home integration channels concentrate specification influence and recurring software subscription revenue pools. Five-to-ten year viability hinges on EU Cyber Resilience Act compliance architecture differentiation. Target acquisition candidates with captive firmware development capabilities and existing CE marking pathways. Watch heat pump integration sourcing strategies as the inflection signal for refrigerant-based water heating disruption under F-Gas Regulation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| EU Cyber Resilience Act Compliance Architecture | Early certification investment differentiates specification-grade suppliers ahead of mandatory phases. |
| Mesh-Networked Valve Control Pilot Programs | Tuscany hotel operators reduce guest complaint resolution times through zonal temperature management. |
| Dual-Vendor Ceramic Disc Qualification | German and Swiss sourcing diversification mitigates lead time volatility during demand spikes. |
| Voice-Control Module Ecosystem Integration | Alexa and Google Home convergence opens premium positioning in Lombardy luxury residential pipeline. |
| Regional Service Network Establishment | Sicily and Apulia first-mover expansion captures underpenetrated southern Italian renovation demand. |
Research Methodology
Multiple input streams — structured interviews with plumbing fixture procurement managers, hospitality renovation contractors, and smart-home integration specialists, alongside regulatory filing analysis and customs trade data — were reconciled to construct demand estimates. Primary fieldwork captured specification workflows in Milan residential developments and Rome boutique hotel retrofits. Secondary validation drew from EU Ecodesign implementation guidance, CE marking databases, and Lombardy regional energy efficiency incentive records. Bottom-up project pipeline enumeration and top-down sectoral expenditure analysis were triangulated to cross-check volume assumptions.
Data-stream reconciliation across system type, control method, end user segment, and installation type dimensions generated segment-level projections throughout the forecast period. CAGRs were derived from fitted growth curves benchmarked against EU water-efficiency mandate implementation timelines and hospitality renovation cycle patterns. Heat pump integration penetration and voice-control adoption velocity served as scenario-weighting variables in the analytical framework.
Caveats apply where EU Cyber Resilience Act final requirements or F-Gas Regulation refrigerant phase-out schedules could materially shift the outlook for connected shower electronics and heat pump sourcing strategies. Forecasts reflect assumptions about regional incentive continuity and ceramic disc manufacturing capacity expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Lunch Box Market
Household Items
Aquarium Heaters and Chillers Market
Household Items
Robot Vacuum Cleaners Market
Household Items
Alarm Clocks Market
Household Items
Infuser Water Bottles Market
Household Items
Waterless Aroma Diffuser Market
Household Items
Brazil Cookware Market
Household Items
Insulated Tumblers Market
Household Items
Air Humidifier Market
Household Items
Ironing Boards Market
Household Items
Infrared Sauna Heaters Market
Household Items
Washing Machine Cleaner Market
Household Items
Desktop Air Purifier Market
Household Items
Toilet Care Wipes Market
Household Items
Smart Bath Heater Market
Household Items
Electric Shoe Dryer Market