
 Jet Hand Dryer Market | 2026-2036
Jet Hand Dryer Market Size, Share, and Industry Trends Forecast 2026-2036
Jet Hand Dryer Market Foresight
ABS plastic housings are recalibrating cost structures across the jet hand dryer industry as manufacturers substitute heavier stainless steel enclosures in mid-tier product lines. Dyson Limited leverages proprietary digital motor technology to sustain premium positioning in high-traffic commercial environments. Mitsubishi Electric Corporation anchors its competitive stance through integrated heating element designs that reduce energy draw during operation cycles. Panasonic Corporation differentiates via channel control across Asian hospitality supply chains.
A jet hand dryer is an electric restroom appliance that accelerates air through narrow apertures at velocities exceeding 300 mph to strip moisture from hands within 10-15 seconds, employing brushless DC motors and HEPA filtration assemblies to deliver hygienic, touch-free drying in high-throughput facilities. Wall-mounted installations dominate volume shipments due to space efficiency in existing restroom footprints, while high-speed automatic variants command margin pools in premium commercial segments. Countertop configurations occupy niche positions in upscale hospitality settings where design integration outweighs unit economics.
The U.S. Department of Energy appliance standards, EU Ecodesign Directive efficiency benchmarks, and China's GB national standards collectively constrain motor wattage and standby power consumption, forcing redesigns of heating coils and blower assemblies across export-bound product portfolios. Stakeholders must monitor evolving efficiency thresholds and certification harmonization between North American and European testing protocols to avoid market access friction in cross-border procurement contracts.
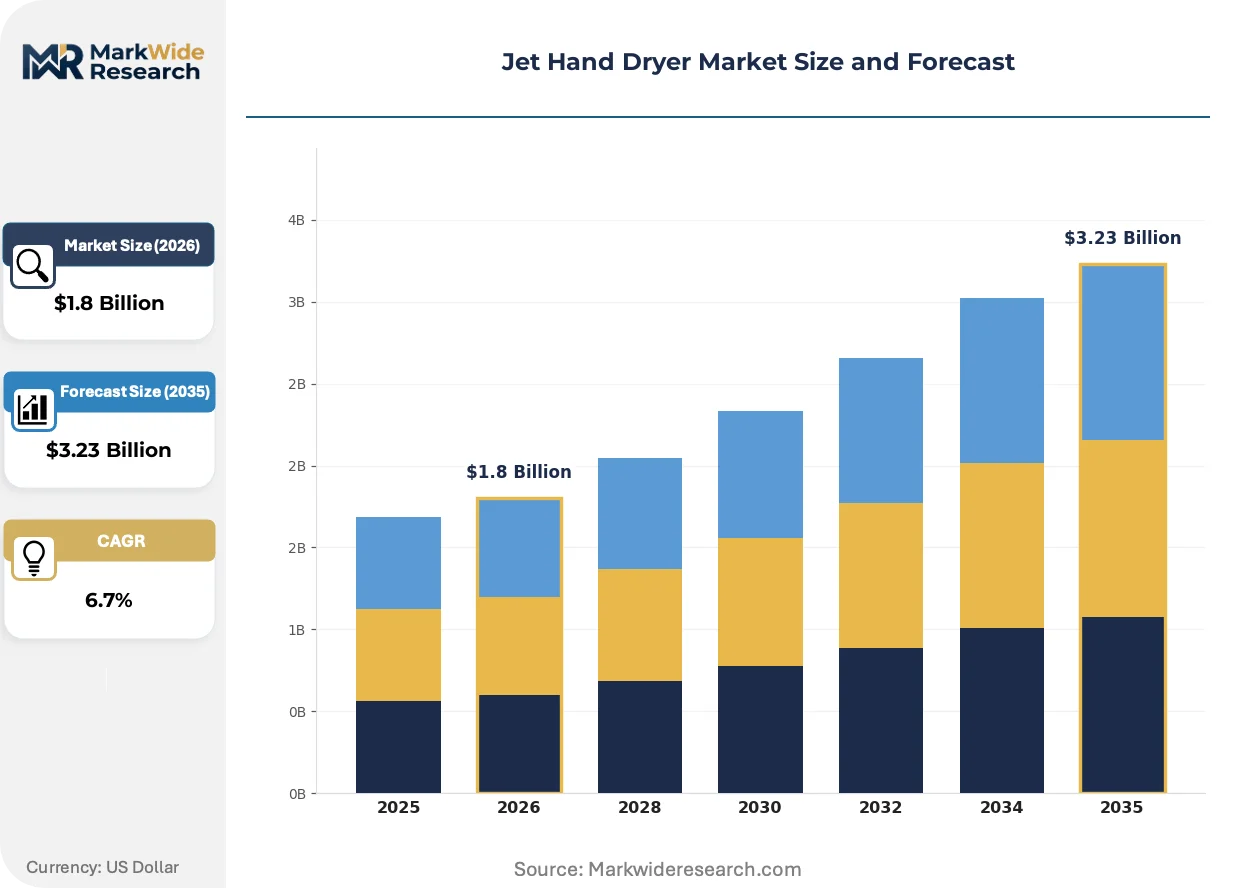
Market Dynamics
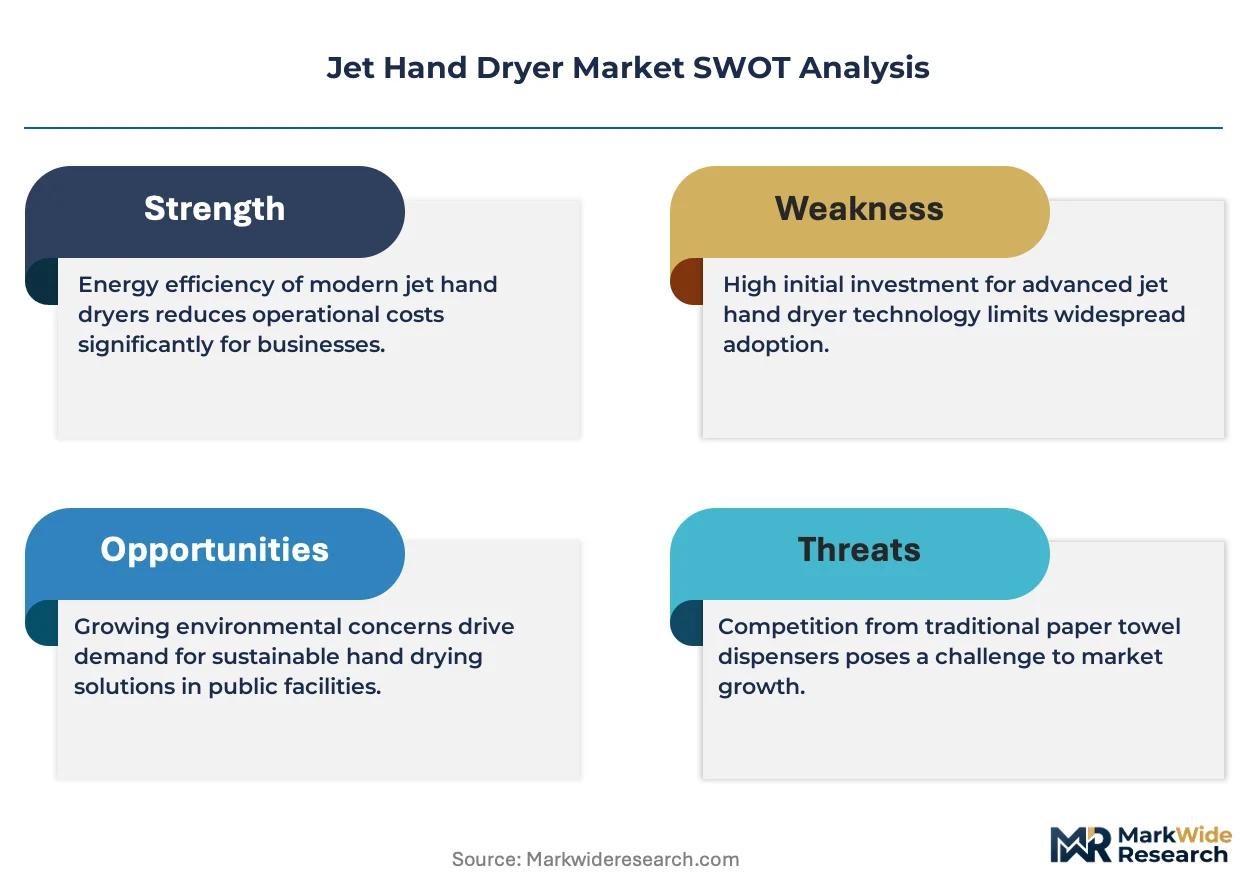
ABS plastic housings are compressing manufacturing costs across mid-tier jet hand dryer lines, forcing stainless steel suppliers to retreat toward premium architectural specifications. This material substitution is redrawing competitive boundaries between cost-optimized and durability-positioned product tiers.
Growth Catalysts
- EU Ecodesign Directive:Efficiency mandates in Europe are compelling motor and heating assembly redesigns, creating upgrade cycles across installed bases in airports and shopping complexes.
- Airport infrastructure modernization:High-throughput facilities in China, the United States, and Germany are expanding touch-free sanitation installations to reduce paper towel dependency and operational waste.
- Brushless DC motor adoption:Higher-efficiency motor architectures are enabling faster dry times while reducing energy draw per use cycle in commercial restroom environments.
Market Restraints
- Heating element input volatility:Nickel-chromium alloy prices fluctuate with energy markets, compressing margins on heated-air variants versus ambient-temperature competitors.
- Supply concentration in East Asian motor production:Brushless DC motor manufacturing clusters in specific Chinese industrial zones create single-source vulnerability for Western OEMs.
- Acoustic emission limitations:Noise restrictions in European workplace directives constrain maximum air velocity specifications, capping performance differentiation.
Strategic Opportunities
- Underpenetrated Indian hospitality sector:Premium hotel chains in Mumbai and Delhi are retrofitting properties with design-integrated hand drying solutions as hygiene standards converge with global benchmarks.
- HEPA filtration convergence with IoT monitoring:Sensor-enabled filter life tracking creates recurring revenue streams through predictive maintenance contracts in facility management.
- China GB standards alignment:Domestic certification harmonization with export protocols enables Chinese manufacturers to serve adjacent Southeast Asian markets without redundant testing.
Industry Challenges
- Electromagnetic compatibility certification timelines:FCC and CE marking convergence delays for high-speed motor controllers extend product launch windows by four to six months.
- Legacy restroom electrical infrastructure:Older commercial buildings lack dedicated circuits for high-wattage installations, requiring costly electrical upgrades that stall procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jet Hand Dryer Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Manual, High-Speed, Low-Speed Installation Type: Wall-Mounted, Countertop, Surface-Mounted, Portable End User: Public Restrooms, Commercial Kitchens, Healthcare Facilities, Educational Institutions Material: Stainless Steel, Plastic, Aluminum, Composite |
| Companies Covered | World Dryer Corporation, Cormax, Dyson Limited, Orchids International, AVRO, Mitsubishi Electric Corporation, Saniflow, Tekflo, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jet Hand Dryer Market Shifts & Advancements
Digital motor control architectures are collapsing the performance gap between premium and standard jet hand dryer tiers. Manufacturers are racing to embed intelligence at the component level while regulatory pressure accelerates efficiency benchmarking across export markets.
Variable-frequency drive circuitry is unifying motor control and thermal management into single-chip architectures. Facility managers in high-traffic transportation hubs are specifying these integrated systems to reduce maintenance callouts. The technology is unifying what were separate BOM line items into consolidated supplier relationships, compressing vendor count in procurement portfolios.
REACH substance restrictions on persistent organic pollutants are forcing reformulation of motor winding insulation and housing flame retardants. European manufacturers face supply chain requalification costs that Asian competitors avoid through alternative chemistries. Heated-air product lines bear disproportionate compliance burden compared to ambient-temperature variants, reshaping regional product mix decisions.
Specification authority is migrating from facilities departments to infection control committees in healthcare-adjacent commercial properties. Hospital-affiliated outpatient centers and senior living complexes now mandate HEPA filtration and touch-free operation as standard requirements. This behavioral shift is most visible in United States metropolitan markets where Joint Commission accreditation standards influence adjacent commercial real estate hygiene protocols.
Jet Hand Dryer Market Segmentation
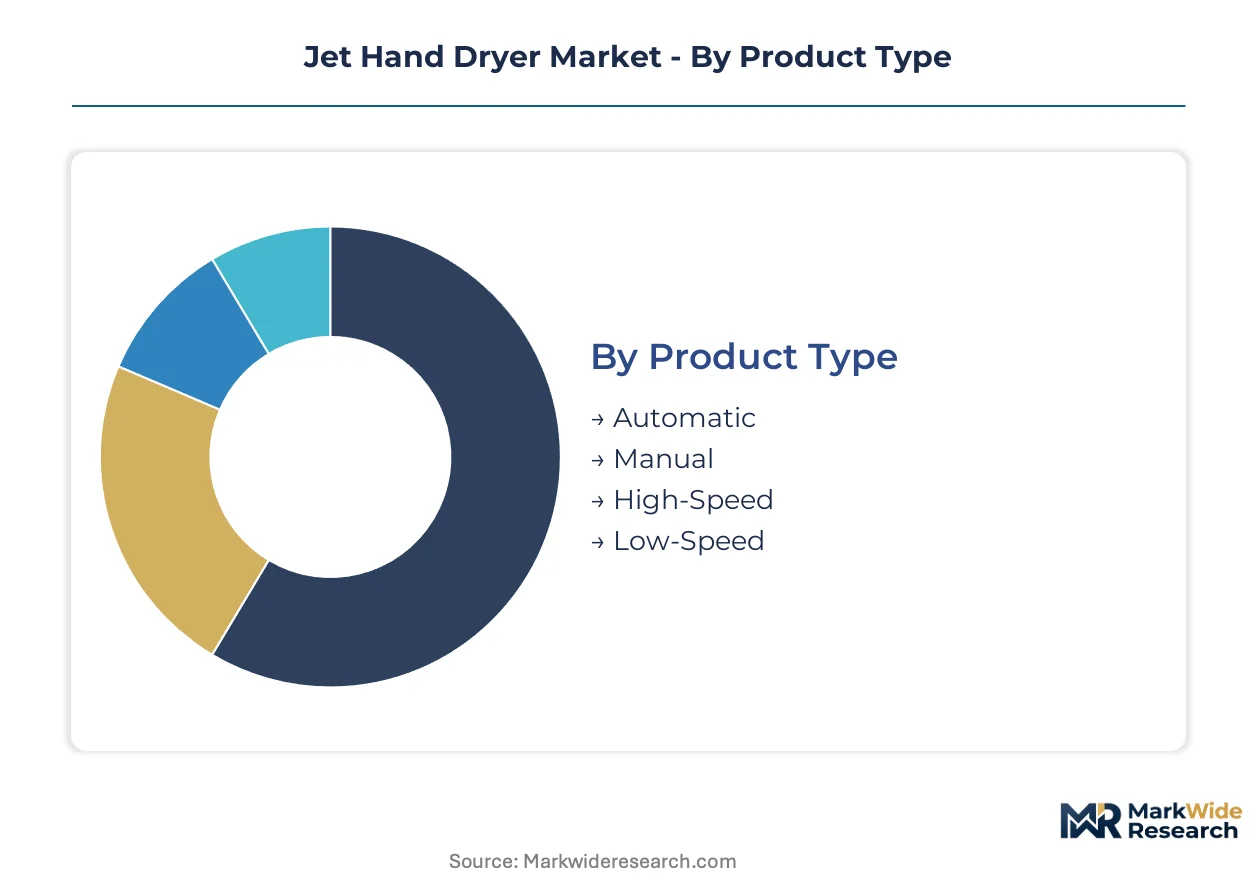
Segmentation in the jet hand dryer market reveals divergent capital requirements across product architectures and installation contexts. Procurement patterns split sharply between facilities prioritizing throughput velocity versus those constrained by legacy electrical infrastructure and acoustic limitations.
Product Type:
Capital intensity escalates dramatically with motor sophistication and control electronics integration, separating high-performance variants from basic electromechanical units.
- High-Speed:Brushless DC motor architectures with digital frequency drives demand 40-60% higher upfront equipment investment than conventional alternatives. Airport terminals in Germany and shopping complexes in China specify these units to minimize queue congestion during peak traffic periods.
- Automatic:Infrared sensor arrays and microcontroller-based activation systems add BOM complexity but reduce per-use energy draw through precise cycle timing. Healthcare facilities in the United States increasingly mandate touch-free activation to satisfy Joint Commission-aligned infection control protocols.
- Manual:Push-button mechanical switches dominate budget-conscious retrofit projects where existing restroom electrical circuits cannot support sensor standby loads.
- Low-Speed:Conventional brushed motors with resistive heating coils serve price-sensitive installations in educational institutions where dry time tolerance exceeds commercial hospitality standards.
High-Speed absorbs the bulk of installed capacity in transportation hubs; Automatic is expanding most quickly across healthcare-adjacent commercial properties.
Installation Type:
Spatial constraints and structural modification costs determine which configurations penetrate existing building stock versus new construction specifications.
- Wall-Mounted:Recessed or surface-applied housings leverage vertical cavity space to preserve floor area in high-density restroom footprints. These units dominate retrofit deployments across aging commercial building stock in the United States where plumbing chase access simplifies electrical routing.
- Countertop:Integrated basin-adjacent designs command premium positioning in upscale Mumbai and Delhi hotel properties where architectural cohesion outweighs unit economics.
- Surface-Mounted:Semi-recessed brackets accommodate wall thickness variations without structural penetration, easing installation in masonry construction common across European heritage buildings.
- Portable:Battery or corded standalone units serve temporary event infrastructure and construction site sanitation where permanent electrical connections are unavailable.
Wall-Mounted carries the volume base across all geographies; Countertop is gaining share fastest in premium Asian hospitality.
End User:
Duty cycle intensity and hygiene certification requirements fragment demand across facility types with divergent procurement authority structures.
- Public Restrooms:High-throughput environments in airports and railway stations prioritize vandal-resistant housings and rapid cycle times to manage queuing behavior.
- Healthcare Facilities:HEPA filtration and antimicrobial surface treatments are becoming non-negotiable specifications in hospital-affiliated outpatient centers.
- Commercial Kitchens:Grease-resistant finishes and higher IP ratings address wash-down requirements distinct from general restroom applications.
- Educational Institutions:Extended warranties and simplified maintenance protocols dominate procurement criteria over performance optimization.
Public Restrooms deploy the largest unit volumes; Healthcare Facilities are climbing the fastest as infection control committees assume specification authority.
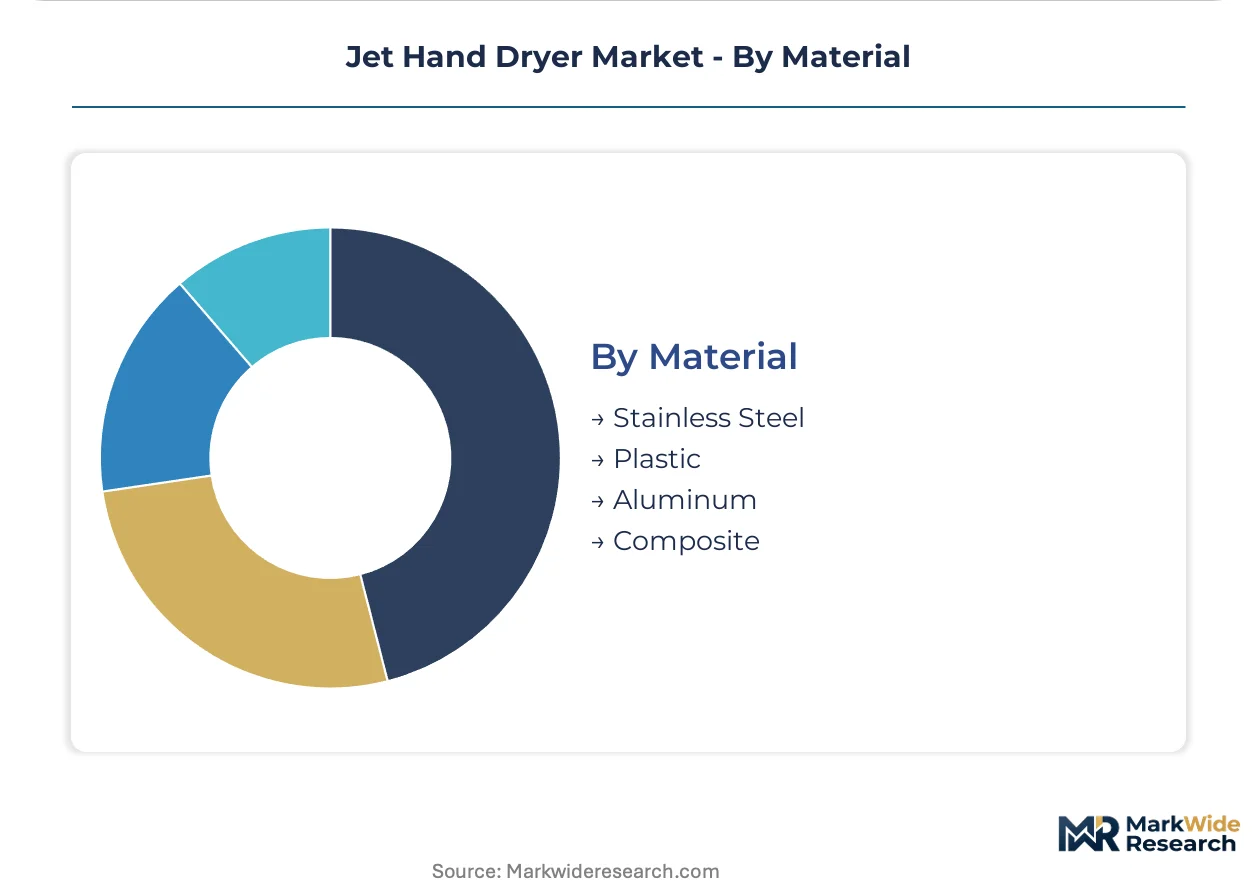
Material:
Raw material cost volatility and regional manufacturing capabilities reshape sourcing strategies for housing and structural components.
- Stainless Steel:Grade 304 and 316 enclosures dominate premium architectural specifications where durability and aesthetic longevity justify 25-35% cost premiums over polymer alternatives.
- Plastic:ABS and polycarbonate formulations enable cost-optimized mid-tier lines, with Chinese manufacturers leveraging domestic petrochemical supply chains to compress export pricing.
- Aluminum:Die-cast and extruded housings balance weight reduction with thermal dissipation requirements in heated-air product variants.
- Composite:Glass-reinforced polymer and metal-polymer hybrids occupy niche positions in design-forward installations seeking differentiated surface finishes.
Plastic captures the widest unit deployment; Stainless Steel maintains steepest expansion trajectory in premium commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Guangdong and Zhejiang provinces concentrate brushless DC motor manufacturing, drawing component suppliers into clustered supply networks serving export-oriented assembly operations.
China
Airport infrastructure modernization in Beijing, Shanghai, and Guangzhou drives bulk procurement of high-speed units. GB national standards on motor efficiency and standby power constrain product designs for domestic and export markets. Shenzhen and Dongguan industrial zones host dense concentrations of motor controller and sensor module suppliers.
United States
Healthcare-adjacent commercial properties and airport terminals in Atlanta, Chicago, and Los Angeles specify HEPA-equipped touch-free models. Department of Energy appliance standards limit motor wattage and heating element draw. Midwest manufacturing corridors supply stamped metal housings and injection-molded ABS components.
Germany
Frankfurt, Munich, and Berlin airports prioritize rapid-dry units to manage passenger throughput peaks. EU Ecodesign Directive efficiency benchmarks force heating coil and blower assembly redesigns. Baden-Württemberg engineering clusters specialize in precision motor control systems and variable-frequency drive components.
India
Premium hotel chains in Mumbai and Delhi retrofit properties with design-integrated solutions as hygiene standards converge with global benchmarks. BIS certification requirements and import duty structures shape sourcing decisions. Tamil Nadu and Karnataka industrial zones develop domestic assembly capacity for cost-optimized mid-tier lines.
Japan
Tokyo and Osaka transportation hubs specify compact wall-mounted configurations for space-constrained retrofit environments. METI energy efficiency guidelines influence motor and thermal management specifications. Nagoya-area electronics manufacturing clusters supply microcontroller-based activation systems and infrared sensor arrays.
Jet Hand Dryer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium architectural positioning commanding steeper margins than cost-optimized volume plays. The vendor base organizes into three tiers: integrated electronics conglomerates with captive motor technologies, dedicated sanitation equipment specialists, and regional fabricators serving price-sensitive retrofit markets. Dominant competitive moves include portfolio diversification into adjacent touch-free restroom fixtures and geographic expansion through distribution partnerships in underpenetrated hospitality corridors.
Within the integrated electronics tier, Mitsubishi Electric Corporation and Panasonic Corporation exemplify diversified conglomerate positioning, leveraging captive component supply chains and established facility management channel relationships. Dyson Limited occupies a distinct premium-tier position, representing proprietary motor technology and high-traffic commercial specification authority. World Dryer Corporation anchors the dedicated specialist archetype, sitting within the traditional sanitation equipment fabricator segment with broad distribution across North American institutional procurement networks.
| Leading Market Players |
|---|
| World Dryer Corporation |
| Cormax |
| Dyson Limited |
| Orchids International |
| AVRO |
| Mitsubishi Electric Corporation |
| Saniflow |
| Tekflo |
| Panasonic Corporation |
| Others |
Supply & Pricing Matrix
Airport procurement consortiums in China, Germany, and the United States dominate volume contracting and enforce project-based pricing with multi-year service bundling. This buyer concentration compresses margins for mid-tier suppliers while rewarding premium-tier manufacturers with specification authority in high-throughput installations.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to rush orders from European airport operators facing EU Ecodesign Directive compliance deadlines. Three-tier pricing structure across premium, standard, and economy levels segments by motor architecture sophistication and HEPA filtration inclusion. Price differentiation hinges on CE marking tier and volume scale, with healthcare facilities least sensitive due to Joint Commission-aligned procurement protocols. Cost compression in economy tiers is intensifying because ABS plastic housing substitution erodes stainless steel supplier pricing power.
Supply Chain Analysis
CE marking and FCC certification timelines gate market access for brushless DC motor controllers, extending supplier qualification cycles. Manufacturing concentrates in China's Guangdong and Zhejiang provinces, with secondary clusters in Japan's Nagoya electronics corridor and Germany's Baden-Württemberg precision engineering zone. Raw material dependencies include nickel-chromium heating alloys, ABS petrochemical feedstocks, and rare-earth magnet materials for motor assemblies. Single-source vulnerability pervades East Asian motor controller production. Distribution runs through facility management service integrators and direct OEM relationships with airport authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The jet hand dryer market sits in a technology-transition phase where brushless DC motor architectures displace conventional brushed motor legacy platforms. Digital motor control integration and HEPA filtration convergence reshape competitive requirements across procurement cycles.
For Market Incumbents: Acquire proprietary digital motor IP to defend specification authority against emerging Asian electronics conglomerates entering through cost-optimized ABS housing lines. Backward integration into sensor module production reduces BOM vulnerability from East Asian single-source clusters. Certification investment in harmonized EU-North American testing protocols preserves cross-border procurement access.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian hospitality retrofit markets offers white-space entry with design-integrated countertop configurations. Underpenetrated senior living complexes in United States metropolitan corridors present specification authority migration toward infection control committees. Go-to-market leverage rests on predictive maintenance IoT bundling with HEPA filter life monitoring.
For Investors and Strategic Acquirers: The window for entry favors component-level specialists with captive brushless DC motor technology and established healthcare channel relationships. Long-term viability hinges on regulatory compliance capability across divergent efficiency mandates. The signal to monitor is EU Ecodesign Directive threshold tightening and subsequent redesign cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| HEPA-IoT Integration Development | Sensor-enabled filter tracking creates recurring facility management revenue streams. |
| Backward Integration into Motor Controllers | Captive production of variable-frequency drive components reduces East Asian supply risk. |
| EU-North American Certification Harmonization | Unified testing protocols accelerate product launches across Atlantic procurement corridors. |
| Healthcare Channel Partnership Expansion | Joint Commission-aligned specification authority migration opens premium pricing access. |
| ABS Housing Supply Chain Localization | Regional petrochemical feedstock access compresses mid-tier export pricing to Southeast Asia. |
Research Methodology
Independent corroboration across procurement directors at airport authorities, facilities managers in healthcare-adjacent commercial properties, and engineering leads at brushless DC motor suppliers underwrites the qualitative findings. Primary interviews with restroom fixture specification consultants, infection control committee members, and aftermarket service contractors combined with secondary validation from customs trade records, EU Ecodesign Directive implementation reports, and GB standards documentation. Bottom-up shipment data triangulates against top-down facility installation tracking across transportation hubs and hospitality properties.
Rate-of-change decomposition separates volume growth from value migration across the projection horizon. The analytical framework models segmentation dimensions including motor architecture tier, installation type, end-use facility category, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and new construction penetration curves. Industry-specific forecast inputs incorporate EU efficiency threshold enforcement timelines and airport infrastructure modernization commitments in China, Germany, and the United States.
Inputs from motor controller suppliers and airport procurement databases were available through the study window; gaps in real-time inventory positioning data introduce uncertainty bands around short-term shipment forecasts. Forecasts reflect documented assumptions regarding regulatory harmonization progress and brushless DC motor cost curves. A model refresh is warranted upon material change in EU Ecodesign Directive implementation schedules or GB standards alignment with export protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Portable Vacuum Cleaner Market
Household Items
Global Buddhist Supplies Market
Household Items
Global Laptop Tables Market
Household Items
US Soap Dispenser Market
Household Items
Consumerware Market
Household Items
Multi-Door Fridges Market
Household Items
Asia-Pacific Air Purifier Market
Household Items
North America Robotic Pool Cleaner Market
Household Items
Gel Warmers Market
Household Items
Home Use Air Purifiers Market
Household Items
Snow Blower Market
Household Items
Powered Lawn Mowers Market
Household Items
Laundry Detergent Sheets Market
Household Items
Neck Pillows Market
Household Items
Russia Residential Water Heaters Market
Household Items
Dry Vacuum Cleaner Market