
 Asia-Pacific Digital Showers Market | 2026-2036
Asia-Pacific Digital Showers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digital Showers Market Analytics
Luxury hospitality chains are bifurcating demand away from mass residential buyers across the Asia-Pacific Digital Showers landscape. TOTO leverages its vertical integration in ceramic valve manufacturing to dominate precision temperature control. LIXIL Corporation anchors its position through deep channel control in Japanese commercial construction. Jaquar competes aggressively in India's mid-market renovation segment with localized touchscreen interfaces.
Digital showers integrate thermostatic mixing valves, electronic flow sensors, and programmable user profiles to deliver precise water temperature and volume management for residential and commercial bathing applications. Smart Showers and Digital Controls command the largest revenue pools as hospitality operators prioritize guest experience standardization, while IoT-Enabled and Voice Control technologies represent the fastest-expanding technology tiers as ecosystem integration with existing building management systems deepens. Mobile App Integration is maturing rapidly in South Korean and Australian urban residential clusters where smartphone-native consumers expect seamless connectivity.
China's GB standards for water efficiency and India's BIS certification requirements for electronic plumbing fixtures are elevating compliance costs for non-compliant imports while creating protected runway for certified domestic manufacturers. Australia's WaterMark certification scheme and WELS rating system further shape product specification criteria across commercial and residential procurement channels. Stakeholders must monitor how Japan's METI energy efficiency directives and evolving ASEAN harmonization talks reshape cross-border certification burdens and sourcing strategies.
Market Dynamics
Hospitality operators across Southeast Asia are standardizing guest experience through IoT-enabled temperature control systems, compressing replacement cycles for legacy thermostatic installations and redrawing competitive requirements for fixture suppliers.
Growth Catalysts
- India's BIS certification mandate:Electronic plumbing fixtures must now meet revised electromagnetic compatibility and safety standards, accelerating formalization of previously fragmented domestic supply chains.
- Luxury hospitality capex:Five-star and boutique hotel chains in Thailand, Vietnam, and Indonesia are specifying digital showers as baseline amenities, creating pull-through demand for premium residential renovations in adjacent districts.
- Voice control module integration:Natural language processing capabilities embedded in shower control units are expanding addressable market to aging populations and accessibility-focused buyers.
Market Restraints
- Ceramic valve component concentration:Precision thermostatic cartridges rely on specialized alumina-zirconia suppliers concentrated in Japan and Germany, exposing assemblers to input bottlenecks.
- Copper and electronic sensor cost volatility:Flow sensors and heating element housings use refined copper grades whose price swings compress margin visibility for mid-tier manufacturers.
- China's GB water efficiency standards:Tightening flow-rate maximums for showerheads rated below 6 liters per minute are forcing product redesigns that lengthen certification timelines for import-dependent brands.
Strategic Opportunities
- Philippines hospitality construction pipeline:Integrated resort developments in Cebu and Clark Freeport Zone are specifying building management system-compatible fixtures, creating first-mover advantage for certified suppliers.
- Australia's WELS rating premium tier:Water efficiency labeling scheme bonuses for connected fixtures that deliver consumption data to utility platforms are opening specification pathways for IoT-native products.
- Japan's METI energy efficiency directives:Building-to-grid integration requirements for commercial properties are mandating smart load management, positioning digital showers as controllable thermal assets.
Industry Challenges
- Embedded firmware cybersecurity certification:Australia's Essential Eight framework and Singapore's Cybersecurity Labelling Scheme for IoT devices are extending product validation timelines by 8-14 months for non-compliant architectures.
- Cross-border installation technician training:Commissioning of networked shower systems requires competencies spanning plumbing, low-voltage electrical, and network configuration that trade schools have not standardized.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digital Showers Market |
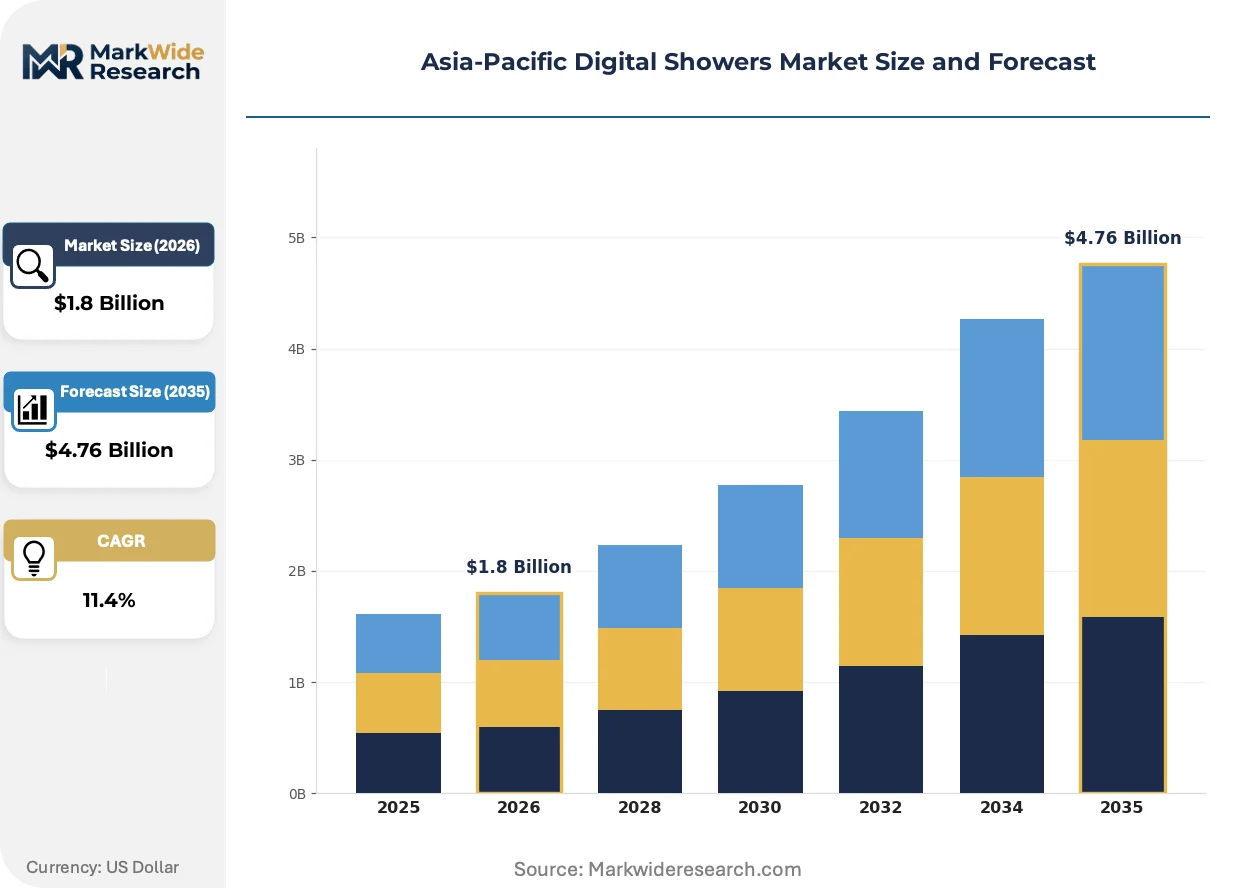
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Showers, Digital Controls, Temperature Control Units, Water Sensor Systems End User: Residential, Hospitality, Commercial, Healthcare Installation Type: Retrofit, New Construction, Renovation, Modular Technology: IoT-Enabled, Touchscreen Interfaces, Mobile App Integration, Voice Control |
| Companies Covered | TOTO, LIXIL Corporation, Jaquar, Kohler, Cera Sanitaryware, Aqualisa Products, Grohe, Hansgrohe, Xiaomi, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digital Showers Market Evolving Landscape
Component-level innovation is compressing the physical footprint of digital shower electronics while expanding their functional scope, enabling installation in retrofit scenarios previously inaccessible to smart fixture architectures.
Solid-state thermoelectric heating elements are miniaturizing temperature modulation hardware from cartridge-based assemblies to thin-film substrates integrated directly into showerhead housings. Boutique hotel operators in Melbourne and Seoul are piloting these systems to eliminate exposed control boxes in minimalist bathroom designs. This physical compression is collapsing the distinction between smart showers and conventional fixtures in renovation cost comparisons.
China's GB standards for water efficiency are tightening flow-rate testing protocols and expanding coverage to include standby power consumption for electronically controlled units. Domestic manufacturers with in-house testing laboratories are compressing certification cycles while import-reliant brands face extended approval queues. The regulatory friction is concentrating specification influence among vertically integrated suppliers with captive compliance infrastructure.
Specifiers in Australia's premium residential renovation segment are unbundling after-sales service contracts from product procurement, treating digital shower maintenance as a separate subscription category managed through property management platforms. This purchasing pattern shift is compressing upfront equipment margins while extending vendor revenue visibility through multi-year service agreements. The model is most visible in Sydney and Brisbane high-rise developments where body corporate governance structures favor operational expenditure smoothing.
Asia-Pacific Digital Showers Market Segmentation
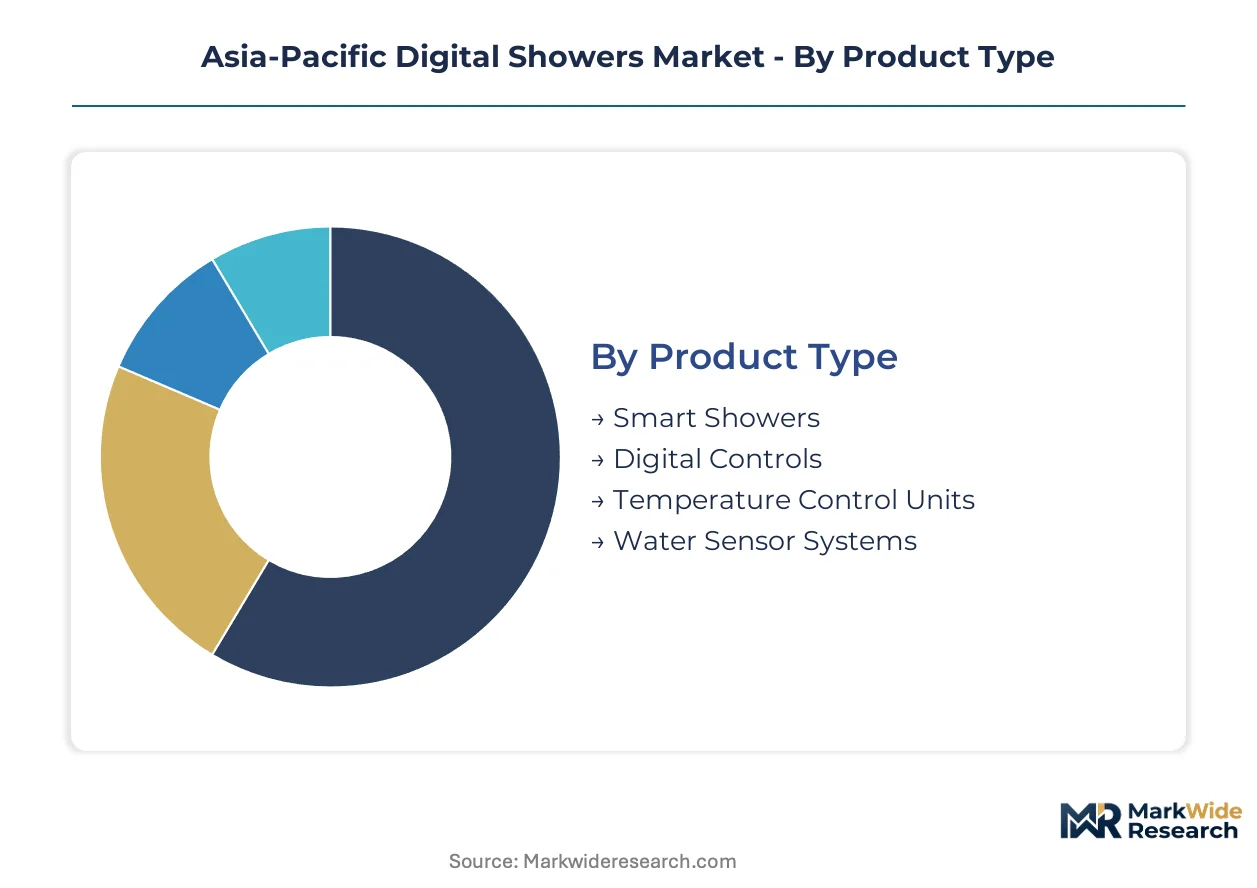
Digital shower architectures fragment across four intersecting dimensions that reshape procurement patterns and vendor specialization. Product type and technology tiers determine compliance burdens and margin structures, while installation mode and end-use concentration dictate channel economics and service attach rates.
Product Type:
Substitute pressure from conventional thermostatic mixers weighs heaviest on standalone temperature control units, while integrated smart shower systems build defensive moats through ecosystem lock-in.
- Smart Showers:Fully integrated systems combine thermostatic mixing, electronic flow modulation, and network connectivity in unified enclosures. Hospitality operators across Thailand and Indonesia specify these as baseline amenities to standardize guest experience and reduce maintenance callouts.
- Digital Controls:Wall-mounted interface panels that retrofit to existing plumbing infrastructure, enabling precision temperature and flow management without full fixture replacement. Australia's premium residential renovation segment favors these for aging bathroom upgrades where preserving existing tilework reduces project scope.
- Temperature Control Units:Standalone thermostatic cartridges with electronic sensors that integrate with third-party showerheads. Mid-market residential buyers in India select these for cost-sensitive upgrades where BIS certification compliance adds mandatory cost layers.
- Water Sensor Systems:Flow monitoring and leak detection modules that install inline with existing plumbing. Commercial property managers in Japan deploy these for METI-mandated building-to-grid integration where consumption data feeds utility optimization platforms.
Smart Showers retains volume leadership; Water Sensor Systems holds the steepest expansion curve.
End User:
Margin concentration follows capex cycles, with hospitality procurement commanding premium pricing for experience-standardized specifications while healthcare compliance requirements lengthen sales cycles.
- Residential:Individual homeowners and multi-unit developers purchasing for private bathroom installations. South Korean urban clusters drive specification toward mobile app integration as smartphone-native consumers demand seamless connectivity.
- Hospitality:Hotel chains, resorts, and serviced apartment operators standardizing guest amenities. Five-star and boutique properties across Vietnam and the Philippines compress replacement cycles for legacy thermostatic installations through IoT-enabled temperature control mandates.
- Commercial:Office buildings, gyms, and public facilities requiring durable, high-traffic fixtures. Australia's WELS rating premium tier creates specification pathways for connected fixtures that deliver consumption data to utility platforms.
- Healthcare:Hospitals, aged care facilities, and rehabilitation centers prioritizing accessibility and infection control. Voice control module integration expands addressable market to aging populations and mobility-limited users in Japan's expanding eldercare infrastructure.
Residential commands installed base dominance; Hospitality generates the highest revenue per unit.
Installation Type:
Channel economics diverge sharply between new construction's specification-driven procurement and retrofit's technician-dependent fulfillment constraints.
- Retrofit:Replacement installations within existing bathroom envelopes without structural modification. Solid-state thermoelectric heating elements enable these projects by miniaturizing temperature modulation hardware to thin-film substrates.
- New Construction:First-fit installations during building development with full network infrastructure pre-deployment. Philippines integrated resort developments in Cebu and Clark Freeport Zone specify building management system-compatible fixtures.
- Renovation:Comprehensive bathroom refurbishment projects involving tile removal and plumbing reconfiguration. Sydney and Brisbane high-rise developments unbundle after-sales service contracts from product procurement through body corporate governance structures.
- Modular:Prefabricated bathroom pods manufactured off-site and craned into position. Japanese commercial construction channels favor these for accelerated project timelines and standardized quality control.
New Construction captures the largest project value per installation; Retrofit expands the addressable building stock most rapidly.
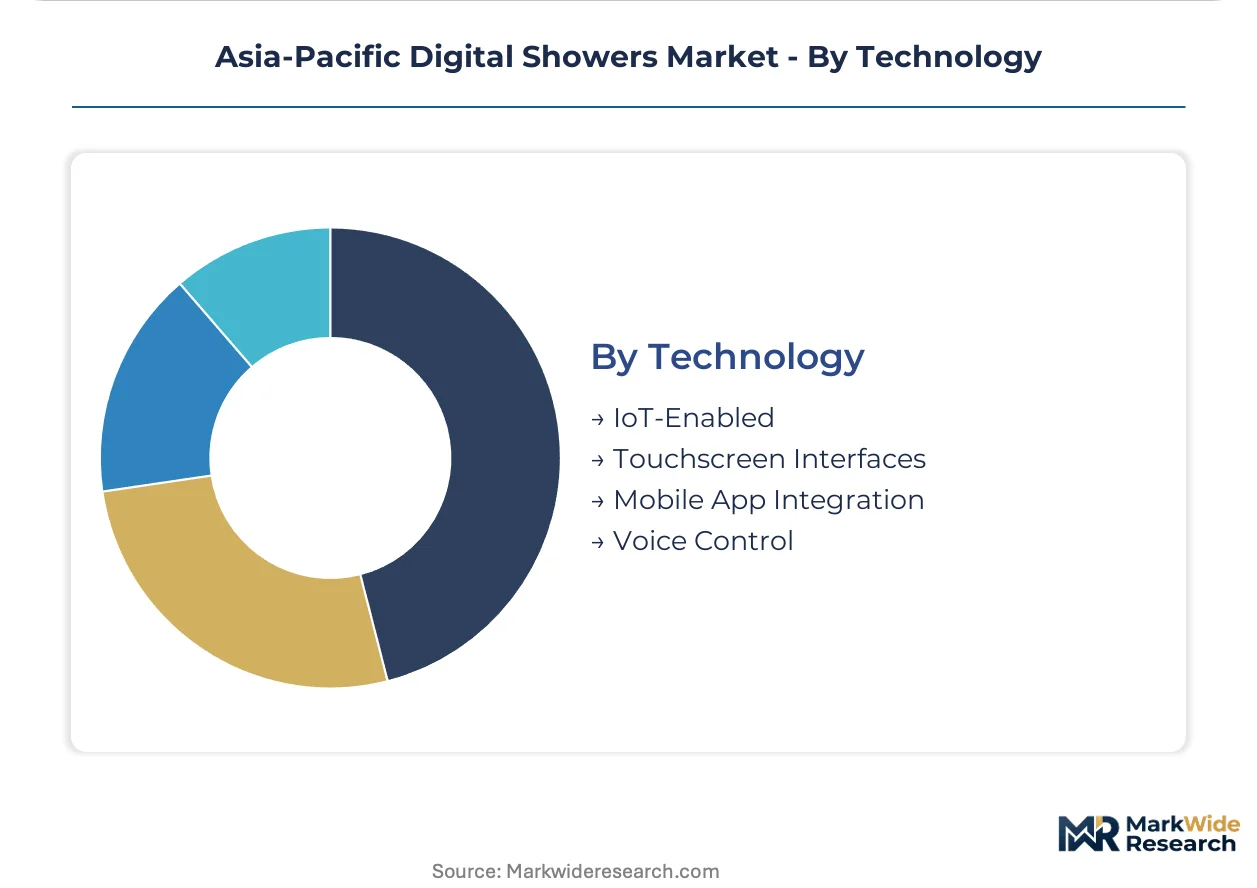
Technology:
Certification complexity escalates with connectivity depth, as networked architectures trigger cybersecurity validation requirements that extend product timelines.
- IoT-Enabled:Network-connected systems supporting remote monitoring, predictive maintenance, and building management integration. Japan's METI energy efficiency directives mandate smart load management, positioning these as controllable thermal assets.
- Touchscreen Interfaces:Capacitive or resistive display panels for local user input. Jaquar competes aggressively in India's mid-market with localized touchscreen interfaces adapted to regional language requirements.
- Mobile App Integration:Smartphone companion applications for remote preset configuration and usage analytics. South Korean and Australian urban residential clusters show rapid maturation as smartphone-native consumers expect seamless connectivity.
- Voice Control:Natural language processing capabilities embedded in shower control units. Australia's Essential Eight framework and Singapore's Cybersecurity Labelling Scheme extend validation timelines for these architectures.
IoT-Enabled dominates commercial specification; Voice Control faces the steepest regulatory friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's manufacturing dominance in ceramic valve components, while Singapore's Changi Airport cargo connectivity positions the city-state as the region's distribution nexus for high-value plumbing electronics.
China
Domestic hospitality construction in Chengdu and Hangzhou absorbs volume from localized smart shower production. GB standards for water efficiency and standby power consumption compress certification timelines for manufacturers with captive testing laboratories. Yangtze River Delta industrial clusters concentrate precision thermostatic cartridge output for export to Southeast Asian hotel developers.
Japan
METI energy efficiency directives mandate building-to-grid integration for commercial properties, positioning digital showers as controllable thermal assets. Kanto region construction channels favor modular bathroom pods with pre-installed network infrastructure. Osaka-based procurement consortia standardize specification criteria across hospitality and healthcare verticals.
India
BIS certification mandates for electromagnetic compatibility accelerate formalization of fragmented domestic supply chains. Maharashtra and Gujarat manufacturing corridors absorb technology transfer partnerships for touchscreen interface localization. Bengaluru residential clusters drive demand for cost-sensitive temperature control retrofits in aging apartment stock.
Australia
WELS rating premium tiers for connected fixtures create specification pathways for IoT-native products delivering consumption data to utility platforms. New South Wales and Victoria high-rise developments unbundle after-sales service contracts through body corporate governance structures. Sydney's premium renovation segment concentrates demand for solid-state thermoelectric heating elements.
South Korea
Seoul Capital Area urban residential clusters show rapid maturation of mobile app integration as smartphone-native consumers expect seamless connectivity. MFDS-equivalent consumer electronics safety frameworks extend to networked bathroom fixtures. Busan-Ulsan manufacturing bases supply thin-film substrate components to regional assemblers.
Asia-Pacific Digital Showers Market Competitive Landscape
Concentration sits with vertically integrated ceramic specialists and diversified sanitaryware conglomerates competing across distinct technology tiers. Three archetypes dominate: precision valve manufacturers with captive alumina-zirconia supply, full-solution bathroom ecosystem providers, and electronics-native entrants leveraging consumer device supply chains. Competitive moves center on backward integration into sensor manufacturing and strategic partnerships with building management system vendors.
Within the integrated bathroom systems tier, TOTO and LIXIL Corporation anchor positioning through divergent channel strategies. TOTO exemplifies precision manufacturing specialization with ceramic valve captive supply, while LIXIL Corporation represents construction-channel dominance through project specification influence. Jaquar occupies the mid-market localization archetype, competing on regional interface adaptation and certification agility.
| Leading Market Players |
|---|
| TOTO |
| LIXIL Corporation |
| Jaquar |
| Kohler |
| Cera Sanitaryware |
| Aqualisa Products |
| Grohe |
| Hansgrohe |
| Xiaomi |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation agreements with Japanese alumina-zirconia suppliers lock in ceramic valve access for tier-one assemblers while insulating them from spot-market volatility in copper and electronic sensor inputs. These contractual structures concentrate procurement influence among vertically integrated manufacturers with captive testing laboratories, compressing margin visibility for import-dependent brands facing extended GB certification queues in China.
Pricing Analysis
Volume-discount tiering separates hospitality procurement consortia from residential renovation buyers and mid-market retrofit segments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—WaterMark and WELS premium tiers in Australia command measurable uplifts over uncertified imports. Pricing pressure stems from copper and electronic sensor cost volatility compressing margin visibility for mid-tier manufacturers. Hospitality operators show lowest price sensitivity given capex standardization mandates, while India's BIS-compliant mid-market buyers face mandatory cost layers that intensify budget constraints.
Supply Chain Analysis
Strategic stockpile preferences dominate ceramic valve procurement given Japan and Germany's concentration of precision alumina-zirconia suppliers, while just-in-time inventory governs downstream electronic component flows from South Korean and Chinese semiconductor fabricators. Thermostatic cartridges draw from specialized Japanese ceramicists, thin-film substrates feed from Busan-Ulsan manufacturing bases, and flow sensors source from Taiwanese MEMS foundries. Single-source vulnerability in precision thermostatic cartridge supply exposes assemblers to input bottlenecks when Yangtze River Delta export capacity tightens. Distribution runs through Singapore's Changi Airport cargo nexus for high-value plumbing electronics serving Southeast Asian hospitality developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific digital showers sit in early-cycle expansion as luxury hospitality capex across Thailand, Vietnam, and Indonesia standardizes IoT-enabled temperature control as baseline amenity specifications.
For Market Incumbents: Secure backward integration into sensor manufacturing to offset copper and electronic component cost volatility compressing mid-tier margins. Defensive consolidation requires deepening channel control in Japanese commercial construction and accelerating captive compliance infrastructure to compress GB certification timelines against emerging domestic Chinese competitors. For New Entrants and Emerging Players: Anchor in Australia's WELS premium tier specification pathways where connected fixtures delivering consumption data to utility platforms face limited incumbent saturation. White-space targets include Philippines integrated resort developments in Cebu and Clark Freeport Zone seeking building management system-compatible fixtures, and India's formalizing mid-market renovation segment where localized touchscreen interfaces unlock BIS certification agility. For Investors and Strategic Acquirers: Electronics-native entrants with consumer device supply chain leverage represent the most compelling acquisition archetype given their capacity to compress firmware development cycles and navigate Australia's Essential Eight cybersecurity framework. Long-term viability hinges on differentiation through ecosystem integration rather than hardware margin capture. Watch for METI energy efficiency directive acceleration in Japan as the inflection signal—building-to-grid integration mandates would reposition digital showers as controllable thermal assets with measurable utility platform value.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Valve Backward Integration | Captive alumina-zirconia supply insulates TOTO and LIXIL from Japanese-German supplier bottlenecks. |
| Cybersecurity Certification Pre-Investment | Early alignment with Australia's Essential Eight framework compresses 8-14 month validation delays for IoT architectures. |
| Building Management System Partnership | Integration with hospitality procurement consortia in Thailand and Indonesia locks in specification influence. |
| Localized Touchscreen Interface Development | Regional language adaptation unlocks BIS certification agility in India's formalizing mid-market segment. |
| After-Sales Service Contract Unbundling | Sydney and Brisbane body corporate governance structures favor operational expenditure smoothing through multi-year agreements. |
Research Methodology
The analysis maps smart shower systems, digital controls, temperature control units, and water sensor systems, each validated through hospitality procurement directors, residential renovation contractors, commercial property managers, and regulatory compliance officers across primary interviews. Secondary validation draws from GB standards documentation, BIS certification registries, WELS rating databases, and METI energy efficiency directive filings. Bottom-up installation volume estimates triangulate against top-down hospitality capex flow analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models product type, technology tier, installation mode, and end-use concentration dimensions with regional regulatory cluster overlays. CAGRs derive from segment-level adoption curve analysis incorporating GB water efficiency standard phase-in timelines and ASEAN harmonization trajectory assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained hospitality construction pipelines and stable copper input costs; material deviation would warrant model refresh. Revision becomes warranted when cybersecurity certification timelines extend beyond current 8-14 month baselines or when China's GB standby power consumption standards expand coverage unexpectedly.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Smart Bath Heater Market
Household Items
Desktop Air Purifier Market
Household Items
Snow Blower Market
Household Items
Cast Iron Cookware Market
Household Items
Laundry Dryer Sheets and Bars Market
Household Items
Mirror Holder Market
Household Items
US Air Purifier Market
Household Items
Italy Digital Showers Market
Household Items
Saudi Arabia Cookware Market
Household Items
Air Purifier Market
Household Items
Remote Control Holder Market
Household Items
Pet Fur Remover Market
Household Items
Sleeping Pods Market
Household Items
HEPA Vacuum Cleaners Market
Household Items
Portable Iron Market
Household Items
UK Digital Showers Market