
 Kitchen Towel Market | 2026-2036
Kitchen Towel Market Size, Share, and Industry Trends Forecast 2026-2036
Kitchen Towel Market Intelligence
The capital-intensity divergence between integrated pulp-to-retail operators and conversion-only specialists is redrawing competitive boundaries in kitchen towel supply. Kimberly-Clark Corporation leverages its captive fiber supply and North American mill network to sustain margin resilience. Essity anchors European market presence through concentrated investment in tissue-grade recycled fiber technology. Koch Industries competes via its Georgia-Pacific subsidiary's control of bleached kraft pulp capacity serving private-label converters.
Kitchen towels are absorbent paper or textile products engineered with basis weights of 20–40 gsm for disposable grades and 200–400 gsm for reusable cotton variants, manufactured through creping or air-laid processes to maximize liquid retention for surface cleaning and food preparation hygiene. Roll-format disposable towels dominate commercial channel volume due to dispenser compatibility and janitorial procurement standardization, while microfiber reusable segments capture premium household margins through extended-use value propositions. Cotton-based products occupy a shrinking but defensible niche in hospitality settings where laundering infrastructure supports circular operating models.
EPA wastewater discharge standards under the Clean Water Act shape US mill siting and bleaching chemistry investments, while EU Ecolabel criteria and the F-Gas Regulation's indirect energy-cost effects constrain European production economics. The EU Green Deal's packaging waste targets are forcing reformulation of wrapper films and core materials across export-oriented manufacturers. Stakeholders must monitor divergence between US state-level extended producer responsibility legislation and EU harmonized circularity mandates when configuring regional product portfolios.
Market Dynamics
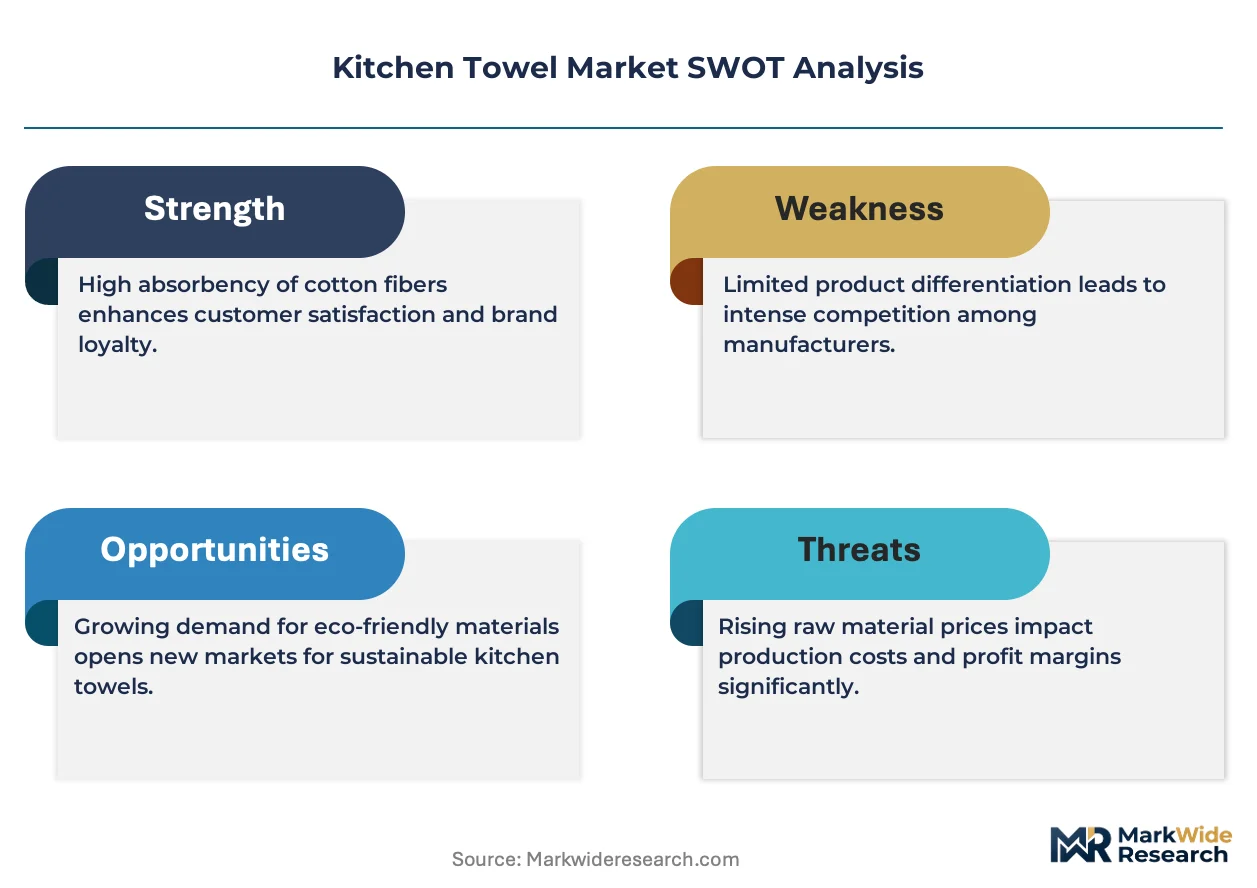
Disposable kitchen towel demand is bifurcating between premium biodegradable grades and economy synthetic blends as commercial foodservice operators face divergent regulatory pressures across North America and Europe.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandates for biodegradable alternatives are pulling fiber innovation investment toward compostable air-laid substrates in German and French manufacturing clusters.
- Commercial foodservice hygiene mandates:Stricter surface-contact protocols in US institutional kitchens are expanding roll-format dispenser installations and janitorial procurement standardization.
- Recycled fiber technology maturation:Tissue-grade de-inking and fiber conditioning advances are enabling closed-loop pulp sourcing without basis-weight penalties.
Market Restraints
- Bleached kraft pulp price volatility:Input cost swings compress margin buffers for conversion-only specialists lacking captive fiber supply.
- EU F-Gas Regulation energy-cost effects:Indirect thermal process constraints raise European mill operating costs relative to North American integrated operators.
- Reusable microfiber substitution:Extended-use value propositions in premium household segments displace disposable volume in hospitality laundering infrastructure.
Strategic Opportunities
- Underpenetrated German institutional channel:Certified sustainable product preference among Bundesrepublik buyers creates white space for Ecolabel-compliant entrants.
- Wrapper film reformulation:EU Green Deal packaging waste targets force core and wrap material innovation, rewarding early movers with export qualification.
- Air-laid and creping process convergence:Hybrid manufacturing platforms enable rapid grade switching between commercial roll and household sheet formats.
Industry Challenges
- EPA Clean Water Act compliance timelines:US mill siting and bleaching chemistry investments face permitting delays that stretch capital deployment cycles.
- Extended producer responsibility fragmentation:Divergent US state-level mandates versus EU harmonized circularity rules complicate regional portfolio configuration.
- Recycled fiber certification complexity:FSC, PEFC, and EU Ecolabel overlapping requirements extend product qualification timelines for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitchen Towel Market |
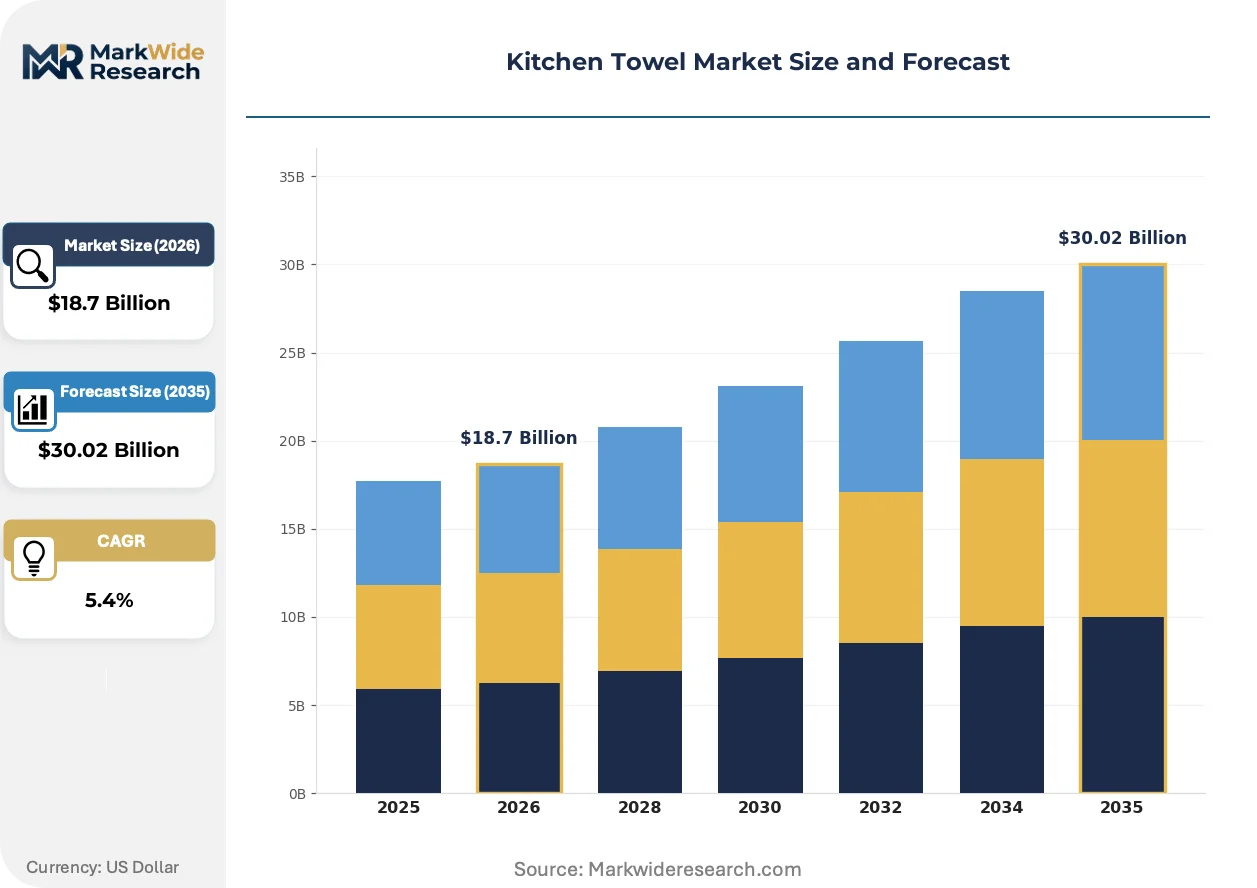
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Microfiber, Cotton End Use: Household, Commercial, Industrial, Hospitality Size: Standard, Extra Large, Compact, Jumbo Packaging Type: Roll, Pack, Bulk, Individually Wrapped |
| Companies Covered | Kimberly-Clark Corporation, Procter & Gamble Corporation, Koch Industries, Inc., Essity, WEPA Professional GmbH, Sofidel Group, Wausau Paper Corp., Accrol Group Holdings Plc, Aldar Tissues Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitchen Towel Market Strategic Shifts & Innovations
Active reshaping in kitchen towel supply stems from fiber technology convergence with packaging reformulation and procurement model compression in institutional channels.
Air-laid nonwoven substrates engineered with cellulose microfiber reinforcement are miniaturizing basis-weight requirements while maintaining liquid retention performance. German commercial foodservice operators are adopting these grades at accelerated replacement cycles for traditional creped towels. The technology is compressing freight and storage cost structures for distributor private-label programs.
REACH chemical authorization protocols and the EU Green Deal's packaging waste targets are forcing wrapper film migration from polypropylene to polylactic acid and paper-based alternatives. European manufacturers face reformulation investment requirements that US exporters must match for market access. Private-label converters serving German retail are responding with certified compostable core materials ahead of mandate deadlines.
Janitorial procurement consolidation through group purchasing organizations is compressing supplier rosters and unbundling after-sales dispenser service from product supply. US institutional buyers are consolidating volume through healthcare and education procurement alliances that displace independent distributor relationships. This concentration is most visible in Midwest hospital systems and California university networks.
Kitchen Towel Market Segmentation
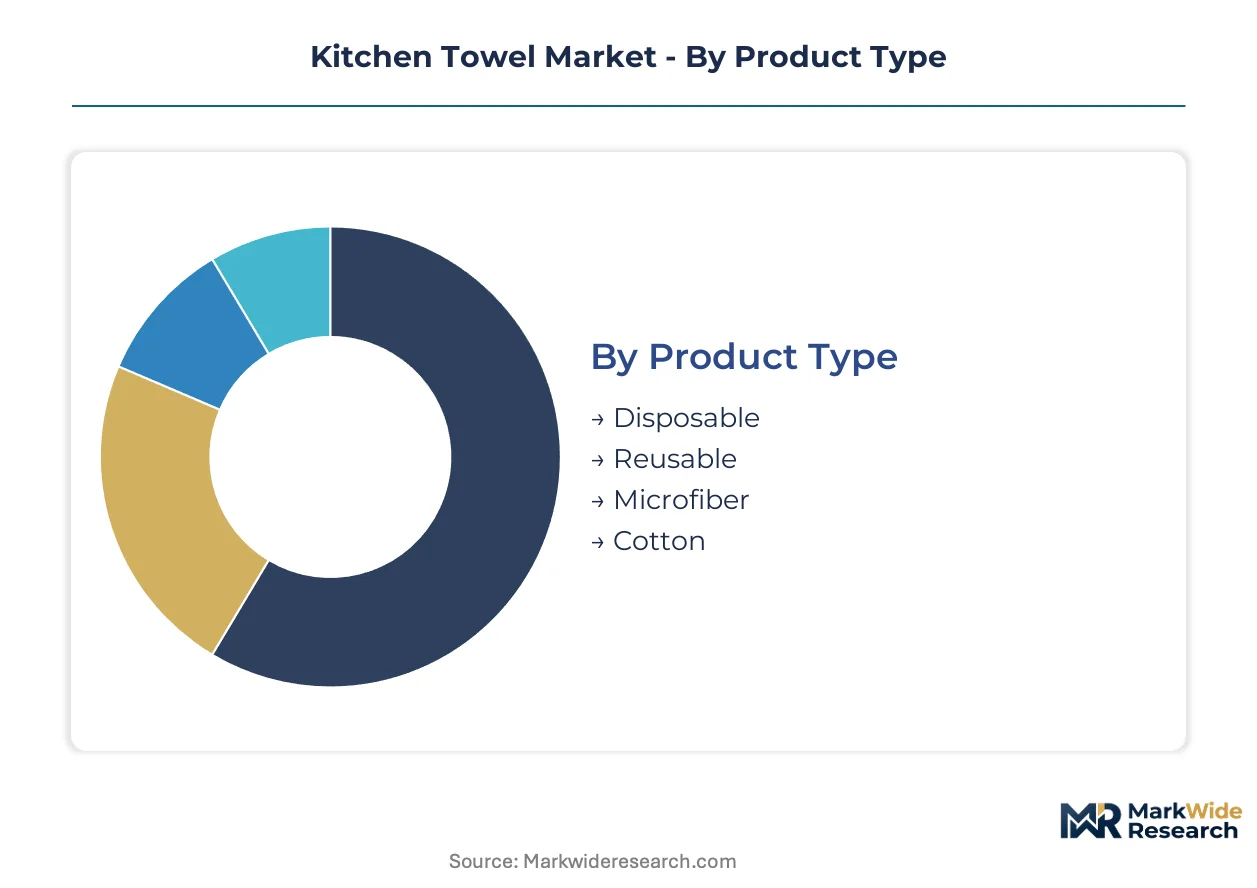
Kitchen towel demand fragments across material technologies, use environments, and procurement formats. Each segment carries distinct margin profiles and regulatory exposure that reshape supplier priorities across North American and European markets.
Product Type:
Disposable grades dominate US domestic volume through institutional procurement standardization. Reusable and specialty fiber variants concentrate export demand toward EU markets with stricter circularity mandates.
- Disposable:Air-laid and creped substrates engineered at 20–40 gsm basis weights serve commercial foodservice roll-format installations. US hospital systems and California university networks are expanding dispenser-compatible procurement through group purchasing organization consolidation.
- Reusable:Cotton and blended textile products at 200–400 gsm support circular operating models in hospitality settings with on-premise laundering infrastructure. German institutional buyers favor certified sustainable variants under EU Ecolabel criteria.
- Microfiber:Synthetic filament constructions capture premium household margins through extended-use value propositions.
- Cotton:Natural fiber products occupy shrinking but defensible niches where laundering economics justify higher upfront cost.
Disposable commands the established base. The steepest expansion runs through microfiber.
End Use:
Commercial channels concentrate volume through janitorial procurement consolidation. Household and industrial applications diverge on price sensitivity and performance specification.
- Household:Sheet-format products in premium and economy tiers serve residential surface cleaning and food preparation hygiene. Microfiber substitution is displacing disposable volume in affluent US coastal markets.
- Commercial:Roll-format dispenser systems dominate foodservice and institutional procurement. Stricter EPA and state-level surface-contact protocols are expanding installation bases across Midwest hospital systems.
- Industrial:Heavy-duty absorbent grades serve manufacturing maintenance and spill response with specification-driven purchasing.
- Hospitality:Reusable cotton variants persist where on-premise laundering infrastructure supports circular cost models. EU Green Deal packaging waste targets are forcing wrapper film reformulation for amenity-format supplies.
Commercial channels anchor volume concentration. Hospitality is gaining share fastest amid sustainability-driven procurement shifts.
Size:
Format dimensions align with dispenser compatibility and storage economics across institutional and retail channels.
- Standard:Baseline dimensions serve residential and light commercial applications with broad retail distribution.
- Extra Large:Extended sheet formats reduce replacement frequency in high-throughput foodservice environments.
- Compact:Space-optimized rolls target urban households and limited-storage commercial kitchens.
- Jumbo:Maximized capacity rolls minimize maintenance labor in airport, stadium, and healthcare dispenser installations.
Standard sizes hold the volume base. Jumbo formats are climbing the fastest as labor cost pressures intensify.
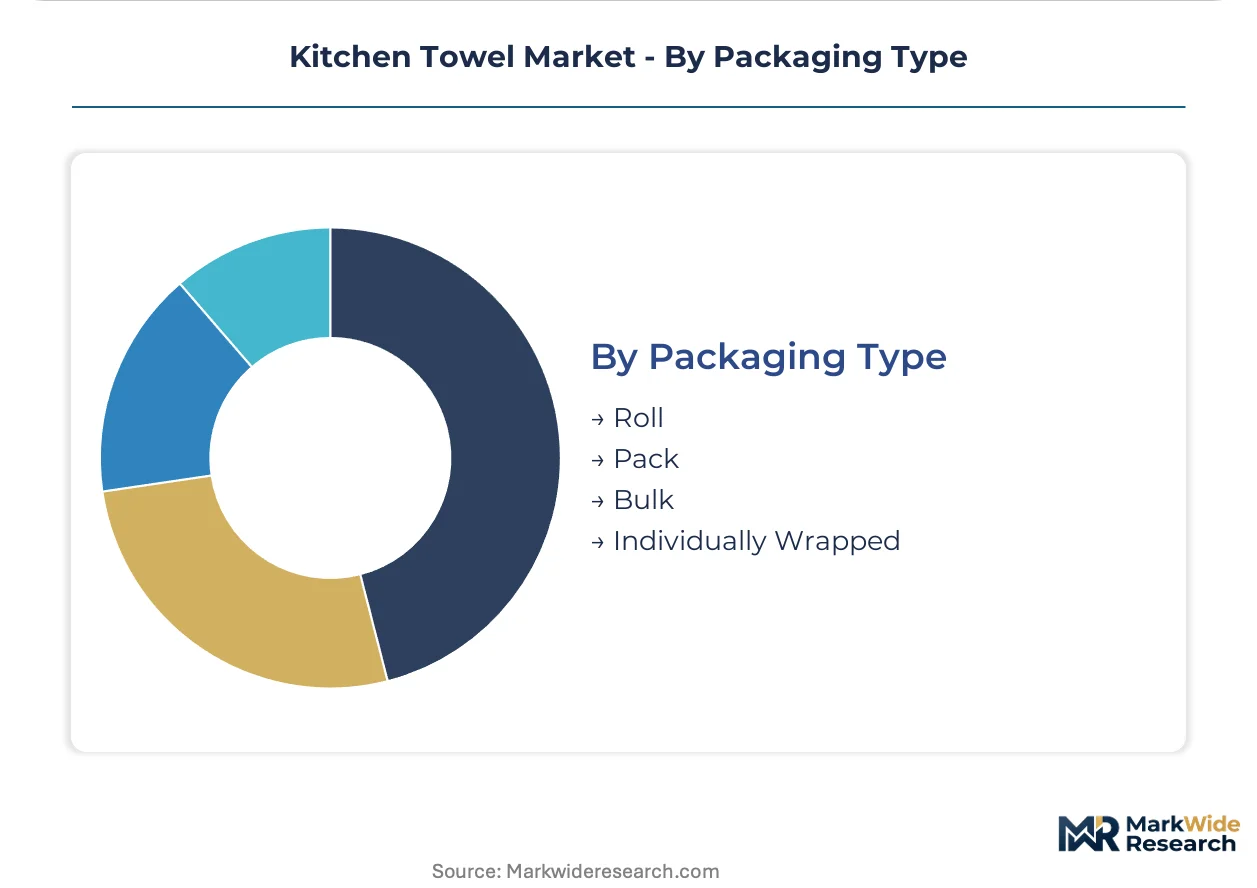
Packaging Type:
Configuration choices reflect channel economics and regulatory pressure on wrapper materials.
- Roll:Core-wound formats dominate commercial channel volume through dispenser compatibility and janitorial procurement standardization. REACH chemical authorization and EU Green Deal targets are forcing core and wrap material migration from polypropylene to polylactic acid.
- Pack:Multi-unit retail configurations serve household stock-up purchasing with shelf-ready presentation.
- Bulk:Unwrapped or minimally packaged volume targets industrial and institutional buyers with established dispenser infrastructure.
- Individually Wrapped:Single-unit hygiene packaging serves hospitality amenity and foodservice to-go applications with premium positioning.
Roll packaging controls the commercial core. Individually wrapped formats show the steepest expansion trajectory amid hygiene protocol tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between North American institutional buyers favoring roll-format dispenser systems and European households gravitating toward certified sustainable sheet products. This geographic split in product-form preference reshapes manufacturing investment and export qualification requirements across supplier networks.
United States
Midwest hospital systems and California university networks are consolidating procurement through healthcare and education purchasing alliances. EPA wastewater discharge standards under the Clean Water Act are stretching capital deployment cycles for mill siting and bleaching chemistry investments. Georgia-Pacific's bleached kraft pulp capacity in the Southeast supplies private-label converters serving institutional channels.
Germany
Bundesrepublik institutional buyers are driving fastest adoption of EU Ecolabel-certified sustainable products amid stricter hygiene mandates in commercial foodservice. The EU Single-Use Plastics Directive is pulling fiber innovation investment toward compostable air-laid substrates in manufacturing clusters around Düsseldorf and Hamburg. WEPA Professional's concentrated recycled fiber technology anchors European market presence.
China
Yangtze River Delta manufacturing hubs are scaling air-laid nonwoven capacity for export markets facing biodegradable packaging mandates. The country's dual carbon goals are pressuring mills toward energy-efficient thermal processes. Shanghai-based converters are reformulating wrapper films to meet EU Green Deal packaging waste targets for European market access.
United Kingdom
Accrol Group Holdings and other tissue specialists are navigating post-Brexit divergence between UK extended producer responsibility legislation and EU harmonized circularity rules. London and Southeast England retail channels are compressing supplier rosters through janitorial procurement consolidation. REACH chemical authorization protocols are forcing core and wrap material migration from polypropylene to polylactic acid alternatives.
France
Île-de-France foodservice operators are accelerating replacement cycles for traditional creped towels with cellulose microfiber-reinforced grades. ANSM hygiene protocols in institutional kitchens are expanding surface-contact standards. Sofidel Group's manufacturing presence in the Auvergne-Rhône-Alpes region serves both domestic and export demand for certified compostable products.
Kitchen Towel Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in kitchen towel supply. Kimberly-Clark Corporation and Koch Industries' Georgia-Pacific subsidiary control captive fiber supply and North American mill networks, sustaining margin resilience against pulp price volatility. Conversion-only specialists lacking backward integration face compressed buffers during input cost swings. The competitive landscape rewards two strategic moves: hybrid manufacturing platforms enabling rapid grade switching, and early reformulation of wrapper films to secure export qualification ahead of mandate deadlines.
Among North American integrated operators, Kimberly-Clark Corporation exemplifies the captive-fiber archetype through its pulp-to-retail control. Essity occupies a position representing European recycled fiber technology concentration. Koch Industries sits within the industrial conglomerate tier leveraging bleached kraft pulp capacity to serve private-label converters. These three anchors illustrate how supply-side structure determines competitive positioning across diverging regulatory environments.
| Leading Market Players |
|---|
| Kimberly-Clark Corporation |
| Procter & Gamble Corporation |
| Koch Industries, Inc. |
| Essity |
| WEPA Professional GmbH |
| Sofidel Group |
| Wausau Paper Corp. |
| Accrol Group Holdings Plc |
| Aldar Tissues Ltd. |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between bleached kraft pulp suppliers and integrated tissue manufacturers lock in fiber access and price visibility across multi-year procurement cycles, insulating North American mills from spot market volatility while binding conversion-only specialists to narrower margin bands.
Pricing Analysis
Dispenser service contracts and maintenance bundling drive lifetime value in commercial channel relationships. Three-tier pricing structure across premium Ecolabel-certified, standard recycled-content, and economy synthetic-blend tiers separates institutional buyers by certification grade and volume scale. Cost compression in economy grades is intensifying because pulp price volatility compresses buffers for non-integrated converters. Quick-service restaurant chains exhibit highest price sensitivity, while German hospital systems demonstrate lowest sensitivity due to mandated hygiene compliance.
Supply Chain Analysis
Bleached kraft pulp concentration in the US Southeast, Canadian boreal forests, and Brazilian eucalyptus plantations anchors global tissue-grade fiber supply. Manufacturing draws from softwood kraft pulp, air-laid bonding agents, and polylactic acid wrapper films as critical inputs. Single-source vulnerability runs through Southeast US mill networks exposed to hurricane-related production interruptions. Distribution runs through janitorial supply distributors and group purchasing organization consolidated channels serving institutional end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern as commercial foodservice operators rebuild inventory positions following pandemic-era destocking, with replacement cycle normalization in institutional dispenser installations providing the cyclical anchor.
For Market Incumbents: Fortify backward integration into recycled fiber conditioning technology to offset virgin pulp volatility. Anchor capacity expansion in German manufacturing clusters where EU Ecolabel certification commands premium positioning. Defend against microfiber substitution in hospitality by embedding laundering service contracts into reusable product offerings. For New Entrants and Emerging Players: Differentiate on compostable air-laid substrate formulations ahead of EU Single-Use Plastics Directive enforcement deadlines. Target the underpenetrated Bundesrepublik institutional channel where certified sustainable preference creates white space. Lead with group purchasing organization direct contracting to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward conversion-only specialists with established private-label relationships and reformulation-ready manufacturing platforms. Five-to-ten year viability hinges on wrapper film migration capability and hybrid grade-switching equipment. Monitor EU Green Deal packaging waste target enforcement timelines as the inflection signal for export qualification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Technology | Essity's concentrated investment in tissue-grade de-inking anchors European market presence against pulp volatility. |
| Hybrid Manufacturing Platform Deployment | Air-laid and creping process convergence enables rapid switching between commercial roll and household sheet formats. |
| EU Ecolabel Certification Investment | German institutional buyers favor certified sustainable products, creating premium positioning for compliant entrants. |
| Wrapper Film Reformulation | Migration from polypropylene to polylactic acid secures export qualification under EU Green Deal packaging waste targets. |
| Group Purchasing Organization Direct Contracting | US healthcare and education procurement alliances displace independent distributor relationships in Midwest hospital systems. |
Research Approach
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from publicly traded tissue manufacturers, EPA discharge permit records, and EU Ecolabel certification databases. Interviews with procurement directors at foodservice operators, mill operations managers, janitorial supply distributors, and sustainability compliance officers informed demand and supply-side validation. Bottom-up volume modeling triangulated against top-down macroeconomic absorption rates.
Segmentation dimensions modeled include material technology, end-use channel, format size, and packaging configuration across the analysis window. CAGRs derive from regression analysis of historical consumption patterns against regulatory mandate timelines and fiber technology substitution curves. Forecast inputs incorporate pulp price cycle positioning and commercial foodservice employment indices as demand proxies.
The analysis sits within stated boundaries; outcomes outside EU regulatory enforcement timelines or North American pulp capacity expansion trajectories would require recalibration. Forecasts reflect documented assumptions regarding biodegradable substrate adoption rates and dispenser installation cycles. Practitioners should keep alternative scenarios live as EU Single-Use Plastics Directive implementation schedules and US state-level extended producer responsibility legislation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Dry and Wet Wipes Market
Household Items
Gas Hobs Market
Household Items
UV Sanitizer Travel Wand Market
Household Items
Consumerware Market
Household Items
Europe Digital Showers Market
Household Items
Household Sewing Machines Market
Household Items
US Coin-Operated Commercial Laundry Market
Household Items
Global on-Premise-Laundry (OPL) Market
Household Items
Pet Safe Cleaners Market
Household Items
Hydration Containers Market
Household Items
Permanent Marker Market
Household Items
Japan Faucets Market
Household Items
Laundry Detergent Sheets Market
Household Items
Deodorizer Bag Market
Household Items
Europe Cookware Market
Household Items
Wet Wipes and Toilet Paper Market