
 US Soap Dispenser Market | 2026-2036
US Soap Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
US Soap Dispenser Market Insights
Stainless steel is shifting from premium niche to standard specification across commercial restroom retrofits, compressing plastic-dominated price bands. GOJO Industries leverages its healthcare channel dominance to push touch-free systems into ambulatory surgical centers. Bradley Corporation anchors its position through captive manufacturing of sensor modules and valve assemblies. Kimberly-Clark competes on institutional contract bundling with paper product lines.
A soap dispenser is a mechanical or electromechanical vessel engineered to release controlled volumes of liquid or foam soap through manual depression, lever actuation, or infrared proximity detection, typically constructed with ABS housings, stainless steel reservoirs, or borosilicate glass chambers rated for repeated sanitization cycles. Its primary purpose is to reduce cross-contamination in high-traffic hygiene environments while enabling precise dosage to control consumable waste. Automatic dispensers lead volume in healthcare and airport installations where touchless protocols are mandated, while wall-mounted units retain margin strength in educational organizations through bulk-refill economics. Manual countertop dispensers occupy the residential segment but face displacement from rechargeable sensor units with lithium-ion power management.
The FDA's medical device surface guidance and OSHA workplace sanitation standards jointly elevate minimum durability and antimicrobial performance thresholds for commercial-grade units. California's Title 24 building efficiency code and municipal green procurement policies in Los Angeles and San Francisco bias specifications toward refillable systems with reduced packaging waste. Stakeholders must monitor how state-level extended producer responsibility legislation restructures aftermarket refill economics and channel control.
Market Dynamics
Healthcare infection control mandates are compressing manual dispenser lifecycles and forcing rapid sensor-system retrofits across inpatient facilities. The FDA's surface guidance elevates antimicrobial performance thresholds, while California's green procurement rules restructure refill economics toward bulk-container systems.
Growth Catalysts
- OSHA workplace sanitation standards:Federal mandates for high-traffic hygiene environments accelerate touch-free installations in manufacturing plants and distribution centers.
- Acute care facilities:Hospital systems deploy infrared proximity dispensers in patient rooms and surgical suites to reduce cross-contamination vectors.
- Lithium-ion power management:Rechargeable sensor units with extended battery life displace alkaline-powered legacy systems in commercial retrofits.
Market Restraints
- Stainless steel input volatility:Raw material price swings compress margin buffers for commercial-grade reservoir manufacturers.
- Sensor module supply concentration:Dependence on Asian semiconductor foundries creates lead-time vulnerability for automatic dispenser assembly.
- ABS plastic substitution ceiling:Healthcare buyers reject lower-grade housings despite cost advantages, limiting price-tier flexibility.
Strategic Opportunities
- Ambulatory surgical centers:Outpatient facilities lag inpatient touch-free penetration, creating retrofit white space in Texas and Florida markets.
- Extended producer responsibility legislation:California and New York pending rules favor refillable systems with reduced packaging waste.
- IoT-enabled consumption tracking:Cloud-connected dispensers with usage analytics converge with facility management software platforms.
Industry Challenges
- Electromechanical calibration expertise:Shortage of technicians skilled in infrared sensor alignment and valve assembly troubleshooting slows field service response.
- FDA 510(k) pathway complexity:Antimicrobial coating claims require extended documentation timelines for medical-grade dispenser certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Soap Dispenser Market |
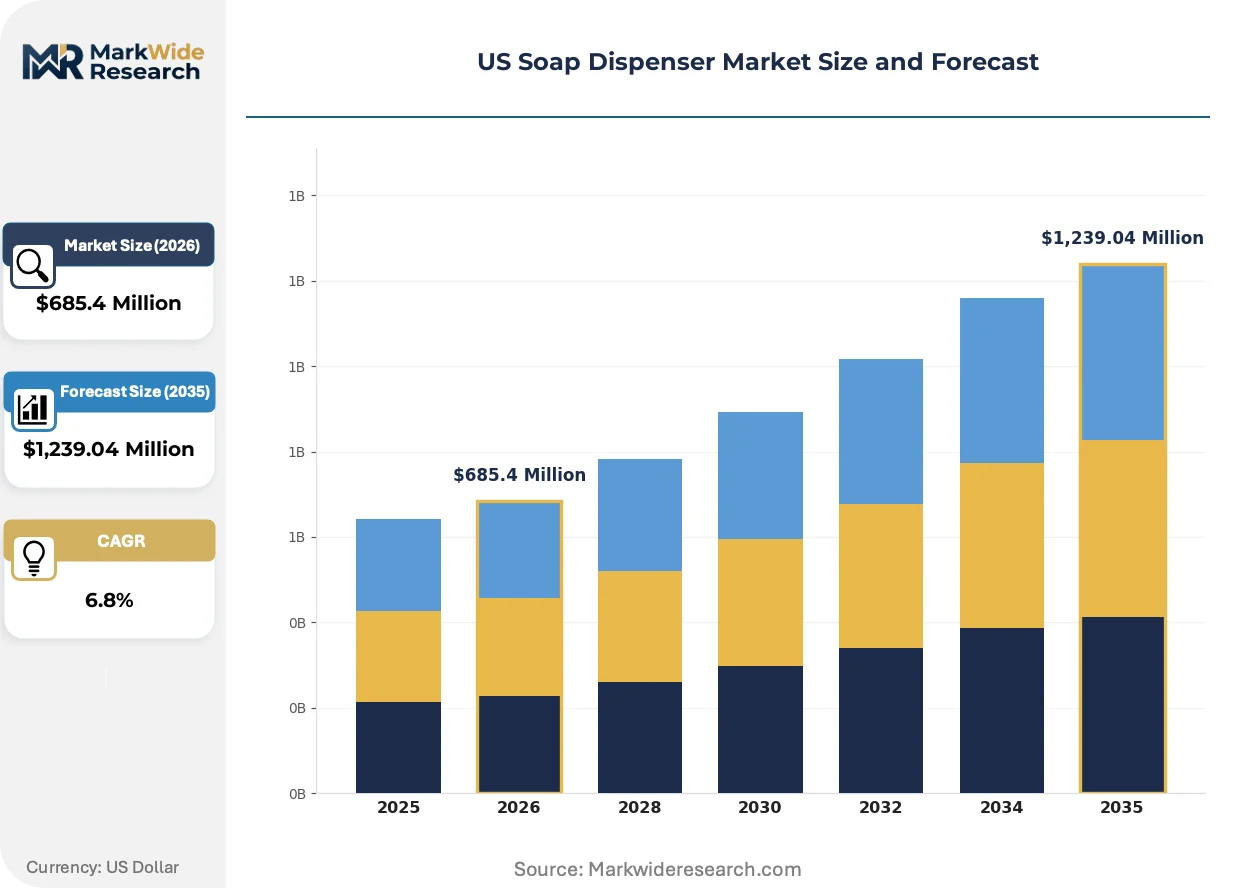
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Dispensers, Automatic Dispensers, Wall-Mounted Dispensers, Countertop Dispensers Distribution Channel: Online Stores, Retail Outlets, Supermarkets, Direct Sales End User: Commercial Facilities, Residential Users, Healthcare Institutions, Educational Organizations Material: Plastic, Stainless Steel, Glass, Aluminum |
| Companies Covered | GOJO Industries, Bobrick Washroom Equipment, Bradley Corporation, American Specialties, Sloan Valve Company, Kimberly-Clark, Simplehuman, Kohler Co., SC Johnson Professional, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Soap Dispenser Market Trends and Innovations
Touchless protocols are rewriting specification standards across commercial restroom infrastructure. Three converging forces—solid-state sensor evolution, federal infection control mandates, and procurement centralization—are compressing legacy product lifecycles and elevating performance minimums.
Solid-state infrared proximity detection is rewriting dispenser reliability benchmarks. The technology eliminates mechanical wear points in high-frequency use environments. Airport authorities and hospital systems in California and Texas are specifying these modules for new construction and deep retrofits alike. This shift compresses demand for lever-actuated and push-button systems in commercial segments.
FDA medical device surface guidance elevates antimicrobial performance thresholds for healthcare-grade units. The regulation mandates validated efficacy claims for dispenser contact surfaces in patient care zones. Acute care systems in New York and Illinois are requiring third-party certification documentation prior to contract award. Manufacturers respond by integrating copper-alloy touchpoints and EPA-registered coating formulations.
Facility management procurement centralization is consolidating vendor relationships across multi-site healthcare networks. Large hospital systems are unbundling dispenser supply from janitorial service contracts and negotiating direct manufacturer agreements. This pattern is most visible in Midwestern integrated delivery networks seeking standardized equipment footprints across dozens of affiliated clinics.
US Soap Dispenser Market Segmentation
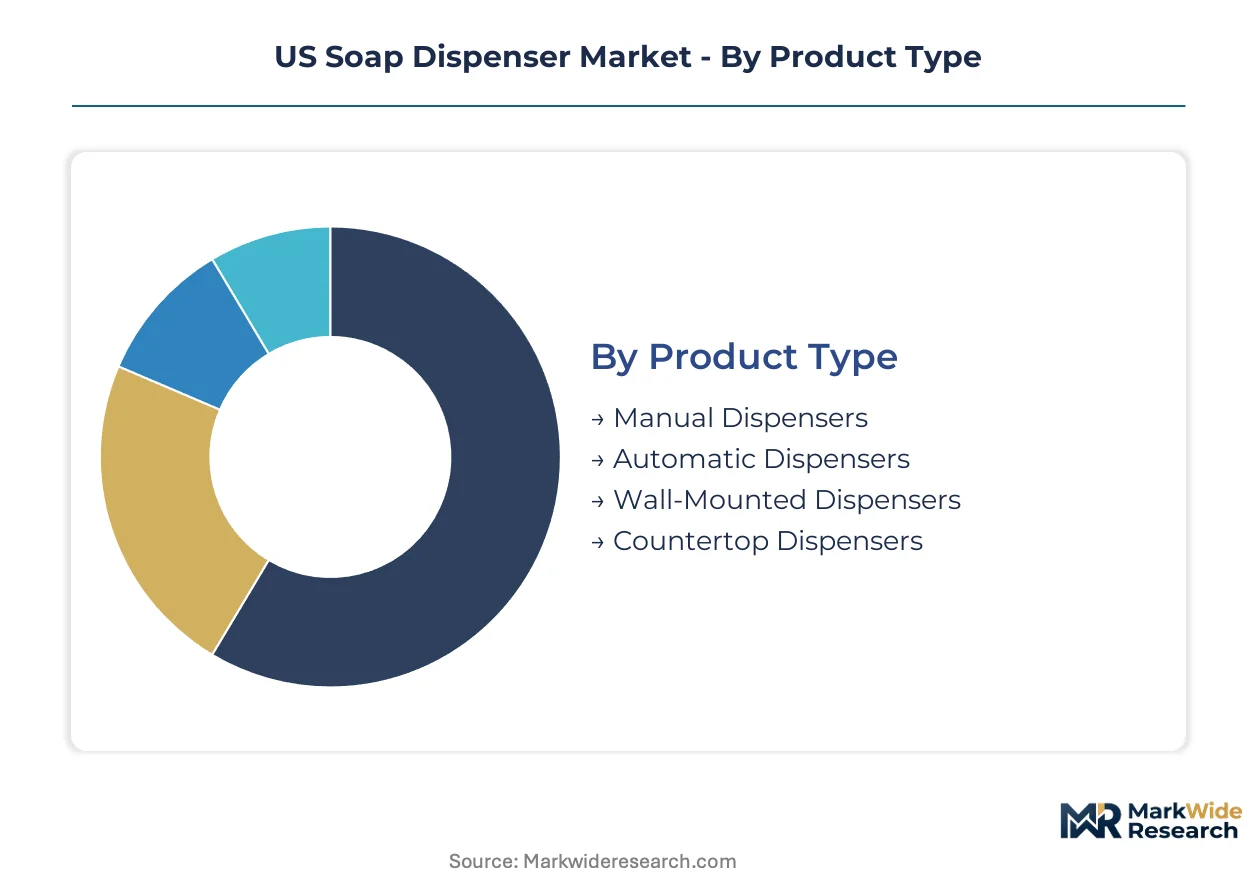
US soap dispenser procurement splits sharply between standardized high-volume contracts and engineered specifications for infection-sensitive environments. Understanding these fault lines reveals where margin concentrates and which technology transitions will reshape supplier relationships.
Product Type:
Customization intensity varies dramatically across this category, from commodity manual units to sensor-integrated systems requiring field calibration protocols.
- Automatic Dispensers:Infrared proximity detection modules with solid-state sensors eliminate mechanical wear in high-frequency healthcare corridors. California hospital systems and Texas airport authorities specify these for new construction and deep retrofits, compressing legacy push-button lifecycles.
- Manual Dispensers:Lever-actuated or push-button mechanisms with ABS housings or stainless steel reservoirs serve cost-constrained educational facilities and residential installations. OSHA workplace sanitation standards are forcing rapid displacement in manufacturing plants and distribution centers.
- Wall-Mounted Dispensers:Bulk-refill economics dominate commercial restroom infrastructure, favored by facility management procurement centralization across Midwestern integrated delivery networks.
- Countertop Dispensers:Portable units for residential kitchens and small commercial spaces face displacement from rechargeable lithium-ion sensor units with extended battery life.
Leading the category by volume: Wall-Mounted Dispensers. Expanding most quickly: Automatic Dispensers.
Distribution Channel:
Channel economics reflect buyer scale and specification complexity, from self-service digital procurement to engineered direct relationships.
- Direct Sales:Manufacturer-led contracting for multi-site healthcare networks unbundles dispenser supply from janitorial service agreements, standardizing equipment footprints across dozens of affiliated clinics.
- Online Stores:E-commerce platforms serve residential replacement demand and small commercial buyers seeking rapid fulfillment without specification engineering.
- Retail Outlets:Big-box and specialty hardware channels stock manual countertop units for consumer kitchen and bathroom renovations.
- Supermarkets:Mass-market grocery chains carry basic refill cartridges and entry-level dispensers for impulse residential purchase.
Highest margin concentration: Direct Sales. Fastest channel expansion: Online Stores.
End User:
Application environment dictates performance thresholds, from antimicrobial coating requirements to bulk-refill economics.
- Healthcare Institutions:Acute care facilities deploy infrared proximity dispensers in patient rooms and surgical suites to reduce cross-contamination vectors, with FDA surface guidance elevating minimum durability and antimicrobial performance thresholds.
- Commercial Facilities:Airport authorities, corporate campuses, and hospitality properties balance touchless protocol mandates with total cost of ownership across high-traffic restrooms.
- Educational Organizations:K-12 and university systems prioritize wall-mounted bulk-refill economics over premium sensor specifications, though lithium-ion rechargeable units are penetrating administrative buildings.
- Residential Users:Manual countertop dispensers dominate home kitchens and bathrooms, though rechargeable sensor units with lithium-ion power management are gaining traction in premium renovation segments.
Steepest specification escalation: Healthcare Institutions. Largest addressable base: Commercial Facilities.
Material:
Material selection tracks durability requirements and aesthetic positioning, with regulatory pressure reshaping traditional hierarchies.
- Stainless Steel:Commercial-grade reservoirs with copper-alloy touchpoints and EPA-registered coating formulations meet FDA-validated efficacy claims for patient care zones, shifting from premium niche to standard specification across commercial restroom retrofits.
- Plastic:ABS housings serve cost-sensitive educational and residential segments, though healthcare buyers reject lower-grade variants despite price advantages, limiting price-tier flexibility.
- Glass:Borosilicate glass chambers rated for repeated sanitization cycles occupy aesthetic-driven hospitality and premium residential installations.
- Aluminum:Lightweight metal housings balance durability and cost for mid-tier commercial applications, particularly in California municipal green procurement contexts favoring recyclable materials.
Fastest share gain: Stainless Steel. Volume anchor: Plastic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in California's commercial building sector, where municipal green procurement rules favor durable refillable units. Healthcare systems in the Northeast and Texas are accelerating touch-free retrofits. The Midwest maintains bulk-refill economics in educational facilities.
California
Los Angeles and San Francisco municipal green procurement policies bias specifications toward refillable systems with reduced packaging waste. Title 24 building efficiency code mandates elevate minimum durability thresholds for commercial restroom infrastructure. San Diego's hospitality sector drives borosilicate glass chamber installations in premium properties.
Texas
Dallas-Fort Worth and Houston ambulatory surgical centers present retrofit white space as outpatient facilities lag inpatient touch-free penetration. OSHA workplace sanitation standards accelerate sensor-system deployments in manufacturing plants along the Gulf Coast. Austin's tech campus expansions specify lithium-ion rechargeable units for administrative buildings.
New York
Acute care systems in New York City and Buffalo require third-party certification documentation prior to contract award under FDA surface guidance. Integrated delivery networks negotiate direct manufacturer agreements unbundling dispenser supply from janitorial contracts. Rochester's educational institutions prioritize wall-mounted bulk-refill economics.
Illinois
Chicago hospital systems deploy infrared proximity dispensers in patient rooms and surgical suites to reduce cross-contamination vectors. Midwestern integrated delivery networks seek standardized equipment footprints across dozens of affiliated clinics. Peoria's manufacturing facilities face OSHA-mandated displacement of manual dispensers.
Florida
Miami and Orlando hospitality properties balance touchless protocol mandates with total cost of ownership across high-traffic restrooms. Tampa's ambulatory surgical centers represent underpenetrated retrofit opportunity. Jacksonville's airport authority specifications compress legacy push-button lifecycles in new construction.
US Soap Dispenser Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers secure sensor module supply and healthcare channel access. The vendor base stratifies across three tiers: integrated hygiene conglomerates with paper product bundling capabilities, specialized washroom equipment fabricators with captive manufacturing, and premium consumer brands leveraging design differentiation. Two archetypes anchor positioning: healthcare channel specialists leveraging FDA compliance documentation, and commercial infrastructure providers with direct contracting relationships. Competitive moves concentrate on M&A for sensor technology capabilities and vertical integration into valve assembly production.
Within the healthcare-specialist tier, GOJO Industries and Bradley Corporation exemplify divergent approaches to channel dominance. GOJO leverages its established healthcare presence to push touch-free systems into ambulatory surgical centers. Bradley anchors positioning through captive manufacturing of sensor modules and valve assemblies, insulating against Asian semiconductor foundry lead-time vulnerability. Among diversified hygiene providers, Kimberly-Clark competes on institutional contract bundling with paper product lines. These three players represent the competitive archetypes reshaping supplier relationships: channel-integrated specialists, vertically integrated fabricators, and bundled-service conglomerates.
| Leading Market Players |
|---|
| GOJO Industries |
| Bobrick Washroom Equipment |
| Bradley Corporation |
| American Specialties |
| Sloan Valve Company |
| Kimberly-Clark |
| Simplehuman |
| Kohler Co. |
| SC Johnson Professional |
| Others |
Pricing and Supply Chain Analysis
Midwestern integrated delivery networks with standardized equipment footprints command contract-based long-term offtake pricing that compresses margin buffers for non-compliant suppliers. California's Title 24 building efficiency code and municipal green procurement rules in Los Angeles and San Francisco further bias specifications toward refillable systems, reshaping supplier economics toward bulk-container service models.
Pricing Analysis
Volume concentrates in wall-mounted bulk-refill systems for educational facilities while margins concentrate in automatic dispensers with infrared proximity detection for healthcare institutions. Three-tier pricing structure across premium stainless steel with copper-alloy touchpoints, standard ABS housings, and economy manual units tracks FDA certification tiers and antimicrobial performance validation. Cost compression in the plastic-dominated mid-tier intensifies because healthcare buyers reject lower-grade housings despite price advantages. Educational organizations exhibit highest price sensitivity, while acute care systems prioritize validated efficacy claims over unit economics.
Supply Chain Analysis
Infrared sensor module supply rests on Taiwanese and South Korean semiconductor foundries, with valve assembly production concentrated in domestic captive manufacturing facilities. Stainless steel reservoir fabrication draws from domestic metalworking centers, while lithium-ion power management systems source from Japanese and South Korean battery specialists. Single-source vulnerability in Asian semiconductor foundries creates lead-time exposure for automatic dispenser assembly. Distribution runs through direct manufacturer agreements for multi-site healthcare networks, with retail and online channels serving residential replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US soap dispenser procurement functions as a cost-of-compliance story where FDA medical device surface guidance erects barrier-to-entry moats favoring manufacturers with validated antimicrobial coating documentation and third-party certification capabilities.
For Market Incumbents: Extend channel control through captive manufacturing of sensor modules and valve assemblies to insulate against Asian foundry lead-time vulnerability. Consolidate position by negotiating direct manufacturer agreements with Midwestern integrated delivery networks seeking standardized equipment footprints, while investing in EPA-registered coating formulations to defend against emerging competitors lacking FDA 510(k) pathway expertise. For New Entrants and Emerging Players: OSHA workplace sanitation standards in Texas and Florida open a window for sensor-system retrofit specialists targeting ambulatory surgical centers where outpatient facilities lag inpatient touch-free penetration. Prioritize lithium-ion rechargeable units with extended battery life for Austin tech campus expansions and Gulf Coast manufacturing plants, leveraging bulk-refill economics as entry wedge against entrenched janitorial service contract bundling. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated fabricators with captive sensor module production in domestic manufacturing corridors. Long-term viability hinges on acquisition targets possessing FDA-validated efficacy claims and direct contracting relationships with hospital systems. Watch California and New York extended producer responsibility legislation as inflection indicator for refillable system economics restructuring channel control.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Module Production | Captive manufacturing insulates Bradley Corporation-style players against Taiwanese foundry lead-time vulnerability. |
| FDA 510(k) Antimicrobial Coating Certification | Validated efficacy claims unlock acute care procurement in New York and Illinois hospital systems. |
| Direct Manufacturer Agreement with IDNs | Unbundling dispenser supply from janitorial contracts concentrates volume with compliant suppliers. |
| IoT-Enabled Consumption Tracking Platform | Cloud-connected dispensers converge with facility management software across California commercial portfolios. |
| Extended Producer Responsibility Compliance Investment | Refillable system design secures preference under pending California and New York packaging waste rules. |
Research Methodology
Document review covered FDA 510(k) filings, OSHA workplace sanitation standards, and California Title 24 building efficiency code provisions, complemented by interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and facility management procurement directors. Secondary validation drew from EPA registered product databases, hospital procurement contracts, and municipal green procurement policy documents in Los Angeles and San Francisco. Bottom-up demand modeling triangulated against top-down market sizing across product type, material, distribution channel, and end-use vertical segmentation.
Unit shipment and value projections across the analysis window reflect demand elasticity modeling for touch-free protocol mandates and bulk-refill economics. Segmentation dimensions included automatic versus manual actuation mechanisms, stainless steel versus ABS versus glass material tiers, direct sales versus retail versus online channel flows, and healthcare versus commercial versus educational versus residential end-use environments. CAGRs derived from regression analysis of historical retrofit cycles and regulatory compliance timelines, with lithium-ion battery cost curves and semiconductor foundry capacity utilization as key forecast inputs.
Caveats apply where FDA guidance revisions, OSHA enforcement intensity shifts, or state-level extended producer responsibility implementation delays could materially shift the outlook. Forecasts reflect assumptions regarding infection control mandate persistence and green procurement policy expansion without guarantee of regulatory continuity. A small set of named triggers—semiconductor supply disruptions, stainless steel price volatility, and ambulatory surgical center consolidation patterns—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Cookware Market
Household Items
Brush Cover Market
Household Items
Multi Pocket Holders Market
Household Items
Floor-Standing Integrated Smart Toilet Market
Household Items
Insulated Tumblers Market
Household Items
Flushable Wipes Market
Household Items
Germany Induction Hobs Market
Household Items
North America Water Purifier Market
Household Items
Smart Fork Market
Household Items
Air Freshener Market
Household Items
US Air Purifier Market
Household Items
Washing Capsules Market
Household Items
Dosage Spoon Market
Household Items
Neck Pillows Market
Household Items
Plastic Carafe Market
Household Items
Waterless Aroma Diffuser Market