
 Non-Stick Cookware Market | 2026-2036
Non-Stick Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Stick Cookware Market Analysis
PTFE-alternative coating chemistry is fragmenting the supplier base into ceramic, diamond-infused, and hybrid sol-gel camps. GreenPan anchors European demand through its Thermolon ceramic platform and direct-to-consumer channel control. T-fal leverages mass-market manufacturing scale across big-box retail in North America. HexClad competes via its laser-etched stainless steel hybrid design that bridges durability claims with non-stick performance.
Non-stick cookware denotes cooking vessels engineered with low-friction surface treatments—typically polytetrafluoroethylene, ceramic, or anodized oxide layers applied at 300-450°C—to prevent food adhesion and reduce oil requirements during thermal processing. Its primary commercial purpose spans residential meal preparation, commercial kitchen throughput optimization, and institutional foodservice consistency. Cookware sets command the broadest margin pools as bundled configurations lift average transaction values, while ceramic material formulations represent the fastest-growing segment as health-conscious buyers migrate from legacy fluoropolymer surfaces. Frying pans remain the volume anchor across all distribution channels.
The US FDA governs indirect food additive safety for coating migrations under 21 CFR 175.300, while the EPA monitors PFAS environmental discharge from manufacturing facilities. The EU REACH regulation restricts long-chain perfluorinated substances in imported cookware, forcing reformulation investments by brands serving European consumers. California's Proposition 65 warning requirements for PTFE decomposition products add a state-level compliance layer for US market access. Stakeholders must monitor evolving PFAS thresholds across jurisdictions to anticipate raw material substitution timelines and inventory obsolescence risks.
Market Dynamics
The EU REACH regulation restricting perfluorinated compounds is fragmenting coating chemistry into ceramic, sol-gel, and diamond-infused alternatives, forcing reformulation investments across the supplier base while creating first-mover advantages for compliant material platforms.
Growth Catalysts
- REACH-driven material substitution:The EU's long-chain perfluorinated substance restrictions accelerate ceramic coating adoption as brands reformulate to maintain European market access.
- Commercial kitchen throughput optimization:North American restaurant chains expand procurement of ceramic-coated lines to reduce oil costs and accelerate cleaning cycles during peak service periods.
- Sol-gel chemistry maturation:Advanced sand-derived coating formulations achieve durability parity with legacy PTFE surfaces at comparable production economics.
Market Restraints
- Fluoropolymer feedstock volatility:PTFE precursor availability constraints concentrate among Chinese chemical suppliers, exposing Western cookware manufacturers to input cost instability.
- Ceramic thermal shock limitations:Silica-based coatings exhibit micro-crack propagation under rapid temperature cycling, compressing product lifespans versus metal-infused alternatives.
- California Proposition 65 friction:State-level warning requirements for PTFE decomposition products create compliance complexity for brands distributing nationally within the United States.
Strategic Opportunities
- Tier-one China urban premiumization:Shanghai and Beijing households displace traditional wok purchases with bundled cookware sets, creating margin expansion for ceramic-platform brands.
- Direct-to-consumer channel control:Owned digital storefronts bypass wholesale margin compression while capturing first-party data on coating preference migration patterns.
- Hybrid laser-etched stainless steel convergence:Metal matrix composite surfaces combine searing performance with reduced-stick properties, opening professional chef segments historically resistant to pure ceramic.
Industry Challenges
- Coating application technician scarcity:Sol-gel and ceramic spray deposition requires specialized thermal control expertise that outpaces vocational training pipeline output.
- Multi-jurisdiction certification timelines:Simultaneous FDA indirect food additive reviews under 21 CFR 175.300 and EFSA migration testing create sequential rather than parallel approval pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Stick Cookware Market |
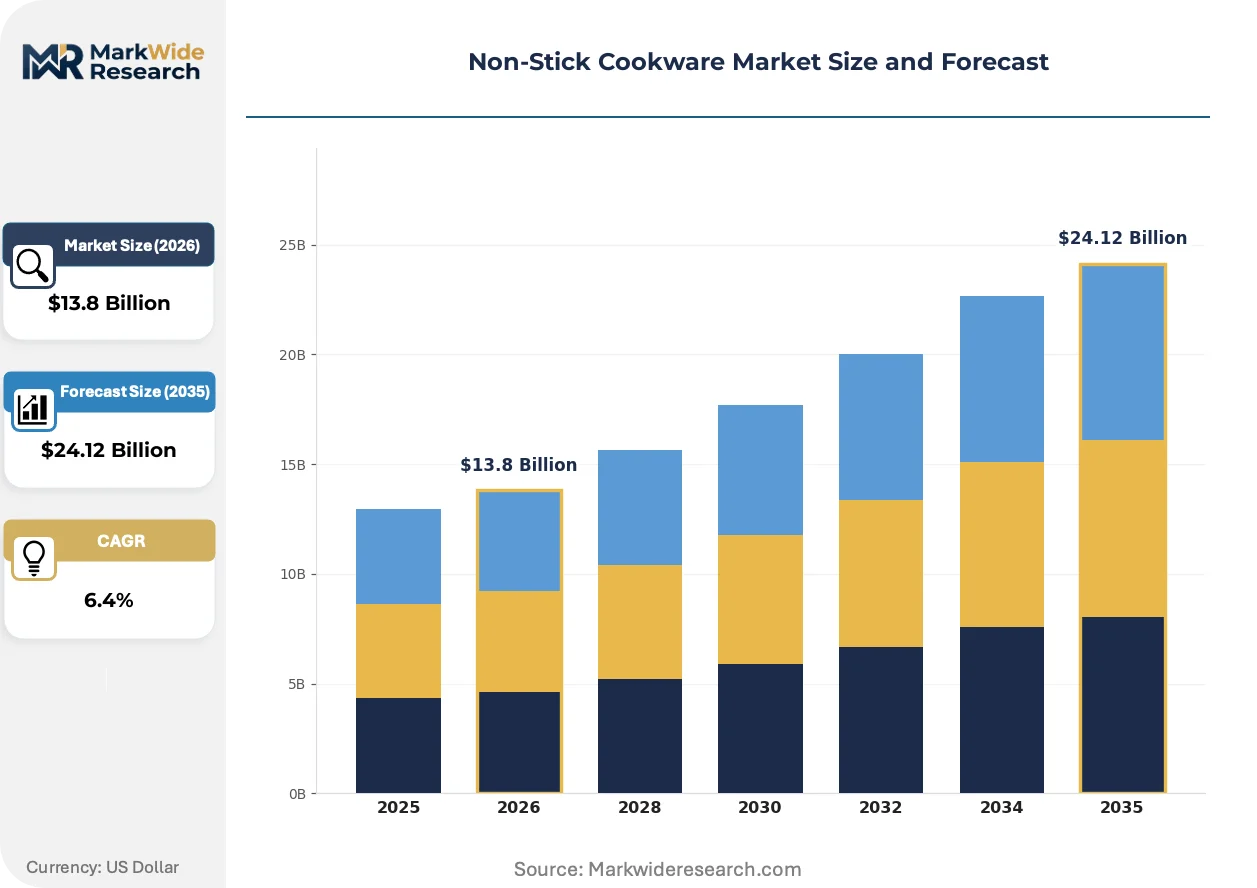
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frying Pans, Saucepans, Cookware Sets, Bakeware Material: Teflon, Ceramic, Anodized Aluminum, Stainless Steel End User: Residential, Commercial, Culinary Schools, Catering Services Distribution Channel: Retail Stores, Online Platforms, Wholesale, Direct Sales |
| Companies Covered | HexClad, Calphalon, Caraway, Made In, T-fal, All-Clad, GreenPan, OXO, Tramontina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Stick Cookware Market Emerging Trajectories
Digital simulation tools are compressing coating formulation development cycles while regulatory pressure on fluorinated chemistry accelerates alternative material validation. These forces reshape competitive positioning around material science capabilities rather than manufacturing scale alone.
Sol-gel ceramic coating technology is virtualizing traditional PTFE-dominated performance benchmarks. Residential buyers in China's coastal provinces adopt these surfaces fastest as health concerns migrate from niche to mainstream purchase criteria. The technology is virtualizing supplier competitive advantage from polymer chemistry expertise toward mineral processing and precision thermal deposition control.
REACH perfluorinated compound restrictions are forcing raw material substitution timelines that outpace inventory planning cycles. European import compliance now requires supply chain documentation extending to precursor chemical origins. Small and mid-sized brands serving EU consumers face disproportionate reformulation cost burdens versus integrated manufacturers with captive coating production.
Urban Chinese households are abandoning single-purpose wok purchases for modular cookware sets that accommodate diverse cooking techniques. E-commerce platforms displace traditional retail in tier-one cities, enabling direct brand relationships that bypass wholesale margin structures. This behavioral shift concentrates in Shanghai, Beijing, and Shenzhen, where premium ceramic-coated sets now dominate new household formation purchases.
Non-Stick Cookware Market Segmentation
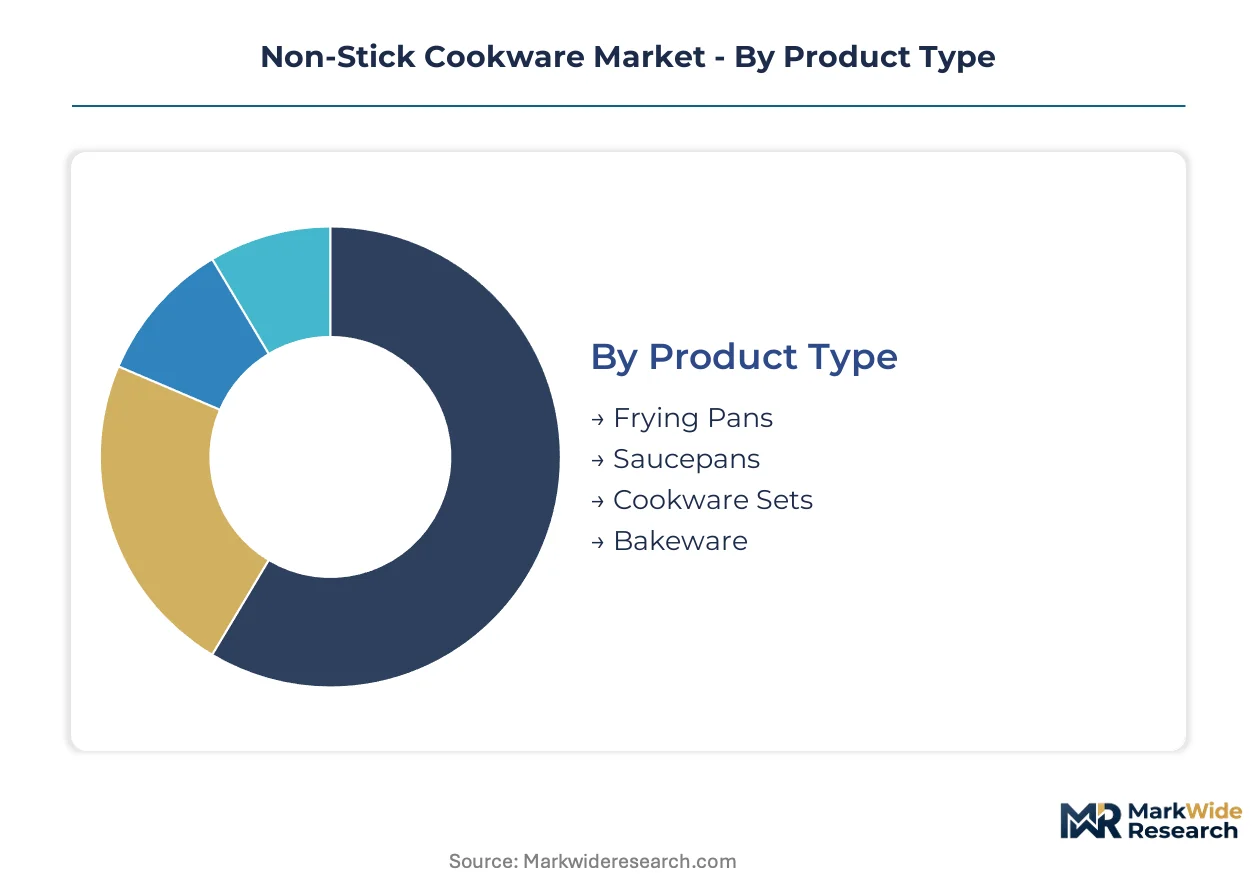
Non-stick cookware segmentation reveals distinct performance requirements across cooking surfaces, material chemistries, and procurement channels. Each dimension carries specific margin profiles and regulatory exposure that reshape supplier competitive positioning.
Product Type:
Home cooks and professional kitchens deploy specialized vessel geometries that trade off thermal mass, surface area, and storage efficiency against specific preparation tasks.
- Frying Pans:Flat-bottomed vessels with sloped sides engineered for rapid heat transfer and toss-motion cooking. Demand concentrates in North American households seeking single-piece versatility, though ceramic thermal shock limitations compress replacement cycles versus metal-infused alternatives.
- Cookware Sets:Bundled configurations spanning multiple vessel geometries and lid combinations. Shanghai and Beijing households displace traditional wok purchases with these modular systems, creating margin expansion for ceramic-platform brands as urban kitchen footprints shrink.
- Saucepans:Medium-depth vessels with vertical walls optimized for liquid reduction and sauce maintenance.
- Bakeware:Oven-rated sheet pans, loaf molds, and cake forms with release-optimized coatings.
The dominant share belongs to Frying Pans, while Cookware Sets is closing the gap fastest.
Material:
Surface chemistry selection now hinges on regulatory compliance timelines rather than pure performance benchmarks, fragmenting supplier capabilities across polymer, mineral, and metallic deposition expertise.
- Ceramic:Sol-gel silica-based coatings derived from sand precursors and applied through precision thermal deposition. Advanced formulations achieve durability parity with legacy PTFE at comparable production economics, with REACH-driven substitution accelerating European adoption.
- Teflon:Polytetrafluoroethylene fluoropolymer coatings applied at 300-450°C. PTFE precursor availability concentrates among Chinese chemical suppliers, exposing Western manufacturers to input cost instability and California Proposition 65 warning complexity.
- Anodized Aluminum:Electrochemically thickened oxide layers providing hardness without applied coatings.
- Stainless Steel:Laser-etched or composite metal matrix surfaces combining searing performance with reduced-stick properties.
Ceramic coatings are expanding most quickly, though Teflon retains volume leadership in price-sensitive segments.
End User:
Procurement authority and performance requirements diverge sharply between individual consumers and institutional foodservice operators.
- Residential:Individual household purchasers prioritizing health perceptions and aesthetic coordination. E-commerce platforms in China's tier-one cities enable direct brand relationships that bypass wholesale margin structures.
- Commercial:Restaurant chain procurement teams optimizing for throughput and total cost of ownership. North American operators expand ceramic-coated line purchases to reduce oil costs and accelerate cleaning cycles during peak service periods.
- Culinary Schools:Training institutions requiring durable surfaces for high-frequency student use.
- Catering Services:Mobile and event-based foodservice operators balancing portability with performance consistency.
Residential purchases dominate transaction volume, while Commercial buyers command the steepest expansion trajectory through chain-level standardization.
Distribution Channel:
Channel selection determines margin capture, customer data ownership, and inventory risk allocation between manufacturers and intermediaries.
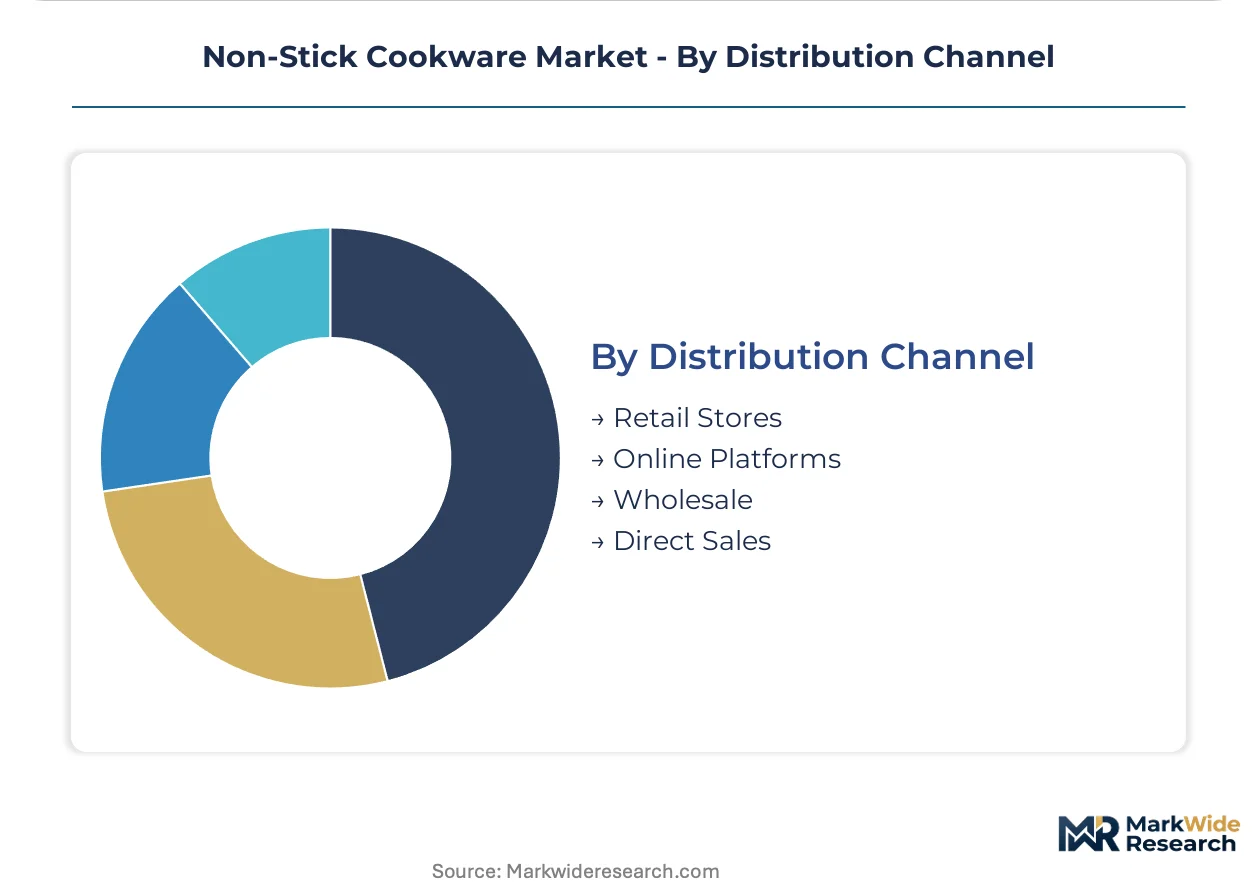
- Online Platforms:Digital marketplaces and owned direct-to-consumer storefronts. First-party data on coating preference migration patterns enables rapid formulation pivots, with channel control bypassing wholesale margin compression.
- Retail Stores:Big-box and specialty kitchenware outlets. T-fal leverages mass-market manufacturing scale across this channel in North America.
- Wholesale:Distributor-mediated bulk procurement for institutional and commercial accounts.
- Direct Sales:Manufacturer-owned sales forces serving large commercial accounts.
Online Platforms are gaining share fastest, though Retail Stores retain dominance in physical product evaluation and immediate fulfillment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers dominate non-stick cookware export flows into North American and European retail channels, with coastal production clusters supplying reformulation-ready ceramic coatings ahead of tightening perfluorinated compound restrictions.
United States
Restaurant chains drive commercial procurement of ceramic-coated lines to reduce oil costs and accelerate cleaning cycles. The FDA governs indirect food additive safety under 21 CFR 175.300, while California's Proposition 65 imposes warning requirements for PTFE decomposition products. Mass-market retail concentration in the Midwest and Southeast sustains high-volume distribution partnerships.
China
Urban households in Shanghai and Beijing displace traditional wok purchases with premium bundled cookware sets. The Ministry of Ecology and Environment enforces dual carbon goals that pressure coating facilities toward cleaner thermal deposition processes. Yangtze River Delta manufacturing clusters export sol-gel ceramic formulations to European buyers navigating REACH compliance.
Germany
Health-conscious consumers accelerate ceramic platform adoption as REACH restrictions eliminate legacy fluoropolymer alternatives. ECHA oversees long-chain perfluorinated substance limitations that force raw material substitution timelines. Industrial coating specialists in North Rhine-Westphalia develop sand-derived sol-gel formulations for pan-European supply.
France
Direct-to-consumer channel control enables ceramic-platform brands to bypass wholesale margin compression. ANSM monitors food contact material safety alongside EU-wide EFSA migration testing requirements. Paris-region e-commerce logistics clusters support rapid fulfillment of premium cookware sets across Western European markets.
Japan
Residential buyers prioritize durability-focused hybrid surfaces combining searing performance with reduced-stick properties. METI promotes advanced material standards through JIS certification frameworks. Osaka-based industrial design studios refine laser-etched metal matrix composites for professional chef segments.
Non-Stick Cookware Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Mass-market scale manufacturers anchor big-box retail distribution, while direct-to-consumer platforms capture first-party data on coating preference migration. Three archetypes dominate: ceramic-platform pure-plays, hybrid metal-matrix innovators, and legacy fluoropolymer defenders. Competitive moves concentrate on M&A for coating chemistry capabilities and geographic expansion into Chinese tier-one cities.
Among premium ceramic specialists, GreenPan and Caraway exemplify direct-to-consumer archetypes that bypass traditional wholesale structures. T-fal occupies a position within mass-market scale manufacturing, leveraging retail channel density across North American big-box distribution. HexClad represents the hybrid convergence tier, bridging professional durability claims with residential non-stick performance expectations.
| Leading Market Players |
|---|
| HexClad |
| Calphalon |
| Caraway |
| Made In |
| T-fal |
| All-Clad |
| GreenPan |
| OXO |
| Tramontina |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta port congestion oscillates between Shanghai and Ningbo terminals, amplifying inventory carrying costs for ceramic-coating manufacturers while compressing margins on economy-grade PTFE imports destined for North American big-box retail. This logistics friction stratifies pricing power: integrated producers with captive coating facilities absorb freight volatility better than import-dependent brands, widening the spread between premium ceramic sets and commodity frying pans.
Pricing Analysis
Next-generation sol-gel ceramic coatings command a 40-60% premium over legacy PTFE equivalents, while prior-generation anodized aluminum occupies a narrowing mid-tier. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—REACH-compliant formulations fetch higher realizations than California Proposition 65-tagged PTFE imports. Cost compression in the economy tier is intensifying because Chinese precursor suppliers concentrate pricing power. Residential buyers in China's tier-one cities show lowest price sensitivity; North American mass-market consumers exhibit highest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for Western cookware brands. Manufacturing concentrates in China, Germany, and Vietnam, with coating chemistry R&D anchored in North Rhine-Westphalia industrial clusters. Raw material sourcing draws from fluoropolymer precursor suppliers in Zhejiang Province, sand-derived silica deposits in Northern Europe, and laser-etching equipment fabricators in Japan. Single-source vulnerability concentrates in PTFE resin supply. Distribution runs through e-commerce platforms, big-box retail partnerships, and commercial foodservice distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against sand-derived sol-gel ceramics displacing legacy fluoropolymer market share. The imperative is reformulation speed: brands slow to certify REACH-compliant coatings risk inventory obsolescence as European import thresholds tighten.
For Market Incumbents: Pre-empt coating chemistry obsolescence by accelerating EFSA migration testing for sol-gel formulations ahead of REACH enforcement waves. Backward integration into ceramic spray deposition facilities in Yangtze River Delta clusters secures supply continuity against precursor export restrictions. Defensive patent filings around thermal shock-resistant silica matrices will raise rival reformulation costs. For New Entrants and Emerging Players: Mid-market commercial kitchen procurement in North American fast-casual chains represents the most penetrable entry point, as these buyers prioritize total cost of ownership over brand heritage. Shanghai and Beijing direct-to-consumer channels offer second white-space opportunity, bypassing wholesale margin compression through owned digital storefronts. Go-to-market angle: lead with chef-validated durability claims backed by professional kitchen trial programs rather than residential health messaging. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized coating chemistry divisions lacking consumer brand architecture. Long-term viability hinges on regulatory compliance agility rather than manufacturing scale alone. Signal to watch: ECHA guidance documents on perfluorinated substance thresholds, which will trigger accelerated M&A for compliant coating capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Certification | European market access now requires documented precursor chemical origins through ECHA oversight. |
| Direct-to-Consumer Channel Launch | Owned digital storefronts bypass wholesale margin compression while capturing first-party coating preference data. |
| Sol-Gel Formulation R&D Partnership | Sand-derived ceramic platforms achieve durability parity with PTFE at comparable production economics. |
| Commercial Kitchen Trial Programs | Professional chef validation opens segments historically resistant to pure ceramic surfaces. |
| Yangtze River Delta Manufacturing Footprint | Coastal production clusters export reformulation-ready coatings ahead of perfluorinated restrictions. |
Methodological Framework
The analysis maps ceramic-coating chemistry platforms, PTFE-alternative formulations, and hybrid metal-matrix surfaces, each validated through coating application technicians, commercial procurement directors at restaurant chains, and regulatory affairs specialists at cookware brands. Primary interviews with these stakeholders combined with secondary validation from FDA 21 CFR 175.300 filings, ECHA REACH substance restriction updates, and Chinese customs export data. Bottom-up vessel shipment estimates triangulated against top-down retail channel revenue assessments.
Assumption sets held regulatory enforcement timelines and raw material substitution curves fixed while varying e-commerce penetration rates and commercial kitchen standardization intensity across the projection horizon. The analytical framework modeled segmentation across material chemistry, product type, end-user procurement authority, and distribution channel control. CAGRs derived from regression analysis of historical price-volume relationships and forward-looking replacement cycle compression. Industry-specific inputs included thermal deposition equipment capacity utilization and REACH-driven reformulation investment schedules.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending, freight rate volatility, or fluoropolymer feedstock availability would shift the trajectory. Forecasts reflect documented assumptions on regulatory compliance timelines and ceramic coating durability improvement curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Acrylic Aquarium Market
Household Items
Shower Heads and Systems Market
Household Items
Mexico Cookware Market
Household Items
Neck Pillows Market
Household Items
Smart Memory Foam Market
Household Items
Insulated Tumblers Market
Household Items
Germany Digital Showers Market
Household Items
Mosquito Trap Market
Household Items
Global Ceramic Tableware Market
Household Items
Shoe Shine Machine Market
Household Items
Portable Steam Cleaners Market
Household Items
Laundry Dryer Sheets and Bars Market
Household Items
Smart Bathtub Market
Household Items
Sanitary Metal Ware Market
Household Items
Cat Hair Remover Market
Household Items
Laundry Detergent Sheets Market