
 UK Smokeless Indoor Grills Market | 2026-2036
UK Smokeless Indoor Grills Market Size, Share, and Industry Trends Forecast 2026-2036
UK Smokeless Indoor Grills Market Insights
The UK Green Deal's home efficiency mandates is shifting consumer preference toward low-emission kitchen appliances that reduce ventilation retrofit costs. George Foreman dominates the value-tier segment through its entrenched retail shelf presence across British supermarkets. Philips differentiates through premium infrared technology platforms that command higher price points in London and Edinburgh. De'Longhi Group anchors the mid-market with multi-function configurations that integrate grilling with air-frying capabilities.
Smokeless indoor grills are closed-plate electric cooking appliances engineered with embedded fan-driven filtration or infrared radiant elements that operate below smoke-ignition thresholds for proteins, typically rated between 1,200 and 1,800 watts for UK 230-volt circuits. Their primary commercial purpose is to replicate char-grilled flavour profiles within residential or commercial kitchens lacking external ventilation infrastructure. Electric product types occupy the largest installed base due to lower unit economics and simpler maintenance protocols, while infrared configurations represent the fastest-expanding margin pool as energy-efficiency consciousness hardens among British consumers. Household end users generate the dominant revenue share, though restaurant and food truck segments are deepening adoption as street-food operators seek compliant indoor production capacity.
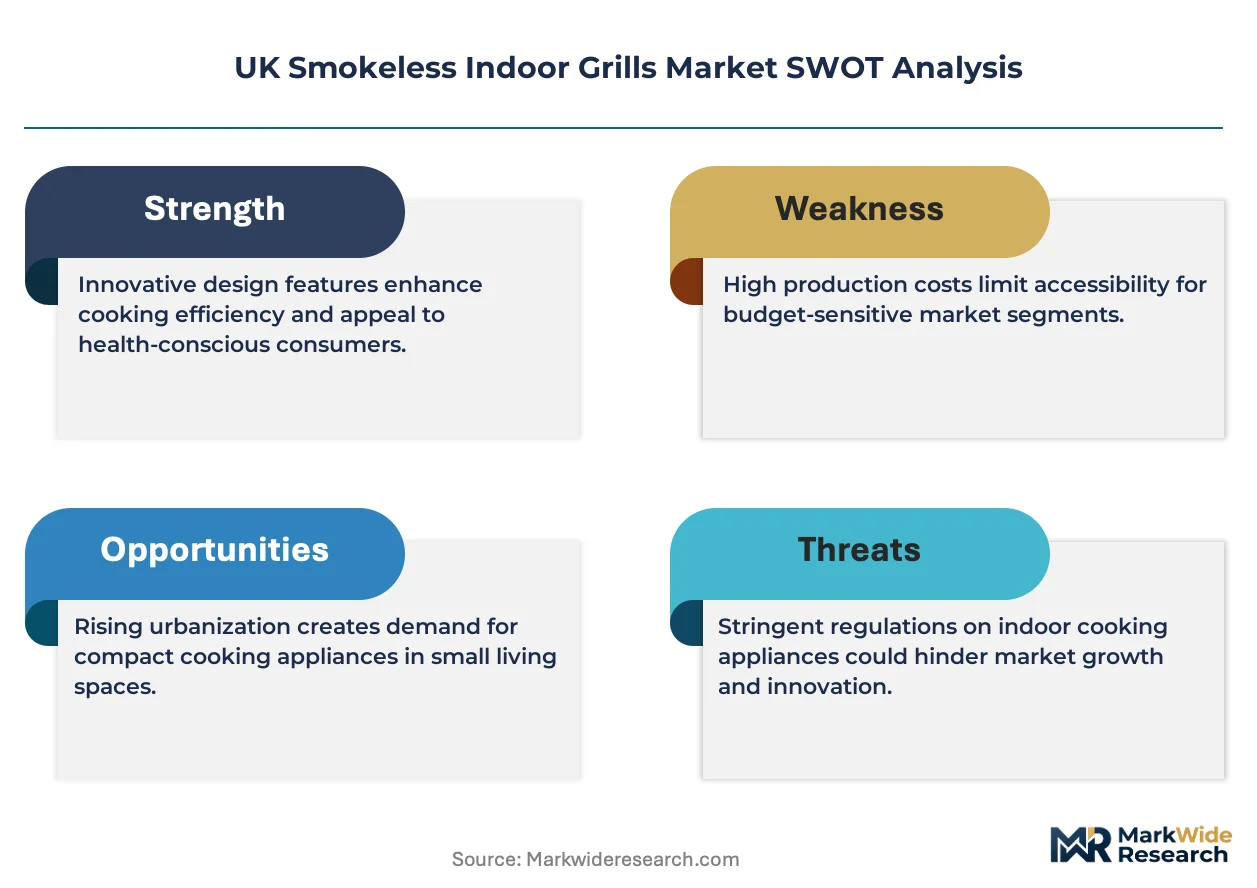
BEIS product safety standards and BSI electrical certification requirements govern minimum performance thresholds and thermal safety cut-offs for UK-market appliances, while local authority enforcement of Part F building regulations constrains installation options in new-build flats without external ducting. The Food Standards Agency's guidance on acrylamide reduction indirectly steers manufacturers toward precision temperature control as a product differentiation vector. Stakeholders must monitor how OfGEM's evolving electricity tariff structures reshape operating-cost comparisons between resistive and infrared heating technologies.
Market Dynamics
Part F ventilation regulations under UK Building Standards are compressing traditional outdoor grilling options in new-build flats, redirecting cooking demand toward engineered smoke-extraction appliances that operate within sealed kitchen environments.
Growth Catalysts
- Urban Flat Density:Greater London's high-rise residential stock creates sustained demand for compact cooking appliances that function without external ducting. Young professionals in studio apartments drive replacement cycles.
- BEIS Product Safety Standards:Certification requirements for thermal cut-offs and electrical safety create consumer confidence barriers that favor established compliant manufacturers over unregulated imports.
- Infrared Radiant Elements:Energy-efficient heating technology reduces operating costs under OfGEM tariff structures, accelerating adoption among cost-conscious households in the Southeast corridor.
Market Restraints
- Copper and Aluminum Input Costs:Resistive heating element manufacturing faces commodity price volatility that compresses margin structures for value-tier producers.
- Technical Smoke Threshold Limitations:Fan-driven filtration systems struggle with fatty protein loads above 180°C, constraining authentic char-grill replication and limiting chef-grade applications.
- Substitution by Air Fryers:Multi-function countertop appliances with crisping capabilities capture overlapping use cases among space-constrained consumers seeking single-appliance solutions.
Strategic Opportunities
- Scottish Urban Expansion:Edinburgh and Glasgow flat conversions present underpenetrated demand for premium infrared configurations as housing stock modernizes.
- Commercial Kitchen Compliance:Street-food operators and cloud kitchens require Part F-compliant production capacity for indoor grilling of halal and specialty proteins.
- UK Green Deal Integration:Low-emission appliance certification aligns with home efficiency retrofit incentives, creating specification pull from social housing providers.
Industry Challenges
- Thermal Engineering Talent Scarcity:Fan-driven filtration and infrared calibration expertise concentrates among a narrow pool of appliance engineers, constraining R&D velocity.
- BSI Certification Timelines:Extended electrical safety testing protocols delay product launches by 8-14 months, compressing competitive windows against faster-certifying substitutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Smokeless Indoor Grills Market |
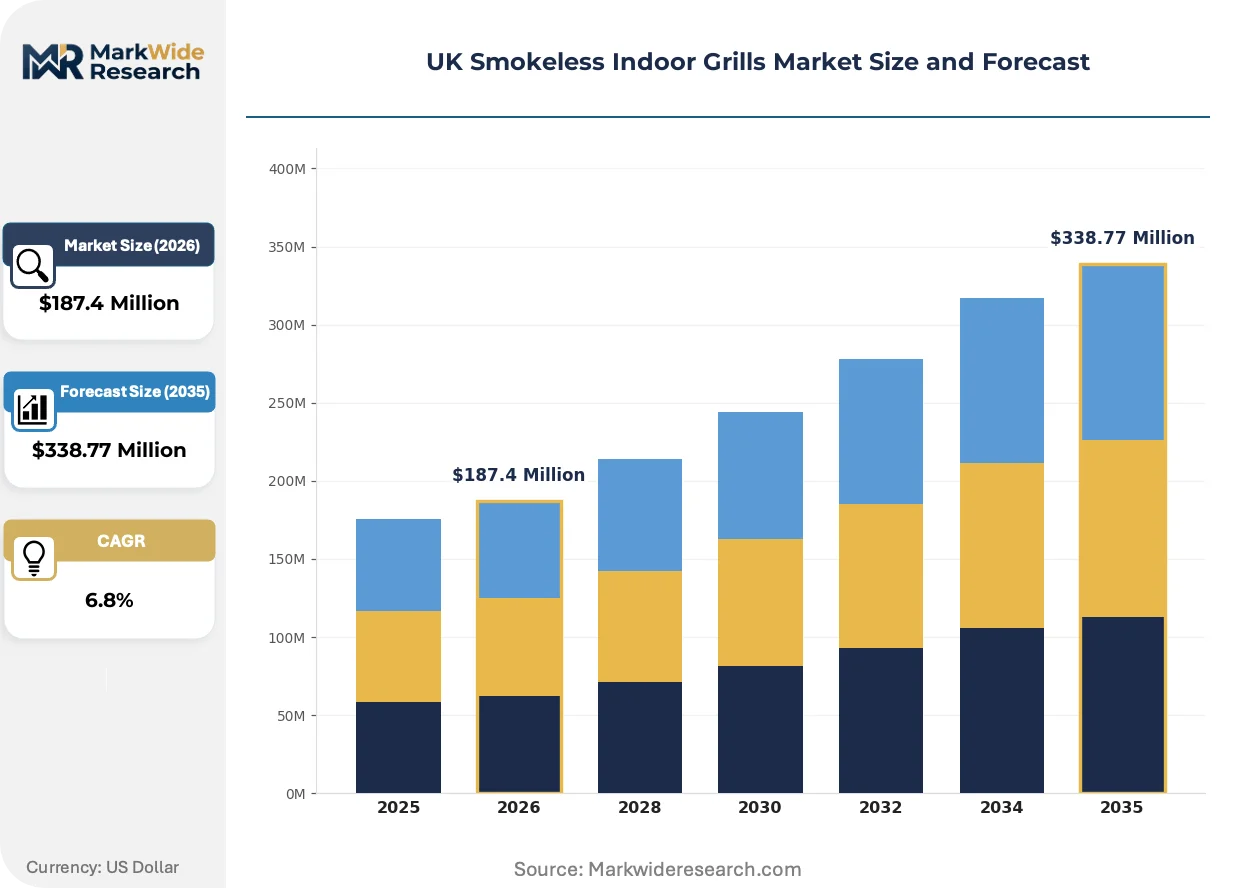
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Infrared, Charcoal, Multi-function End User: Households, Restaurants, Food Trucks, Catering Services Technology: Non-stick Coating, Smokeless Technology, Induction Heating, Temperature Control Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | George Foreman, Philips, Geepas, SEVERIN, Tefal, LionsHome, Char-Broil, De'Longhi Group, CostWay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Smokeless Indoor Grills Market Trends and Innovations
Smoke-extraction engineering and precision temperature control are converging to redefine product performance benchmarks, with manufacturers racing to satisfy both regulatory compliance and flavor authenticity demands from sophisticated home cooks.
Fan-driven filtration with activated carbon layers is absorbing grease particulates and odor molecules at the point of generation, enabling closed-plate operation below visible smoke thresholds. Urban apartment dwellers in Manchester and Birmingham are adopting these systems fastest as lease restrictions on balcony grilling tighten. This absorption capability is compressing the performance gap between indoor electric units and traditional outdoor charcoal methods.
Part F building regulations are mandating mechanical ventilation with heat recovery in new-build flats without external ducting, disqualifying conventional extractor hoods and privileging self-contained smokeless appliances. Developers in the Southeast corridor are specifying certified indoor grills as standard fitments to avoid costly centralized ventilation retrofits. Housebuilders are responding by bundling mid-market multi-function units into kitchen packages.
Specialist kitchen retailers are losing share to direct-to-consumer channels as buyers research infrared technology specifications online before purchase. Independent cookware shops in London and Edinburgh are pivoting toward experiential demonstration models to justify premium price positions. This channel rotation is most pronounced among millennial buyers seeking warranty transparency and subscription filter replacement services.
UK Smokeless Indoor Grills Market Segmentation
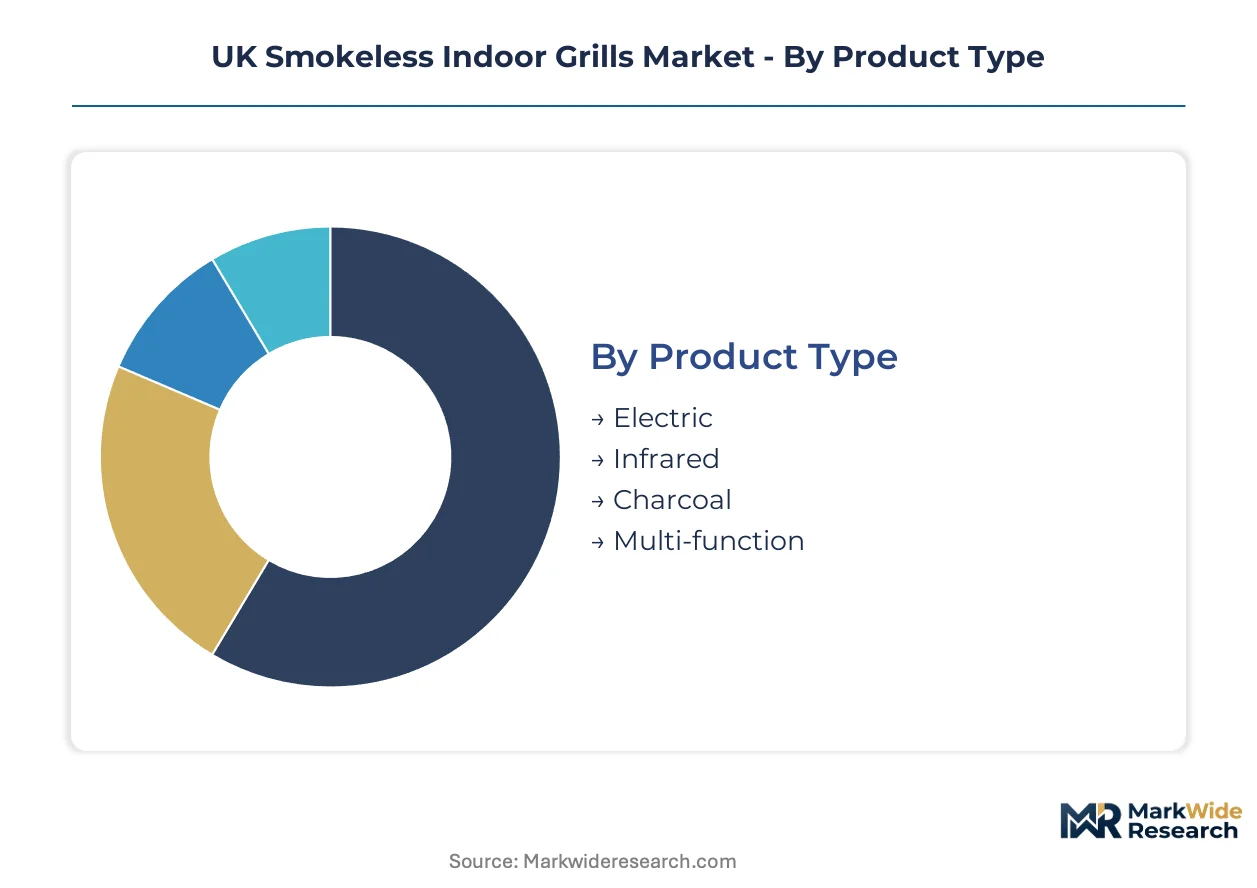
Smokeless indoor grill purchasing decisions in the UK pivot on ventilation compliance, energy economics, and kitchen footprint constraints. Segmentation reveals how distinct buyer profiles prioritize technical specifications differently across product architectures and procurement channels.
Product Type:
Purchase volume splits along the trade-off between unit affordability and operating efficiency under OfGEM tariff structures.
- Electric:Resistive heating elements rated 1,200–1,800 watts dominate installed base economics through lower acquisition costs and minimal maintenance protocols. Greater London studio apartments sustain replacement cycles as young professionals prioritize upfront accessibility over lifetime energy expenditure.
- Infrared:Radiant ceramic elements operate below smoke-ignition thresholds while reducing electricity draw by 30–40% versus resistive alternatives. Edinburgh and Glasgow flat conversions are absorbing premium infrared configurations as Scottish housing stock modernizes and energy-efficiency consciousness hardens.
- Charcoal:Compact ceramic-housed units with active filtration layers replicate authentic char-grill flavor profiles for flavor-purists in suburban semis with limited balcony access.
- Multi-function:Integrated air-frying and grilling configurations capture space-constrained buyers seeking single-appliance solutions in Birmingham and Manchester high-rises.
Electric leads on scale; Infrared leads on momentum.
End User:
Application environment dictates smoke-extraction engineering requirements and duty-cycle durability specifications.
- Households:Residential buyers in the Southeast corridor generate dominant revenue share through year-round indoor cooking appliance purchases driven by Part F ventilation constraints in new-build flats without external ducting.
- Restaurants:Cloud kitchens and halal specialty operators in Greater London require Part F-compliant production capacity for indoor protein grilling, deepening commercial adoption as street-food segments professionalize.
- Food Trucks:Mobile operators face dual constraints of power supply limitations and enclosed cabin ventilation, favoring low-wattage infrared units with rapid heat-up profiles.
- Catering Services:Event-based providers prioritize portability and rapid deployment over precision temperature control, absorbing value-tier electric units for occasional-use scenarios.
Households anchor volume concentration; Restaurants are climbing the fastest.
Technology:
Surface engineering and thermal management specifications differentiate compliance-grade appliances from commodity imports.
- Non-stick Coating:Ceramic-titanium composite layers reduce protein adhesion and simplify cleaning protocols for time-constrained urban dwellers in Manchester and Leeds.
- Smokeless Technology:Fan-driven filtration with activated carbon absorption enables closed-plate operation below visible smoke thresholds, satisfying Part F requirements for sealed kitchen environments in Southeast corridor new-builds.
- Induction Heating:Electromagnetic coil systems deliver rapid thermal response and precise zone control, commanding premium positioning among serious home cooks in Edinburgh.
- Temperature Control:PID-regulated thermal cut-offs align with BEIS product safety standards and Food Standards Agency acrylamide reduction guidance, creating specification pull from social housing providers under UK Green Deal mandates.
Non-stick Coating holds installed base dominance; Temperature Control is gaining share fastest.
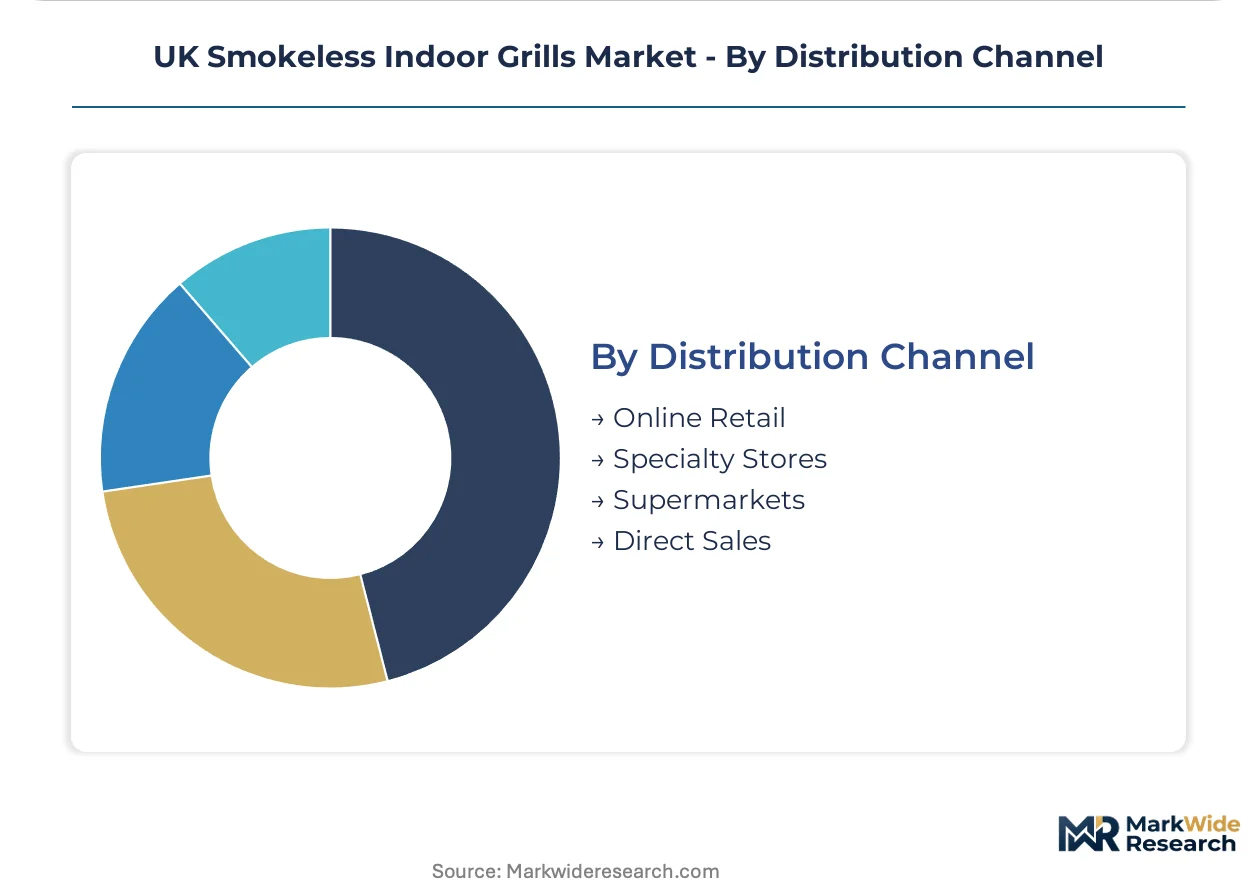
Distribution Channel:
Channel selection reflects buyer research behavior and warranty transparency preferences across demographic cohorts.
- Online Retail:Direct-to-consumer platforms capture millennial buyers researching infrared specifications and subscription filter replacement services before purchase, eroding specialist kitchen retailer share.
- Specialty Stores:Independent cookware shops in London and Edinburgh pivot toward experiential demonstration models to justify premium price positions and technical consultation value.
- Supermarkets:Value-tier electric units maintain entrenched shelf presence across British grocery multiples, serving impulse replacement demand and gift purchase occasions.
- Direct Sales:Housebuilders in the Southeast corridor bundle mid-market multi-function units into kitchen packages as standard fitments, avoiding costly centralized ventilation retrofits.
Supermarkets retain volume leadership; Online Retail shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smokeless indoor grill technology first achieved commercial scale in Japanese urban apartments during the 1990s, where external ventilation restrictions created early demand for closed-plate electric cooking. British adoption accelerated after 2010 as Part F regulations tightened across new-build residential stock.
Greater London
High-rise residential density sustains the UK's largest concentration of indoor grill purchases. Young professionals in studio apartments drive replacement cycles for compact electric units. BEIS product safety standards favor established compliant manufacturers over unregulated imports. Tower Hamlets and Southwark house the densest clusters of flat-dwelling buyers seeking Part F-compliant cooking solutions.
Southeast Corridor
Energy-efficiency consciousness hardens fastest in Brighton, Reading, and Milton Keynes as OfGEM tariff structures reshape operating-cost calculations. Infrared configurations command premium positioning among cost-conscious households prioritizing lifetime energy expenditure. Housebuilders in Kent and Surrey bundle mid-market multi-function units into kitchen packages as standard fitments.
Scotland
Edinburgh and Glasgow flat conversions present underpenetrated demand for premium infrared configurations as Scottish housing stock modernizes. The Scottish Government's energy efficiency programs indirectly steer specification toward low-emission appliances. Leith and Glasgow's West End absorb the fastest-adopting cohort of infrared buyers outside London.
Midlands
Birmingham and Manchester high-rises sustain demand for space-constrained multi-function appliances combining grilling with air-frying capabilities. Lease restrictions on balcony grilling tighten fastest in Manchester city centre. The West Midlands absorbs value-tier electric units through entrenched supermarket retail presence.
North England
Leeds and Newcastle studio apartment stock generates replacement demand for ceramic-titanium non-stick configurations. Time-constrained urban dwellers prioritize simplified cleaning protocols. Yorkshire's independent cookware retailers pivot toward experiential demonstration models to justify premium price positions.
UK Smokeless Indoor Grills Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and certification compliance dimensions. The vendor base stratifies into three tiers: value-tier electric specialists, mid-market multi-function integrators, and premium infrared technology platforms. Two dominant competitive moves are reshaping positioning: portfolio diversification into air-frying convergence and direct-to-consumer channel expansion eroding specialist retailer share.
Within the value-tier segment, George Foreman anchors entrenched retail shelf presence across British supermarkets. Philips and De'Longhi Group occupy positions on the premium-to-mid-market spectrum, with the former representing infrared technology leadership and the latter exemplifying multi-function configuration integration. These three entities collectively illustrate how compliance with BEIS standards and Part F alignment serve as competitive moats against unregulated import competition.
| Leading Market Players |
|---|
| George Foreman |
| Philips |
| Geepas |
| SEVERIN |
| Tefal |
| LionsHome |
| Char-Broil |
| De'Longhi Group |
| CostWay |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap appliance specialists anchor UK manufacturing capacity, translating concentrated ownership into disciplined pricing power across infrared and resistive heating tiers. Their captive control over thermal engineering talent pools insulates premium configurations from commodity margin erosion while value-tier producers absorb copper and aluminum volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Philips infrared platforms from De'Longhi multi-function units from George Foreman value-tier electric models. Price differentiation rests on BEIS certification grade and after-sales filter subscription bundling. Pricing pressure stems from substitution by multi-function air fryers capturing overlapping use cases. First-time flat buyers in Greater London exhibit highest price sensitivity; Edinburgh premium buyers prioritize lifetime energy economics over upfront cost.
Supply Chain Analysis
Direct-to-consumer channels handle millennial buyer demand for specification transparency and warranty clarity, eroding specialist kitchen retailer share. Component sourcing draws from China for resistive heating elements, Germany for precision temperature sensors, and Taiwan for PID control chipsets. Supply chain risk centers on single-source vulnerability for infrared ceramic substrates. Distribution runs through supermarket multiples for impulse replacement, online platforms for research-heavy purchases, and housebuilder bundling for new-build specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK smokeless indoor grills market offers margin expansion through infrared technology adoption and filter subscription bundling, with energy-efficiency consciousness reducing price elasticity among Scottish and Southeast corridor buyers.
For Market Incumbents: Acquire thermal engineering talent pools to defend proprietary calibration expertise against fan-driven filtration commoditization. Secure backward integration into infrared ceramic substrate supply to offset single-source vulnerability. Deepen housebuilder direct sales relationships in Kent and Surrey to lock in new-build specification share before Part F compliance mandates harden. For New Entrants and Emerging Players: Direct-to-consumer demonstration content on TikTok and Instagram Reels bypasses entrenched supermarket shelf dominance. Target Edinburgh and Glasgow flat conversions for premium infrared penetration where housing stock modernization outpaces established brand presence. Position around BEIS certification speed as competitive wedge against incumbents facing 8-14 month BSI testing timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among value-tier electric specialists facing copper cost compression and air fryer substitution. Long-term viability hinges on infrared technology transition completion and filter subscription revenue attachment. Monitor OfGEM tariff restructuring announcements as inflection signal for operating cost comparison shifts between resistive and radiant heating technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Infrared Technology Platform Migration | Philips and premium specialists capture margin expansion as OfGEM tariffs reshape operating cost calculations. |
| Filter Subscription Service Launch | Direct-to-consumer channels secure recurring revenue attachment and reduce customer acquisition cost over replacement cycles. |
| Housebuilder Bundling Partnerships | Southeast corridor developers specify mid-market units as standard fitments to avoid centralized ventilation retrofits. |
| BSI Certification Fast-Track Investment | Reduced testing timelines compress competitive windows against slower-certifying substitutes and unregulated imports. |
| Scottish Urban Distribution Expansion | Edinburgh and Glasgow flat conversions present underpenetrated demand as Scottish housing stock modernizes. |
Research Methodology
Coverage spans Greater London, Southeast corridor, Scotland, Midlands, and North England, with primary inputs from each region combined with secondary validation. Appliance engineering directors, housebuilder procurement managers, independent cookware retailer owners, and social housing specification officers contributed structured interviews. Secondary sources include BEIS product safety filings, BSI certification records, OfGEM tariff documentation, and local authority Part F enforcement guidance. Bottom-up unit economics triangulate against top-down addressable market sizing.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions model product type, end user, technology specification, and distribution channel. CAGRs derive from installed base replacement cycles, new-build housing completion trajectories, and energy-efficiency adoption curves. Infrared technology penetration rates and filter subscription attachment ratios serve as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for induction heating would alter the outlook if electromagnetic coil costs compress faster than projected. Forecasts reflect assumptions about Part F regulatory enforcement intensity and OfGEM tariff restructuring timing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Food Truck Services Market
Food Service
Restaurant Griddle Market
Food Service
Saudi Arabia Cloud Kitchen Market
Food Service
Food and Grocery Retail Market
Food Service
Spain Food Service Market
Food Service
Vietnam Online Food Delivery Market
Food Service
North America Food Service Market
Food Service
Food Away from Home Market
Food Service
United Kingdom Barbeque Grill Market
Food Service
Foodservice Coffee Market
Food Service
Europe Online Grocery Delivery Market
Food Service
Restaurant Takeout Market
Food Service
United States Quick Service Restaurants Market
Food Service
Air Fryer Market
Food Service
Restaurants in Belgium Market
Food Service
Light Meal Market