
 Soybean Seed Treatment Market | 2026-2036
Soybean Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Soybean Seed Treatment Market Insights
Consolidation among large-scale farming cooperatives in South America is expanding the addressable base for premium treatment formulations. BASF SE leverages its fungicide pipeline to anchor supply relationships with these consolidated buyers. Syngenta Group competes through biological platform specialization, while Bayer CropScience sustains scale advantages in conventional insecticide seed treatments.
Soybean seed treatment encompasses chemical and biological formulations applied to seeds prior to planting, with active ingredient loadings typically ranging from 0.5 to 5.0 grams per kilogram of seed, designed to protect germinating embryos from soil-borne pathogens and early-season pests. The primary commercial purpose centers on reducing replant risk and optimizing stand establishment in high-value soybean production systems. Fungicides dominate current value pools across conventional farming regions, while biologicals represent the fastest-expanding category as residue-conscious buyers in European import markets tighten procurement specifications. Application segmentation shows field crops absorbing the majority of volume, though organic farming channels command disproportionate margin contributions due to limited supplier competition and certification complexity.
The EPA governs active ingredient registration and tolerance thresholds in the United States, while Brazil's national agricultural regulator enforces residue monitoring protocols that directly shape export-oriented treatment choices. REACH compliance in European destination markets further constrains formulation chemistry options for suppliers serving international grain traders. Stakeholders must monitor evolving biological efficacy standards and coordinate regulatory dossier investments across multiple jurisdictions to maintain market access.
Market Dynamics
Consolidation among South American farming cooperatives is compressing procurement timelines and favoring suppliers with integrated biological-chemical portfolios capable of meeting EU residue protocols.
Growth Catalysts
- EU Green Deal restrictions:Neonicotinoid phase-outs in European destination markets are accelerating biological seed treatment adoption among Brazilian export-oriented growers.
- Argentina's Pampas cooperatives:Consolidated procurement by large-scale farming operations is expanding volume commitments for premium fungicide-insecticide combination products.
- Biological efficacy validation:Improved field performance data for microbial inoculants is displacing conventional chemistry in early-season pest management protocols.
Market Restraints
- Active ingredient cost volatility:Petrochemical feedstock fluctuations compress margins for synthetic fungicide manufacturers serving price-sensitive Brazilian mid-scale farms.
- Supply concentration in formulated products:Three multinational suppliers control the majority of patented strobilurin and triazole chemistries, limiting bargaining power for regional distributors.
- Biological storage limitations:Temperature-sensitive microbial formulations require cold-chain infrastructure absent across Argentina's interior grain belt.
Strategic Opportunities
- Underpenetrated organic channels:Certified organic soybean acreage in Brazil's Mato Grosso expansion zones lacks sufficient biological treatment suppliers.
- Seed-coating equipment convergence:Integration of precision application systems with biological inoculant dosing is opening retrofit service revenue streams.
- REACH compliance services:European residue documentation requirements create advisory fee potential for laboratories serving Brazilian export cooperatives.
Industry Challenges
- Microbiologist talent scarcity:Formulation scientists with dual expertise in entomopathogenic fungi and seed physiology command premium compensation.
- Multi-jurisdiction dossier timelines:Simultaneous EPA, ANVISA, and ECHA registration processes extend product commercialization cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soybean Seed Treatment Market |
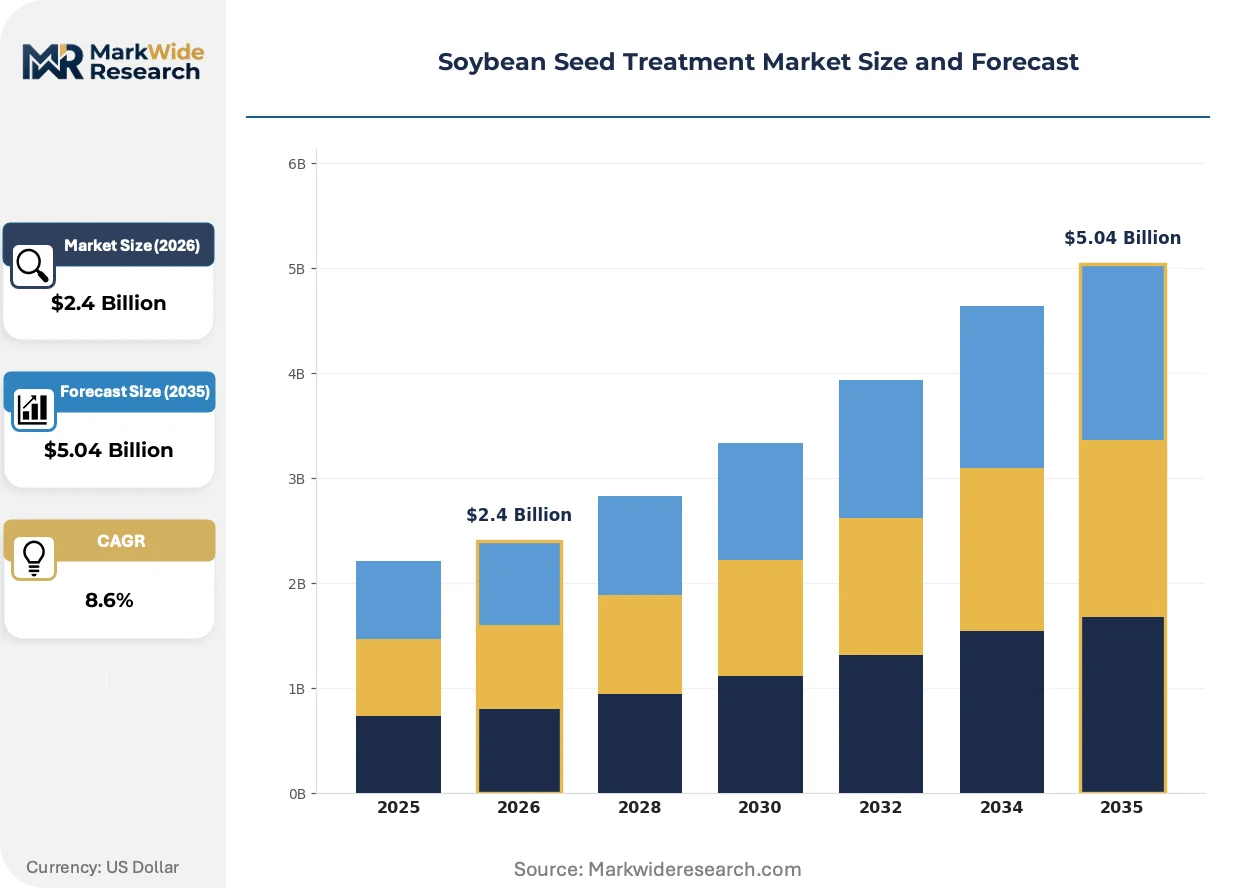
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.04 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fungicides, Insecticides, Biologicals, Growth Promoters Application: Field Crops, Row Crops, Organic Farming, Greenhouse End User: Farmers, Distributors, Agricultural Cooperatives, Research Institutions Distribution Channel: Online Retail, Offline Retail, B2B Sales, Direct Sales |
| Companies Covered | BASF SE, Syngenta Group, Bayer CropScience, Corteva Agriscience, UPL Limited, FMC Corporation, Nufarm Limited, ADAMA Ltd., Sumitomo Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soybean Seed Treatment Market Trends and Innovations
Biological seed treatment platforms are maturing from niche alternatives to core portfolio components, while regulatory fragmentation across export destination markets forces formulation complexity.
RNA interference-based pest suppression is decentralizing early-season insect management away from broad-spectrum neonicotinoid dependence. Argentine cooperatives in Buenos Aires province are piloting RNAi-coated seeds for soybean cyst nematode control. This technology is decentralizing chemical supplier influence toward biotechnology-specialized input providers capable of delivering trait-specific solutions.
REACH authorization timelines are compressing available chemistry options for suppliers serving EU grain traders. The European Chemicals Agency's substance evaluation backlog now exceeds 36 months for several triazole fungicides. Brazilian exporters are responding by accelerating biological platform investments to preempt future import restriction scenarios.
Cooperative procurement centralization is consolidating treatment decisions into fewer technical staff across South American grain belts. Individual farm managers in Rio Grande do Sul increasingly delegate seed treatment selection to centralized agronomy teams at cooperative headquarters. This pattern concentrates supplier relationship management into a smaller buyer pool with standardized technical specifications.
Soybean Seed Treatment Market Segmentation
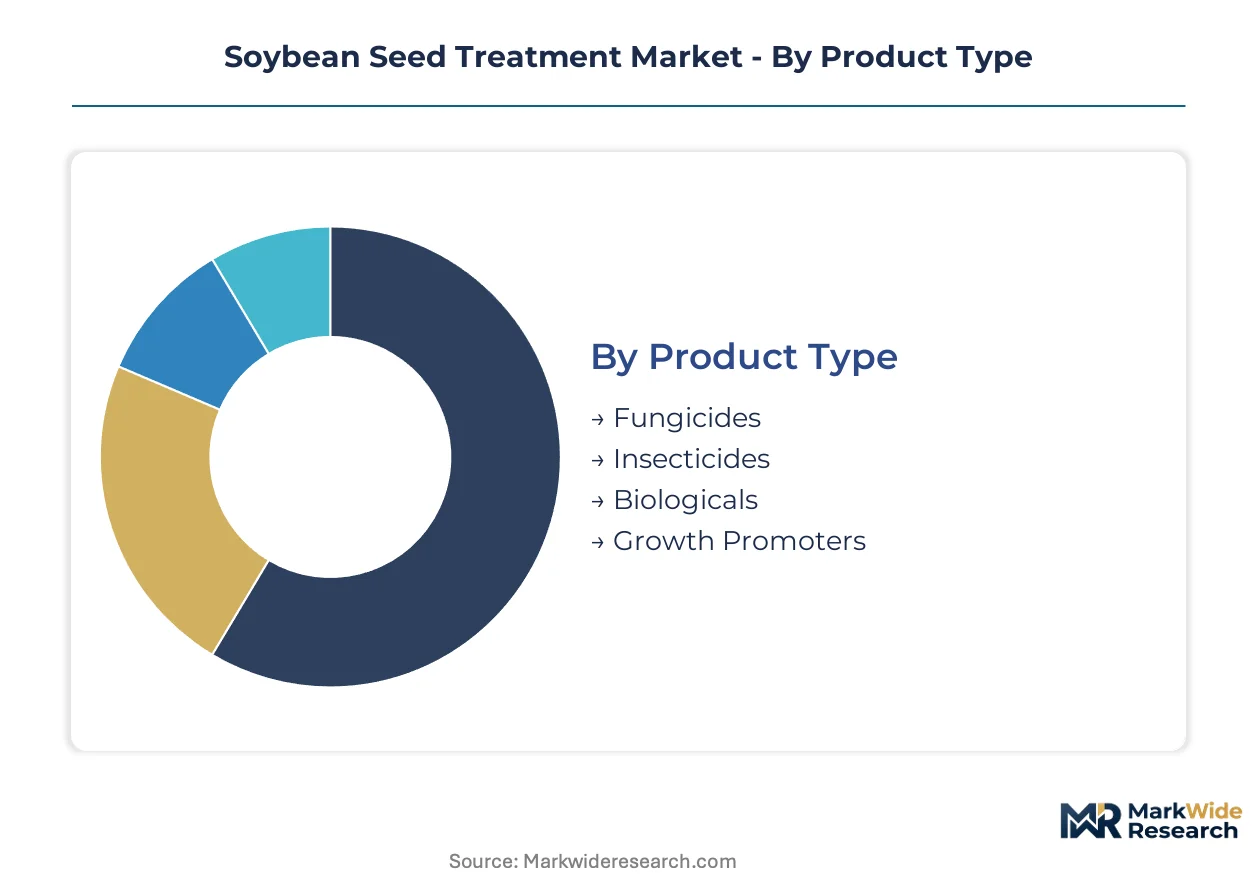
Soybean seed treatment segmentation reveals divergent capital requirements across formulation chemistries and distribution architectures. Treatment choices cascade through regulatory compliance costs, cold-chain infrastructure needs, and precision application equipment investments that reshape supplier economics.
Product Type:
Capital intensity peaks with biological manufacturing facilities requiring fermentation capacity and live-culture preservation systems, while chemical synthesis demands continuous-process reactor investments.
- Fungicides:Strobilurin and triazole chemistries dominate commercial soybean acres across Iowa and Illinois. EPA registration timelines and residue tolerance protocols in European destination markets concentrate procurement among export-oriented Brazilian cooperatives seeking dual-jurisdiction compliance.
- Insecticides:Neonicotinoid-based coatings face EU Green Deal phase-out pressures, accelerating replacement investments. Brazilian Mato Grosso operations are retrofitting treatment facilities to accommodate biological alternatives as ANVISA tightens export residue monitoring.
- Biologicals:Microbial inoculants and entomopathogenic fungi require refrigerated storage infrastructure absent across Argentina's interior grain belt.
- Growth Promoters:Plant hormone formulations and nutrient priming agents command premium positioning in high-input farming systems.
Most installed capacity flows through Fungicides. Expansion is steepest in Biologicals.
Application:
Volume concentration varies sharply by certification requirements and treatment protocol complexity, with organic channels demanding specialized supplier relationships.
- Field Crops:Conventional soybean acres across the US Corn Belt absorb the majority of fungicide-insecticide combination treatments. Illinois and Iowa farm operations prioritize stand establishment reliability through standardized coating protocols.
- Row Crops:Precision-planted soybean systems in Brazil's Rio Grande do Sul favor high-loading treatments calibrated to seed spacing density.
- Organic Farming:Certified organic acreage in Brazil's Mato Grosso expansion zones faces biological treatment supply constraints.
- Greenhouse:Controlled-environment soybean propagation for breeding programs requires ultra-low dose application systems.
Field Crops absorb the dominant treatment volume. Organic Farming channels command the highest margin premiums.
End User:
Procurement consolidation is compressing supplier relationship management into fewer technical decision-makers with standardized specifications.
- Farmers:Individual operators in Argentina's Pampas region increasingly delegate treatment selection to cooperative agronomy teams.
- Distributors:Regional input suppliers in Brazil's interior states face margin pressure from multinational direct sales expansion.
- Agricultural Cooperatives:Consolidated buyers in Buenos Aires province centralize seed treatment procurement for thousands of member hectares.
- Research Institutions:University breeding programs and government extension services pilot RNA interference and novel biological platforms.
Agricultural Cooperatives are capturing procurement volume share. Research Institutions drive technology validation pipelines.
Distribution Channel:
Channel economics reflect cold-chain requirements for biologicals and the technical advisory intensity of integrated treatment decisions.
- Online Retail:E-commerce platforms capture smaller-scale Brazilian farm orders for standard fungicide formulations.
- Offline Retail:Brick-and-mortar agrochemical dealers across the US Midwest maintain treatment application services.
- B2B Sales:Direct supplier relationships with Argentine cooperatives handle bulk formulation procurement and technical support.
- Direct Sales:Multinational suppliers bypass distributors for large-scale Brazilian farming operations with integrated agronomy programs.
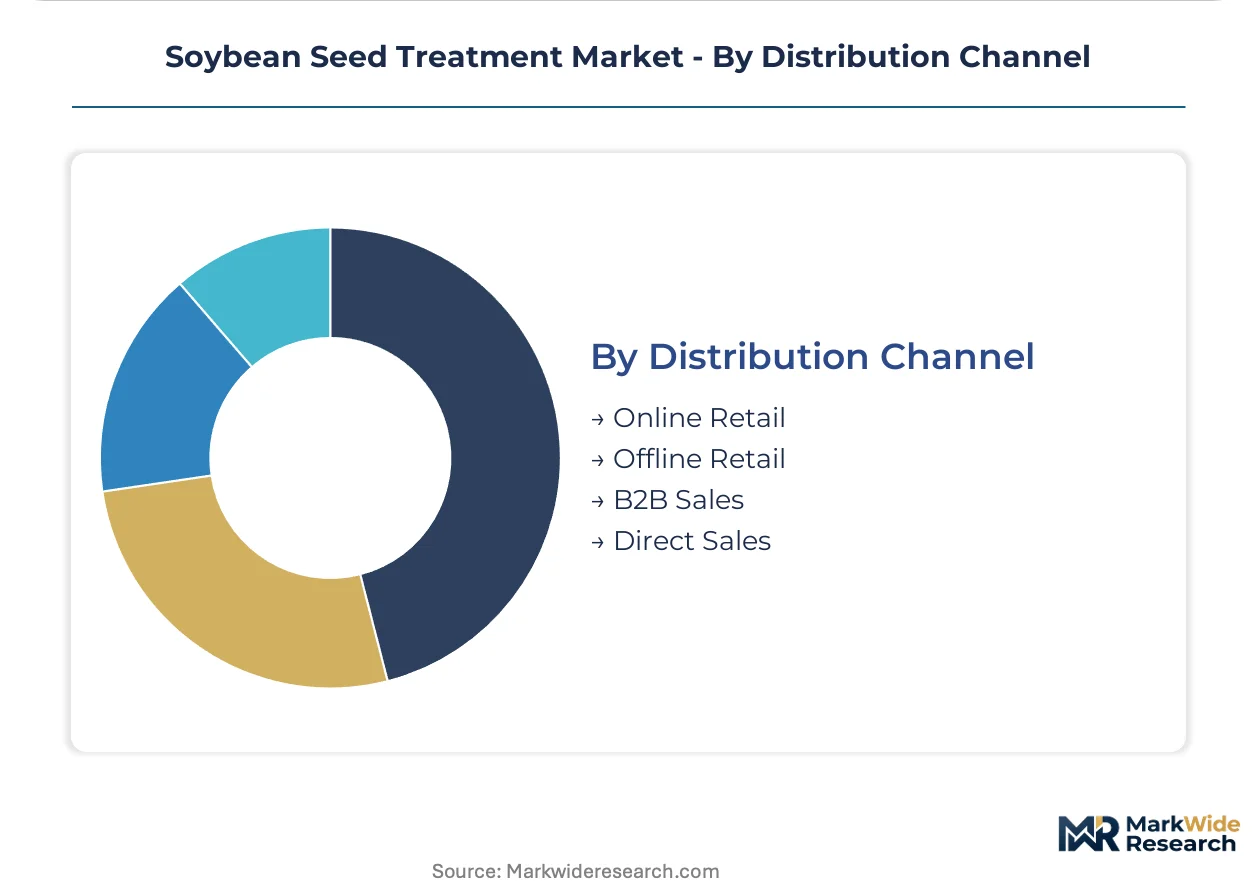
B2B Sales channels coordinate the majority of biological treatment volume. Direct Sales are expanding fastest among consolidated South American buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian export cooperatives outpace Argentine procurement consolidation in biological treatment adoption, while US Corn Belt operations maintain conventional chemistry dominance through EPA-registered fungicide platforms.
United States
Illinois and Iowa soybean operations prioritize strobilurin-based stand establishment protocols for high-density planting systems. EPA tolerance thresholds for azoxystrobin residues shape formulation selections across the Corn Belt. Purdue University extension services in Indiana pilot RNA interference coatings for soybean cyst nematode suppression.
Brazil
Mato Grosso farming cooperatives retrofit treatment facilities to accommodate microbial inoculants ahead of ANVISA export residue tightening. EU Green Deal neonicotinoid restrictions redirect procurement toward biological platforms for European grain traders. Rio Grande do Sul precision-planted systems favor high-loading combination treatments calibrated to seed spacing density.
Argentina
Buenos Aires province cooperatives centralize procurement decisions for thousands of member hectares into single agronomy teams. ANVISA-aligned residue monitoring protocols influence treatment choices across the Pampas grain belt. Córdoba's interior farming zones lack cold-chain infrastructure for temperature-sensitive biological formulations.
Germany
REACH authorization backlogs exceeding thirty-six months compress available triazole fungicide options for suppliers serving EU grain traders. ECHA substance evaluation timelines force Brazilian exporters to accelerate biological platform investments. BASF SE leverages Ludwigshafen-based fungicide pipeline capacity to anchor supply relationships with consolidated South American buyers.
China
Domestic soybean breeding programs in Heilongjiang province drive demand for ultra-low dose application systems in controlled propagation environments. NMPA registration pathways for novel biological active ingredients extend commercialization timelines. Yangtze River Delta agrochemical distributors expand biological treatment portfolios for organic certification channels.
Soybean Seed Treatment Market Competitive Landscape
German and Swiss producers anchor the integrated chemistry tier; Brazilian and Indian specialists hold positions in biological formulation and generic active ingredient supply. Market structure concentrates around three multinational suppliers controlling patented strobilurin and triazole chemistries, with regional distributors facing compressed bargaining power. Strategic archetypes separate into fungicide pipeline owners, biological platform specialists, and generic insecticide formulators. Capacity expansion in fermentation-based manufacturing and strategic partnerships for cold-chain distribution represent dominant competitive moves.
Within the integrated multinational tier, BASF SE and Bayer CropScience occupy positions defined by synthetic chemistry scale and regulatory dossier depth. Syngenta Group exemplifies biological platform specialization through microbial inoculant portfolios. Among Asia-Pacific formulators, Sumitomo Chemical Co., Ltd. represents the diversified agrochemical conglomerate archetype with seed treatment as one vertical within broader crop protection offerings.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta Group |
| Bayer CropScience |
| Corteva Agriscience |
| UPL Limited |
| FMC Corporation |
| Nufarm Limited |
| ADAMA Ltd. |
| Sumitomo Chemical Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Petrochemical feedstock volatility cascades through strobilurin and triazole synthesis costs into tiered fungicide pricing for Brazilian export cooperatives, while cold-chain biological premiums reflect fermentation capacity scarcity and ANVISA residue compliance investments.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for generic azoxystrobin and tebuconazole active ingredients. Pricing stratifies across premium branded formulations, standard cooperative-contracted blends, and economy generic alternatives. Cost compression in the economy tier is intensifying because Indian formulators capture export share through backward integration into petrochemical intermediates. Mid-scale Brazilian farms exhibit highest price sensitivity, while consolidated Argentine cooperatives absorb premium biological loadings to secure EU market access.
Supply Chain Analysis
Brazil's ANVISA domestic-content mandates for seed treatment registration dossiers are reshaping sourcing toward locally fermented biological active ingredients. Manufacturing concentrates in Germany, China, and India for synthetic fungicides, while microbial inoculant production clusters in Brazil, the United States, and Denmark. The chain draws from petrochemical feedstocks, phosphoric acid derivatives, and live-culture fermentation media. Single-source vulnerability concentrates in patented strobilurin chemistry controlled by three multinational suppliers. Distribution runs through B2B cooperative procurement channels for biologicals and direct sales for conventional chemical volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: Brazilian producers absorb premium biological costs to access EU grain markets where REACH restrictions block cheaper neonicotinoid-treated imports.
For Market Incumbents: Anchor supply relationships through exclusive fermentation capacity contracts with Mato Grosso cooperatives ahead of ANVISA biological registration acceleration. Defend against RNA interference platform displacement by integrating trait-specific biological inoculants into bundled agronomy service contracts. Prioritize cold-chain infrastructure investments across Argentina's interior to preempt regional specialist entrants. For New Entrants and Emerging Players: E-commerce platforms for smaller-scale Brazilian farm orders represent the lowest-friction entry vector. Target certified organic acreage in Brazil's Mato Grosso expansion zones where biological treatment supply constraints create immediate addressable demand. Pursue retrofit seed-coating equipment services with precision biological dosing as the primary go-to-market wedge. For Investors and Strategic Acquirers: Roll-up economics work for regional biological formulation specialists because cooperative procurement consolidation compresses supplier relationship management into fewer technical decision-makers with standardized specifications. Mid-cap fermentation-based manufacturers with ANVISA registration pipelines present acquisition targets. Watch RNA interference field trial results from Purdue University extension programs as the signal indicating platform displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Brazilian facilities with ANVISA-aligned live-culture preservation systems capture cooperative procurement consolidation. |
| Cold-Chain Distribution Partnership | Argentina's interior grain belt access requires refrigerated logistics networks absent from incumbent chemical distribution. |
| REACH Compliance Service Launch | Laboratory advisory fees for residue documentation create recurring revenue from Brazilian export cooperatives. |
| RNA Interference Platform Investment | Trait-specific pest suppression decentralizes influence from broad-spectrum chemistry suppliers toward biotechnology specialists. |
| Cooperative Technical Integration | Centralized agronomy teams at Argentine headquarters standardize procurement specifications into fewer supplier relationships. |
Research Methodology
Multiple input streams — cooperative procurement managers, fermentation facility operators, regulatory affairs specialists at ANVISA and EPA, and EU grain trader procurement leads — were reconciled against customs trade data, SEC agrochemical division filings, ECHA substance evaluation backlogs, and Brazilian agricultural export statistics. Bottom-up treatment volume estimates from state-level soybean acreage data triangulated with top-down supplier revenue disclosures.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry type, application channel certification requirements, end-user procurement consolidation tier, and regional regulatory cluster alignment. CAGRs derived from historical volume trajectories adjusted for EU Green Deal phase-out schedules and ANVISA residue protocol evolution. Forecast inputs incorporated biological efficacy validation timelines and RNA interference platform development milestones.
The model assumes a particular technology adoption path; alternative pathways for RNA interference seed coatings would alter the outlook if field performance data accelerates regulatory approval timelines or displaces microbial inoculant investment. Forecasts reflect assumptions around cooperative consolidation velocity, REACH authorization backlog resolution, and cold-chain infrastructure buildout rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Processing Innovations
Rice Seed Treatment Market
Seed Processing Innovations
North America Soybean Seed Treatment Market
Seed Processing Innovations
Kiwi Seed Extract Market
Seed Processing Innovations
Fenugreek Seed Extract Market
Seed Processing Innovations
Brazil Seed Treatment Market
Seed Processing Innovations
Australia Seed Treatment Market
Seed Processing Innovations
Oilseed Processing Market
Seed Processing Innovations
Sprouted Durum Wheat for Pasta Applications Market
Seed Processing Innovations
United States Seed Treatment Market
Seed Processing Innovations
Maize Seed Treatment Market
Seed Processing Innovations
India Seed and Grain Cleaning and Grading Machine Market
Seed Processing Innovations
Seed Sorting Machine Market
Seed Processing Innovations
Asia-Pacific Seed Treatment Market
Seed Processing Innovations
Italy Seed Treatment Market
Seed Processing Innovations
South America Seed Treatment Market
Seed Processing Innovations
Alfalfa Seed Extract Market