
 Seed Sorting Machine Market | 2026-2036
Seed Sorting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Seed Sorting Machine Market Insights
Market Context
REACH compliance in Europe is expanding the cost-of-entry calculus for seed sorting equipment sold into EU member states, forcing non-European manufacturers to reformulate lubricants, coatings, and electronic components. Bühler Group leverages its Swiss engineering heritage to sustain premium positioning across optical sorting lines. CIMBRIA A/S anchors Nordic supply chains through extensive dealer networks in Denmark and Sweden. VMek Sorting Technology competes on imaging software customization for specialty crop applications.
Technical Definition and Structural Segments
A seed sorting machine is an electromechanical or optoelectronic system that separates individual seeds by physical properties—size, shape, density, color, or internal defect—using conveyor belts, air columns, camera arrays, or electromagnetic sensors, achieving throughput rates from hundreds to tens of thousands of seeds per minute depending on configuration. Its primary purpose is to upgrade raw harvested seed lots to certified commercial grades that meet germination uniformity and purity thresholds required for agricultural planting stock. Optical sorters command the highest unit margins due to multispectral camera integration and AI-driven defect detection, while gravity separators remain the volume workhorse in developing markets where capital constraints limit technology uptake. The horticulture end-use segment shows the steepest adoption curve as high-value vegetable seed producers seek varietal purity levels exceeding mechanical sorting limits.
Regulatory Frame and Outlook
The EPA governs pesticide residue thresholds on treated seeds entering US commerce, directly influencing cleaning intensity specifications built into machines destined for North American deployment. India's BIS certification mandates electrical safety and electromagnetic compatibility testing for imported agricultural machinery, creating procedural delays that shape supplier selection criteria. Seed producers and equipment vendors must monitor evolving phytosanitary protocols in target export corridors, as bilateral agreements increasingly require lot-level traceability that only advanced sorting and data-logging systems can deliver.
Market Dynamics
Optical sorter manufacturers face intensifying pressure from REACH compliance costs and the EU's Sustainable Use of Pesticides Regulation, which together force equipment redesigns and expand the cost-of-entry calculus for non-European suppliers seeking access to EU member states.
Growth Catalysts
- Export phytosanitary mandates:Brazil's commercial seed producers scale optical sorter procurement to meet stringent international export standards, creating sustained equipment demand from South American contract farming operations.
- Precision agriculture regulation:The EU's Sustainable Use of Pesticides Regulation accelerates demand for precision seed grading equipment that reduces chemical treatment needs through superior defect removal.
- Contract farming concentration:India's Punjab and Haryana states drive bulk-processing machine uptake as organized contract farming clusters consolidate seed handling operations.
Market Restraints
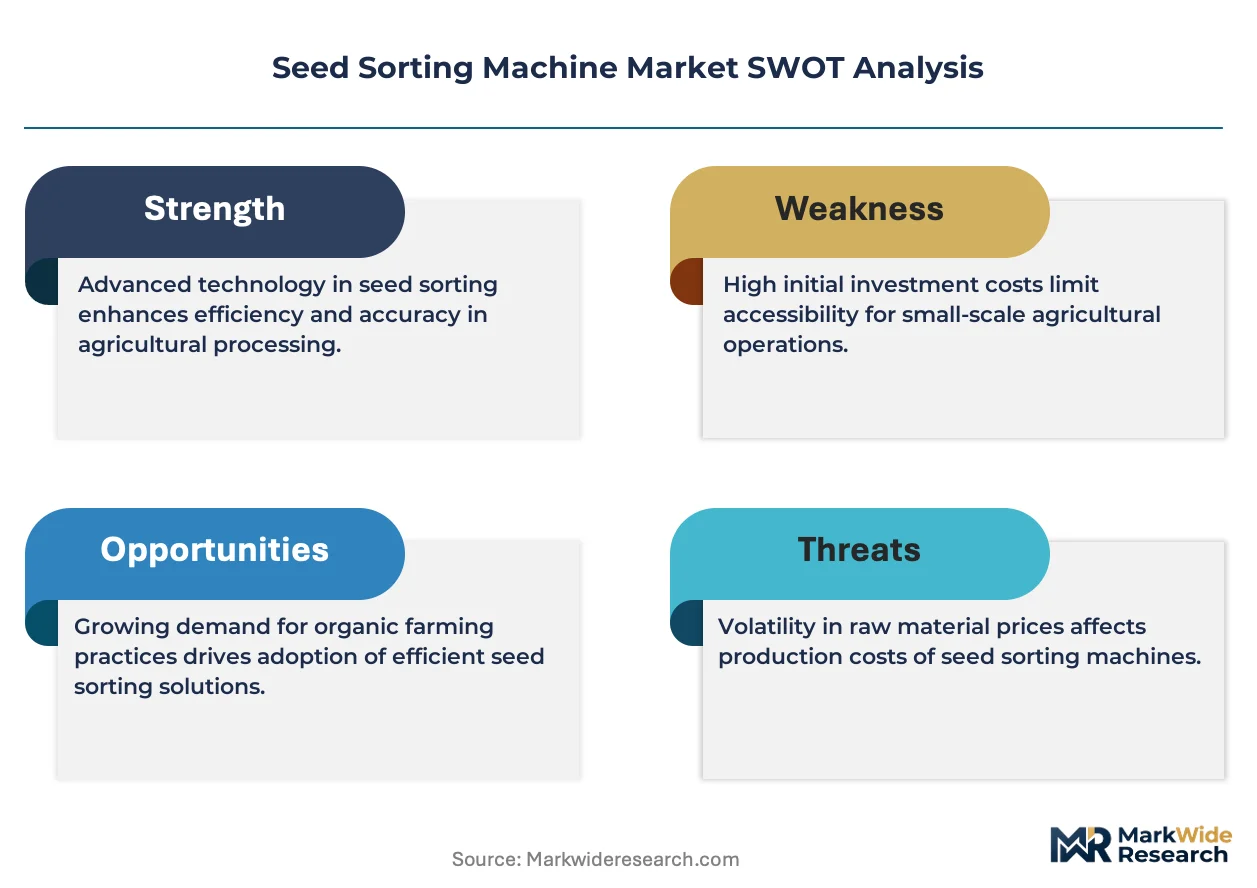
- Multispectral component costs:Camera arrays and AI processing units for optical sorters carry premium price tags that limit technology penetration in capital-constrained developing markets.
- Import certification delays:India's BIS certification mandates create procedural bottlenecks for foreign equipment suppliers, extending sales cycles and elevating working capital requirements.
- Gravity separator substitution:Mechanical density-based sorting remains the volume workhorse in price-sensitive regions, compressing addressable market expansion for advanced optoelectronic systems.
Strategic Opportunities
- Horticulture varietal purity:High-value vegetable seed producers seek purity levels exceeding mechanical sorting limits, opening premium market segments for hyperspectral imaging systems.
- Lot-level traceability mandates:Bilateral phytosanitary agreements increasingly require data-logging capabilities that only advanced sorting systems can deliver, creating regulatory-driven upgrade cycles.
- AI-software customization:Specialty crop applications demand tailored imaging algorithms, enabling vendors to capture recurring revenue through software licensing rather than hardware sales alone.
Industry Challenges
- Electromechanical integration complexity:Legacy conveyor and air-column systems resist seamless retrofit with camera arrays and electromagnetic sensors, forcing complete replacement decisions.
- Multidisciplinary talent scarcity:Equipment vendors struggle to hire engineers fluent in both optical physics and agricultural seed biology, slowing product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seed Sorting Machine Market |
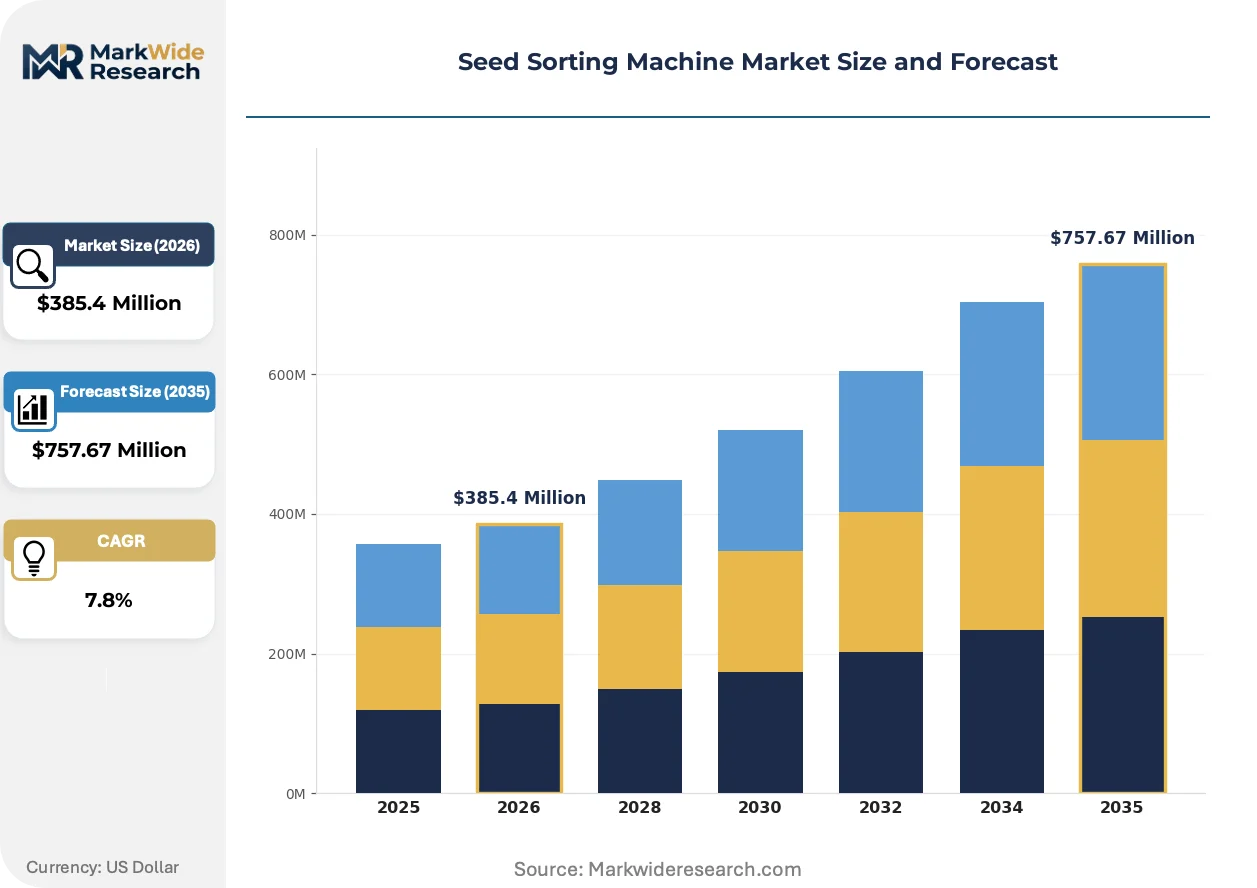
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $757.67 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Sorters, Gravity Separators, Seed Cleaners, Electronic Sorters Technology: Mechanical, Pneumatic, Imaging, Vibratory End Use Industry: Agriculture, Horticulture, Seed Production, Food Processing Capacity: Small Scale, Medium Scale, Large Scale, Bulk Processing |
| Companies Covered | DAEWON GSI CO LTD, VMek Sorting Technology, Bühler Group, Quadra Machinery, Fowler Westrup Pvt Ltd, ALMACO, CSort, CIMBRIA A/S, Orange Sorting Machines Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seed Sorting Machine Market Trends and Innovations
Multispectral imaging systems are rewriting competitive boundaries in seed sorting, compressing the performance gap between premium optical lines and mid-tier mechanical equipment while enabling entirely new defect detection categories.
Hyperspectral cameras paired with edge-computing AI processors is rewriting how seed lots achieve certification-grade purity. Large-scale commercial seed producers in the Netherlands and Denmark deploy these systems at throughput rates previously reserved for mechanical sorters. The technology is rewriting margin structures by allowing real-time internal defect detection that gravity separators cannot replicate, forcing equipment vendors to reposition legacy product lines.
REACH compliance in Europe is expanding the cost-of-entry calculus for seed sorting equipment sold into EU member states. Non-European manufacturers must reformulate lubricants, coatings, and electronic components to meet ECHA substance restrictions. Optical sorting lines destined for Germany, France, and Italy now require extensive redesign cycles that add 12-18 months to product launch timelines.
After-sales service unbundling is altering how seed processors contract for equipment support. Large agricultural cooperatives in Brazil and India now procure sorting hardware and software maintenance through separate vendor relationships, displacing traditional bundled service agreements. This pattern is most visible in Punjab and Haryana, where contract farming clusters negotiate direct AI-algorithm updates from specialized software houses rather than original equipment manufacturers.
Seed Sorting Machine Market Segmentation
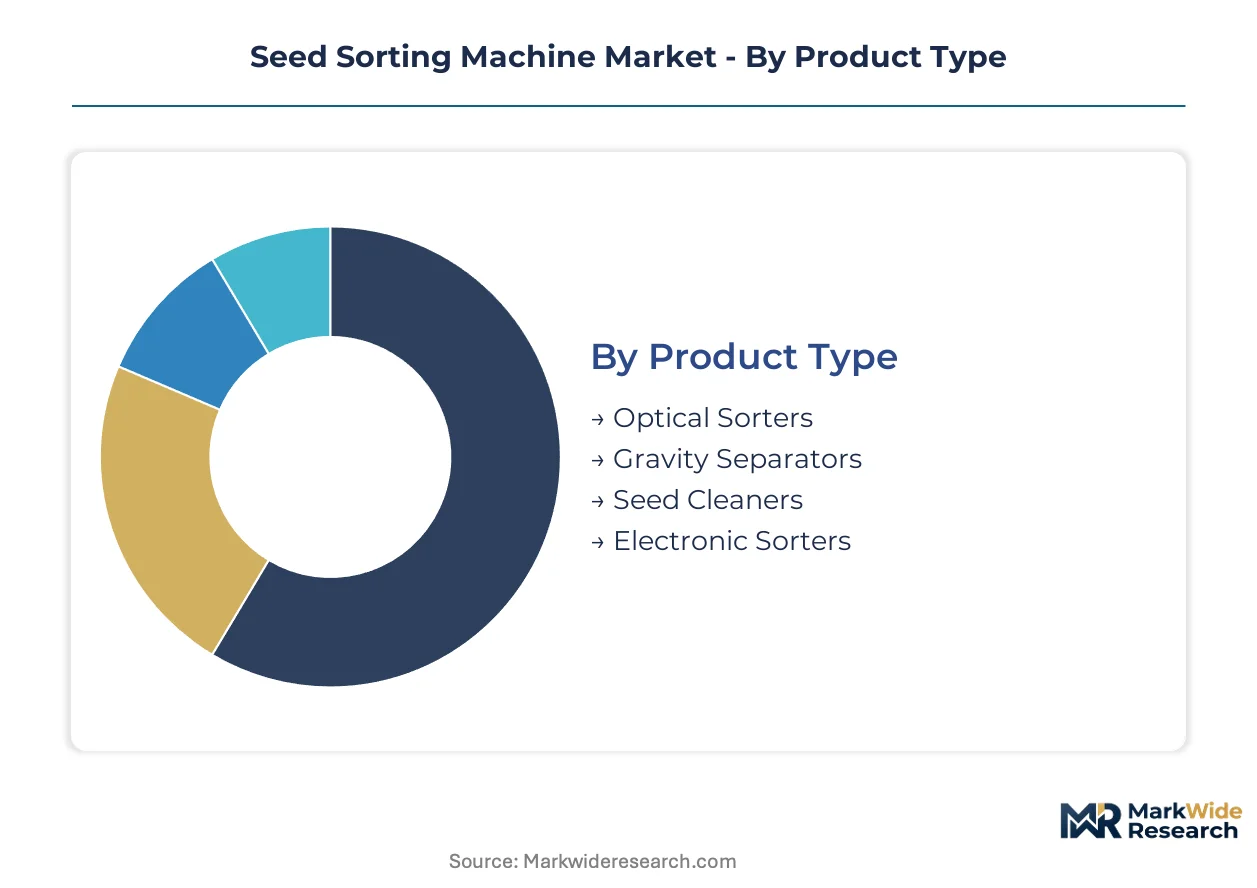
Equipment segmentation in seed sorting reflects divergent capital deployment strategies across commercial seed producers and contract farming operations. Technology tier and throughput capacity determine total cost of ownership calculations, while end-use purity requirements dictate sensor sophistication thresholds.
Product Type:
Capital intensity varies sharply across product categories, with optical sorters demanding the highest upfront investment due to multispectral camera arrays and AI processing infrastructure.
- Optical Sorters:Multispectral camera systems paired with edge-computing processors detect surface defects, color variations, and internal seed abnormalities at throughput rates exceeding mechanical alternatives. Dutch and Danish commercial seed producers deploy these systems to achieve certification-grade purity for vegetable seed exports to Germany and France.
- Gravity Separators:Density-based mechanical separation using air columns and vibrating decks remains the volume workhorse in developing markets. Punjab and Haryana contract farming clusters in India rely on gravity separators for bulk cereal seed processing where capital constraints limit technology uptake.
- Seed Cleaners:Pre-conditioning equipment removes chaff, debris, and oversized contaminants through screens and air aspiration. Brazilian soybean seed cooperatives integrate cleaners upstream of optical finishing lines to protect sensor arrays from abrasive field residues.
- Electronic Sorters:Conductivity and electromagnetic sensors identify moisture content and internal structural defects without optical components. These systems occupy a mid-tier price position for processors seeking defect detection beyond mechanical limits without full hyperspectral investment.
Most installed capacity flows through Gravity Separators. Expansion is steepest in Optical Sorters.
Technology:
Technology selection tracks the maturity curve of seed processing operations, with established facilities favoring pneumatic and mechanical systems while greenfield investments lean toward imaging platforms.
- Mechanical:Screens, indented cylinders, and air-aspiration systems separate seeds by size, shape, and density using physical contact methods. These systems dominate retrofit installations in Eastern European grain processing facilities where legacy infrastructure resists full optoelectronic replacement.
- Pneumatic:Air-column separation exploits aerodynamic properties to stratify seeds by terminal velocity. Pneumatic systems achieve high throughput with lower energy consumption than vibratory alternatives, attracting Brazilian commercial seed producers scaling for export phytosanitary compliance.
- Imaging:Camera-based detection spanning visible, near-infrared, and ultraviolet spectra enables defect categories invisible to mechanical sensors. REACH compliance costs in Europe accelerate imaging system redesigns as manufacturers reformulate lubricants and electronic components for ECHA substance restrictions.
- Vibratory:Oscillating decks and resonance-based feeders align seeds for singulation and sensor presentation. Vibratory technology concentrates in high-value horticulture applications where gentle handling preserves seed coat integrity for delicate vegetable varieties.
Mechanical systems retain the largest installed base. Imaging platforms are climbing the fastest as AI defect detection capabilities mature.
End Use Industry:
End-use segmentation reveals divergent purity thresholds, with horticulture and specialized seed production demanding precision levels that agricultural commodity processing cannot justify economically.
- Agriculture:Bulk cereal and oilseed processing for commercial planting stock emphasizes throughput and germination uniformity over varietal purity. India's BIS certification mandates for imported machinery shape equipment selection criteria for agricultural cooperatives scaling operations in Punjab and Haryana.
- Horticulture:High-value vegetable and flower seed production requires varietal purity exceeding mechanical sorting limits, opening premium segments for hyperspectral imaging. Dutch greenhouse seed suppliers deploy advanced optical lines to meet EU Sustainable Use of Pesticides Regulation targets through superior defect removal.
- Seed Production:Certified seed multiplication operations balance purity requirements with volume economics, often deploying tiered processing flows. Brazilian export-oriented seed houses combine gravity pre-cleaning with optical finishing to satisfy bilateral phytosanitary traceability mandates.
- Food Processing:Grain and pulse cleaning for human consumption applies seed sorting technology to food safety applications, with FDA and USDA residue thresholds influencing cleaning intensity specifications for equipment destined for North American deployment.
Agriculture channels the majority of unit volume. Horticulture applications are gaining share fastest on premium pricing power.
Capacity:
Capacity tier selection reflects operational scale and ownership structure, with cooperative and corporate entities consolidating around bulk processing while independent farms retain small-scale equipment.
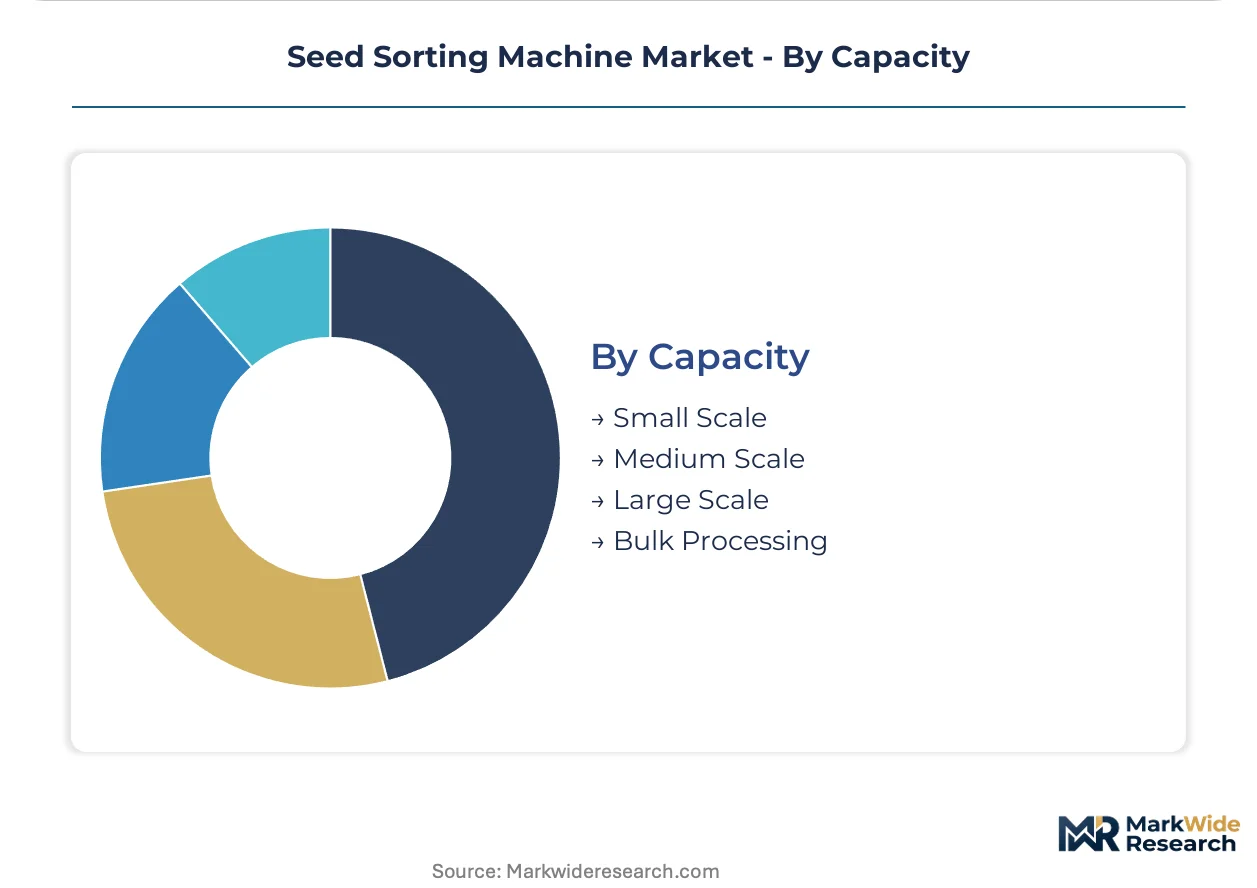
- Small Scale:Benchtop and mobile units processing hundreds of kilograms per hour serve research stations and specialty seed breeders. These systems prioritize flexibility over throughput, enabling rapid changeover between varietal trials.
- Medium Scale:Stationary equipment processing 1-5 tonnes per hour anchors regional seed service centers and mid-sized farming operations. Medium-scale procurement concentrates in India's organized contract farming clusters consolidating formerly dispersed seed handling.
- Large Scale:Integrated processing lines handling 10-50 tonnes per hour support commercial seed houses with dedicated varietal programs. Large-scale optical installations in Denmark and the Netherlands achieve throughput rates previously reserved for mechanical sorters.
- Bulk Processing:Continuous-flow systems exceeding 100 tonnes per hour serve commodity grain exporters and multinational seed corporations. Bulk processing demand in Brazil scales with export phytosanitary standard enforcement.
Medium Scale equipment represents the most common procurement tier. Bulk Processing is expanding most quickly as contract farming concentration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical physicists and agricultural engineers cluster in Denmark and the Netherlands, anchoring Europe's hyperspectral imaging development. Brazilian technicians specializing in phytosanitary compliance concentrate around São Paulo state seed corridors. India's mechanical engineering workforce dominates gravity separator fabrication in Punjab and Haryana.
United States
Commercial seed houses in Iowa and Illinois deploy bulk-processing optical lines to meet FDA residue thresholds for treated soybean and corn exports. EPA pesticide regulations govern cleaning intensity specifications built into equipment destined for North American deployment. The Corn Belt's contract farming cooperatives consolidate procurement around medium-scale pneumatic systems.
Brazil
Export-oriented soybean seed producers in Mato Grosso and Rio Grande do Sul scale optical sorter procurement to satisfy bilateral phytosanitary agreements with China and the EU. ANVISA traceability mandates accelerate data-logging system adoption across commercial seed houses. São Paulo state's seed technology corridor concentrates equipment service capabilities and technical training infrastructure.
Germany
REACH compliance and ECHA substance restrictions force equipment redesign cycles adding 12-18 months to product launch timelines for optical sorting lines. The EU's Sustainable Use of Pesticides Regulation accelerates precision seed grading equipment demand to reduce chemical treatment needs. Bavaria's agricultural machinery cluster anchors premium optical system integration and AI algorithm development.
India
BIS certification mandates for imported agricultural machinery create procedural bottlenecks extending sales cycles for foreign equipment suppliers. Punjab and Haryana contract farming clusters drive bulk-processing gravity separator uptake for cereal seed handling consolidation. Gujarat's manufacturing belt supplies domestic seed cleaner fabrication serving regional agricultural cooperatives.
Netherlands
Greenhouse vegetable seed suppliers deploy hyperspectral imaging systems to achieve varietal purity levels exceeding mechanical sorting limits for EU export markets. The country's national agricultural regulator enforces strict germination uniformity standards that only advanced optical systems can reliably deliver. Wageningen's agricultural research corridor anchors collaboration between equipment vendors and seed biology specialists.
Seed Sorting Machine Market Competitive Landscape
The competitive structure tilts toward engineering-intensive specialists with deep optical physics capabilities. Consolidation pressure concentrates around premium optical tier vendors capable of REACH-compliant redesigns, while mid-market mechanical fabricators compete on price in capital-constrained developing regions. Three archetypes dominate: Swiss-German precision engineering houses, Nordic supply chain integrators, and imaging software specialists. M&A activity targets AI algorithm capabilities, and geographic expansion follows contract farming concentration in Brazil and India.
Among European precision engineering houses, Bühler Group exemplifies the premium-tier archetype through its Swiss heritage and sustained optical sorting line positioning. CIMBRIA A/S anchors Nordic supply chain integration through extensive dealer networks in Denmark and Sweden. VMek Sorting Technology occupies a specialist position competing on imaging software customization for specialty crop applications. These three represent distinct competitive vectors: heritage engineering, supply chain reach, and software adaptability.
| Leading Market Players |
|---|
| DAEWON GSI CO LTD |
| VMek Sorting Technology |
| Bühler Group |
| Quadra Machinery |
| Fowler Westrup Pvt Ltd |
| ALMACO |
| CSort |
| CIMBRIA A/S |
| Orange Sorting Machines Private Limited |
| Others |
Pricing and Supply Chain Analysis
REACH compliance mandates in Europe are forcing equipment redesign cycles that compress supplier margins and reshape procurement negotiations across the seed sorting machine market. Buyers in Germany and France now demand extended warranty coverage and software update guarantees as standard terms, pressuring vendors to unbundle service components or absorb compliance costs.
Pricing Analysis
Service unbundling is fragmenting traditional pricing structures as Brazilian and Indian cooperatives separately negotiate hardware procurement and AI algorithm maintenance. Three-tier pricing structure across premium, standard, and economy levels reflects divergence in sensor sophistication, with optical sorters commanding substantial premiums over gravity separators. Cost compression in mid-tier electronic sorters is intensifying because Indian contract farming clusters prioritize capital efficiency over defect detection granularity. Agricultural cooperatives in Punjab and Haryana exhibit highest price sensitivity, while Dutch greenhouse seed suppliers show least sensitivity due to varietal purity premiums.
Supply Chain Analysis
Freight cost volatility from Swiss and German precision engineering hubs to Brazilian soybean seed corridors is elevating landed cost differentials for optical sorting lines. Manufacturing concentration centers on Denmark, Switzerland, and Germany for hyperspectral camera integration, while India and China supply mechanical components and gravity separator fabrication. Multispectral sensor arrays draw from specialized Taiwanese semiconductor foundries and Japanese optical glass suppliers. Single-source vulnerability in AI processor chips creates exposure to export control restrictions. Distribution runs through authorized dealer networks in Nordic markets and direct technical sales teams in South American seed corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seed sorting equipment demand is shifting toward certification-grade optical systems as bilateral phytosanitary agreements mandate lot-level traceability, elevating quality specifications above mechanical sorting thresholds.
For Market Incumbents: Deploy AI algorithm licensing as a recurring revenue lever to offset hardware margin compression from REACH compliance redesigns. Deepen vertical integration into hyperspectral camera module production to reduce dependency on Taiwanese semiconductor supply chains. Consolidate service capabilities in São Paulo and Wageningen corridors to defend against software house disintermediation in aftermarket support. For New Entrants and Emerging Players: Launch via direct algorithm licensing to Indian contract farming clusters bypassing traditional OEM distribution. Target medium-scale pneumatic systems in Brazil's Mato Grosso seed belt where export compliance urgency outpaces incumbent delivery capacity. White-space exists in specialty crop imaging for high-value vegetable seed producers seeking customized defect detection beyond standard optical configurations. For Investors and Strategic Acquirers: Asymmetric upside sits with imaging software specialists possessing adaptable AI architectures for specialty crop applications. Long-term viability hinges on regulatory-driven upgrade cycles rather than commodity grain processing volume. Watch for EU phytosanitary traceability mandate expansion as inflection indicator for premium optical system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Licensing | Enables recurring revenue streams from Indian contract farming clusters seeking direct software updates. |
| Hyperspectral Camera Integration | Positions vendors for Dutch greenhouse seed export compliance with EU Sustainable Use of Pesticides Regulation. |
| REACH-Compliant Component Redesign | Opens German and French markets while extending product launch timelines for non-European manufacturers. |
| Regional Service Center Expansion | Anchors aftermarket presence in São Paulo and Punjab corridors against software house competition. |
| Specialty Crop Imaging Customization | Captures premium segments in horticulture where varietal purity exceeds mechanical sorting limits. |
Research Methodology
Coverage spans North America, Europe, South America, and Asia-Pacific, with primary inputs from each region's seed processing corridors. Primary interviews engaged equipment engineering directors at optical sorting manufacturers, procurement leads at Brazilian commercial seed houses, maintenance supervisors at Indian contract farming cooperatives, and regulatory affairs specialists at Dutch greenhouse seed exporters. Secondary validation drew from EPA pesticide residue databases, ECHA substance restriction filings, ANVISA traceability mandates, and Indian BIS certification records. Bottom-up equipment shipment tracking triangulated against top-down seed industry investment surveys.
Granularity-level modeling disaggregated volume and value across product type, technology tier, end-use industry, and capacity scale, with additional dimensioning by regional regulatory cluster and export compliance intensity. CAGRs were derived from equipment replacement cycle analysis and phytosanitary mandate implementation timelines. Forecast inputs incorporated seed production consolidation patterns in Punjab and Haryana, bilateral trade agreement evolution between Brazil and China, and REACH substance restriction phase-in schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU phytosanitary traceability adoption or extended Taiwanese semiconductor export restrictions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Processing Innovations
South America Seed Treatment Market
Seed Processing Innovations
Sprouted Durum Wheat for Pasta Applications Market
Seed Processing Innovations
Asia-Pacific Seed Treatment Market
Seed Processing Innovations
Fenugreek Seed Extract Market
Seed Processing Innovations
Oilseed Processing Market
Seed Processing Innovations
Australia Seed Treatment Market
Seed Processing Innovations
North America Soybean Seed Treatment Market
Seed Processing Innovations
Brazil Seed Treatment Market
Seed Processing Innovations
Kiwi Seed Extract Market
Seed Processing Innovations
Rice Seed Treatment Market
Seed Processing Innovations
Italy Seed Treatment Market
Seed Processing Innovations
United States Seed Treatment Market
Seed Processing Innovations
India Seed and Grain Cleaning and Grading Machine Market
Seed Processing Innovations
Maize Seed Treatment Market
Seed Processing Innovations
Argentina Seed Treatment Market
Seed Processing Innovations
Alfalfa Seed Extract Market