
 Rice Seed Treatment Market | 2026-2036
Rice Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Rice Seed Treatment Market Outlook
Buyer concentration among large-scale commercial rice farming cooperatives is pivoting procurement patterns toward bulk-treated seed contracts with integrated technical support. Bayer AG leverages its global germplasm network to bundle proprietary seed treatment chemistry with certified seed varieties. FMC Corporation sustains competitive positioning through specialized insecticide seed treatments targeting rice water weevil populations. UPL Limited anchors its presence in South Asian markets with localized biological treatment formulations adapted to tropical humidity conditions.
Rice seed treatment encompasses the application of protective biological, chemical, or physical agents to rice seeds prior to sowing, typically involving active ingredient loadings of 0.5–5 grams per kilogram of seed to ensure uniform coating adhesion and controlled release during germination. Its primary commercial purpose is to suppress soil-borne pathogens, early-season insect pests, and abiotic stress factors that disproportionately damage rice during the vulnerable seedling establishment phase. Fungicide-based treatments occupy the dominant revenue position due to persistent pressure from Rhizoctonia solani and Pyricularia oryzae across humid rice belts, while biological formulations represent the fastest-expanding category as residue-conscious export markets tighten maximum residue limits. Seed coating as a delivery mechanism commands premium positioning because polymer-encapsulated formulations improve active ingredient retention during mechanized drilling and submerged germination.
The EPA regulates treated seed as a pesticide-end-use product under FIFRA, requiring registration review of seed treatment active ingredients with particular scrutiny on pollinator toxicity profiles. India's Central Insecticides Board enforces mandatory label declarations for treated seed bags under the Insecticides Act, directly shaping product formulation choices for exporters serving South Asian cooperatives. China's Ministry of Agriculture and Rural Affairs maintains a national positive list for seed treatment compounds used on staple crops, creating compliance thresholds for foreign suppliers. Stakeholders must monitor evolving residue thresholds in destination export markets and align R&D pipelines with biological registration pathways that offer accelerated approval timelines.
Market Dynamics
Regulatory tightening on neonicotinoid insecticides across the European Union and several Asian jurisdictions is redirecting investment toward biological seed treatments, fundamentally restructuring competitive positioning and R&D priorities across the value chain.
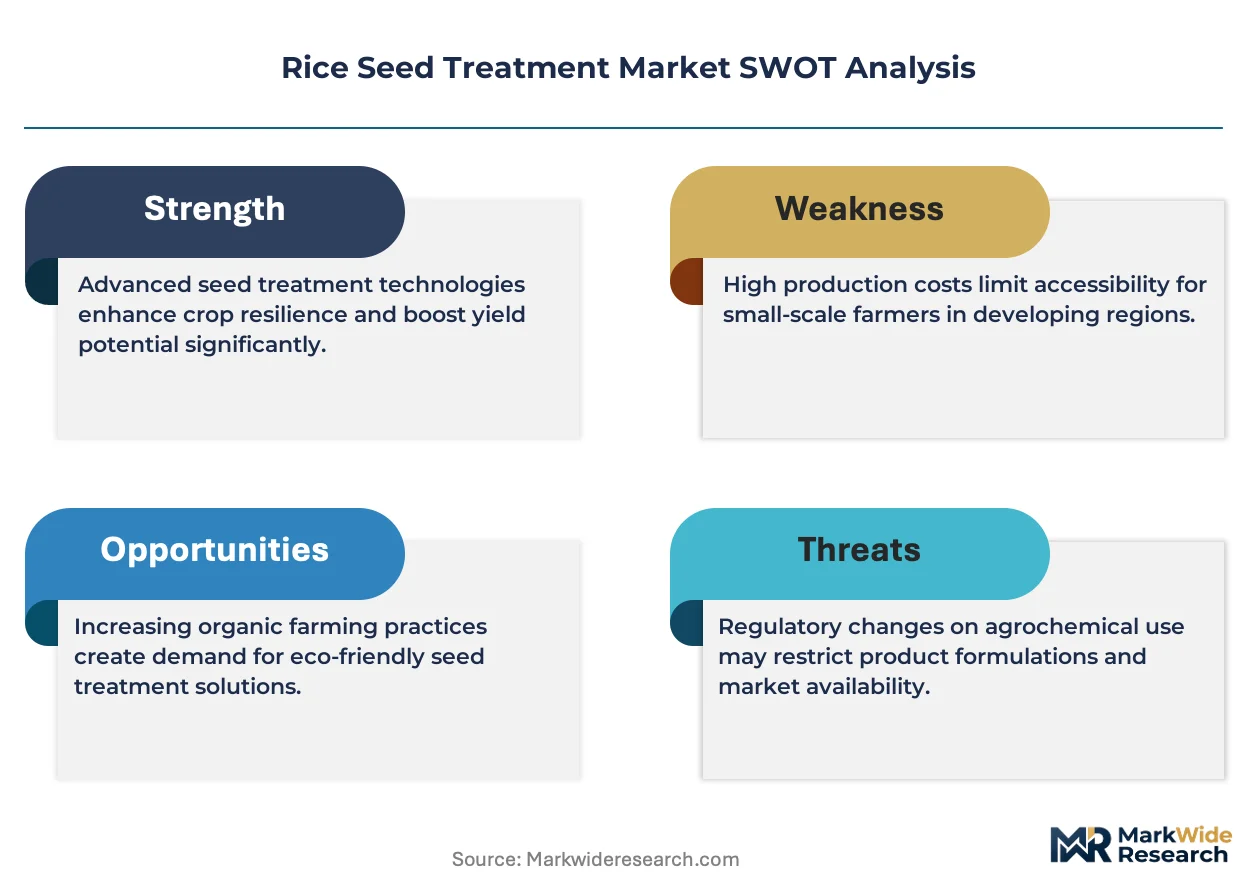
Growth Catalysts
- EU Green Deal agricultural sustainability targets:The EU's Farm to Fork strategy mandates 50% reduction in chemical pesticide use, accelerating biological treatment registration timelines and creating first-mover advantages for compliant suppliers.
- Double-cropping intensity in Vietnam's Mekong Delta:Intensive rice production systems amplify seedling vulnerability to soil-borne pathogens, generating concentrated demand for protective seed coatings with extended residual efficacy.
- Polymer encapsulation technology:Advanced seed coating formulations improve active ingredient retention during submerged germination, enabling mechanized drilling adoption among commercial cooperatives.
Market Restraints
- Petrochemical input cost volatility:Synthetic polymer carriers and chemical active ingredients face price instability tied to crude oil derivatives, compressing formulation margins.
- Registration concentration risk:China's Ministry of Agriculture and Rural Affairs maintains restrictive positive lists for seed treatment compounds, creating compliance bottlenecks for foreign suppliers seeking market entry.
- Technical limitation in tropical humidity:Biological formulations suffer reduced shelf stability under high-moisture storage conditions prevalent across Southeast Asian supply chains.
Strategic Opportunities
- Underpenetrated Myanmar commercial farming:Emerging large-scale rice operations in the Ayeyarwady Delta lack established seed treatment infrastructure, presenting greenfield partnership potential.
- Integrated pest management mandates:Thailand's national agricultural extension programs incentivize biological-chemical combination treatments, opening hybrid formulation markets.
- Drone-based seed coating services:Aerial application technology convergence with precision agriculture enables on-demand treatment delivery, bypassing centralized processing bottlenecks.
Industry Challenges
- Biological formulation expertise scarcity:Limited talent pools in microbial strain selection and fermentation scale-up constrain domestic production capacity across South Asian markets.
- Maximum residue limit certification timelines:Export-oriented cooperatives face protracted testing protocols for destination markets, delaying commercial deployment of novel active ingredients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rice Seed Treatment Market |
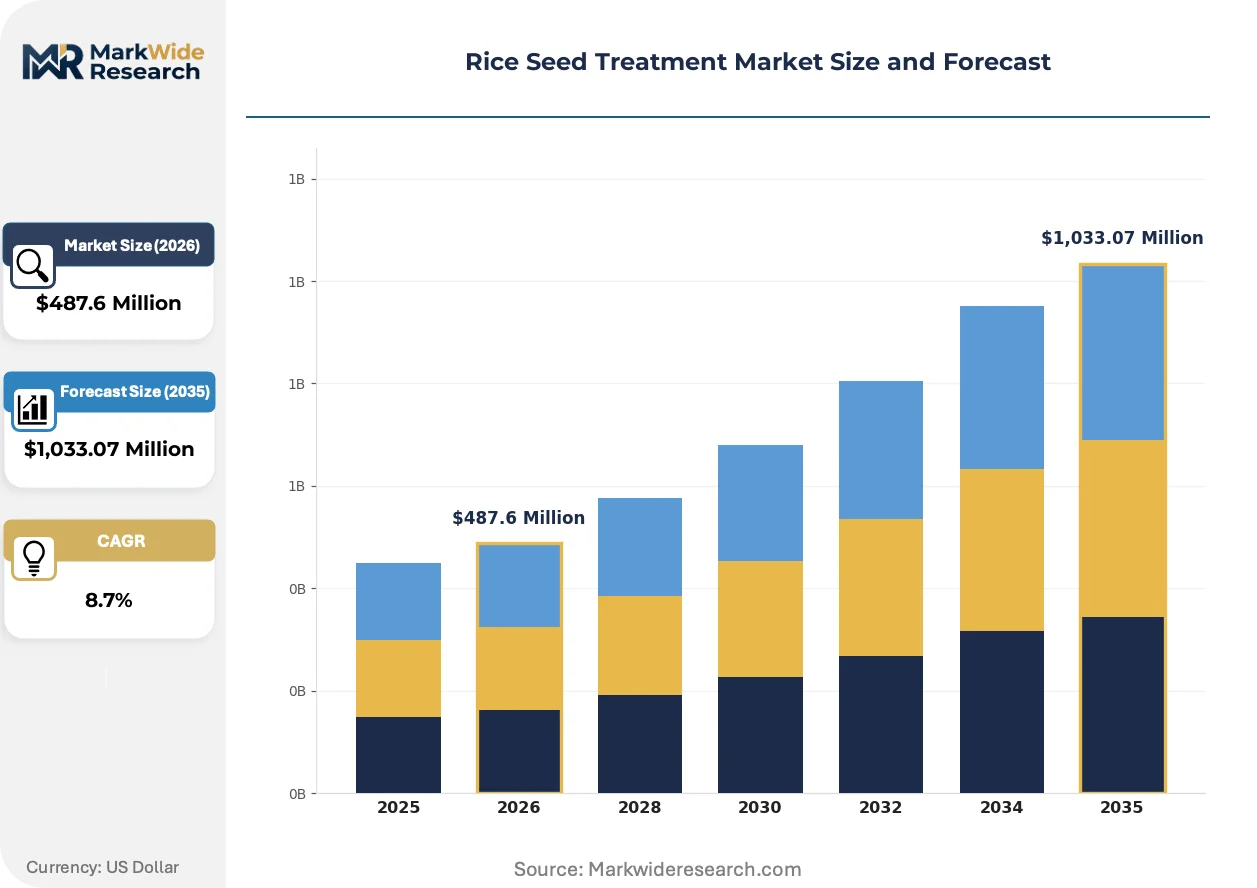
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologicals, Fungicides, Insecticides, Seed Coatings Application: Soil Treatment, Seed Treatment, Foliar Application, Post-Harvest Treatment End Use Industry: Agriculture, Horticulture, Organic Farming, Research Institutions Distribution Channel: Direct Sales, Distributors, Online Retail, Agricultural Cooperatives |
| Companies Covered | BASF SE, FMC Corporation, Bayer AG, Nufarm Ltd, Croda International, UPL Limited, Corteva Agriscience, Sumitomo Chemical, Syngenta Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rice Seed Treatment Market Strategic Shifts
Biological seed treatment technology is consolidating market share as residue-conscious export markets tighten compliance thresholds and commercial farming operations seek registration-ready alternatives to restricted chemistries.
Microbial inoculant formulations incorporating Trichoderma and Bacillus species are consolidating technical validation through field trials across Vietnam, Thailand, and Indonesia. Large-scale cooperatives in the Mekong Delta are adopting these treatments at accelerating rates to preempt EU import rejection risks. The technology is consolidating supplier differentiation around strain-specific efficacy claims and tropical stability guarantees, compressing commodity chemical pricing power.
The EPA's pollinator toxicity review framework under FIFRA is intensifying scrutiny of neonicotinoid seed treatments, triggering reformulation mandates and extended registration review cycles. This regulatory pressure is elevating biological pathway investments and accelerating partnership structures between agrochemical majors and microbial technology specialists. Rice export-oriented operations in Vietnam and Cambodia are most affected, pivoting procurement specifications toward pollinator-safe certified treatments.
Cooperative procurement managers are consolidating purchasing through multi-year bulk-treated seed contracts bundled with technical advisory services. Traditional spot-market seed treatment sales through local agro-dealer networks are losing share to direct manufacturer-cooperative agreements in Vietnam's intensive production zones. This concentration is most visible among double-cropping operations seeking integrated pest management compliance documentation for European export contracts.
Rice Seed Treatment Market Segmentation
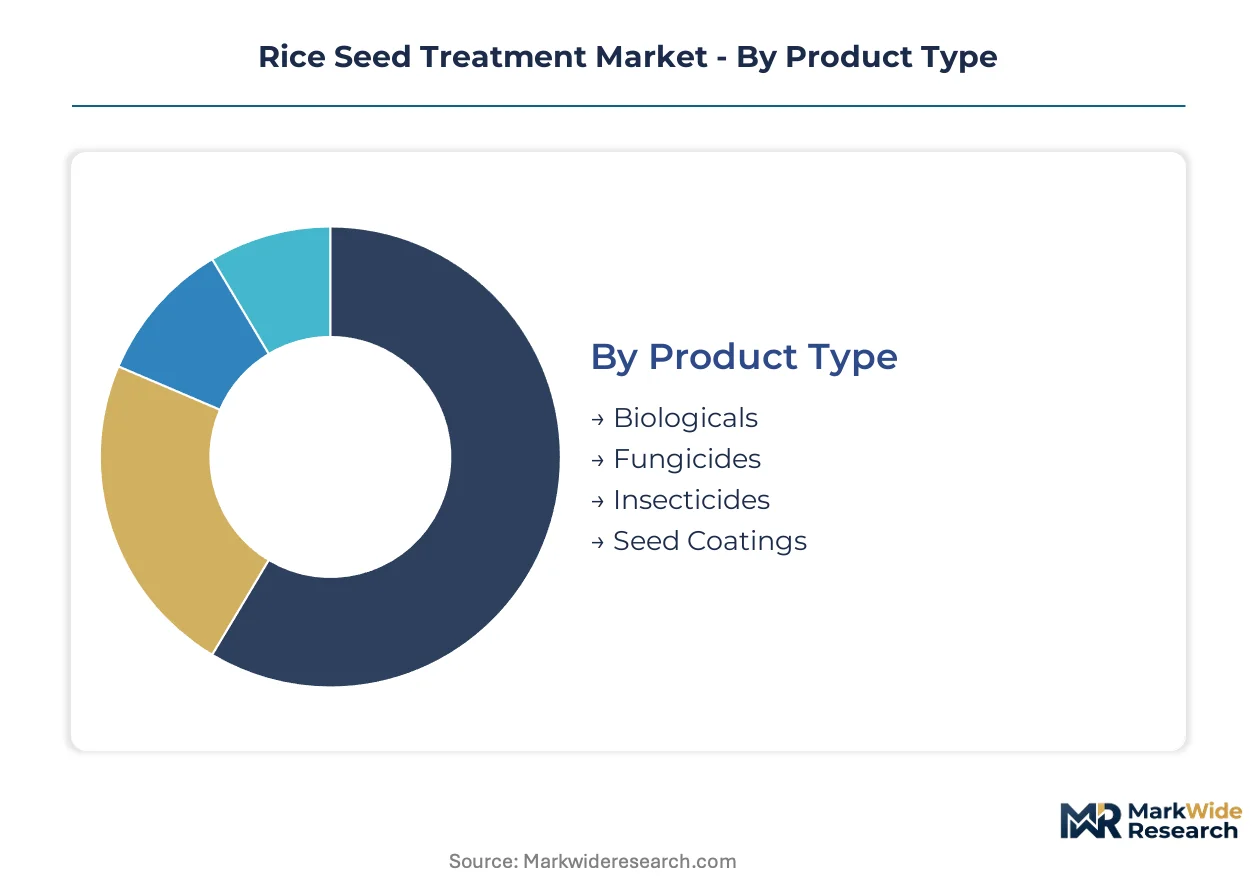
Segmentation in rice seed treatment reveals how capital deployment, technical complexity, and regulatory compliance intersect to shape supplier strategies across distinct product and channel configurations.
Product Type:
Capital intensity varies sharply across formulation categories, with polymer-encapsulated chemical systems demanding the highest upfront R&D and manufacturing infrastructure investment.
- Fungicides:Azole and strobilurin-based formulations dominate commercial rice belts through proven efficacy against Rhizoctonia solani and Pyricularia oryzae. Vietnam's Mekong Delta cooperatives purchase these treatments in bulk to preempt blast disease losses during intensive double-cropping cycles.
- Biologicals:Microbial inoculants incorporating Trichoderma and Bacillus species require specialized fermentation capacity and strain stabilization protocols. Demand concentrates among export-oriented operations seeking EU-compliant residue profiles for premium rice contracts.
- Insecticides:Neonicotinoid alternatives and novel chemistry target early-season rice water weevil pressure. Regulatory tightening across multiple Asian jurisdictions accelerates reformulation timelines.
- Seed Coatings:Polymer carrier systems improve active ingredient retention during submerged germination and mechanized drilling operations.
Most installed capacity flows through fungicide manufacturing. Expansion is steepest in biologicals.
Application:
Application method selection determines equipment requirements, labor intensity, and timing flexibility across rice production systems.
- Seed Treatment:Pre-sowing coating delivers protective chemistry directly to the germination zone with controlled-release precision. Commercial cooperatives in intensive production zones favor this method for its integration with certified seed procurement and mechanized planting workflows.
- Soil Treatment:Broadcast or incorporated applications address broader pathogen pressure but sacrifice seed-specific targeting. Double-cropping operations in tropical humidity conditions deploy these treatments where seed coating infrastructure is unavailable.
- Foliar Application:Post-emergence spraying supplements seed-applied protection during tillering stages.
- Post-Harvest Treatment:Storage protection applications preserve seed viability for subsequent planting seasons.
Seed treatment commands the dominant equipment investment. Foliar systems are gaining share fastest among smallholder transition zones.
End Use Industry:
Customer type segmentation exposes divergent purchasing power, technical sophistication, and compliance documentation requirements.
- Agriculture:Large-scale commercial rice farming operations generate concentrated demand for bulk-treated seed contracts with integrated pest management documentation. These buyers prioritize residue compliance for export market access over per-unit cost minimization.
- Organic Farming:Certified organic producers require exclusively biological formulations with third-party input approvals. Supply chains serving this segment emphasize strain-specific efficacy guarantees and tropical stability validation.
- Horticulture:Specialty rice varieties for premium culinary markets utilize targeted treatment protocols.
- Research Institutions:Breeding programs and field trial networks purchase small-volume experimental formulations.
Agriculture absorbs the majority of formulation volume. Organic farming is climbing the fastest as export premiums widen.
Distribution Channel:
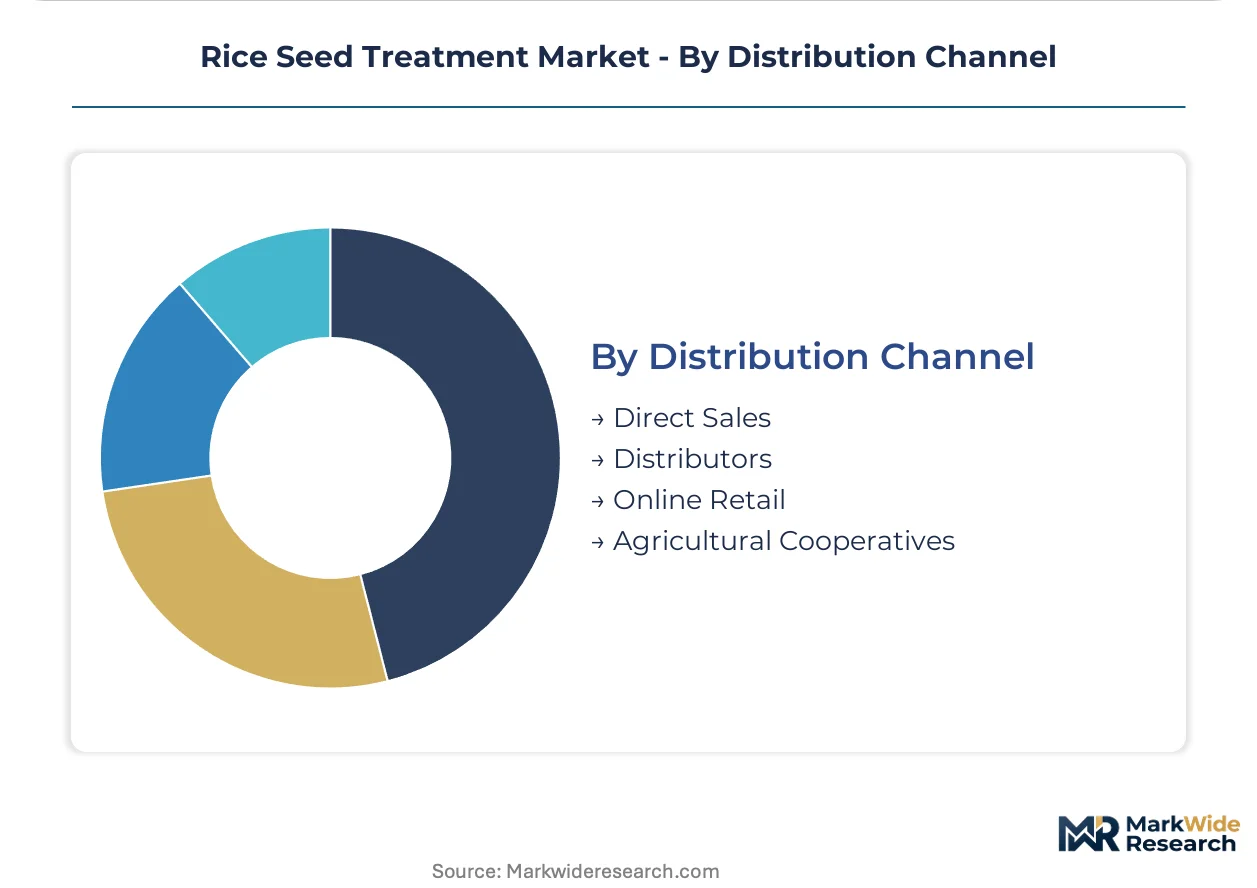
Channel structure reflects the shift from fragmented agro-dealer networks toward consolidated procurement relationships with technical service bundling.
- Agricultural Cooperatives:Consolidated purchasing through multi-year bulk contracts enables direct manufacturer relationships with embedded advisory services. Vietnam's intensive production zones exhibit the most pronounced cooperative procurement concentration.
- Direct Sales:Manufacturer-to-farm relationships serve large-scale operations requiring customized formulation blends and compliance documentation.
- Distributors:Regional agro-input networks maintain inventory proximity for smaller commercial farms and spot-market purchasers.
- Online Retail:Digital platforms facilitate smallholder access to biological treatments with technical guidance content.
Cooperative channels carry the heaviest transaction volume. Direct sales are expanding most quickly among export-certified operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Mekong Delta drives biological seed treatment adoption at double the rate of India's eastern rice belts, while regulatory divergence between the EU and China creates distinct compliance corridors for multinational suppliers.
Vietnam
Intensive double-cropping systems in the Mekong Delta amplify seedling vulnerability to blast disease and sheath rot, generating concentrated demand for polymer-encapsulated fungicide coatings. The Ministry of Agriculture and Rural Affairs enforces residue limits aligned with EU import standards, pressuring cooperatives toward biological alternatives. Can Tho and An Giang provinces anchor commercial procurement, where large-scale farming operations purchase bulk-treated seed through direct manufacturer contracts.
China
The Yangtze River Delta and northeastern rice belts sustain volume demand for chemical seed treatments targeting rice water weevil and stem borer pressure. The Ministry of Agriculture and Rural Affairs maintains a restrictive positive list for seed treatment compounds, creating registration bottlenecks for foreign active ingredients. Heilongjiang Province concentrates mechanized drilling adoption, driving demand for coating formulations with enhanced retention during submerged germination.
India
Eastern states of West Bengal and Odisha generate substantial demand for protective seed treatments against sheath blight and bacterial leaf blight in monsoon-dependent cultivation systems. The Central Insecticides Board mandates label declarations for all treated seed bags under the Insecticides Act, directly shaping exporter formulation choices. Andhra Pradesh's Godavari Delta exhibits accelerating biological treatment uptake among export-oriented basmati cooperatives seeking EU compliance documentation.
Thailand
The Chao Phraya River Basin sustains commercial demand for integrated pest management-compliant seed treatments as national extension programs incentivize biological-chemical combinations. The Department of Agriculture promotes farmer training on proper treated seed handling to reduce environmental runoff. Central Plains provinces concentrate procurement through agricultural cooperatives that negotiate multi-year supply contracts with embedded technical advisory services.
Indonesia
Java's irrigated lowlands drive demand for protective seed coatings against tungro virus vectors and seedling rot in intensified production systems. The Ministry of Agriculture regulates treated seed imports through variety registration requirements that delay novel active ingredient commercialization. West Java's Indramayu and Subang regencies cluster commercial rice operations adopting mechanized planting workflows compatible with polymer-encapsulated treatments.
Rice Seed Treatment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation categories, creating a tiered structure where scale advantages in chemical manufacturing confront agility advantages in biological strain development. The vendor base organizes around three strategic archetypes: integrated agrochemical majors with germplasm bundling capabilities, regional specialists in tropical formulation adaptation, and microbial technology developers targeting residue-compliant export channels. Dominant competitive moves include strategic partnerships between chemical and biological technology platforms, plus geographic expansion through cooperative procurement channel capture.
Within the integrated agrochemical tier, Bayer AG and BASF SE occupy positions exemplifying germplasm-treatment bundling strategies, while UPL Limited represents regional specialists with localized biological formulations. Sumitomo Chemical anchors the Asia-Pacific manufacturing footprint for tropical-adapted seed treatment chemistry. These companies exemplify divergent pathways: multinational conglomerates leverage global registration networks and proprietary seed variety linkages, while regional players concentrate on humidity-stable biological strain development and cooperative direct sales relationships.
| Leading Market Players |
|---|
| BASF SE |
| FMC Corporation |
| Bayer AG |
| Nufarm Ltd |
| Croda International |
| UPL Limited |
| Corteva Agriscience |
| Sumitomo Chemical |
| Syngenta Group |
| Others |
Value Chain & Pricing Dynamics
Polymer resin indices and petrochemical feedstock benchmarks cascade through rice seed treatment manufacturing into distinct pricing tiers, with synthetic carrier costs compressing margins for chemical formulations while biological alternatives command stability premiums in EU-facing export channels.
Pricing Analysis
Capacity additions in India's Gujarat and Maharashtra are reshaping price floors for azole-based fungicide coatings. Three-tier pricing structure across premium, standard, and economy levels separates EU-certified biological formulations from generic chemical treatments and uncoated commodity seed. Price differentiation hinges on residue compliance documentation and volume scale of cooperative procurement. Margins are tightening due to crude oil derivative volatility, with smallholder spot-market buyers exhibiting highest price sensitivity versus export-certified cooperatives prioritizing compliance over per-unit cost.
Supply Chain Analysis
EU MRL certification and China's positive list qualification gate foreign supplier access, creating compliance-driven supply segmentation. Manufacturing concentrates in India, China, and Germany for chemical actives; Brazil and Indonesia for biological strain fermentation. Formulation draws from synthetic polymer carriers, microbial inoculant stocks, and specialized coating equipment. Single-source vulnerability runs through neonicotinoid alternative chemistry patents. Distribution runs through agricultural cooperatives in Vietnam's Mekong Delta and direct manufacturer relationships with large-scale commercial operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: biological formulation investments in South Asia capture cost advantages against EU regulatory compliance premiums for residue-conscious export channels.
For Market Incumbents: Anticipate accelerated biological registration timelines by pre-positioning strain libraries for EU Green Deal alignment. Defend against pure-play microbial specialists through backward integration into fermentation capacity in tropical humidity zones. Prioritize cooperative channel lock-in via multi-year bulk contracts with embedded IPM advisory services. For New Entrants and Emerging Players: Myanmar's Ayeyarwady Delta commercial farming operations represent an underserved buyer archetype lacking established seed treatment infrastructure. Penetrate through drone-based aerial coating services bypassing centralized processing bottlenecks. Target Thailand's biological-chemical hybrid formulation demand driven by national extension program incentives. For Investors and Strategic Acquirers: Consolidation pressure builds where microbial strain expertise scarcity constrains domestic biological production capacity across South Asian markets. Five-to-ten year viability favors acquisition of tropical-stability-validated biological developers over commodity chemical formulation assets. Watch EU import rejection rates for Vietnamese rice as inflection indicator for biological treatment penetration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Strain Library Expansion | Accelerates EU MRL-compliant product pipelines for Vietnamese export cooperatives. |
| Cooperative Direct Sales Channel Capture | Locks in multi-year offtake commitments with Mekong Delta bulk purchasers. |
| Tropical Humidity Stability Validation | Enables shelf-life guarantees for biological formulations in Southeast Asian storage conditions. |
| Drone-Based Coating Service Partnership | Bypasses centralized processing infrastructure gaps in emerging commercial farming zones. |
| Backward Integration into Fermentation Capacity | Secures captive supply of microbial inoculants against strain supplier concentration risk. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured seed treatment formulators, cooperative procurement managers, regulatory affairs specialists at agrochemical majors, and Ministry of Agriculture extension officers across Vietnam, India, and Thailand. Secondary validation drew from Central Insecticides Board registration databases, EU pesticide residue monitoring reports, FAO rice production statistics, and customs trade flow records. Bottom-up cooperative procurement surveys and top-down manufacturer shipment data were triangulated against national rice planted area estimates.
Segment-weighting approaches distributed value and volume across product type, application method, end-use industry, and distribution channel dimensions. CAGRs were derived from trend extrapolation of biological adoption curves and chemical registration attrition rates across the analysis window. Industry-specific forecast inputs incorporated EU Farm to Fork pesticide reduction targets and double-cropping intensity indices for Vietnam's Mekong Delta.
Underlying measurement precision varies by segment; biological formulation revenue estimates carry tighter precision than chemical spot-market pricing due to concentrated cooperative reporting. Forecasts reflect assumptions around regulatory timeline stability and residue limit stringency evolution. A model refresh is warranted upon material change in EU import rejection rates for Vietnamese rice or China's positive list expansion for foreign seed treatment actives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Processing Innovations
Maize Seed Treatment Market
Seed Processing Innovations
Italy Seed Treatment Market
Seed Processing Innovations
Kiwi Seed Extract Market
Seed Processing Innovations
India Seed and Grain Cleaning and Grading Machine Market
Seed Processing Innovations
Soybean Seed Treatment Market
Seed Processing Innovations
Asia-Pacific Seed Treatment Market
Seed Processing Innovations
Oilseed Processing Market
Seed Processing Innovations
North America Seed Treatment Market
Seed Processing Innovations
Brazil Seed Treatment Market
Seed Processing Innovations
Alfalfa Seed Extract Market
Seed Processing Innovations
United States Seed Treatment Market
Seed Processing Innovations
North America Soybean Seed Treatment Market
Seed Processing Innovations
Argentina Seed Treatment Market
Seed Processing Innovations
Seed Sorting Machine Market
Seed Processing Innovations
South America Seed Treatment Market
Seed Processing Innovations
Sprouted Durum Wheat for Pasta Applications Market