
 Maize Seed Treatment Market | 2026-2036
Maize Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Maize Seed Treatment Market Foresight
Agricultural cooperative procurement channels is tilting toward bundled seed-plus-treatment packages across the US Midwest and Brazilian grain belts. BASF SE leverages its polymer coating technology to anchor premium positioning in high-value corn hybrids. Bayer AG sustains broad fungicide-seed treatment integration through its crop science division's distribution reach. Syngenta competes on biological inoculant portfolios that reduce synthetic chemical dependency for sustainability-focused growers.
Maize seed treatment encompasses chemical, biological, and physical agents applied to corn seed surfaces or substrates to protect germinating embryos from soilborne pathogens, insect pests, and abiotic stressors, typically involving film coatings at application rates of milligrams per seed. These formulations integrate active ingredients with binding polymers and colorants to ensure uniform adhesion, rapid root emergence, and early vigor in commercial field corn production. Pesticide-based coatings still occupy the largest value share but face margin compression from regulatory scrutiny, while inoculant segments represent the fastest-expanding margin pool as nitrogen-fixing and phosphate-solubilizing biologicals gain traction in regenerative systems. Seed coating as an application method dominates volume throughput due to equipment compatibility with high-speed planting operations, though liquid treatment protocols are gaining adoption in precision agriculture setups that customize rates by field zone.
The EPA oversees active ingredient registration and tolerance setting for maize seed treatments in the United States, while Brazil's national agricultural regulator evaluates import equivalence and local residue limits for treated seed entering its expanding frontier croplands. REACH compliance in Europe constrains certain azole fungicide chemistries, redirecting formulation innovation toward exempt biological actives that bypass lengthy substance authorization timelines. Stakeholders must monitor how the EU Green Deal's pesticide reduction targets cascade into import standards that could reshape competitive access for treated seed exports destined for European feed supply chains.
Market Dynamics
The EPA's evolving neonicotinoid review is compressing synthetic chemistry margins while redirecting R&D capital toward biological actives. This regulatory pivot is fragmenting formulation portfolios across the value chain.
Growth Catalysts
- Brazil's Cerrado expansion:No-till farming systems in this frontier zone require premium seed protection packages that integrate fungicide-insecticide-biological combinations.
- EU Green Deal pesticide reduction targets:Import standards tightening across European feed supply chains create pull-through demand for residue-compliant biological alternatives.
- Polymer coating technology:Advanced film-forming binders enable multi-active layering at milligram-per-seed precision, improving adhesion uniformity under mechanized high-speed planting.
Market Restraints
- Active ingredient cost volatility:Azole fungicide feedstocks face supply concentration from Chinese intermediate manufacturers, compressing formulation margins.
- REACH authorization timelines:ECHA's lengthy substance evaluation windows for novel chemistries delay commercialization by 18-36 months versus exempt biological pathways.
- Biological shelf-life limitations:Viable cell count degradation in nitrogen-fixing inoculants restricts distribution radius and cold-chain requirements.
Strategic Opportunities
- India's maize belt penetration:BIS certification alignment for biological seed treatments opens access to state procurement programs in Punjab and Haryana.
- Precision agriculture convergence:Variable-rate liquid treatment equipment paired with field-zone soil microbiome mapping enables customized biological dosing.
- Carbon credit stacking:Regenerative agriculture certification programs monetize nitrogen-fixing inoculant adoption through verified emission reduction protocols.
Industry Challenges
- Formulation chemist scarcity:Cross-functional expertise bridging polymer science and microbial viability engineering commands premium compensation and extends hiring cycles.
- Multi-jurisdiction registration synchronization:Divergent residue tolerance setting between EPA, ANVISA, and EFSA requires parallel dossier preparation, inflating regulatory affairs overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maize Seed Treatment Market |
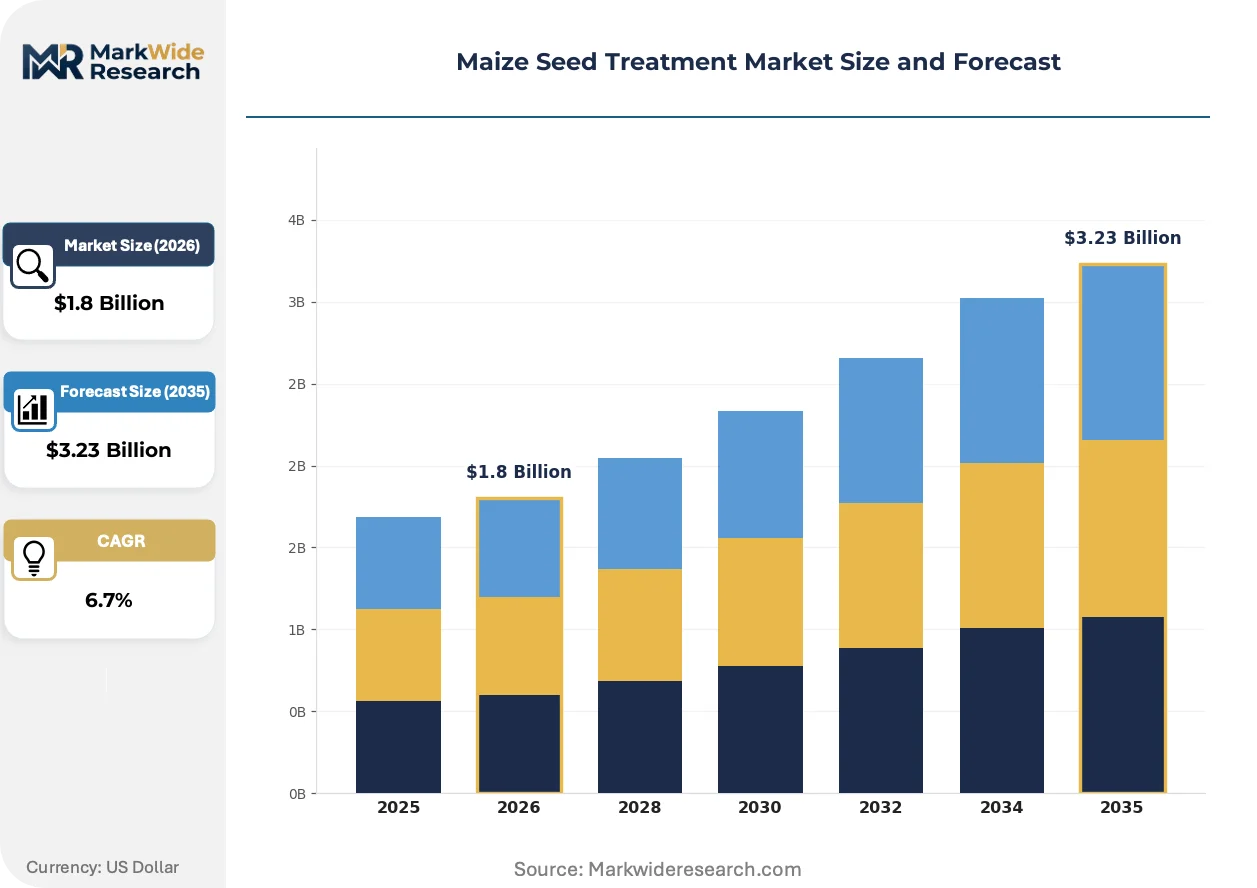
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pesticides, Fungicides, Inoculants, Growth Regulators Application: Seed Coating, Soil Treatment, Foliar Application, Liquid Treatment End Use Industry: Agriculture, Horticulture, Research Institutions, Commercial Farming Distribution Channel: Online Retail, Distributors, Agricultural Cooperatives, Wholesale Suppliers |
| Companies Covered | BASF SE, Bayer AG, Syngenta, Corteva Agriscience, UPL Limited, Adama Agricultural Solutions, Incotec Group, Valent USA Corporation, Lesaffre, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maize Seed Treatment Market Shifts & Advancements
Digital seed treatment monitoring systems are displacing visual quality control. Remote sensing of coating uniformity and active ingredient distribution is compressing batch rejection rates while enabling real-time process adjustment.
Microencapsulation of Bacillus-based biocontrol agents is virtualizing the biological seed treatment category. Leading cooperatives in Iowa and Mato Grosso are deploying these shelf-stable formulations at commercial scale. The technology is virtualizing supply chain logistics by eliminating cold-chain dependency and extending distribution reach into remote grain belts.
REACH compliance constraints on azole fungicides are redirecting European formulation R&D toward exempt biological actives. ECHA's substance authorization timelines for novel synthetics now exceed 48 months in many categories. German and Dutch seed treatment facilities are retooling blending lines to handle living inoculant cultures alongside conventional chemistries.
Agronomic service bundling is restructuring buyer-supplier relationships. Midwestern cooperatives now specify performance guarantees on early vigor and stand establishment rather than purchasing inputs separately. This shift concentrates procurement authority with technical agronomists and compresses price transparency across treatment tiers.
Maize Seed Treatment Market Segmentation
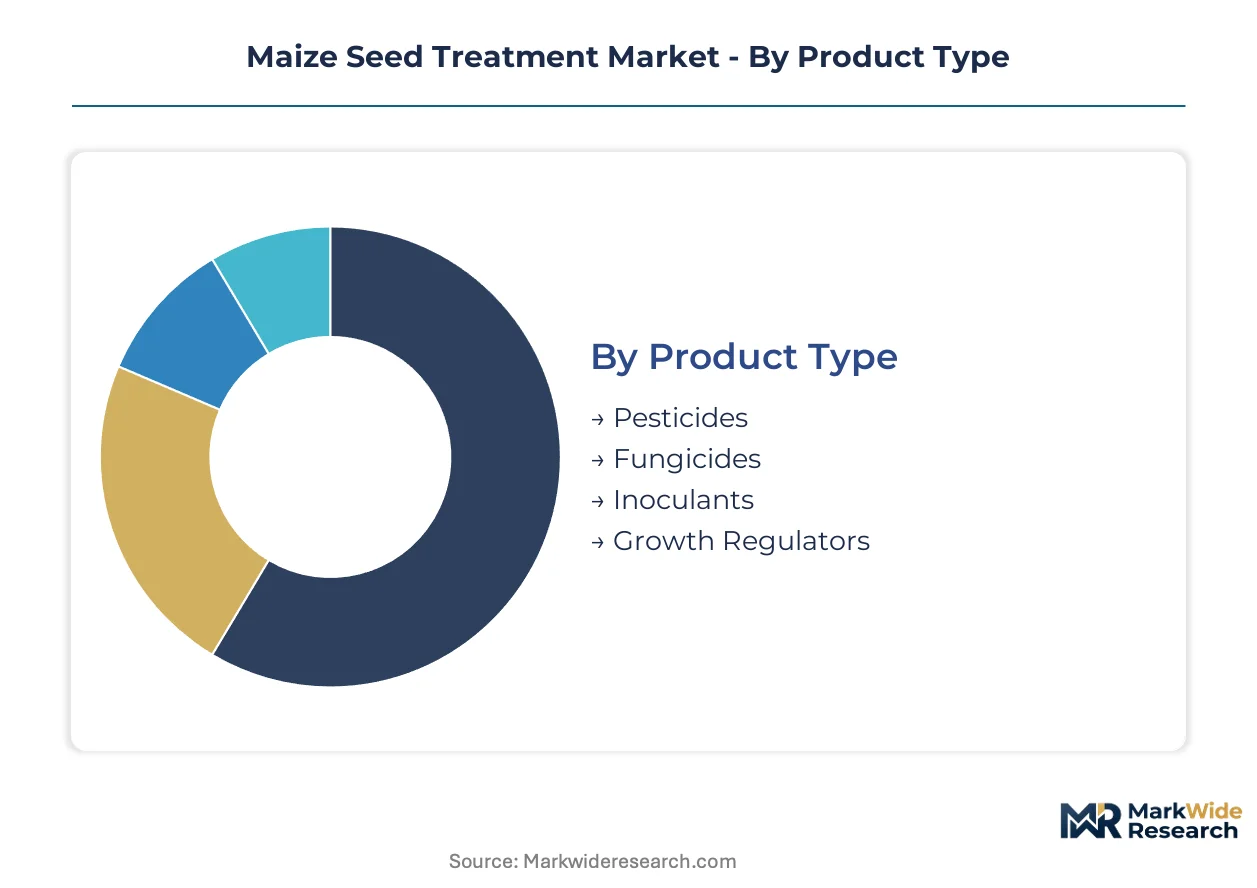
Maize seed treatment segmentation reveals how protection chemistry, application hardware, and procurement channels intersect. Distinct margin pools emerge across synthetic versus biological actives, coating equipment versus liquid systems, and cooperative versus retail distribution.
Product Type:
Cost tiers separate commodity synthetics from premium biological formulations, with R&D intensity and regulatory exposure driving portfolio stratification.
- Pesticides:Neonicotinoid and pyrethroid chemistries dominate volume throughput in conventional corn belts. EPA registration reviews are compressing margins and accelerating phase-out timelines for actives under pollinator scrutiny.
- Fungicides:Azole and strobilurin seed coatings protect germinating embryos from soilborne pathogens like Fusarium and Pythium. REACH authorization constraints in Europe are redirecting formulation investment toward exempt biological alternatives with shorter regulatory pathways.
- Inoculants:Nitrogen-fixing and phosphate-solubilizing microbial formulations targeting regenerative agriculture premiums.
- Growth Regulators:Gibberellin and cytokinin-based treatments optimizing root architecture and early vigor.
Pesticides command the established base. The steepest expansion runs through inoculants.
Application:
Application modality determines equipment compatibility, precision granularity, and labor integration across planting operations.
- Seed Coating:Film-forming polymer binders integrate multiple actives at milligram-per-seed precision for high-speed mechanized planting. Brazil's Cerrado no-till expansion and US Midwest commercial operations concentrate demand for multi-layer coating durability.
- Liquid Treatment:Variable-rate application protocols paired with precision agriculture setups enable field-zone customization. Iowa and Mato Grosso cooperatives are deploying these systems for biological dosing tailored to soil microbiome mapping.
- Soil Treatment:In-furrow delivery of protection chemistry at planting.
- Foliar Application:Post-emergence supplemental treatments addressing mid-season pest pressure.
Seed coating anchors volume throughput. Liquid treatment is climbing the fastest as precision agriculture converges with biological deployment.
End Use Industry:
Customer type dictates performance specifications, price sensitivity, and bundling expectations across the value chain.
- Commercial Farming:Large-scale operations across the US Corn Belt and Brazilian grain belts specify performance guarantees on stand establishment rather than purchasing inputs separately. Procurement concentrates through cooperative channels with technical agronomist oversight.
- Agriculture:Mid-scale independent growers purchasing through distributor networks with extension service guidance.
- Horticulture:Specialty maize varieties for seed production and high-value markets.
- Research Institutions:Experimental treatments for germplasm development and regulatory field trials.
Commercial farming captures the premium tier. Agriculture represents the broadest volume base.
Distribution Channel:
Supply concentration varies sharply between cooperative procurement, distributor networks, and direct digital channels.
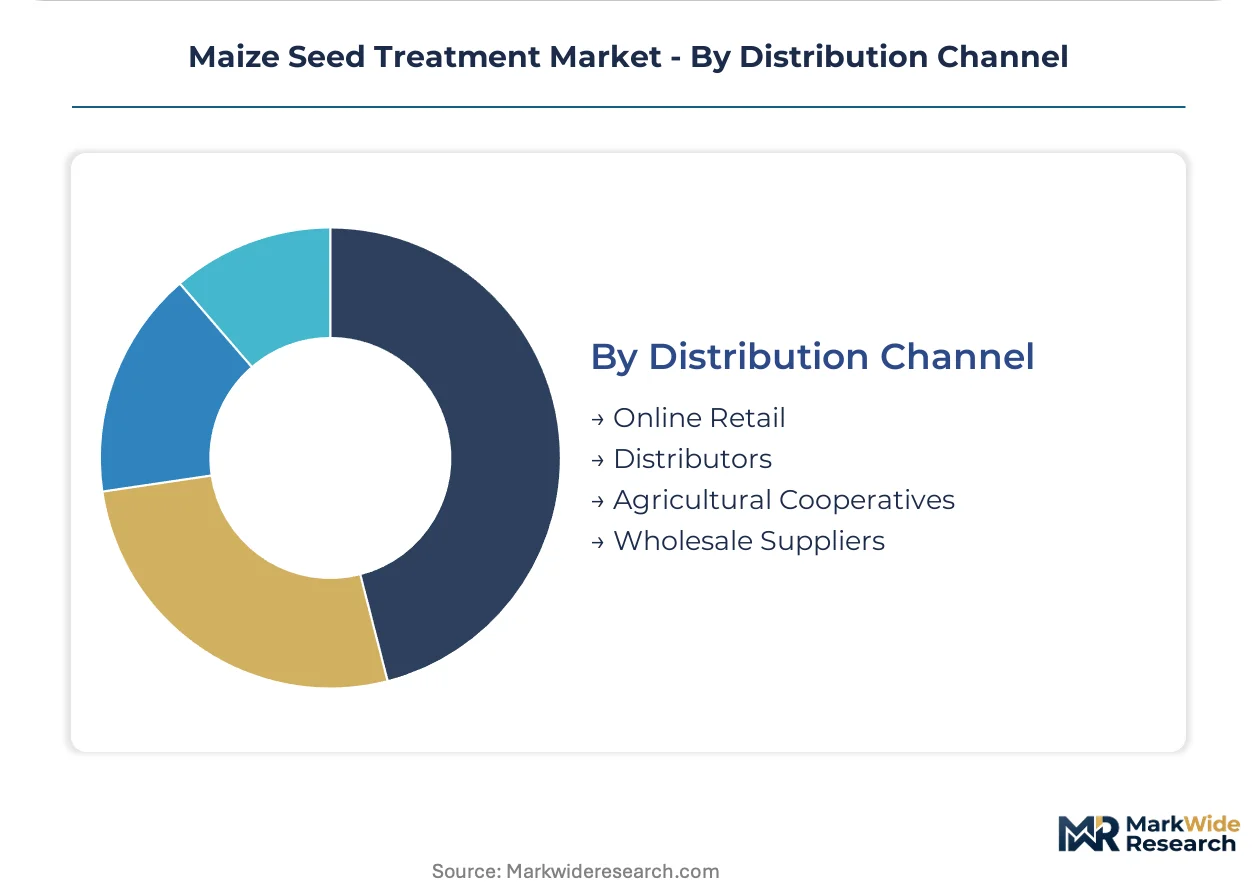
- Agricultural Cooperatives:Bundled seed-plus-treatment packages dominate across the US Midwest and Brazilian grain belts. Technical agronomists concentrate procurement authority and compress price transparency across treatment tiers.
- Distributors:Independent retail networks serving mid-scale growers with credit terms and extension support.
- Online Retail:Direct-to-grower platforms expanding for biological inoculants with extended shelf-life formulations.
- Wholesale Suppliers:Bulk active ingredient and formulation supply to downstream blenders.
Agricultural cooperatives hold the anchored share. Online retail is gaining share fastest as biological shelf-stability extends distribution reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River barge system underwrites North American grain logistics, positioning the United States as the anchor geography for treated seed throughput and formulation R&D concentration.
United States
Commercial farming operations across Iowa and Illinois expand treated seed acreage as climate stress intensifies. The EPA's evolving neonicotinoid review redirects R&D investment toward biological alternatives. Midwestern cooperatives in the Corn Belt concentrate procurement authority for bundled seed-plus-treatment packages.
Brazil
No-till farming systems in the Cerrado expansion zone require premium seed protection packages integrating fungicide-insecticide-biological combinations. ANVISA evaluates import equivalence and local residue limits for treated seed entering frontier croplands. Mato Grosso grain belts deploy precision agriculture setups for field-zone biological dosing.
Germany
REACH compliance constrains certain azole fungicide chemistries, redirecting formulation innovation toward exempt biological actives. ECHA's substance authorization timelines for novel synthetics exceed 48 months. German seed treatment facilities in the Rhine-Ruhr industrial corridor retool blending lines for living inoculant cultures.
India
State procurement programs in Punjab and Haryana drive demand for certified biological seed treatments. BIS certification alignment opens access to maize belt penetration. The Indo-Gangetic Plain sees cooperative channel consolidation for bundled input packages.
Netherlands
EU Green Deal pesticide reduction targets cascade into import standards reshaping competitive access for treated seed exports. Dutch formulation facilities near Rotterdam port clusters specialize in polymer coating technology for multi-active layering. The Randstad region anchors European distribution for biological inoculants with extended shelf-life formulations.
Maize Seed Treatment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in active ingredient supply. The vendor base stratifies between diversified agrochemical conglomerates with seed-treatment divisions and focused biotechnology firms specializing in microbial formulations. Two strategic archetypes dominate: polymer-coating technology platforms enabling multi-layer precision application, and biological inoculant portfolios targeting regenerative agriculture premiums. Competitive moves concentrate on M&A for microbial strain libraries and capacity expansion in Brazil's Cerrado corridor.
Within the diversified agrochemical tier, BASF SE and Bayer AG exemplify platform breadth spanning chemical synthesis through distribution reach. Syngenta occupies a position emphasizing biological inoculant development. These three anchors represent contrasting R&D allocation strategies under regulatory pressure from EPA neonicotinoid reviews and EU Green Deal targets.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta |
| Corteva Agriscience |
| UPL Limited |
| Adama Agricultural Solutions |
| Incotec Group |
| Valent USA Corporation |
| Lesaffre |
| Others |
Supply & Pricing Matrix
Chinese azole fungicide intermediate manufacturers anchor upstream supply concentration, pushing margin pools downstream toward formulation blenders with polymer-coating capabilities and biological inoculant stabilization expertise. Cooperative procurement channels in the US Midwest and Brazilian Cerrado compress price transparency by bundling seed-plus-treatment packages under technical agronomist oversight.
Pricing Analysis
Volume-discount tiering structures separate commodity synthetic coatings from premium biological formulations across cooperative procurement channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales agronomic service bundling. Cost compression in azole fungicide feedstocks intensifies due to Chinese intermediate supply concentration, while biological inoculant tiers show pricing resilience from regenerative agriculture premiums. Mid-scale independent growers through distributor networks exhibit highest price sensitivity; commercial farming cooperatives demonstrate lowest sensitivity given performance guarantee contracting.
Supply Chain Analysis
Extended payment terms from Brazilian and Indian agricultural cooperatives to formulation blenders have become standard working-capital arrangements. Active ingredient synthesis concentrates in China and India, while polymer coating technology and microbial strain development centers in Germany and the Netherlands. Formulation draws from azole fungicide feedstocks, Bacillus-based biocontrol agents, and nitrogen-fixing bacterial cultures. Single-source vulnerability in Chinese intermediate manufacturing creates structural risk exposure. Distribution runs through agricultural cooperative channels with technical agronomist gatekeeping.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities dominate this market as performance guarantees on early vigor and stand establishment expand faster than standalone input sales. Recurring agronomic advisory subscriptions bundled with biological inoculant resupply represent the fastest-growing revenue layer.
For Market Incumbents: Pre-empt biological inoculant shelf-life limitations by acquiring microencapsulation technology platforms that eliminate cold-chain dependency. Defend against precision agriculture entrants by embedding variable-rate liquid treatment equipment into cooperative service contracts. Prioritize backward integration into polymer coating technology to capture multi-active layering premiums. For New Entrants and Emerging Players: India's Punjab and Haryana state procurement programs offer the most penetrable geographic entry point given BIS certification alignment requirements for biological seed treatments. White-space exists in carbon credit stacking services that monetize nitrogen-fixing inoculant adoption through verified emission reduction protocols. Partner with precision agriculture equipment OEMs for field-zone biological dosing integration. For Investors and Strategic Acquirers: Capital is best deployed toward microbial strain library platforms with REACH-exempt biological actives and extended shelf-life formulation capabilities. Long-term viability across the analysis window favors acquisition targets with dual synthetic-biological blending line capacity. Monitor EPA neonicotinoid review timelines as inflection indicators for biological alternative demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Microbial Strain Library Acquisition | Bypasses ECHA's 48-month synthetic substance authorization timelines through REACH-exempt biological pathways. |
| Polymer Coating Capacity Expansion | Captures premium positioning in Brazil's Cerrado no-till systems requiring multi-active durability. |
| Precision Agriculture Partnership | Enables field-zone biological dosing customization through variable-rate liquid treatment equipment integration. |
| Carbon Credit Protocol Development | Monetizes nitrogen-fixing inoculant adoption through regenerative agriculture certification programs. |
| Cold-Chain Elimination Technology | Extends distribution radius into remote grain belts via microencapsulated Bacillus formulation stability. |
Research Methodology
Desk research of EPA registration databases, ANVISA import equivalence filings, and ECHA substance authorization records preceded structured interviews with seed treatment formulation chemists, agricultural cooperative procurement directors, and precision agriculture equipment specialists. Primary fieldwork with microbial strain library curators and polymer R&D directors combined with secondary validation through customs trade data and SEC crop science division filings. Bottom-up volume modeling and top-down value triangulation anchored forecast development.
Assumption sets held regulatory review timelines and climate stress intensity patterns fixed while varying biological adoption rates and cooperative channel consolidation scenarios across the modeling period. Segmentation dimensions spanned active ingredient type, application modality, end-use farming scale, and distribution channel structure. CAGRs derived from weighted average of historical trajectory analysis and diffusion curve modeling for biological inoculant penetration. Forecast inputs incorporated EPA neonicotinoid phase-out scenarios and EU Green Deal pesticide reduction target implementation pace.
Practitioners should monitor EPA registration review acceleration and ECHA substance authorization backlog clearance for early signals of competitive access shifts. Forecasts reflect documented assumptions on regulatory pathway timelines and biological shelf-life technology maturation. Macroeconomic commodity price volatility, pollinator health regulatory stringency, or precision agriculture hardware cost curves would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Processing Innovations
Australia Seed Treatment Market
Seed Processing Innovations
Seed Sorting Machine Market
Seed Processing Innovations
Oilseed Processing Market
Seed Processing Innovations
North America Soybean Seed Treatment Market
Seed Processing Innovations
Argentina Seed Treatment Market
Seed Processing Innovations
South America Seed Treatment Market
Seed Processing Innovations
Rice Seed Treatment Market
Seed Processing Innovations
Alfalfa Seed Extract Market
Seed Processing Innovations
Kiwi Seed Extract Market
Seed Processing Innovations
Asia-Pacific Seed Treatment Market
Seed Processing Innovations
United States Seed Treatment Market
Seed Processing Innovations
Soybean Seed Treatment Market
Seed Processing Innovations
Sprouted Durum Wheat for Pasta Applications Market
Seed Processing Innovations
India Seed and Grain Cleaning and Grading Machine Market
Seed Processing Innovations
Fenugreek Seed Extract Market
Seed Processing Innovations
North America Seed Treatment Market