
 Italy Seed Treatment Market | 2026-2036
Italy Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Seed Treatment Market Foresight
Subscription-based precision application services is restructuring how Italian distributors monetize seed treatment, shifting revenue from product sales to per-hectare service agreements. Bayer Crop Science anchors this transition through digital agronomy platforms bundled with coating services. BASF SE leverages its Ludwigshafen R&D pipeline to sustain fungicide innovation leadership. Syngenta International AG competes via biological nematicide portfolios tailored to Mediterranean soil profiles.
Italy Seed Treatment encompasses chemical and biological formulations applied to seeds before planting to protect against soil-borne pathogens, insect pests, and nematodes while enhancing germination rates, typically involving active ingredients such as neonicotinoids, thiram, or Trichoderma species at application rates of grams per kilogram of seed. The practice reduces early-season crop losses and minimizes field-spray requirements across intensive Italian agriculture. Fungicide coatings occupy the dominant margin pool given wet spring conditions in northern growing regions, while bio-stimulant formulations represent the fastest-expanding segment as Italian organic acreage expands under EU Green Deal targets. Liquid formulations lead volume due to compatibility with high-speed coating equipment prevalent in Po Valley conditioning facilities.
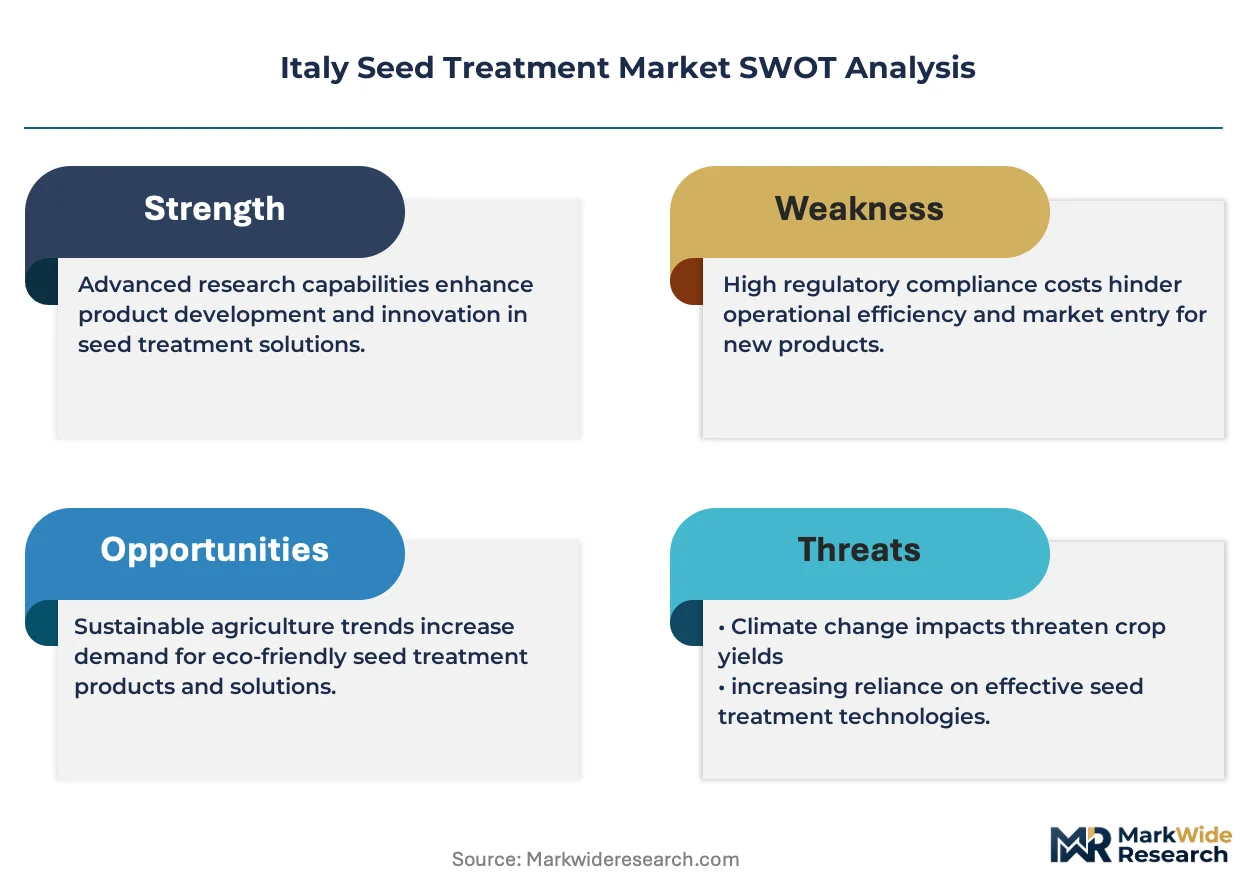
Italy's Ministry of Health enforces EU MDR-aligned agrochemical residue limits, while the national framework transposes REACH and F-Gas Regulation provisions governing active ingredient registration and neonicotinoid restrictions. These rules elevate compliance costs for chemical treatments while creating preferential market access for biological alternatives meeting EFSA safety thresholds. Stakeholders must monitor pending EU AI Act implementations affecting drone-based precision application systems and anticipate how CSRD sustainability reporting will reshape procurement criteria among Italian agricultural cooperatives.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing chemical seed treatment margins while accelerating biological formulation R&D investment across Italian cooperatives and Po Valley conditioning facilities.
Growth Catalysts
- Neonicotinoid restrictions under EU F-Gas Regulation:The phasedown of systemic insecticides creates immediate replacement demand for biological nematicides and bio-stimulant coatings among Emilia-Romagna cereal growers.
- Precision application drone fleets:Agricultural service providers in Lombardy deploy UAV-mounted coating systems that reduce labor costs and enable variable-rate seed treatment across irregular field geometries.
- Organic acreage expansion mandates:Italy's national organic conversion targets under EU Green Deal commitments require certified biological seed inputs for compliance, driving cooperative procurement shifts.
Market Restraints
- Active ingredient registration costs:REACH compliance timelines and EFSA safety threshold documentation impose capital requirements that exclude smaller domestic formulators from chemical product pipelines.
- Biological formulation stability:Trichoderma species and bacterial inoculants exhibit shelf-life degradation in Mediterranean temperature conditions, limiting distribution radius from production facilities.
- Copper-based fungicide substitution limits:Organic certification standards cap copper application rates, constraining disease control efficacy in wet spring conditions across northern growing regions.
Strategic Opportunities
- Subscription service models:Per-hectare coating agreements bundled with digital agronomy platforms enable Italian distributors to capture recurring revenue from precision agriculture adoption.
- Southern region underpenetration:Puglia and Sicily specialty vegetable seed markets remain underserved by high-speed liquid coating infrastructure concentrated in the Po Valley corridor.
- CSRD sustainability reporting alignment:Agricultural cooperatives sourcing EFSA-certified biological treatments gain procurement preference from food processors facing supply chain disclosure mandates.
Industry Challenges
- Formulation chemist scarcity:Italian universities produce limited graduates with dual expertise in agrochemistry and biological fermentation processes required for next-generation coating development.
- Legacy equipment retrofit costs:Po Valley conditioning facilities must upgrade dust containment and precision metering systems to handle low-dose biological formulations without cross-contamination.
- Drone operator certification delays:Pending EU AI Act implementations for autonomous aerial application systems create regulatory uncertainty for service providers scaling precision coating fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Seed Treatment Market |
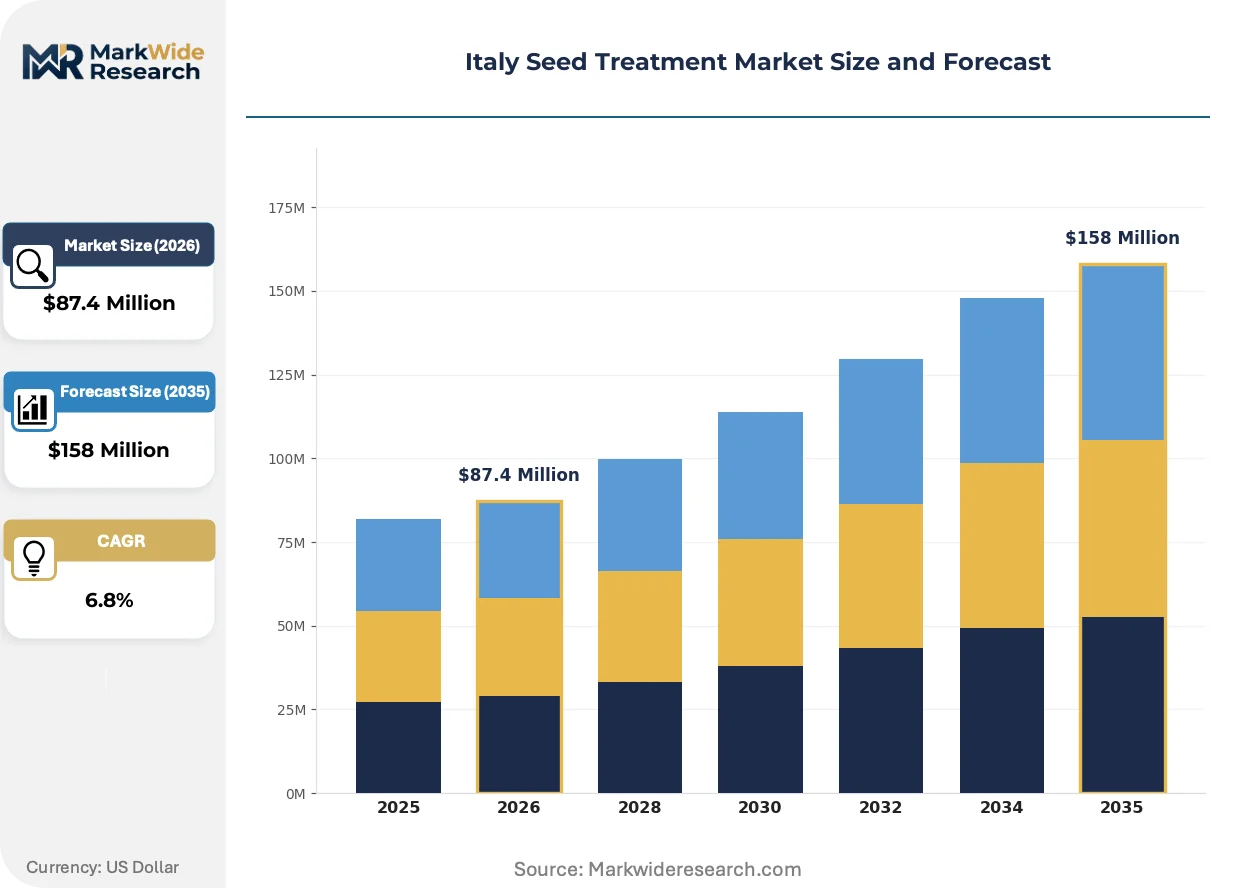
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fungicides, Insecticides, Nematicides, Bio-stimulants Formulation Type: Granules, Liquids, Pellets, Coatings Application Method: Soil Drench, Seed Coating, Foliar Spray, Precision Application Crop Type: Cereal, Vegetables, Fruits, Pulses |
| Companies Covered | BASF SE, Bayer Crop Science AG, Syngenta International AG, FMC Corporation, Sumitomo Chemical Co Ltd, ADAMA Agricultural Solutions Ltd, Nufarm Limited, DuPont de Nemours Inc, Almo SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Seed Treatment Market Shifts & Advancements
Biological seed coating technologies are displacing chemical formulations as the primary innovation vector, while regulatory compliance automation and cooperative procurement centralization reshape competitive positioning across Italian agriculture.
Microbial inoculant coatings containing Trichoderma harzianum and Bacillus subtilis strains provide nitrogen fixation and induced systemic resistance in cereal crops. Po Valley cooperatives adopt these formulations at accelerating rates for winter wheat and maize programs. The technology is expanding into specialty vegetable seed segments previously dominated by synthetic fungicide treatments.
Italy's transposition of EU MDR-aligned residue limits and REACH registration requirements elevates compliance documentation burdens for chemical active ingredients. Formulators redirect R&D investment toward biological pipelines meeting EFSA safety thresholds. Northern Italian conditioning facilities face the steepest adaptation costs given their historical concentration in synthetic coating services.
Agronomic service bundling now dominates distributor revenue models across Emilia-Romagna and Lombardy. Per-hectare treatment agreements replace transactional product sales as cooperatives consolidate procurement through integrated supply platforms. This restructuring concentrates vendor relationships among digital-capable suppliers capable of delivering outcome-based performance guarantees.
Italy Seed Treatment Market Segmentation
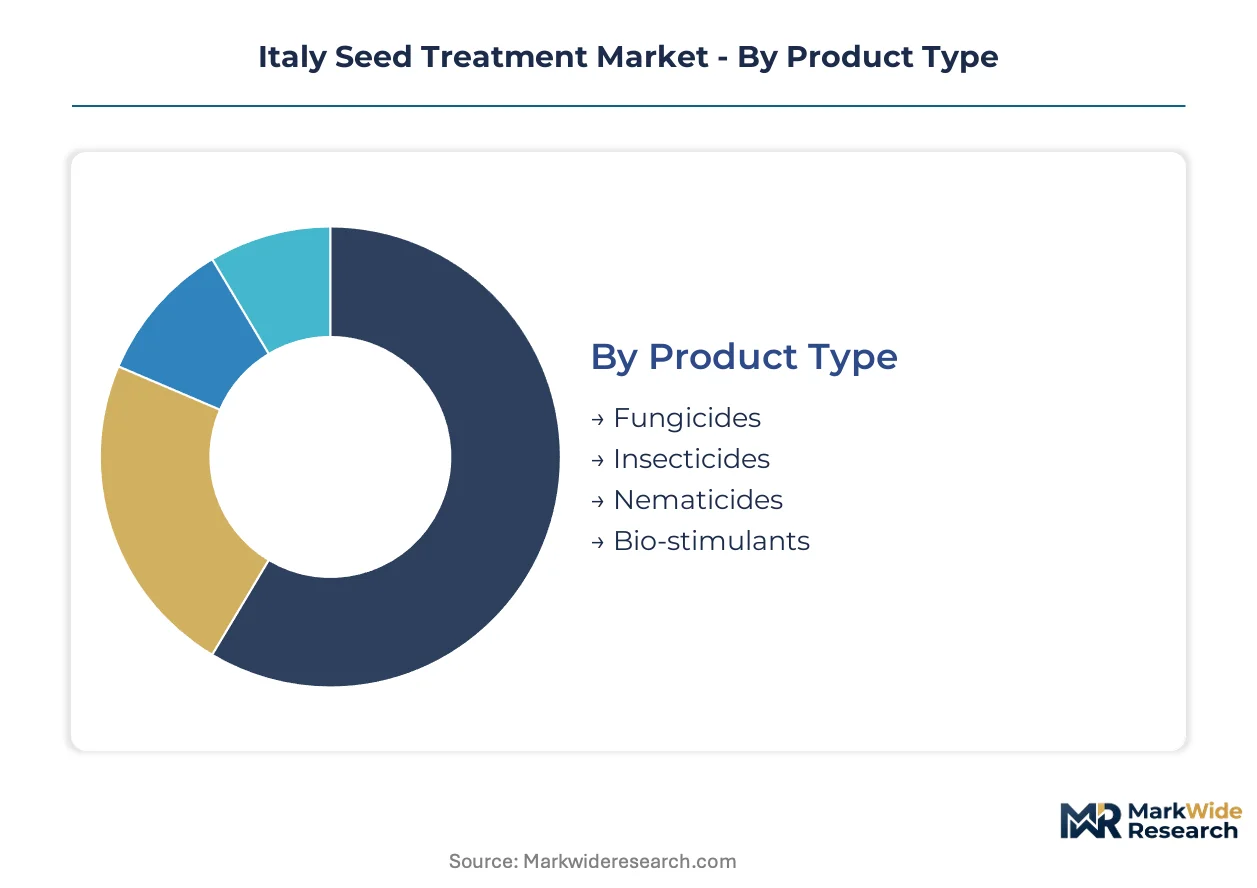
Seed treatment segmentation in Italy reflects divergent technical requirements across crop protection chemistry, physical delivery systems, and precision agriculture adoption. Cooperatives in the Po Valley corridor select formulations based on equipment compatibility and regulatory compliance pathways under EU Green Deal mandates.
Product Type:
Fungicide formulations dominate margin capture given wet spring disease pressure across Emilia-Romagna and Lombardy cereal production zones.
- Fungicides:Thiram-based and triazole formulations protect against Pythium and Fusarium soil-borne pathogens in winter wheat and maize programs. Demand concentrates in Po Valley cooperatives managing high-value seed conditioning operations where germination rate guarantees determine procurement decisions.
- Insecticides:Neonicotinoid-restricted markets drive replacement chemistry development, with pyrethroid and biological alternatives gaining traction in Lombardy vegetable seed programs. Regulatory compression under EU F-Gas Regulation accelerates formulation transitions among distributors serving organic conversion targets.
- Nematicides:Biological nematicide portfolios containing Purpureocillium lilacinum target Mediterranean soil nematode pressure in Puglia tomato and pepper seed segments.
- Bio-stimulants:Trichoderma and Bacillus subtilis inoculants represent the steepest expansion trajectory as EFSA-certified biological inputs satisfy organic certification requirements under national conversion mandates.
Mature deployment sits with fungicide coatings. Newer deployment is concentrated in bio-stimulant formulations.
Formulation Type:
Physical state determines equipment compatibility and active ingredient stability across Italy's regional conditioning infrastructure.
- Liquids:Suspension concentrates and flowable formulations enable high-speed coating equipment operation at Po Valley central conditioning facilities. Volume leadership reflects compatibility with automated metering systems and reduced dust exposure versus dry alternatives.
- Coatings:Polymer-based film coatings provide controlled-release characteristics for sensitive biological actives in organic cereal programs. Emilia-Romagna cooperatives specify coating thickness parameters to ensure seed flowability through precision planters.
- Granules:Clay-based carriers suit low-volume vegetable seed treatments in southern region operations lacking liquid handling infrastructure.
- Pellets:Pelleting formulations encapsulate small-seeded vegetable varieties for mechanized planting in Sicily specialty crop zones.
Established volume flows through liquid systems. Emerging adoption clusters around advanced coating technologies.
Application Method:
Delivery mechanism selection tracks labor cost pressures and field geometry complexity across Italian agricultural service models.
- Seed Coating:Pre-plant coating at conditioning facilities remains the standard for cereal and pulse programs, with Po Valley cooperatives operating centralized treatment lines serving multiple member farms.
- Precision Application:UAV-mounted coating systems enable variable-rate treatment across irregular field geometries in Lombardy vineyard and orchard seedling operations. Agricultural service providers deploy drone fleets under per-hectare service agreements.
- Soil Drench:In-furrow liquid applications supplement coated seed protection in high-pathogen-pressure vegetable transplant systems.
- Foliar Spray:Post-emergence treatment of seedling crops addresses gaps in seed-applied protection for organic conversion programs in southern regions.
Conventional deployment centers on conditioning facility coating. Service model innovation is expanding fastest through precision application.
Crop Type:
Crop-specific protection requirements drive formulation selection and pricing differentiation across Italy's agricultural value chain.
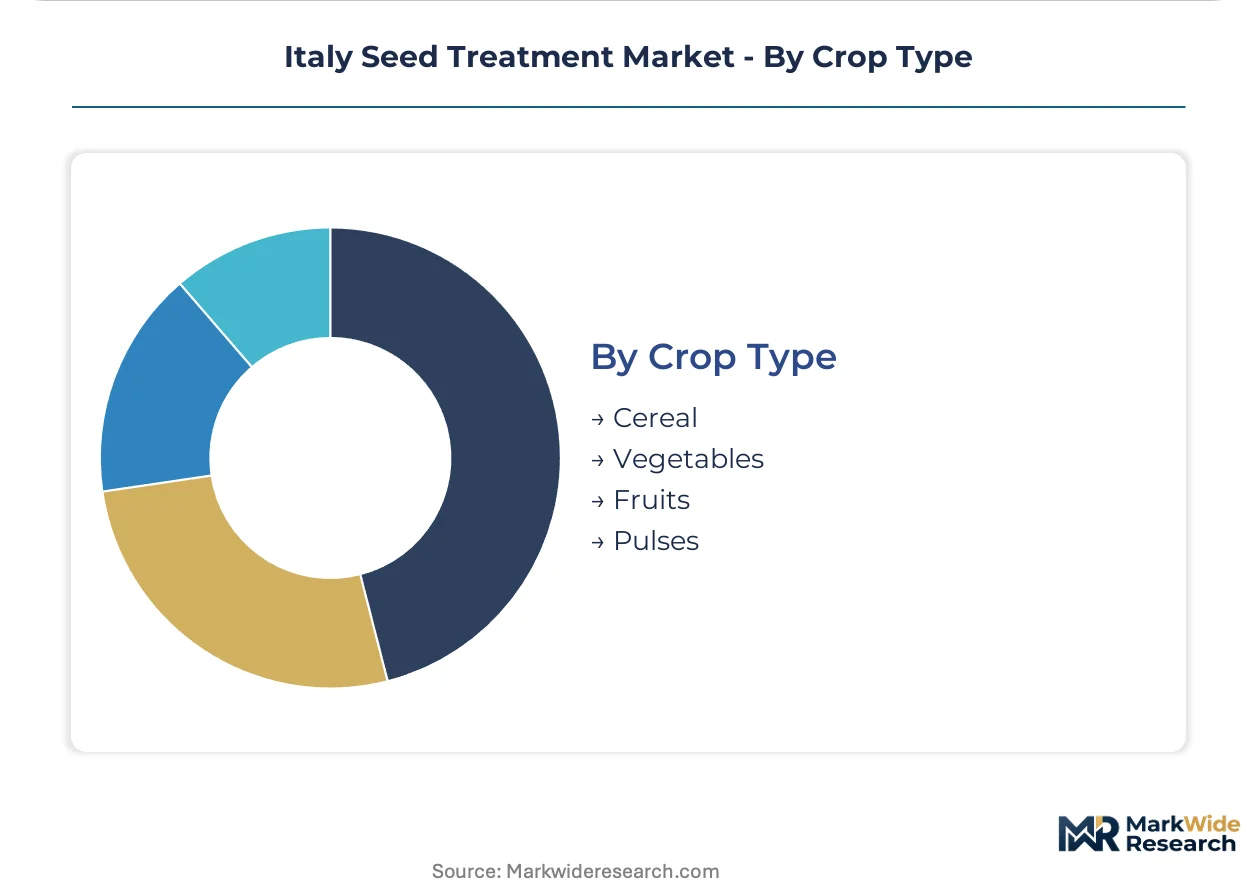
- Cereal:Winter wheat and maize programs in the Po Valley corridor generate the highest treatment volumes, with fungicide-bio-stimulant combination coatings standard for certified seed production.
- Vegetables:Tomato, pepper, and leafy green seed treatments in Puglia and Sicily demand specialized nematicide and biological formulations for protected cultivation systems.
- Fruits:Rootstock treatments for stone fruit and citrus nurseries in Calabria and Sicily require distinct pathogen protection profiles versus field crop programs.
- Pulses:Chickpea and lentil seed treatments in Apennine foothill zones address specific Rhizobium inoculation and fungal protection requirements.
Volume concentration remains with cereal programs. Fastest portfolio diversification is occurring in vegetable segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian seed treatment demand concentrates in northern production zones while southern regions remain structurally underpenetrated. Po Valley conditioning facilities process the majority of national cereal seed volumes. Regulatory pressure from Brussels reshapes regional competitive dynamics.
Lombardy
Winter wheat and maize programs drive fungicide coating volumes across the Pianura Padana. EFSA safety thresholds govern active ingredient approvals for regional conditioning cooperatives. Milan-based distributors deploy UAV-mounted precision application systems for vineyard seedling operations.
Emilia-Romagna
High-value vegetable seed production generates specialized nematicide demand for protected cultivation systems. REACH registration timelines delay chemical product introductions among Bologna-area formulators. Ravenna corridor facilities upgrade dust containment infrastructure for biological formulation handling.
Veneto
Organic conversion targets accelerate bio-stimulant procurement across Verona and Padua cereal cooperatives. EU Green Deal Farm to Fork mandates reshape input sourcing criteria. Vicenza conditioning plants retrofit liquid metering equipment for low-dose microbial inoculants.
Piedmont
Specialty crop seed treatments for wine grape rootstocks sustain niche formulation demand. Neonicotinoid restrictions under EU F-Gas Regulation compress conventional insecticide margins. Turin-area agricultural service providers pilot subscription-based per-hectare coating agreements.
Puglia
Tomato and pepper seed segments remain underserved by high-speed liquid coating infrastructure concentrated in the north. EFSA-certified biological inputs gain procurement preference under national organic mandates. Bari-area distributors face distribution radius constraints from biological formulation stability limitations.
Italy Seed Treatment Market Competitive Landscape
Top-tier vendors anchor integrated supply platforms, while regional formulators occupy specialized biological niches. Three strategic archetypes dominate: multinational agrochemical conglomerates with digital bundling capabilities, mid-scale biological specialists with EFSA certification pathways, and cooperative-owned conditioning operators with captive demand bases. Competitive moves center on portfolio diversification toward biological pipelines and backward integration into microbial fermentation capacity.
Within the multinational tier, Bayer Crop Science AG, BASF SE, and Syngenta International AG exemplify divergent strategic positioning. Bayer Crop Science AG anchors subscription service models through digital agronomy platform bundling. BASF SE occupies fungicide innovation leadership via centralized R&D pipeline control. Syngenta International AG represents biological nematicide specialization calibrated to Mediterranean soil profiles. These three entities structure competitive intensity across Po Valley cooperative procurement decisions.
| Leading Market Players |
|---|
| BASF SE |
| Bayer Crop Science AG |
| Syngenta International AG |
| FMC Corporation |
| Sumitomo Chemical Co Ltd |
| ADAMA Agricultural Solutions Ltd |
| Nufarm Limited |
| DuPont de Nemours Inc |
| Almo SpA |
| Others |
Supply & Pricing Matrix
Neonicotinoid active ingredient prices, tracked through ECHA registration cost benchmarks, cascade through Italian formulator margins into three distinct procurement tiers serving Po Valley cooperatives, mid-scale distributors, and southern region operators lacking liquid coating infrastructure.
Pricing Analysis
Margin tightening in chemical fungicide tiers reflects REACH compliance documentation burdens and EFSA safety threshold testing costs that smaller domestic formulators cannot absorb. Three-tier pricing structure across premium EFSA-certified biologicals, standard synthetic coatings, and economy copper-based alternatives separates procurement budgets. Price differentiation hinges on certification grade and volume scale. Agricultural cooperatives in Lombardy exhibit lowest price sensitivity due to outcome-based performance guarantees, while Puglia vegetable growers face acute cost pressure from biological formulation stability limitations.
Supply Chain Analysis
Italy's transposition of EU Green Deal domestic-content preferences for biological inputs reshapes sourcing patterns among Po Valley conditioning facilities. Active ingredient supply concentrates in Germany, Switzerland, and domestic fermentation facilities near Milan. Formulation chemists and microbial inoculant strains constitute critical input dependencies. Single-source vulnerability sits with Trichoderma harzianum strain suppliers serving organic conversion programs. Distribution runs through cooperative-owned central conditioning facilities with captive member demand, supplemented by agricultural service providers deploying UAV-mounted precision application fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy seed treatment is consolidating around biological certification capabilities as EU F-Gas Regulation and Farm to Fork mandates force out chemical-dependent smaller formulators lacking EFSA pathway investment capacity.
For Market Incumbents: Lock in cooperative procurement relationships through subscription-based per-hectare service agreements bundled with digital agronomy platforms. Backward integration into microbial fermentation capacity secures strain supply against biological nematicide demand surges. Prioritize EFSA safety threshold documentation investment ahead of pending regulatory implementations. For New Entrants and Emerging Players: The price-point gap between premium Bayer Crop Science subscription tiers and economy copper-based fungicide alternatives creates entry space for mid-tier biological specialists. Southern region vegetable seed markets in Puglia and Sicily present the most penetrable geography given liquid coating infrastructure underinvestment. Pursue EFSA certification pathways for Trichoderma-based formulations as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors biological formulation specialists with existing EFSA safety clearances and captive fermentation assets. Mid-cap targets with dual expertise in agrochemistry and microbial process engineering offer strongest long-term viability as chemical margins compress. Watch for EU AI Act implementation clarity on drone operator certification as the signal for precision application service scalability.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Safety Certification Investment | Biological formulators gain preferential procurement access under Farm to Fork mandates. |
| Microbial Fermentation Capacity Buildout | In-house strain production reduces dependency on German and Swiss suppliers. |
| UAV Fleet Certification Pathway | Drone operators secure regulatory clarity for precision coating service scaling. |
| Cooperative Procurement Platform Integration | Distributors capture recurring revenue through per-hectare subscription agreements. |
| Southern Region Distribution Partnership | Liquid coating infrastructure gaps in Puglia create first-mover expansion opportunity. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with Po Valley cooperative procurement managers, conditioning facility operators, EFSA regulatory affairs specialists, and agricultural drone service providers. Secondary sources included ECHA registration databases, EU MDR transposition documents, Italian Ministry of Health agrochemical residue bulletins, and seed industry association production statistics. Bottom-up volume estimates from regional conditioning facility throughput triangulated against top-down market sizing from active ingredient import flows.
Data-stream reconciliation across product type, formulation state, application method, and crop-specific protection requirements generated segment-level projections across the analysis window. CAGRs were derived from trend extrapolation of biological formulation adoption curves and regulatory phase-out timelines for restricted chemistries. Forecast inputs incorporated EU Green Deal organic acreage conversion targets and precision agriculture penetration rates among Lombardy agricultural service providers.
Inputs from EFSA safety assessment databases and cooperative procurement surveys were available through the study window; gaps in real-time biological formulation shelf-life degradation data introduce uncertainty bands around southern region distribution radius estimates. Forecasts reflect documented assumptions regarding regulatory implementation pacing and technology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Processing Innovations
Sprouted Durum Wheat for Pasta Applications Market
Seed Processing Innovations
United States Seed Treatment Market
Seed Processing Innovations
North America Soybean Seed Treatment Market
Seed Processing Innovations
Australia Seed Treatment Market
Seed Processing Innovations
South America Seed Treatment Market
Seed Processing Innovations
Fenugreek Seed Extract Market
Seed Processing Innovations
Seed Sorting Machine Market
Seed Processing Innovations
Oilseed Processing Market
Seed Processing Innovations
India Seed and Grain Cleaning and Grading Machine Market
Seed Processing Innovations
Argentina Seed Treatment Market
Seed Processing Innovations
Soybean Seed Treatment Market
Seed Processing Innovations
Rice Seed Treatment Market
Seed Processing Innovations
Maize Seed Treatment Market
Seed Processing Innovations
Alfalfa Seed Extract Market
Seed Processing Innovations
Brazil Seed Treatment Market
Seed Processing Innovations
North America Seed Treatment Market