
 Sprouted Durum Wheat for Pasta Applications Market | 2026-2036
Sprouted Durum Wheat for Pasta Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Sprouted Durum Wheat for Pasta Applications Market Insights
Premium whole-grain specification tiers is unwinding conventional commodity positioning across the sprouted durum wheat value chain. Bay State Milling leverages its North American milling infrastructure to secure consistent supply for specialty pasta brands. King Arthur Baking Company anchors premium retail positioning through rigorous sprouting protocol transparency. One Degree Organics differentiates via certified organic supply chains that trace back to individual farm sources.
Sprouted durum wheat for pasta applications denotes durum wheat subjected to controlled germination before milling, typically achieving 0.8–1.2 mm sprout length and reduced phytic acid content, producing semolina with altered enzyme activity and modified starch gelatinization properties suited to fresh and extruded pasta formats. Organic sprouted durum commands the dominant value share as clean-label pasta manufacturers prioritize certified inputs, while gluten-free sprouted durum represents the fastest-expanding product type amid celiac-safe formulation demand. Fresh pasta applications absorb the highest volume of premium sprouted durum as artisan producers emphasize enzymatic activity for superior texture, though dry pasta channels offer larger absolute tonnage potential through scaled retail distribution.
USDA organic certification and FDA food safety modernization rules govern sprouted grain processing standards in the United States, while the EU's EFSA evaluates novel enzyme claims in sprouted cereal products under health claim regulations. These frameworks elevate compliance costs for sprouted durum suppliers but simultaneously create market access barriers that favor established certified operators. Stakeholders must monitor evolving mycotoxin thresholds for sprouted grains and assess whether regenerative agriculture certifications will become a mandatory procurement filter for major pasta manufacturers.

Market Dynamics
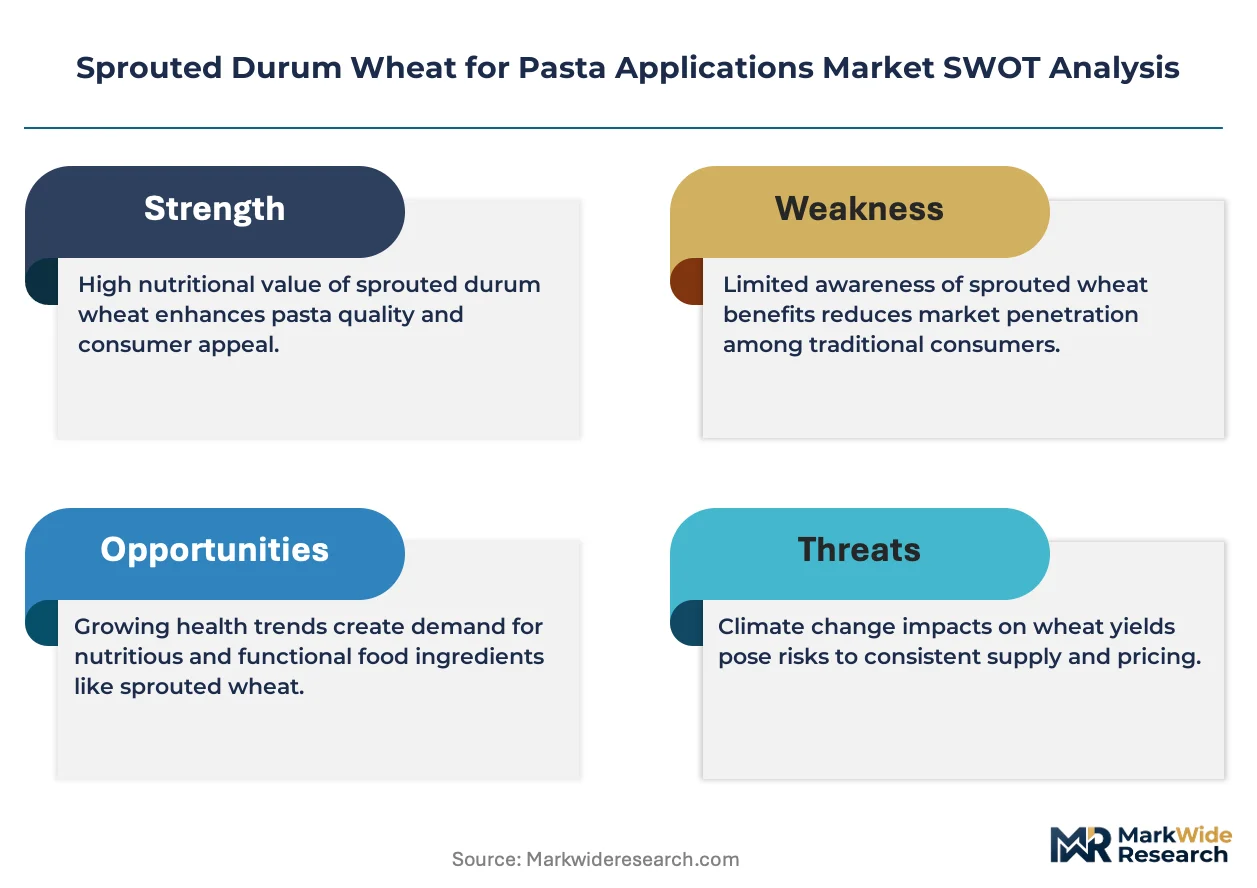
The EU's Farm to Fork strategy is compressing conventional commodity margins as pasta manufacturers face binding sustainability benchmarks for certified ingredient procurement. This regulatory pressure is concentrating demand around sprouted durum suppliers capable of demonstrating regenerative agriculture compliance and transparent supply chain documentation.
Growth Catalysts
- Clean-label certification mandates:The European Green Deal's sustainability disclosure requirements are forcing traditional pasta brands to reformulate with traceable sprouted inputs that meet EFSA novel enzyme evaluation standards.
- Enzymatic texture innovation:Artisan fresh pasta producers are leveraging modified starch gelatinization properties in sprouted semolina to achieve superior mouthfeel without additive use.
- Italy:Domestic manufacturers facing consumer pressure for ingredient deck transparency are accelerating procurement of organic sprouted durum for premium product positioning.
Market Restraints
- Input cost volatility:Organic durum wheat premiums fluctuate with weather-driven yield variability across the North American prairie provinces and Italian Puglia region.
- Supply concentration risk:Certified organic sprouting capacity clusters among a limited set of North American millers with validated food safety modernization protocols.
- Technical limitation:Controlled germination achieving precise 0.8–1.2 mm sprout length requires capital-intensive climate-controlled infrastructure that smaller operators cannot replicate.
Strategic Opportunities
- Underpenetrated retail channel:Direct-to-consumer subscription pasta services in Germany and France represent untapped volume for specialty sprouted durum SKUs.
- Regenerative agriculture certification:The EU's developing soil health verification framework will create first-mover advantage for suppliers documenting carbon-sequestering cultivation practices.
- Gluten-free formulation convergence:Celiac-safe sprouted durum development combined with enzymatic modification technology opens formulation partnerships with European free-from pasta specialists.
Industry Challenges
- Skill scarcity in sprouting protocol management:Food science professionals capable of optimizing phytic acid reduction while preserving enzymatic activity command premium compensation and limited availability.
- Certification timeline compression:USDA organic and EU organic dual certification processes extend procurement lead times by eight to fourteen months for new supplier onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sprouted Durum Wheat for Pasta Applications Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Sprouted Durum, Conventional Sprouted Durum, Fortified Sprouted Durum, Whole Grain Sprouted Durum, Gluten-Free Sprouted Durum Application: Fresh Pasta, Dry Pasta, Ready-to-Cook Pasta, Pasta Snacks, Gluten-Free Pasta End User: Pasta Manufacturers, Foodservice Providers, Retail Chains, Specialty Food Stores, Artisan Producers Packaging Type: Vacuum Packs, Bulk Bags, Retail Boxes, Pouches, Modified Atmosphere Packaging |
| Companies Covered | Bay State Milling, Central Milling, Anita’s Organic Mill, One Degree Organics, Food For Life, KoRo, Narmada Agro Industries, Arrowhead Mills, King Arthur Baking Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sprouted Durum Wheat for Pasta Applications Market Trends and Innovations
Controlled germination technology is fragmenting conventional milling economics as enzyme-active semolina commands pricing premiums unavailable to commodity durum processors. This technological divergence is reshaping supplier qualification criteria across fresh and extruded pasta channels.
Precision sprouting equipment is bifurcating the supplier base between capital-intensive automated systems and manual batch operations. Large-scale North American millers are deploying continuous-flow germination chambers with real-time moisture monitoring, while smaller Italian operators retain artisan positioning through hand-managed sprouting cycles. This equipment divergence is compressing mid-tier suppliers unable to achieve either scale economies or craft premium credentials.
The EU's Corporate Sustainability Reporting Directive is mandating granular Scope 3 emissions disclosure for food manufacturers sourcing cereal inputs. Pasta producers serving European retail channels must now document agricultural upstream impacts or face delisting from sustainability-focused distributors. Italian manufacturers with established regenerative supplier networks are securing preferential shelf placement as retailers preempt compliance risk.
Direct farm contracting is displacing spot-market purchasing as large pasta brands seek supply security for certified organic sprouted durum. Bay State Milling and comparable processors are establishing multi-year cultivation agreements with individual farms, bypassing traditional grain elevators. This procurement restructuring concentrates most visibly in Italy, where Barilla and De Cecco compete for limited organic acreage through guaranteed offtake contracts.
Sprouted Durum Wheat for Pasta Applications Market Segmentation
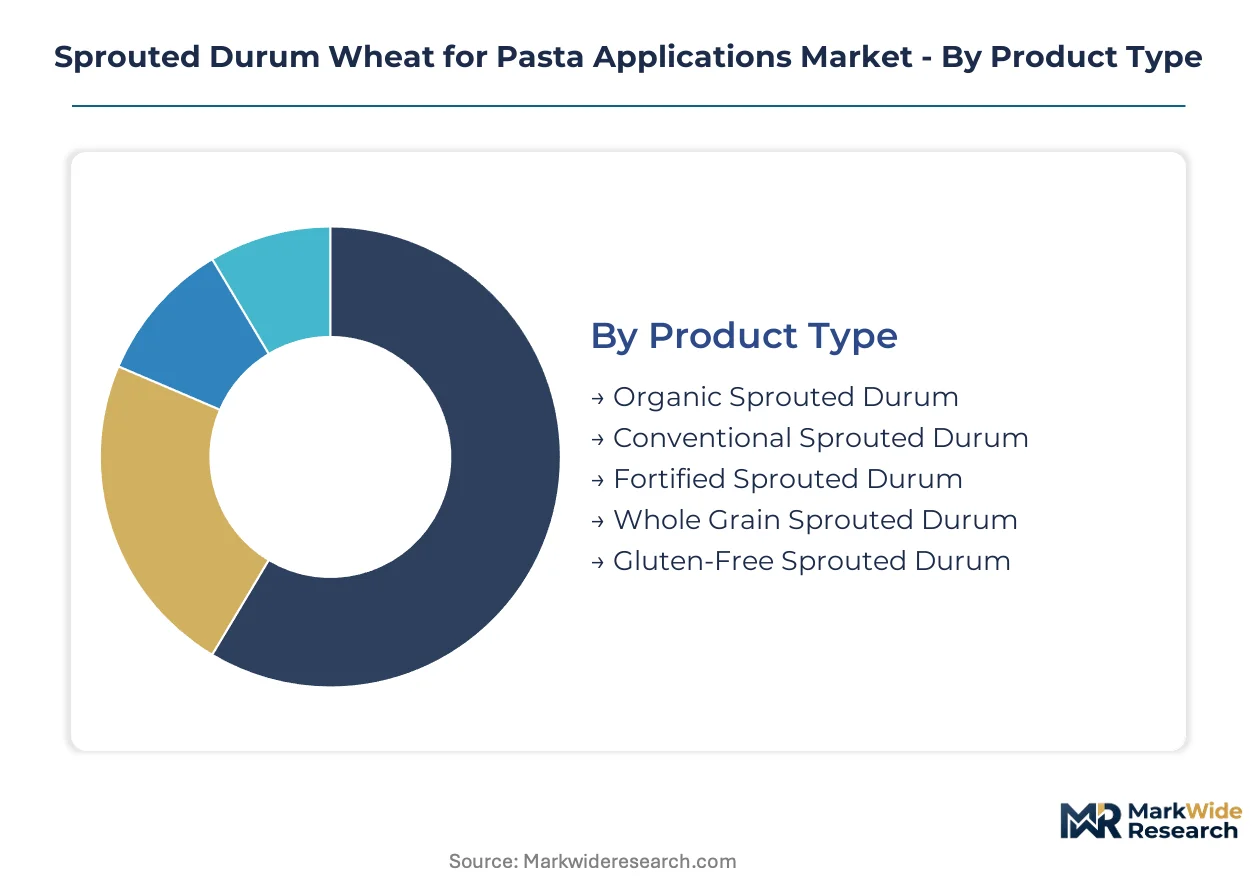
Segmentation in sprouted durum wheat reveals how certification tiers, application formats, and procurement channels create distinct margin pools. Channel alignment determines which segments command premium pricing versus volume throughput.
Product Type:
Channel flow splits sharply between certified organic inputs destined for retail pasta brands and conventional grades serving foodservice bulk contracts.
- Organic Sprouted Durum:USDA and EU organic dual-certified grain with documented germination protocols. Clean-label pasta manufacturers in Italy and North America concentrate procurement here, driven by EFSA disclosure requirements under the EU Green Deal.
- Gluten-Free Sprouted Durum:Enzymatically modified to reduce gluten content while preserving durum functionality. Celiac-safe formulation demand from European free-from specialists represents the segment climbing fastest.
- Conventional Sprouted Durum:Non-certified grain meeting basic sprouting specifications for cost-sensitive pasta applications.
- Fortified Sprouted Durum:Vitamin and mineral enriched variants targeting nutritional positioning in retail channels.
- Whole Grain Sprouted Durum:Bran-inclusive milling for fiber-forward pasta products.
Organic sprouted durum dominates installed base. Gluten-free sprouted durum is where expansion concentrates.
Application:
Fresh pasta channels absorb premium enzyme-active semolina for texture differentiation, while dry pasta scales through retail distribution velocity.
- Fresh Pasta:Refrigerated and frozen formats leveraging modified starch gelatinization for superior mouthfeel. Artisan producers in Italy emphasize enzymatic activity as a clean-label alternative to additives.
- Dry Pasta:Shelf-stable extruded products offering the largest absolute tonnage pathway through scaled retail distribution networks.
- Ready-to-Cook Pasta:Pre-portioned formats with reduced cooking time requirements.
- Pasta Snacks:Baked and extruded snack applications using sprouted durum for nutritional claims.
- Gluten-Free Pasta:Dedicated production lines avoiding cross-contamination for celiac-safe positioning.
Fresh pasta commands premium positioning. Dry pasta offers volume scale.
End User:
Procurement sophistication varies from multi-year cultivation contracts by major manufacturers to spot purchasing by specialty retailers.
- Pasta Manufacturers:Industrial-scale producers with validated food safety modernization protocols and regenerative agriculture compliance documentation.
- Artisan Producers:Small-batch operators emphasizing hand-managed sprouting cycles and transparent farm sourcing for craft premium credentials.
- Foodservice Providers:Restaurant and institutional buyers prioritizing cost efficiency over certification tiers.
- Retail Chains:Supermarket private-label programs requiring consistent supply for shelf-stable pasta lines.
- Specialty Food Stores:Curated assortments focusing on certified organic and single-origin provenance claims.
Pasta manufacturers anchor volume demand. Artisan producers drive premium innovation.
Packaging Type:
Packaging selection tracks shelf-life requirements and retail channel positioning, from oxygen barrier films for extended distribution to minimal formats for local delivery.
- Vacuum Packs:Oxygen-excluded barrier films preserving enzyme activity in fresh pasta formats for extended refrigerated distribution.
- Modified Atmosphere Packaging:Gas-flushed enclosures balancing shelf-life extension with clean-label positioning in premium retail.
- Bulk Bags:Foodservice and industrial totes for high-volume pasta manufacturing operations.
- Retail Boxes:Shelf-ready cartons for dry pasta supermarket placement.
- Pouches:Flexible stand-up formats for ready-to-cook and snack pasta applications.
Vacuum packs dominate fresh pasta logistics. Modified atmosphere packaging is gaining fastest in premium retail.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian sprouted durum processors supply premium semolina to North American artisan pasta brands, establishing the dominant transatlantic trade corridor in specialty grain inputs.
Italy
Traditional pasta manufacturers in Emilia-Romagna and Puglia face consumer pressure for clean-label ingredient decks. The EU's Farm to Fork strategy under the European Green Deal tightens sustainability benchmarks for cereal processing. Barilla and De Cecco compete for limited organic acreage through guaranteed offtake contracts across the Italian peninsula.
United States
Artisan pasta producers in California and New York expand procurement of sprouted durum for premium product lines. USDA organic certification and FDA food safety modernization rules govern sprouted grain processing standards. Bay State Milling leverages North American milling infrastructure to secure consistent supply for specialty pasta brands in the Northeast corridor.
Canada
Organic durum wheat premiums fluctuate with weather-driven yield variability across the prairie provinces. The Canadian Food Inspection Agency enforces grain quality standards aligned with international export requirements. Saskatchewan and Manitoba organic grain cooperatives supply North American millers with certified sprouting-grade durum.
Germany
Direct-to-consumer subscription pasta services represent untapped volume for specialty sprouted durum SKUs. The EU's Corporate Sustainability Reporting Directive mandates granular Scope 3 emissions disclosure for food manufacturers. Berlin and Munich-based foodtech startups pilot regenerative agriculture verification frameworks for pasta supply chains.
India
Narmada Agro Industries and comparable processors serve domestic and export markets for value-added grain products. FSSAI food safety regulations govern sprouted grain processing for commercial distribution. Gujarat and Maharashtra agricultural zones cultivate durum wheat varieties suited to controlled germination protocols.
Sprouted Durum Wheat for Pasta Applications Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and milling scale. The supplier base concentrates around North American millers with validated food safety modernization protocols, while mid-tier operators face compression from capital-intensive automated systems and artisan craft positioning. Three archetypes dominate: large-scale certified organic processors, regional specialty millers, and direct-farm-traceable organic specialists. Competitive moves center on multi-year cultivation agreements bypassing traditional grain elevators, and precision sprouting equipment deployment achieving continuous-flow germination.
Within the certified organic tier, One Degree Organics and King Arthur Baking Company exemplify supply chain transparency strategies, while Bay State Milling anchors the scale-driven segment with North American infrastructure coverage. These three entities represent divergent positioning vectors—farm-traceable certification, retail brand premiumization, and industrial-scale supply security—without overlapping core competencies.
| Leading Market Players |
|---|
| Bay State Milling |
| Central Milling |
| Anita's Organic Mill |
| One Degree Organics |
| Food For Life |
| KoRo |
| Narmada Agro Industries |
| Arrowhead Mills |
| King Arthur Baking Company |
| Others |
Pricing and Supply Chain Analysis
USDA organic certification gates both supply qualification and price differentiation simultaneously, forcing pasta manufacturers to absorb dual-certification timelines while commanding premiums for traceable inputs. This regulatory filter concentrates pricing power among North American millers with validated food safety modernization protocols, compressing margins for uncertified operators unable to meet EFSA novel enzyme evaluation standards.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing, with three-tier pricing structure across premium, standard, and economy levels separating certified organic sprouted durum from conventional grades and gluten-free variants. Price differentiation rests on certification tier and volume scale, with organic dual-certified grain commanding substantial premiums over non-certified alternatives. Cost compression in conventional grades is intensifying because weather-driven yield variability across North American prairie provinces and Italian Puglia region destabilizes input costs. Foodservice providers exhibit highest price sensitivity, while artisan pasta manufacturers in Italy demonstrate lowest sensitivity due to clean-label positioning requirements.
Supply Chain Analysis
Just-in-time inventory strategies dominate fresh pasta channels where enzymatic activity degradation risks demand rapid throughput, while strategic stockpiling characterizes dry pasta manufacturers securing multi-year cultivation agreements. Geographic supply concentration centers on the United States, Canada, and Italy, with Saskatchewan and Manitoba organic cooperatives feeding North American millers and Emilia-Romagna processors serving European demand. Raw material dependencies include certified organic durum seed stock, climate-controlled germination infrastructure, and oxygen-barrier packaging films. Single-source vulnerability runs through limited certified organic sprouting capacity clustered among validated North American millers. Distribution runs through direct farm contracting displacing traditional grain elevators, with Bay State Milling and comparable processors establishing guaranteed offtake arrangements bypassing spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as EU Corporate Sustainability Reporting Directive mandates fragment procurement requirements across pasta manufacturers, creating niches for specialized suppliers capable of documenting regenerative agriculture compliance and transparent supply chain provenance.
For Market Incumbents: Fortify supply security through backward integration into certified organic acreage via multi-year cultivation agreements with individual farms, bypassing traditional grain elevators that introduce contamination and documentation risks. Invest in continuous-flow germination chambers with real-time moisture monitoring to achieve scale economies that hand-managed Italian artisan operations cannot replicate, defending against mid-tier compression from capital-intensive automated systems. For New Entrants and Emerging Players: Anchor in direct-to-consumer subscription pasta services across Germany and France, the most penetrable channel where established manufacturers lack specialized SKU development for regenerative agriculture-verified product lines. Target gluten-free sprouted durum formulation partnerships with European free-from pasta specialists, leveraging enzymatic modification technology as a differentiated go-to-market angle absent from incumbent portfolios. For Investors and Strategic Acquirers: EU Farm to Fork strategy implementation milestones reshape the acquisition landscape, elevating valuations for suppliers with documented carbon-sequestering cultivation practices and dual USDA-EU organic certification. Long-term viability across the analysis window favors vertically integrated processors controlling both farm relationships and climate-controlled germination infrastructure. The signal to watch is mycotoxin threshold tightening for sprouted grains, which would trigger consolidation toward established certified operators with validated food safety protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Acreage | Bay State Milling's multi-year farm contracts bypass grain elevator contamination risks and secure supply. |
| Precision Sprouting Equipment Deployment | Continuous-flow germination chambers with real-time moisture monitoring achieve enzymatic consistency artisan batches cannot match. |
| Regenerative Agriculture Certification Investment | Soil health verification frameworks under EU Green Deal create first-mover shelf placement advantages with sustainability-focused retailers. |
| Gluten-Free Formulation Partnership | Celiac-safe enzymatic modification technology opens European free-from pasta channels where conventional durum functionality is preserved. |
| Direct-to-Consumer Channel Development | Subscription pasta services in Germany and France represent white-space volume for specialty sprouted durum SKUs absent from supermarket shelves. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation across regulatory and trade databases. Primary fieldwork engaged milling operations directors, pasta manufacturer procurement leads, organic certification auditors, and food safety compliance officers across North American and European supply chains. Secondary sources included USDA organic certification records, EFSA novel enzyme evaluation filings, EU Farm to Fork strategy implementation documents, and customs trade data for durum wheat flows. Bottom-up volume modeling triangulated against top-down value estimates derived from channel pricing intelligence.
Across the projection horizon, the analytical framework segmented volume and value outputs by certification tier, application format, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to disclosed capacity expansion timelines and cultivation contract volumes. Industry-specific forecast inputs incorporated organic acreage conversion rates and climate-controlled germination infrastructure deployment pipelines.
Material uncertainties — weather-driven yield variability, mycotoxin threshold revisions, and regenerative agriculture certification mandate timing — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained EU Green Deal implementation and stable organic certification reciprocity between USDA and EU frameworks. Revision becomes warranted when organic durum premium volatility crosses thresholds that destabilize multi-year cultivation contract economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Processing Innovations
India Seed and Grain Cleaning and Grading Machine Market
Seed Processing Innovations
Alfalfa Seed Extract Market
Seed Processing Innovations
North America Seed Treatment Market
Seed Processing Innovations
North America Soybean Seed Treatment Market
Seed Processing Innovations
Maize Seed Treatment Market
Seed Processing Innovations
Seed Sorting Machine Market
Seed Processing Innovations
Kiwi Seed Extract Market
Seed Processing Innovations
Oilseed Processing Market
Seed Processing Innovations
United States Seed Treatment Market
Seed Processing Innovations
Italy Seed Treatment Market
Seed Processing Innovations
Soybean Seed Treatment Market
Seed Processing Innovations
Brazil Seed Treatment Market
Seed Processing Innovations
South America Seed Treatment Market
Seed Processing Innovations
Rice Seed Treatment Market
Seed Processing Innovations
Asia-Pacific Seed Treatment Market
Seed Processing Innovations
Argentina Seed Treatment Market