
 South America Seed Treatment Market | 2026-2036
South America Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
South America Seed Treatment Market Analytics
Biological inoculant subscription programs is restructuring how seed treatment value gets captured in South America. Bayer AG leverages its R&D pipeline to sustain leadership in microbial formulations across Brazilian soybean acres. Syngenta Group anchors its position through proprietary coating technologies that integrate fungicide and biostimulant layers. BASF SE differentiates via biologicals manufacturing scale in Argentina's Pampas corridor.
Seed treatment encompasses the application of crop protection agents, biological inoculants, and growth regulators onto seeds prior to planting to shield germinating embryos from soil-borne pathogens and early-season pests. The process employs film-coating, pelleting, or encapsulation techniques to achieve uniform active ingredient distribution at application rates typically measured in grams per 100 kilograms of seed. Fungicide formulations dominate commercial value given their essential role in protecting soybean and maize germination against Fusarium and Rhizoctonia pressure. Biopesticide segments expand fastest as Brazilian growers face tightening chlorothalonil restrictions and seek ANVISA-registered biological alternatives. Liquid formulations command premium positioning due to handling efficiency and compatibility with high-speed treating equipment deployed across large-scale operations.
ANVISA governs pesticide registration timelines and residue thresholds in Brazil, while Argentina's SENASA enforces phytosanitary standards for treated seed cross-border movement. REACH-equivalent chemical frameworks under Mercosur harmonization discussions are compressing approval windows for novel active ingredients. Stakeholders must monitor regulatory divergence between Brazilian federal biocide protocols and provincial Argentine enforcement to anticipate product portfolio rebalancing requirements.
Market Dynamics
ANVISA's tightening residue thresholds and chlorothalonil phase-outs are compressing product approval timelines while accelerating biological substitution across Brazilian soybean operations. This regulatory compression is redistributing market power toward firms with established microbial formulation pipelines and in-country manufacturing assets.
Growth Catalysts
- Biological Inoculant Demand:Brazilian growers facing SENASA cross-border phytosanitary requirements for treated seed are prioritizing ANVISA-registered microbial alternatives over synthetic chemistry.
- Argentina's Pampas Intensification:Double-cropping rotations in Buenos Aires and Córdoba provinces are expanding fungicide seed treatment application rates per hectare.
- Film-Coating Equipment Upgrades:High-speed treating lines deployed across Mato Grosso's large-scale operations are enabling precision application of multi-layer formulations.
Market Restraints
- Active Ingredient Concentration:Three suppliers control over 70% of proprietary fungicide chemistry supply to Brazilian formulators, creating input vulnerability.
- Registration Timeline Friction:ANVISA's novel active ingredient review windows now extend 18-24 months, delaying product commercialization.
- Biological Efficacy Variability:Temperature-sensitive microbial viability in Brazil's tropical storage conditions limits shelf-life guarantees.
Strategic Opportunities
- Paraguay's Untreated Acreage:Soybean expansion in Alto Paraná and Itapúa departments remains below 15% seed treatment penetration.
- Biostimulant-Fungicide Convergence:Layered coating technologies combining Rhizobia inoculants with strobilurin chemistry are commanding premium positioning.
- Subscription Service Models:Annual biological inoculant programs bundled with agronomic advisory are capturing recurring revenue from Brazilian cooperatives.
Industry Challenges
- Formulation Chemistry Expertise Scarcity:Brazil lacks sufficient industrial chemists trained in encapsulation technologies for biological actives.
- Legacy Equipment Retrofit Costs:Converting pelleting lines to precision film-coating systems requires capital outlays exceeding mid-scale operator thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Seed Treatment Market |
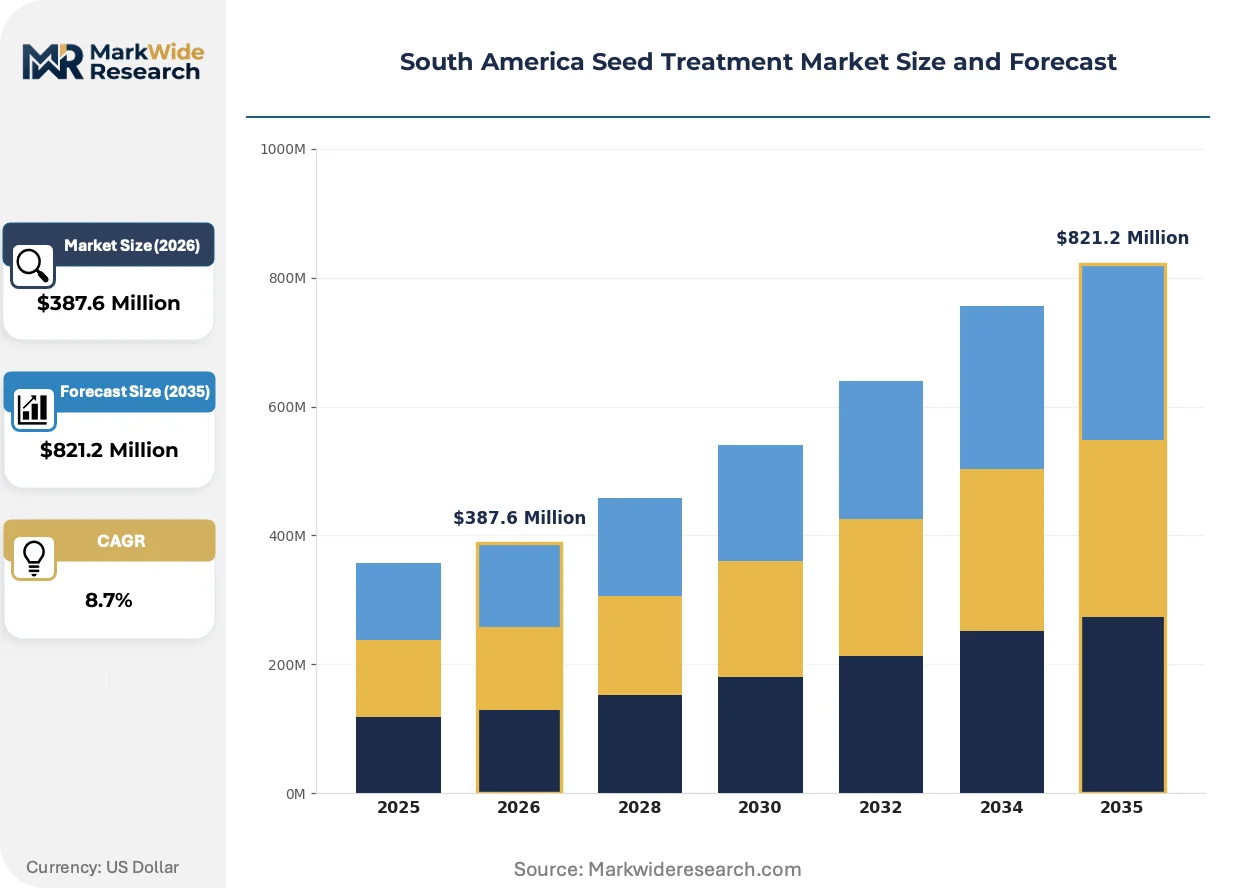
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fungicides, Insecticides, Biopesticides, Growth Regulators Application: Agricultural Seeds, Horticultural Seeds, Turf Seeds, Others Formulation: Liquid, Granular, Powder, Coated Distribution Channel: Online Retail, Specialty Stores, Distributors, Direct Sales |
| Companies Covered | Bayer AG, Syngenta Group, BASF SE, Corteva Agriscience, UPL Limited, FMC Corporation, Nufarm, Rhizobacter Argentina, Novozymes, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Seed Treatment Market Evolving Landscape
Biological seed treatment technologies are displacing synthetic chemistry across South American soybean hectares as regulatory pressure compounds with grower sustainability commitments. Three interconnected developments are restructuring competitive positioning.
Microbial consortia formulations containing Bradyrhizobium and Trichoderma species are expanding into Brazil's Cerrado soybean belt as growers seek nitrogen fixation bundled with disease suppression. Large-scale operators in Mato Grosso and Goiás are adopting these dual-function biologicals at rates outpacing historical synthetic adoption curves. The technology is expanding into premium market tiers previously reserved for proprietary fungicide chemistry.
ANVISA's revised pesticide residue protocols under Mercosur harmonization discussions are compressing maximum residue limits for chlorothalonil and mancozeb in soybean exports. Brazilian exporters targeting EU markets must now document seed treatment compliance across entire supply chains. Formulators with existing biological portfolios are capturing displaced synthetic demand while competitors await registration approvals.
Cooperative procurement aggregators in Argentina's Rosario hub are consolidating seed treatment purchasing for Pampas growers, displacing individual farm-level supplier relationships. These buying groups negotiate volume-based biological inoculant contracts directly with manufacturers, compressing distributor margins. The concentration is most visible in Buenos Aires province where three cooperatives now control over 40% of treated soybean seed procurement.
South America Seed Treatment Market Segmentation
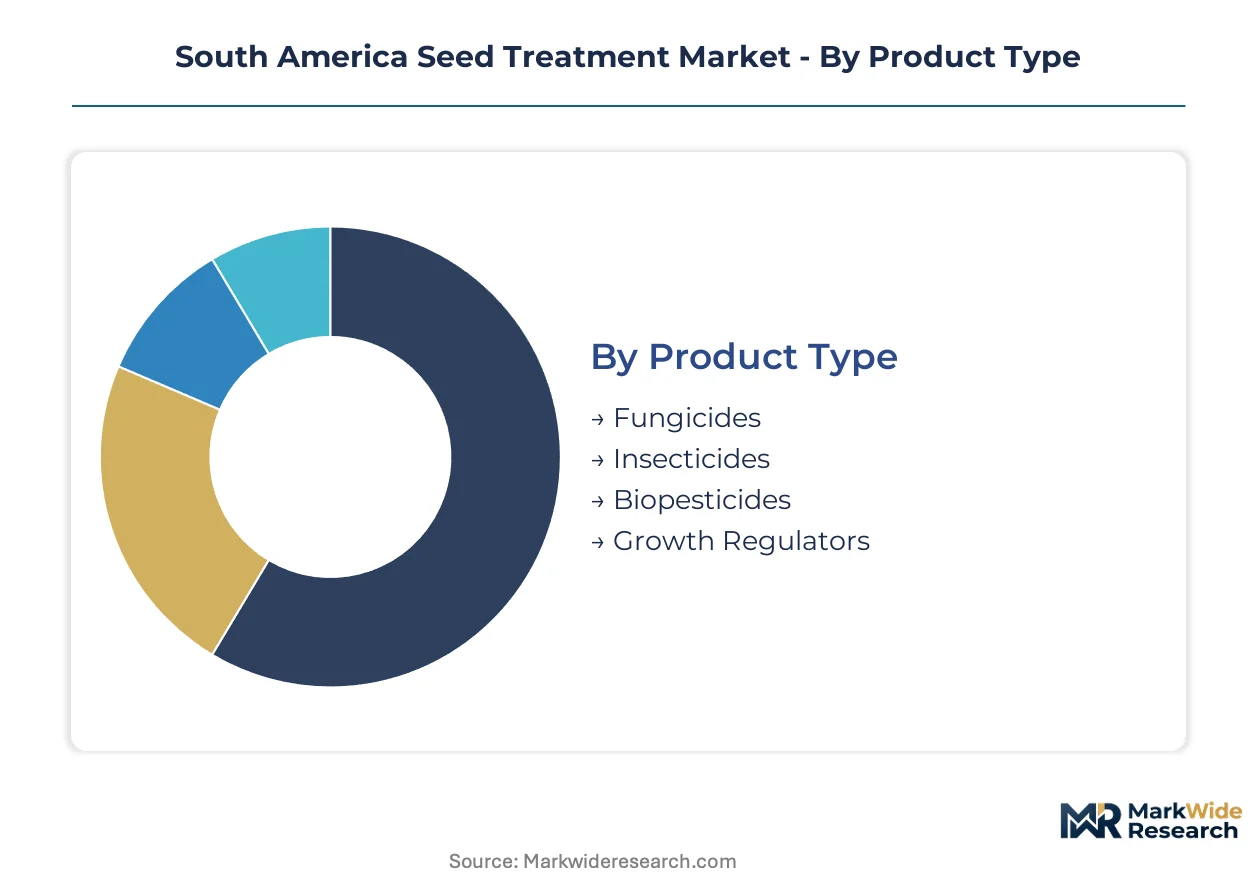
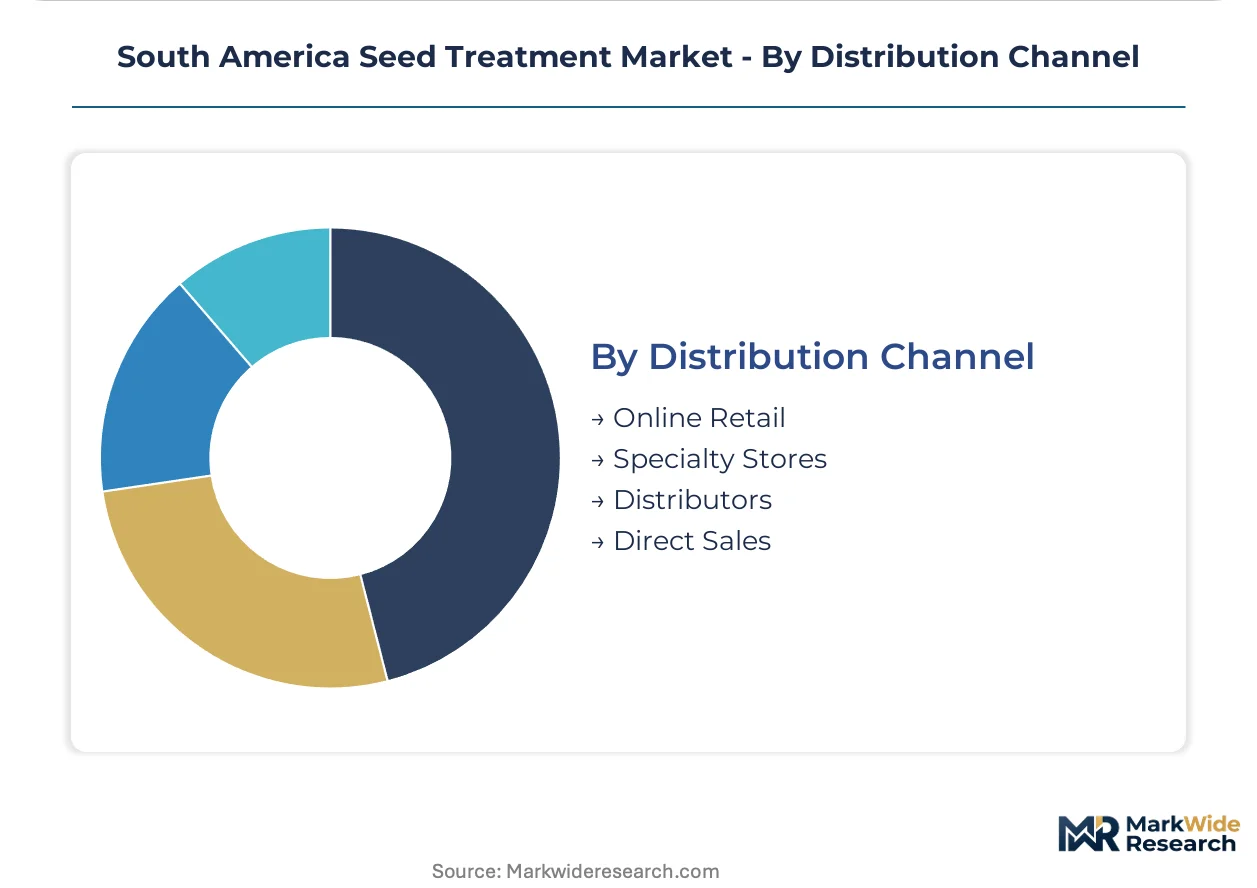
Seed treatment formulations in South America fragment across four structural dimensions that determine pricing power and channel access. Product type and formulation chemistry govern manufacturing margins, while application focus and distribution reach dictate customer capture rates across Brazilian and Argentine farming operations.
Product Type:
Equipment upgrade cycles across Brazilian treating facilities are accelerating substitution between synthetic and biological chemistries as coating lines modernize.
- Fungicides:Azoxystrobin, fludioxonil, and metalaxyl-based formulations protect soybean and maize germination against Fusarium and Rhizoctonia soil pressure. Demand concentrates in Brazil's Mato Grosso and Goiás states where large-scale operators require proven disease suppression for export-grade output.
- Insecticides:Neonicotinoid and diamide chemistry targets early-season soil pests including Diabrotica speciosa in Argentine maize rotations. Adoption is climbing fastest in Buenos Aires province where double-cropping intensifies pest pressure.
- Biopesticides:ANVISA-registered microbial alternatives containing Bacillus subtilis and Trichoderma harzianum are displacing chlorothalonil in Brazilian soybean operations facing residue threshold compression.
- Growth Regulators:Gibberellin and cytokinin formulations enhance germination uniformity in high-value horticultural seed segments.
Volume placements concentrate in Fungicides; the faster expansion belongs to Biopesticides.
Application:
Customer scale and crop value per hectare determine formulation complexity and service bundling intensity.
- Agricultural Seeds:Soybean, maize, and wheat treatments dominate commercial value with multi-layer coating protocols integrating fungicide, insecticide, and inoculant actives. Brazilian cooperatives in the Cerrado region drive specification standards for precision application equipment compatibility.
- Horticultural Seeds:Pepper, tomato, and melon treatments command premium positioning due to high seed cost and germination sensitivity. Argentine producers in Córdoba province are expanding protected cultivation acreage requiring specialized pelleting.
- Turf Seeds:Golf course and sports field applications utilize lower-volume fungicide coatings with aesthetic performance requirements.
- Others:Forage and cover crop segments utilize basic film-coating with minimal active ingredient loading.
Revenue gravity centers on Agricultural Seeds; Horticultural Seeds capture the steepest margin expansion.
Formulation:
Handling efficiency and equipment compatibility shape farmer procurement preferences across treating facility scales.
- Liquid:Suspension concentrates and emulsifiable concentrates enable uniform active distribution at high throughput rates. Mato Grosso's industrial-scale treating plants specify liquid compatibility for continuous-flow application systems.
- Granular:Dust-free carrier formulations suit manual application in smallholder segments with limited equipment access.
- Powder:Wettable powder chemistry retains cost positioning for legacy treating operations in Paraguay's expanding soybean frontier.
- Coated:Pre-treated seed products eliminate on-farm handling requirements for Argentine Pampas cooperatives consolidating procurement.
Procurement volumes favor Liquid formulations; Coated products are climbing the fastest as service models displace input sales.
Distribution Channel:
Channel selection reflects customer scale, technical support requirements, and credit access patterns across South American farming structures.
- Direct Sales:Manufacturer relationships with Brazilian cooperatives and Argentine agrarian federations bypass distributor margins for volume commitments exceeding 50,000 hectares annually.
- Distributors:Regional agrochemical networks dominate mid-scale farmer access in Brazil's interior states and Argentine provincial markets.
- Specialty Stores:Horticultural and turf segments utilize technical retailers with formulation expertise in São Paulo and Buenos Aires urban peripheries.
- Online Retail:E-commerce platforms capture smallholder orders in Brazil's southern states with consolidated logistics for packaged biological inoculants.
Transaction volume concentrates through Distributors; Direct Sales channels are expanding most quickly as cooperative consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's industrial corridor anchors South American seed treatment manufacturing, with formulation plants clustered near the Port of Santos for export logistics to Mercosur partners.
Brazil
Mato Grosso's Cerrado soybean belt drives biological inoculant demand as growers face ANVISA's tightening chlorothalonil residue thresholds. The federal regulator's 18-24 month novel active ingredient review windows are compressing product launch timelines. Formulation facilities in Rondonópolis and Sorriso are expanding microbial production capacity to serve cooperative procurement aggregators.
Argentina
Buenos Aires province's double-cropping rotations intensify fungicide application rates per hectare for wheat-soybean sequences. SENASA enforces phytosanitary documentation for treated seed cross-border movement into Brazil and Uruguay. Rosario's cooperative hub consolidates purchasing for Pampas growers, with three buying groups now controlling over 40% of regional procurement volume.
Paraguay
Alto Paraná and Itapúa departments hold substantial untreated soybean acreage with seed treatment penetration below 15%. The national plant health regulator mandates import permits for biological formulations entering from Brazilian manufacturers. Ciudad del Este's agrochemical distribution corridor channels Argentinian and Brazilian products to commercial farms expanding hectarage.
Chile
Central Valley horticultural producers command premium pricing for specialized pelleting of high-value pepper and tomato seed. The national agricultural service maintains residue monitoring protocols aligned with EU export requirements. Santiago's formulation laboratories develop customized coatings for protected cultivation operations in O'Higgins and Maule regions.
Uruguay
Paysandú and Colonia departments concentrate soybean production with seed treatment adoption trailing Brazilian benchmarks. The national agricultural ministry coordinates with SENASA for regional phytosanitary certification harmonization. Montevideo's port infrastructure supports transshipment of treated seed for Mercosur intra-regional trade.
South America Seed Treatment Market Competitive Landscape
Capital-heavy producers with in-house fermentation capacity compete with asset-light formulators outsourcing biological active sourcing. Market structure tilts toward consolidated leadership among integrated agrochemical conglomerates with established ANVISA registration portfolios. Three archetypes dominate: multinational R&D-driven innovators, regional biological specialists with manufacturing scale, and cooperative-anchored service providers bundling agronomic advisory. Dominant competitive moves include backward integration into microbial strain development and strategic partnerships with Brazilian cooperative procurement hubs.
Within the multinational tier, Bayer AG, Syngenta Group, and BASF SE exemplify integrated players combining proprietary chemistry pipelines with biological formulation capabilities. These Germany and Switzerland-anchored conglomerates occupy positions defined by Mercosur registration depth and coating technology ownership. Their market presence reflects decades of accumulated regulatory dossiers and established relationships with Mato Grosso treating facility operators.
| Leading Market Players |
|---|
| Bayer AG |
| Syngenta Group |
| BASF SE |
| Corteva Agriscience |
| UPL Limited |
| FMC Corporation |
| Nufarm |
| Rhizobacter Argentina |
| Novozymes |
| Others |
Value Network & Pricing Analysis
Soybean futures price volatility at the Chicago Board of Trade cascades through South American seed treatment supply chains, compressing margins for formulators serving Mato Grosso cooperatives while elevating premium-tier biological inoculant pricing in Argentina's Pampas belt.
Pricing Analysis
Margin tightening in standard fungicide tiers reflects chlorothalonil phase-out costs and ANVISA registration fee inflation. Three-tier pricing structure across premium microbial consortia, standard synthetic fungicides, and economy wettable powders governs Brazilian procurement. Price differentiation hinges on certification tier—ANVISA-registered biologicals command 15-25% premiums over synthetic alternatives—and volume scale, with cooperatives negotiating direct manufacturer contracts. Pricing pressure intensifies in insecticide segments as neonicotinoid restrictions expand. Smallholder operations in Paraguay exhibit highest price sensitivity; large-scale Cerrado operators prioritize performance guarantees over unit cost.
Supply Chain Analysis
Brazilian federal domestic-content mandates for ANVISA registration dossiers are reshaping microbial strain sourcing toward in-country fermentation capacity. Supply concentrates in Brazil, Argentina, and Germany—Bayer and BASF anchor production in Rondonópolis and Pergamino respectively, while specialty biologicals feed from European R&D hubs. Active ingredient supply draws from Chinese azoxystrobin intermediates, Indian metalaxyl precursors, and domestic Bradyrhizobium culture collections. Single-source vulnerability pervades proprietary fungicide chemistry, with three suppliers controlling over 70% of key inputs. Distribution runs through cooperative procurement hubs in Mato Grosso and Rosario, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity scarcity for biological actives props pricing power across South American seed treatment markets, constraining supply expansion faster than acreage demand growth.
For Market Incumbents: Deploy backward integration into microbial strain development to secure supply against emerging biological specialists. Incumbents should lock ANVISA registration pipelines for novel active ingredients before review windows extend further. Capacity addition in Mato Grosso's Sorriso corridor captures cooperative procurement consolidation. Channel control through exclusive treating equipment partnerships defends position against asset-light formulators. For New Entrants and Emerging Players: Enter via Paraguay's Alto Paraná soybean frontier, where seed treatment penetration trails regional benchmarks by 60 percentage points. White-space targets include subscription-based biological inoculant programs for Brazilian cooperatives seeking recurring revenue models, and specialized pelleting services for Chile's Central Valley horticultural exporters. Go-to-market angle: partner with Argentine cooperative buying groups in Rosario to bypass established distributor margins. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional biological specialists with captive fermentation assets in Argentina's Pampas corridor. Long-term viability centers on Mercosur regulatory harmonization completion and biological efficacy standardization. Acquisition target archetype: mid-scale formulators with existing ANVISA dossiers and underutilized treating equipment. Signal to watch: ANVISA novel active ingredient approval velocity as inflection indicator for synthetic chemistry reinvestment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microbial Strain Development | Captive Bradyrhizobium and Trichoderma supply secures formulation margins against input volatility. |
| Cooperative Procurement Hub Partnership | Direct contracts with Mato Grosso buying groups displace distributor margins and lock volume commitments. |
| ANVISA Registration Pipeline Investment | Early dossier submission ahead of residue threshold compression captures displaced synthetic demand. |
| Film-Coating Equipment Upgrade Program | Precision application compatibility meets Cerrado large-scale operator specifications for multi-layer formulations. |
| Subscription Service Model Launch | Annual biological inoculant programs bundled with agronomic advisory generate recurring revenue from Brazilian cooperatives. |
Research Methodology
Document review covered ANVISA registration databases, SENASA phytosanitary protocols, and Mercosur harmonization frameworks, complemented by interviews with formulation plant managers, cooperative procurement officers, and agrochemical distribution executives. Secondary validation drew from customs trade records, SEC filings of listed agrochemical conglomerates, and regional agricultural ministry production statistics. Bottom-up acreage estimates triangulated against top-down manufacturer revenue disclosures.
Market size outputs reflect product-type segmentation across fungicides, insecticides, biopesticides, and growth regulators; formulation chemistry splits between liquid, granular, powder, and pre-coated; application focus spanning agricultural, horticultural, turf, and forage seeds; and distribution channel differentiation. CAGRs derive from regression analysis of historical adoption curves and regulatory phase-out schedules. Industry-specific inputs include ANVISA approval velocity indices and soybean futures price correlation models.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ANVISA regulatory acceleration or Mercosur trade disruption scenarios. Forecasts reflect assumptions regarding biological efficacy standardization and cooperative procurement consolidation velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Processing Innovations
Oilseed Processing Market
Seed Processing Innovations
Sprouted Durum Wheat for Pasta Applications Market
Seed Processing Innovations
Australia Seed Treatment Market
Seed Processing Innovations
Kiwi Seed Extract Market
Seed Processing Innovations
Seed Sorting Machine Market
Seed Processing Innovations
Soybean Seed Treatment Market
Seed Processing Innovations
Rice Seed Treatment Market
Seed Processing Innovations
United States Seed Treatment Market
Seed Processing Innovations
Italy Seed Treatment Market
Seed Processing Innovations
Asia-Pacific Seed Treatment Market
Seed Processing Innovations
North America Soybean Seed Treatment Market
Seed Processing Innovations
Argentina Seed Treatment Market
Seed Processing Innovations
Maize Seed Treatment Market
Seed Processing Innovations
Alfalfa Seed Extract Market
Seed Processing Innovations
Fenugreek Seed Extract Market
Seed Processing Innovations
North America Seed Treatment Market