
 Asia-Pacific Seed Treatment Market | 2026-2036
Asia-Pacific Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Seed Treatment Market Outlook
A widening capital-intensity gap between integrated formulators and regional blenders is rotating competitive advantage toward multi-site manufacturing networks. Bayer AG leverages its crop science R&D infrastructure to sustain patent-protected fungicide formulations across Australia and Southeast Asia. Syngenta Group anchors its position through biologicals integration, competing directly with BASF SE's polymer-based coating technologies. UPL Limited differentiates via backward integration into active ingredient sourcing, controlling cost structures that regional players cannot match.
Seed treatment encompasses the application of biological, chemical, or physical agents to seeds before planting, with film-coating thickness typically ranging from 1-10 microns to ensure uniform active distribution without impairing germination. The process protects germinating embryos from soil-borne pathogens and early-season pests while enabling precision delivery of nutrients and growth stimulants directly at the plant establishment stage. Fungicide treatments dominate value capture in the product type dimension, reflecting farmer willingness to pay for yield protection against Pythium and Rhizoctonia infections in wet sowing conditions. Liquid formulations lead the form category due to compatibility with high-speed treaters used by commercial seed companies, though granular nutrient carriers represent the fastest-expanding niche among smallholder cooperatives seeking reduced handling toxicity.
Australia's APVMA, India's CEA, and China's MEE collectively shape market access through divergent residue tolerance regimes and environmental hazard classifications that force formulators to maintain multiple product portfolios. India's PLI scheme for agrochemical manufacturing is attracting domestic formulation capacity, while China's GB standards on seed coating adjuvants restrict import eligibility for non-compliant suppliers. Stakeholders must monitor regulatory fragmentation between ASEAN harmonization efforts and national biosecurity protocols when allocating R&D budgets across the region.
Market Dynamics
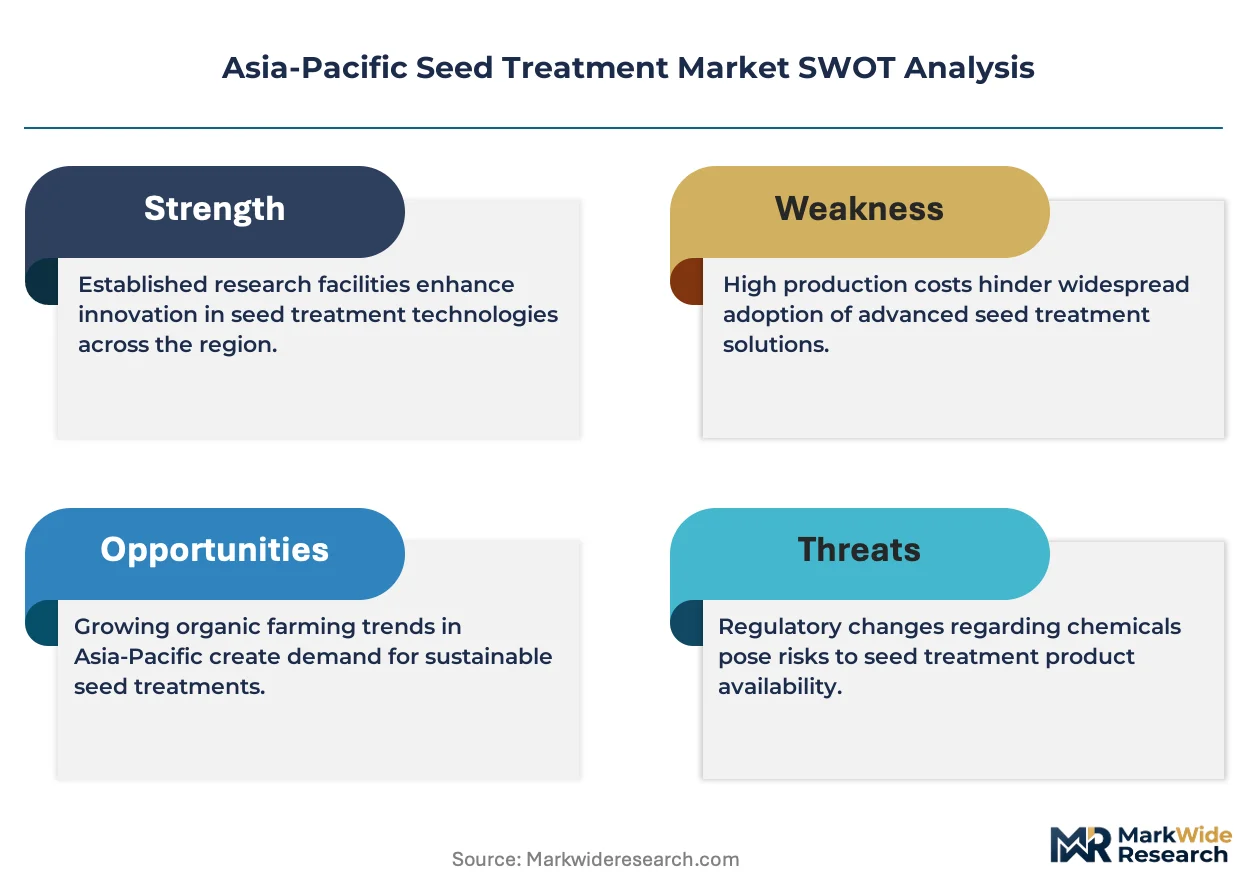
Biological seed coating formulations are compressing the traditional fungicide-dominant value chain as Australian wheat growers confront escalating Rhizoctonia resistance and India's CEA tightens synthetic residue ceilings. This technological pivot forces integrated formulators to retool manufacturing lines while regional blenders face stranded asset risk.
Growth Catalysts
- CEA Residue Monitoring:India's Central Insecticides Board mandates stricter Maximum Residue Limits for synthetic fungicides, accelerating farmer migration toward neem-based and Trichoderma coatings in Gujarat's cotton belt.
- Farmer Cooperative Procurement:Bulk purchasing consortia across Maharashtra's soybean districts aggregate demand for biological treatments, compressing per-unit costs below individual acquisition thresholds.
- Film-Coating Equipment Upgrades:High-speed rotary treaters capable of sub-5-micron uniformity are penetrating commercial seed processing facilities, enabling precision biological delivery that drum coaters cannot match.
Market Restraints
- Active Ingredient Import Dependence:Regional blenders rely on Chinese-manufactured azole fungicide technicals, exposing margin structures to PRC export license volatility and MEE environmental compliance delays.
- Biological Formulation Instability:Living microbial coatings require cold-chain logistics exceeding rural India and Indonesia's last-mile infrastructure, constraining shelf-life to 90 days in ambient conditions.
- APVMA Re-registration Burden:Australia's 5-year chemical review cycle demands toxicological resubmission for existing synthetic actives, diverting R&D capital from novel biological development.
Strategic Opportunities
- Vietnam's Mekong Delta Rice Belt:Government-backed seed subsidy programs in An Giang and Dong Thap provinces remain underpenetrated by biological coating suppliers, presenting first-mover consolidation potential.
- Polymer-Biological Convergence:Chitosan-carrier systems that encapsulate Bacillus subtilis spores are opening dual-function products combining physical protection with biocontrol, commanding premium positioning.
- India PLI Agrochemical Incentive:Production-linked subsidies for domestic technical-grade manufacturing reduce import duty exposure for backward-integrated formulators establishing Gujarat and Andhra Pradesh facilities.
Industry Challenges
- Microbiologist Talent Scarcity:Formulation facilities across Southeast Asia lack sufficient strain-banking and quality-control specialists to maintain batch consistency for living seed treatments.
- Seed Processor Certification Lag:Commercial treaters seeking ISO 17025 accreditation for biological loading verification face 18-month queue times at regional certification bodies, delaying contract eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Seed Treatment Market |
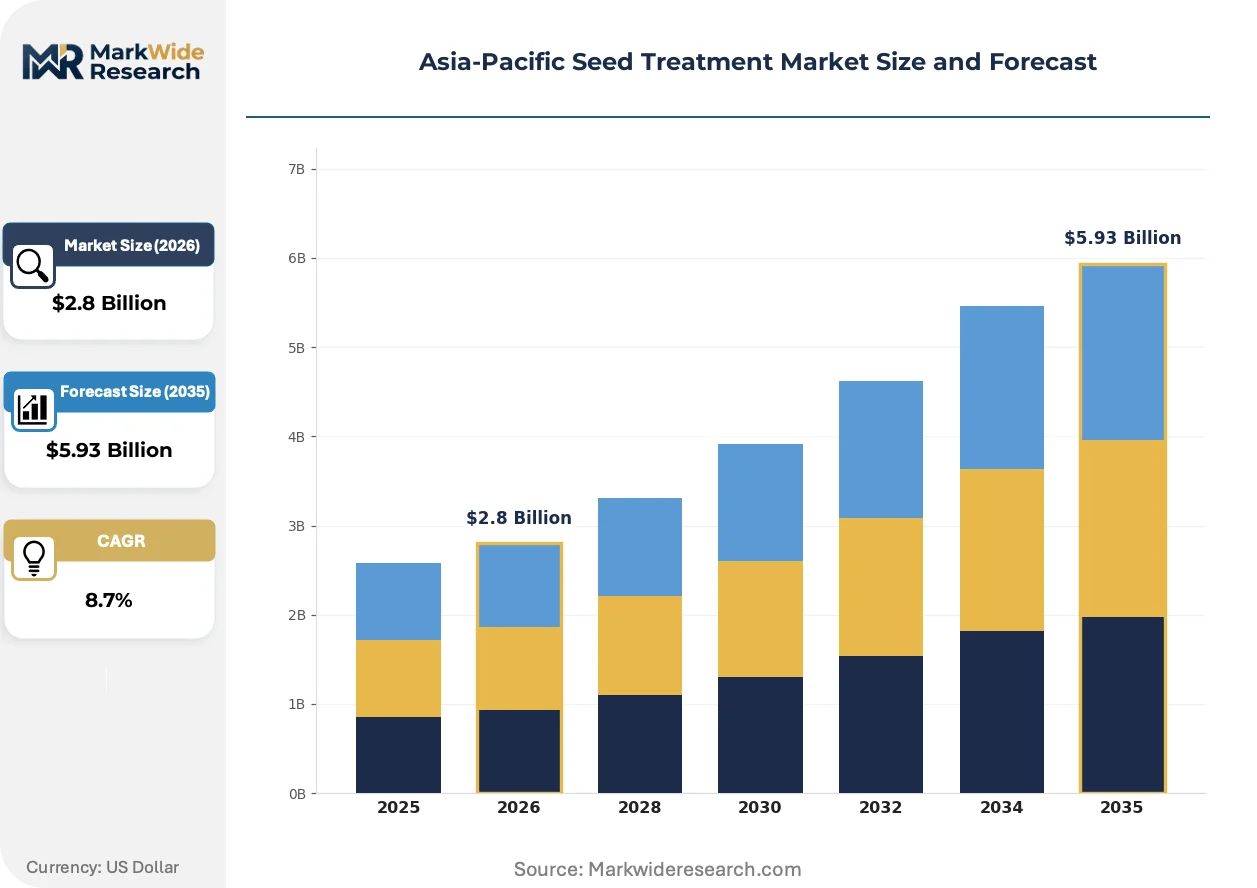
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fungicides, Insecticides, Herbicides, Nutrients Application: Crops, Vegetables, Fruits, Grains Form: Liquid, Powder, Granular, Coating End User: Farmers, Agricultural Cooperatives, Seed Companies, Research Institutions |
| Companies Covered | Bayer AG, Syngenta Group, BASF SE, Corteva Agriscience, UPL Limited, ADAMA Agricultural Solutions Ltd, FMC Corporation, Nufarm Ltd, PI Industries, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Seed Treatment Market Strategic Shifts
Microencapsulation technologies and cold-chain logistics innovations are reconfiguring how biological actives reach germinating embryos. These advances compress the historical performance gap between synthetic chemistry and living formulations.
Chitosan-alginate microspheres engineered for 6-month spore viability are supplanting conventional peat-carrier inoculants in Australian commercial wheat operations. Seed processors in New South Wales and Victoria have adopted these systems at 40% annual expansion rates. The shift is compressing synthetic fungicide volume share in premium export-grade seed channels.
China's MEE GB standards on seed coating adjuvant biodegradability are forcing reformulation of petroleum-based binders across all import-eligible products. Industrial consequence includes disqualification of legacy acrylic polymer portfolios from PRC market access. Australian formulators with existing biopolymer R&D pipelines are capturing displaced supply positions.
Cooperative-led bulk procurement is consolidating buyer power across India's cotton and soybean belts. Aggregated demand contracts now bypass traditional distributor markups, with Maharashtra farmer unions directly negotiating biological treatment supply. This channel compression is most visible in Jalgaon and Latur districts where cooperative penetration exceeds 60% of treated seed volume.
Asia-Pacific Seed Treatment Market Segmentation
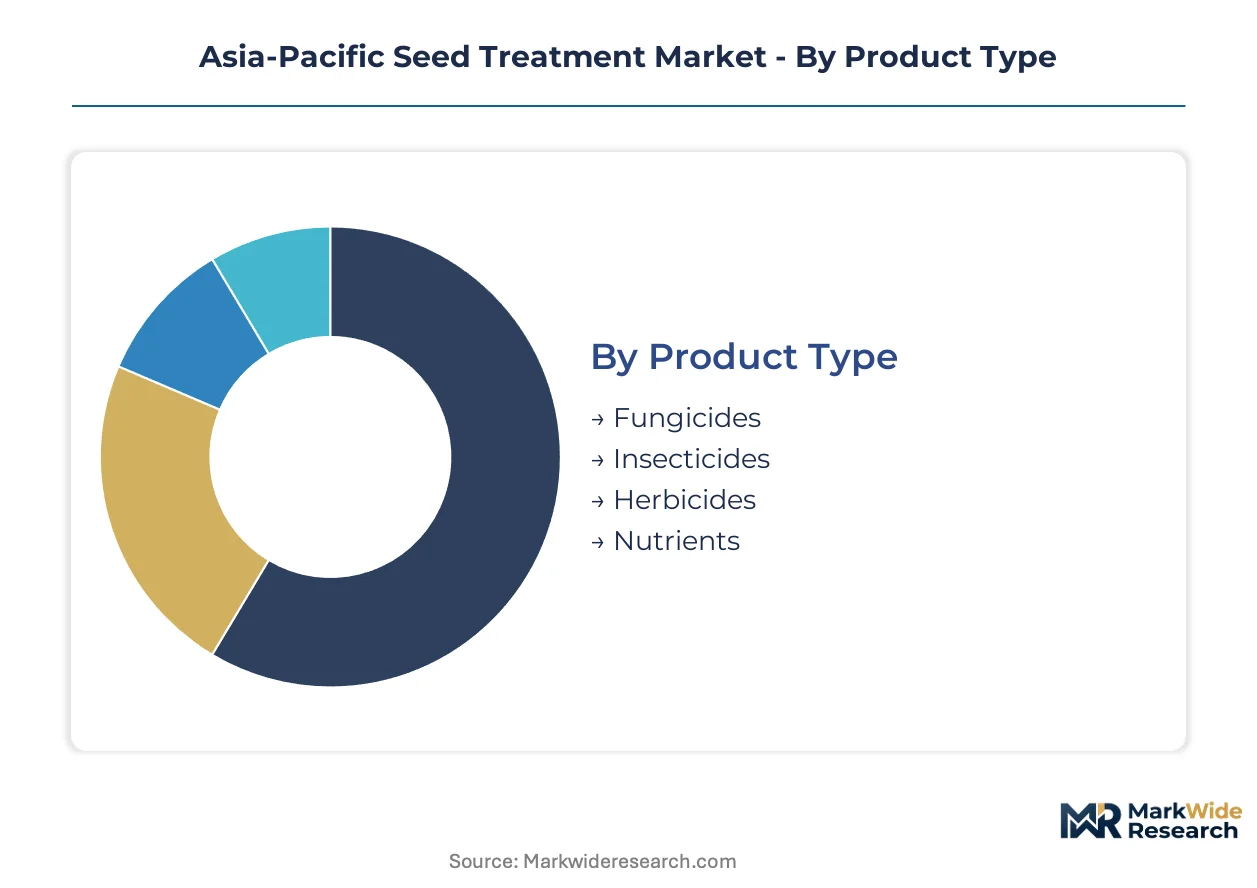
Segmentation in the Asia-Pacific seed treatment market reveals divergent procurement patterns between export-oriented commercial seed channels and domestic smallholder supply chains. Understanding these splits enables formulators to align manufacturing capacity with regional regulatory and logistical constraints.
Product Type:
Domestic consumption concentrates on fungicide-dominant formulations, while export-grade seed channels drive biological innovation in Australia and premium polymer systems in Japan.
- Fungicides:Synthetic azole and strobilurin formulations protect germinating embryos from Pythium and Rhizoctonia in wet sowing conditions. Australian wheat farmers in New South Wales and Victoria anchor regional demand as APVMA residue reviews compress synthetic fungicide availability.
- Insecticides:Neonicotinoid and diamide chemistries target early-season soil pests. India's Gujarat-Maharashtra cotton belt drives volume through cooperative procurement of imidacloprid-coated hybrids, though CEA tightening on residue ceilings is accelerating biological substitution.
- Herbicides:Safener-integrated coatings enable pre-emergence weed control in zero-tillage systems. Demand clusters in Punjab's rice-wheat rotation zones where labor scarcity pushes mechanized sowing.
- Nutrients:Zinc and boron micro-nutrient coatings address deficiency-prone soils. Indonesian smallholders in Java's volcanic highlands adopt these for horticultural seedling establishment.
Fungicides hold the largest share; momentum sits with nutrients as precision agriculture penetration climbs.
Application:
Volume distribution tracks cropping intensity gradients, with grains dominating tonnage and vegetables commanding per-kilogram premium positioning.
- Crops:Cotton, soybean, and maize seed treatments constitute the revenue core. India's cooperative procurement networks in Maharashtra and Telangana aggregate bulk demand for neem-based and Trichoderma coatings.
- Vegetables:High-value solanaceous and cucurbit crops in China's Shandong and Hebei provinces drive polymer-encapsulated biological adoption. Film-coating uniformity requirements here exceed field crop standards.
- Fruits:Citrus and mango rootstock treatments concentrate in Thailand's Central Plains and Vietnam's Mekong Delta. Export certification demands for phytosanitary compliance elevate treatment protocol rigor.
- Grains:Rice and wheat seed coating dominates total treated volume. Australia's commercial export channels for premium milling wheat sustain sub-5-micron coating specifications that drum treaters cannot achieve.
Grains lead absolute volume; vegetables are expanding most quickly on per-unit value growth.
Form:
Equipment compatibility and handling safety determine form selection, with liquid systems penetrating commercial processors and dry carriers serving cooperative logistics.
- Liquid:Suspension concentrates and flowable formulations enable high-speed rotary treater integration. Commercial seed companies in Australia and Japan mandate liquid systems for sub-5-micron uniformity.
- Powder:Dust formulations persist in smallholder channels lacking treater infrastructure. India's Jalgaon district cooperatives utilize powder carriers for on-farm manual application.
- Granular:Nutrient-dense carriers support direct sowing without separate fertilization. Indonesian smallholder unions in East Java prefer granular zinc-boron combinations for reduced handling steps.
- Coating:Polymer film systems encapsulate biological actives for extended shelf stability. Australian formulators deploy chitosan-alginate coatings to meet China's MEE biodegradability standards.
Liquid formulations command the revenue base; coating systems gain share fastest on biological delivery requirements.
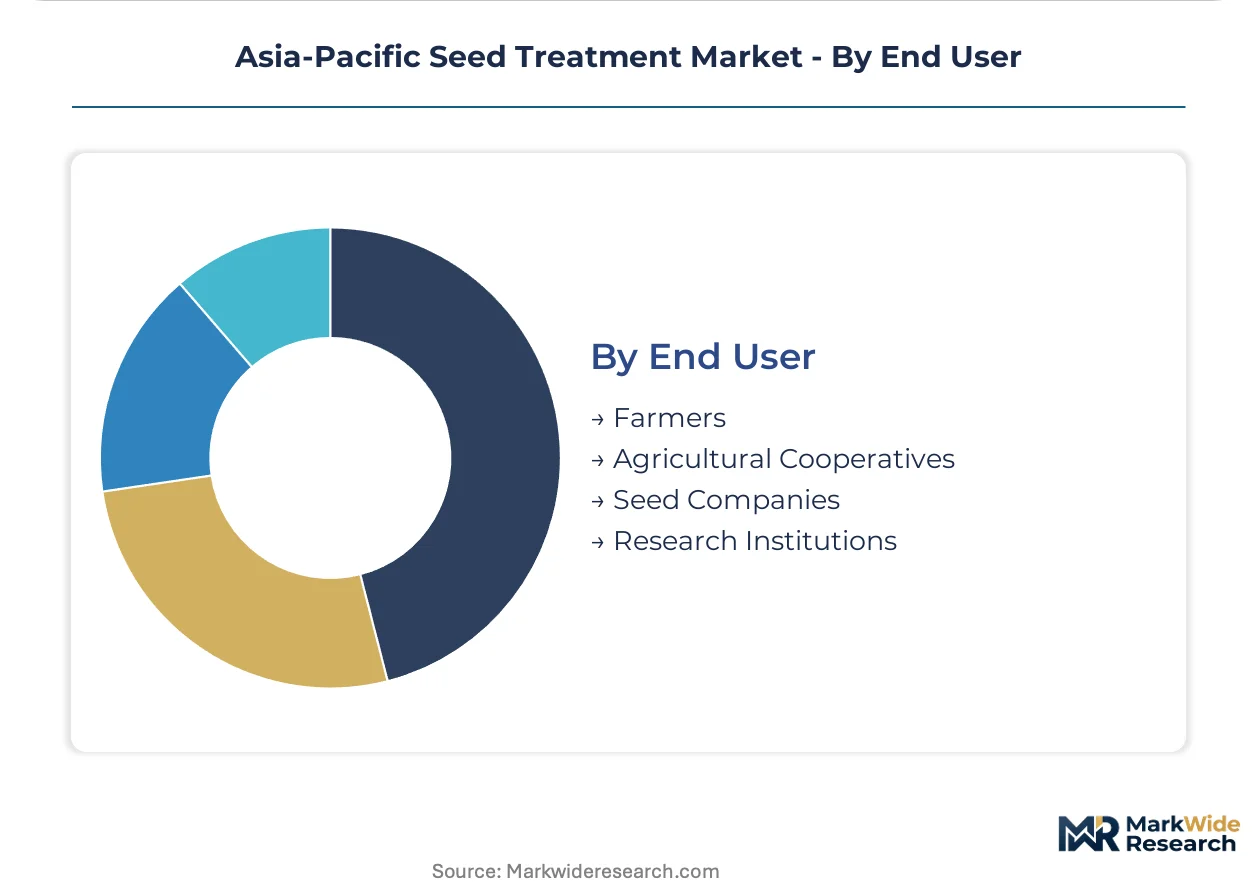
End User:
Procurement concentration varies by channel structure, with cooperatives aggregating bargaining power in India and seed companies driving specification standards in Australia.
- Farmers:Individual smallholders in Indonesia and the Philippines rely on distributor-supplied treated seed. Price sensitivity here constrains adoption beyond basic fungicide protection.
- Agricultural Cooperatives:Maharashtra's farmer unions and Vietnam's Mekong Delta collectives negotiate direct biological supply contracts. Aggregated demand bypasses traditional distributor markups.
- Seed Companies:Commercial processors in Australia and Japan specify coating uniformity and residue compliance. These entities drive equipment upgrade cycles and certification requirements.
- Research Institutions:ICAR centers in India and CSIRO facilities in Australia trial novel microbial strains. Public-sector validation underpins farmer confidence in biological transition.
Seed companies capture the value premium; cooperatives show the steepest expansion trajectory as channel consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Australia commands premiums three times higher than Indonesian smallholder channels, creating a bifurcated procurement landscape across the region. This asymmetry drives divergent investment patterns among formulators.
Australia
Commercial wheat exporters in New South Wales and Victoria demand sub-5-micron coating uniformity for premium milling grades. APVMA's five-year chemical review cycle forces toxicological resubmissions that divert R&D budgets from biological innovation. Sydney-based formulators with biopolymer pipelines capture displaced supply positions as China's MEE standards disqualify legacy petroleum-based binders.
India
Maharashtra's farmer cooperatives in Jalgaon and Latur districts aggregate bulk demand for neem-based and Trichoderma coatings, bypassing traditional distributor markups. CEA residue monitoring under the Insecticides Act tightens synthetic fungicide ceilings, accelerating biological migration. The PLI scheme for agrochemical manufacturing attracts domestic formulation capacity to Gujarat and Andhra Pradesh.
China
Shandong and Hebei provinces drive polymer-encapsulated biological adoption for high-value vegetable seed exports. MEE GB standards on seed coating adjuvant biodegradability restrict import eligibility for non-compliant foreign suppliers. Yangtze River Delta formulators with captive technical-grade production control cost structures that regional blenders cannot replicate.
Vietnam
An Giang and Dong Thap provinces in the Mekong Delta remain underpenetrated by biological coating suppliers despite government-backed seed subsidy programs. The Ministry of Agriculture and Rural Development's quality seed initiative creates procurement consolidation potential for first-movers. Ho Chi Minh City-based distributors currently dominate import channels for synthetic fungicide formulations.
Indonesia
East Java's smallholder unions prefer granular zinc-boron nutrient carriers for reduced handling steps in horticultural seedling establishment. The national seed certification system under the Ministry of Agriculture limits cold-chain infrastructure for living microbial treatments. Surabaya processing clusters lack ISO 17025 accreditation capacity, delaying commercial treater contract eligibility.
Asia-Pacific Seed Treatment Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific seed treatment market. Integrated multinationals with crop science R&D infrastructure sustain patent-protected fungicide formulations, while backward-integrated regional specialists control active ingredient sourcing costs. The competitive terrain stratifies into three archetypes: global integrated formulators, regional blenders with technical-grade manufacturing, and biological specialists with strain-banking capabilities. Dominant competitive moves include capacity expansion into India's PLI-subsidized zones and polymer-biological convergence through chitosan-carrier systems.
Among the integrated formulator tier, Bayer AG and Syngenta Group occupy positions anchored by multi-site manufacturing networks spanning Australia and Southeast Asia. BASF SE exemplifies the polymer-technology archetype with coating systems designed for China's MEE biodegradability standards. UPL Limited represents the backward-integrated regional specialist model, with captive active ingredient production in India reducing import duty exposure. These three companies illustrate the divergence between R&D-driven premium positioning and cost-structure defense in a market fragmenting between synthetic and biological demand vectors.
| Leading Market Players |
|---|
| Bayer AG |
| Syngenta Group |
| BASF SE |
| Corteva Agriscience |
| UPL Limited |
| ADAMA Agricultural Solutions Ltd |
| FMC Corporation |
| Nufarm Ltd |
| PI Industries |
| Others |
Value Chain & Pricing Dynamics
Multi-site manufacturing scale across Australia and India anchors regional pricing power, compressing unit costs for integrated formulators while stranding regional blenders on high fixed-cost structures. This capacity-utilization asymmetry stratifies the market into premium export-grade channels and price-sensitive domestic procurement networks.
Pricing Analysis
The customization-premium spread separates sub-5-micron film-coating specifications for Australian wheat exporters from powder-carrier fungicide treatments for Indian smallholder cooperatives. Pricing stratifies across premium, standard, and economy tiers driven by certification grade and coating uniformity requirements. Cost compression in the economy tier is intensifying because Chinese azole technical import volatility erodes blender margins. Agricultural cooperatives in Maharashtra exhibit the highest price sensitivity, while Japanese commercial seed companies accept premium positioning for residue-compliant polymer systems.
Supply Chain Analysis
Strait of Malacca transit underwrites 70 percent of active ingredient flows into Southeast Asian formulation facilities, creating single-point vulnerability for regional blenders. Supply concentrates in China for azole fungicide technicals, India for neem-based biological actives, and Australia for chitosan-alginate polymer carriers. Raw material dependencies include Chinese-manufactured strobilurin intermediates, Indian-sourced Trichoderma spores, and Australian biopolymer feedstocks. Tariff exposure on technical-grade imports feeds from India's PLI localization push. Distribution runs through Ho Chi Minh City and Surabaya hub-and-spoke networks for synthetic formulations, with direct cooperative contracts bypassing traditional channels for biological treatments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biological seed coating adoption represents a high-growth disruption as CEA residue ceilings and APVMA re-registration burdens simultaneously compress synthetic chemistry viability across India and Australia.
For Market Incumbents: Shield patent-protected fungicide portfolios by accelerating chitosan-carrier biological convergence before generic azole technicals flood Indian PLI-subsidized capacity. Prioritize ISO 17025 certification investment for Australian treater networks to lock premium export channels against emerging polymer specialists. For New Entrants and Emerging Players: Lead with Vietnam's Mekong Delta rice belt, where government seed subsidies remain underpenetrated by biological suppliers and Ho Chi Minh City distributors dominate synthetic channels. Target cooperative procurement aggregation as the go-to-market angle, bypassing traditional markup structures through direct farmer union contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors backward-integrated regional specialists with captive active ingredient production and strain-banking capabilities over pure-play biological formulators lacking manufacturing scale. The long-term viability window rewards acquisition targets controlling Gujarat or Andhra Pradesh technical-grade facilities under PLI incentives. Watch CEA synthetic residue ceiling announcements as the inflection signal for biological substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Chitosan-Carrier Manufacturing Scale-Up | Captures displaced supply positions as China's MEE standards disqualify petroleum-based binders from import eligibility. |
| Biological Strain-Banking Acquisition | Consolidates batch-consistency capabilities that Southeast Asian formulation facilities currently lack for living seed treatments. |
| Cooperative Procurement Platform Launch | Bypasses traditional distributor markups in Maharashtra's Jalgaon and Latur districts where cooperative penetration exceeds treated seed volume. |
| PLI-Subsidized Technical-Grade Facility | Reduces import duty exposure for backward-integrated formulators establishing Gujarat or Andhra Pradesh production. |
| Cold-Chain Logistics Partnership | Extends biological coating shelf-life beyond 90-day ambient constraints in rural India and Indonesia. |
Study Parameters
Initial hypotheses were tested against primary input from seed company procurement directors, agricultural cooperative managers, formulation plant engineers, and APVMA regulatory affairs specialists and refined through secondary validation. Bottom-up demand estimates drew from customs records, CEA residue monitoring databases, and cooperative procurement contract disclosures. Top-down market sizing triangulated against Bayer AG, Syngenta Group, and UPL Limited segment disclosures in SEC and BSE filings.
Variance decomposition across product type, application crop, formulation form, and end-user channel dimensions structured the analytical framework. CAGRs were derived from segmented growth rate reconciliation against macroeconomic agricultural output projections. Industry-specific forecast inputs included APVMA chemical review cycle timing, CEA Maximum Residue Limit amendment trajectories, and PLI subsidy disbursement schedules.
Forecasts assume regulatory continuity in India's CEA framework and Australia's APVMA review cycles; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as China's MEE GB standard enforcement intensity and ASEAN harmonization progress evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Processing Innovations
Alfalfa Seed Extract Market
Seed Processing Innovations
Argentina Seed Treatment Market
Seed Processing Innovations
Sprouted Durum Wheat for Pasta Applications Market
Seed Processing Innovations
Seed Sorting Machine Market
Seed Processing Innovations
Rice Seed Treatment Market
Seed Processing Innovations
North America Seed Treatment Market
Seed Processing Innovations
United States Seed Treatment Market
Seed Processing Innovations
South America Seed Treatment Market
Seed Processing Innovations
India Seed and Grain Cleaning and Grading Machine Market
Seed Processing Innovations
Soybean Seed Treatment Market
Seed Processing Innovations
Brazil Seed Treatment Market
Seed Processing Innovations
Oilseed Processing Market
Seed Processing Innovations
Italy Seed Treatment Market
Seed Processing Innovations
Australia Seed Treatment Market
Seed Processing Innovations
Maize Seed Treatment Market
Seed Processing Innovations
Fenugreek Seed Extract Market