
 Alfalfa Seed Extract Market | 2026-2036
Alfalfa Seed Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Alfalfa Seed Extract Market Analytics
Asset-light contract manufacturing and third-party extraction leasing is reconfiguring competitive entry barriers for botanical suppliers. Martin Bauer Group leverages backward integration into seed sourcing to sustain margin control across European supply chains. Shaanxi Jiaherb Phytochem anchors its position through concentrated R&D investment in standardized flavonoid extraction protocols. Sun Prime Extracts competes by occupying specialized organic certification tiers that command premium positioning in North American health food channels.
Alfalfa seed extract comprises bioactive isoflavones, saponins, and coumestans derived from Medicago sativa germplasm through aqueous or solvent-based extraction, typically standardized to 5-20% total flavonoids for nutraceutical and pharmaceutical applications. The powder segment leads volume throughput due to stability advantages in bulk dietary supplement manufacturing, while liquid extracts capture faster growth in functional beverage formulations where solubility and dosing precision matter. Capsule formats concentrate margin pools through direct-to-consumer branding, though granules retain niche strength in animal feed premix applications where flowability and uniform dispersion prove critical.
EU REACH and EFSA Novel Food frameworks govern extract purity and new ingredient market access across European nutraceutical channels, while China's SAMR enforces GB standards for pesticide residues and heavy metals in botanical exports. FDA GRAS self-determination and DSHEA compliance shape U.S. dietary supplement positioning, with third-party USP or NSF certification increasingly required by major health food retailers. Stakeholders must monitor evolving novel food approval pathways and contaminant threshold tightening, as regulatory divergence between jurisdictions threatens to fragment formulation strategies and sourcing footprints.
Market Dynamics
Standardization pressures from EU EFSA Novel Food and China's SAMR GB standards are compressing supplier margins while concentrating procurement among certified extractors capable of meeting divergent purity thresholds across jurisdictions.
Growth Catalysts
- EFSA Novel Food framework:EU nutraceutical brands accelerate alfalfa extract incorporation into menopause-support formulations, creating validated demand pull under harmonized safety assessments.
- Powder formulation stability:Bulk dietary supplement manufacturers favor spray-dried extracts with 18-24 month shelf integrity, reducing inventory risk in long supply chains.
- Functional beverage channel:North American health food retailers expand liquid extract SKUs for adaptogenic drink applications where solubility and precise dosing prove critical.
Market Restraints
- Input cost volatility:Alfalfa seed prices fluctuate with drought cycles in major growing regions, squeezing extractor margins when contract pricing locks in advance.
- Supply concentration risk:Certified organic seed stocks concentrate among limited North American and Australian growers, creating bottleneck vulnerability for premium-tier extractors.
- Regulatory friction:Divergent heavy metal thresholds between EU REACH and China's SAMR GB standards force dual-testing protocols that add 12-15% to compliance costs.
Strategic Opportunities
- India nutraceutical penetration:FSSAI's evolving botanical ingredient guidelines open formulation pathways for standardized alfalfa isoflavones in domestic Ayurveda-integrated supplements.
- Animal feed premix expansion:Poultry and aquaculture integrators in Southeast Asia trial flavonoid-enriched feed additives for antibiotic-reduction programs.
- Direct-to-consumer capsule channels:Subscription wellness platforms bypass traditional wholesale distribution, capturing margin pools previously retained by retail intermediaries.
Industry Challenges
- Flavonoid standardization expertise:Chromatography technicians capable of validating 5-20% total flavonoid consistency remain scarce, extending batch release timelines.
- Organic certification maintenance:Annual third-party audits for USDA Organic and EU Organic equivalence demand sustained documentation investment across multi-year crop rotations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alfalfa Seed Extract Market |
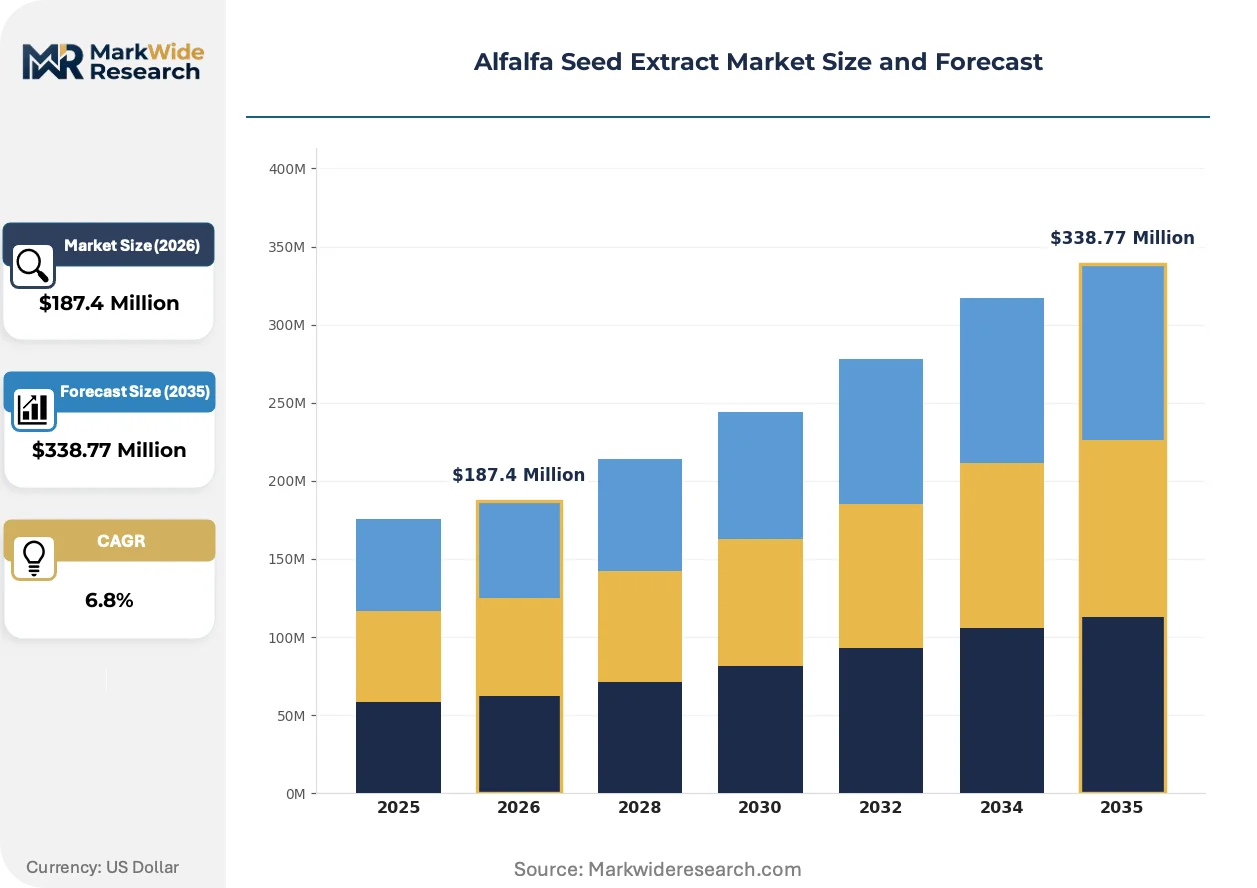
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Liquid, Capsules End User: Food Industry, Nutraceuticals, Pharmaceuticals, Cosmetics Application: Dietary Supplements, Functional Foods, Animal Feed, Personal Care Distribution Channel: Online Stores, Health Food Stores, Supermarkets, Pharmacies |
| Companies Covered | Martin Bauer Group, Sun Prime Extracts, Desialis, Nature LLC, LiquaDry, Shaanxi Jiaherb Phytochem, Naturalin, Nanjing Zhi Bai Cui Biology Technology, Changsha Active Ingredients Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alfalfa Seed Extract Market Evolving Landscape
Extraction technology and regulatory science are converging to reshape competitive capabilities, with solvent recovery systems and novel food dossier expertise becoming decisive differentiators among mid-scale suppliers.
Supercritical CO2 extraction is migrating from pharmaceutical-grade applications toward mid-volume nutraceutical production, enabling terpene preservation without residual solvent concerns. German contract manufacturers adopt these systems to serve EFSA-compliant brands demanding clean-label positioning. The technology is migrating from premium niche toward mainstream powder production, compressing cost differentials between ethanol and supercritical processing routes.
China's SAMR enforcement of revised GB standards for pesticide residues in botanical exports is forcing upstream seed sourcing audits. Exporters must now document field-level cultivation practices to maintain market access. Concentrated extractors with captive organic acreage or long-term grower contracts gain preferential positioning against spot-market dependent competitors.
Ingredient buyers are consolidating supplier panels around vertically integrated extractors capable of delivering standardized certificates of analysis with each lot. Direct sourcing from seed-to-extract operators displaces multi-tier trading relationships that obscured origin documentation. This preference shift is most visible among North American contract manufacturers serving NSF-certified retail channels.
Alfalfa Seed Extract Market Segmentation
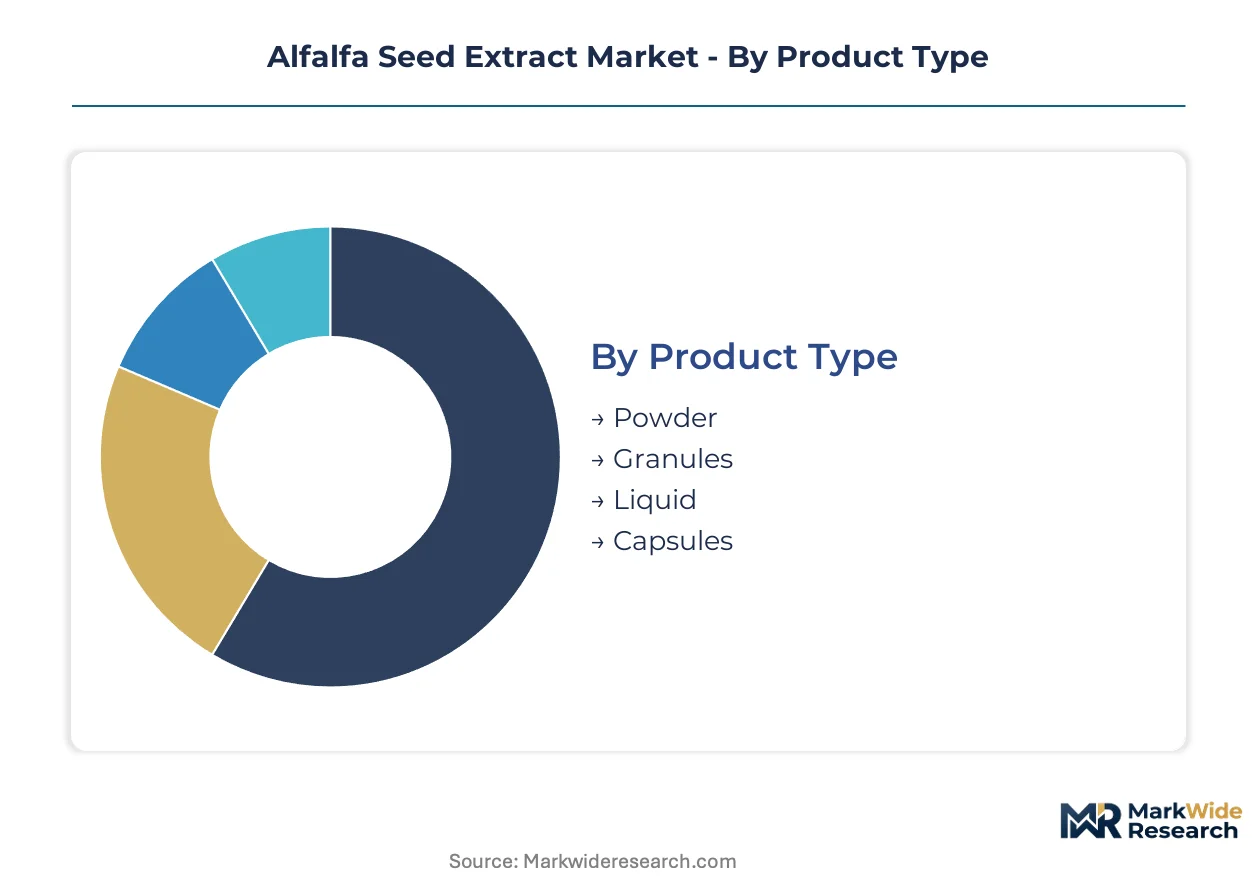
Alfalfa seed extract procurement patterns diverge sharply across formulation formats and end-use channels, with inventory velocity and margin capture varying by an order of magnitude between bulk powder contracts and finished capsule SKUs. Understanding these segment dynamics reveals where capital efficiency concentrates and where new entrants face steepest barriers.
Product Type:
Powder formulations turn inventory fastest through bulk dietary supplement manufacturing, while capsules and liquids operate on longer production cycles with higher per-unit value capture.
- Powder:Spray-dried extracts standardized to 5-20% total flavonoids dominate bulk procurement from contract manufacturers. German and French nutraceutical brands drive volume through menopause-support formulations requiring shelf-stable inputs with 18-24 month integrity.
- Liquid:Aqueous and glycerin-based extracts serve functional beverage applications where solubility and precise dosing prove critical. North American health food retailers are expanding liquid extract SKUs for adaptogenic drink lines, though cold-chain requirements extend fulfillment cycles.
- Capsules:Hard-shell and soft-gel formats concentrate margin pools through direct-to-consumer subscription platforms that bypass wholesale intermediaries.
- Granules:Flowable particulate forms retain niche strength in animal feed premix applications across Southeast Asian poultry and aquaculture integrators.
Powder dominates installed base. Liquid is where expansion concentrates.
End User:
Cost tier stratification separates commodity-grade feed applications from pharmaceutical-grade specifications, with nutraceuticals occupying the contested middle ground where standardization premiums apply.
- Nutraceuticals:Dietary supplement brands command the largest addressable volume, purchasing standardized extracts under EU Novel Food and FDA DSHEA frameworks. Procurement panels are consolidating around vertically integrated extractors capable of delivering certificates of analysis with each lot.
- Pharmaceuticals:Clinical-grade extracts face stringent chromatographic validation requirements for isoflavone and saponin consistency. Batch release timelines extend due to scarcity of technicians capable of validating 5-20% total flavonoid specifications.
- Food Industry:Functional food manufacturers incorporate extracts into fortified beverages and baked goods, though flavor masking challenges limit inclusion rates.
- Cosmetics:Topical applications leverage coumestan content for antioxidant positioning in premium skincare lines, with smaller batch sizes and higher per-kilogram pricing.
Nutraceuticals anchor volume throughput. Pharmaceuticals command the steepest expansion trajectory.
Application:
Customer type differentiation separates institutional procurement from consumer-direct channels, with animal feed integrators demanding fundamentally different service models than wellness subscription platforms.
- Dietary Supplements:Capsule, tablet, and soft-gel manufacturers purchase standardized powders and liquids through contract manufacturing arrangements. EFSA Novel Food framework validation accelerates incorporation into menopause-support formulations.
- Animal Feed:Poultry and aquaculture operations in Southeast Asia trial flavonoid-enriched premixes for antibiotic-reduction programs, with flowability and uniform dispersion driving granule format preference.
- Functional Foods:Beverage and bakery applications require solubility-optimized liquid extracts, though heat stability constraints limit processing flexibility.
- Personal Care:Cosmetic formulators source smaller volumes with premium positioning, emphasizing organic certification and clean-label extraction methods.
Dietary Supplements command installed base concentration. Animal Feed is gaining share fastest.
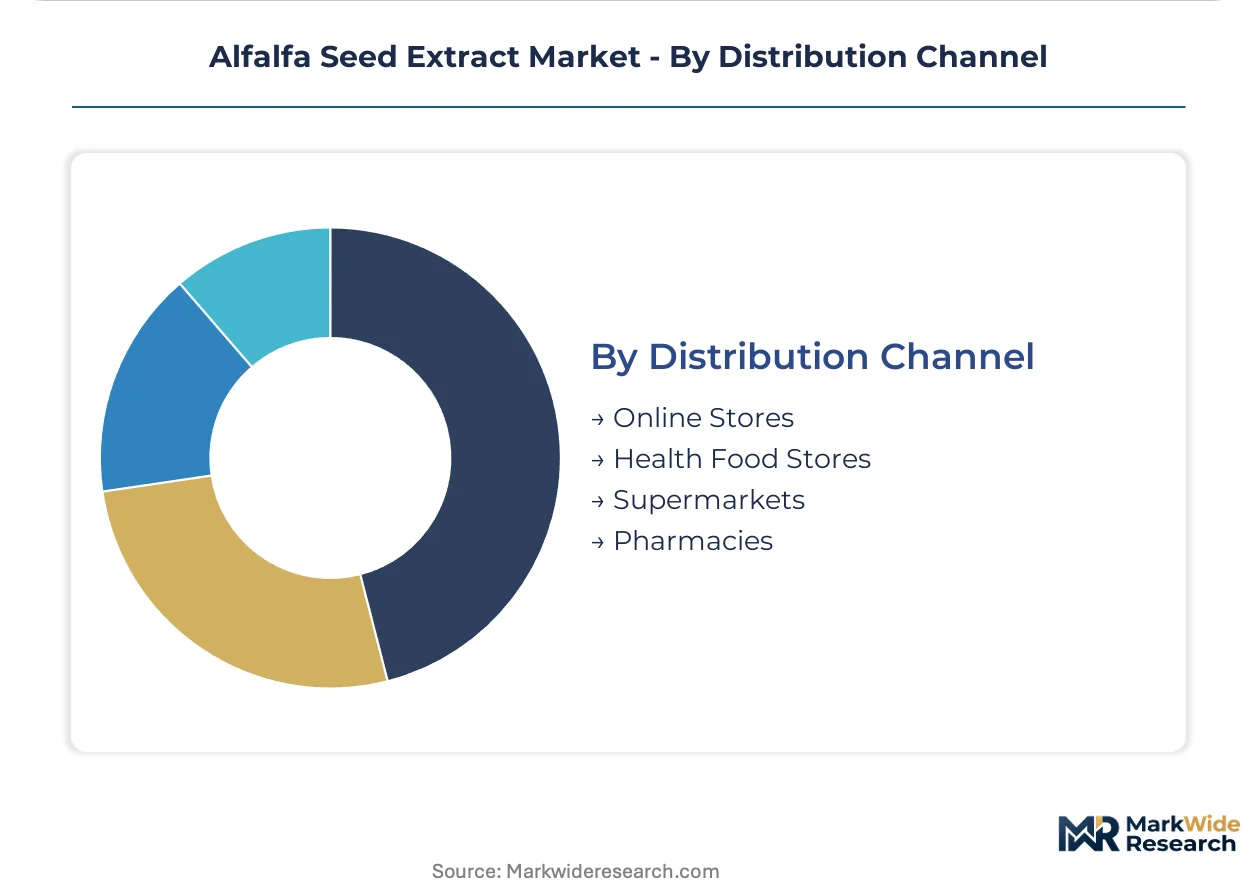
Distribution Channel:
Supply concentration varies by fulfillment infrastructure, with certified organic SKUs bottlenecking through health food specialists while commodity-grade powders flow through diversified wholesale networks.
- Health Food Stores:Independent and chain retailers in North America and Europe require third-party USP or NSF certification, consolidating procurement around vertically integrated extractors with documented seed-to-extract traceability.
- Online Stores:Direct-to-consumer platforms capture margin pools previously retained by retail intermediaries, with subscription wellness services driving recurring revenue models for capsule-format brands.
- Pharmacies:Professional channel distribution serves clinician-recommended supplement lines, with formulary inclusion requiring pharmacopeial-grade documentation.
- Supermarkets:Mass retail placement demands price-competitive positioning, with private-label extraction contracts favoring high-volume, lower-margin powder supply.
Health Food Stores dominate premium-tier distribution. Online Stores are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reshape competitive positioning as certified extractors in Germany and China redirect supply toward compliant channels while North American buyers consolidate procurement around documented seed-to-extract operators.
Germany
EFSA Novel Food framework validation accelerates menopause-support formulation demand from nutraceutical brands. Martin Bauer Group anchors supply through backward integration into seed sourcing across European cultivation networks. Bavaria-based extraction facilities process standardized flavonoid outputs for dietary supplement manufacturers requiring REACH-compliant documentation.
United States
FDA DSHEA compliance and third-party USP certification requirements consolidate procurement among vertically integrated extractors. Sun Prime Extracts occupies specialized organic certification tiers commanding premium positioning in health food retail channels. California and Pacific Northwest health food retailers drive liquid extract SKU expansion for adaptogenic beverage applications.
China
SAMR enforcement of revised GB standards for pesticide residues redirects supply toward certified producers with documented field-level cultivation. Shaanxi Jiaherb Phytochem anchors market position through concentrated R&D investment in standardized extraction protocols. Shaanxi Province extraction clusters face tightened purity thresholds that compress margins for non-compliant operators.
France
ANSM and EFSA dual oversight shapes pharmaceutical-grade extract specifications for clinical applications. Desialis and Nature LLC represent European specialists navigating novel food approval pathways. Paris-region nutraceutical brands accelerate alfalfa-derived ingredient incorporation under harmonized safety assessments.
India
FSSAI evolving botanical ingredient guidelines open formulation pathways for standardized isoflavones in Ayurveda-integrated supplements. Maharashtra and Gujarat dietary supplement manufacturers trial imported extracts for domestic menopause-support positioning. Import dependency on Chinese and European certified extractors persists pending domestic standardization infrastructure maturation.
Alfalfa Seed Extract Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated extractors capable of delivering standardized certificates of analysis, while spot-market dependent operators face margin compression from dual-testing protocols. Three archetypes dominate: seed-to-extract operators with captive organic acreage, contract manufacturers leasing supercritical CO2 capacity, and regional traders without cultivation control. Competitive moves concentrate on backward integration into seed sourcing and geographic expansion into India and Southeast Asia.
Within the integrated extraction tier, Martin Bauer Group and Shaanxi Jiaherb Phytochem exemplify divergent regional models—European backward integration versus Chinese R&D-intensive standardization. Sun Prime Extracts occupies a specialized position in North American organic certification tiers. These three anchors illustrate how regulatory compliance capabilities and cultivation control separate sustainable margin capture from commodity trading exposure.
| Leading Market Players |
|---|
| Martin Bauer Group |
| Sun Prime Extracts |
| Desialis |
| Nature LLC |
| LiquaDry |
| Shaanxi Jiaherb Phytochem |
| Naturalin |
| Nanjing Zhi Bai Cui Biology Technology |
| Changsha Active Ingredients Group |
| Others |
Value Network & Pricing Analysis
Shaanxi Province extraction clusters anchor global powder supply, with capacity utilization rates at captive facilities directly transmitting downstream to contract pricing power among certified operators. Dual-testing protocols for EU REACH and China's SAMR GB standards compress margins for spot-market dependent competitors while concentrating procurement among vertically integrated extractors with documented seed-to-extract traceability.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake pricing structure, with nutraceutical manufacturers locking in 12-18 month supply agreements to hedge against alfalfa seed price volatility. Price differentiation hinges on organic certification tier and chromatographic validation depth, with NSF-certified extracts commanding substantial premiums over commodity-grade powders. Pricing pressure stems from input cost volatility in drought-affected growing regions, squeezing extractor margins when contract pricing locks in advance. Animal feed integrators exhibit highest price sensitivity due to volume scale and substitution options, while pharmaceutical-grade buyers prioritize consistency over cost.
Supply Chain Analysis
Alfalfa seed stocks concentrate among certified organic growers in the United States, Australia, and Canada, with germplasm quality determining downstream extract standardization feasibility. Extraction capacity draws from aqueous and solvent-based processing infrastructure, supercritical CO2 systems, and spray-drying equipment, with solvent recovery investments becoming decisive cost differentiators. Single-source vulnerability concentrates in certified organic seed supply, where multi-year crop rotation requirements limit rapid supplier switching. Distribution runs through health food retail channels requiring third-party USP or NSF certification, alongside direct-to-consumer subscription platforms capturing margin pools previously retained by wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The alfalfa seed extract market operates as a regulatory entrenchment story, where EFSA Novel Food dossier expertise and SAMR GB compliance capabilities construct durable defensive moats against commodity trading competitors.
For Market Incumbents: Pre-empt margin compression by deepening backward integration into captive organic seed acreage across North American and Australian cultivation networks, while accelerating supercritical CO2 capacity deployment to serve EFSA-compliant brands demanding clean-label positioning. Dual-testing protocol costs threaten spot-market dependent operators; consolidate procurement relationships through multi-year supply agreements with menopause-support formulation specialists.
For New Entrants and Emerging Players: Pursue white-space opportunities in India's FSSAI-regulated Ayurveda-integrated supplement channel, where domestic standardization infrastructure remains underdeveloped and import dependency on certified extractors persists. Southeast Asian poultry and aquaculture integrators trial flavonoid-enriched feed additives, offering the most penetrable application segment for antibiotic-reduction program positioning. A certification-first go-to-market angle, emphasizing USDA Organic and EU Organic equivalence documentation, bypasses established supplier relationships in premium health food retail channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified botanical extract houses with underutilized alfalfa-specific chromatography capacity and dormant organic certification assets. Long-term viability centers on regulatory compliance capabilities rather than commodity trading scale, favoring seed-to-extract operators with documented field-level cultivation practices. Monitor SAMR enforcement intensity as the critical inflection signal, as tightened GB standards for pesticide residues accelerate supply redirection toward certified producers with upstream sourcing control.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Sourcing | Martin Bauer Group's European cultivation networks demonstrate margin control through captive germplasm supply. |
| Supercritical CO2 Capacity Expansion | German contract manufacturers adopt these systems to serve EFSA-compliant brands demanding terpene preservation without residual solvent concerns. |
| Novel Food Dossier Investment | EFSA framework validation accelerates menopause-support formulation incorporation, creating validated demand pull under harmonized safety assessments. |
| Organic Certification Maintenance | Annual third-party audits for USDA Organic and EU Organic equivalence sustain premium positioning in North American health food channels. |
| Direct-to-Consumer Channel Development | Subscription wellness platforms bypass traditional wholesale distribution, capturing margin pools previously retained by retail intermediaries. |
Research Methodology
Cross-validation between primary interviews with extraction facility operators, regulatory affairs specialists at nutraceutical brands, and procurement managers at contract manufacturers anchors the qualitative findings. Secondary sources include SAMR GB standard documentation, EFSA Novel Food guidance publications, FDA DSHEA compliance records, and customs/trade data on botanical extract flows. Bottom-up triangulation across product type, end user, application, and distribution channel segmentation dimensions converges with top-down market sizing approaches.
Calibration against historical capacity utilization rates at Shaanxi Province extraction clusters and organic seed acreage expansion patterns across North America and Australia validates the analytical framework across the projection horizon. Segmentation modeling incorporates formulation format, certification tier, end-use channel, and geographic regulatory cluster dimensions. CAGRs derive from regression analysis of procurement volume trends, with flavonoid standardization protocol adoption rates and supercritical CO2 capacity deployment timelines serving as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in drought frequency across major alfalfa growing regions or abrupt SAMR enforcement escalations would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway durations and certification maintenance costs. Cross-checking against EFSA Novel Food approval timelines and organic seed stock availability benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Processing Innovations
Soybean Seed Treatment Market
Seed Processing Innovations
Rice Seed Treatment Market
Seed Processing Innovations
Fenugreek Seed Extract Market
Seed Processing Innovations
North America Soybean Seed Treatment Market
Seed Processing Innovations
Kiwi Seed Extract Market
Seed Processing Innovations
North America Seed Treatment Market
Seed Processing Innovations
United States Seed Treatment Market
Seed Processing Innovations
Australia Seed Treatment Market
Seed Processing Innovations
Argentina Seed Treatment Market
Seed Processing Innovations
India Seed and Grain Cleaning and Grading Machine Market
Seed Processing Innovations
Maize Seed Treatment Market
Seed Processing Innovations
Asia-Pacific Seed Treatment Market
Seed Processing Innovations
Seed Sorting Machine Market
Seed Processing Innovations
South America Seed Treatment Market
Seed Processing Innovations
Italy Seed Treatment Market
Seed Processing Innovations
Brazil Seed Treatment Market