
 Industrial Air Compressor Market | 2026-2036
Industrial Air Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Air Compressor Market Intelligence
Buyer concentration in automotive manufacturing is rebalancing toward tier-one suppliers and EV battery producers seeking dedicated compressed air infrastructure. Atlas Copco leverages its oil-free compressor portfolio to dominate semiconductor-adjacent clean air applications. Kaeser Kompressoren sustains German engineering credibility through energy-efficient rotary screw systems. ELGi Equipments anchors cost-competitive positioning across Asian manufacturing hubs with localized assembly and aftermarket networks.
An industrial air compressor is a mechanical device that converts power into potential energy stored in pressurized air, typically achieving discharge pressures from 100 to 175 psi through positive displacement or dynamic compression principles. The equipment powers pneumatic tools, automated assembly lines, and process air systems across factories, construction sites, and material handling operations. Rotary screw compressors occupy the core revenue pool due to continuous-duty reliability in manufacturing environments, while oil-free technology captures expanding margins in food processing and pharmaceutical applications where ISO 8573 Class 0 purity is mandatory. Variable speed drive configurations represent the fastest-growing technology segment as facilities prioritize energy recovery and demand-responsive output over fixed-speed baseload units.
EPA energy efficiency standards under the Clean Air Act compel compressor manufacturers to publish verified performance data and phase out legacy lubricated designs in US industrial installations. ISO 8573 purity classes and EU F-Gas Regulation restrict synthetic lubricant formulations and refrigerant-based dryer chemistries across European markets. OSHA workplace noise exposure limits shape enclosure engineering and drive demand for low-decibel scroll compressor alternatives in indoor manufacturing. Stakeholders must monitor how carbon border adjustment mechanisms and regional energy pricing divergences reshape total cost-of-ownership calculations for fleet replacement decisions.
Market Dynamics
Variable speed drive technology is compressing replacement cycles across manufacturing fleets as energy pricing volatility forces facilities to prioritize demand-responsive output over fixed-speed baseload units. Oil-free compressor architectures are displacing legacy lubricated designs in food processing and pharmaceutical clean rooms where ISO 8573 Class 0 purity is non-negotiable.
Growth Catalysts
- EPA Clean Air Act efficiency mandates:Verified performance data requirements are phasing out legacy designs and accelerating verified equipment turnover across US industrial installations.
- EV battery manufacturing expansion:Gigafactory construction in Germany's industrial corridor is pulling dedicated compressed air infrastructure for electrode coating and dry room operations.
- Semiconductor fabrication:Clean-room air quality specifications in advanced node production are mandating oil-free rotary screw and scroll compressor deployments.
Market Restraints
- Copper and rare-earth magnet cost volatility:Electric motor and permanent magnet rotor supply exposure constrains variable speed drive compressor pricing stability.
- Supply concentration in German precision engineering:Rotary screw airend manufacturing clusters in Bavaria and Baden-Württemberg create single-source vulnerability for premium efficiency tiers.
- EU F-Gas Regulation refrigerant restrictions:Desiccant and refrigerant dryer chemistries face reformulation timelines that compress product certification windows.
Strategic Opportunities
- India's PLI scheme for manufacturing:Localized compressor assembly and captive aftermarket networks can anchor cost-competitive positioning in Asian industrial hubs.
- Carbon border adjustment mechanisms:EU CBAM implementation creates first-mover advantage for manufacturers documenting lifecycle carbon intensity of compressor fleets.
- Digital twin integration:Predictive maintenance platforms converging with compressor control systems open recurring revenue streams in fleet management services.
Industry Challenges
- Compressed air system auditor certification gaps:Shortage of ISO 50001 energy management specialists delays efficiency audit backlogs and extends sales cycles.
- Legacy pneumatic infrastructure integration:Retrofitting variable speed drives into existing fixed-speed distribution networks requires custom control architecture engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Air Compressor Market |
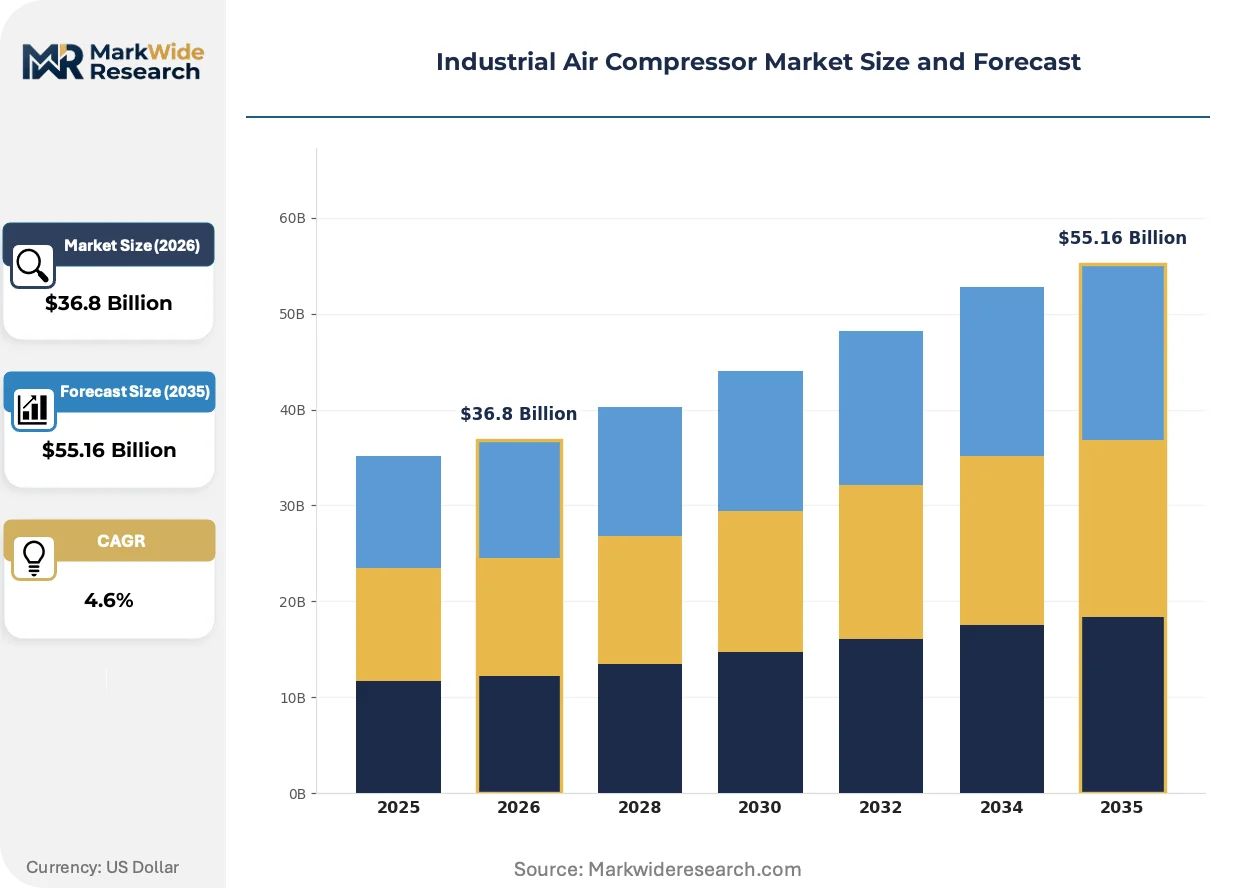
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $55.16 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating Compressors, Rotary Screw Compressors, Centrifugal Compressors, Scroll Compressors End User: Manufacturing, Construction, Automotive, Food Processing Technology: Oil-Free Technology, Lubricated Technology, Variable Speed Drive, Multi-Stage Compression Application: Pneumatic Tools, Spray Painting, Sandblasting, Material Handling |
| Companies Covered | Atlas Copco, Ingersoll Rand, Doosan Infracore, Kaeser Kompressoren, Gardner Denver, Mitsubishi Heavy Industries, Hitachi, Sulzer, ELGi Equipments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Air Compressor Market Strategic Shifts & Innovations
Electrification of industrial processes and tightening carbon accounting standards are rewriting how compressed air systems are specified, monitored, and financed across manufacturing verticals.
Magnetic bearing turbo compressor technology is rewriting efficiency benchmarks in large-scale process air applications. Chemical processing and wastewater treatment facilities in the Netherlands and Belgium are adopting oil-free turbo designs for continuous-duty aeration and pneumatic conveying. The elimination of gearbox and lubricant maintenance intervals is compressing total cost-of-ownership calculations against traditional centrifugal alternatives.
REACH regulation restrictions on synthetic lubricant formulations are forcing reformulation of compressor fluids across European installations. Manufacturers must now certify biodegradable and low-toxicity alternatives for rotary screw and vane compressor applications. Food processing and pharmaceutical end-users in Germany and France are accelerating qualification timelines for compliant fluid chemistries ahead of enforcement deadlines.
Compressed air-as-a-utility contracting models are displacing capital purchase patterns among mid-sized manufacturing facilities. Third-party operators in the US Midwest and Southeast are installing and maintaining on-site compressor systems while charging per-cubic-meter consumption fees. Automotive tier-one suppliers in Michigan and Ohio are piloting these arrangements to offload balance-sheet equipment ownership and energy risk.
Industrial Air Compressor Market Segmentation
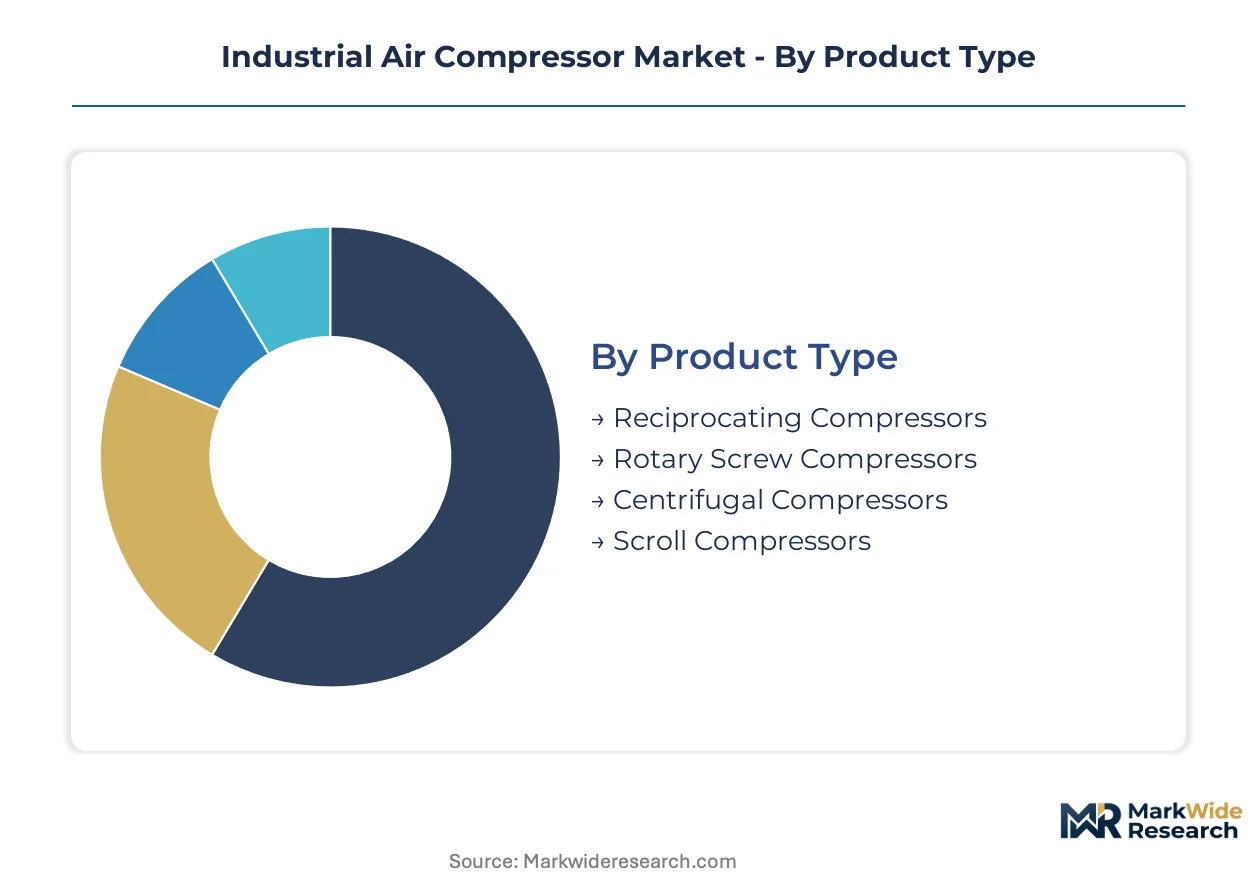
Industrial air compressor segmentation reveals how specification requirements diverge across duty cycles, purity mandates, and energy recovery priorities. Technology choices cascade through product architecture, end-use qualification, and total cost-of-ownership calculations.
Product Type:
Compression mechanism determines reliability profiles, maintenance intervals, and pressure range suitability across industrial environments.
- Rotary Screw Compressors:Positive displacement systems using intermeshing helical rotors deliver continuous-duty airflow with minimal pulsation. German automotive clusters and precision manufacturing corridors anchor replacement demand as facilities retire legacy fixed-speed baseload units.
- Centrifugal Compressors:Dynamic compression via high-speed impellers achieves large-volume process air delivery above 500 hp. Chemical processing installations in the Netherlands and Belgium adopt oil-free turbo variants for aeration and pneumatic conveying applications.
- Reciprocating Compressors:Piston-driven positive displacement suits intermittent-duty workshops and portable construction sites requiring pressures above 200 psi.
- Scroll Compressors:Orbiting spiral compression delivers oil-free air with minimal noise signatures, qualifying for indoor pharmaceutical clean rooms where OSHA noise limits apply.
Mature deployment sits with rotary screw systems in general manufacturing. Newer deployment is concentrated in scroll compressors for ISO 8573 Class 0 environments.
End User:
Industry-specific air quality and reliability standards reshape compressor specification priorities and service contract structures.
- Manufacturing:Automated assembly lines and robotic work cells require uninterrupted compressed air supply with demand-responsive output capabilities. Tier-one suppliers in Michigan and Ohio are piloting air-as-a-utility contracting to offload capital ownership.
- Food Processing:Clean-room operations and packaging lines mandate oil-free compression meeting FDA sanitation standards and ISO 8573 purity classifications. EPA efficiency mandates accelerate verified equipment turnover in US protein processing plants.
- Automotive:EV battery gigafactories pull dedicated compressed air infrastructure for electrode coating and dry room humidity control.
- Construction:Portable reciprocating units power pneumatic breakers and fastening tools on job sites with intermittent duty cycles.
Volume concentration clusters in manufacturing baseload operations. Margin expansion is steepest in food processing purity-compliant installations.
Technology:
Energy recovery architectures and lubrication strategies define efficiency compliance and regulatory qualification pathways.
- Variable Speed Drive:Permanent magnet motors with demand-responsive output modulate airflow to match real-time consumption, compressing energy waste in fluctuating load environments. Copper and rare-earth magnet cost volatility constrains pricing stability for premium efficiency tiers.
- Oil-Free Technology:Dry-running rotors and coated airends eliminate lubricant contamination risk for semiconductor fabrication and pharmaceutical packaging. EU F-Gas Regulation restrictions on synthetic formulations accelerate fluid chemistry reformulation timelines.
- Lubricated Technology:Oil-flooded compression remains cost-advantaged for general industrial applications without purity mandates.
- Multi-Stage Compression:Intercooled sequential compression improves thermodynamic efficiency for high-pressure process applications.
Installed base dominance belongs to lubricated fixed-speed systems. Technology transition is accelerating toward variable speed drive configurations.
Application:
Downstream equipment specifications dictate pressure stability, moisture control, and particulate filtration requirements.
- Pneumatic Tools:Impact wrenches, grinders, and nailers require consistent pressure delivery between 90-120 psi with rapid cycle response. Construction fleets and automotive assembly stations drive portable and stationary compressor demand.
- Material Handling:Conveyor systems and pneumatic actuators in distribution centers prioritize continuous-duty reliability over pressure extremes.
- Spray Painting:Coating applications demand moisture-free air to prevent finish defects, pulling refrigerated and desiccant dryer integration.
- Sandblasting:Surface preparation operations consume high-volume airflow at elevated pressures, favoring two-stage reciprocating or rotary screw configurations.
Standard practice centers on pneumatic tool supply. Application expansion is gaining traction in automated material handling with predictive maintenance integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany's industrial corridor, where automotive and precision manufacturing clusters anchor replacement cycles. EPA efficiency mandates and ISO 8573 purity classes push oil-free technology upgrades across food processing plants expanding clean-room operations.
United States
EV battery gigafactories in Michigan and Ohio pull dedicated compressed air infrastructure for electrode coating and dry room humidity control. EPA Clean Air Act efficiency mandates compel manufacturers to publish verified performance data and phase out legacy lubricated designs. Automotive tier-one suppliers in the Midwest pilot compressed air-as-a-utility contracting to offload capital ownership.
Germany
Rotary screw airend manufacturing clusters in Bavaria and Baden-Württemberg create supply concentration for premium efficiency tiers. EU F-Gas Regulation restricts synthetic lubricant formulations and refrigerant-based dryer chemistries. Precision engineering corridors around Stuttgart and Munich sustain replacement demand as facilities retire fixed-speed baseload units.
China
Semiconductor fabrication clean-room specifications mandate oil-free compressor deployments for advanced node production. MIIT energy efficiency standards accelerate verified equipment turnover in industrial installations. Yangtze River Delta manufacturing hubs prioritize demand-responsive variable speed drive configurations amid energy pricing volatility.
India
PLI scheme incentives for manufacturing anchor localized compressor assembly and captive aftermarket networks. BIS certification requirements shape product qualification timelines for domestic industrial installations. Gujarat and Maharashtra industrial corridors drive cost-competitive positioning for general manufacturing baseload operations.
Netherlands
Chemical processing and wastewater treatment facilities adopt oil-free turbo designs for continuous-duty aeration applications. REACH regulation restrictions force reformulation of compressor fluids ahead of enforcement deadlines. Rotterdam-Antwerp petrochemical cluster compresses total cost-of-ownership calculations against traditional centrifugal alternatives.
Industrial Air Compressor Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue digital service integration and energy-as-a-utility contracting models. The vendor base stratifies across premium engineering specialists, scale-driven diversified industrials, and cost-optimized regional assemblers. Two dominant competitive moves are reshaping positioning: strategic partnerships for predictive maintenance platform integration, and geographic expansion through localized assembly joint ventures in Asian manufacturing hubs.
Within the premium engineering tier, Atlas Copco and Kaeser Kompressoren exemplify European precision manufacturing archetypes. ELGi Equipments occupies a position among cost-competitive regional specialists with localized production footprints. These three anchors illustrate how competitive positioning diverges across technology sophistication, geographic reach, and service model intensity.
| Leading Market Players |
|---|
| Atlas Copco |
| Ingersoll Rand |
| Doosan Infracore |
| Kaeser Kompressoren |
| Gardner Denver |
| Mitsubishi Heavy Industries |
| Hitachi |
| Sulzer |
| ELGi Equipments |
| Others |
Cost & Logistics Intelligence
Copper and rare-earth magnet pricing volatility cascades through variable speed drive compressor manufacturing, feeding from upstream mining concentrations in Chile and China through tiered equipment pricing in German automotive clusters and US EV battery facilities.
Pricing Analysis
Volume concentrates in lubricated fixed-speed rotary screw baseload units while margin expansion accrues to oil-free and variable speed drive configurations. Price differentiation separates ISO 8573 Class 0 certified systems from general industrial tiers, with energy efficiency ratings and after-sales service bundling as secondary drivers. Pricing pressure stems from copper and permanent magnet cost volatility constraining premium efficiency tiers. Tier-one automotive suppliers in Michigan and Ohio exhibit highest price sensitivity through air-as-a-utility contracting pilots, while semiconductor fabs in Germany and China show lowest sensitivity due to purity mandate non-negotiability.
Supply Chain Analysis
Rotary screw airend manufacturing rests on precision engineering clusters in Germany, Japan, and Italy, with final assembly drawing from localized facilities in India and China for cost-competitive positioning. Critical inputs include high-grade cast iron for airend housings, permanent magnet rotors for variable speed drives, and synthetic lubricants facing REACH reformulation timelines. Single-source vulnerability concentrates in Bavarian and Baden-Württemberg precision machining for premium efficiency tiers. Distribution runs through OEM direct sales for large installations, regional distributors for mid-market manufacturing, and captive aftermarket networks for service contract retention.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Clean Air Act efficiency mandates and EU F-Gas Regulation restrictions erect compliance moats that favor incumbent engineering specialists with verified certification pipelines and documented lifecycle carbon intensity.
For Market Incumbents: Hedge against rare-earth magnet supply exposure through backward integration into permanent magnet sourcing or alternative motor topology R&D. Defend margin position in oil-free segments by accelerating ISO 8573 Class 0 qualification timelines ahead of enforcement deadlines, while compressing aftermarket service response times through predictive maintenance platform deployment. For New Entrants and Emerging Players: Enter via India's PLI scheme manufacturing incentives to anchor localized assembly and captive service networks. Target mid-sized food processing facilities in Southeast Asia with cost-optimized oil-free scroll configurations. Pursue digital twin integration partnerships with established controls vendors to bypass proprietary platform development costs. For Investors and Strategic Acquirers: Atlas Copco's oil-free compressor portfolio expansion is the leading indicator that semiconductor-adjacent clean air applications are consolidating toward integrated system providers. Long-term viability favors specialists with documented carbon intensity metrics and predictive maintenance recurring revenue streams. Watch for carbon border adjustment mechanism enforcement timelines as the signal for accelerated fleet replacement financing demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Supply | Mitigates rare-earth cost volatility for variable speed drive motor production. |
| ISO 8573 Class 0 Certification Acceleration | Captures food processing and pharmaceutical margin expansion ahead of enforcement deadlines. |
| Predictive Maintenance Platform Deployment | Converts equipment sales into recurring fleet management revenue streams with OEMs. |
| Localized Assembly Joint Ventures | Secures PLI scheme benefits and aftermarket network density in Indian industrial corridors. |
| Carbon Intensity Documentation Systems | Positions compliant fleets for EU CBAM first-mover advantage in replacement cycles. |
Research Approach
Independent corroboration across maintenance directors at automotive tier-one suppliers, plant engineers in German precision manufacturing clusters, aftermarket service heads at regional distributors, and procurement teams at food processing facilities underwrites the qualitative findings. Secondary validation draws from EPA Clean Air Act filings, EU ECHA REACH substance registrations, SEC 10-K equipment disclosures, and customs trade data for compressor component flows. Bottom-up triangulation across end-user specification requirements and top-down validation against installed base estimates anchor the analysis.
Rate-of-change decomposition separates volume growth from mix shift toward premium efficiency tiers and oil-free configurations across the analysis window. Segmentation dimensions include compression mechanism, lubrication strategy, end-use industry, and regional regulatory cluster. CAGRs derive from equipment replacement cycle modeling, energy price elasticity assumptions, and purity mandate compliance timelines. Forecast inputs incorporate MIIT efficiency standard enforcement patterns and semiconductor fabrication capacity expansion announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper price spike scenarios or accelerated EU F-Gas refrigerant restrictions. A small set of named triggers warrants ongoing watch: carbon border adjustment mechanism implementation timelines, rare-earth export licensing shifts, and ISO 50001 energy management auditor certification backlog resolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Portable Compressor Market
Compressors
Hydrogen Compressor Market
Compressors
Liquid Ring Compressors Market
Compressors
Compressor Wheel Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
Asia-Pacific Booster Compressor Market
Compressors
High Speed Blowers Market
Compressors
Oil-Injected Screw Compressor Market
Compressors
Rotary Air Compressor Market
Compressors
Gas Compressors Market
Compressors
PAG Compressor Oil Market
Compressors
Oil Free Compressor Market
Compressors
North America Air Compressor Market
Compressors
Positive-Displacement Hydrogen Compressor Market
Compressors
Reciprocating Air Compressor Market
Compressors
Oil Filled Air Compressor Market