
 Delayed Coker Unit Market | 2026-2036
Delayed Coker Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Delayed Coker Unit Market Outlook
Modular coker unit configurations is broadening buyer choice across the delayed coker landscape. Honeywell UOP leverages its technology leadership in process licensing to anchor premium project economics. Lummus Technology competes through specialized reactor system designs that sustain engineering margins on complex refinery upgrades. McDermott International dominates large-scale EPC execution, positioning its fabrication yards for multi-unit installations.
A delayed coker unit thermally cracks heavy residual oil feedstock at temperatures near 480°C to produce lighter distillates, petroleum coke, and gas oils for downstream processing. Vacuum distillation technology leads the technology segment due to its integration with upstream atmospheric units in modern refineries, while reactor systems represent the fastest-growing category as operators seek higher liquid yields from inferior crudes. Refinery application captures the dominant share of installed base, though bitumen processing is gaining traction in markets with heavy oil reserves.
EPA emission standards and the EU Green Deal's carbon border adjustments are reshaping coker unit design requirements, pushing operators toward coke gasification and carbon capture integration. India's CEA mandates and China's MEE environmental rules are tightening particulate and SOx limits for refinery expansions. Stakeholders must monitor regulatory divergence between jurisdictions when standardizing equipment specifications for multinational project portfolios.
Market Dynamics
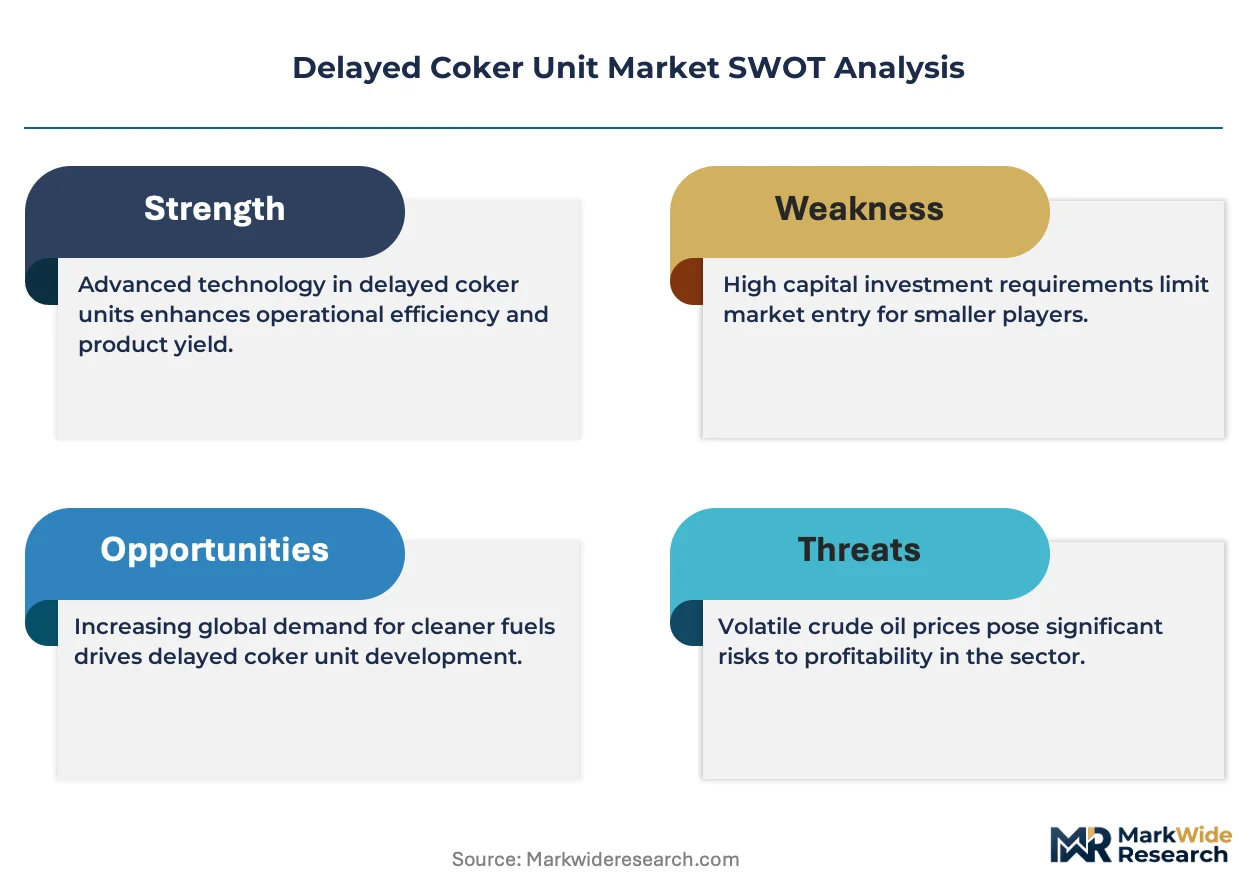
The delayed coker unit sector faces intensifying pressure from carbon border adjustments and coke gasification mandates that are restructuring capital allocation across refinery portfolios. Operators now weigh residual upgrading economics against emissions compliance costs when committing to new coker installations.
Growth Catalysts
- India's CEA mandates:The Central Electricity Authority's environmental standards for refinery expansions are accelerating coker unit deployments at greenfield complexes in Gujarat and Rajasthan.
- Heavy crude processing:Refinery operators across Asia-Pacific are expanding coker capacity to process inferior crudes with higher sulfur and metal content.
- Transportation fuel demand:India's refining sector is adding delayed coker units to maximize gasoline and diesel yields from domestic heavy oil reserves.
Market Restraints
- High-temperature metallurgy costs:Reactor vessel fabrication requires specialized chrome-molybdenum steel alloys subject to volatile nickel pricing.
- Engineering talent concentration:Process design expertise for complex coker configurations clusters in Houston, Tokyo, and The Hague, creating procurement bottlenecks.
- Residual fuel oil substitution:Marine fuel sulfur regulations under IMO standards are compressing bunker fuel demand, eroding the economic case for some coker investments.
Strategic Opportunities
- China's dual carbon goals:National carbon neutrality targets are creating incentives for coke gasification integration with carbon capture at Sinopec and PetroChina refineries.
- Modular unit configurations:Skid-mounted coker designs are opening mid-scale refinery upgrades in Southeast Asia previously excluded from project economics.
- Bitumen processing applications:Canadian oil sands operators are deploying delayed coker technology for heavy bitumen upgrading beyond traditional refinery settings.
Industry Challenges
- Weld integrity certification:Pressure vessel fabrication for 480°C operating conditions requires ASME Section VIII compliance timelines extending 18-24 months.
- Legacy control system integration:Digital twin deployment for coker optimization must interface with decades-old DCS infrastructure at established refineries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Delayed Coker Unit Market |
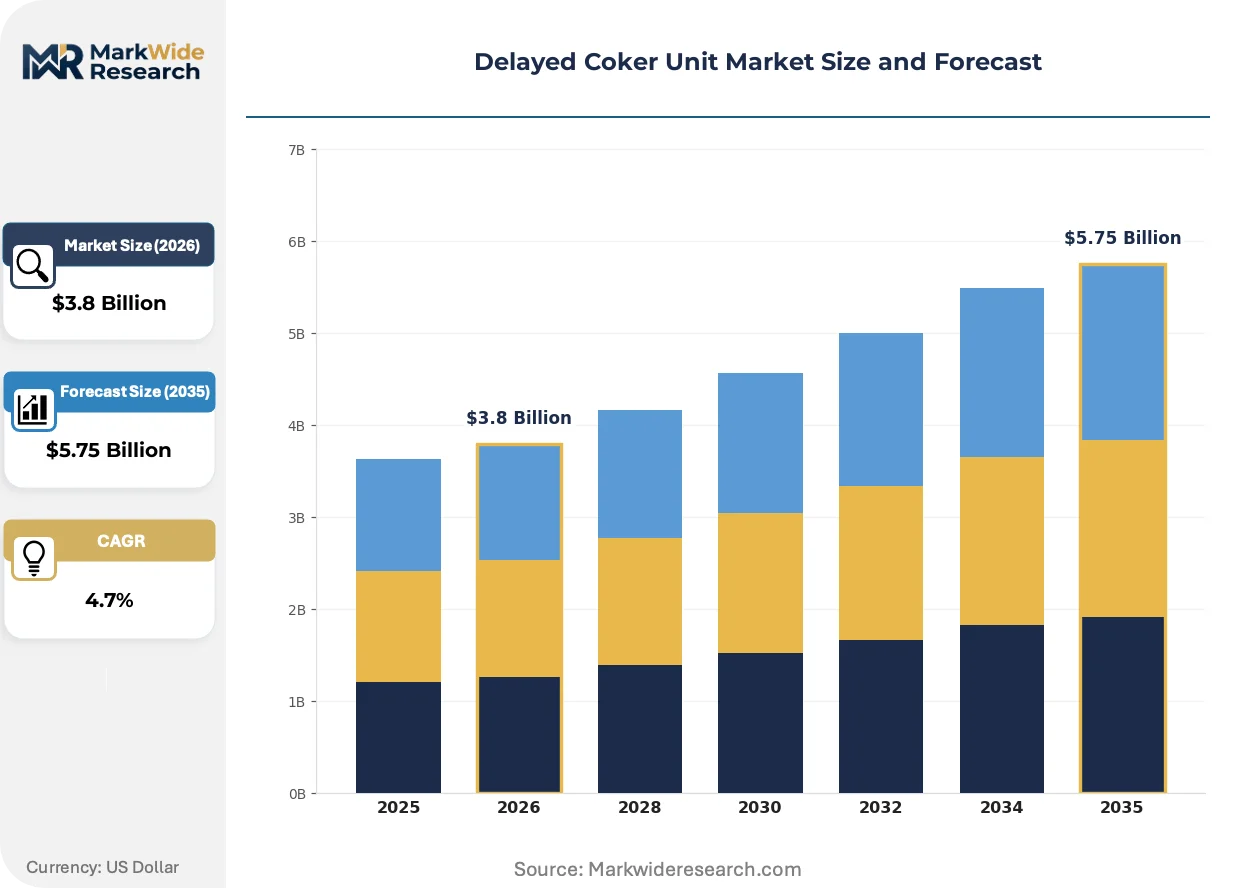
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Vacuum Distillation, Heat Exchangers, Condensers, Reactor Systems Application: Refinery, Petrochemical Production, Coal Upgrading, Bitumen Processing Service Type: Maintenance, Installation, Consulting, Operational Support End User: Oil Refineries, Chemical Manufacturers, Energy Sector, Industrial Users |
| Companies Covered | Sulzer, McDermott International, Bechtel Corporation, Worley Parsons Limited, CNPC, Lummus Technology, Honeywell UOP, MOGAS Industries, Wood PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Delayed Coker Unit Market Strategic Shifts
Process intensification and emissions abatement technologies are converging to redefine delayed coker unit design specifications. The competitive frontier now centers on liquid yield maximization rather than throughput scale alone.
Advanced reactor quench systems are unifying thermal cracking control with real-time temperature management. Refinery operators in the Middle East are retrofitting existing units with automated quench injection to suppress secondary coking reactions. This convergence is compressing the performance gap between conventional and high-specification coker designs.
EU Green Deal carbon border adjustments are forcing equipment suppliers to document embodied emissions across coker unit supply chains. Fabricators must now provide lifecycle carbon footprints for reactor vessels and coke drums to access European refinery projects. Asian equipment manufacturers are responding by relocating carbon-intensive casting operations to regions with lower grid emissions intensity.
After-sales service unbundling is fragmenting the traditional EPC bundled model. Refinery operators in India and China are separating process licensing from construction execution, awarding reactor system design to technology specialists while sourcing fabrication from independent yards. This disaggregation is most pronounced at Reliance Industries and Saudi Aramco joint venture projects where modular procurement reduces single-source dependency.
Delayed Coker Unit Market Segmentation
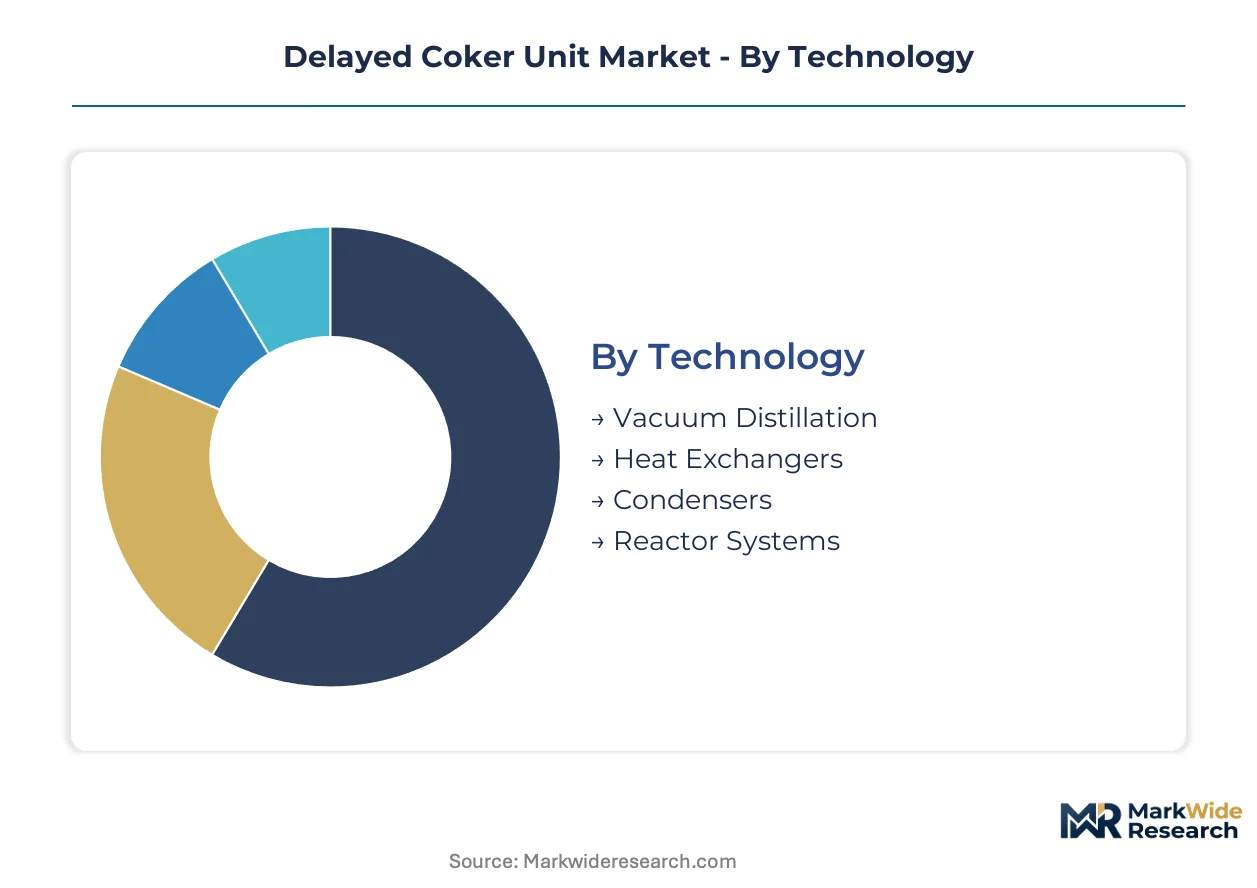
Delayed coker unit segmentation reveals how capital allocation splits between mature refinery infrastructure and emerging heavy oil applications. Equipment suppliers configure reactor systems, heat exchangers, and service portfolios differently depending on whether buyers operate legacy complexes or greenfield bitumen upgrading facilities.
Technology:
Supply concentration for critical components centers on specialized fabricators with ASME Section VIII certification for high-temperature pressure vessels.
- Vacuum Distillation:This upstream integration technology separates heavy residual fractions at reduced pressure before coker feed preparation. Indian refiners in Gujarat and Rajasthan specify vacuum distillation packages to handle domestic heavy crude slates with elevated sulfur content.
- Reactor Systems:Thermal cracking vessels operating near 480°C require chrome-molybdenum steel alloys with precise weld integrity. Chinese operators under MEE environmental rules are retrofitting reactor systems with automated quench injection to suppress secondary coking and improve liquid yields.
- Heat Exchangers:Shell-and-tube configurations recover energy from hot coke vapors to preheat incoming feedstock.
- Condensers:Overhead cooling systems handle vapor recovery from coke drums and fractionation towers.
Vacuum distillation absorbs the bulk of installed capacity; reactor systems are expanding most quickly as operators pursue higher liquid yields from inferior crudes.
Application:
Cost tier differentiation separates large-scale refinery deployments from modular bitumen processing installations with lower capital intensity.
- Refinery:Integrated delayed coker units process atmospheric and vacuum residuum into transportation fuels and feedstocks. Sinopec and PetroChina refineries are adding coke gasification integration to align with China's dual carbon goals and carbon neutrality targets.
- Bitumen Processing:Canadian oil sands operators deploy coker technology outside traditional refinery boundaries for heavy bitumen upgrading. This application is gaining traction as steam-assisted gravity drainage projects seek downstream integration.
- Petrochemical Production:Coker-derived gas oils feed ethylene crackers and aromatics complexes.
- Coal Upgrading:Delayed coking principles apply to coal liquefaction and synthetic fuel production.
Refinery applications command the dominant share of current deployments; bitumen processing shows the steepest expansion trajectory as heavy oil producers seek captive upgrading capacity.
Service Type:
Customer type fragmentation is unbundling the traditional EPC bundled model across Asian project portfolios.
- Maintenance:Coke drum replacement cycles and refractory repairs sustain long-term unit availability. Indian operators at Reliance Industries complexes separate maintenance procurement from initial construction to reduce single-source dependency.
- Installation:Field erection of reactor vessels and coke drums requires specialized heavy-lift coordination. Saudi Aramco joint ventures are sourcing installation from independent yards while retaining process licensing from technology specialists.
- Consulting:Process optimization studies and yield improvement assessments support operational decisions.
- Operational Support:Remote monitoring and technical assistance supplement in-house engineering teams.
Maintenance captures the largest recurring revenue pool; installation is climbing the fastest as modular procurement patterns spread across Southeast Asian project markets.
End User:
Volume concentration tracks crude slate heaviness and transportation fuel demand across major refining centers.
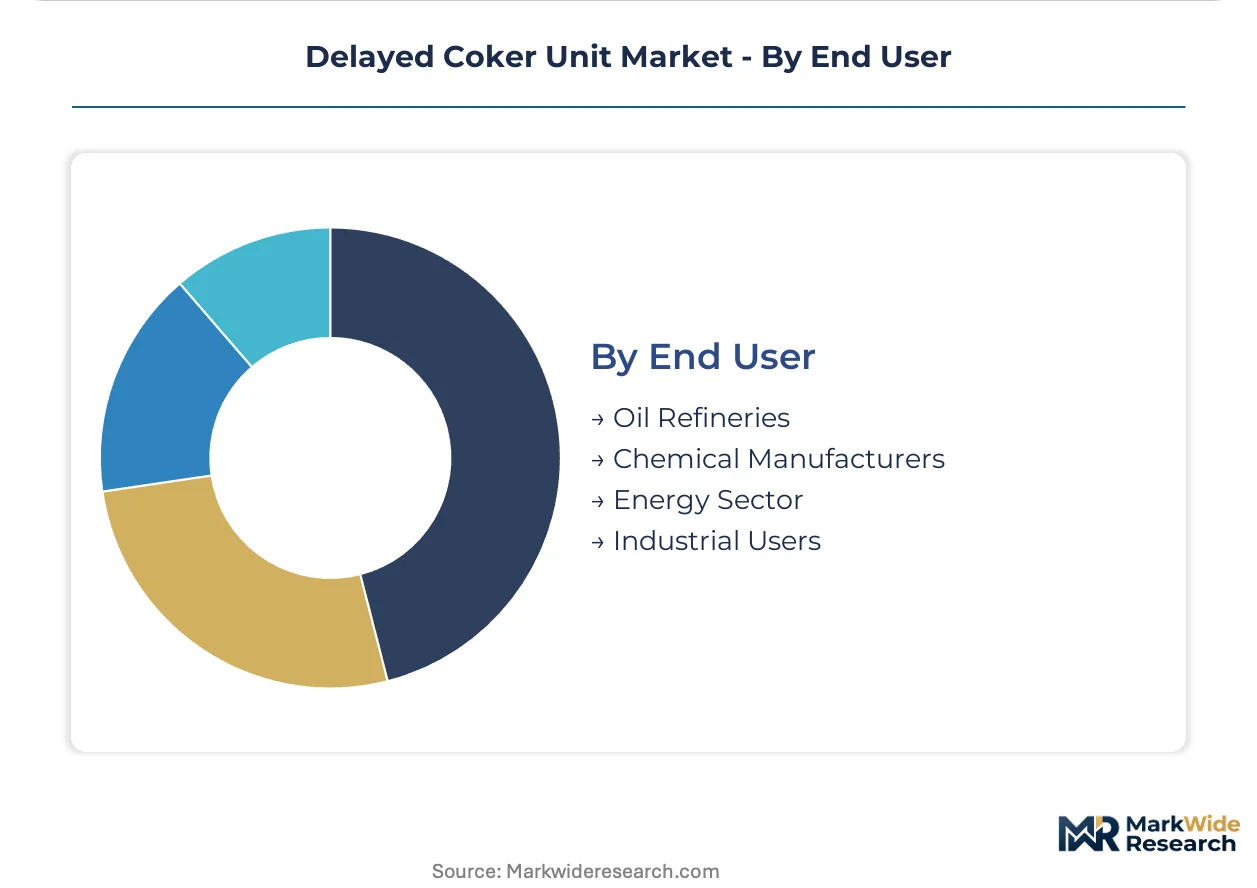
- Oil Refineries:Integrated refining complexes represent the core demand base for delayed coker capacity additions. China's greenfield refinery builds are maximizing gasoline and diesel yields from domestic heavy oil reserves through coker unit integration.
- Chemical Manufacturers:Petrochemical producers utilize coker-derived feedstocks for olefins and aromatics production.
- Energy Sector:Power generators and synthetic fuel producers access coker technology for alternative feedstock processing.
- Industrial Users:Steelmakers and cement producers consume petroleum coke as fuel and reducing agent.
Oil refineries anchor the overwhelming majority of unit deployments; chemical manufacturers are gaining share fastest as feedstock flexibility becomes a competitive priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refinery operators in China and India consume the majority of new delayed coker capacity, while fabrication supply concentrates among specialized yards in South Korea and Japan. This production-consumption divide shapes procurement patterns across the project lifecycle.
China
Sinopec and PetroChina are integrating coke gasification with carbon capture at multiple refinery complexes to align with MEE environmental rules and dual carbon goals. The Yangtze River Delta hosts the densest concentration of coker unit deployments, with Zhejiang and Jiangsu provinces adding capacity to process domestic heavy oil reserves.
India
Reliance Industries and Indian Oil Corporation are expanding coker installations at greenfield complexes in Gujarat and Rajasthan to maximize gasoline and diesel yields. CEA mandates for refinery expansions are accelerating project timelines, with the Jamnagar cluster emerging as the primary fabrication coordination hub for domestic and export orders.
United States
Gulf Coast refiners are retrofitting existing coker units with automated quench systems to improve liquid yields from heavier domestic crude slates. EPA emission standards are driving coke gasification investments, with the Houston Ship Channel maintaining its position as the center of process design engineering for complex configurations.
Saudi Arabia
Saudi Aramco joint ventures are separating process licensing from construction execution to reduce single-source dependency on large-scale coker projects. The Eastern Province around Jubail Industrial City is attracting modular fabrication yards to support multi-unit installations serving both domestic and export markets.
South Korea
SK Innovation and GS Caltex are adding coker capacity to process heavier Middle Eastern crude imports at Yeosu and Ulsan refining complexes. The country's specialized pressure vessel fabricators are securing orders for reactor systems requiring ASME Section VIII certification for 480°C operating conditions.
Delayed Coker Unit Market Competitive Environment
The competitive structure tilts toward technology licensors with established process know-how. Market concentration remains moderate, with distinct tiers separating premium technology providers from execution-focused EPC contractors. Two strategic archetypes dominate: process specialists monetizing proprietary reactor designs, and full-service contractors capturing value through fabrication scale. Competitive moves center on unbundling the traditional EPC bundle and expanding modular unit offerings for mid-scale refinery upgrades.
Among technology-focused players, Honeywell UOP and Lummus Technology occupy positions as process licensing anchors, while McDermott International exemplifies the large-scale EPC execution archetype. These three companies represent the spectrum of competitive positioning, from premium technology monetization through integrated project delivery.
| Leading Market Players |
|---|
| Sulzer |
| McDermott International |
| Bechtel Corporation |
| Worley Parsons Limited |
| CNPC |
| Lummus Technology |
| Honeywell UOP |
| MOGAS Industries |
| Wood PLC |
| Others |
Value Chain & Pricing Dynamics
ASME Section VIII certification tiers create a sharp bifurcation between premium reactor fabricators and commodity pressure vessel suppliers, concentrating pricing power among South Korean and Japanese yards while Indian and Chinese buyers face extended lead times for qualified sources. This certification ladder simultaneously shapes procurement budgets and supply chain resilience as operators balance upfront capital against weld integrity guarantees.
Pricing Analysis
Margin tightening in reactor system fabrication reflects volatile nickel pricing for chrome-molybdenum alloys and concentrated engineering talent in Houston and The Hague. Project-based pricing dominates, with differentiation resting on ASME certification tier and after-sales service bundling. Cost-down pressure accelerates as Indian and Chinese operators unbundle EPC contracts, separating process licensing from construction execution. Mid-scale refineries in Southeast Asia exhibit highest price sensitivity, while Sinopec and PetroChina prioritize yield performance over capital expenditure.
Supply Chain Analysis
Single-source vulnerability sits with specialized pressure vessel fabricators in South Korea and Japan holding ASME Section VIII certification for 480°C operating conditions. Reactor vessels, coke drums, and automated quench systems draw from concentrated metallurgical supply bases in East Asia. Tariff exposure on specialty steel alloys presents structural risk as nickel price volatility feeds through fabrication costs. Distribution runs through EPC contractors and direct refinery procurement channels, with modular skid-mounted designs opening independent yard sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA emission standards and EU Green Deal carbon border adjustments function as a cost-of-compliance moat, elevating capital requirements for coke gasification integration and carbon capture readiness while protecting incumbent technology licensors with established environmental engineering capabilities.
For Market Incumbents: Deepen vertical integration into automated quench system manufacturing to capture margins from retrofit demand at Gulf Coast and Yangtze River Delta refineries. Defend against modular EPC unbundling by embedding process licensing with digital twin deployment for legacy DCS integration, creating switching costs at Reliance Industries and Saudi Aramco joint venture installations. For New Entrants and Emerging Players: The price-point gap between premium ASME-certified fabricators and economy-tier vessel suppliers opens white-space at mid-scale bitumen processing facilities in Canada and steam-assisted gravity drainage projects seeking captive upgrading capacity. Target modular skid-mounted configurations for Southeast Asian refinery upgrades previously excluded from project economics by scale constraints. Lead with fabrication-only positioning separated from process licensing to exploit procurement disaggregation trends. For Investors and Strategic Acquirers: Exit pathways concentrate in technology licensing acquisitions by EPC contractors seeking to rebundle process know-how with construction execution. Long-term viability favors specialists with coke gasification integration capabilities aligned with China's dual carbon goals and MEE environmental rules. Watch for carbon border adjustment enforcement stringency as the inflection signal separating compliant from stranded refinery assets.| Strategic Initiative | Industry Significance |
|---|---|
| Coke Gasification Integration | Aligns Sinopec and PetroChina refineries with China's dual carbon goals and carbon neutrality targets. |
| Modular Unit Configuration | Opens mid-scale refinery upgrades in Southeast Asia through skid-mounted coker designs reducing project scale thresholds. |
| Automated Quench System Retrofit | Improves liquid yields at Middle East refineries by suppressing secondary coking reactions in existing reactor vessels. |
| ASME Certification Investment | Secures access to Indian CEA-mandated refinery expansions at Gujarat and Rajasthan greenfield complexes. |
| Digital Twin Deployment | Enables coker optimization interfacing with decades-old DCS infrastructure at established Gulf Coast refineries. |
Study Parameters
Trade publications, refinery engineering databases, and regulatory filing repositories formed the secondary backbone, cross-referenced with primary interviews involving delayed coker unit procurement managers, EPC project directors, pressure vessel fabrication specialists, and refinery process engineers. Bottom-up unit deployment tracking across China, India, the United States, Saudi Arabia, and South Korea combined with top-down capital expenditure analysis from customs records and project development databases.
Historical trendline analysis of coker capacity additions, crude slate heavification patterns, and emissions compliance cost trajectories informed the projection framework across the analysis window. Segmentation modeling incorporated technology type, application category, service configuration, and end-user industry, with CAGRs derived from elasticity analysis against transportation fuel demand and heavy crude processing requirements. Coke gasification adoption curves and carbon capture integration timelines served as industry-specific forecast inputs.
Inputs from refinery operators and technology licensors were available through the study window; gaps in proprietary yield performance data and unannounced modular procurement contracts introduce uncertainty bands around unit deployment timing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Asia Pacific Upstream Oil and Gas Services Market
Oil & Gas
AI in Oil and Gas Market
Oil & Gas
Enclosed Flares Market
Oil & Gas
LNG Loading Skid Market
Oil & Gas
Digital Twin in Oil and Gas Market
Oil & Gas
Cuttings Re-Injection Services Market
Oil & Gas
North America Natural Gas Market
Oil & Gas
Operational Digital Oilfield Solution Market
Oil & Gas
LAMEA Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Oman Directional Drilling Market
Oil & Gas
Middle East Wireline Services Market
Oil & Gas
Nigeria Oil and Gas Midstream Market
Oil & Gas
Wellhead System Market
Oil & Gas
Global Completion Equipment and Services Market
Oil & Gas
Global Oilfield Stimulation Chemicals Market
Oil & Gas
Global Well Logging Equipment Market