
 Oil and Gas Automation Market | 2026-2036
Oil and Gas Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Automation Market Analytics
Edge-to-cloud distributed control architecture is reshaping how automation systems are deployed across upstream and downstream operations. ABB Ltd. leverages its integrated electrification and automation portfolio to anchor large-scale offshore projects in the North Sea. Emerson Electric Co. competes through specialized process control software that dominates liquefied natural gas train automation. Honeywell International Inc. differentiates via its Experion platform, which sustains long-term contracts with supermajor operators across the Permian Basin.
Oil and gas automation encompasses the hardware, software, and communication infrastructure that monitors, controls, and optimizes hydrocarbon extraction, processing, and distribution workflows, typically operating across temperature ranges from minus 40 to plus 85 degrees Celsius and requiring SIL 3 safety integrity levels for emergency shutdown systems. Its primary industrial purpose is to minimize unplanned downtime, reduce personnel exposure to hazardous environments, and maximize recovery rates from declining reservoirs. Control systems and sensors together form the mature revenue core, where margin pools have compressed due to commoditization of programmable logic controllers. Software solutions represent the fastest-growing structural segment, as operators shift from perpetual licenses to subscription-based analytics platforms that integrate machine learning for predictive corrosion monitoring.
The EPA enforces methane emissions standards that compel operators to deploy continuous monitoring automation rather than periodic manual inspection. OSHA process safety management regulations mandate automated safety instrumented systems for facilities handling threshold quantities of flammable substances. The EU AI Act introduces conformity requirements for autonomous decision-making systems in critical infrastructure, affecting how European operators validate machine learning models deployed in refining units. Stakeholders must decide whether to build proprietary AI competencies or partner with specialized vendors as regulatory scrutiny of automated operational technology intensifies.
Market Dynamics
The EPA's methane emissions standards are forcing upstream operators to replace periodic manual inspection with continuous monitoring automation, compressing deployment timelines and rewiring capital allocation toward sensor networks and edge analytics infrastructure.
Growth Catalysts
- Shale operators in the Permian Basin:Integrated drilling automation reduces well completion times and labor exposure, driving replacement cycles for legacy pneumatic controllers.
- F-Gas Regulation:The European Union's phasedown of hydrofluorocarbon-based refrigeration in offshore platforms accelerates retrofit demand for lower-emission control architectures.
- Predictive maintenance systems:Machine learning models trained on vibration and corrosion data now predict equipment failures 30-90 days in advance, cutting unplanned shutdowns on North Sea production platforms.
Market Restraints
- Semiconductor supply concentration:Advanced process controllers depend on industrial-grade chips sourced primarily from Taiwan and South Korea, creating vulnerability to geopolitical disruption.
- SIL 3 certification timelines:Safety instrumented systems require 18-24 month validation cycles under IEC 61511, delaying project commissioning and freezing capital.
- Skilled automation engineer scarcity:Competency in both hydrocarbon process engineering and Python-based analytics is concentrated among mid-career professionals in Houston, Aberdeen, and Stavanger.
Strategic Opportunities
- Carbon capture integration:Post-combustion capture units on Gulf Coast refineries require novel automation for solvent regeneration cycles, opening greenfield specification opportunities.
- Subscription analytics platforms:Operators in Norway's Johan Sverdrup field are piloting machine-learning-as-a-service for subsea flow assurance, shifting vendor relationships from hardware to recurring revenue.
- Electrification of offshore platforms:Grid-connected North Sea installations need power management automation that harmonizes variable renewable supply with gas turbine baseload.
Industry Challenges
- Legacy DCS integration:Brownfield refineries in the US Gulf Coast run 1990s-era distributed control systems that resist seamless API connection to cloud analytics layers.
- Cybersecurity certification lag:IEC 62443 compliance for operational technology networks requires specialized assessors, creating 9-12 month bottlenecks before production deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Automation Market |
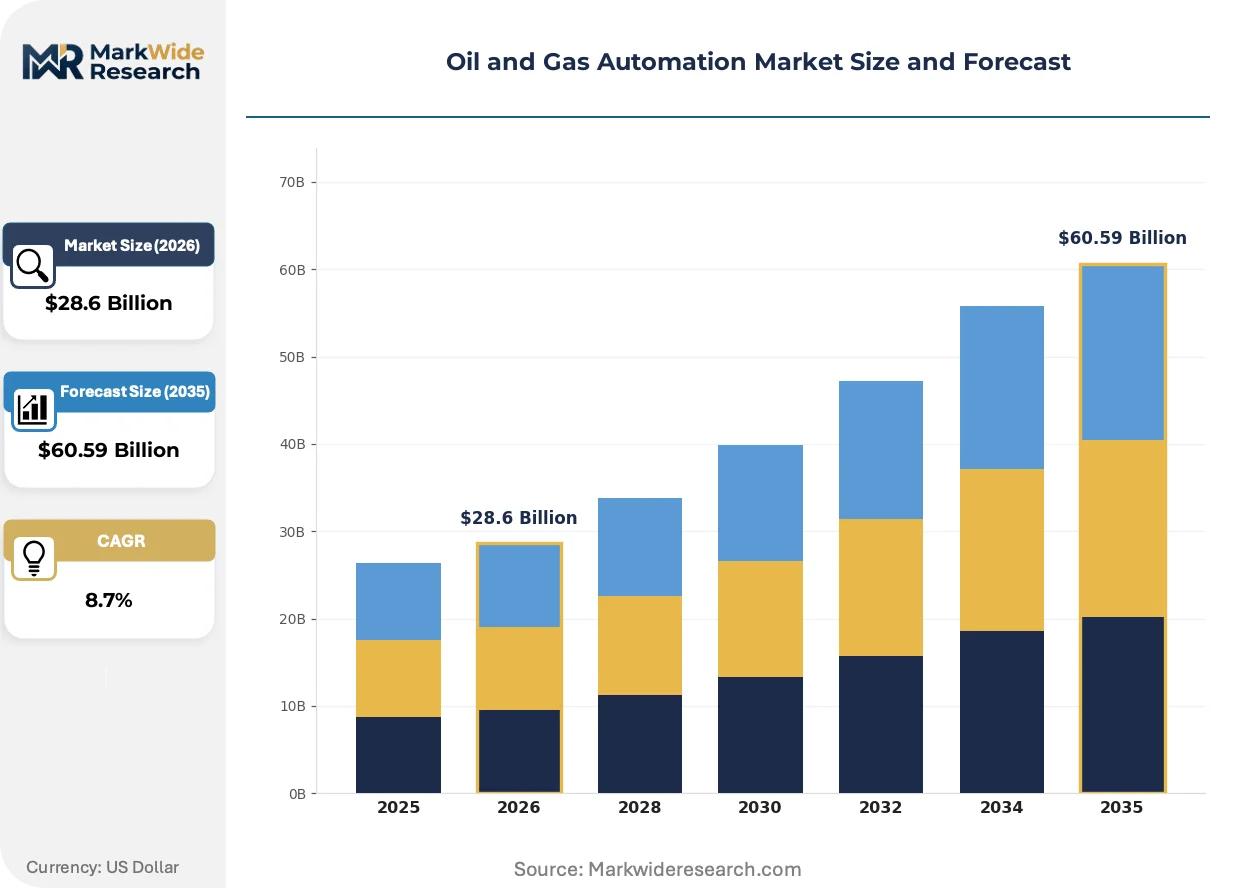
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Control Systems, Software Solutions, Sensors, Robotics Technology: Cloud Computing, IoT, AI, Machine Learning Application: Exploration, Drilling, Production, Refining End User: Oil Field Operators, Service Providers, EPC Contractors, Integrators |
| Companies Covered | Emerson Electric Co., ABB Ltd., Honeywell International Inc., Yokogawa Electric Corp., Schneider Electric SE, Siemens AG, Rockwell Automation Inc., General Electric, Endress+Hauser AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Automation Market Evolving Landscape
Edge-to-cloud distributed control architecture is collapsing the traditional separation between field instrumentation and enterprise data lakes, enabling real-time optimization loops that were previously impossible.
Digital twin technology is collapsing the cost structure of offshore commissioning. Operators in Norway's Equinor-led projects deploy virtual replicas of subsea production systems six months before physical installation, compressing integration timelines and reducing offshore personnel requirements by 40%. Shell's Prelude FLNG facility now runs parallel digital and physical trains for troubleshooting.
The EU AI Act introduces mandatory conformity assessments for autonomous decision-making systems in critical infrastructure. European refiners must document training data provenance and algorithmic robustness for machine learning models deployed in distillation unit control, adding 6-9 months to validation cycles. Germany's TÜV and France's ANSM are developing sector-specific guidance for hydrocarbon processing applications.
Buying patterns among supermajor operators are rotating toward integrated electrification-automation procurement. Rather than sourcing power systems and process controls separately, BP and TotalEnergies now issue single-source tenders for combined packages, compressing vendor lists and favoring suppliers with in-house capabilities across both domains. This consolidation is most visible in North Sea brownfield electrification projects.
Oil and Gas Automation Market Segmentation
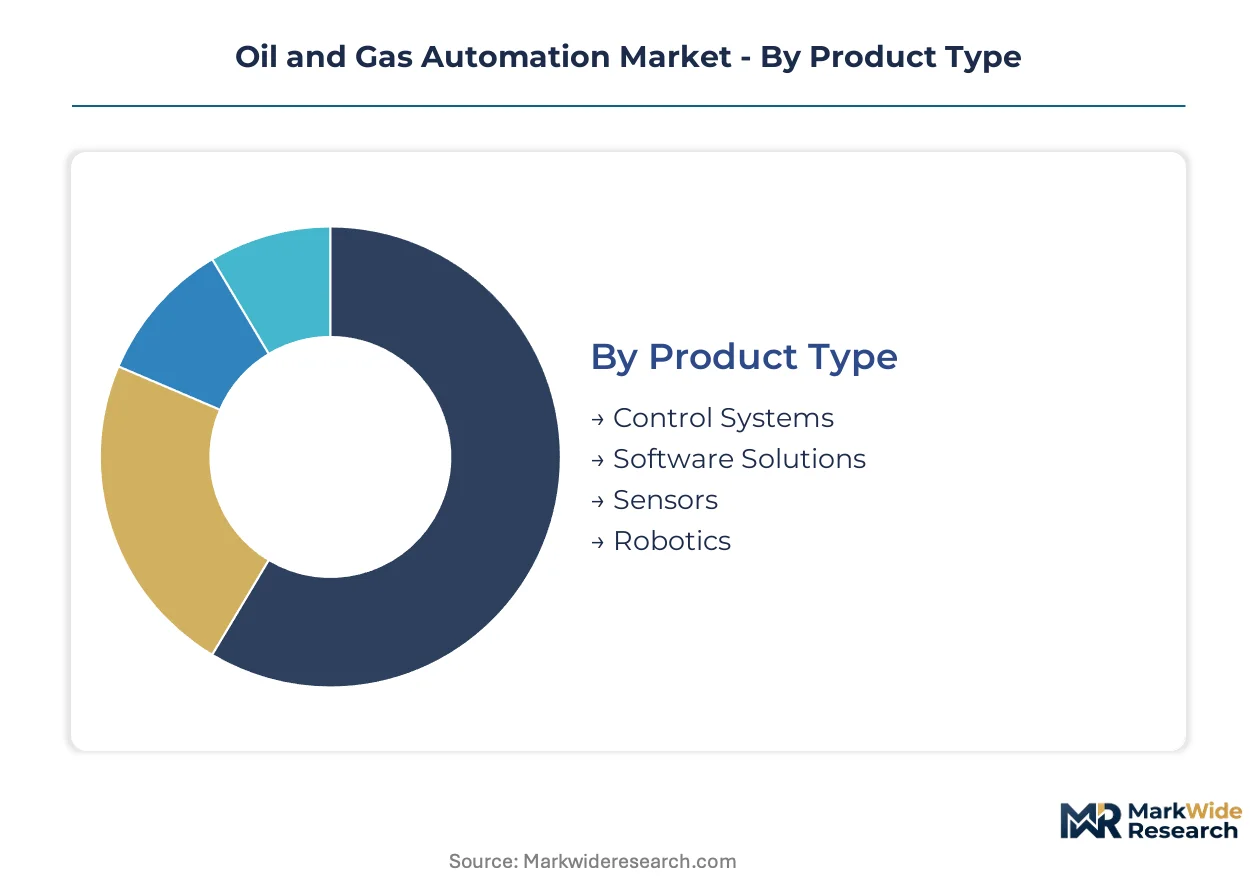
Automation deployment patterns across oil and gas operations diverge sharply by technical function, with control hardware forming the installed base while software and analytics capture replacement budgets. Segmentation reveals how capital allocation splits between sustaining mature infrastructure and funding predictive capabilities.
Product Type:
The use-case spectrum spans closed-loop process control through autonomous field robotics, with each product class serving distinct operational moments from wellhead to export terminal.
- Control Systems:Distributed control systems and programmable logic controllers execute real-time process regulation across temperature extremes from minus 40 to plus 85 degrees Celsius. Permian Basin shale operators deploy integrated drilling control packages that compress well completion cycles and reduce manual intervention exposure.
- Software Solutions:Subscription-based analytics platforms integrate machine learning for predictive corrosion monitoring and flow assurance, displacing perpetual license models. Norwegian operators in the Johan Sverdrup field pilot machine-learning-as-a-service for subsea optimization, climbing the fastest among product categories as vendors shift to recurring revenue relationships.
- Sensors:Pressure, temperature, and flow transmitters feed edge-to-cloud architectures with continuous data streams.
- Robotics:Autonomous inspection drones and subsea remotely operated vehicles reduce personnel deployment to hazardous environments.
Established volume favors control systems; emerging adoption favors software solutions.
Technology:
Cost tier separation distinguishes capital-intensive edge infrastructure from operational expenditure models in cloud and AI services.
- Cloud Computing:Edge-to-cloud distributed architectures collapse traditional separation between field instrumentation and enterprise data lakes, enabling optimization loops previously impossible. North Sea offshore platforms leverage hybrid cloud for predictive maintenance data aggregation, though cybersecurity certification under IEC 62443 creates 9-12 month deployment bottlenecks.
- IoT:Wireless sensor networks and industrial mesh protocols connect stranded assets without cabling infrastructure. EPA methane emissions standards compel continuous monitoring via IoT sensor grids, replacing periodic manual inspection across US Gulf Coast production facilities.
- AI:Autonomous decision-making systems face EU AI Act conformity requirements that add 6-9 months to validation cycles for European refinery applications.
- Machine Learning:Vibration and corrosion data models predict equipment failures 30-90 days in advance on North Sea production platforms.
Capital expenditure concentration favors IoT; operational expenditure transition favors cloud computing.
Application:
Application maturity correlates with automation penetration depth, from exploratory frontier operations through mature downstream processing.
- Production:Subsea and surface production systems deploy the most sophisticated automation stacks, integrating safety instrumented systems at SIL 3 levels with real-time optimization. North Sea offshore platforms accelerate predictive maintenance adoption as declining reservoirs demand maximum recovery efficiency.
- Refining:Distillation and conversion units require continuous process control with minimal unplanned downtime. EU refiners face AI Act documentation requirements for machine learning models in distillation unit control, extending validation timelines.
- Exploration:Seismic data processing and well logging utilize specialized automation with limited standardization.
- Drilling:Integrated automation reduces well completion times and labor exposure in shale operations.
Process intensity favors production; regulatory complexity favors refining.
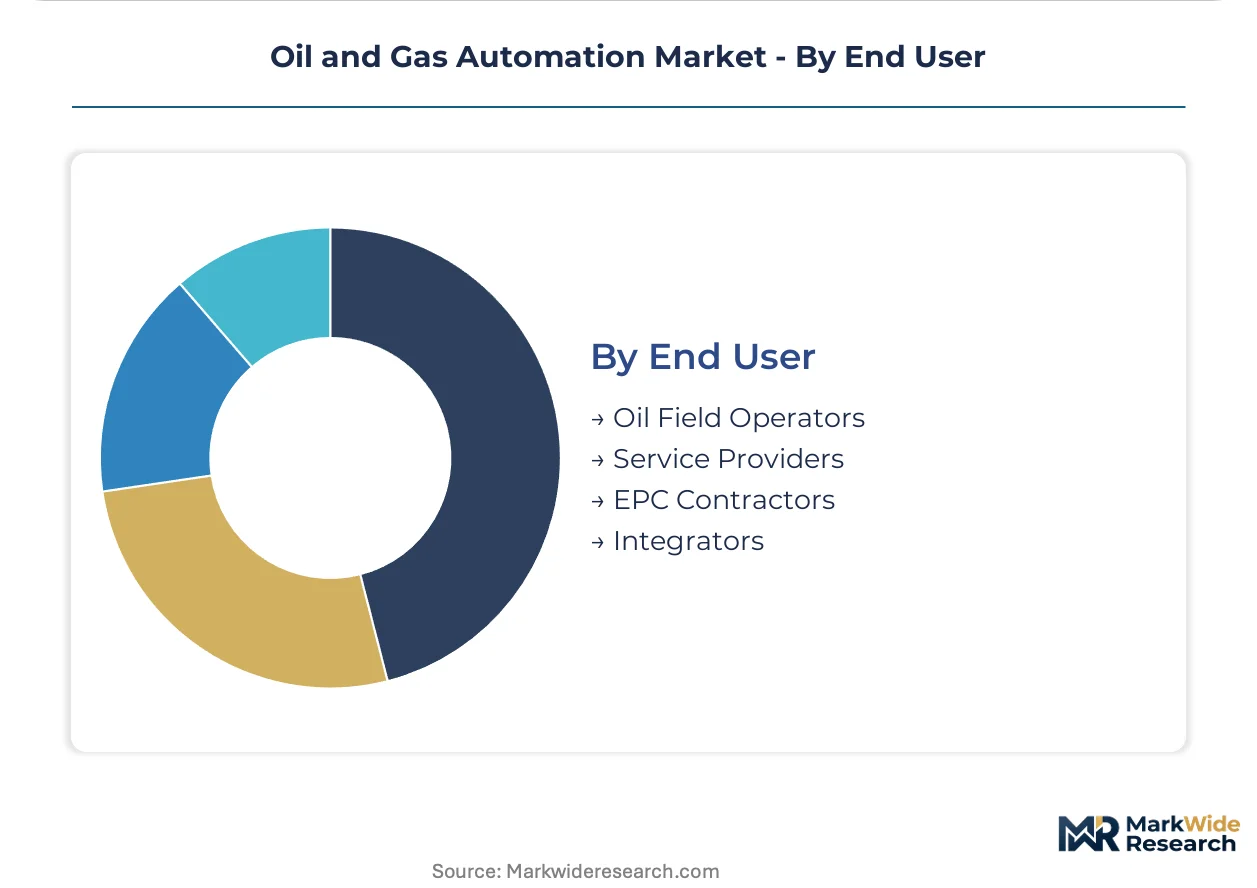
End User:
Procurement authority and technical competency split between asset-owning operators and specialized service intermediaries.
- Oil Field Operators:Supermajors and national oil companies issue integrated electrification-automation tenders, compressing vendor lists toward suppliers with cross-domain capabilities. BP and TotalEnergies single-source combined power and control packages for North Sea brownfield electrification.
- EPC Contractors:Engineering-procurement-construction firms specify automation during greenfield project development, embedding standards that persist through operational life. Carbon capture integration on Gulf Coast refineries opens specification opportunities for novel solvent regeneration automation.
- Service Providers:Drilling and completion contractors operate leased automation equipment with rapid replacement cycles.
- Integrators:System integration specialists bridge legacy DCS and modern cloud analytics layers.
Long-term contract value favors oil field operators; specification influence favors EPC contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supermajor operators and national oil companies concentrate procurement authority in five countries where hydrocarbon production scale justifies integrated automation investment. Regulatory pressure on emissions and safety integrity drives replacement cycles unevenly across these markets.
United States
Permian Basin shale operators deploy integrated drilling automation at scale, compressing well completion timelines while reducing field personnel exposure. EPA methane emissions standards compel continuous monitoring via sensor networks across Gulf Coast production facilities. Houston anchors the largest concentration of automation engineering competency, with mid-career professionals bridging hydrocarbon process engineering and Python-based analytics.
Norway
North Sea offshore platforms accelerate predictive maintenance adoption as declining reservoirs demand maximum recovery efficiency. Johan Sverdrup field pilots machine-learning-as-a-service for subsea flow assurance, shifting vendor relationships toward recurring revenue models. Stavanger clusters automation engineering talent alongside Oslo's regulatory technology assessment capacity under EU AI Act frameworks.
United Kingdom
Aberdeen's offshore supply chain integrates electrification and automation procurement for North Sea brownfield projects, compressing vendor lists toward cross-domain suppliers. EU F-Gas Regulation phases down hydrofluorocarbon-based refrigeration in offshore platforms, accelerating retrofit demand. London-based supermajors issue single-source tenders for combined power and control packages.
Saudi Arabia
National oil company megaprojects specify automation during greenfield development, embedding standards that persist through operational life. Grid-connected offshore installations require power management automation harmonizing variable supply with gas turbine baseload. Eastern Province production complexes drive regional demand for SIL 3 safety instrumented systems.
China
State-owned refiners face dual carbon goals while expanding downstream processing capacity, creating tension between emission reduction and throughput maximization. National standards for industrial automation equipment shape procurement specifications across Sichuan-Chongqing shale plays and Yangtze River Delta refining clusters. Domestic suppliers compete with multinational vendors on cost-engineered control system tenders.
Oil and Gas Automation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a consolidated vendor landscape where cross-domain capability determines tender success. Integrated electrification-automation portfolios anchor large-scale offshore projects, while specialized process control software dominates liquefied natural gas applications. Two strategic archetypes predominate: full-stack platform vendors and vertical software specialists. Competitive moves center on backward integration into power systems and geographic expansion through regional engineering partnerships.
Among diversified industrial conglomerates, Emerson Electric Co., ABB Ltd., and Honeywell International Inc. exemplify the full-stack archetype, each leveraging integrated portfolios to anchor multi-decade operator relationships. These entities occupy positions where combined electrification and automation procurement favors in-house capabilities across both domains. Specialized competitors including Yokogawa Electric Corp. and Schneider Electric SE sit within focused tiers where process control software or safety instrumented systems expertise commands premium positioning in specific application verticals.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| ABB Ltd. |
| Honeywell International Inc. |
| Yokogawa Electric Corp. |
| Schneider Electric SE |
| Siemens AG |
| Rockwell Automation Inc. |
| General Electric |
| Endress+Hauser AG |
| Others |
Value Network & Pricing Analysis
The Rotterdam-Houston container corridor carries industrial-grade semiconductors and safety-certified controllers from Taiwanese foundries to Gulf Coast automation integrators, with freight cost volatility feeding directly into project-based pricing spreads and compressing margins for mid-tier system integrators serving Permian Basin shale operators.
Pricing Analysis
Cost-plus contracts indexed to steel and copper commodity benchmarks dominate large-scale offshore automation procurement, with ABB and Honeywell anchoring premium tiers through integrated electrification-automation bundles while smaller vendors compete on standard control hardware with thinner after-sales service coverage. Price differentiation separates SIL 3-certified safety systems from uncertified alternatives, with EPA methane compliance mandates driving buyers toward certified tiers despite higher upfront outlays. Cost compression in standard programmable logic controllers intensifies as Chinese suppliers enter European tender processes. National oil companies exhibit lowest price sensitivity, prioritizing long-term service reliability over capital expenditure minimization.
Supply Chain Analysis
Export controls under US Commerce Department restrictions limit flows of advanced process controllers and edge-computing hardware to certain end-users, forcing European and Middle Eastern operators toward alternative sourcing channels. Manufacturing concentrates in Germany, Japan, and the United States for precision instrumentation, while industrial-grade chip fabrication rests on Taiwanese and South Korean supply. Raw material dependencies span rare earth elements for magnetic sensors, high-purity copper for signal transmission, and specialized alloys for subsea pressure housings. Single-source vulnerability concentrates in advanced microcontroller units. Distribution runs through authorized system integrators with regional engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent automation vendors face substitution pressure from cloud-native analytics platforms and machine-learning-as-a-service offerings that displace traditional perpetual-license software models.
For Market Incumbents: Entrench integrated electrification-automation portfolios through multi-decade service contracts with North Sea supermajors, while accelerating backward integration into power systems manufacturing to defend against specialist electrical contractors encroaching on combined procurement tenders. Prioritize IEC 62443 cybersecurity certification investment to capture EPA-mandated continuous monitoring upgrade cycles before software-native competitors achieve compliance.
For New Entrants and Emerging Players: Establish a beachhead in carbon capture integration automation for Gulf Coast refinery retrofits, where novel solvent regeneration control specifications remain undefined and incumbent relationships carry less weight. Target brownfield distributed control system modernization in US Gulf Coast facilities running 1990s-era hardware, offering API-native cloud connectivity as a migration path. Lead with subscription-based predictive corrosion monitoring to bypass capital-intensive hardware procurement barriers.
For Investors and Strategic Acquirers: Specialist AI model validators with hydrocarbon process domain expertise represent the most defensible acquisition archetype, as EU AI Act conformity requirements extend validation timelines and create captive demand for regulatory technology capabilities. Long-term viability hinges on recurring revenue share expansion versus perpetual license dependence. Watch for inflection when machine-learning-as-a-service pilots in Norway's Johan Sverdrup field transition to production-scale deployment, signaling subscription model acceptance among conservative operator procurement functions.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Electrification-Automation Bundling | Captures single-source tender preference from BP and TotalEnergies in North Sea brownfield projects. |
| Machine-Learning-as-a-Service Pilot Expansion | Shifts vendor relationships from hardware sales to recurring revenue in Norwegian subsea operations. |
| Carbon Capture Control System Development | Opens greenfield specification opportunities for solvent regeneration automation on Gulf Coast refineries. |
| IEC 62443 Cybersecurity Certification Acceleration | Resolves 9-12 month deployment bottlenecks blocking EPA-mandated continuous monitoring adoption. |
| Digital Twin Commissioning Platform Deployment | Reduces offshore personnel requirements by 40% in Equinor-led Norwegian projects. |
Research Methodology
Cross-validation between executive interviews at automation vendors and secondary trade flow data anchors the qualitative findings on procurement pattern shifts. Primary research engaged automation engineering directors at supermajor operators, EPC contractor procurement leads, system integrator technical specialists, and regulatory compliance officers across Houston, Stavanger, and Aberdeen. Secondary sources encompassed SEC filings from listed industrial conglomerates, IEC standards documentation, EPA enforcement action records, and EU regulatory impact assessments. Bottom-up project pipeline analysis and top-down macro allocation modeling were reconciled to triangulate market sizing.
Calibration against historical automation capital expenditure cycles and disclosed order backlogs informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology deployment architecture, application process intensity, and end-user procurement authority structure. CAGRs were derived from fitted growth curves applied to disclosed vendor revenue trajectories and operator automation budget allocations. Forecast inputs incorporated shale well completion automation penetration rates and offshore platform electrification project announcements.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories and North Sea decommissioning timelines would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and semiconductor supply normalization. Material shifts in EU AI Act implementation stringency or US-China technology export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Wireline Logging Services Market
Oil & Gas
Frac Tree Market
Oil & Gas
Oil and Gas Asset Integrity Management Services Market
Oil & Gas
Mexico Oil and Gas Downstream Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
Colombia Oil and Gas Midstream Market
Oil & Gas
United States Oil and Gas Market
Oil & Gas
GCC and North Africa Coiled Tubing Market
Oil & Gas
Delayed Coker Unit Market
Oil & Gas
North America Oil and Gas Line Pipe Market
Oil & Gas
Russia Drill Pipe Market
Oil & Gas
Thailand Oil and Gas Market
Oil & Gas
Underreamers Market
Oil & Gas
Middle East and Africa Drilling Market
Oil & Gas
Copper Mining Market
Oil & Gas
Middle-East Completion Equipment and Services Market