
 Off-Street Parking Management System Market | 2026-2036
Off-Street Parking Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Street Parking Management System Market Analytics
Direct municipal procurement is fragmenting as private operators and real estate developers gain purchasing authority over off-street parking infrastructure. Kapsch TrafficCom AG leverages its transponder expertise to anchor high-throughput automated payment installations at airport and hospital complexes. Amano Corporation sustains dominance in Japanese municipal contracts through dense service networks and localized hardware calibration. Cubic Corporation competes aggressively in North American transit-adjacent parking by integrating fare-collection backends with city mobility platforms.
An off-street parking management system coordinates vehicle entry, space allocation, payment processing, and occupancy monitoring within enclosed or surface lots detached from public roadways. These systems typically integrate license plate recognition cameras, ultrasonic or magnetic sensors, and centralized software dashboards to maintain real-time space visibility and dynamic rate adjustment. Cloud-based solutions now lead technology adoption because operators prioritize remote diagnostics and API connectivity with third-party navigation apps. IoT integration represents the fastest-expanding segment as sensor networks enable predictive maintenance and energy-efficient lighting control. Management analytics commands the deepest margin pool by converting raw occupancy data into yield-optimization subscriptions sold to commercial landlords.
The U.S. Department of Transportation's smart city grants and the European Union's F-Gas Regulation on refrigerants in enclosed structures shape product standards and retrofit timelines. Germany's KBA enforces electromagnetic compatibility certifications that filter non-compliant hardware from automated parking installations. Stakeholders must monitor how municipal procurement rules evolve as cities bundle parking data into broader mobility-as-a-service platforms.
Market Dynamics
Municipal zero-emission zone mandates across Western Europe are forcing commercial real estate developers to accelerate retrofit cycles in aging parking structures, shifting procurement authority from city governments to private operators.
Growth Catalysts
- Congestion pricing pilots:New York City and San Francisco are deploying dynamic rate-adjustment infrastructure that requires automated payment integration, pulling through sensor and software upgrades in adjacent off-street facilities.
- F-Gas Regulation:The European Union's refrigerant restrictions in enclosed structures are mandating HVAC retrofits that operators bundle with parking management system overhauls to minimize disruption.
- Cloud-based remote diagnostics:API connectivity demands from third-party navigation apps are compressing replacement cycles for legacy on-premise installations.
Market Restraints
- Electromagnetic compatibility certification:Germany's KBA filtering requirements create compliance friction for non-EU hardware suppliers, concentrating vendor options.
- Copper and semiconductor input volatility:Sensor network deployment costs fluctuate with commodity pricing, squeezing margins on fixed-price municipal contracts.
- Proprietary legacy protocols:Decades-old parking equipment uses non-standard communication interfaces that resist integration with modern IoT architectures.
Strategic Opportunities
- Mobility-as-a-service bundling:Cities are aggregating parking data into unified transit platforms, creating subscription revenue streams for yield-optimization analytics providers.
- Predictive maintenance convergence:Sensor networks combined with energy-efficient lighting control systems open bundled service contracts in airport and hospital complexes.
- Smart city infrastructure grants:The U.S. Department of Transportation's funding programs are covering retrofit costs for public-private partnership structures.
Industry Challenges
- Integration complexity with fare-collection backends:Transit-adjacent parking operators face API standardization gaps when connecting to city mobility platforms.
- Electrical contractor skill scarcity:Installation of license plate recognition cameras and ultrasonic sensor networks requires certified low-voltage technicians in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Street Parking Management System Market |
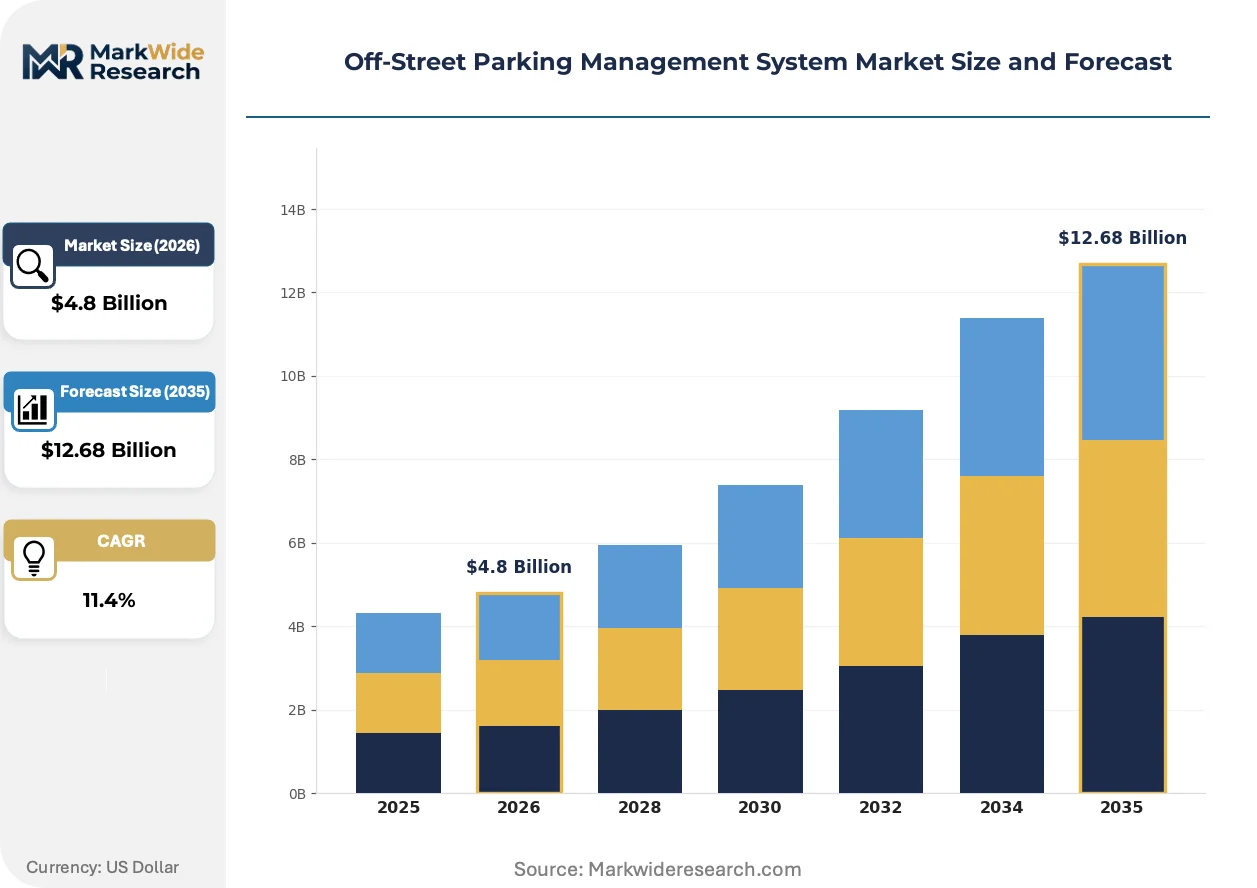
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Guided Parking Solutions, Automated Payment Systems, Parking Reservation Software, Management Analytics Technology: Cloud-Based Solutions, IoT Integration, Mobile Applications, Sensor Technology End User: Municipalities, Private Operators, Real Estate Developers, Shopping Malls Service Type: Installation Services, Maintenance Services, Consulting Services, Customer Support |
| Companies Covered | Nortech Control Systems Limited, 3M Co., Swarco AG, Cubic Corporation, Amano Corporation, Kudelski Group (SKIDATA AG), TIBA Parking LLC, Kapsch TrafficCom AG, Xerox Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Street Parking Management System Market Evolving Landscape
Software-defined infrastructure is displacing hardware-centric architectures across off-street parking operations, compressing capital deployment timelines and enabling remote reconfiguration without physical site visits.
Edge computing nodes deployed at garage entry points are virtualizing license plate recognition processing, eliminating dependency on centralized server infrastructure. Airport and hospital complexes in the United States are adopting these distributed architectures fastest, driven by uptime requirements for high-throughput facilities. This virtualization is compressing hardware refresh cycles from seven years to three as software updates substitute for equipment replacement.
The European Union's F-Gas Regulation on refrigerants in enclosed structures is mandating simultaneous HVAC and parking system upgrades to minimize tenant disruption. Commercial landlords in Germany, the United Kingdom, and France are bundling these retrofits, accelerating automated payment installation timelines. Surface lot operators face lighter compliance burdens, creating a two-speed adoption pattern across facility types.
Buyer concentration among institutional real estate investment trusts is compressing vendor negotiation cycles and unbundling after-sales service contracts. Property managers now procure software subscriptions separately from hardware installation, displacing traditional turnkey vendors. This unbundling is most visible in the United States, where REITs operate national parking portfolios and demand standardized dashboards across geographically dispersed assets.
Off-Street Parking Management System Market Segmentation
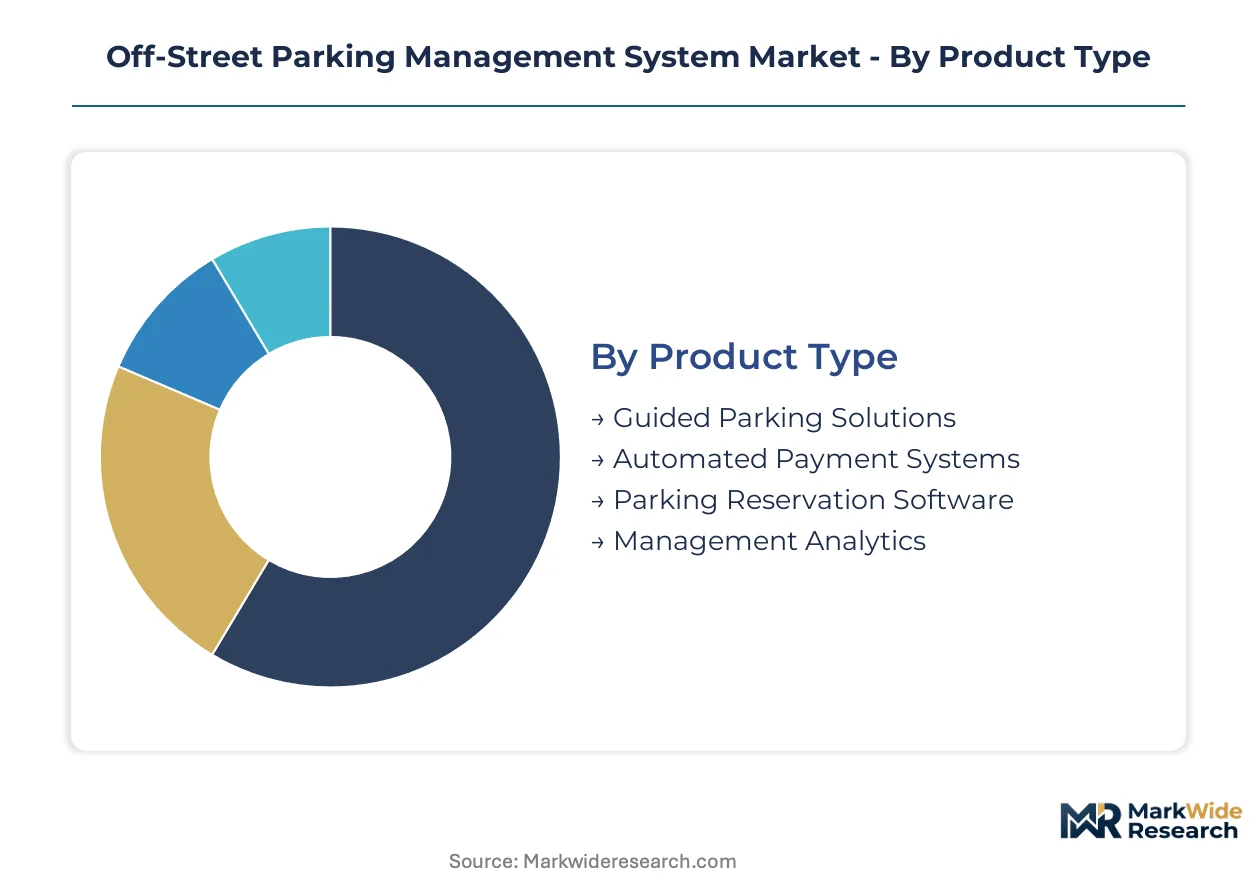
Off-street parking management systems fragment across four distinct dimensions that shape procurement patterns and vendor positioning. Product type and technology selections determine capital intensity, while end user identity dictates contract structure and service bundling preferences.
Product Type:
Mature hardware solutions coexist with emerging software platforms as operators balance reliability against upgrade flexibility.
- Management Analytics:Cloud-native platforms convert raw occupancy data into yield-optimization subscriptions, with commercial landlords in the United States and Germany purchasing these tools separately from underlying hardware. Real estate investment trusts demand standardized dashboards across dispersed portfolios, compressing vendor negotiation cycles.
- Automated Payment Systems:High-throughput transponder and license plate recognition installations anchor revenue for airport and hospital complexes. Congestion pricing pilots in New York City and San Francisco pull through sensor upgrades in adjacent facilities.
- Guided Parking Solutions:Ultrasonic and magnetic sensor networks with LED wayfinding displays serve aging municipal structures requiring retrofit compatibility.
- Parking Reservation Software:API-connected booking platforms integrate with third-party navigation apps for shopping mall operators seeking pre-arrival revenue capture.
Management Analytics retains volume leadership; Automated Payment Systems holds the steepest expansion curve.
Technology:
Cost tier separation runs deep between capital-heavy edge infrastructure and lightweight software layers.
- Cloud-Based Solutions:Remote diagnostics platforms with API connectivity enable operators to monitor distributed assets without physical site visits. European Union F-Gas Regulation compliance timelines accelerate replacement of legacy on-premise installations.
- IoT Integration:Predictive maintenance networks combined with energy-efficient lighting control open bundled service contracts. Germany's KBA electromagnetic compatibility certifications filter non-compliant hardware, concentrating vendor options.
- Sensor Technology:License plate recognition cameras and ultrasonic arrays require certified low-voltage technicians in short supply across major metropolitan markets.
- Mobile Applications:Consumer-facing payment and navigation interfaces carry lower deployment barriers but thinner margin pools.
Cloud-Based Solutions retains volume leadership; IoT Integration is climbing the fastest.
End User:
Customer type determines whether procurement flows through municipal RFP processes or private negotiation channels.
- Real Estate Developers:Western European zero-emission zone mandates force accelerated retrofit cycles, shifting purchasing authority from city governments to private operators.
- Private Operators:Institutional investors unbundle hardware from software subscriptions, demanding standardized platforms across national portfolios.
- Municipalities:U.S. Department of Transportation smart city grants cover retrofit costs for public-private partnership structures.
- Shopping Malls:Revenue-sharing arrangements with parking management vendors predominate in this segment.
Real Estate Developers retains volume leadership; Private Operators is gaining share fastest.
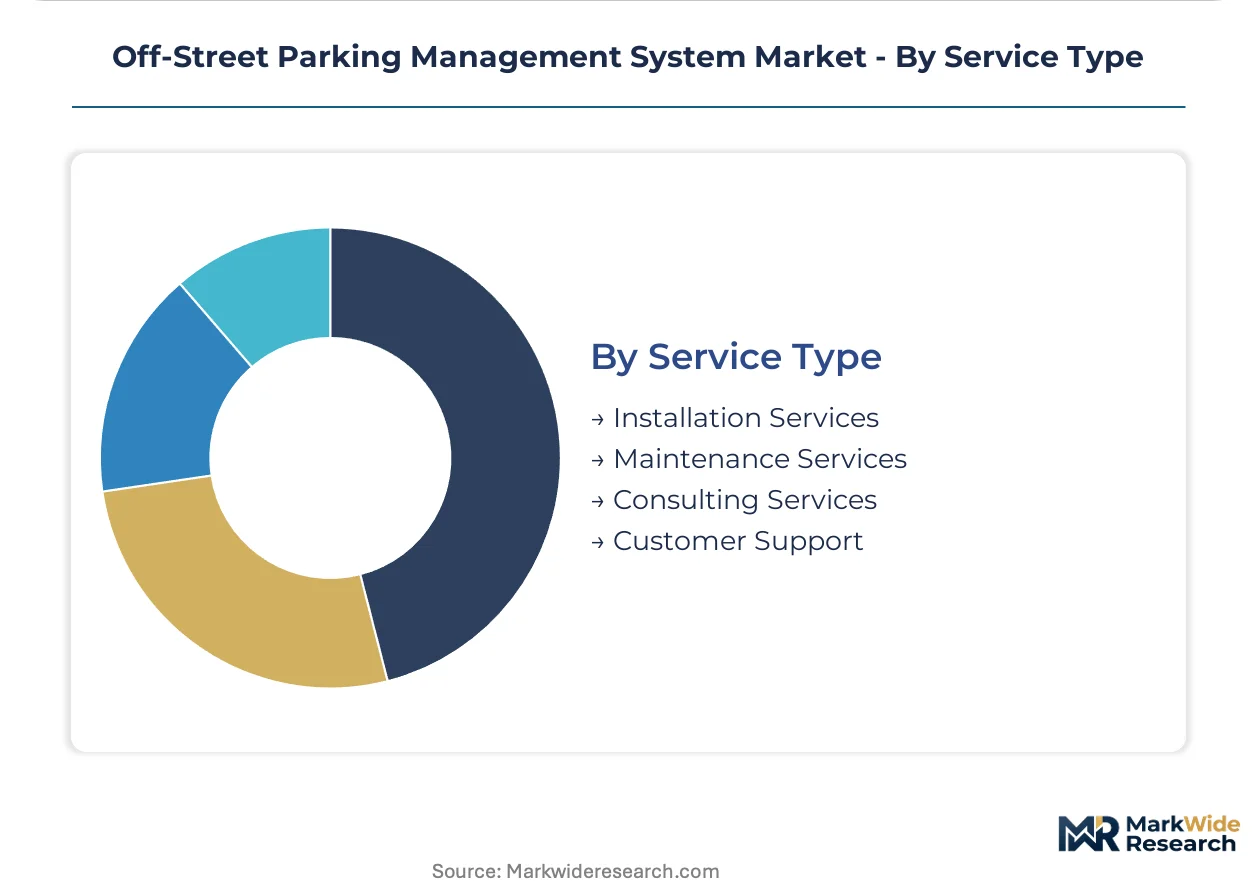
Service Type:
Margin concentration follows the post-installation lifecycle, with recurring revenue streams displacing one-time deployment fees.
- Maintenance Services:Predictive service contracts tied to IoT sensor networks generate multi-year revenue visibility for vendors.
- Installation Services:Electrical contractor skill scarcity in license plate recognition and ultrasonic deployment extends project timelines.
- Consulting Services:Yield optimization advisory supports REITs standardizing operations across geographically dispersed assets.
- Customer Support:Help desk operations for driver-facing mobile applications scale efficiently but compete on price.
Maintenance Services retains volume leadership; Consulting Services shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where smart city infrastructure budgets and congestion pricing pilots command premium deployment rates, while Western European markets face compressed margins under stringent regulatory compliance timelines.
United States
New York City and San Francisco congestion pricing pilots are accelerating sensor and software upgrades in adjacent off-street facilities. The U.S. Department of Transportation's smart city grants cover retrofit costs for public-private partnership structures. Airport and hospital complexes across the Southeast and Pacific Northwest are adopting edge computing nodes for license plate recognition processing.
Germany
Commercial real estate developers are bundling HVAC retrofits with parking management overhauls to comply with F-Gas Regulation timelines. The KBA enforces electromagnetic compatibility certifications that filter non-compliant hardware from automated installations. Munich and Frankfurt property managers are unbundling software subscriptions from hardware procurement.
United Kingdom
Municipal zero-emission zone mandates in London and Birmingham are shifting procurement authority from city governments to private operators. The EU Green Deal influences extended product lifecycle requirements for enclosed parking structures. Manchester and Edinburgh REITs are standardizing dashboards across geographically dispersed portfolios.
Japan
Amano Corporation sustains dominance in municipal contracts through dense service networks and localized hardware calibration. METI standards guide IoT integration protocols for predictive maintenance networks. Tokyo and Osaka commercial landlords are purchasing yield-optimization analytics separately from underlying hardware systems.
France
ANSM and CNIL data governance frameworks shape API connectivity specifications for third-party navigation app integrations. Paris and Lyon surface lot operators face lighter F-Gas compliance burdens than enclosed structure owners. Private operators are compressing vendor negotiation cycles through institutional buyer concentration.
Off-Street Parking Management System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors, transponders, and payment modules. The vendor base organizes around three strategic archetypes: transponder-anchored traffic technology conglomerates, precision hardware specialists with municipal service density, and cloud-native analytics platforms unbundling software from physical infrastructure. Competitive moves concentrate on strategic partnerships with real estate investment trusts and technology licensing agreements for API connectivity standards.
Within the transponder-anchored tier, Kapsch TrafficCom AG and 3M Co. exemplify platform integrators leveraging traffic infrastructure expertise into high-throughput automated payment installations. Amano Corporation occupies a position among precision hardware specialists with sustained municipal contract density through localized calibration capabilities. These three companies represent distinct competitive vectors: traffic technology extension, hardware precision with service networks, and unbundled software analytics.
| Leading Market Players |
|---|
| Nortech Control Systems Limited |
| 3M Co. |
| Swarco AG |
| Cubic Corporation |
| Amano Corporation |
| Kudelski Group (SKIDATA AG) |
| TIBA Parking LLC |
| Kapsch TrafficCom AG |
| Xerox Corporation |
| Others |
Value Network & Pricing Analysis
Semiconductor foundry concentration in Taiwan and South Korea feeds directly into sensor network margins, concentrating pricing power among vendors with captive chip supply or long-term foundry allocations. Cloud-native software layers escape this input volatility, capturing margin expansion as hardware tiers absorb commodity squeezes.
Pricing Analysis
The customization-premium spread separates configured-to-order automated payment installations from standard guided parking solutions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling. Pricing pressure stems from copper and semiconductor input volatility squeezing fixed-price municipal contracts. Real estate investment trusts exhibit lowest price sensitivity due to national portfolio standardization needs, while aging municipal structures face acute budget constraints.
Supply Chain Analysis
Contract manufacturing concentrates among Taiwanese and South Korean electronics manufacturing services producing license plate recognition cameras and ultrasonic sensor arrays. The supply chain draws from Chinese rare earth processing for magnetic components, German precision optics, and Japanese semiconductor packaging. Single-source vulnerability in edge computing chipsets poses structural risk. Distribution runs through electrical contractor networks requiring certified low-voltage technicians.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery driven by smart city infrastructure grant cycles and municipal zero-emission zone retrofit waves. Procurement authority shifts from city governments to private operators create consolidation windows.
For Market Incumbents: Insulate service revenue streams from hardware commoditization by deepening predictive maintenance subscriptions tied to IoT sensor networks. Invest in electromagnetic compatibility certification ahead of Germany's KBA enforcement waves. Vertical integration into edge computing chip sourcing hedges against foundry allocation constraints. For New Entrants and Emerging Players: Pursue surface lot operators in France and the United Kingdom where F-Gas Regulation compliance burdens remain lighter than enclosed structures. Target yield-optimization analytics as the most penetrable software layer, unbundled from legacy hardware procurement. Lead with API-first architectures that integrate with third-party navigation apps. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native analytics platforms with recurring revenue visibility and REIT-standardization traction. Long-term viability favors vendors capturing mobility-as-a-service data aggregation roles. Watch congestion pricing pilot expansion in additional U.S. cities as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API connectivity with city mobility platforms anchors transit-adjacent parking contracts. |
| Strategic Partnership | Real estate investment trust alliances compress vendor negotiation cycles across national portfolios. |
| Acquisition of Specialist Firm | Predictive maintenance analytics targets expand service contract durations and margins. |
| Geographic Expansion | Surface lot penetration in lighter-regulation European markets captures two-speed adoption. |
| Product Launch | Edge computing nodes for license plate recognition virtualization displace centralized server architectures. |
Research Methodology
A spread of perspectives from parking facility operators, municipal procurement officers, electrical contractors, and real estate asset managers converged on the working assumptions. Primary interviews combined with secondary validation from SEC filings, smart city grant disclosures, and electromagnetic compatibility certification databases. Bottom-up sensor deployment modeling and top-down infrastructure budget analysis triangulated volume estimates.
Demand-supply balance framing anchored the forecast framework across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user category, and service bundling pattern. CAGRs derived from retrofit cycle compression rates and cloud migration velocity. Industry-specific inputs incorporated F-Gas Regulation compliance timelines and congestion pricing pilot expansion trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native analytics entrants or foundry-integrated hardware vendors would shift outcomes. Forecasts assume steady municipal procurement fragmentation toward private operators. Quarterly review of smart city grant award flows and electromagnetic compatibility certification issuance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Fleet Management Solution Market
Smart Transportation Solutions
Smart Ports Market
Smart Transportation Solutions
Mobility As a Service Market
Smart Transportation Solutions
Global Integrated Traffic System Market
Smart Transportation Solutions
Temperature-Controlled Last-Mile Delivery Services Market
Smart Transportation Solutions
Europe Smart Parking Market
Smart Transportation Solutions
North America Passenger Information System Market
Smart Transportation Solutions
Rail Freight Digital Transformation Market
Smart Transportation Solutions
Global Smart Commute Market
Smart Transportation Solutions
Semi Height Platform Screen Door Market
Smart Transportation Solutions
Contactless Ticketing Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
North America Traffic Signal Recognition Market
Smart Transportation Solutions
Global Intelligent Traffic Management System Market
Smart Transportation Solutions
Transportation by Drone Market
Smart Transportation Solutions
Europe Electronic Toll Collection Market