
 Semi Height Platform Screen Door Market | 2026-2036
Semi Height Platform Screen Door Market Size, Share, and Industry Trends Forecast 2026-2036
Semi Height Platform Screen Door Market Insights
Consolidation among state-owned metro operators is recalibrating procurement volumes and technical specifications across major contracts. Nabtesco Corporation leverages its railway door actuator expertise to anchor long-term supply relationships with Japanese and Southeast Asian rail authorities. Fangda Group Co., Ltd. competes on manufacturing scale, operating one of China's largest dedicated platform screen door production facilities. Panasonic Corporation differentiates through integrated sensor and drive system technology that reduces field commissioning complexity.
Semi Height Platform Screen Doors are partial-height barriers, typically 1.2 to 1.5 meters tall, installed along platform edges to prevent passenger falls while maintaining open airflow and natural ventilation in underground stations. These systems employ brushless DC motor drives with infrared or microwave detection arrays to synchronize door movement with train car positioning. Automatic product types dominate current revenue pools due to their compatibility with driverless train operation protocols, while Retrofit installation types represent the fastest-expanding segment as aging metro networks seek platform safety upgrades without full station reconstruction. Metro Systems as an end-user category captures the majority of firm order backlogs, though Airport deployments are gaining traction where terminal-train interfaces require modular barrier solutions.
Japan's METI maintains JIS standards for railway platform safety equipment that directly specify door response times and emergency release mechanisms. China's MIIT and NMPA jointly oversee rail transit equipment certification under GB standards that mandate electromagnetic compatibility and fire resistance ratings for platform screen door assemblies. The EU's CE marking and Machinery Directive requirements shape market access for European suppliers bidding on continental rail projects. Stakeholders must monitor how evolving platform autonomy standards and cross-border rail interoperability protocols reshape technical compliance burdens and supplier qualification timelines.
Market Dynamics
Legacy metro network expansion across China's tier-one cities is forcing platform safety retrofits that favor semi-height barriers over full-height alternatives, compressing procurement cycles and recalibrating supplier qualification criteria toward rapid-deployment engineering capabilities.
Growth Catalysts
- MIIT Platform Edge Standards:China's updated GB certification mandates for legacy line upgrades accelerate semi-height door deployment where full reconstruction proves economically unfeasible.
- Driverless Train Protocols:Automatic door synchronization systems align with unmanned metro operations, creating specification pull from rail authorities modernizing signaling infrastructure.
- Brushless DC Motor Maturation:Improved torque control and reduced maintenance intervals lower total lifecycle costs for platform barrier operators.
Market Restraints
- Copper and Rare Earth Input Volatility:Permanent magnet motor supply chains concentrate in processing facilities vulnerable to export quota fluctuations.
- Electromagnetic Compatibility Certification Burden:GB standards and CE marking require parallel testing protocols that extend supplier qualification timelines by 8-14 months.
- Full-Height Door Substitution:New-build metro stations in climate-controlled environments increasingly specify complete platform enclosures with integrated HVAC.
Strategic Opportunities
- Airport Terminal-Train Interfaces:Modular semi-height barriers address safety gaps in automated people mover systems where platform geometry varies by gate position.
- India's Urban Rail Expansion:Metro projects in Delhi, Mumbai, and Bangalore seek platform edge protection compatible with elevated station ventilation requirements.
- Sensor-Drive Convergence:Microwave detection arrays fused with brushless motor controllers enable predictive maintenance algorithms that unbundle service contracts.
Industry Challenges
- Legacy Signaling Integration:Retrofit installations must interface with 1980s-era train control systems lacking standardized door-open protocols.
- Field Commissioning Skill Scarcity:Infrared array calibration and motor-drive synchronization require technicians with combined electromechanical and software competencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semi Height Platform Screen Door Market |
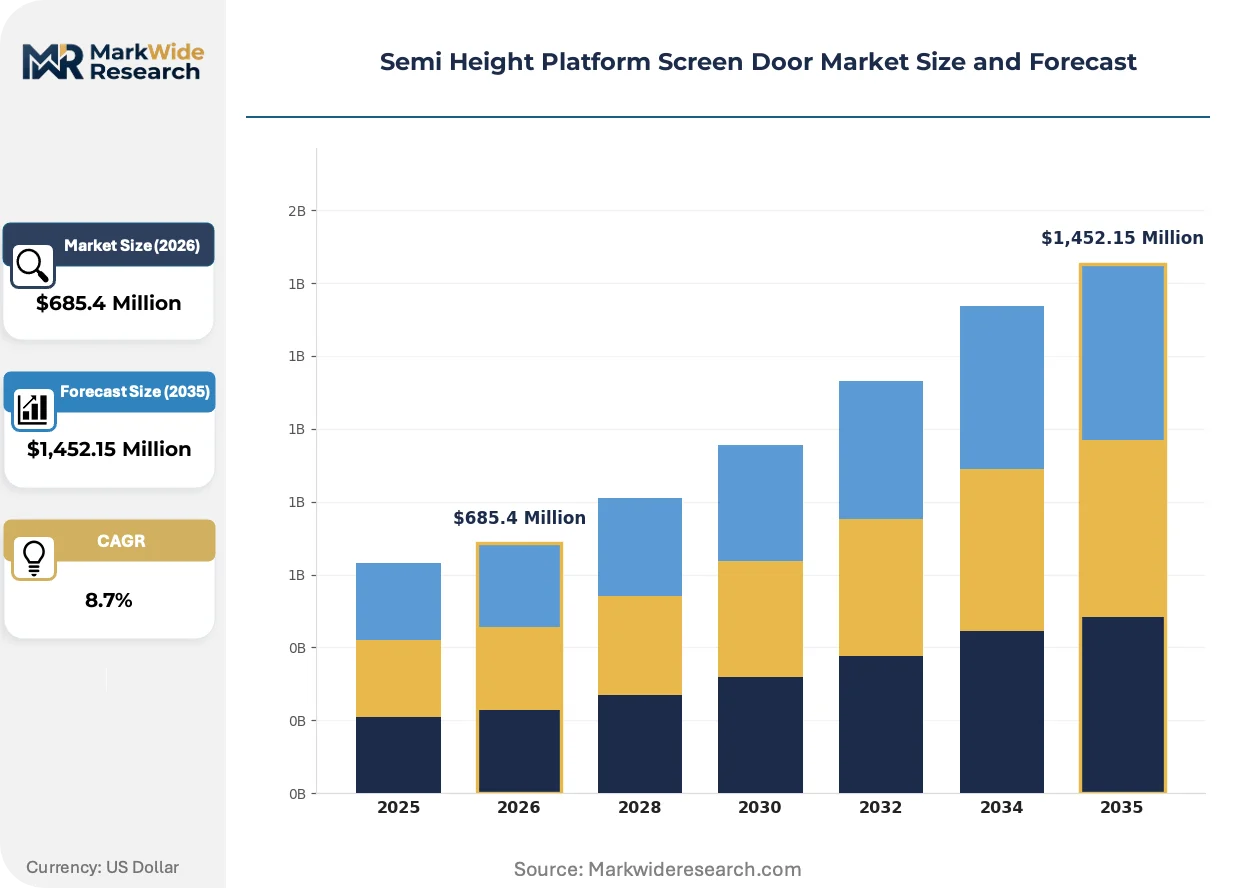
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automatic, Semi-Automatic, Customized End User: Metro Systems, Railways, Airports, Bus Stations Installation Type: Stand-Alone, Integrated, Modular, Retrofit Material: Aluminum, Glass, Steel, Polycarbonate |
| Companies Covered | Nabtesco Corporation, Nanjing Kangni Mechanical & Electrical Co., Ltd., Fangda Group Co., Ltd., Stanley Access Technologies LLC, Horton Automatics, Westinghouse Platform Screen Doors, Panasonic Corporation, KTK Group Co., Ltd., Gilgen Door Systems AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semi Height Platform Screen Door Market Trends and Innovations
Platform screen door engineering is pivoting toward predictive automation and modular retrofit architectures that compress deployment timelines for aging infrastructure. Three developments are restructuring competitive capabilities.
Brushless DC motor drives with embedded torque sensors are integrating machine-learning-based wear prediction algorithms that flag bearing degradation before failure. Japanese and Southeast Asian rail authorities specify these systems for unmanned operations where maintenance access windows contract to overnight hours. The technology is integrating condition-based service models that shift vendor revenue from equipment sales to uptime guarantees.
China's MIIT and NMPA joint certification framework now mandates fire resistance testing under GB 8624 and electromagnetic compatibility under GB/T 17626 for all platform barrier assemblies. Suppliers must maintain parallel testing facilities or third-party laboratory relationships in multiple provinces. European manufacturers bidding on Chinese projects face extended documentation requirements that favor domestic producers with established conformity assessment partnerships.
Metro operators are unbundling maintenance contracts from initial equipment procurement, creating discrete service markets where diagnostic capability determines vendor retention. Chinese state-owned rail groups now separate capital expenditure approvals from ten-year service agreements, forcing door manufacturers to demonstrate remote monitoring infrastructure. This pattern is most visible in Shanghai and Beijing where procurement departments report to asset management divisions with independent performance metrics.
Semi Height Platform Screen Door Market Segmentation
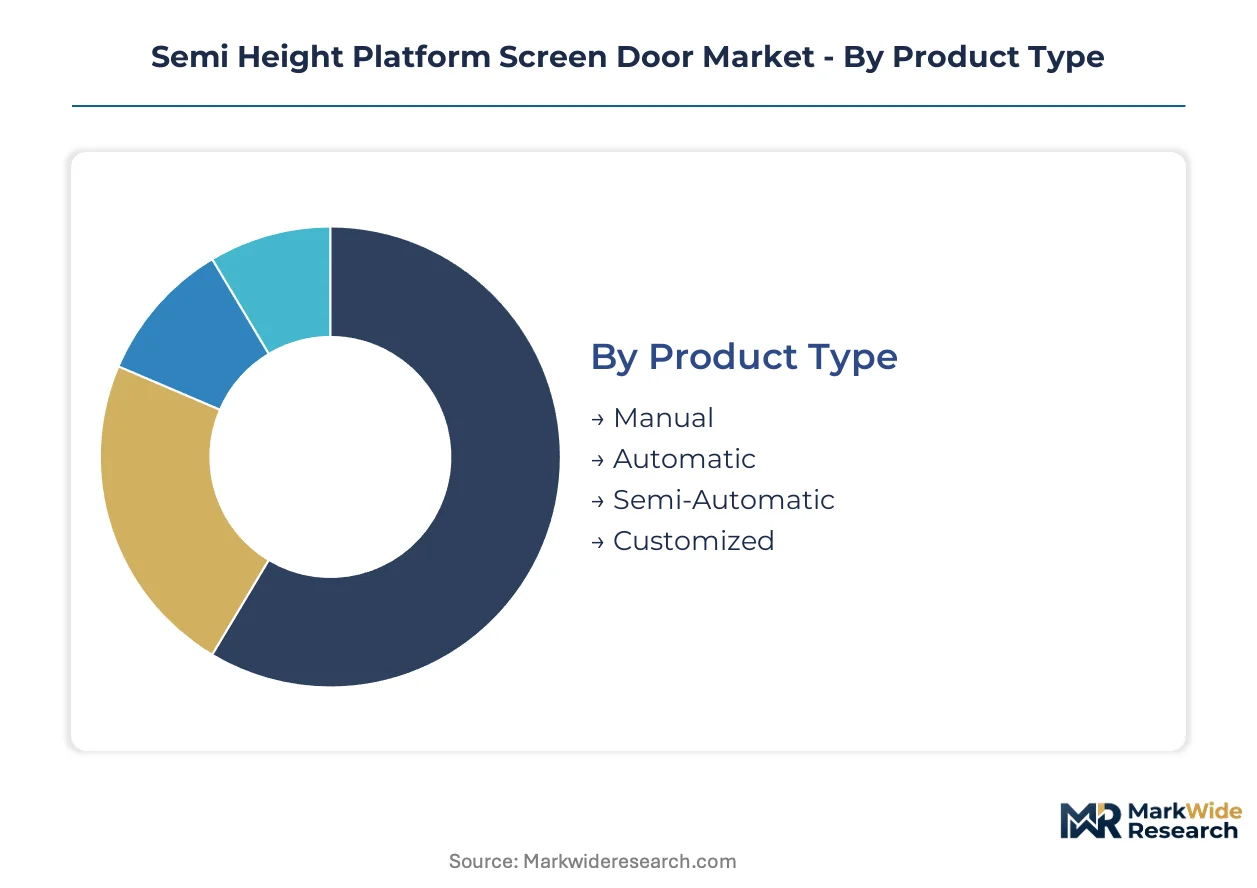
Platform screen door procurement varies sharply by operational environment and infrastructure constraints. Buyers prioritize synchronization precision, ventilation compatibility, and retrofit feasibility over uniform specifications.
Product Type:
Metro operators and rail authorities select door automation tiers based on train control system maturity and staffing models.
- Automatic:Brushless DC motor drives with infrared detection arrays synchronize door movement with train positioning for driverless operations. China's tier-one cities specify these systems for new metro lines integrating unmanned train protocols.
- Manual:Operator-initiated release mechanisms suit legacy stations with 1980s-era signaling infrastructure lacking standardized door-open protocols. Demand concentrates in Southeast Asian rail networks where labor costs offset automation capital expenditure.
- Semi-Automatic:Hybrid actuation combines automated sensing with manual override for emergency scenarios.
- Customized:Bespoke configurations address non-standard platform geometries in airport terminal-train interfaces.
Automatic leads volumes today; Retrofit-compatible variants are gaining share fastest.
End User:
Facility type dictates barrier height, throughput capacity, and environmental sealing requirements.
- Metro Systems:Underground and elevated urban rail networks deploy semi-height barriers to maintain natural ventilation while preventing passenger falls. China's MIIT mandates platform edge protection on legacy line extensions where full-height enclosures prove economically unfeasible.
- Airports:Automated people mover systems at terminal-train interfaces require modular barriers accommodating variable platform geometry by gate position.
- Railways:Intercity and regional rail stations specify lighter-duty configurations for lower-frequency service patterns.
- Bus Stations:Bus rapid transit platforms adopt adapted screen door systems for guided busway applications.
Metro Systems anchor current procurement; Airport deployments show steepest expansion trajectory.
Installation Type:
Project economics and station downtime tolerance determine architectural approach.
- Retrofit:Surface-mounted barrier systems install without platform slab reconstruction, compressing deployment timelines for aging infrastructure. China's state-owned rail groups favor these for tier-one city network extensions outpacing new-build capacity.
- Modular:Prefabricated panel assemblies enable rapid reconfiguration for temporary platforms or phased station upgrades.
- Stand-Alone:Self-supporting frames suit elevated stations with structural load constraints.
- Integrated:Built-in systems coordinate with platform edge finishes and tactile paving during new station construction.
Retrofit commands the largest project pipeline; Modular solutions are climbing the fastest.
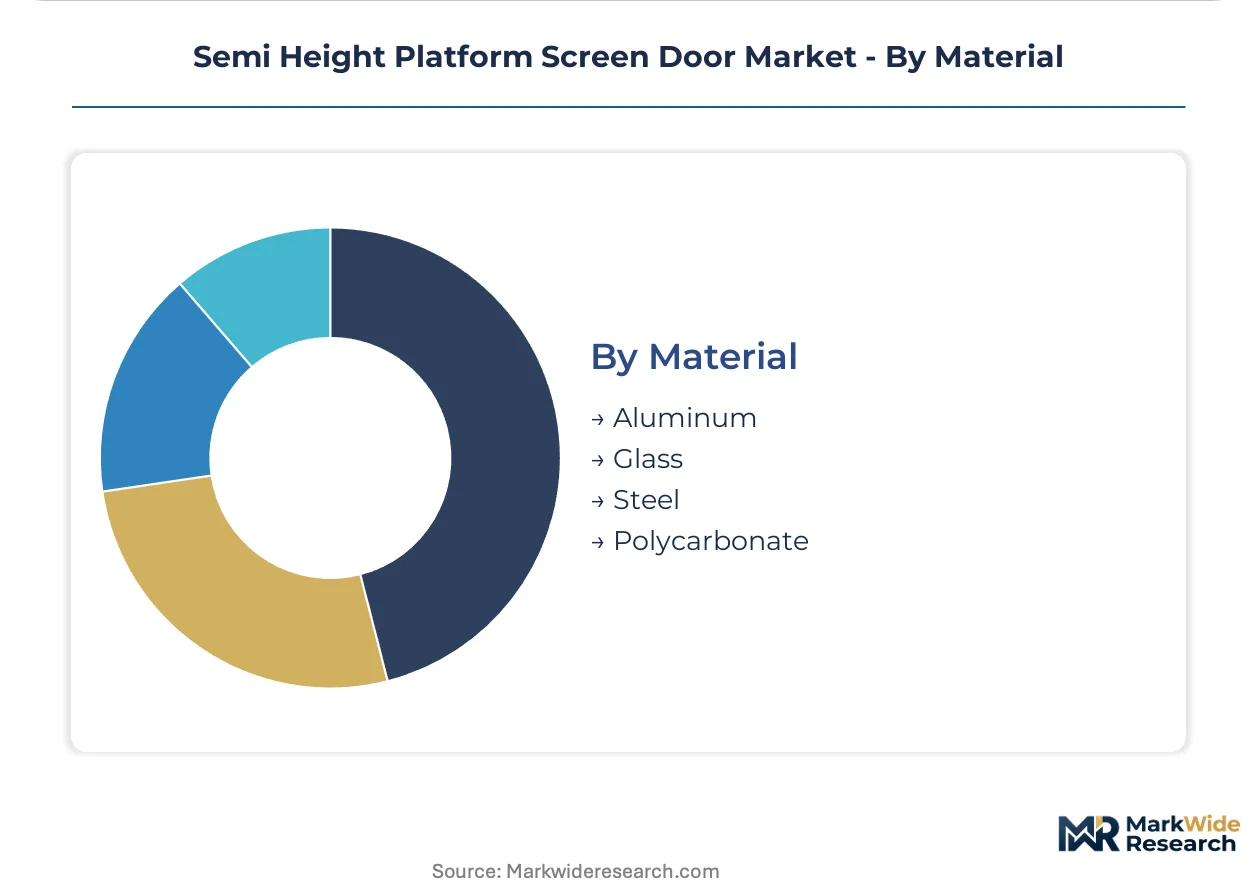
Material:
Fire resistance ratings and electromagnetic compatibility requirements shape substrate selection under GB and CE certification frameworks.
- Aluminum:Extruded alloy frames balance structural rigidity with corrosion resistance for humid subtropical climates. Chinese manufacturers dominate supply through integrated casting and finishing operations.
- Glass:Tempered safety glazing provides visibility for platform supervision while meeting GB 8624 fire resistance mandates.
- Steel:Galvanized or stainless substrates serve high-impact environments with stringent vandalism resistance requirements.
- Polycarbonate:Lightweight transparent panels reduce structural loading for elevated station retrofits.
Aluminum leads current specification volumes; Glass-infused hybrid assemblies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-one cities deploy semi-height barriers at triple the rate of Japanese metro operators, reflecting divergent infrastructure strategies between legacy network retrofits and new-build automation mandates.
China
Beijing and Shanghai subway extensions drive procurement volumes as MIIT's updated GB standards accelerate platform edge protection on aging lines. The MIIT-NMPA joint certification framework mandates fire resistance testing under GB 8624 and electromagnetic compatibility under GB/T 17626. Shenzhen's Fangda Group operates one of China's largest dedicated production facilities, supplying state-owned rail groups with rapid-deployment engineering capabilities.
Japan
Tokyo Metro and JR East prioritize automatic door synchronization for unmanned train operations on Yamanote and Oedo line extensions. METI maintains JIS standards specifying door response times and emergency release mechanisms. Osaka's Kansai rail cluster sources brushless DC motor drives with embedded torque sensors for overnight maintenance windows.
India
Delhi Metro Phase IV and Mumbai Metro Line 3 seek semi-height barriers compatible with elevated station ventilation requirements. The Ministry of Housing and Urban Affairs mandates platform screen door deployment on all new urban rail corridors. Bangalore's metro expansion concentrates procurement activity among domestic fabricators bidding on modular retrofit contracts.
South Korea
Seoul Metropolitan Subway modernizes Line 1-4 signaling infrastructure to support driverless protocols requiring automatic door synchronization. The Ministry of Land, Infrastructure and Transport enforces platform safety equipment certification under KCS standards. Busan-Ulsan rail authorities specify microwave detection arrays for coastal humidity environments.
Germany
Berlin U-Bahn and Munich S-Bahn evaluate semi-height retrofits where full platform reconstruction faces heritage preservation constraints. The KBA and federal railway authority coordinate CE marking and Machinery Directive compliance for cross-border rail interoperability. Stuttgart's rail manufacturing cluster supplies sensor-drive convergence technology to European metro operators.
Semi Height Platform Screen Door Market Competitive Landscape
Chinese producers anchor the scale-driven tier; Japanese specialists hold the precision-automation segment. Market structure consolidates around state-affiliated rail equipment groups and electromechanical conglomerates with captive transit divisions. Three archetypes dominate: integrated door-actuator manufacturers, modular barrier system fabricators, and sensor-drive technology integrators. Capacity expansion and strategic partnerships with metro operators constitute the dominant competitive moves.
Within the integrated manufacturing tier, Nabtesco Corporation and Fangda Group Co., Ltd. exemplify contrasting geographic anchoring strategies. Panasonic Corporation occupies a position bridging automation technology and rail-specific certification expertise. These three entities represent the spectrum from precision electromechanical components to mass-scale platform barrier deployment.
| Leading Market Players |
|---|
| Nabtesco Corporation |
| Nanjing Kangni Mechanical & Electrical Co., Ltd. |
| Fangda Group Co., Ltd. |
| Stanley Access Technologies LLC |
| Horton Automatics |
| Westinghouse Platform Screen Doors |
| Panasonic Corporation |
| KTK Group Co., Ltd. |
| Gilgen Door Systems AG |
| Others |
Pricing and Supply Chain Analysis
State-backed rail equipment producers anchor pricing discipline through captive procurement relationships with China's state-owned metro operators, compressing margin levers for independent suppliers while concentrating volume leverage in domestic fabrication networks.
Pricing Analysis
Capacity additions in China's Jiangsu and Guangdong provinces are reshaping price floors for aluminum-framed barrier assemblies. Project-based contracting dominates, with price differentiation hinging on GB certification tier and after-sales service bundling. Cost compression in manual-actuation tiers intensifies because Southeast Asian labor-cost arbitrage offsets automation premiums. State-owned rail groups exhibit lowest price sensitivity; private airport operators show highest.
Supply Chain Analysis
Refurbishment flows for legacy brushless DC motor drives concentrate in Osaka and Seoul, feeding remanufactured actuators back into Southeast Asian retrofit pipelines. Supply draws from China, Japan, and South Korea for permanent magnet motors, tempered glass, and infrared sensor arrays. Single-source vulnerability in rare earth processing feeds tariff exposure. Distribution runs through state-affiliated rail equipment trading companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Metro operators in China and India are shifting procurement specifications toward predictive maintenance compatibility and GB/T 17626 electromagnetic compliance.
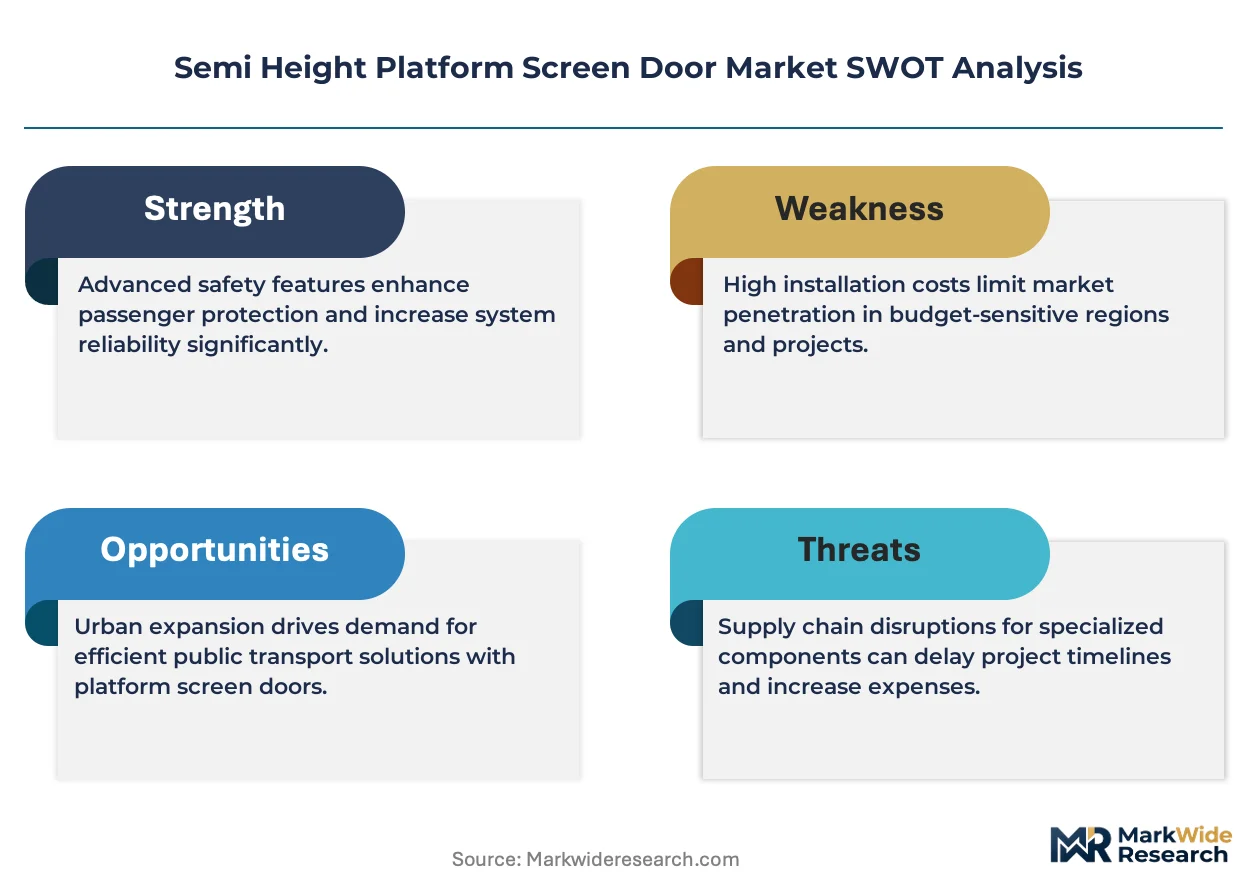
For Market Incumbents: Anchor long-term supply relationships through captive service contract structures that unbundle maintenance from initial equipment sales. Invest in remote monitoring infrastructure to retain vendor retention under asset management divisions. Defend against modular retrofit specialists by deepening backward integration into brushless DC motor production. For New Entrants and Emerging Players: Airport automated people mover systems represent the most penetrable buyer archetype, with variable platform geometry creating specification gaps incumbent rail specialists under-serve. Target modular barrier contracts in India's Bangalore and Mumbai metro expansions where domestic fabrication partnerships satisfy local content requirements. Lead with rapid-deployment engineering capabilities that compress field commissioning timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among sensor-drive technology integrators lacking established GB or JIS certification partnerships. Five-to-ten-year viability hinges on regulatory compliance infrastructure rather than manufacturing scale alone. Monitor MIIT platform autonomy standard revisions as the critical inflection signal for supplier qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| GB Certification Investment | Accelerates supplier qualification under MIIT-NMPA joint framework for Chinese state-owned rail contracts. |
| Predictive Maintenance Platform Launch | Enables condition-based service contracts that shift revenue from equipment sales to uptime guarantees. |
| Backward Integration into Motor Production | Reduces rare earth supply chain exposure while capturing margin from brushless DC actuator assemblies. |
| Airport Terminal Partnership Program | Addresses modular barrier demand from automated people mover systems with non-standard platform geometry. |
| Southeast Asian Service Hub Expansion | Supports overnight maintenance windows for Japanese and South Korean unmanned metro operations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged metro procurement directors, rail authority engineering leads, platform screen door maintenance heads, and brushless DC motor supplier technical directors. Secondary validation drew from MIIT GB standard filings, METI JIS certification registers, metro operator annual procurement disclosures, and customs trade data for aluminum extrusion and permanent magnet imports. Bottom-up project pipeline analysis triangulated against top-down market sizing.
Comparable-period anchoring linked forward projections to historical installation data across retrofit and new-build metro line completions. The analytical framework segmented by automation tier, end-user facility type, installation architecture, and regional regulatory cluster. CAGRs derived from unit deployment trajectories and average contract values per platform-kilometer. Forecast inputs incorporated MIIT platform edge protection mandate timelines and driverless train protocol adoption curves.
Underlying measurement precision varies by segment; automatic product types and metro system end-users carry tighter precision than manual configurations and bus station deployments. Forecasts reflect documented assumptions on regulatory enforcement consistency and rare earth supply stability. Practitioners should monitor MIIT autonomous platform standard drafts and copper price volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Vertical Mobility Market
Smart Transportation Solutions
Automated Parking Systems Market
Smart Transportation Solutions
Fleet Management Software Market
Smart Transportation Solutions
Off-Street Parking Management System Market
Smart Transportation Solutions
Global Connected Mobility Solutions Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Smart Logistic Market
Smart Transportation Solutions
Vehicle Parking Meter Market
Smart Transportation Solutions
Europe Electronic Toll Collection Market
Smart Transportation Solutions
Rail Freight Digital Transformation Market
Smart Transportation Solutions
Global Automated Fare Collection Market
Smart Transportation Solutions
Global Crowdsourced Smart Parking Market
Smart Transportation Solutions
France Ridesharing Market
Smart Transportation Solutions
Global Parking Meter Apps Market
Smart Transportation Solutions
Smart Fleet Management Market
Smart Transportation Solutions
North America IoT Transportation Market