
 Brexucabtagene Autoleucel Market | 2026-2036
Brexucabtagene Autoleucel Market Size, Share, and Industry Trends Forecast 2026-2036
Brexucabtagene Autoleucel Market Outlook
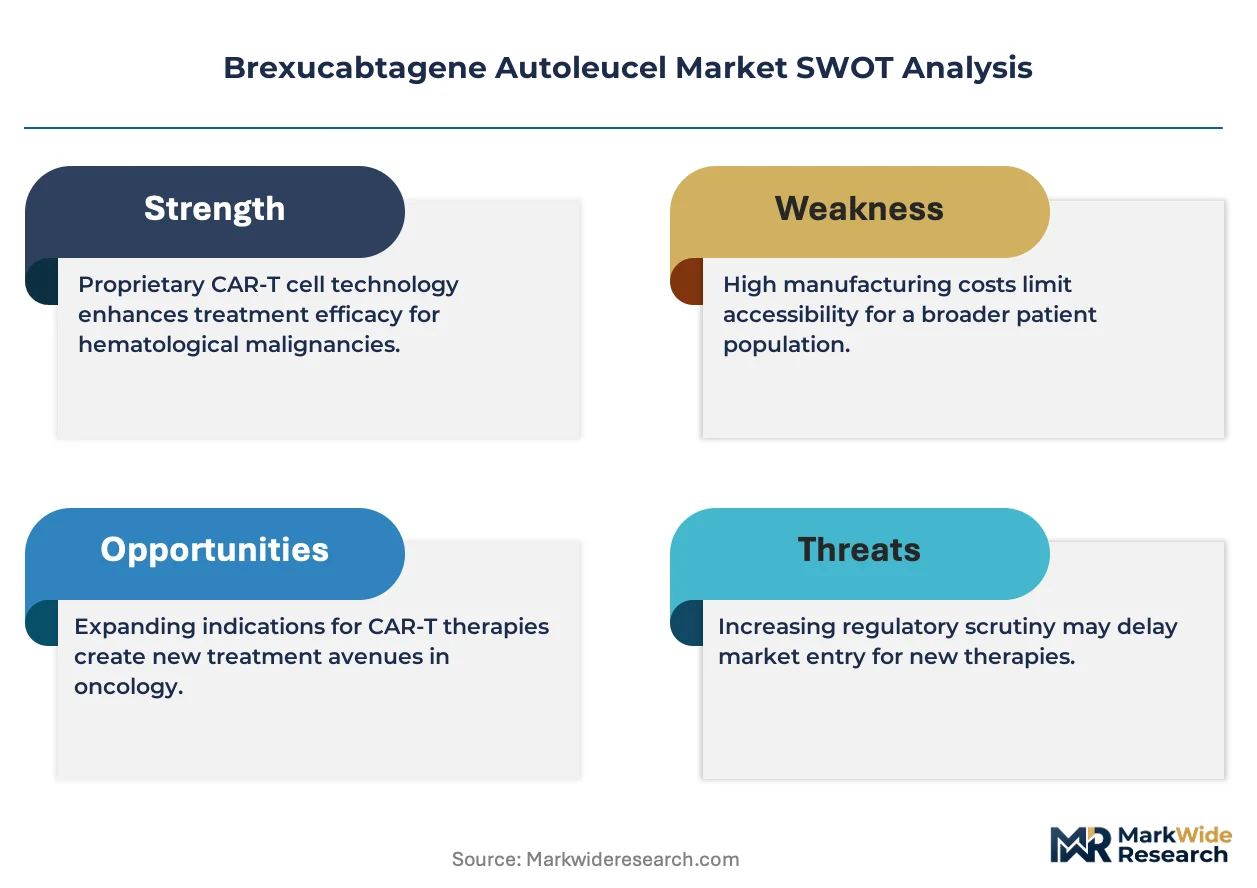
Outcome-based reimbursement and risk-sharing agreements for CAR T-cell therapies is reconfiguring competitive economics, shifting financial risk from payers to manufacturers and enabling broader patient access. Gilead Sciences leverages its Kite Pharma subsidiary to sustain integrated manufacturing from vector production through commercial infusion. Bristol-Myers Squibb Company anchors its position through deep clinical data in mantle cell lymphoma, the approved indication for brexucabtagene autoleucel. Novartis AG competes across the broader CAR T landscape with parallel pipeline investments in allogeneic platforms.
Brexucabtagene autoleucel is an autologous anti-CD19 CAR T-cell therapy manufactured through leukapheresis, T-cell activation, lentiviral transduction, and expansion over approximately two weeks, designed for intravenous infusion in relapsed or refractory mantle cell lymphoma. The CAR T-Cell technology segment dominates current revenue as the foundational platform, while CRISPR-engineered allogeneic approaches represent the fastest-growing innovation vector with potential to eliminate patient-specific manufacturing delays. Hospitals absorb the majority of end-user value given their role as both infusion sites and reimbursement collectors, whereas oncology clinics are emerging as preferred settings for earlier-line administration.
FDA's accelerated approval pathways and ongoing REMS requirements shape manufacturing quality standards and post-market surveillance obligations for all CD19-directed therapies. EMA's ATMP classification and centralized marketing authorization procedures govern commercial access across European Union member states, with national health technology assessments determining reimbursement. Manufacturers must monitor evolving FDA guidance on manufacturing changes and comparability protocols, as process innovations could alter supply economics faster than regulatory frameworks adapt.
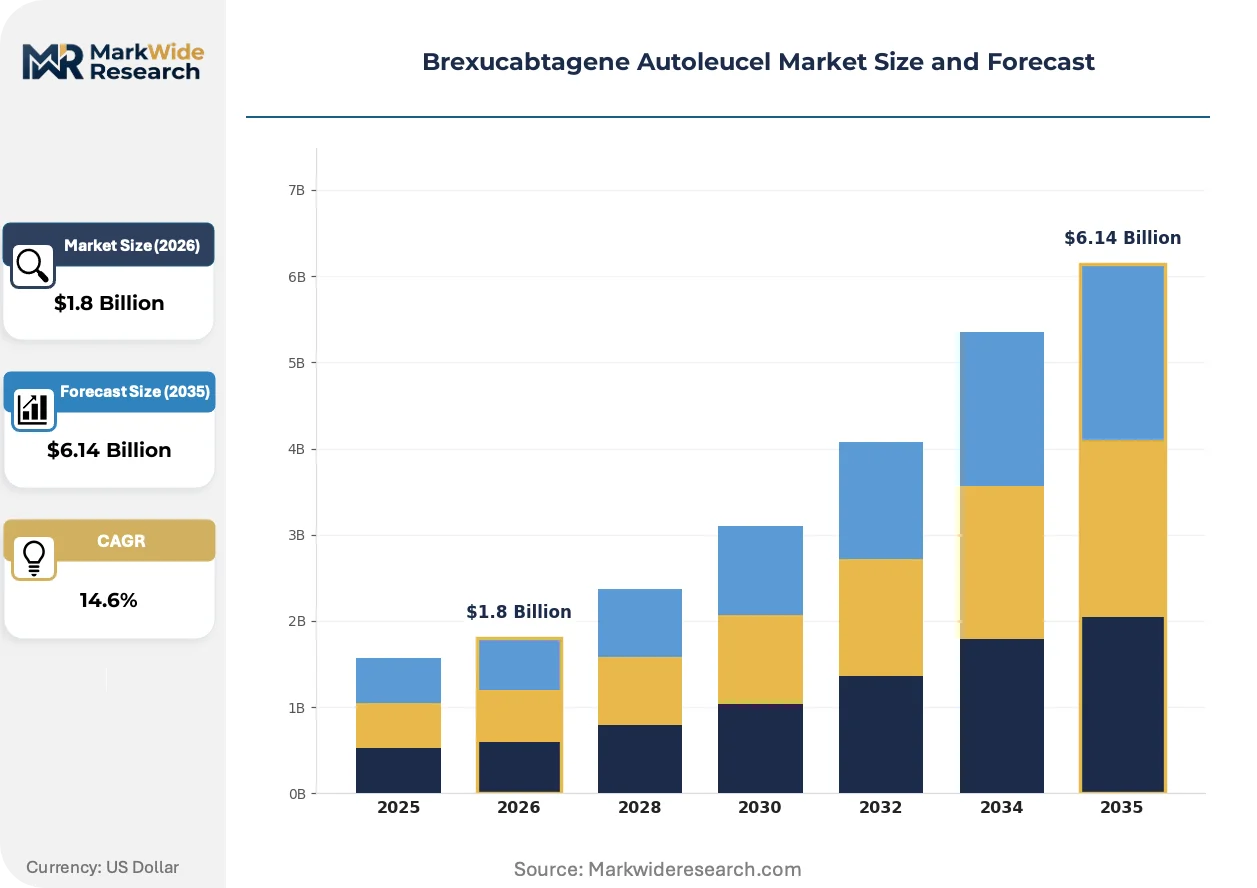
Market Dynamics
Outcome-based reimbursement contracts for CAR T-cell therapies are compressing traditional pharmaceutical pricing models and forcing manufacturers to absorb efficacy risk alongside clinical development costs. This structural shift reconfigures how value is captured across the autologous cell therapy supply chain.
Growth Catalysts
- FDA Accelerated Approval Pathways:Compressed timelines for breakthrough therapy designation are shortening commercialization cycles for autologous cell therapies in hematologic malignancies.
- Leukapheresis Infrastructure Expansion:Academic medical centers are deploying dedicated apheresis units capable of supporting CAR T-cell collection volumes at scale.
- Germany's Diagnosis-Related Group Reforms:Updated reimbursement codes for inpatient cell therapy administration are enabling hospital network adoption of advanced immunotherapies.
Market Restraints
- Vector Manufacturing Bottlenecks:Lentiviral vector production concentrates among limited contract manufacturers, creating supply vulnerability for autologous programs.
- Vein-to-Vein Timeline Rigidity:The fourteen-day manufacturing window for brexucabtagene autoleucel imposes hard constraints on patient eligibility and clinical workflow integration.
- EMA ATMP Classification Complexity:Centralized marketing authorization procedures impose prolonged regulatory review periods distinct from conventional biologics pathways.
Strategic Opportunities
- Japan's Sakigake Designation System:Priority review frameworks for regenerative medicines offer expedited market entry for autologous cell therapies with demonstrated efficacy signals.
- Allogeneic Platform Convergence:CRISPR-engineered universal donor cells paired with existing CAR constructs could eliminate patient-specific manufacturing infrastructure requirements.
- Outpatient Infusion Migration:Oncology clinics are developing capabilities for earlier-line administration outside traditional hospital admission frameworks.
Industry Challenges
- Cell Processing Technician Scarcity:Qualified personnel capable of aseptic manipulation in cleanroom environments remain concentrated at established manufacturing sites.
- Comparability Protocol Uncertainty:FDA guidance on manufacturing process changes lacks specificity for vector production modifications, creating regulatory submission risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brexucabtagene Autoleucel Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Therapy, Gene Therapy, Biologics, Immunotherapy End User: Hospitals, Research Facilities, Oncology Clinics, Diagnostic Centers Application: Blood Cancer, Solid Tumors, Autoimmune Disorders, Transplantation Technology: CRISPR, Viral Vectors, mRNA, CAR T-Cell |
| Companies Covered | Gilead Sciences, Kite Pharma, Bristol-Myers Squibb Company, Novartis AG, Johnson & Johnson, Juno Therapeutics, Iovance Biotherapeutics, Vericel Corporation, JW Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brexucabtagene Autoleucel Market Strategic Shifts
Digital supply chain coordination tools are virtualizing traditional cell therapy logistics, compressing the coordination burden between apheresis centers, manufacturing facilities, and infusion sites. This technological layer is enabling scale without proportional headcount expansion.
Closed-system bioreactors are virtualizing conventional open-cell culture processes, reducing contamination risk and enabling distributed manufacturing footprints. Kite Pharma and academic partners are deploying these systems to bring production closer to treatment centers. The technology is virtualizing the geographic constraints that previously concentrated manufacturing in centralized cleanroom facilities.
EMA's evolving guidance on post-authorization efficacy studies is tightening evidentiary requirements for accelerated ATMP approvals. Manufacturers must now commit to larger confirmatory trial populations and longer follow-up periods before commercial launch. European hematology networks are responding by consolidating patient data infrastructure to support mandated real-world evidence collection.
Hospital procurement departments are unbundling cell therapy service contracts, separating vector supply from manufacturing slot guarantees and clinical administration fees. This fragmentation is pressuring manufacturers to demonstrate discrete value at each supply chain node. United States academic medical centers are pioneering this decomposition, with German hospital networks following in subsequent contracting cycles.
Brexucabtagene Autoleucel Market Segmentation
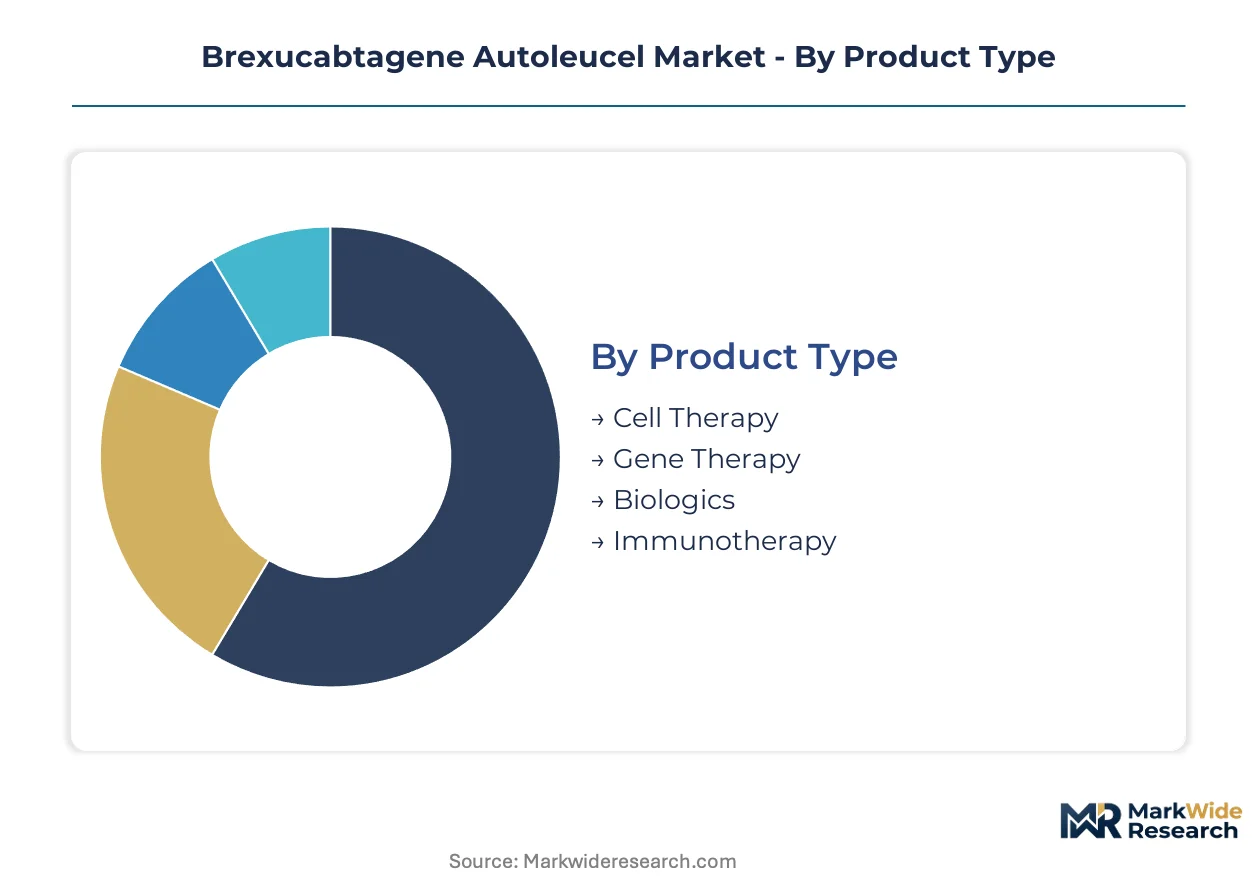
Segmentation in the brexucabtagene autoleucel market reveals how value flows through distinct technical and delivery channels. Each category exposes different velocity constraints, from manufacturing cycle times to patient eligibility windows.
Product Type:
Cell therapy products turn over fastest due to patient-specific manufacturing, while biologics move slowest through centralized batch production.
- Cell Therapy:Autologous CAR T-cell products require leukapheresis collection, lentiviral transduction, and expansion before infusion. Demand concentrates in hematology-oncology hospital networks across the United States, Germany, and Japan where apheresis infrastructure and cleanroom manufacturing coexist.
- Gene Therapy:Viral vector-based interventions target genetic modification at the cellular level. Academic medical centers in Germany absorb the majority of European demand, driven by EMA's ATMP classification pathway and national reimbursement frameworks for advanced therapeutic medicinal products.
- Biologics:Monoclonal antibodies and recombinant proteins serve as bridging or combination therapies.
- Immunotherapy:Checkpoint inhibitors and immune modulators complement CAR T-cell protocols.
Cell therapy dominates installed base. Gene therapy is where expansion concentrates.
End User:
Cost tier segmentation separates high-complexity inpatient administration from lower-cost outpatient settings.
- Hospitals:Academic medical centers and comprehensive cancer centers manage the full CAR T-cell workflow from apheresis through inpatient monitoring for cytokine release syndrome. United States hospital networks capture the majority of value given their integrated reimbursement collection and REMS-certified administration sites.
- Oncology Clinics:Community-based infusion centers are developing capabilities for earlier-line administration outside traditional admission frameworks. United States outpatient migration is accelerating fastest where payer contracts permit site-of-service flexibility.
- Research Facilities:University-affiliated centers conduct investigator-initiated trials and real-world evidence collection.
- Diagnostic Centers:Specialized pathology and flow cytometry laboratories support patient selection and response monitoring.
Hospitals dominate installed base. Oncology clinics are gaining share fastest.
Application:
Application segments stratify by patient volume and manufacturing maturity.
- Blood Cancer:Relapsed or refractory mantle cell lymphoma constitutes the approved indication, with well-established CD19-directed manufacturing protocols. United States hematology networks absorb the majority of demand, supported by FDA accelerated approval pathways and established REMS infrastructure.
- Solid Tumors:CAR T-cell penetration faces antigen heterogeneity and tumor microenvironment barriers. Early-phase trials concentrate at United States and German academic centers with dedicated cell processing facilities.
- Autoimmune Disorders:CD19-directed depletion approaches are advancing through investigator-initiated protocols.
- Transplantation:Graft-versus-host disease prophylaxis represents an emerging utility for engineered T-cell products.
Blood cancer dominates installed base. Solid tumors represent the steepest expansion trajectory.
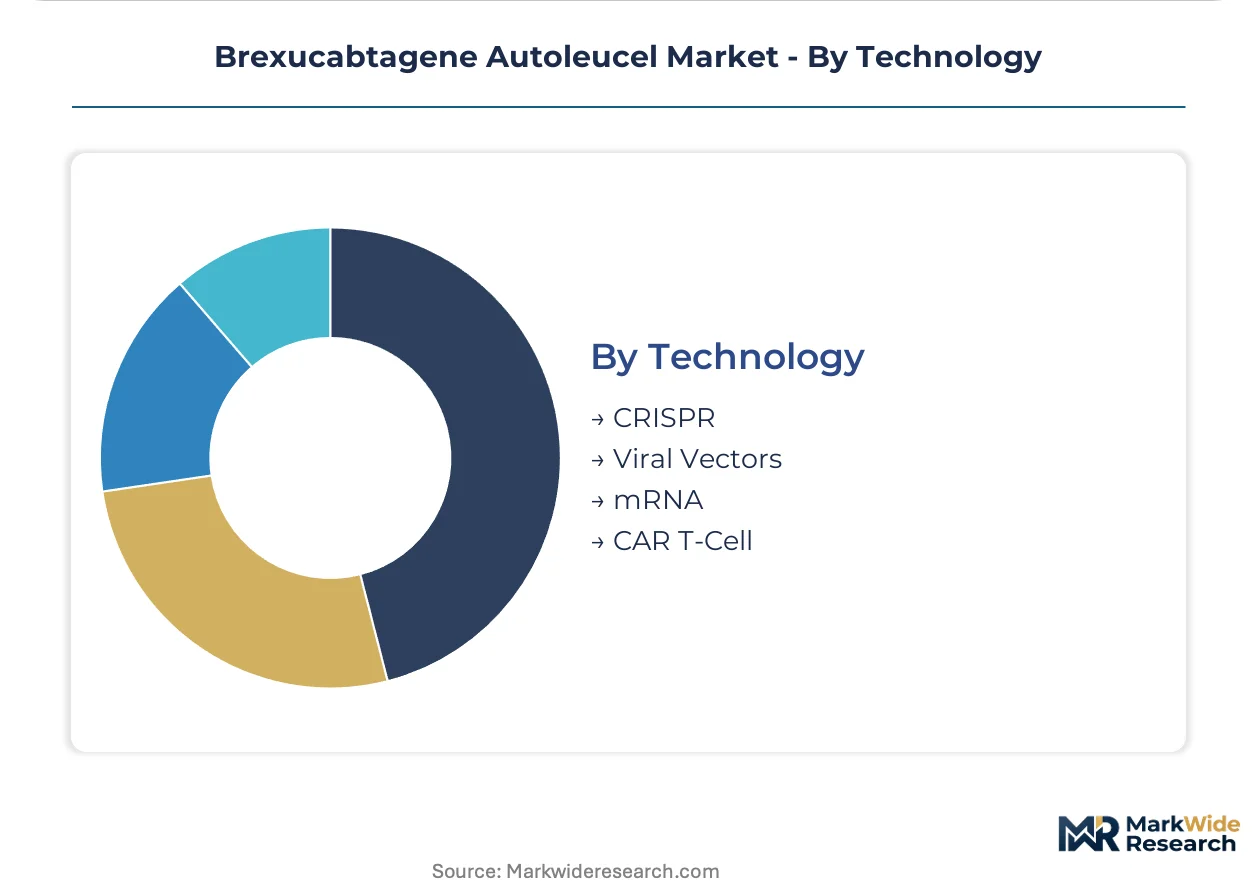
Technology:
Technology segments separate established platforms from next-generation engineering approaches.
- CAR T-Cell:Autologous anti-CD19 constructs manufactured through lentiviral transduction remain the commercial standard. Kite Pharma's integrated vector-to-infusion infrastructure anchors United States production capacity.
- CRISPR:Gene-edited allogeneic platforms promise to eliminate patient-specific manufacturing delays. Development activity concentrates at United States and Swiss biotech clusters with advanced gene editing capabilities.
- Viral Vectors:Lentiviral and gamma-retroviral delivery systems underpin current CAR T-cell production.
- mRNA:Transient expression systems enable rapid manufacturing iterations without genomic integration.
CAR T-Cell dominates installed base. CRISPR is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways and EMA's ATMP classification system compress commercialization timelines for autologous cell therapies. Payer frameworks in the United States, Germany, and Japan absorb the majority of manufacturing capacity. Hospital networks in these markets deploy dedicated apheresis units and REMS-certified infusion sites.
United States
Academic medical centers in Boston, Houston, and Seattle anchor demand through integrated vector-to-infusion infrastructure. FDA's breakthrough therapy designation and REMS requirements shape manufacturing quality standards and post-market surveillance obligations. Kite Pharma's manufacturing network concentrates in California and Maryland, supplying CAR T-cell products to hematology-oncology hospital networks nationwide.
Germany
University hospitals in Munich, Heidelberg, and Berlin absorb the majority of European demand for CD19-directed therapies. EMA's centralized marketing authorization procedures govern commercial access, with Germany's diagnosis-related group reforms enabling inpatient cell therapy reimbursement. The country's national pharmaceutical regulator mandates post-authorization efficacy studies that tighten evidentiary requirements for accelerated ATMP approvals.
Japan
Metropolitan hospital networks in Tokyo and Osaka lead Asia-Pacific adoption of autologous cell therapies. PMDA's Sakigake designation system offers priority review frameworks for regenerative medicines with demonstrated efficacy signals. Domestic manufacturers partner with United States-based vector suppliers to localize lentiviral production and reduce vein-to-vein timelines.
United Kingdom
London and Manchester hematology centers concentrate NHS-funded CAR T-cell administration within specialized treatment centers. The country's national pharmaceutical regulator aligns with EMA pathways while maintaining independent health technology assessment through NICE. Academic partnerships between Imperial College London and commercial manufacturers advance closed-system bioreactor deployment for distributed manufacturing.
Switzerland
Basel and Zurich hospital networks serve as European distribution hubs for vector supply and quality control. Swissmedic's marketing authorization procedures run parallel to EMA centralized procedures, enabling early commercial access. The country's pharmaceutical manufacturing heritage supports specialized cleanroom facilities for aseptic cell processing at scale.
Brexucabtagene Autoleucel Market Competitive Environment
Channel-controlling players compete with product-specialist players across the autologous cell therapy supply chain. The market structure concentrates around integrated manufacturers with captive vector production and hospital network partnerships. Three archetypes dominate: pharmaceutical conglomerates with cell therapy subsidiaries, standalone CAR T-cell specialists, and allogeneic platform developers. Competitive moves center on manufacturing capacity expansion and outcome-based reimbursement contracting with payers.
Among pharmaceutical conglomerates with integrated cell therapy infrastructure, Gilead Sciences and Bristol-Myers Squibb Company exemplify the channel-control archetype through subsidiary-based manufacturing. Kite Pharma, operating under Gilead Sciences, anchors United States production capacity with vector-to-infusion integration. Novartis AG occupies a position spanning both autologous commercial products and allogeneic pipeline investments, representing the diversified platform approach.
| Leading Market Players |
|---|
| Gilead Sciences |
| Kite Pharma |
| Bristol-Myers Squibb Company |
| Novartis AG |
| Johnson & Johnson |
| Juno Therapeutics |
| Iovance Biotherapeutics |
| Vericel Corporation |
| JW Therapeutics |
| Others |
Value Chain & Pricing Dynamics
Cold-chain logistics corridors connecting California manufacturing hubs to United States academic medical centers impose freight premiums that concentrate pricing power among integrated manufacturers with captive vector production, while compressing margins for contract-dependent competitors unable to absorb apheresis-to-infusion coordination costs.
Pricing Analysis
Certification level (FDA-grade manufacturing and REMS-certified administration sites) creates the primary spread between premium-tier autologous therapies and standard care alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects vein-to-vein timeline guarantees, vector quality grades, and bundled cytokine release syndrome monitoring. Cost compression in the standard tier is intensifying because hospital procurement departments are unbundling service contracts and demanding discrete value demonstration at each supply chain node. Community oncology clinics exhibit highest price sensitivity due to limited payer contract flexibility, while academic medical centers with integrated reimbursement collection tolerate premium positioning.
Supply Chain Analysis
Upstream lentiviral vector production draws from concentrated contract manufacturing capacity in the United States, Switzerland, and select German facilities with specialized cleanroom infrastructure. Critical inputs span plasmid DNA, packaging cell lines, and GMP-grade cell culture media with stringent lot-release requirements. Single-source vulnerability pervades vector supply given the limited qualified manufacturers capable of meeting FDA comparability protocols. Distribution runs through hospital-centric networks where REMS-certified sites control patient access and reimbursement capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CRISPR-engineered allogeneic platforms threaten to displace autologous manufacturing economics entirely, forcing incumbent CAR T-cell specialists to defend substitution risk through manufacturing efficiency and outcome-based contracting lock-in.
For Market Incumbents: Pre-empt allogeneic substitution by accelerating closed-system bioreactor deployment to compress vein-to-vein timelines below fourteen days, while deepening backward integration into lentiviral vector production to eliminate contract manufacturing dependency. Outcome-based reimbursement contracts with United States payers create switching costs that anchor patient volume against universal donor cell competition. For New Entrants and Emerging Players: Mid-market oncology clinics in Japan and Germany represent the most penetrable entry point for earlier-line administration outside saturated academic medical center networks. These settings lack integrated vector-to-infusion infrastructure but possess payer flexibility and growing patient eligibility pools. A go-to-market angle emphasizing outpatient cytokine release syndrome management protocols enables site-of-service differentiation without competing on manufacturing scale. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates with underutilized cell therapy subsidiaries lacking standalone commercial infrastructure. Long-term viability hinges on manufacturing slot utilization rates and vector production self-sufficiency rather than pipeline breadth alone. The signal to watch is FDA guidance clarity on manufacturing comparability protocols, which would trigger consolidation among vector-dependent developers unable to meet heightened quality standards.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-System Bioreactor Deployment | Kite Pharma's distributed manufacturing partnerships reduce geographic constraints on production capacity. |
| Outcome-Based Reimbursement Contracting | Bristol-Myers Squibb's mantle cell lymphoma risk-sharing agreements shift efficacy burden to manufacturers. |
| Allogeneic Platform Convergence | Novartis AG's parallel CRISPR investments target elimination of patient-specific manufacturing delays. |
| REMS-Certified Site Expansion | Hospital network partnerships in Houston and Seattle anchor United States infusion capacity growth. |
| Vector Production Backward Integration | Gilead Sciences' captive supply chain insulates against contract manufacturing bottlenecks. |
Study Parameters
Initial hypotheses were tested against primary input from cell therapy manufacturing executives, hospital procurement managers, payer access specialists, and regulatory affairs leads, then refined through secondary validation across FDA REMS databases, EMA ATMP submission records, ClinicalTrials.gov protocols, and national reimbursement code registries. Bottom-up patient volume modeling triangulated with top-down manufacturing capacity assessments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type (autologous versus allogeneic), end user (hospital versus clinic), and regional regulatory cluster (FDA breakthrough pathway, EMA centralized procedure, PMDA Sakigake designation). CAGRs were derived from manufacturing slot expansion trajectories and patient eligibility pool growth without year-specific calibration.
Practitioners should monitor FDA manufacturing change guidance and allogeneic clinical readouts for early signals of forecast revision triggers. Material shifts in vector production economics or accelerated approval evidentiary requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Rhu Albumin Market
Biopharmaceuticals
Biotherapeutics Cell Line Development Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
Global Monoclonal Antibodies (Mabs) Market
Biopharmaceuticals
Global Anti-Tuberculosis Therapeutics Market
Biopharmaceuticals
Influenza Vaccine Market
Biopharmaceuticals
Middle East and Africa Insulin Delivery Devices Market
Biopharmaceuticals
Global Vaccine Conjugate Market
Biopharmaceuticals
Biobetters Market
Biopharmaceuticals
Combination Antibody Therapy Market
Biopharmaceuticals
Oral Chemotherapy Market
Biopharmaceuticals
Global Staphylococcal Infection Drugs Market
Biopharmaceuticals
Generic Injectables Market
Biopharmaceuticals
Coagulation Factor IX Market
Biopharmaceuticals
Oncology Drugs Market
Biopharmaceuticals
Spectinomycin Market