
 Recombinant Human Interferon Protein Market | 2026-2036
Recombinant Human Interferon Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Recombinant Human Interferon Protein Market Analytics
Modular dosing formats and combination-ready vial configurations is expanding prescriber flexibility across outpatient oncology settings. Merck & Co., Inc. leverages its therapeutic protein manufacturing scale to supply bulk interferon alpha for institutional formulators. F. Hoffmann-La Roche Ltd anchors European distribution through specialty pharmacy networks that handle cold-chain biologics. GenScript Biotech Corporation competes on custom interferon constructs for preclinical research buyers in Asia-Pacific.
Recombinant human interferon proteins are glycosylated signaling cytokines produced in engineered mammalian or bacterial expression systems, typically exhibiting molecular weights between 16 and 27 kDa and antiviral, antiproliferative, and immunomodulatory activity. These proteins function primarily as therapeutic agents that modulate host immune responses against viral infections and malignant cell proliferation. Interferon alpha retains the largest revenue share among product types due to entrenched hepatitis and oncology indications, while interferon lambda represents the fastest-expanding category as investigators explore its tissue-restricted receptor profile for respiratory viral targets. Cancer therapy commands the dominant application value pool, though autoimmune disorders are gaining protocol share as rheumatology departments test interferon beta in combination with monoclonal antibody regimens.
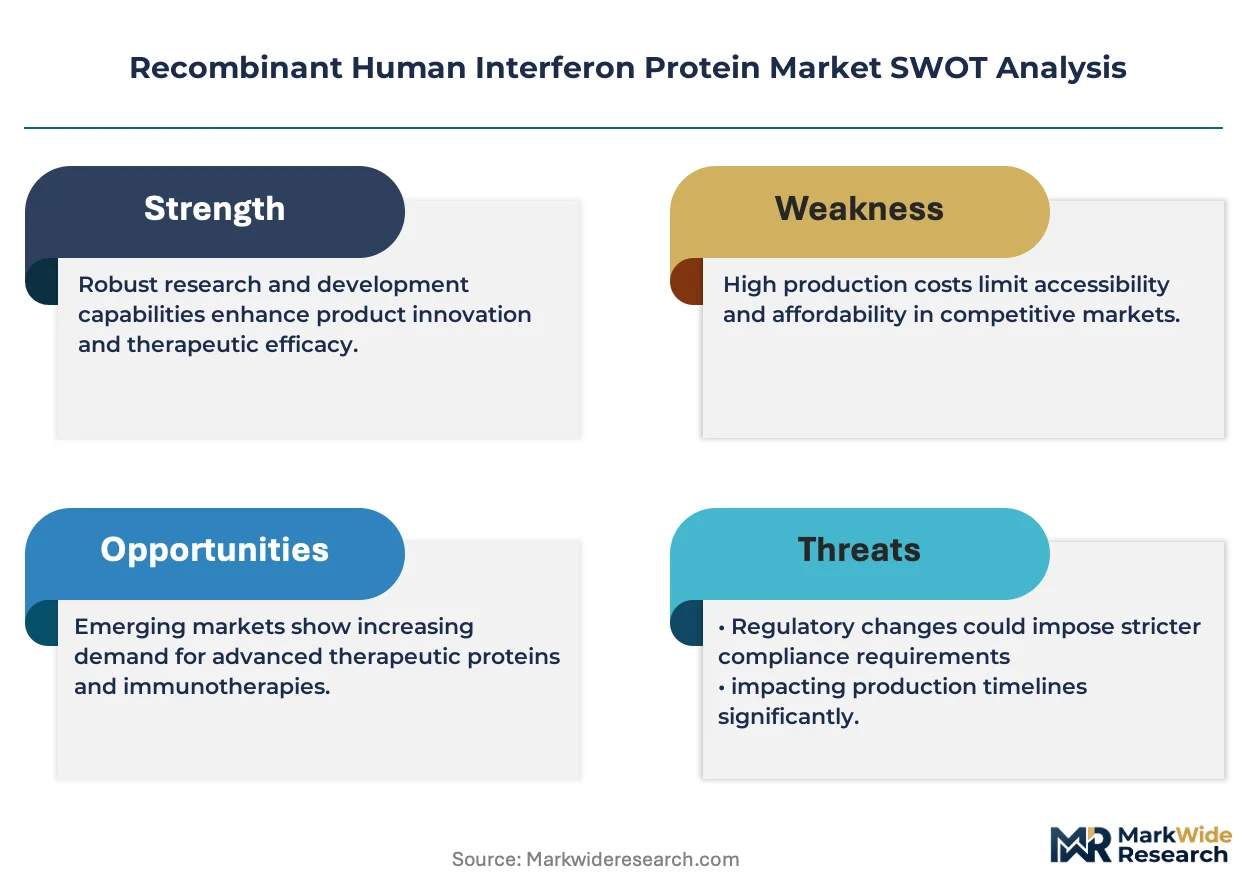
FDA biologics license application requirements and EMA biosimilar comparability guidelines shape clinical development costs and market entry timelines for interferon manufacturers. ISO 13485 quality management standards and WHO prequalification protocols govern contract manufacturing organizations that supply active pharmaceutical ingredient to emerging markets. Stakeholders must monitor regulatory divergence between FDA accelerated approval pathways and EMA conditional marketing authorization criteria when prioritizing development-stage assets.
Market Dynamics
Checkpoint inhibitor combination protocols in oncology are redrawing demand patterns for interferon alpha, pulling manufacturing investment toward high-potency, low-volume bioreactor configurations that serve immuno-oncology formulators.
Growth Catalysts
- FDA Biosimilar Pathway Refinements:Accelerated comparability protocols for second-generation interferon candidates compress development timelines and reduce clinical trial burden for sponsors targeting the United States.
- Respiratory Viral Targets:Interferon lambda's tissue-restricted receptor profile is attracting investigator interest for inhaled delivery against seasonal coronaviruses and influenza strains.
- China Biologics Manufacturing Clusters:Dedicated interferon production zones in Suzhou and Shanghai are attracting contract development organizations serving domestic hepatitis C eradication programs.
Market Restraints
- Mammalian Cell Culture Input Costs:Serum-free media and recombinant growth factors for Chinese hamster ovary expression systems face price volatility tied to agricultural commodity markets.
- Cold-Chain Distribution Concentration:Specialty pharmacy networks handling interferon vials concentrate in Germany, the United States, and Switzerland, creating single-point vulnerability for temperature excursions.
- PEGylated Interferon Substitution:Long-acting pegylated formulations in hepatitis B protocols displace standard interferon alpha in maintenance regimens across reimbursed markets.
Strategic Opportunities
- Autoimmune Disorder Protocols:Rheumatology departments in Germany and the United States are testing interferon beta in combination with monoclonal antibody regimens for multiple sclerosis and lupus.
- WHO Prequalification:Emerging market procurement through WHO-prequalified active pharmaceutical ingredient suppliers opens institutional volume for contract manufacturers meeting ISO 13485 standards.
- Modular Dosing Formats:Combination-ready vial configurations enable outpatient oncology clinics to customize interferon dosing alongside checkpoint inhibitors without compounding pharmacy delays.
Industry Challenges
- Glycosylation Consistency:Batch-to-batch heterogeneity in N-linked glycan patterns complicates biosimilar comparability studies and requires sophisticated analytical chemistry capabilities.
- EMA Conditional Marketing Authorization:Accelerated approval pathways demand post-authorization efficacy commitments that strain pharmacovigilance infrastructure for mid-cap sponsors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recombinant Human Interferon Protein Market |
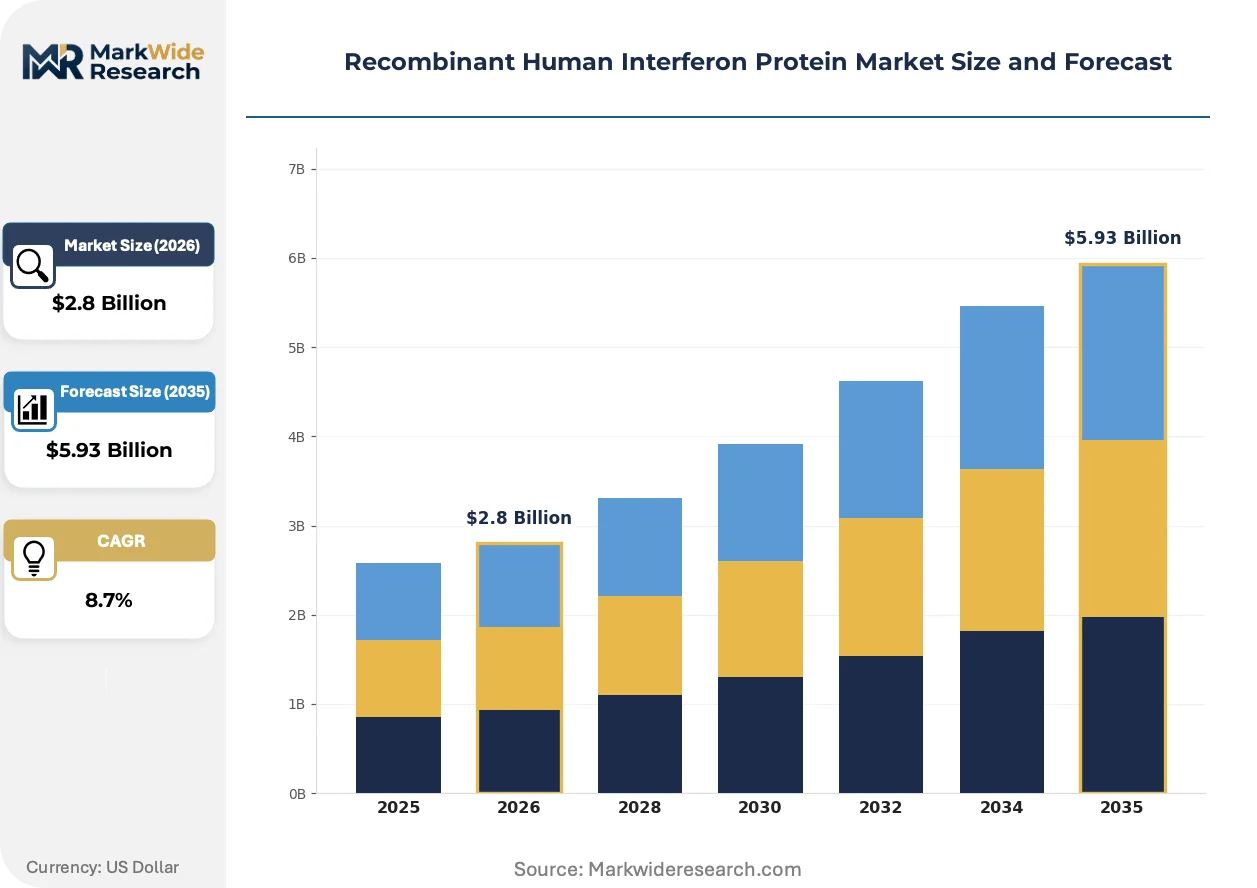
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interferon Alpha, Interferon Beta, Interferon Gamma, Interferon Lambda Application: Cancer Therapy, Autoimmune Disorders, Infectious Diseases, Hepatitis Treatment End User: Hospitals, Research Institutions, Diagnostic Laboratories, Pharmaceutical Companies Delivery Mode: Injectable, Intranasal, Oral, Transdermal |
| Companies Covered | Merck & Co., Inc., Biogen Inc., F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific Inc., Bio-Techne, Abcam plc, Merck KGaA, GenScript Biotech Corporation, Sino Biological, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recombinant Human Interferon Protein Market Evolving Landscape
Continuous bioprocessing architectures are displacing traditional fed-batch manufacturing, compressing facility footprints while demanding new skill sets in process analytical technology and real-time release testing.
Single-use bioreactor technology is automating upstream interferon production through integrated perfusion systems that maintain cell density without manual sampling. Contract manufacturers in Singapore and Ireland are adopting these platforms to serve multi-product facilities. The shift is automating changeover protocols and reducing cross-contamination risk for high-value cytokine campaigns.
EMA biosimilar comparability guidelines now mandate extensive physicochemical characterization that exceeds FDA requirements for analytical depth. Sponsors targeting European approval must invest in mass spectrometry and glycan mapping capabilities earlier in development. Interferon alpha biosimilars face the steepest compliance burden due to entrenched reference product complexity.
Hospital procurement consortia in the United States are consolidating interferon purchasing through specialty pharmacy networks that bundle cold-chain logistics with reimbursement support. Academic medical centers in Boston and Houston are negotiating multi-year supply agreements that lock in volume commitments. The consolidation is squeezing independent distributors and favoring vertically integrated biologics suppliers with captive cold-chain infrastructure.
Recombinant Human Interferon Protein Market Segmentation
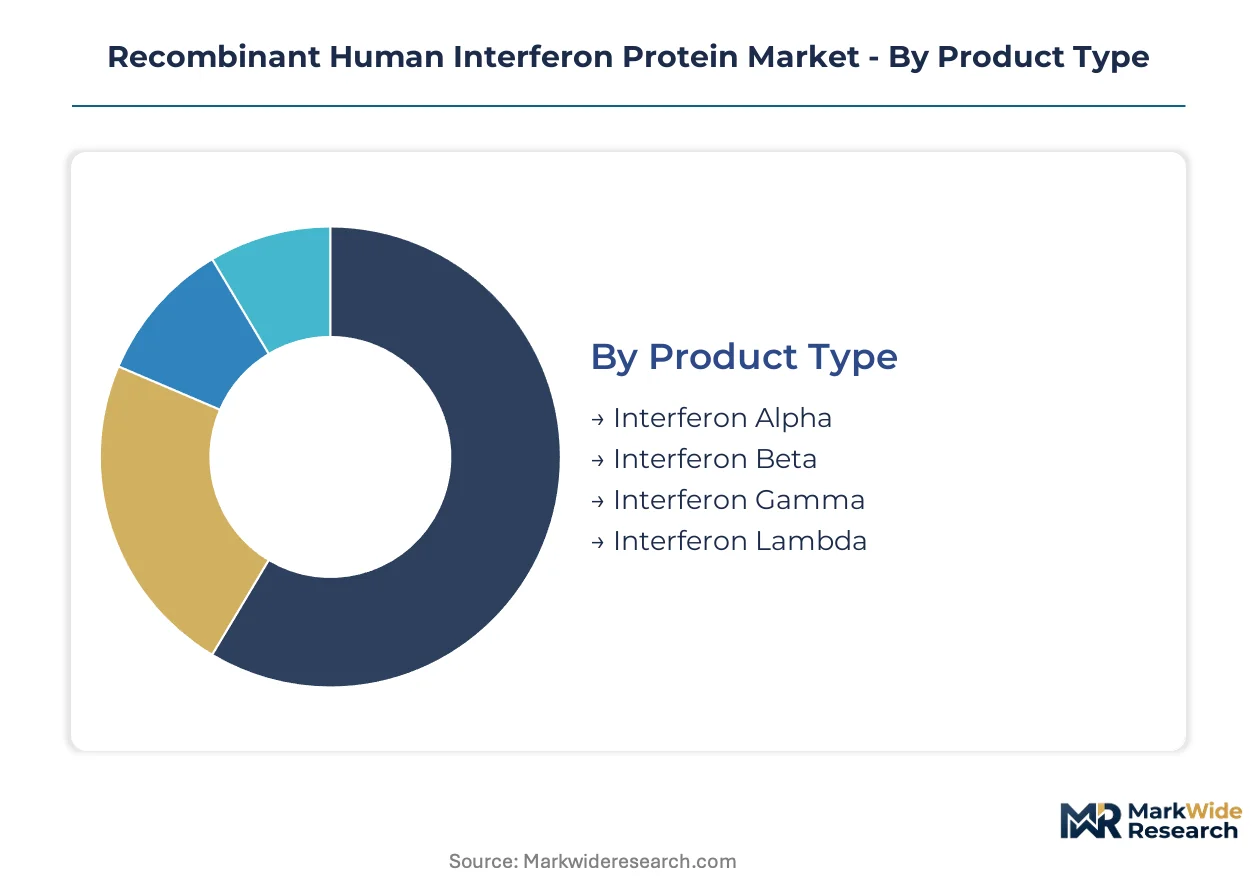
Segmentation in the recombinant human interferon protein market reveals how regulatory pathways, manufacturing complexity, and clinical application requirements fragment procurement patterns across buyer categories. Understanding these divisions enables suppliers to align quality certifications, cold-chain capabilities, and dosing formats with specific customer technical specifications.
Product Type:
EMA biosimilar comparability guidelines and FDA biologics license application requirements impose distinct analytical chemistry burdens on each interferon variant, with glycosylation complexity determining the depth of physicochemical characterization needed for approval.
- Interferon Alpha:The most extensively glycosylated variant with entrenched reference product complexity requiring mass spectrometry and glycan mapping capabilities for biosimilar sponsors. Oncology clinics in the United States and hepatitis eradication programs in China concentrate procurement volume for this segment, though PEGylated formulations are displacing standard versions in maintenance regimens.
- Interferon Beta:A 22 kDa glycoprotein with established multiple sclerosis protocols driving institutional demand. Rheumatology departments in Germany and the United States are testing this variant in combination with monoclonal antibody regimens for lupus, expanding its addressable patient population beyond neurology.
- Interferon Gamma:A non-glycosylated homodimer produced in bacterial expression systems with simpler manufacturing requirements but narrower clinical indications.
- Interferon Lambda:The tissue-restricted receptor profile of this variant attracts respiratory viral target development, with investigators exploring inhaled delivery against seasonal coronaviruses.
Leading the category by volume: Interferon Alpha. Growing fastest: Interferon Lambda.
Application:
Cost tier stratification across these applications reflects the difference between reimbursed oncology protocols and emerging infectious disease programs with less predictable procurement funding.
- Cancer Therapy:Checkpoint inhibitor combination protocols in North American oncology clinics are redrawing demand patterns, pulling manufacturing investment toward high-potency, low-volume bioreactor configurations. Academic medical centers in Boston and Houston negotiate multi-year supply agreements that lock in volume commitments for interferon alpha.
- Autoimmune Disorders:Multiple sclerosis and lupus protocols generate recurring institutional demand with less price sensitivity than infectious disease applications. The segment benefits from established reimbursement codes in Germany and the United States.
- Infectious Diseases:Respiratory viral targets and emerging pathogen preparedness programs concentrate procurement through government stockpiles.
- Hepatitis Treatment:Declining protocol share in developed markets as direct-acting antivirals displace interferon-based regimens, though China's eradication programs sustain regional volume.
Dominant by revenue concentration: Cancer Therapy. Expanding most quickly: Autoimmune Disorders.
End User:
Customer type determines whether procurement runs through consolidated hospital consortia, fragmented research grant funding, or specialized pharmaceutical supply chains.
- Hospitals:Consolidated purchasing through specialty pharmacy networks bundles cold-chain logistics with reimbursement support, squeezing independent distributors. These buyers demand modular dosing formats and combination-ready vial configurations for outpatient oncology settings.
- Pharmaceutical Companies:Contract development organizations serving this segment require ISO 13485 quality management standards and WHO prequalification for emerging market supply. Multi-product facilities in Singapore and Ireland automate upstream production through single-use bioreactor technology.
- Research Institutions:Custom interferon constructs for preclinical buyers in Asia-Pacific drive smaller-batch procurement with higher per-unit margins.
- Diagnostic Laboratories:Standardized reference materials and assay development kits constitute a lower-volume, specification-driven segment.
Highest procurement volume: Hospitals. Steepest expansion trajectory: Pharmaceutical Companies.
Delivery Mode:
Supply concentration in cold-chain infrastructure creates single-point vulnerability for temperature excursions, with distribution networks in Germany, the United States, and Switzerland handling the majority of injectable volumes.
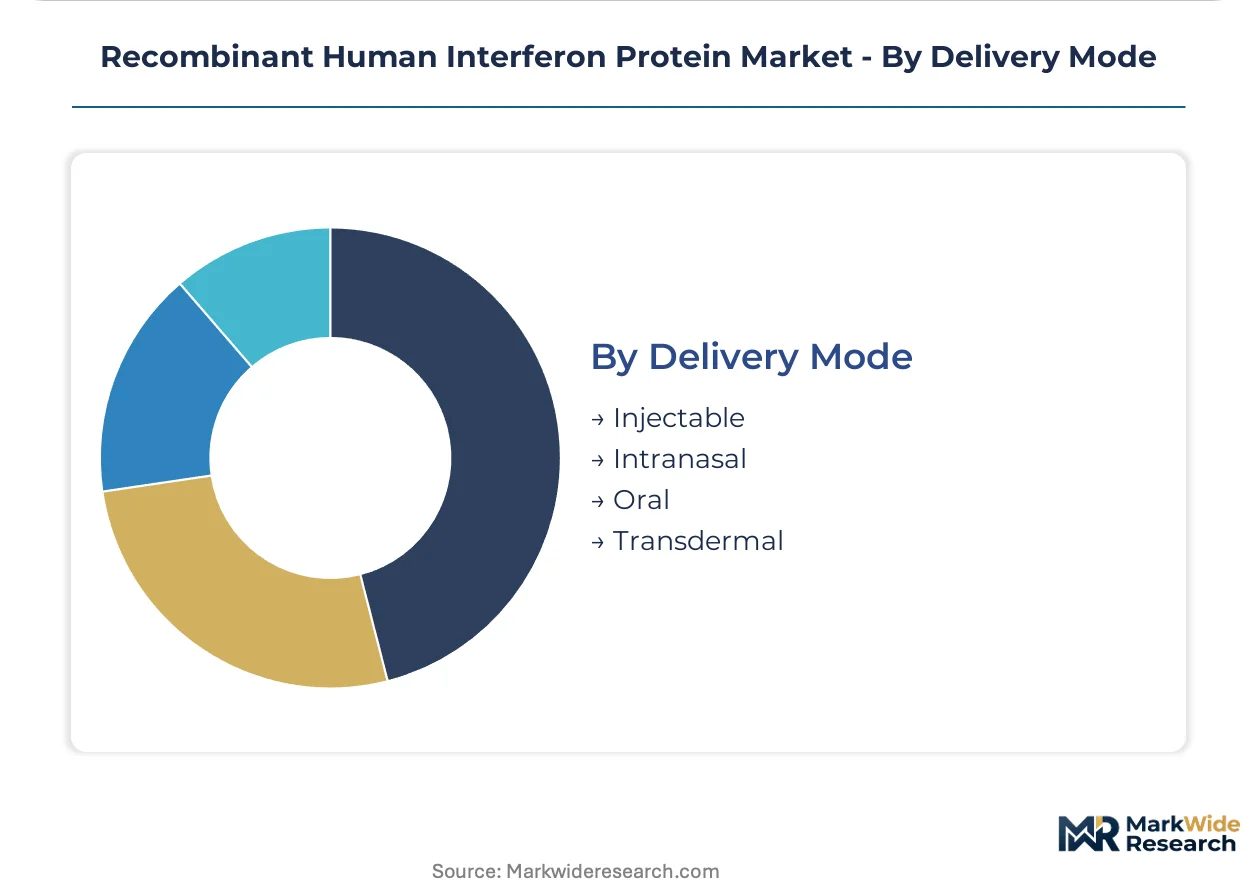
- Injectable:The dominant delivery format requiring captive cold-chain infrastructure and specialty pharmacy networks. Vial configurations must accommodate combination protocols without compounding pharmacy delays.
- Intranasal:Emerging format for interferon lambda respiratory applications with simpler storage requirements but unproven reimbursement pathways.
- Oral:Limited bioavailability challenges for interferon proteins constrain clinical development, with most programs stalled in preclinical stages.
- Transdermal:Patch-based delivery systems under investigation for interferon beta in multiple sclerosis maintenance protocols.
Commanding institutional procurement: Injectable. Gaining share fastest: Intranasal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Suzhou Industrial Park's 15% corporate income tax rate for biotech enterprises concentrates interferon manufacturing investment in China's Yangtze River Delta corridor. This fiscal architecture pulls contract development organizations toward dedicated production zones.
United States
Oncology clinics in Boston and Houston negotiate multi-year supply agreements for interferon alpha used in checkpoint inhibitor combinations. FDA biosimilar pathway refinements compress development timelines for second-generation candidates. Academic medical centers anchor procurement volume through consolidated specialty pharmacy networks.
China
Hepatitis C eradication programs sustain regional demand for interferon alpha despite declining protocol share elsewhere. NMPA streamlined biologics license reviews for contract manufacturers meeting dual carbon goals. Shanghai and Suzhou biologics manufacturing clusters attract CDMO investment through tax incentives and dedicated production zones.
Germany
Rheumatology departments in Berlin and Munich test interferon beta in combination with monoclonal antibody regimens for lupus. EMA biosimilar comparability guidelines mandate extensive physicochemical characterization exceeding FDA analytical depth requirements. Bavaria's specialty pharmacy networks handle cold-chain distribution for institutional formulators across Central Europe.
Switzerland
Swissmedic's alignment with EMA conditional marketing authorization criteria attracts sponsors seeking European approval pathways. Basel and Zurich host multi-product biologics facilities serving interferon campaigns through single-use bioreactor technology. The country's captive cold-chain infrastructure supports distribution to German and French hospital consortia.
Singapore
Contract manufacturers automate upstream interferon production through integrated perfusion systems for Asia-Pacific pharmaceutical clients. The country's ISO 13485-certified facilities supply WHO-prequalified active pharmaceutical ingredient to emerging market procurement programs. Jurong Island's biologics hub serves multi-product campaigns with reduced cross-contamination risk.
Recombinant Human Interferon Protein Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the interferon protein value chain. The market structure tilts toward consolidated supply relationships, with hospital procurement consortia squeezing independent distributors in favor of vertically integrated biologics suppliers. Three archetypes dominate: therapeutic protein manufacturers leveraging mammalian cell culture scale, research-grade suppliers serving preclinical buyers with custom constructs, and contract development organizations offering multi-product flexibility. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players secure captive cold-chain infrastructure and automate changeover protocols.
Within the diversified pharmaceutical tier, Merck & Co., Inc. and F. Hoffmann-La Roche Ltd occupy positions anchored by therapeutic protein manufacturing scale and European specialty pharmacy distribution respectively. GenScript Biotech Corporation exemplifies the research-grade specialist archetype, serving custom construct demand from Asia-Pacific preclinical buyers. These three entities represent the spectrum from institutional formulator supply to smaller-batch, higher-margin research procurement.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Biogen Inc. |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific Inc. |
| Bio-Techne |
| Abcam plc |
| Merck KGaA |
| GenScript Biotech Corporation |
| Sino Biological, Inc. |
| Others |
Value Network & Pricing Analysis
Captive cold-chain infrastructure anchors both supply position and pricing power for interferon suppliers serving institutional formulators. Vertically integrated biologics manufacturers with in-house temperature-controlled distribution command premium positioning against distributors dependent on third-party logistics networks.
Pricing Analysis
Short lead-time premiums separate emergency procurement from scheduled replenishment contracts in institutional interferon purchasing. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with WHO-prequalified API commanding highest positioning. Cost compression in standard interferon alpha runs through PEGylated substitution pressure in hepatitis protocols. Pharmaceutical companies show least price sensitivity due to captive formulation requirements, while research institutions exhibit highest elasticity.
Supply Chain Analysis
Returns and temperature excursion protocols absorb substantial working capital for interferon distributors handling injectable vials. Manufacturing concentrates in China, Germany, and the United States, with Suzhou and Shanghai biologics clusters feeding domestic hepatitis programs. Serum-free media and recombinant growth factors draw from agricultural commodity markets, creating input cost volatility. Single-source vulnerability concentrates in specialty pharmacy networks handling cold-chain logistics. Distribution runs through consolidated hospital consortia bundling reimbursement support with physical delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EMA biosimilar comparability guidelines erect barrier-to-entry moats favoring sponsors with mass spectrometry and glycan mapping capabilities.
For Market Incumbents: Acquire cold-chain infrastructure assets to defend against independent distributor displacement by hospital procurement consortia. Expand single-use bioreactor capacity in Singapore or Ireland to automate changeover protocols for multi-product interferon campaigns. PEGylated formulation substitution in hepatitis maintenance regimens threatens standard interferon alpha volume. For New Entrants and Emerging Players: The premium-economy price-point gap in interferon lambda respiratory applications opens white-space for inhaled delivery development. Target autoimmune disorder protocols in German rheumatology departments testing interferon beta combination regimens. Pursue WHO prequalification pathway to access emerging market procurement through institutional volume commitments. For Investors and Strategic Acquirers: Exit pathways concentrate in contract development organizations with ISO 13485 certification and captive mammalian cell culture scale. Long-term viability hinges on sponsors navigating divergent FDA accelerated approval and EMA conditional marketing authorization requirements. Watch for checkpoint inhibitor combination protocol maturation as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Biosimilar Comparability Investment | Mass spectrometry and glycan mapping capabilities enable European market entry for second-generation candidates. |
| Single-Use Bioreactor Technology Adoption | Singapore and Ireland facilities automate upstream production while reducing cross-contamination risk. |
| Cold-Chain Infrastructure Captive Buildout | Vertically integrated temperature-controlled distribution secures positioning against third-party logistics dependence. |
| Checkpoint Inhibitor Combination Development | Oncology clinics in Boston and Houston lock multi-year supply agreements for immuno-oncology formulators. |
| WHO Prequalification Pathway Pursuit | Emerging market procurement through institutional volume opens for ISO 13485-certified API suppliers. |
Research Methodology
Document review covered FDA biologics license applications, EMA marketing authorization submissions, and WHO prequalification records, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and contract manufacturing officers. Secondary validation drew from ClinicalTrials.gov, formulary databases, and customs trade data. Bottom-up and top-down triangulation reconciled facility capacity estimates with institutional purchasing patterns.
Segmented outputs across product type, application, end user, and delivery mode fed into analytical framework spanning the projection horizon. CAGRs derived from regression against historical volume trajectories and regulatory approval timelines. Modeled inputs included bioreactor capacity utilization, glycosylation batch consistency rates, and cold-chain infrastructure expansion.
Inputs from EMA and FDA filings were available through the study window; gaps in real-time manufacturing cost data introduce uncertainty bands around margin projections. Forecasts reflect assumptions on biosimilar pathway refinement velocity and checkpoint inhibitor protocol maturation. Practitioners should monitor PEGylated substitution rates in hepatitis protocols and interferon lambda respiratory trial readouts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Asia-Pacific Plant-Based Biologics Market
Biopharmaceuticals
Insulin Secretagogues Market
Biopharmaceuticals
Biopharmaceuticals Packaging Market
Biopharmaceuticals
Insulin API Market
Biopharmaceuticals
Hemophilia B Market
Biopharmaceuticals
Global Immuno Oncology Assays Market
Biopharmaceuticals
Global Mono Vaccine Market
Biopharmaceuticals
Rhu Albumin Market
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
Global Diagnostic Specialty Antibodies Market
Biopharmaceuticals
Global Akabane Vaccines Market
Biopharmaceuticals
Recombinant Erythropoietin Market
Biopharmaceuticals
Europe Monoclonal Antibodies Market
Biopharmaceuticals
Global Recombinant Proteins Market
Biopharmaceuticals
US Generic Drug Market
Biopharmaceuticals
Plasmid DNA Manufacturing Market