
 Global Exosome Research Products Market | 2026-2036
Global Exosome Research Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Exosome Research Products Market Foresight
The EU Green Deal's push for sustainable biomanufacturing is consolidating demand for cleaner production chemistries across exosome research supply chains. Thermo Fisher Scientific leverages its chromatography and reagent portfolios to anchor North American distribution. Bio-Techne sustains competitive intensity through specialized antibody and protein reagent development. QIAGEN dominates nucleic acid extraction workflows that feed downstream exosome RNA analysis pipelines.
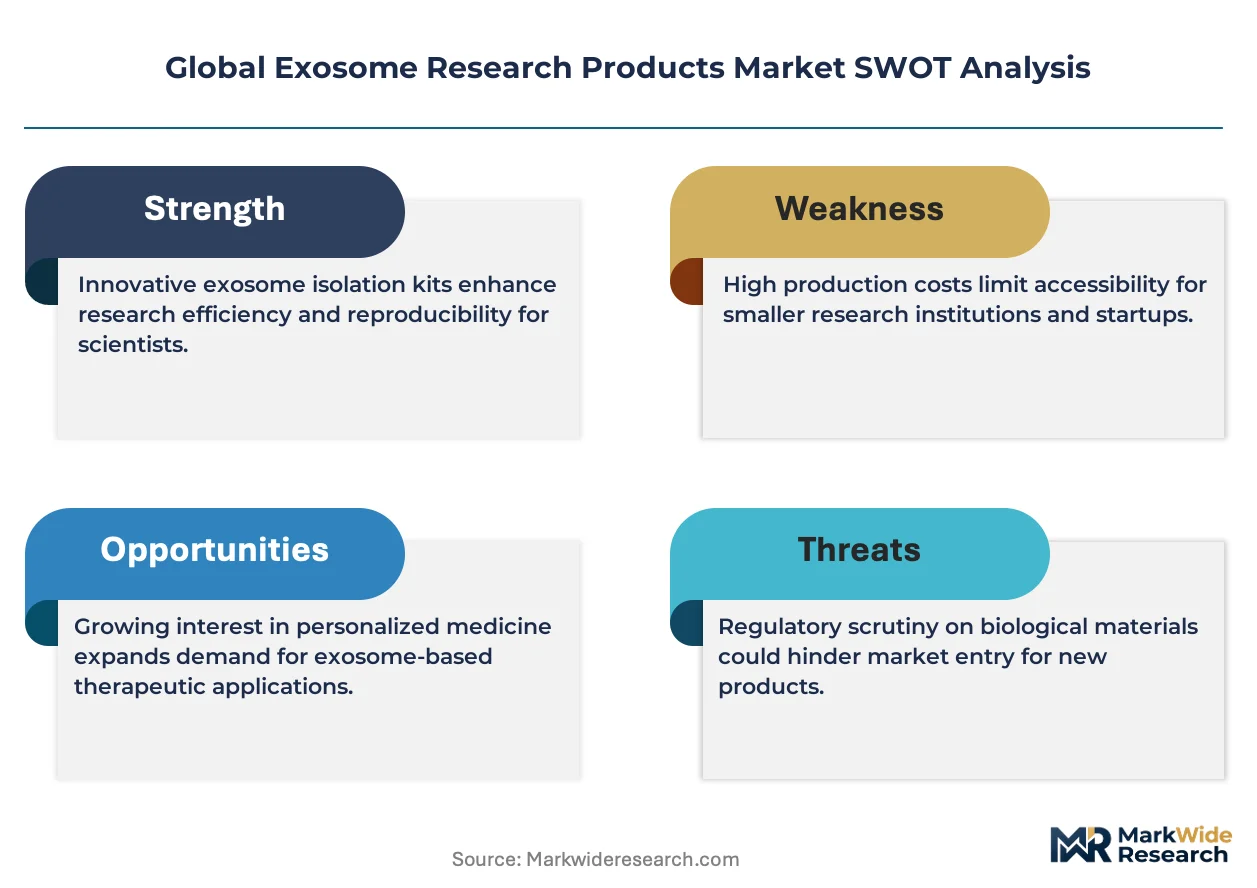
Exosome research products encompass specialized reagents, instruments, and media formulated for the isolation, purification, labeling, and characterization of extracellular vesicles 30–150 nm in diameter, typically derived from cell culture supernatants or biofluids through differential ultracentrifugation or size-based separation methods. These products enable quantification of surface markers, cargo profiling, and functional assays critical to translational research in oncology and neurology. Academic research institutes represent the most mature demand pool, though biopharmaceutical companies are accelerating fastest as exosome engineering matures toward therapeutic applications. Ultracentrifugation technology occupies the largest installed base, while microfluidics-based isolation systems command premium positioning due to throughput and purity advantages.
FDA draft guidance on extracellular vesicle characterization, combined with EMA's advanced therapy medicinal products framework and ISO 13485 quality system requirements, is tightening validation standards for commercial reagent suppliers. Japan's PMDA has signaled closer scrutiny of exosome-derived therapeutic submissions, adding compliance layers for manufacturers targeting Asian clinical translation. Stakeholders must monitor how evolving pharmacopeial standards for extracellular vesicle potency and purity reshape product qualification timelines and R&D prioritization across the value chain.
Market Dynamics
Microfluidics-based isolation systems are compressing the installed base advantage of ultracentrifugation, forcing reagent suppliers to reconfigure purification chemistry portfolios around gentler, higher-throughput workflows demanded by biopharmaceutical contract manufacturers.
Growth Catalysts
- EMA Advanced Therapy Medicinal Products framework:The classification pathway accelerates clinical translation timelines for engineered exosome therapeutics, pulling demand for characterization reagents into European biopharmaceutical pipelines.
- NIH extramural funding concentration:United States academic oncology and neurology institutes are expanding core facility budgets for extracellular vesicle analysis, sustaining instrument and consumable procurement cycles.
- Size-exclusion chromatography:This gentler isolation method preserves surface marker integrity for downstream functional assays, displacing harsher density-gradient protocols in stem cell research workflows.
Market Restraints
- High-purity sucrose and density gradient media costs:Input chemical prices fluctuate with agricultural commodity cycles, squeezing margin structures for reagent kit manufacturers.
- Ultracentrifuge rotor supply concentration:Precision-machined titanium rotors depend on a limited supplier base in Germany and Japan, creating lead time vulnerability for replacement parts.
- ISO 13485 compliance timelines:Quality system certification for clinical-grade reagents extends product development cycles by 18-24 months versus research-use-only formulations.
Strategic Opportunities
- India contract research expansion:CDSCO's streamlined biologics guidelines and PLI scheme incentives are attracting exosome engineering investment to Hyderabad and Bengaluru clusters.
- Point-of-care diagnostic integration:Lateral flow and electrochemical biosensor platforms are converging with exosome surface marker detection, opening decentralized testing channels.
- Japan PMDA regenerative medicine designation:The expedited review pathway for exosome-derived therapeutics is concentrating CRO and CDMO partnerships in Kobe and Osaka bioclusters.
Industry Challenges
- Extracellular vesicle quantification standardization:Inconsistent nanoparticle tracking analysis protocols across laboratories complicate cross-study data comparability and regulatory submission packages.
- Cross-functional talent scarcity:The intersection of vesicle biology, analytical chemistry, and regulatory science requires hybrid skill sets that academic training programs have not yet scaled.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Exosome Research Products Market |
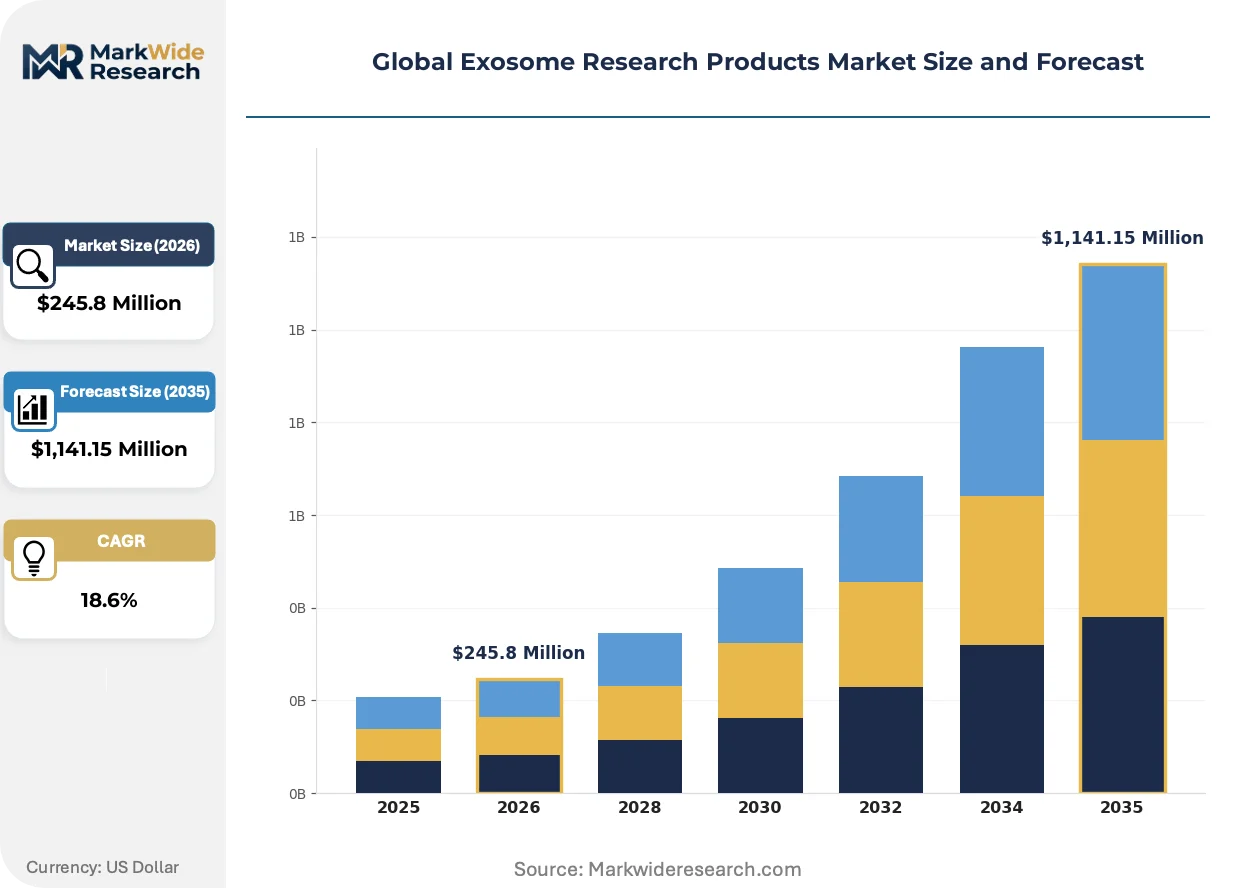
| Market Size in 2026 | $245.8 Million |
| Market Size in 2035 | $1,141.15 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exosome Isolation Kits, Exosome Characterization Instruments, Exosome Labeling Reagents, Culture Media, RNA Extraction Kits Application: Cancer Diagnostics, Neurodegenerative Disease Research, Cardiovascular Research, Drug Delivery Systems, Biomarker Discovery End User: Academic Research Institutes, Biopharmaceutical Companies, Clinical Laboratories, Contract Research Organizations, Government Research Bodies Technology: Ultracentrifugation, Size Exclusion Chromatography, Microfluidics, Immunoaffinity Capture, Polymer-based Precipitation |
| Companies Covered | Thermo Fisher Scientific Inc., Bio-Techne, QIAGEN, Lonza, Danaher Corporation, System Biosciences LLC, Hologic Inc., Miltenyi Biotec, Takara Bio Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Exosome Research Products Market Shifts & Advancements
Automation and miniaturization are compressing manual workflow steps while regulatory science advances are hardening analytical validation standards for clinical translation.
Microfluidic immunoaffinity capture chips are overtaking traditional immunomagnetic bead workflows in high-throughput screening applications. Biopharmaceutical discovery groups in the United States and Switzerland are adopting these platforms for parallel processing of biofluid cohorts. The shift is compressing sample-to-data timelines from days to hours while reducing operator-dependent variability.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of surface coating chemistries used in exosome isolation membranes. European reagent suppliers are substituting fluorine-free alternatives into spin column and filtration device production lines. The transition is elevating R&D costs for manufacturers serving EMA-regulated clinical markets.
Consolidated procurement through core facility managers is displacing principal investigator-driven purchasing in major research universities. Centralized budget authority in Boston, Heidelberg, and Singapore clusters is favoring vendors offering multi-year service contracts and integrated training programs. The pattern concentrates purchasing power among fewer supplier relationships per institution.
Global Exosome Research Products Market Segmentation
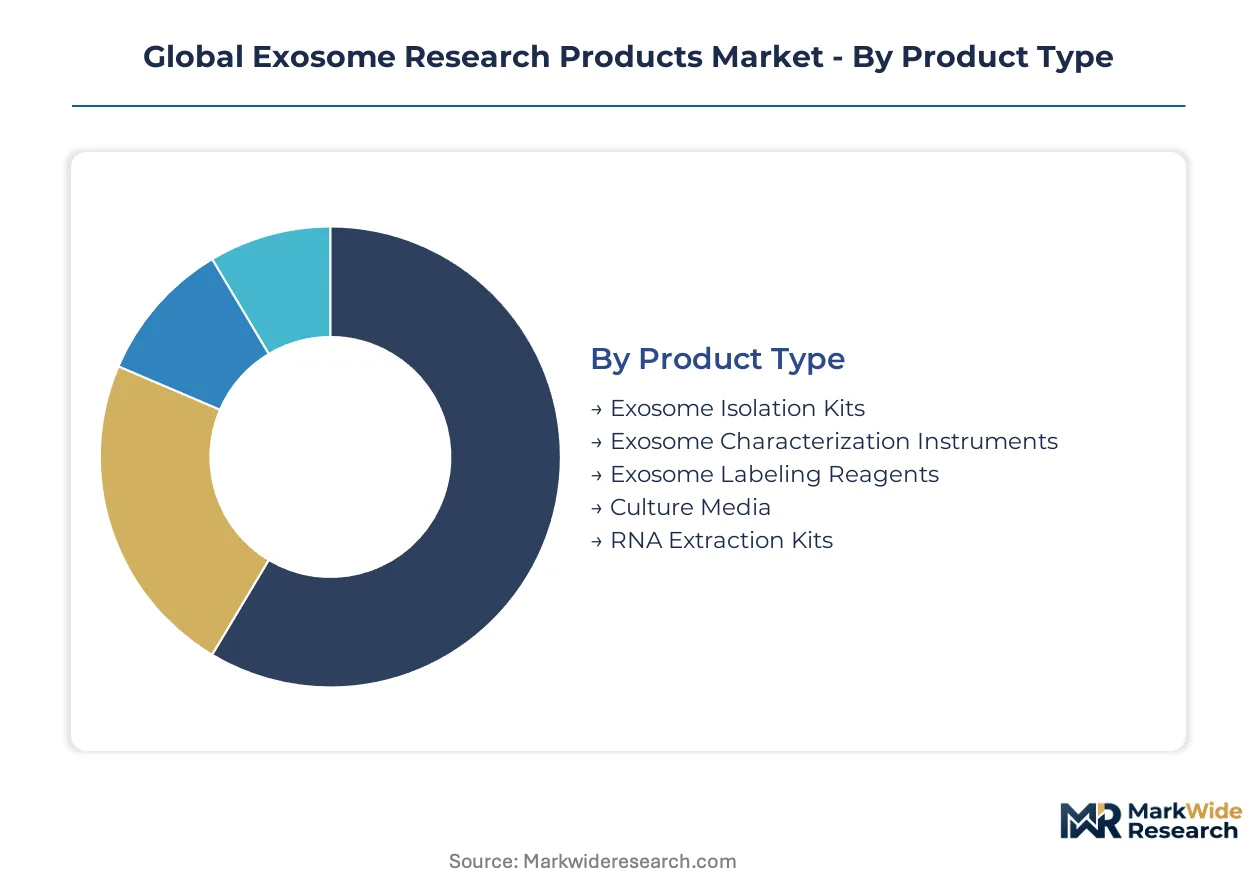
Exosome research product purchasing decisions fragment across technical performance requirements, regulatory compliance tiers, and workflow integration needs. Supply chain configuration varies sharply by segment, with reagent kits flowing through distribution networks distinct from capital equipment procurement channels.
Product Type:
Supply concentration for raw materials and manufacturing expertise shapes competitive dynamics across each product category.
- Exosome Isolation Kits:Chromatography spin columns and precipitation reagents dominate commercial portfolios. Academic core facilities in the United States and Germany are consolidating procurement around multi-year kit supply contracts with integrated protocol validation support.
- Exosome Characterization Instruments:Nanoparticle tracking analyzers and flow cytometry systems represent the highest capital commitment segment. Biopharmaceutical quality control laboratories in Switzerland and Massachusetts are driving demand for instruments with 21 CFR Part 11-compliant software packages.
- Exosome Labeling Reagents:Fluorescent membrane dyes and antibody conjugation kits enable downstream functional assays. Stem cell research centers in California and Singapore represent concentrated uptake for live-cell compatible formulations.
- Culture Media:Exosome-depleted fetal bovine serum and chemically defined alternatives support upstream vesicle production. Contract manufacturers in India and South Korea are scaling media volume procurement as exosome engineering capacity expands.
- RNA Extraction Kits:Column-based and magnetic bead workflows isolate miRNA and mRNA cargo for sequencing pipelines. Oncology biomarker discovery programs at NIH-funded institutes sustain the largest consumable throughput.
Today's leader: Exosome Isolation Kits. Tomorrow's challenger: Exosome Characterization Instruments.
Application:
End-use maturity and funding concentration determine margin structures and customer support requirements across therapeutic and diagnostic development pathways.
- Cancer Diagnostics:Liquid biopsy development for early-stage tumor detection commands premium reagent pricing. Academic medical centers in Texas and New York are expanding core facility budgets for exosome-based oncology panels.
- Neurodegenerative Disease Research:CNS-derived vesicle analysis for Alzheimer's and Parkinson's biomarker discovery represents the application climbing fastest. Brain bank networks in the United Kingdom and Sweden are standardizing collection protocols for cross-study comparability.
- Cardiovascular Research:Cardiac-derived exosome profiling for myocardial injury assessment. Regenerative medicine institutes in Japan and Germany are establishing dedicated cardiovascular extracellular vesicle workflows.
- Drug Delivery Systems:Engineered exosome loading and targeting for therapeutic cargo transport. Biopharmaceutical startups in Massachusetts and California are building internal manufacturing capabilities rather than outsourcing.
- Biomarker Discovery:Unbiased proteomic and transcriptomic profiling of vesicle cargo across disease states. Population-scale cohort studies in Denmark and the Netherlands are driving demand for high-throughput isolation platforms.
Neurodegenerative Disease Research is gaining share fastest as funding priorities shift toward CNS indications. Cancer Diagnostics retains the largest absolute revenue base.
End User:
Procurement authority centralization and validation requirements create distinct sales cycle patterns across institutional customer types.
- Academic Research Institutes:Principal investigator-driven purchasing is yielding to core facility manager consolidation. Major university clusters in Boston, Heidelberg, and Singapore are favoring vendors with multi-year service contracts and integrated training programs.
- Biopharmaceutical Companies:Exosome engineering groups require clinical-grade reagents with ISO 13485 documentation. Process development teams in Switzerland and California are driving demand for scalable, GMP-compatible workflows.
- Clinical Laboratories:Diagnostic service providers need validated, high-throughput platforms for patient sample processing. Reference laboratories in Germany and the United States are piloting exosome-based liquid biopsy services.
- Contract Research Organizations:CDMOs serving exosome therapeutic developers require flexible, multi-client manufacturing capabilities. Exosome engineering specialists in India and South Korea are attracting international sponsor contracts.
- Government Research Bodies:NIH, MRC, and DFG-funded programs sustain foundational research demand. National extracellular vesicle consortiums in the United States and United Kingdom coordinate multi-site standardization efforts.
Biopharmaceutical Companies are expanding most quickly as therapeutic candidates advance toward clinical validation. Academic Research Institutes maintain the deepest installed base.
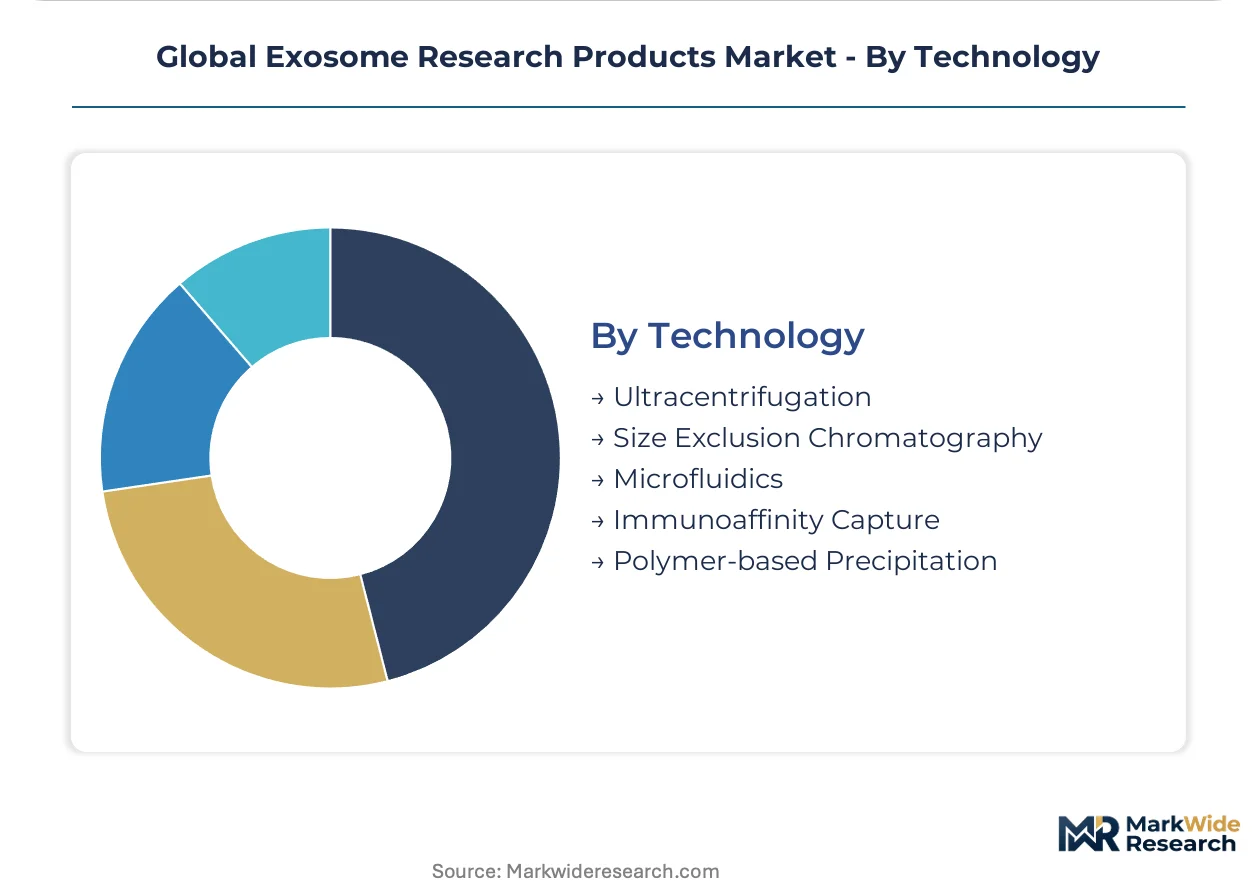
Technology:
Performance trade-offs between purity, yield, throughput, and surface marker integrity determine technology selection across research and manufacturing contexts.
- Ultracentrifugation:Differential density gradient separation remains the reference method with the largest installed base. Core facilities in established research clusters in California and Massachusetts maintain substantial rotor inventory despite longer processing times.
- Size Exclusion Chromatography:Gentler buffer conditions preserve functional surface epitopes for downstream assays. Stem cell research groups in Sweden and Singapore are displacing harsher protocols with SEC-based workflows.
- Microfluidics:Integrated fluidic circuits enable parallel processing with reduced sample volumes. High-throughput screening groups in Switzerland and the United States are adopting chip-based platforms for biofluid cohort analysis.
- Immunoaffinity Capture:Antibody-mediated selection isolates subpopulations expressing specific surface markers. Oncology research programs targeting tumor-derived vesicles are driving antibody reagent development partnerships.
- Polymer-based Precipitation:Cost-effective bulk isolation for preliminary screening applications. Resource-constrained laboratories in India and Brazil utilize precipitation kits for initial vesicle enrichment prior to downstream purification.
Microfluidics is climbing the fastest as biopharmaceutical manufacturing demands throughput and reproducibility. Ultracentrifugation retains the deepest equipment installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Exosome research products originated in academic laboratories clustered around NIH-funded institutes in the United States, with early commercialization emerging from reagent suppliers serving cell biology workflows in Massachusetts and California. European expansion followed through EMA-regulated biopharmaceutical corridors, while Asian manufacturing scale developed later through CDMO networks in India and South Korea.
United States
NIH extramural funding sustains the largest academic procurement base for isolation kits and characterization instruments. FDA draft guidance on extracellular vesicle therapeutics tightens validation requirements for clinical-grade reagent suppliers. Boston and San Diego bioclusters concentrate biopharmaceutical R&D investment in oncology and neurology applications.
Germany
EMA Advanced Therapy Medicinal Products framework accelerates clinical translation timelines for engineered exosome therapeutics. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force reformulation of membrane coating chemistries in spin column production. Heidelberg and Munich research universities consolidate core facility procurement around multi-year service contracts.
Japan
PMDA regenerative medicine designation creates expedited review pathways for exosome-derived therapeutic submissions. METI funding programs support microfluidics manufacturing scale-up for diagnostic platform integration. Kobe and Osaka bioclusters attract CRO and CDMO partnerships targeting clinical translation.
India
CDSCO streamlined biologics guidelines and PLI scheme incentives attract exosome engineering investment to contract research organizations. Central government biotechnology funding expands academic core facility budgets in Hyderabad and Bengaluru. Local media suppliers scale chemically defined alternatives to imported exosome-depleted serum.
Switzerland
Swissmedic quality system requirements align with ISO 13485 standards for clinical-grade reagent manufacturing. Precision instrument manufacturers in Basel and Zurich supply nanoparticle tracking analyzers with 21 CFR Part 11-compliant software. Biopharmaceutical quality control laboratories drive premium instrument procurement cycles.
Global Exosome Research Products Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory certification tiers, with clinical-grade ISO 13485 documentation commanding price multiples over research-use-only formulations. The vendor base stratifies into three archetypes: diversified life science conglomerates with chromatography and reagent portfolios, specialized antibody and protein reagent developers, and nucleic acid extraction workflow specialists. Consolidation pressure intensifies through multi-year core facility service contracts and integrated training programs that displace principal investigator-driven purchasing.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. anchors North American distribution through chromatography and reagent portfolios. Bio-Techne occupies a position within the specialized reagent developer tier, sustaining competitive intensity through antibody and protein development capabilities. QIAGEN exemplifies the nucleic acid extraction specialist archetype, dominating workflows that feed downstream exosome RNA analysis pipelines.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bio-Techne |
| QIAGEN |
| Lonza |
| Danaher Corporation |
| System Biosciences LLC |
| Hologic Inc. |
| Miltenyi Biotec |
| Takara Bio Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up reagent specialists have consolidated fragmented antibody and chromatography suppliers across Massachusetts and California, compressing procurement channels while hardening price discipline through multi-year core facility contracts. This ownership concentration amplifies pricing power for ISO 13485-certified formulations while squeezing margin structures for research-use-only kit manufacturers dependent on volatile agricultural chemical inputs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market by certification grade and after-sales service bundling. Premium tiers attach to clinical-grade reagents with FDA-recognized validation packages, while economy tiers serve preliminary screening workflows in resource-constrained laboratories. Pricing pressure stems from REACH Annex XVII compliance costs elevating European manufacturing expenses. Academic core facilities in Germany and Singapore exhibit highest price sensitivity, whereas biopharmaceutical quality control laboratories in Switzerland accept substantial premiums for 21 CFR Part 11-compliant instrumentation.
Supply Chain Analysis
High-purity sucrose and density gradient media supply rests on specialty chemical producers in Germany and Japan, with precision-machined titanium ultracentrifuge rotors anchoring in a limited German-Japanese supplier base. Exosome-depleted fetal bovine serum draws from Australian and South American serum processors, while chromatography resin production concentrates in Sweden and the United States. Single-source vulnerability in rotor manufacturing creates lead time exposure for replacement parts. Distribution runs through authorized life science distributors serving academic core facilities and direct sales teams penetrating biopharmaceutical quality control laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with FDA draft guidance on extracellular vesicle therapeutics accelerating validation requirements that pull demand toward clinical-grade product tiers.
For Market Incumbents: Cement multi-year service contracts with integrated training programs at consolidating academic core facilities in Boston and Heidelberg. Deepen backward integration into chromatography resin manufacturing to offset REACH-driven reformulation costs. Defend against microfluidics-based workflow displacement by embedding ultracentrifugation expertise into protocol validation support. For New Entrants and Emerging Players: Enter via point-of-care diagnostic integration partnerships, targeting lateral flow biosensor platforms for decentralized exosome surface marker detection. White-space concentrates in India contract research expansion, where CDSCO streamlined biologics guidelines attract exosome engineering investment to Hyderabad clusters. Pursue antibody reagent co-development agreements with oncology research programs seeking tumor-derived vesicle subpopulation isolation. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized antibody developers lacking ISO 13485 certification infrastructure. Long-term viability hinges on regulatory science capabilities bridging research-use and clinical-grade product transitions. Watch Japan PMDA regenerative medicine designation submissions as inflection indicator for engineered exosome therapeutic commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality system documentation unlocks clinical-grade reagent pricing multiples and EMA-regulated market access. |
| Microfluidics Platform Integration | Chip-based isolation workflows displace ultracentrifugation in Swiss and United States biopharmaceutical screening applications. |
| REACH-Compliant Chemistry Reformulation | Fluorine-free membrane coatings preserve European manufacturing access amid Annex XVII substance restrictions. |
| India CDMO Partnership Expansion | Hyderabad and Bengaluru clusters attract international sponsor contracts through PLI scheme incentives. |
| Core Facility Consolidation Capture | Multi-year service contracts at centralized procurement authorities in Singapore and Heidelberg concentrate purchasing power. |
Research Methodology
Bottom-up academic and biopharmaceutical procurement modeling reconciled against top-down reagent supplier shipment tracking forms the analytical core of this study. Primary interviews with core facility managers, regulatory affairs leads at reagent manufacturers, biopharmaceutical process development scientists, and ISO 13485 quality system auditors combined with secondary validation from FDA guidance documents, EMA advanced therapy submissions, NIH RePORTER funding databases, and REACH Annex XVII regulatory filings.
Historical trendline analysis of instrument installation records and consumable procurement cycles established baseline penetration patterns across the projection horizon. Segmentation modeling incorporated product type, application, end user, technology, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves calibrated against funding concentration shifts and clinical translation pipeline maturation, with particular weighting applied to NIH extramural award trajectories and EMA ATMP classification pathway utilization rates.
Inputs from primary fieldwork and published regulatory guidance were available through the study window; gaps in real-time biopharmaceutical R&D budget allocation data introduce uncertainty bands around near-term instrument procurement forecasts. Forecasts reflect assumptions regarding FDA guidance finalization timelines and EMA quality system requirement evolution. Material deviation in PMDA regenerative medicine designation submission volumes or REACH enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Europe Serine Proteases Market
Biomedical Technology
Exonucleases Market
Biomedical Technology
3D Cell Culture Market
Biomedical Technology
Fluorescence in-Situ Hybridization Probe Market
Biomedical Technology
DNA Forensics Market
Biomedical Technology
Nucleic Acid Isolation, Quantitation, and Purification Market
Biomedical Technology
Global Cell Harvesting Market
Biomedical Technology
Southern Blotting Market
Biomedical Technology
ST2 Biomarker Market
Biomedical Technology
In-Vitro Transcription Templates Market
Biomedical Technology
Global Ligation Market
Biomedical Technology
Asia-Pacific Digital PCR Market
Biomedical Technology
Global Peptide Microarray Market
Biomedical Technology
America Cell Counting Market
Biomedical Technology
Strand Displacement Amplicon (SDA) Market
Biomedical Technology
Single Cell Multiomics Market