
 Rat and Mouse Model Market | 2026-2036
Rat and Mouse Model Market Size, Share, and Industry Trends Forecast 2026-2036
Rat and Mouse Model Market Intelligence
Multi-source contracting for genetically engineered models is pivoting toward hybrid arrangements that blend Charles River Laboratories' commercial scale with Taconic Biosciences' specialized pathogen-free capabilities. Charles River leverages its North American breeding infrastructure to dominate high-volume toxicology contracts. The Jackson Laboratory anchors academic and government research demand through its repository of over 12,000 standardized inbred and mutant strains. Cyagen competes on CRISPR-edited custom model turnaround, differentiating through rapid germline transmission timelines that compress study initiation schedules.
Rat and mouse models constitute purpose-bred rodents standardized for genetic uniformity, pathogen status, and physiological parameters to serve as experimental surrogates in biomedical investigation; breeding programs maintain specific microbiome profiles and genetic drift thresholds below 0.1% per generation to preserve experimental reproducibility across multi-site trials. Genetically engineered models command premium positioning due to CRISPR proliferation and humanized immune system complexity, while inbred strains retain volume leadership in legacy toxicology protocols. Drug discovery applications absorb the fastest-growing share of model output as biopharma pipelines shift toward immuno-oncology and cell therapy modalities requiring humanized host platforms.
FDA guidance on Good Laboratory Practice and EMA Directive 2010/63/EU on animal research harmonization jointly elevate barrier-facility standards and audit documentation burdens for international suppliers. USDA Animal Welfare Act inspection protocols and AAALAC accreditation requirements further segment market access between accredited commercial vendors and non-compliant regional breeders. Stakeholders must weigh captive breeding investments against outsourced model sourcing as regulatory divergence between FDA and EMA reporting standards intensifies qualification complexity for multinational preclinical programs.
Market Dynamics
Pharmaceutical companies are dismantling captive breeding infrastructure and consolidating outsourced preclinical testing contracts with accredited commercial vendors, compressing supplier qualification timelines while elevating barrier-facility standards.
Growth Catalysts
- Immuno-oncology pipeline expansion:Biopharma developers require humanized immune system models for cell therapy validation, pulling specialized germline-edited strains into toxicology workflows.
- EMA Directive 2010/63/EU harmonization:Standardized animal welfare documentation across European member states reduces multi-site trial friction and accelerates cross-border model transfers.
- CRISPR germline transmission advances:Rapid custom model generation compresses study initiation schedules from months to weeks for targeted gene knockout programs.
Market Restraints
- Genetic drift containment costs:Maintaining sub-0.1% per generation drift thresholds demands continuous genotyping and cryopreservation infrastructure that elevates per-unit model pricing.
- USDA Animal Welfare Act inspection density:Unannounced facility audits and veterinary staffing mandates impose operational overhead that marginalizes non-accredited regional breeders.
- In vitro organoid maturation:Liver and intestinal organoid platforms are capturing share in absorption-distribution-metabolism-excretion screening, constraining rodent model volume in early-phase pharmacokinetics.
Strategic Opportunities
- India CDSCO preclinical outsourcing:Domestic contract research organizations are building barrier-capable breeding facilities to serve multinational sponsors seeking cost-advantaged toxicology execution.
- Microbiome-standardized gnotobiotic models:Defined flora consortia enable reproducible immunology outcomes for inflammatory disease and metabolic syndrome research applications.
- AAALAC accreditation as market access tool:Voluntary international accreditation programs differentiate commercial vendors in government and academic procurement where funding agencies mandate documented welfare compliance.
Industry Challenges
- CRISPR off-target detection expertise:Whole-genome sequencing validation for edited lines requires bioinformatics capabilities that outpace veterinary pathology training pipelines.
- FDA-EMA reporting standard divergence:Multinational sponsors face redundant documentation burdens when study designs must satisfy non-aligned Good Laboratory Practice interpretation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rat and Mouse Model Market |
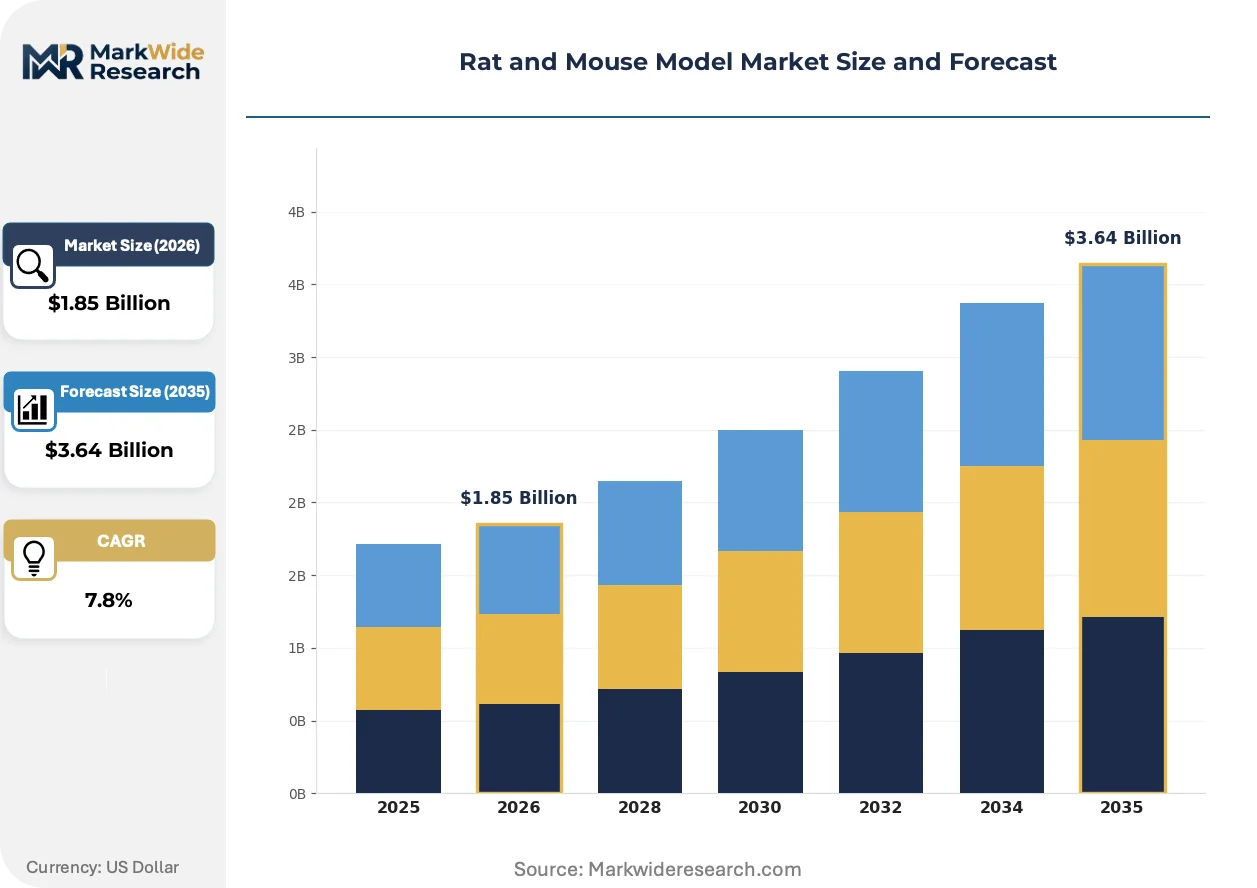
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Model Type: Inbred Strains, Outbred Strains, Hybrid Strains, Genetically Engineered Models Application: Toxicology Testing, Drug Discovery, Genetic Research, Preclinical Studies End User: Pharmaceutical Companies, Academic Institutions, Contract Research Organizations, Biotechnology Firms Age Group: Neonatal, Juvenile, Adult, Senescent |
| Companies Covered | Charles River Laboratories, The Jackson Laboratory, Taconic Biosciences, Inc., genOway, Inotiv, Janvier Labs, Cyagen, Biomedical Research Models (Biomere), Hera Biolabs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rat and Mouse Model Market Strategic Shifts & Innovations
Preclinical model supply chains are fragmenting across specialized competencies, with speed-to-study and genetic precision emerging as decisive procurement criteria over historical volume discounts.
CRISPR-Cas9 germline editing is overtaking embryonic stem cell-based targeting for complex allele construction. Large-molecule developers in Boston-Cambridge and San Diego biotech clusters now specify 8-12 week custom model delivery as standard procurement terms. This acceleration is compressing competitive differentiation timelines and forcing repository-based suppliers to expand rapid-turnaround service tiers.
REACH chemical registration requirements in Europe are elevating demand for rat models in reproductive toxicology endpoints. The extended one-generation and two-generation study protocols mandated under Annexes VIII-XIII are consuming specific-pathogen-free Sprague-Dawley and Wistar colonies at elevated rates. Contract research organizations in Germany and the Netherlands are expanding dedicated breeding capacity to capture this regulatory-driven volume.
Academic and government laboratories are unbundling after-sales technical support from model procurement, instead purchasing direct from repositories and contracting independent veterinary pathology consultancies. This disintermediation is eroding traditional full-service supplier margins in the United States, where NIH funding pressures accelerate unit-cost scrutiny. Principal investigators now prioritize strain documentation depth over bundled husbandry training.
Rat and Mouse Model Market Segmentation
Procurement patterns in the rat and mouse model market diverge sharply by experimental objective, genetic specification, and regulatory compliance burden. Buyers select segments based on reproducibility requirements, turnaround constraints, and the complexity of human disease mimicry needed for specific therapeutic modalities.
Model Type:
Cost tiers separate buyers seeking standardized legacy strains from those commissioning complex germline modifications with multi-month validation cycles.
- Genetically Engineered Models:CRISPR-edited lines with targeted knockouts, knock-ins, or humanized loci command premium positioning due to germline transmission complexity and intellectual property licensing. Demand concentrates in Boston-Cambridge and San Diego immuno-oncology clusters where cell therapy developers require humanized immune system hosts for CAR-T validation.
- Inbred Strains:Decades of brother-sister mating produce 99% genetic uniformity across generations, making C57BL/6 and BALB/c lines the workhorse for toxicology protocols and baseline immunology studies. Volume leadership persists in legacy pharmaceutical safety assessment programs where regulatory familiarity outweighs genetic sophistication.
- Outbred Strains:Heterogeneous stocks like Sprague-Dawley rats maintain genetic diversity that mirrors human population variation in safety pharmacology screens.
- Hybrid Strains:F1 crosses combine vigor and uniformity for specific immunological applications requiring defined histocompatibility.
Volume sits with Inbred Strains; growth tilts toward Genetically Engineered Models.
Application:
Study phase determines model specification, with early discovery favoring speed and late-stage development demanding regulatory-compliant documentation depth.
- Drug Discovery:Target identification and lead optimization consume humanized models and rapid-turnaround CRISPR lines for mechanism-of-action studies. Application expansion is accelerating most quickly in cell therapy and gene therapy pipelines where immunodeficient host platforms enable xenograft engraftment.
- Toxicology Testing:GLP-compliant safety assessment mandates specific-pathogen-free status, certified genetic backgrounds, and complete health monitoring documentation. FDA and EMA harmonization pressures are elevating barrier-facility standards for reproductive and carcinogenicity endpoints.
- Preclinical Studies:Efficacy modeling bridges discovery and IND-enabling work with disease-specific strains.
- Genetic Research:Academic inquiry into gene function drives repository demand for mutant archives and embryonic stem cell resources.
Revenue concentration favors Toxicology Testing; margin expansion tracks Drug Discovery.
End User:
Organizational scale and funding source shape procurement sophistication, from multinational vendor consolidation to principal investigator direct purchasing.
- Pharmaceutical Companies:Dismantling captive breeding infrastructure and consolidating outsourced contracts with Charles River Laboratories and Taconic Biosciences for accredited supply security. Fastest volume gains as sponsor companies displace in-house colonies with vendor-managed inventory programs.
- Contract Research Organizations:Toxicology service providers in Germany, the Netherlands, and India maintain dedicated breeding capacity to capture regulatory-driven study volume.
- Academic Institutions:NIH-funded laboratories unbundle after-sales support from procurement, purchasing direct from The Jackson Laboratory repository.
- Biotechnology Firms:Venture-backed developers in Cambridge and San Diego specify 8-12 week custom model delivery as standard procurement terms.
Procurement volume aggregates at Pharmaceutical Companies; flexibility requirements favor Biotechnology Firms.
Age Group:
Developmental stage selection aligns with disease model temporality and pharmacokinetic maturation patterns.
- Adult:Sexually mature animals dominate toxicology and efficacy studies where metabolic enzyme expression stabilizes. Standardization in 6-8 week cohorts enables cross-study comparability for IND submissions.
- Juvenile:Post-weaning models address pediatric indication requirements and developmental pharmacology questions.
- Neonatal:Early-life interventions study developmental origins of disease and perinatal therapeutic windows.
- Senescent:Aged colonies support geroscience and late-life intervention studies with documented health span metrics.
Study volume concentrates in Adult; specialized protocol growth favors Senescent.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States biotech clusters in Boston-Cambridge and San Diego absorb disproportionate volumes of specialized immunodeficient strains, driving regional procurement concentration for humanized model platforms.
United States
FDA Animal Welfare Act amendments tighten sourcing compliance across supplier networks, elevating barrier-facility documentation burdens for preclinical programs. Pharmaceutical sponsors dismantle captive breeding infrastructure and consolidate outsourced contracts with Charles River Laboratories and Taconic Biosciences. Boston-Cambridge and San Diego biotech clusters specify 8-12 week custom model delivery as standard procurement terms for cell therapy validation.
Germany
EMA Directive 2010/63/EU harmonization reduces multi-site trial friction and accelerates cross-border model transfers for toxicology service providers. REACH chemical registration requirements elevate demand for rat models in reproductive toxicology endpoints under Annexes VIII-XIII. Contract research organizations in Germany and the Netherlands expand dedicated breeding capacity to capture regulatory-driven study volume.
China
Domestic biopharma pipeline expansion pulls specialized germline-edited strains into toxicology workflows for immuno-oncology development. NMPA Good Laboratory Practice standards elevate audit documentation requirements for international sponsors conducting multi-regional trials. Shanghai and Beijing biotech clusters drive demand for CRISPR-edited custom models with compressed turnaround timelines.
United Kingdom
Academic and government laboratories unbundle after-sales technical support from model procurement, purchasing direct from The Jackson Laboratory repository. Home Office regulations on genetically engineered organism containment tighten facility licensing for breeding programs. Oxford and Cambridge research institutions prioritize strain documentation depth over bundled husbandry training to manage NIH funding pressures.
India
CDSCO preclinical outsourcing opportunities attract multinational sponsors seeking cost-advantaged toxicology execution in barrier-capable breeding facilities. Domestic contract research organizations build specialized pathogen-free infrastructure to serve international pharmaceutical sponsors. Hyderabad and Bangalore biotech corridors develop captive breeding alternatives for regional drug discovery programs.
Rat and Mouse Model Market Key Industry Players
Capacity expansion dominates the current landscape as repository-based suppliers build rapid-turnaround service tiers to match biotechnology firm procurement timelines. The vendor base separates into three tiers: commercial-scale breeders with North American infrastructure, specialized pathogen-free capability providers, and rapid-turnaround CRISPR editing specialists. Strategic archetypes include accredited full-service vendors, repository-based academic suppliers, and custom germline editing boutiques. M&A consolidation and geographic capacity expansion represent the dominant competitive moves as sponsors dismantle captive breeding programs.
Within the accredited full-service tier, Charles River Laboratories leverages commercial scale for high-volume toxicology contracts, while Taconic Biosciences occupies a position specializing in pathogen-free capabilities. The Jackson Laboratory anchors academic and government research demand through repository depth. Cyagen exemplifies the rapid-turnaround specialist archetype, competing on CRISPR-edited custom model delivery timelines that compress study initiation schedules for biotechnology sponsors.
| Leading Market Players |
|---|
| Charles River Laboratories |
| The Jackson Laboratory |
| Taconic Biosciences, Inc. |
| genOway |
| Inotiv |
| Janvier Labs |
| Cyagen |
| Biomedical Research Models (Biomere) |
| Hera Biolabs |
| Others |
Cost & Logistics Intelligence
CRISPR germline transmission standardization is compressing custom model generation timelines from months to weeks while simultaneously concentrating production economics among vendors with validated bioinformatics pipelines and barrier-capable breeding infrastructure. This technological shift elevates fixed-cost thresholds for entry while rewarding incumbents with cryopreservation networks and AAALAC-accredited facilities.
Pricing Analysis
After-sales technical support unbundling from core model procurement is fragmenting traditional full-service pricing architectures. Three-tier pricing structure across premium germline-edited lines, standard inbred repositories, and economy outbred toxicology strains dominates transactional volume. Price differentiation rests on AAALAC accreditation tier and genetic documentation depth rather than base animal unit cost. Cost compression in standard inbred strains is intensifying because NIH funding pressures accelerate unit-cost scrutiny among academic buyers. Biotechnology firms in Boston-Cambridge and San Diego demonstrate lowest price sensitivity due to speed-to-study imperatives.
Supply Chain Analysis
Dual-sourcing mandates from pharmaceutical sponsors require qualified backup vendors for critical immunodeficient strains, elevating supplier qualification overhead. Geographic supply concentration centers on the United States, Germany, and China as the dominant breeding jurisdictions. Raw material dependencies include specific-pathogen-free feed formulations, sentinel animal colonies for health monitoring, and cryopreservation infrastructure for genetic drift containment. Single-source vulnerability persists for specialized humanized immune system models where germline transmission expertise concentrates. Distribution runs through vendor-managed inventory programs with direct-to-facility delivery for GLP-compliant toxicology sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rat and mouse model market is transitioning from embryonic stem cell-based targeting to CRISPR-Cas9 germline editing as the dominant production methodology, compressing competitive differentiation timelines and forcing repository-based suppliers to build rapid-turnaround service tiers.
For Market Incumbents: Deploy cryopreservation network expansion to defend germline integrity guarantees against emerging CRISPR boutiques. Backward integration into veterinary pathology consultancies captures margin erosion from academic unbundling trends. Charles River Laboratories and Taconic Biosciences should consolidate barrier-facility capacity in Boston-Cambridge and San Diego to anchor cell therapy developer contracts. For New Entrants and Emerging Players: Digital repository platforms enable direct-to-principal-investor sales channels bypassing traditional distributor markups. White-space concentration sits with microbiome-standardized gnotobiotic models for inflammatory disease applications, where defined flora consortia command premium positioning. India CDSCO preclinical outsourcing corridors offer geographic entry with cost-advantaged barrier-capable infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by contract research organizations seeking captive breeding security. Long-term viability hinges on CRISPR off-target detection bioinformatics capabilities that outpace veterinary pathology training pipelines. The signal to watch is FDA-EMA Good Laboratory Practice harmonization progress, which would eliminate redundant documentation burdens and accelerate multinational sponsor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| AAALAC Accreditation Investment | Unlocks government and academic procurement where funding agencies mandate documented welfare compliance. |
| Cryopreservation Infrastructure Expansion | Preserves genetic drift thresholds below 0.1% per generation for multi-site trial reproducibility. |
| CRISPR Germline Service Tier Launch | Compresses custom model delivery to 8-12 week timelines demanded by Boston-Cambridge biotechnology sponsors. |
| Microbiome-Standardized Gnotobiotic Colony Development | Enables reproducible immunology outcomes for metabolic syndrome and inflammatory disease research applications. |
| India Barrier-Facility Capacity Buildout | Captures CDSCO preclinical outsourcing volume from multinational sponsors seeking cost-advantaged toxicology execution. |
Research Approach
FDA guidance documents, EMA Directive 2010/63/EU implementation reports, and USDA Animal Welfare Act inspection records formed the secondary backbone for regulatory framework validation. Primary interviews with preclinical operations directors, AAALAC accreditation specialists, vendor procurement managers, and academic principal investigators combined with secondary source triangulation. Bottom-up model demand estimates from toxicology study volume and top-down market sizing from breeder capacity disclosures were reconciled across the analysis window.
Historical trendline analysis of pharmaceutical R&D outsourcing ratios and captive breeding program dismantlement patterns anchored projection assumptions. Segmentation modeling incorporated model type, application, end-user organizational scale, and regional regulatory cluster dimensions. CAGRs were derived from slope analysis of breeder capacity expansion announcements and sponsor contract consolidation trends. Forecast inputs included immuno-oncology pipeline progression and REACH chemical registration volume for reproductive toxicology endpoints.
The model holds under continued FDA-EMA regulatory divergence; deviation in harmonization acceleration would shift sponsor qualification timelines and vendor consolidation pace materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
In-Vitro Transcription Templates Market
Biomedical Technology
Global Primary Cell Culture Market
Biomedical Technology
Europe Biobanks Market
Biomedical Technology
North America Proteomics Market
Biomedical Technology
Blood Brain Barrier Technologies Market
Biomedical Technology
DNA Synthesis Market
Biomedical Technology
Nucleic Acid Aptamers Market
Biomedical Technology
Bioadhesive Microspheres Market
Biomedical Technology
Immunoprecipitation Market
Biomedical Technology
Bioprocess Technology Market
Biomedical Technology
High-End Cellomics Market
Biomedical Technology
Global Peptide Microarray Market
Biomedical Technology
Latin America Digital Biology Market
Biomedical Technology
Reverse Transcriptase Enzymes Market
Biomedical Technology
Global Serological Transplant Diagnostics Market
Biomedical Technology
Global RNA Analysis Market