
 Uranium Enrichment Market | 2026-2036
Uranium Enrichment Market Size, Share, and Industry Trends Forecast 2026-2036
Uranium Enrichment Market Outlook
REACH is broadening the cost-of-entry calculus for European enrichment suppliers by imposing stricter chemical handling and waste accountability rules on conversion and enrichment facilities. Centrus Energy Corp. leverages its American Centrifuge technology to sustain domestic production capacity in the United States. Cameco Corp. anchors the front end of the fuel cycle with integrated mining and conversion operations. Westinghouse Electric Company competes through its fuel fabrication and reactor services ecosystem.
Uranium enrichment is the physical process of increasing the concentration of the fissile isotope uranium-235 from its natural abundance of 0.7% to levels between 3% and 5% for light water reactor fuel, or up to 20% for research reactors, using gaseous uranium hexafluoride as the process medium. Gas centrifugation dominates installed capacity due to superior energy efficiency compared with legacy gas diffusion plants, while laser enrichment represents the fastest-growing technology category as SILEX and molecular laser isotope separation methods approach commercial scale. Nuclear power generation commands the largest application share, though defense applications concentrate the highest margin pools due to stringent security and certification requirements.
The US Nuclear Regulatory Commission governs enrichment plant licensing and material control, while the International Atomic Energy Agency administers safeguards verification that conditions market access for non-weapon states. Euratom Supply Agency oversight shapes procurement patterns across European Union member states by mandating diversification of fuel sources. Stakeholders must monitor how emerging national security screening of foreign investment in enrichment infrastructure reshapes partnership structures and technology transfer rules.
Market Dynamics
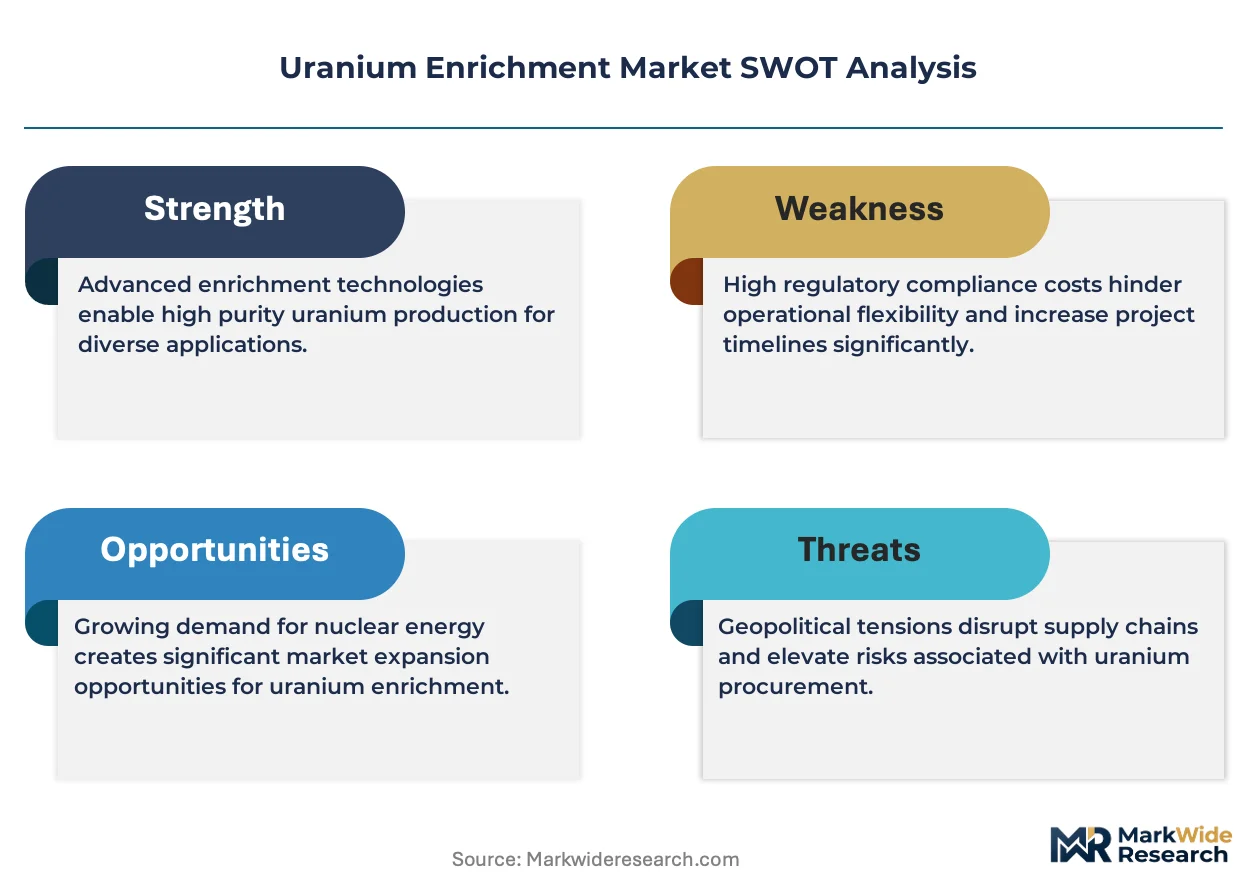
Gas centrifuge capacity concentration in Russia and Europe creates supply vulnerability as utilities diversify sourcing. The US Inflation Reduction Act is redirecting capital toward domestic enrichment infrastructure, fragmenting previously integrated procurement patterns.
Growth Catalysts
- Reactor buildouts in China:State-owned utilities are contracting for multi-year fuel supplies ahead of grid connection timelines, pulling forward enrichment demand.
- The US Inflation Reduction Act:Tax credits and loan guarantees for domestic fuel cycle investments are accelerating centrifuge plant development.
- High-assay low-enriched uranium (HALEU):Advanced reactor designs require enrichment levels above 5% U-235, opening premium service tiers.
Market Restraints
- SWU price volatility:Separative work unit contracts index to natural uranium feedstock costs, squeezing margin predictability for toll enrichment providers.
- Russian supply dominance:State nuclear corporation Rosatom controls roughly one-third of global enrichment capacity, creating concentration risk for Western utilities.
- Laser enrichment technical barriers:SILEX and molecular laser isotope separation methods face unresolved energy efficiency thresholds at commercial scale.
Strategic Opportunities
- Undercontracted Southeast Asian markets:Vietnam, Indonesia, and the Philippines are advancing nuclear power programs without established fuel supply relationships.
- HALEU production infrastructure:First-mover investment in enrichment cascades capable of 19.75% U-235 output captures advanced reactor fuel demand.
- EU Green Deal nuclear taxonomy:Recognition of nuclear power as sustainable finance-eligible is unlocking institutional capital for European enrichment capacity expansion.
Industry Challenges
- Centrifuge rotor manufacturing bottlenecks:Carbon fiber composite production for high-speed rotors requires specialized aerospace-grade suppliers with limited qualification.
- IAEA safeguards integration:New enrichment facilities face 18-36 month certification timelines for material accountancy system approval before commercial operation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uranium Enrichment Market |
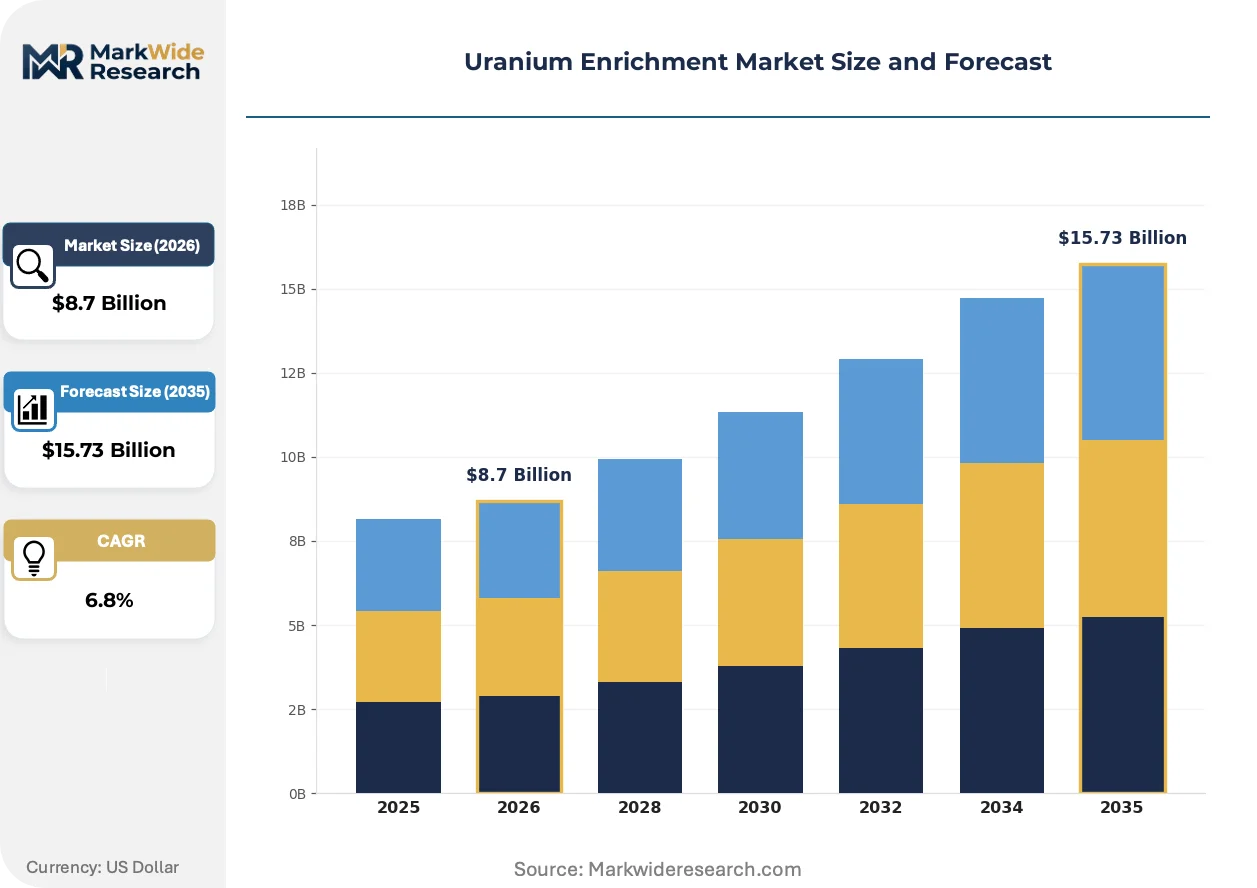
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Gas Diffusion, Gas Centrifugation, Laser Enrichment, Electromagnetic Separation Application: Nuclear Power Generation, Research Reactors, Isotope Production, Defense Applications End User: Utilities, Government Agencies, Research Institutions, Industrial Users Service Type: Consulting, Operational Support, Decommissioning, Technical Services |
| Companies Covered | NANO Nuclear Energy, Westinghouse Electric Company, Centrus Energy Corp., Global Laser Enrichment, TerraPower, Uranium Energy Corp., LIS Technologies, Brookfield Corporation, Cameco Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uranium Enrichment Market Strategic Shifts
Technology substitution and regulatory fragmentation are compressing legacy plant economics while opening niche service tiers. Three developments are restructuring competitive positioning.
Advanced centrifuge designs are integrating magnetic bearing systems and composite rotor materials to achieve separative work outputs per machine that double previous generation performance. European and Asian utilities are specifying these machines in new-build tenders to minimize electricity consumption per SWU. The technology is integrating modular plant architectures that reduce construction timelines and permit incremental capacity scaling.
REACH chemical handling amendments are imposing extended producer responsibility on uranium conversion and enrichment waste streams across European Union member states. Facilities must now account for fluorine compound recovery and decommissioning liabilities across full asset lifecycles. German and French conversion plants are responding by retrofitting closed-loop fluorine recycling systems ahead of compliance deadlines.
Long-term contracting structures are displacing spot market purchases as utilities seek supply security amid geopolitical fragmentation. Asian state-owned buyers are negotiating 10-15 year offtake agreements directly with enrichment providers, bypassing traditional trader intermediaries. This pattern is most visible in China and India, where reactor fleet expansion outpaces domestic fuel cycle capacity.
Uranium Enrichment Market Segmentation
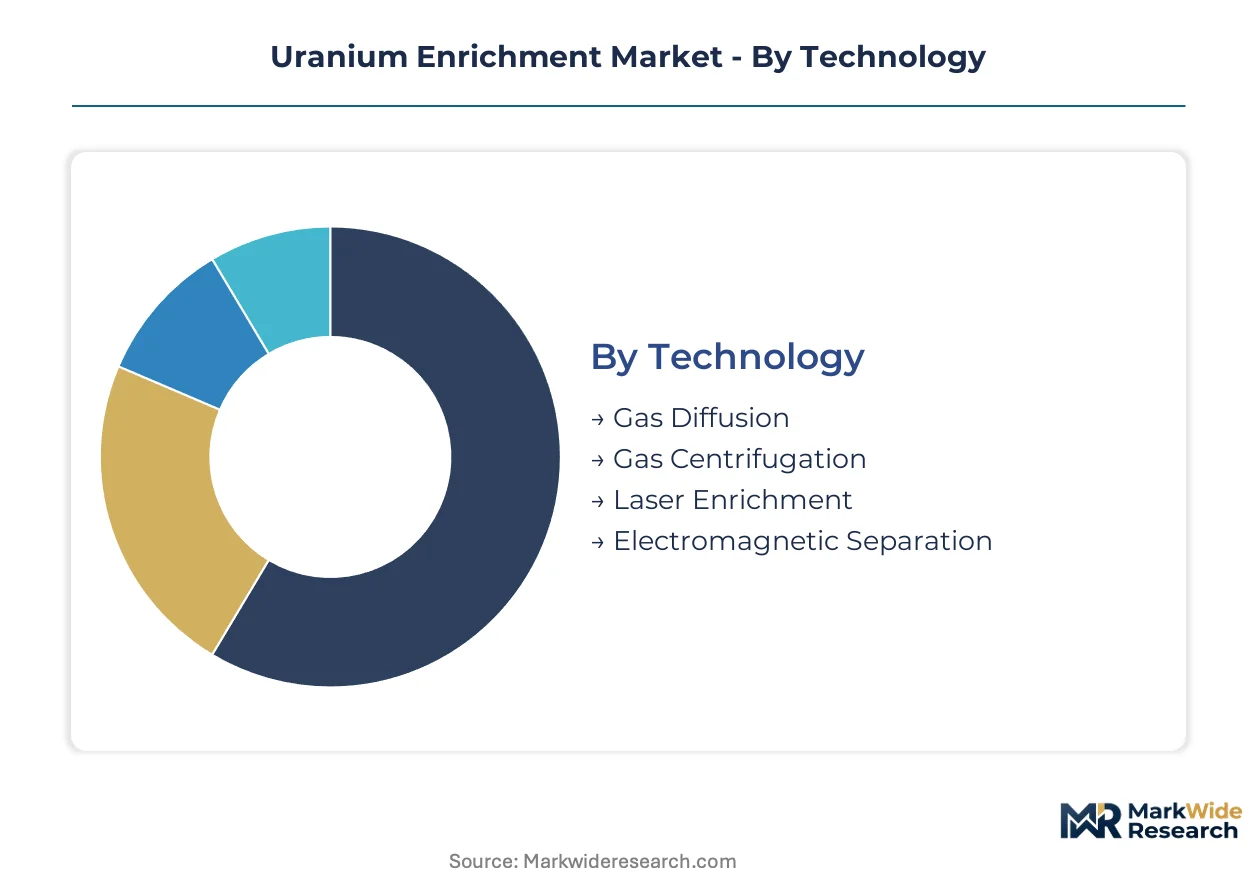
Enrichment service procurement varies sharply by technology maturity and regulatory exposure. Capital requirements cascade differently across centrifuge cascades versus laser systems, reshaping how utilities structure long-term contracting.
Technology:
Gas centrifugation demands the heaviest upfront investment due to precision manufacturing of carbon fiber rotors and cascade infrastructure. Laser enrichment requires comparable facility capital but spreads differently across R&D amortization and specialized laser arrays.
- Gas Centrifugation:Rotating uranium hexafluoride gas at supersonic speeds exploits minute mass differences between U-235 and U-238 isotopes. Chinese utilities are specifying advanced machines with magnetic bearing systems to reduce electricity consumption per separative work unit. European plants face retrofit pressure from REACH fluorine compound recovery mandates.
- Laser Enrichment:Molecular laser isotope separation and SILEX methods use tuned lasers to selectively excite U-235 atoms for electromagnetic extraction. Australian and US developers are advancing pilot facilities toward commercial scale, targeting HALEU production premiums. Energy efficiency thresholds remain unresolved at industrial throughput.
- Gas Diffusion:Legacy porous membrane technology consumes substantially more electricity per SWU than centrifuge alternatives.
- Electromagnetic Separation:Calutron and plasma separation methods serve specialized defense and research applications with limited commercial deployment.
Most installed capacity flows through gas centrifugation. Expansion is steepest in laser enrichment.
Application:
Revenue concentration tilts toward segments with certification barriers and security clearance requirements rather than pure volume throughput.
- Nuclear Power Generation:Light water reactor fuel requires 3-5% U-235 enrichment levels, representing the volume base of commercial enrichment services. Chinese state-owned utilities are contracting multi-year fuel supplies ahead of reactor grid connections. The US Inflation Reduction Act is redirecting procurement toward domestic enrichment providers.
- Defense Applications:Naval reactor fuel and weapons-grade material demand stringent security protocols and dedicated facility certification. Highly enriched uranium above 90% U-235 commands premium pricing tiers due to facility security investment and limited supplier qualification.
- Research Reactors:High-assay low-enriched uranium at 19.75% U-235 serves medical isotope production and materials testing.
- Isotope Production:Stable and radioactive isotopes for medical and industrial applications require specialized enrichment cascades with dedicated material accountancy.
Defense applications capture the highest margins per SWU. Nuclear power generation absorbs the greatest absolute throughput.
End User:
Procurement sophistication divides between state-backed buyers with sovereign credit guarantees and private utilities managing merchant power exposure.
- Utilities:State-owned nuclear operators in China and India negotiate direct long-term offtake agreements, bypassing traditional trader intermediaries. Merchant utilities in deregulated markets face SWU price volatility indexed to natural uranium feedstock costs.
- Government Agencies:National strategic stockpile managers and naval propulsion programs require dedicated enrichment capacity with security-cleared personnel.
- Research Institutions:Universities and national laboratories contract for small-batch HALEU and specialized isotope enrichment.
- Industrial Users:Radiography and process control applications source depleted uranium and trace isotopes through secondary suppliers.
Utilities dominate contracted volume. Government agencies concentrate the most security-intensive demand.
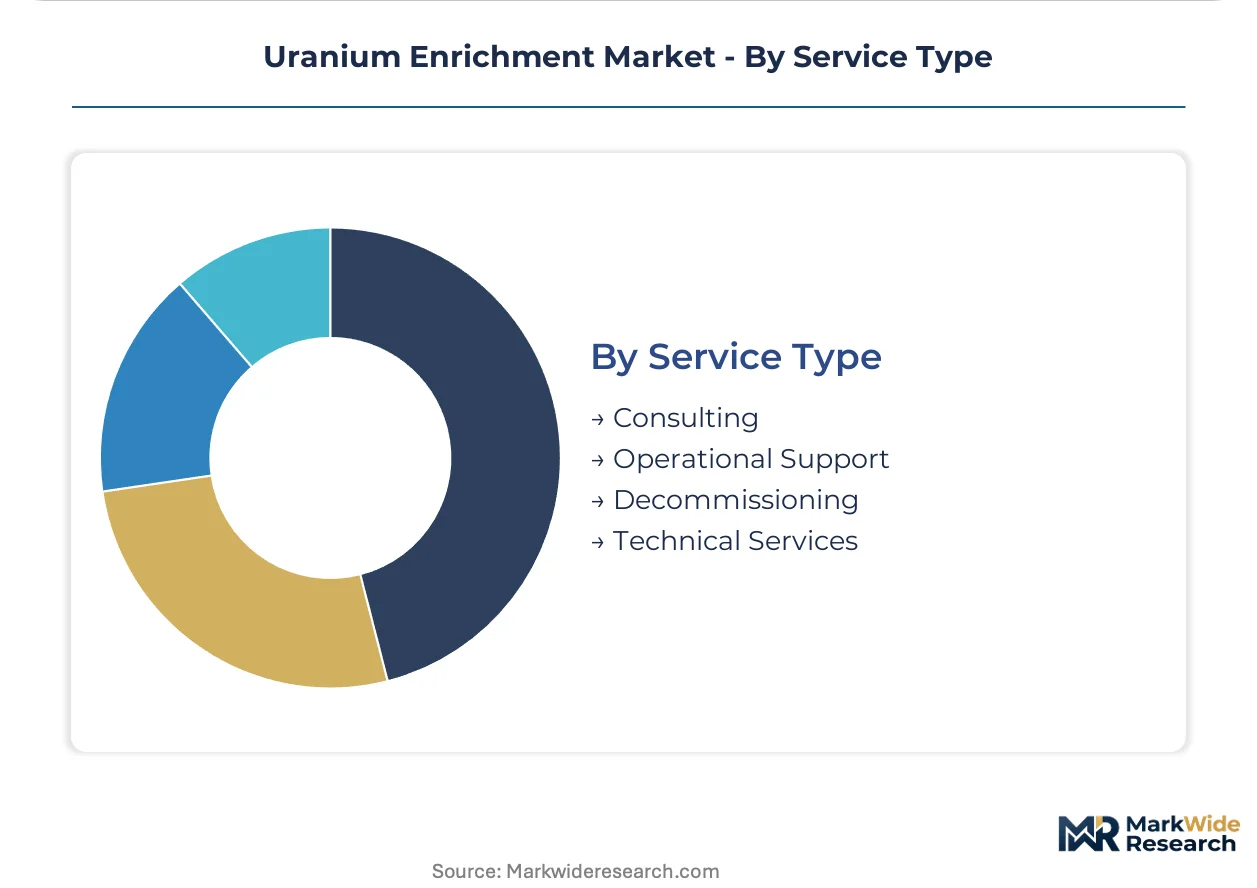
Service Type:
Value capture shifts from commodity SWU tolling toward technical advisory and liability management as decommissioning obligations mature.
- Operational Support:Cascade optimization and maintenance contracts extend facility lifecycles while reducing unplanned outage risk. European enrichment plants are procuring predictive analytics services to manage fluorine compound handling under REACH extended producer responsibility rules.
- Decommissioning:Facility closure and waste liability management services are expanding as first-generation centrifuge plants approach end-of-design-life. German and French operators are prefunding decommissioning trusts ahead of regulatory deadlines.
- Consulting:Regulatory licensing and safeguards integration advisory supports new facility development.
- Technical Services:Material accountancy system design and IAEA safeguards implementation assistance conditions market access for non-weapon states.
Operational support absorbs the largest service revenue share. Decommissioning is climbing fastest as legacy capacity ages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized nuclear engineering talent concentrates in government laboratories and centrifuge manufacturing clusters across five countries driving enrichment capacity decisions.
United States
The US Inflation Reduction Act is channeling investment toward domestic fuel cycle capabilities as utilities reduce dependence on foreign enrichment. The Nuclear Regulatory Commission governs enrichment plant licensing and material control, creating compliance benchmarks for new facility development. Oak Ridge National Laboratory in Tennessee anchors advanced centrifuge research programs.
China
State-owned utilities are contracting for multi-year fuel supplies ahead of grid connection timelines, pulling forward enrichment demand. The country's nuclear regulator mandates technology transfer requirements for foreign joint ventures. Lanzhou and Hainan host expanding centrifuge cascades serving reactor buildouts outpacing global averages.
Russia
State nuclear corporation Rosatom controls roughly one-third of global enrichment capacity, creating concentration risk for Western utilities. The country's strategic export controls shape procurement patterns across Eastern European and Central Asian markets. Novouralsk and Seversk house legacy diffusion and modern centrifuge facilities.
France
Euratom Supply Agency oversight mandates diversification of fuel sources across European Union member states. REACH chemical handling amendments impose extended producer responsibility on uranium conversion and enrichment waste streams. The Tricastin nuclear site in Provence-Alpes-Côte d'Azur operates centrifuge cascades under EU safeguards verification.
United Kingdom
Merchant utilities in deregulated markets face SWU price volatility indexed to natural uranium feedstock costs. The Office for Nuclear Regulation licenses enrichment activities under post-Brexit safeguards arrangements. Springfields in Lancashire remains a conversion and fuel fabrication hub serving domestic and export contracts.
Uranium Enrichment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across technology generations and service tiers. The vendor base spans state-backed nuclear corporations, publicly traded fuel cycle companies, and venture-backed advanced reactor developers. Two strategic archetypes dominate: integrated mining-to-fuel operators controlling upstream feedstock, and technology licensors monetizing centrifuge or laser enrichment intellectual property. Capacity expansion and long-term offtake contracting represent the dominant competitive moves as utilities seek supply security.
Within the technology-licensor tier, Centrus Energy Corp. and Global Laser Enrichment occupy positions exemplifying divergent enrichment methodologies. Cameco Corp. anchors the integrated-operator archetype with exposure across mining, conversion, and fuel services. Westinghouse Electric Company sits within the reactor-services ecosystem, leveraging fuel fabrication relationships to secure enrichment partnerships.
| Leading Market Players |
|---|
| NANO Nuclear Energy |
| Westinghouse Electric Company |
| Centrus Energy Corp. |
| Global Laser Enrichment |
| TerraPower |
| Uranium Energy Corp. |
| LIS Technologies |
| Brookfield Corporation |
| Cameco Corp. |
| Others |
Value Chain & Pricing Dynamics
State-owned utilities in China and India command the dominant share of contracted enrichment volumes, anchoring pricing power in long-term offtake agreements that bypass spot market volatility. Their procurement scale enables fixed-price SWU contracts indexed to natural uranium feedstock costs, compressing margin flexibility for toll enrichment providers while securing supply certainty for reactor buildouts.
Pricing Analysis
Bundled fuel supply contracts that integrate conversion, enrichment, and fabrication services command premium positioning over unbundled SWU tolling arrangements. Price differentiation hinges on security certification tier and contract duration, with defense-grade material above 90 percent U-235 capturing the widest spreads. Cost compression in standard enrichment services is intensifying because utilities are consolidating procurement through direct state-backed negotiations. Merchant utilities in deregulated markets exhibit the highest price sensitivity, while government strategic stockpile programs demonstrate minimal elasticity due to mission-critical requirements.
Supply Chain Analysis
IAEA safeguards certification and national security clearance protocols gate facility qualification, creating 18-36 month approval timelines that constrain supply expansion. Manufacturing concentrates in Russia, France, and the United States, with carbon fiber rotor production anchored in specialized aerospace-grade supplier networks. Raw material dependencies span high-purity uranium hexafluoride feedstock, fluorine gas for conversion circuits, and carbon fiber composites for centrifuge rotors. Single-source vulnerability in Russian enrichment capacity exposes Western utilities to geopolitical disruption risk. Distribution runs through direct utility contracting channels rather than trader intermediaries, particularly for Asian state-owned buyers negotiating multi-year agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through HALEU production premiums and operational efficiency gains in advanced centrifuge designs. Cost compression in legacy SWU tolling is being offset by premium-tier shifts toward high-assay low-enriched uranium services for advanced reactor developers.
For Market Incumbents: Anchor domestic supply security positioning by securing long-term offtake agreements with utilities diversifying away from Russian enrichment. Invest in HALEU-capable cascade certification ahead of advanced reactor deployment timelines. Counter laser enrichment substitution threats by demonstrating proven reliability at commercial scale. Prioritize carbon fiber rotor manufacturing partnerships to resolve supply bottlenecks. For New Entrants and Emerging Players: Advanced reactor developers represent the most penetrable customer segment, lacking established fuel supply relationships and requiring HALEU services that incumbent capacity cannot yet fulfill. Target Southeast Asian nuclear programs in Vietnam, Indonesia, and the Philippines advancing first-reactor projects without legacy supplier ties. Pursue technology licensing arrangements with national laboratories to accelerate centrifuge or laser enrichment deployment without full cascade capital burden. For Investors and Strategic Acquirers: State-backed nuclear corporations are the most active acquirer in this space, consolidating fuel cycle capabilities through integrated mining-to-enrichment transactions. Long-term viability centers on HALEU infrastructure positioning and domestic supply chain resiliency over the next decade. Acquisition targets with IAEA-certified facilities and existing utility relationships command scarcity premia. Watch for inflection in US Inflation Reduction Act funding disbursement velocity as a signal for domestic capacity buildout acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| HALEU Production Infrastructure | First-mover investment in 19.75% U-235 cascades captures advanced reactor fuel premiums. |
| Domestic Centrifuge Capacity Buildout | US Inflation Reduction Act funding accelerates American Centrifuge technology deployment. |
| Long-term Utility Offtake Agreements | Direct contracting with Chinese and Indian state-owned utilities locks in volume commitments. |
| Carbon Fiber Rotor Supply Partnership | Aerospace-grade composite manufacturing qualification resolves centrifuge production bottlenecks. |
| IAEA Safeguards Certification | Material accountancy system approval enables market access for non-weapon state facilities. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility fuel procurement officers, enrichment plant operations managers, nuclear regulatory specialists, and advanced reactor development engineers with secondary validation. Secondary sources included IAEA safeguards documentation, Nuclear Regulatory Commission licensing records, EIA nuclear fuel cycle data, and utility annual procurement disclosures. Bottom-up facility capacity modeling and top-down demand projection from reactor deployment pipelines were triangulated for convergence.
Historical reference periods anchored the forecast window through retrospective analysis of SWU pricing volatility, capacity utilization trends, and regulatory approval timelines. Segmentation dimensions modeled include enrichment technology generation, application tier from power generation through defense, end-user procurement sophistication, and regional regulatory framework clusters. CAGRs were derived from compounding annual growth assumptions across the projection horizon. Industry-specific inputs incorporated reactor buildout schedules in China, US Inflation Reduction Act funding trajectories, and HALEU demand curves from advanced reactor design specifications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical fragmentation in Russian supply access and laser enrichment commercialization breakthroughs. Assumptions underlying capacity expansion timelines and utility contracting behavior may require revision upon material shifts in national security screening of foreign investment or advanced reactor deployment delays. A model refresh is warranted upon material change in US domestic enrichment subsidy disbursement velocity or IAEA safeguards protocol amendments affecting facility certification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
North America Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Nuclear Power Pump Market
Nuclear Energy
France Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Thorium Market
Nuclear Energy
Global Molten Salt Reactor Market
Nuclear Energy
Middle-East and Africa Nuclear Power Plant Equipment Market
Nuclear Energy
Industrial Radioactive Source Market
Nuclear Energy
Nuclear Power Plant Equipment Market
Nuclear Energy
Japan Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Nuclear Power Market
Nuclear Energy
Global Nuclear Fusion Market
Nuclear Energy
Asia-Pacific Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Powered Merchant Vessel Market
Nuclear Energy
Nuclear Energy Market
Nuclear Energy
United Kingdom Nuclear Power Reactor Decommissioning Market