
 Russia Payments Market | 2026-2036
Russia Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Payments Market Analytics
The Central Bank of Russia's Faster Payments System (SBP) regulation is rebalancing the cost-of-entry calculus for non-bank payment providers. Sberbank leverages its branch network to sustain dominance in merchant acquiring across provincial cities. Tinkoff Bank competes through mobile-first architecture that bypasses physical infrastructure entirely. Qiwi anchors its position in peer-to-peer transfers and cash-in/cash-out terminal networks.
Russia payments encompass electronic fund transfer systems, card networks, digital wallets, and real-time gross settlement infrastructure operating through proprietary switching protocols and tokenized authentication layers. The primary commercial purpose involves enabling ruble-denominated transactions between consumers, businesses, and government entities while reducing cash dependency. E-wallets within the payment method dimension are capturing the fastest growth as smartphone penetration deepens beyond Moscow and Saint Petersburg. Online payments within transaction type classification concentrate margin pools in e-commerce gateway fees, while bank transfers retain structural importance in B2B settlement corridors. Retail within end user industry segments generates the highest transaction frequency, though hospitality recovery is expanding point-of-sale terminal deployment.
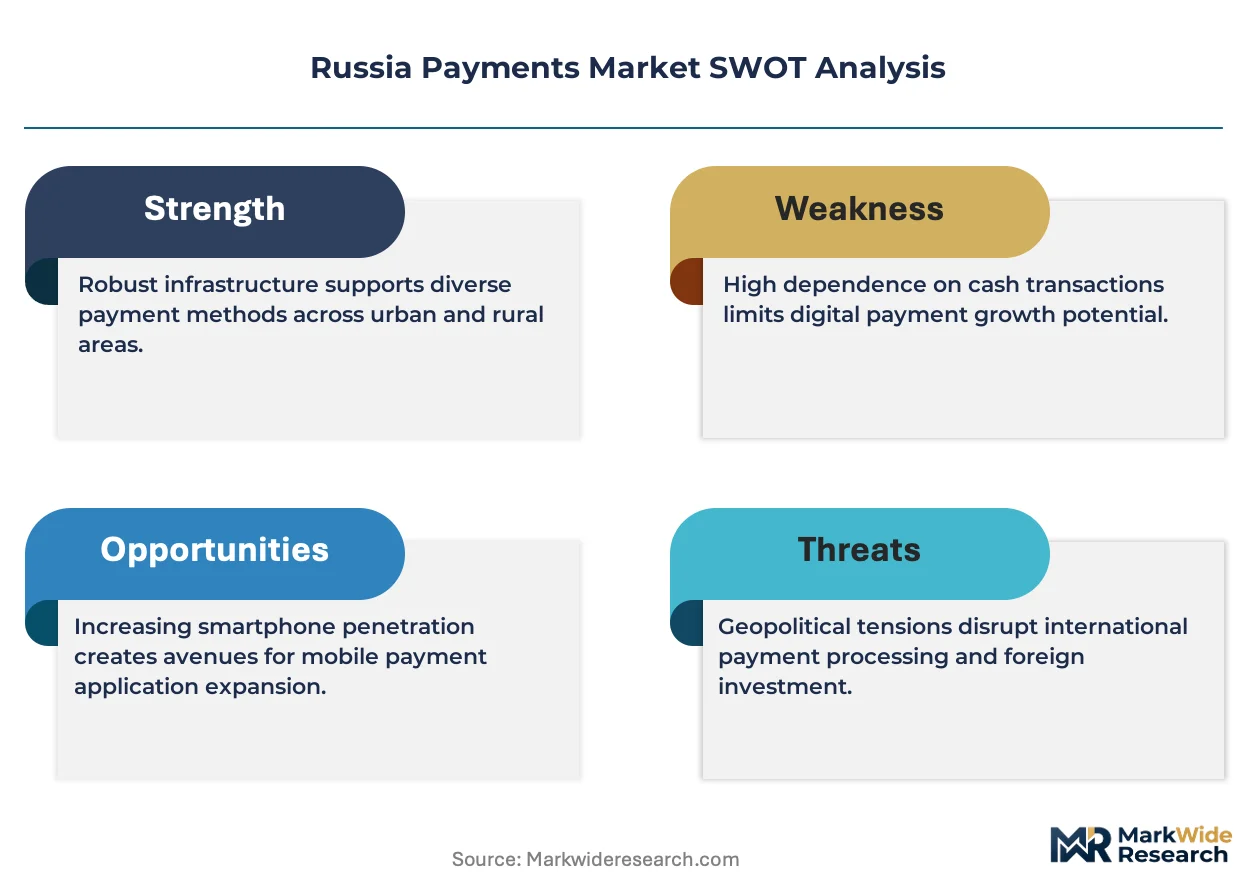
The Central Bank of Russia governs licensing, anti-money laundering protocols, and systemic risk thresholds for payment service providers. BIS-aligned technical standards for card security and data protection shape product certification requirements for terminal hardware and software. The national regulator's sandbox framework permits controlled testing of blockchain-based settlement and biometric authentication. Stakeholders must monitor how sanctions-driven exclusion from SWIFT accelerates domestic alternative development and cross-border ruble clearing arrangements.
Market Dynamics
The Central Bank of Russia's Faster Payments System (SBP) mandates are compressing interchange economics and forcing infrastructure rebuilds across the acquiring stack. This regulatory architecture is redistributing margin pools from international card schemes toward domestic rails while accelerating tokenization investments.
Growth Catalysts
- SBP Mandates:The Faster Payments System regulation caps merchant discount rates at 0.4-0.7% for qualifying transactions, expanding addressable merchant segments previously priced out of electronic acceptance.
- Smartphone Penetration:Deepening mobile device ownership beyond Moscow and Saint Petersburg is converting cash-preferred demographics into digital wallet users through carrier-billing and super-app integrations.
- E-commerce Gateway Expansion:Online retail transaction volumes are driving demand for integrated checkout solutions that unify card, wallet, and pay-later options in single API architectures.
Market Restraints
- Sanctions-Driven Hardware Sourcing:Terminal manufacturers face restricted access to chipsets and secure element modules, elongating procurement cycles and elevating unit costs for POS deployment.
- Concentrated Issuer Power:Sberbank and VTB collectively control over sixty percent of issued cards, limiting negotiating leverage for independent acquirers and fintech intermediaries.
- SWIFT Exclusion Friction:Cross-border ruble clearing outside correspondent banking relationships requires experimental bilateral arrangements with limited transaction throughput and elevated settlement risk.
Strategic Opportunities
- Siberian and Far East Corridors:Merchant acquiring density in Novosibirsk, Vladivostok, and Krasnoyarsk lags Moscow by factors of eight to twelve, creating first-mover expansion potential.
- Biometric Authentication:The Central Bank's regulatory sandbox permits facial-recognition-linked payment authorization, opening regulatory-compliant pathways for checkout-free retail and transit applications.
- B2B Embedded Finance:Supply chain platforms serving manufacturing and commodity trading verticals are integrating working capital advances with invoice settlement workflows.
Industry Challenges
- Legacy Core Modernization:Regional banks operate on Soviet-era COBOL architectures that resist API-native integration with real-time payment rails, requiring multi-year transformation programs.
- Certification Bottlenecks:Hardware security module validation for contactless terminals faces queue lengths exceeding fourteen months at accredited testing laboratories.
- Sanctions Compliance Complexity:Payment service providers must implement dynamic screening against evolving restricted party lists without degrading transaction velocity or false-positive rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Payments Market |
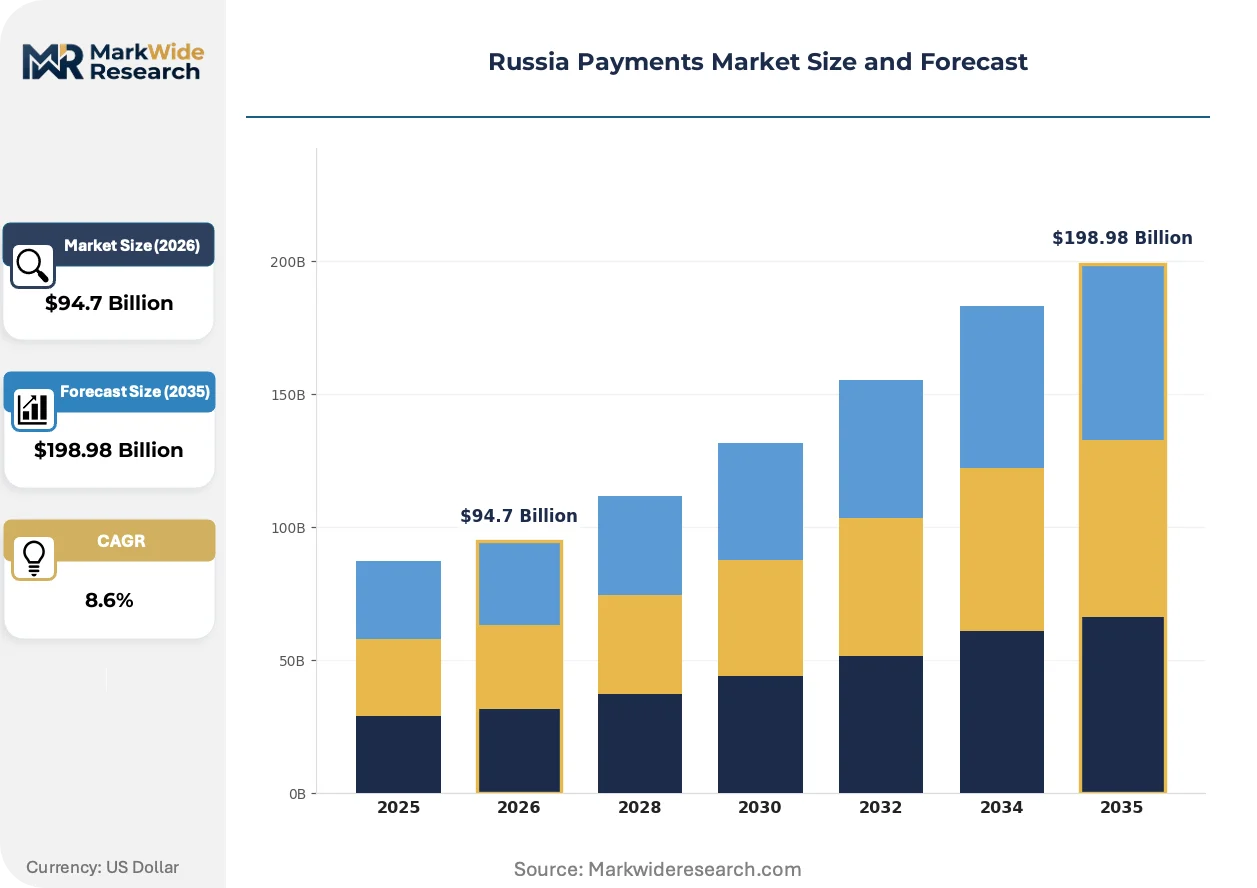
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $198.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Cards, Debit Cards, E-Wallets, Bank Transfers Transaction Type: Online Payments, In-Store Payments, Recurring Payments, Peer-to-Peer Transfers Service Provider: Banks, Fintech Companies, Payment Gateways, Payment Processors End User Industry: Retail, E-commerce, Hospitality, Telecommunications |
| Companies Covered | YooMoney, 2Checkout.com Inc. (Verifone), Sberbank, Qiwi, OnePay, Tinkoff Bank, Ingenico, MTS, Alfa-Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Payments Market Evolving Landscape
Tokenization and biometric authentication are converging to displace static card credentials across Russia's payment infrastructure. These shifts are compressing fraud vectors while elevating infrastructure requirements for merchants and acquirers.
SoftPOS technology is modularizing the merchant acquiring value chain by converting Android smartphones into payment acceptance terminals without dedicated hardware. Small retailers and delivery couriers in Kazan and Yekaterinburg are adopting these solutions fastest, bypassing traditional terminal distribution networks and compressing deployment costs by eliminating hardware logistics entirely.
The Central Bank of Russia's data localization mandates are reshaping cloud architecture decisions for payment service providers. Foreign-hosted transaction processing must migrate to domestic data centers certified under national security standards, forcing infrastructure rebuilds and elevating operational expenditure for international operators maintaining Russian market presence.
Consumer preference is rotating toward invisible checkout experiences in grocery and convenience retail. Moscow-based supermarket chains are piloting computer-vision-enabled stores where biometric-linked accounts settle purchases without physical interaction, displacing traditional POS queues and reducing per-transaction labor costs in high-frequency, low-margin categories.
Russia Payments Market Segmentation
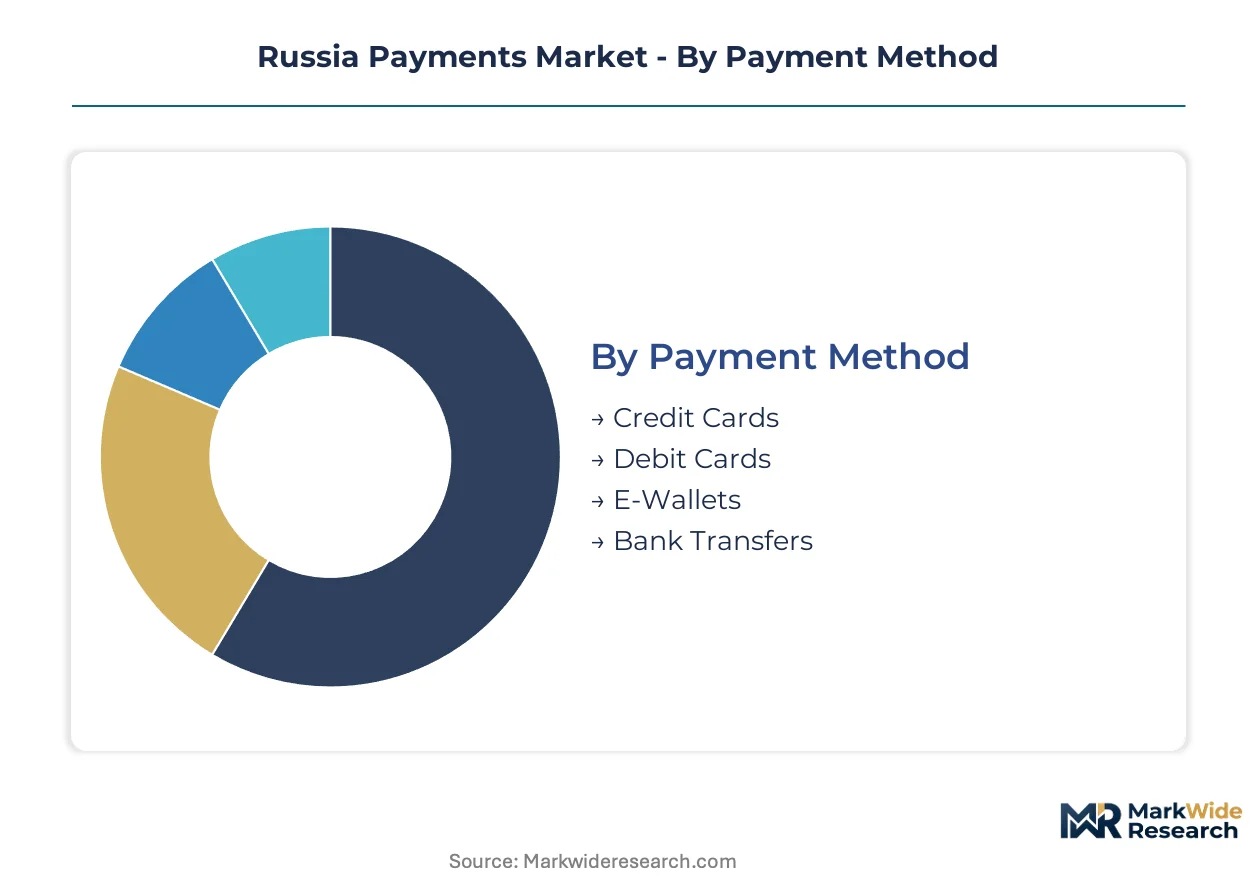
Segmentation in Russia's payments landscape reveals how regulatory mandates and infrastructure investments concentrate capital across different stakeholder groups. Understanding these divisions clarifies where the Central Bank's SBP requirements impose the heaviest transformation burdens.
Payment Method:
Capital intensity varies sharply across methods, with physical card issuance demanding manufacturing and distribution networks while digital rails require cloud infrastructure and tokenization layers.
- Credit Cards:Embossed plastic with EMV chips and contactless antennas requires secure element foundries and personalization bureaus. Moscow and Saint Petersburg issuers dominate outstanding volumes, though sanctions have restricted access to chip suppliers and elongated procurement cycles.
- E-Wallets:Software-based credential storage leverages smartphone secure enclaves and server-side token vaults. Demand concentrates in Kazan and Yekaterinburg where carrier billing integrations convert cash-preferred users through super-app architectures.
- Debit Cards:Direct-linked to deposit accounts with lower interchange economics and simpler risk scoring.
- Bank Transfers:Legacy mainframe batch processing dominates B2B settlement corridors with real-time replacement underway.
E-Wallets absorb the bulk of installed capacity expansion; E-Wallets are expanding most quickly.
Transaction Type:
Margin structures diverge by transaction type, with gateway fees in online commerce sustaining higher take rates than commoditized in-store acquiring.
- Online Payments:E-commerce checkout flows unify card, wallet, and pay-later options through single API integrations. Marketplace merchants in Moscow's digital retail corridor drive volume concentration, though cross-border settlement friction elevates gateway risk premiums.
- In-Store Payments:POS terminal acceptance with contactless and QR-code modalities. Regional deployment lags metropolitan density by factors exceeding ten in Siberian cities.
- Recurring Payments:Subscription billing with tokenized credentials and pre-authorized debit mandates.
- Peer-to-Peer Transfers:SBP-enabled instant crediting between individuals with minimal friction.
Online Payments command the deepest margin pools; Peer-to-Peer Transfers are climbing the fastest.
Service Provider:
Regulatory licensing tiers create capital barriers that favor incumbent banks over lean fintech challengers.
- Banks:Full-service deposit-taking institutions with proprietary processing cores and branch networks. Sberbank and VTB leverage existing infrastructure to absorb SBP compliance costs without margin compression.
- Payment Gateways:Technical intermediaries routing transactions between merchants and acquirers. E-commerce platform integration demands dominate customer acquisition in the Moscow metropolitan corridor.
- Fintech Companies:Mobile-first challengers with API-native architectures and no legacy branch overhead.
- Payment Processors:Backend transaction clearing and settlement operators.
Banks retain structural dominance in transaction volume; Fintech Companies are gaining share fastest.
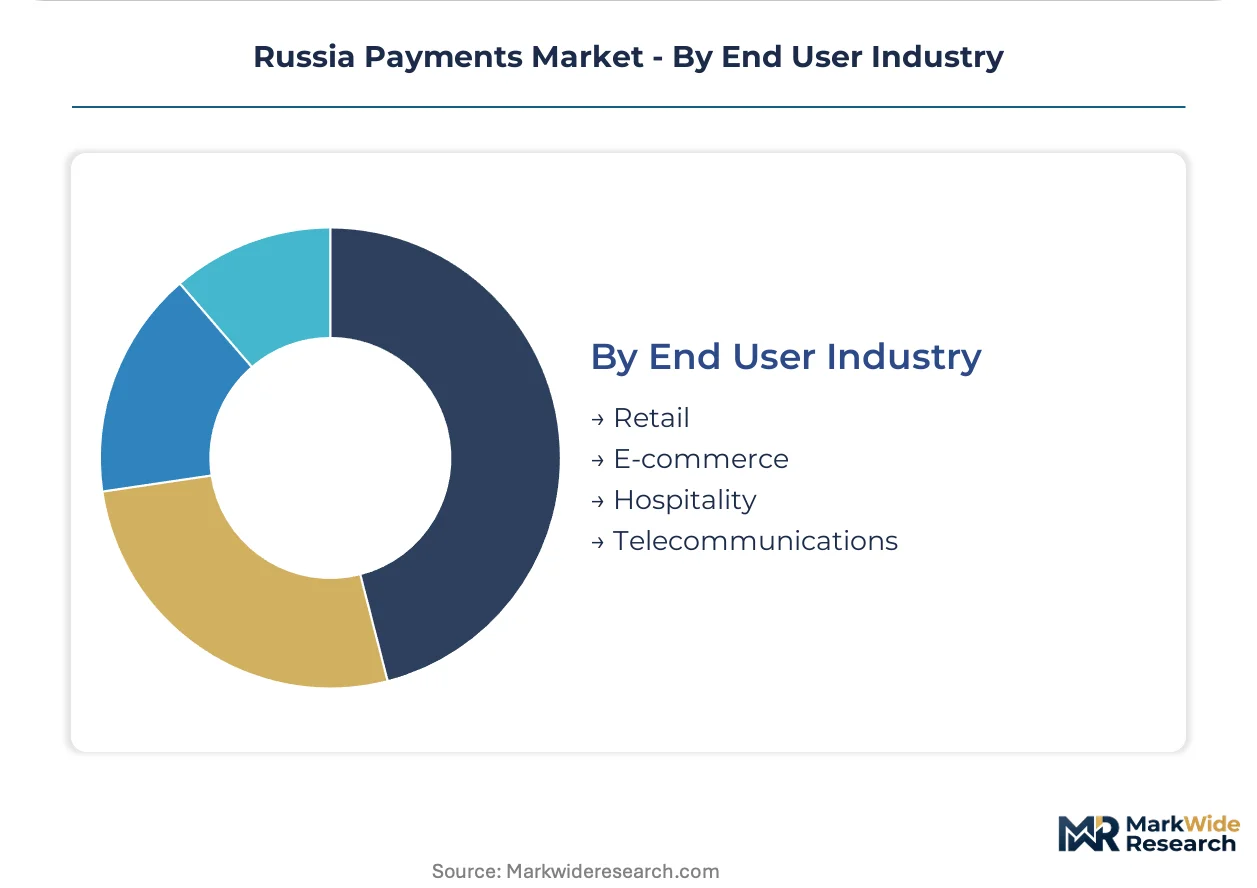
End User Industry:
Merchant acquiring density and digital literacy levels determine adoption velocity across verticals.
- Retail:High-frequency low-value transactions with demanding terminal uptime requirements. Moscow supermarket chains pilot biometric checkout systems that displace traditional POS queues entirely.
- E-commerce:Digital-native transactions with integrated fraud scoring and one-click repeat purchasing. Marketplace sellers drive gateway volume concentration in the capital region.
- Hospitality:Post-recovery expansion of restaurant and hotel terminal deployment with tip-adjustment workflows.
- Telecommunications:Carrier billing integrations and mobile top-up corridors.
Retail absorbs the bulk of terminal installed base; Hospitality is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technopolis Moscow anchors payment infrastructure concentration through tax incentives for fintech residency. The Central Bank's regulatory sandbox privileges cluster participants with accelerated licensing timelines. This zone concentrates biometric authentication pilots and blockchain settlement experiments that diffuse to secondary cities.
Moscow Metropolitan Corridor
Merchant acquiring density and consumer digital literacy intersect most favorably here. The Central Bank of Russia mandates SBP participation for all licensed institutions operating in the capital. Supermarket chains pilot computer-vision checkout systems displacing traditional POS queues entirely.
Saint Petersburg
Port logistics and cross-border trade finance drive B2B payment platform demand. The national regulator's data localization requirements force foreign operators to migrate processing to domestic certified data centers. Fintech challengers leverage the city's technical talent pool for mobile-first architecture development.
Kazan
Carrier-billing integrations convert cash-preferred demographics through super-app architectures. The Central Bank's Faster Payments System caps merchant discount rates, expanding electronic acceptance to previously priced-out merchant segments. Regional banks modernize Soviet-era COBOL cores to API-native integration.
Novosibirsk
Siberian corridor underpenetration creates first-mover expansion potential with merchant acquiring density lagging Moscow by factors of eight to twelve. SoftPOS technology adoption accelerates among small retailers bypassing traditional terminal distribution networks. The national payment system mandates reshape infrastructure requirements across the region.
Vladivostok
Far East trade corridors generate experimental bilateral ruble clearing arrangements outside correspondent banking relationships. Sanctions-driven exclusion from SWIFT accelerates domestic alternative development in this gateway city. Biometric-linked transit payment authorization tests in the regulatory sandbox.
Russia Payments Market Competitive Landscape
Moscow-based banking groups anchor one tier; mobile-native fintech specialists hold differentiated positions through architecture advantage. The structure concentrates around state-affiliated institutions with branch network scale against API-native challengers with zero physical overhead. Three archetypes dominate: full-service deposit-taking banks with proprietary processing cores, technical intermediaries routing merchant transactions, and super-app platforms integrating wallet, commerce, and credit functions. Consolidation pressure operates through SBP compliance cost absorption and sanctions-driven hardware sourcing constraints.
Within the banking tier, Sberbank and VTB occupy positions reflecting state-affiliated scale and infrastructure depth. Tinkoff Bank exemplifies the mobile-first challenger archetype with branchless operations. Among technical intermediaries, YooMoney and Qiwi sit within distinct specializations—wallet credential management and peer-to-peer terminal networks respectively.
| Leading Market Players |
|---|
| YooMoney |
| 2Checkout.com Inc. (Verifone) |
| Sberbank |
| Qiwi |
| OnePay |
| Tinkoff Bank |
| Ingenico |
| MTS |
| Alfa-Bank |
| Others |
Value Network & Pricing Analysis
SoftPOS technology adoption is compressing merchant acquiring costs while redistributing supply chain leverage from hardware manufacturers toward software platforms and mobile device ecosystems. This shift simultaneously lowers entry barriers for small retailers and elevates dependency on Android device supply chains and domestic cloud infrastructure certification.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent terminal deployments from scheduled hardware refreshes, with expedited procurement commanding premiums of thirty to fifty percent above standard delivery windows. Three-tier pricing structure across premium biometric-enabled terminals, standard EMV-contactless units, and economy QR-code readers reflects certification complexity and secure element sourcing tiers. Pricing pressure stems from sanctions-restricted chipset access elongating procurement cycles and elevating unit costs. Small independent merchants in Siberian corridors exhibit highest price sensitivity, while Moscow supermarket chains prioritize uptime guarantees over per-unit economics.
Supply Chain Analysis
Workforce availability constraints in Chinese and Taiwanese secure element foundries are elongating lead times for EMV chip modules and hardware security components. Terminal manufacturing draws from semiconductor fabrication concentrated in East Asia, with final assembly migrating to domestic Russian facilities to satisfy data localization mandates. Single-source vulnerability pervades cryptographic processor supply, where restricted export controls limit alternative sourcing. Distribution runs through bank-owned logistics networks and independent value-added resellers serving regional acquiring markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's payments infrastructure is consolidating around state-affiliated institutions capable of absorbing SBP compliance costs and sanctions-driven hardware sourcing constraints, forcing weaker fintech challengers toward niche specialization or exit.
For Market Incumbents: Deploy biometric authentication infrastructure as a defensive moat against mobile-native challengers. Sberbank and VTB should accelerate regulatory sandbox participation for facial-recognition checkout systems, while investing in backward integration into domestic terminal assembly to mitigate import dependency. Threat substitution from SoftPOS platforms demands branch network repurposing toward advisory services and merchant onboarding rather than transaction processing alone. For New Entrants and Emerging Players: Independent software vendors represent the most penetrable channel partner type for bypassing hardware-dependent acquiring economics. White-space targets concentrate in B2B embedded finance for commodity trading platforms and supply chain working capital solutions. Novosibirsk and Vladivostok merchant acquiring corridors offer first-mover expansion potential with density gaps exceeding eightfold versus Moscow. Go-to-market execution should anchor in carrier-billing integrations through MTS and regional mobile network operators. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by state-affiliated banking groups seeking API-native architecture and mobile engineering talent. Long-term viability over the next decade hinges on regulatory compliance automation capabilities and domestic infrastructure ownership. Acquisition target archetypes include fintech challengers with established SBP integration and regional merchant networks. The signal to watch is Central Bank sandbox expansion permitting blockchain settlement and cross-border ruble clearing pilots.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Authentication Deployment | Regulatory sandbox approvals for facial-recognition checkout displace traditional POS infrastructure in Moscow retail corridors. |
| Domestic Terminal Assembly Buildout | Hardware security module localization satisfies Central Bank data residency mandates while reducing import dependency exposure. |
| SoftPOS Platform Integration | Android smartphone conversion into payment terminals bypasses sanctions-constrained chip procurement for small merchants. |
| B2B Embedded Finance Partnership | Supply chain platforms for commodity trading integrate working capital advances with SBP settlement workflows. |
| Siberian Merchant Network Expansion | First-mover terminal deployment in Novosibirsk and Krasnoyarsk captures density gaps versus Moscow infrastructure concentration. |
Research Methodology
Document review covered Central Bank of Russia regulatory filings, payment system operator disclosures, and sanctions compliance documentation, complemented by interviews with payment gateway technical architects, merchant acquiring executives, fintech product managers, and regional bank IT modernization leads. Secondary validation drew from domestic cloud infrastructure certification records, terminal hardware import statistics, and mobile network operator carrier-billing integration announcements. Bottom-up transaction volume modeling triangulated against top-down GDP-linked payment flow estimates.
Market size outputs across the analysis window reflect segmentation by payment method, transaction type, service provider tier, and end-user industry vertical. CAGRs were derived from smartphone penetration trajectories, SBP mandate implementation schedules, and e-commerce gateway expansion rates. Industry-specific inputs incorporated biometric authentication pilot adoption curves, SoftPOS merchant activation velocities, and regional acquiring density differentials between Moscow metropolitan and Siberian corridor markets.
Several conditions sit outside the modeled scope, including escalation or relaxation of international sanctions regimes, Central Bank interest rate volatility affecting merchant discount rate economics, and breakthrough developments in quantum-resistant cryptography requiring infrastructure replacement. Forecasts reflect assumptions regarding regulatory sandbox continuity and domestic cloud certification capacity expansion. Material deviation in sanctions enforcement intensity or biometric authentication regulatory authorization timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Payments As a Service Market
Payments
Hong Kong Credit Cards Market
Payments
South Korea Real Time Payments Market
Payments
South Korea Payments Market
Payments
Mexico Real Time Payments Market
Payments
Fingerprint Payment Market
Payments
Fuel and Convenience Store POS Market
Payments
China POS Terminals Market
Payments
Payment Instruments Market
Payments
Brazil POS Terminal Market
Payments
Tanzania Mobile Money Market
Payments
Vietnam Payments Market
Payments
In-Vehicle Payment Services Market
Payments
Global Bitcoin Payments Ecosystem Market
Payments
Digital Payment Market
Payments
United States Clearing Houses and Settlements Market