
 Cash Management Software Market | 2026-2036
Cash Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Cash Management Software Market Insights
Mid-market corporates are unwinding reliance on legacy spreadsheet-based treasury workflows, while large enterprises deepen platform consolidation. SAP anchors its position through embedded finance modules within broader ERP ecosystems. Oracle leverages cloud infrastructure to extend treasury functionality across multi-entity structures. Kyriba specializes in connectivity layers that aggregate bank feeds across fragmented geographic footprints.
Cash management software encompasses systems that automate liquidity forecasting, payment execution, bank reconciliation, and working capital optimization through API-driven data aggregation and predictive analytics. These platforms process multi-currency cash positions in real time, reducing manual intervention in treasury operations. Cloud-based deployment leads solution type adoption as corporates prioritize scalability over capital-intensive on-premises infrastructure. Treasury management functionality captures the largest margin pool, while fraud detection grows fastest as real-time payment rails expand attack surfaces. Payment processing remains mature, with consolidation pressure on standalone vendors.
The European Banking Authority's PSD3 framework shapes open banking data access requirements, while the EU AI Act imposes transparency obligations on automated liquidity forecasting algorithms. The Securities and Exchange Commission's climate disclosure rules in the United States are forcing treasury teams to integrate sustainability-linked cash positioning into reporting workflows. Stakeholders must monitor how regulatory divergence between jurisdictions fragments platform certification requirements.
Market Dynamics
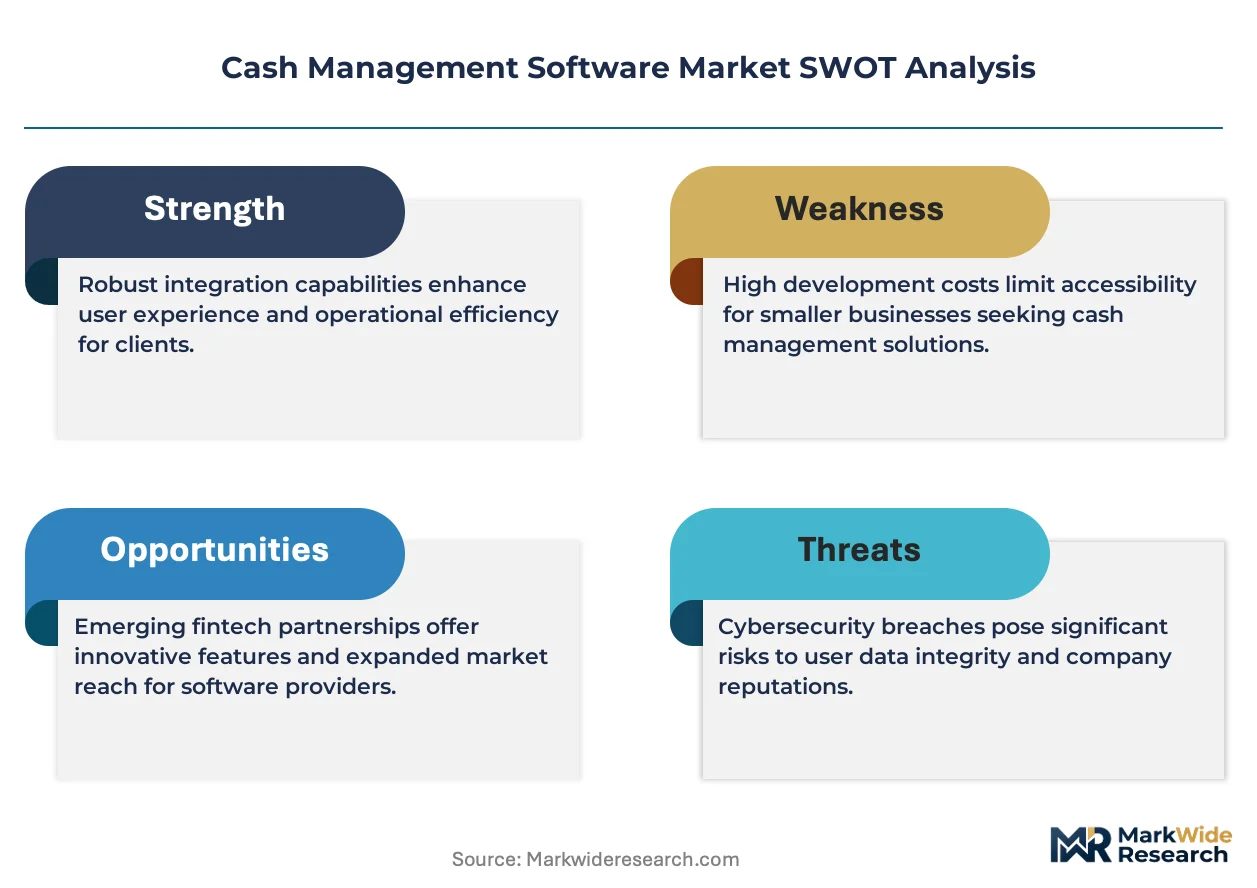
Real-time payment infrastructure is compressing treasury settlement cycles from T+2 to instant, forcing software vendors to rebuild core engines around ISO 20022 messaging standards and API-first architectures.
Growth Catalysts
- PSD3 Open Banking Mandates:The European Banking Authority's framework compels banks to expose standardized APIs, enabling treasury platforms to aggregate multi-bank cash positions without screen-scraping workarounds.
- Mid-Market Cloud Migration:Corporates with $500M-$5B revenue are abandoning spreadsheet-based forecasting for SaaS treasury modules that scale without capital expenditure.
- Embedded Finance Modules:ERP vendors are pre-integrating liquidity management tools into core financial systems, reducing procurement friction for treasury buyers.
Market Restraints
- Bank API Fragmentation:Despite open banking mandates, German, French, and Italian banks implement divergent technical standards, forcing vendors to maintain costly connectivity layers.
- Cyber Insurance Escalation:Real-time payment rails expand fraud attack surfaces, driving up premiums for treasury software vendors and their corporate clients.
- Legacy ERP Lock-In:Large enterprises with decade-old SAP or Oracle deployments face seven-figure switching costs to modern cloud-native alternatives.
Strategic Opportunities
- AI-Enabled Forecasting:Machine learning models trained on payment timing patterns can predict cash positions 30-90 days forward with accuracy unattainable through statistical methods alone.
- Sustainability-Linked Treasury:The SEC's climate disclosure rules create demand for carbon-adjusted liquidity reporting that tracks green bond proceeds and ESG-linked deposit instruments.
- India's Digital Rupee Infrastructure:The Reserve Bank of India's CBDC pilot creates white space for treasury platforms supporting programmable money and conditional settlement logic.
Industry Challenges
- Treasury-Tech Talent Scarcity:Platforms struggle to hire engineers fluent in both SWIFT messaging standards and modern cloud architecture.
- Multi-Jurisdiction Certification Burden:Vendors must maintain separate SOC 2, ISO 27001, and GDPR compliance attestations for each geographic market.
- Legacy System Integration Complexity:Corporates demand pre-built connectors to 1990s-era ERPs, consuming disproportionate engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cash Management Software Market |
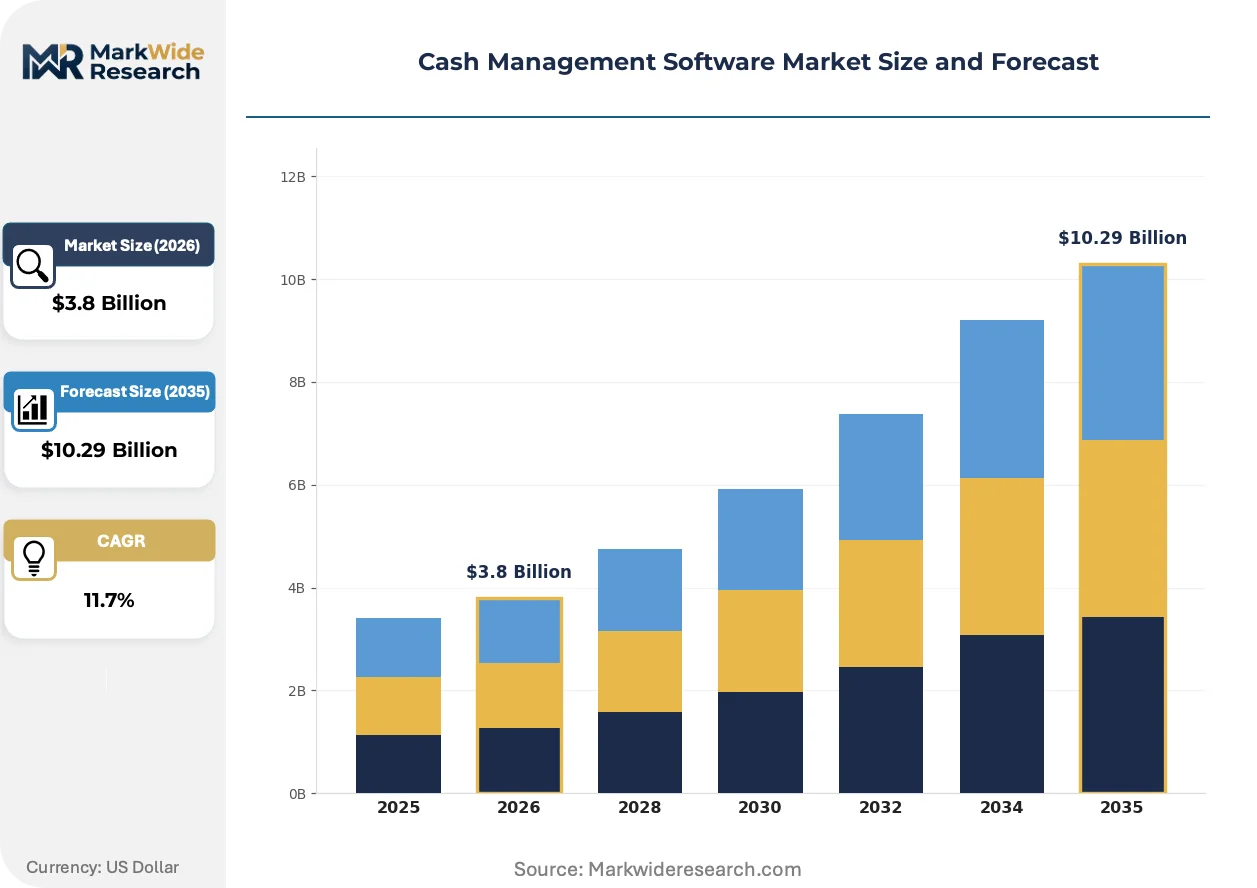
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Hosted Solution Type: Payment Processing, Treasury Management, Liquidity Management, Risk Management, Fraud Detection Application: Corporate Finance, Banking Operations, Government Agencies, Educational Institutions, Non-Profit Organizations End User: Financial Institutions, Insurance Companies, Retail Chains, Hospitality Firms, Consulting Firms |
| Companies Covered | Kyriba, Cobase, Highradius, Nomentia, SAP, FIS Global, Oracle, ION Group, Treasury Intelligence Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cash Management Software Market Trends and Innovations
API-driven data architecture is displacing batch-file imports as the dominant integration pattern, compressing cash visibility latency from hours to seconds.
Embedded liquidity forecasting is miniaturizing treasury intelligence into ERP workflows. SAP and Oracle are pre-deploying cash position algorithms within their financial modules. Mid-market buyers now expect forecasting without separate logins. This capability is miniaturizing standalone treasury software into feature sets rather than discrete purchases.
The EU AI Act imposes transparency obligations on automated liquidity forecasting algorithms used by European corporates. Vendors must document training data sources and decision logic for audit trails. German treasury teams are demanding explainable AI modules that satisfy both internal risk committees and external auditors.
Subscription pricing is displacing perpetual license models across the buyer base. Mid-market corporates prefer OpEx-aligned SaaS contracts with usage-based tiers. French and Dutch treasury departments are piloting outcome-based arrangements tied to forecast accuracy improvements rather than seat counts.
Cash Management Software Market Segmentation
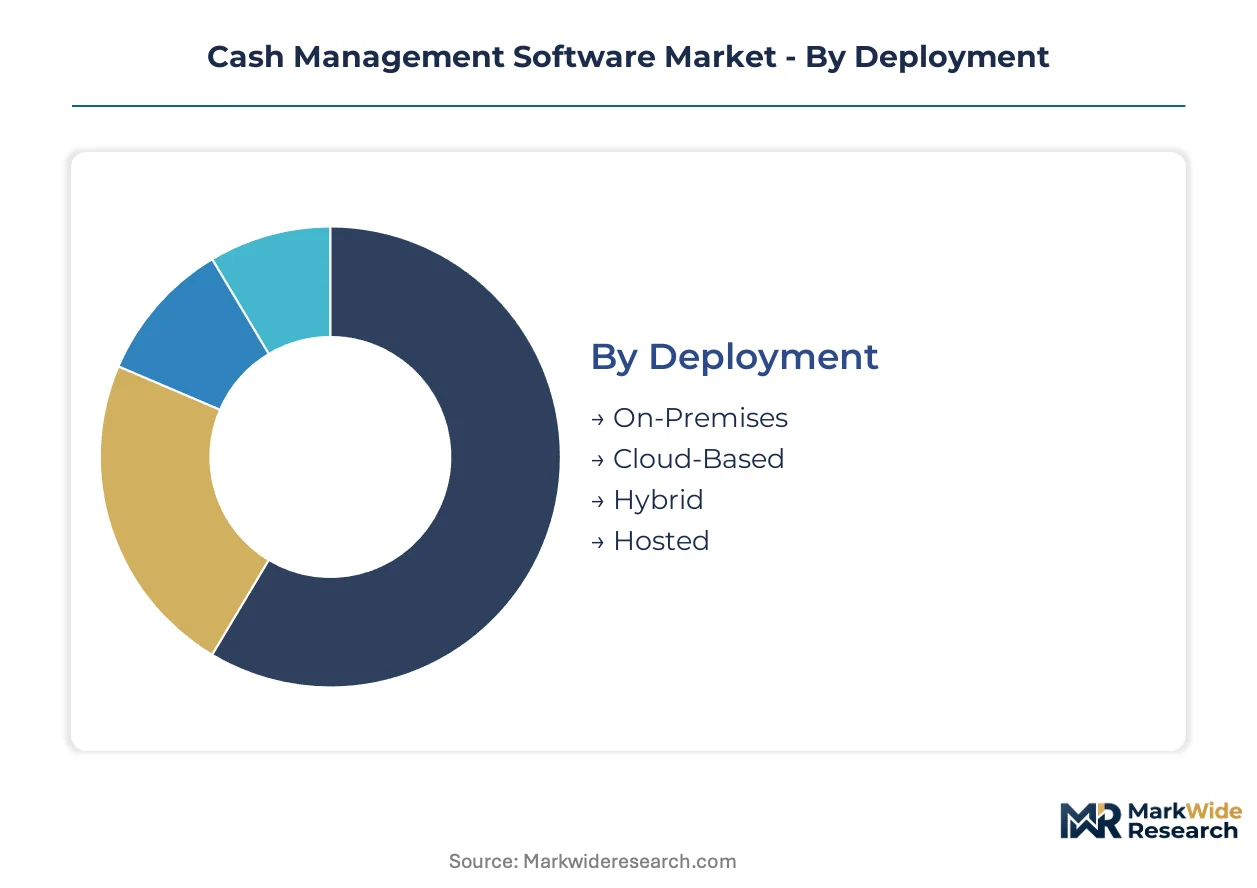
Cash management software segments diverge sharply by compliance burden and infrastructure maturity. Deployment choices determine how treasury teams satisfy PSD3 data residency rules and ISO 20022 messaging requirements.
Deployment:
Regulatory differentiation separates deployment modes most decisively in the European Union, where GDPR data localization and ECB operational resilience directives impose divergent technical obligations.
- Cloud-Based:Multi-tenant SaaS architectures with regional data sovereignty controls dominate new procurement. German and French mid-market corporates prioritize these platforms to satisfy ECB guidance on critical service outsourcing without capital expenditure.
- On-Premises:Dedicated hardware installations within corporate data centers persist where national banking regulators mandate physical control over payment infrastructure. Italian and Spanish treasury teams in defense and energy sectors maintain these deployments to satisfy sector-specific operational continuity requirements.
- Hybrid:Split configurations process sensitive payment data on-premises while leveraging cloud analytics for forecasting workloads.
- Hosted:Single-tenant private cloud deployments managed by third-party providers offer middle-ground control for compliance-conscious buyers.
Cloud-Based handles the majority of throughput; Hybrid is gaining share fastest as regulated industries seek balanced control.
Solution Type:
Margin concentration follows functional complexity, with modules requiring real-time data aggregation commanding premium pricing over batch-processed alternatives.
- Treasury Management:Core platforms integrating cash positioning, bank connectivity, and payment execution represent the most mature revenue pool. These systems anchor procurement decisions for large enterprises with multi-entity structures spanning German, Dutch, and Belgian operations.
- Fraud Detection:Machine learning modules analyzing payment pattern anomalies in real time address expanded attack surfaces from instant payment rails. Demand concentrates among French retail banks and German automotive suppliers processing high-velocity transaction volumes.
- Payment Processing:Legacy infrastructure for batch payment execution faces consolidation pressure from embedded ERP alternatives.
- Liquidity Management:Forecasting engines predicting cash positions across currency pairs and time horizons.
- Risk Management:Modules quantifying foreign exchange and interest rate exposures for hedge accounting compliance.
Treasury Management commands the largest margin pool; Fraud Detection shows the steepest expansion trajectory as real-time rails proliferate.
Application:
Customer sophistication separates segments, with banking operations demanding API-native architectures while public sector buyers prioritize audit trails and procurement compliance.
- Corporate Finance:Treasury departments within multinational manufacturers and energy firms drive requirements for multi-bank aggregation and automated reconciliation. German industrial conglomerates with centralized liquidity operations represent the most demanding specification setters.
- Banking Operations:Financial institutions building white-label treasury services for corporate clients require scalable infrastructure handling millions of accounts. Dutch and Irish banks expanding transaction banking platforms anchor this demand.
- Government Agencies:Public sector treasuries managing tax collection and disbursement flows.
- Educational Institutions:University endowment offices and research fund administrators with restricted grant compliance needs.
- Non-Profit Organizations:Charitable foundations managing donor-restricted funds across multiple currencies and jurisdictions.
Corporate Finance generates the dominant revenue share; Banking Operations is expanding most quickly as institutions build embedded treasury services.
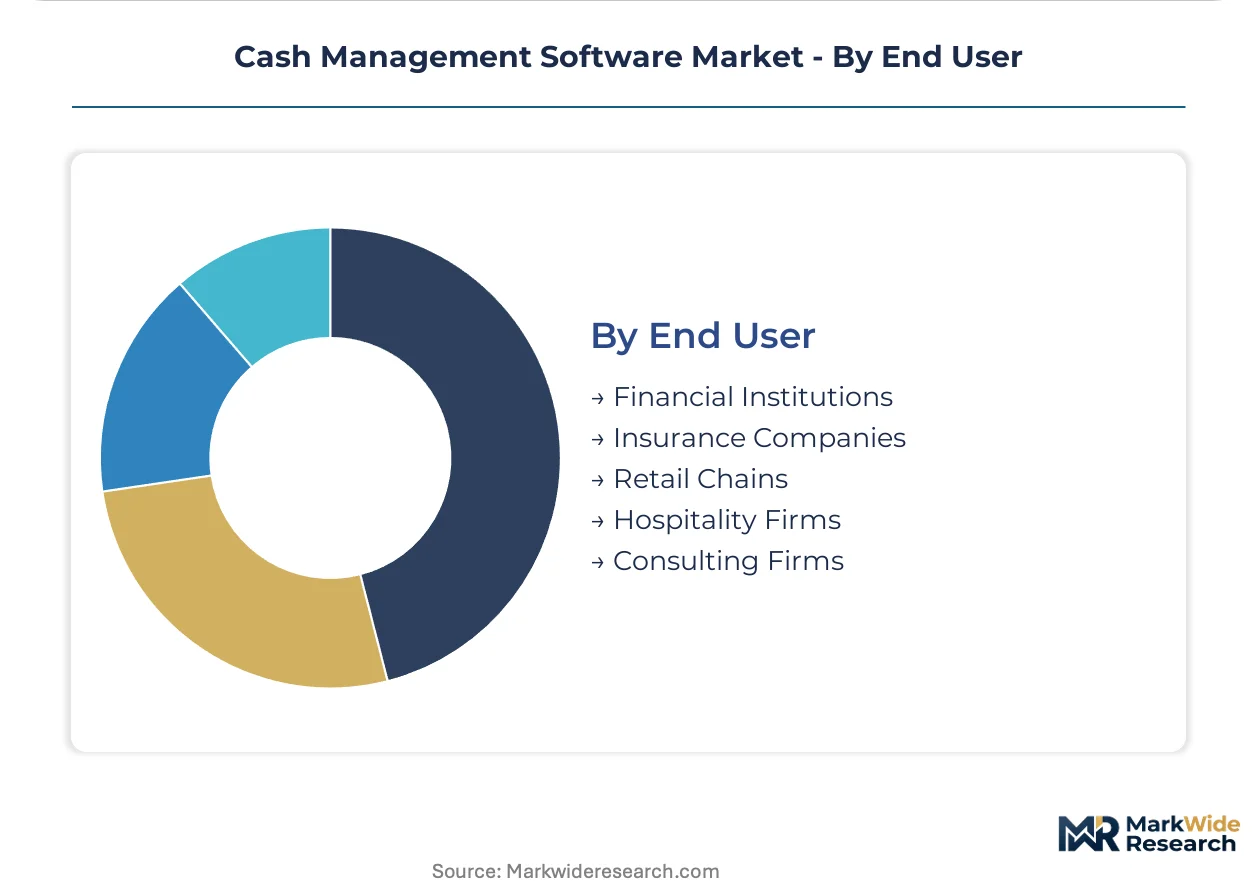
End User:
Vertical specialization determines connectivity requirements, with financial institutions demanding SWIFT integration while retail chains prioritize POS-to-treasury data flows.
- Financial Institutions:Banks, credit unions, and asset managers requiring real-time visibility across correspondent banking networks and custody accounts. Frankfurt and Paris-based institutions lead specification demands for ECB collateral management integration.
- Retail Chains:Multi-location merchants consolidating cash flows from thousands of POS terminals and e-commerce gateways. German and Polish grocery and apparel retailers with dense store networks drive requirements for intraday liquidity visibility.
- Insurance Companies:Carriers managing premium collection and claims disbursement timing across life and property lines.
- Hospitality Firms:Hotel and restaurant groups with seasonal cash flow volatility and multi-currency booking platforms.
- Consulting Firms:Professional services partnerships with project-based revenue recognition and partner distribution workflows.
Financial Institutions represent the deepest buyer base; Retail Chains are climbing the fastest on share as real-time payment adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German treasury software vendors export connectivity solutions to Dutch and French banking clients, while Indian SaaS providers supply forecasting modules to Southeast Asian manufacturing conglomerates.
United States
Corporate treasurers at Fortune 500 manufacturers drive demand for real-time liquidity visibility across multi-bank relationships. The SEC's climate disclosure rules force integration of sustainability-linked cash positioning into reporting workflows. Silicon Valley fintech clusters and New York financial centers anchor development of AI-enabled forecasting engines.
Germany
Industrial conglomerates with centralized treasury operations require multi-entity cash aggregation across Eurozone subsidiaries. The ECB's operational resilience directives impose strict outsourcing controls on critical payment infrastructure. Frankfurt-based banking technology clusters concentrate vendor engineering teams serving automotive and chemical supply chains.
United Kingdom
Post-Brexit treasury teams demand platforms handling Sterling-Euro fragmentation in payment corridors. The Financial Conduct Authority's operational resilience framework mandates recovery time objectives for cash management systems. London's transaction banking hubs drive specifications for real-time gross settlement integration.
India
Mid-market manufacturers with $500M-$2B revenue abandon spreadsheet forecasting for cloud treasury modules. The Reserve Bank of India's digital rupee pilot creates demand for programmable money infrastructure. Mumbai and Bangalore technology corridors host engineering centers building API-native bank connectivity layers.
Netherlands
Dutch multinational trading houses require multi-currency liquidity management across commodity supply chains. The Dutch Central Bank's PSD3 implementation guidelines shape open banking API standards for corporate treasury access. Rotterdam logistics clusters and Amsterdam financial centers concentrate demand for intraday cash visibility.
Cash Management Software Market Competitive Landscape
Listed leaders compete with private specialists across cloud infrastructure and embedded finance dimensions. The vendor base organizes into three tiers: ERP incumbents with treasury modules, standalone SaaS platforms, and banking technology providers. Strategic archetypes include connectivity aggregators, forecasting engine specialists, and payment infrastructure builders. Dominant competitive moves encompass API partnership networks with regional banks and vertical integration into embedded finance workflows.
Within the ERP-anchored tier, SAP and Oracle exemplify platform consolidation strategies that pre-integrate liquidity tools into core financial systems. Kyriba occupies a position among connectivity specialists, representing the archetype of vendors building multi-bank aggregation layers across fragmented European banking standards. These three companies sit within distinct competitive vectors: ERP incumbents leverage installed base relationships, while standalone platforms compete on implementation speed and bank coverage breadth.
| Leading Market Players |
|---|
| Kyriba |
| Cobase |
| Highradius |
| Nomentia |
| SAP |
| FIS Global |
| Oracle |
| ION Group |
| Treasury Intelligence Solutions |
| Others |
Pricing and Supply Chain Analysis
GDPR data residency certification gates both vendor qualification and price stratification in European treasury software procurement. German and French buyers demand SOC 2 Type II and ISO 27001 attestations as table stakes, while premium pricing attaches to ECB operational resilience compliance and explainable AI modules satisfying the EU AI Act.
Pricing Analysis
Next-generation API-native architectures command 40-60% subscription premiums over legacy batch-file systems, while prior-generation on-premises installations trade at depreciation-heavy maintenance rates. Three-tier pricing structure across premium, standard, and economy levels segments by bank connectivity count, forecast accuracy SLAs, and embedded ERP integration depth. Cost compression in the mid-market tier is intensifying because SAP and Oracle bundle treasury modules at marginal cost to core ERP contracts. Small and medium corporates with $500M-$2B revenue exhibit highest price sensitivity, while German automotive conglomerates prioritize compliance over cost.
Supply Chain Analysis
Just-in-time engineering deployment dominates cloud-native vendors, while strategic stockpiling of bank API documentation and certification artifacts buffers against regulatory fragmentation. Software engineering concentrates in Germany, India, and the Netherlands, with Frankfurt and Bangalore hosting the deepest SWIFT messaging expertise. Cloud infrastructure draws from hyperscaler regions in Ireland, Germany, and India, while specialized forecasting talent rests on academic pipelines in Zurich and London. Single-source vulnerability sits with SWIFT network access and ECB collateral management integration. Distribution runs through direct enterprise sales teams for large accounts and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring revenue from bank connectivity maintenance and API subscription tiers expands faster than perpetual license recognition, positioning after-sales attach as the primary margin expansion lever. Vendors capturing forecasting outcome-based contracts capture disproportionate lifetime value.
For Market Incumbents: Fortify embedded finance positioning by deepening pre-integration with SAP and Oracle ERP ecosystems, neutralizing standalone SaaS displacement threats. Invest in explainable AI certification to satisfy German risk committee requirements under the EU AI Act. Prioritize ISO 20022 messaging engine upgrades to defend against cloud-native entrants targeting instant payment rails.
For New Entrants and Emerging Players: Lead with API-first bank aggregation targeting mid-market Dutch and Belgian corporates underserved by legacy connectivity layers. India's digital rupee infrastructure and programmable money pilots represent the most penetrable white space. Pursue vertical specialization in sustainability-linked treasury reporting to exploit SEC climate disclosure compliance gaps.
For Investors and Strategic Acquirers: The EU AI Act's transparency mandates reshape the acquisition landscape toward vendors with documented training data lineage and audit-trail infrastructure. Five-to-ten year viability favors connectivity aggregators with dense European bank coverage over point-solution forecasting engines. Target acquisition archetype: mid-market SaaS platforms with 50+ bank API connectors and German manufacturing client concentration. Watch for PSD3 implementation variance between member states as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| API Partnership Network Expansion | Dense bank connectivity in Germany and France accelerates mid-market customer acquisition velocity. |
| Embedded ERP Integration | Pre-deployment within SAP S/4HANA modules reduces procurement friction for treasury buyers. |
| AI Forecasting Engine Development | Machine learning models trained on payment timing patterns unlock outcome-based pricing contracts. |
| Regulatory Certification Investment | ECB operational resilience and EU AI Act compliance attestation gates premium tier access. |
| Geographic Engineering Expansion | Bangalore and Mumbai talent pools address treasury-tech scarcity in SWIFT and cloud architecture. |
Research Methodology
Desk research of SEC filings, ECB statistical data warehouse, and SWIFT network traffic reports preceded structured interviews with corporate treasury directors, bank transaction banking heads, ERP implementation consultants, and fintech product managers. Primary fieldwork combined telephonic and in-person engagements across Frankfurt, London, Amsterdam, and Bangalore. Secondary validation drew from vendor pricing disclosures, bank API documentation repositories, and regulatory guidance papers. Bottom-up segmentation modeling triangulated against top-down macroeconomic liquidity indicators.
Variance decomposition across deployment mode, solution type, organization size tier, and regional regulatory cluster shaped the analytical framework throughout the forecast period. CAGRs derived from logistic diffusion curves fitted to cloud adoption rates and real-time payment infrastructure rollout timelines. Modeled inputs included corporate cash concentration indices, mid-market SaaS procurement velocity, and open banking API penetration by country.
Forecasts assume regulatory continuity in EU PSD3 implementation, SEC climate disclosure enforcement, and RBI digital rupee pilot expansion; material policy shifts would require re-modeling. Specific risks include bank API standardization delays, cyber insurance market contraction, and legacy ERP lock-in persistence. Revision becomes warranted when instant payment rail adoption crosses 60% penetration in core European markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Payment Service Provider Market
Payments
Europe Real Time Payments Market
Payments
Credit Card Issuance Services Market
Payments
Spain Payments Market
Payments
United Arab Emirates Real Time Payments Market
Payments
UAE Card Payments Market
Payments
United States Electronic Toll Collection Market
Payments
France Payments Market
Payments
Vietnam Mobile Payments Market
Payments
Canada Prepaid Cards Market
Payments
Europe Payment Gateways Market
Payments
Asia Pacific Buy Now Pay Later Service Market
Payments
Global Mobile Point of Sale (Mpos) Terminals Market
Payments
Mobile Payment Security Software Market
Payments
Middle East and Africa Payments Market
Payments
France Buy Now Pay Later Services Market