
 Canada Data Center Storage Market | 2026-2036
Canada Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Data Center Storage Market Insights
Premium all-flash arrays and commodity hard disk tiers is recalibrating procurement patterns across Canadian enterprise buyers. Dell Technologies leverages its PowerStore architecture to anchor high-performance workloads in Toronto financial corridors. NetApp competes through cloud-connected fabric deployments that bridge on-premises and colocation environments. Pure Storage differentiates with subscription-based Evergreen models that reduce refresh cycle friction.
Canada data center storage encompasses electromechanical and solid-state devices engineered for persistent digital retention, typically operating across latency thresholds from sub-millisecond flash to multi-second tape archive tiers, serving sovereign data residency requirements and enterprise continuity mandates. Solid state drives now lead capital allocation among product types as workload density intensifies, while magnetic storage retains dominance in cold-archive economics. Cloud storage within the technology dimension captures the fastest expansion trajectory as federal procurement shifts toward hybrid deployment models.
Health Canada and the Office of the Superintendent of Financial Institutions jointly shape data sovereignty and breach-notification standards that govern storage architecture decisions across healthcare and banking verticals. The Canadian Centre for Cyber Security issues baseline controls that influence encryption-at-rest specifications and geographic redundancy requirements. Stakeholders must monitor evolving federal cloud-first directives against provincial privacy fragmentation to align capacity planning with compliance exposure.
Market Dynamics
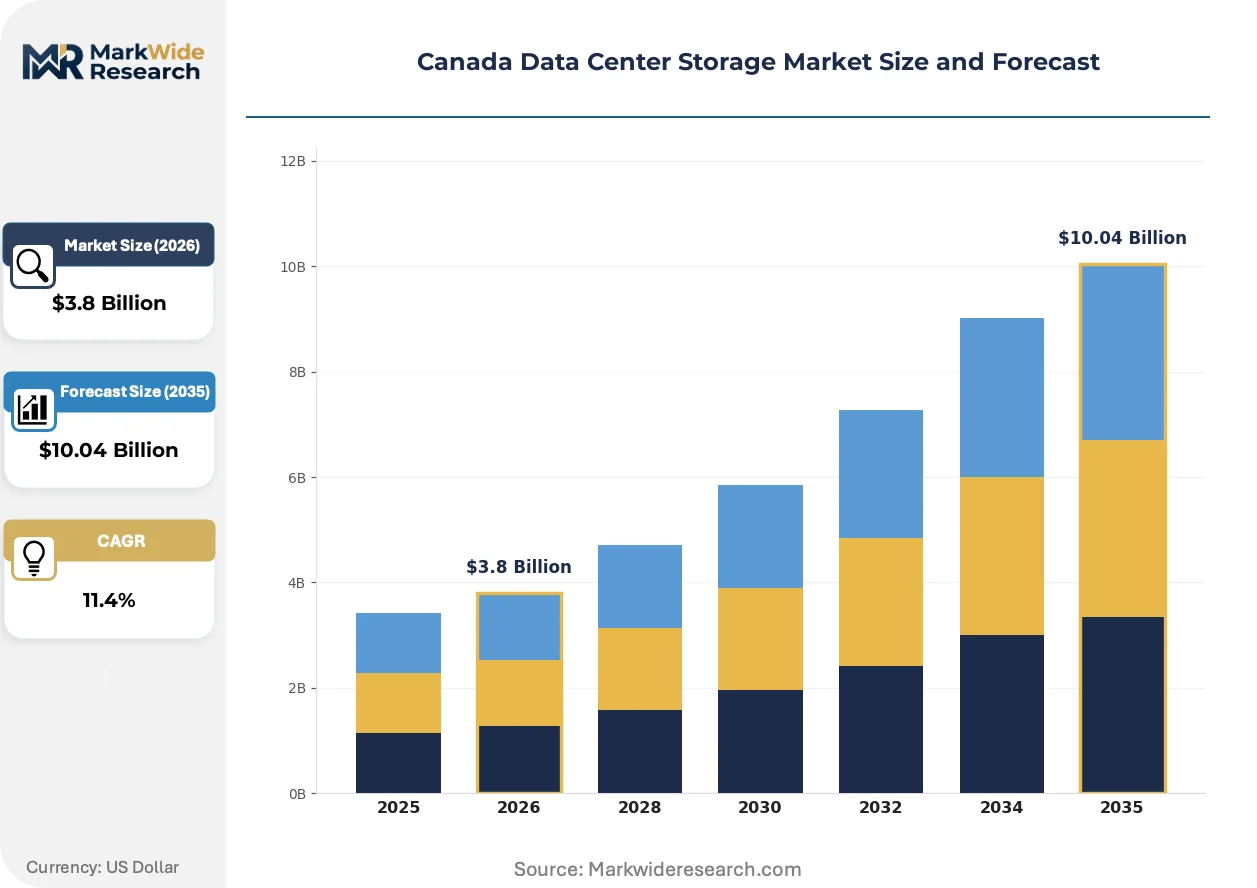
Canadian financial institutions are accelerating storage infrastructure buildouts to satisfy OSFI cybersecurity guidelines, compressing procurement timelines and favoring sovereign cloud architectures over hyperscale alternatives.
Growth Catalysts
- OSFI B-13 Cybersecurity Guidelines:Mandated resilience testing and geographic redundancy requirements force tier-one banks to expand primary and secondary storage footprints across Toronto and Vancouver corridors.
- Health Canada Data Residency Mandates:Provincial health authorities must retain patient records within Canadian borders, driving dedicated storage procurement for healthcare networks in Ontario, Quebec, and British Columbia.
- NVMe-oF Fabric Adoption:High-frequency trading firms and AI research clusters deploy NVMe-over-fabrics to collapse latency between compute and persistent storage layers.
Market Restraints
- Flash Memory Supply Concentration:NAND fabrication concentrates in South Korea and Taiwan, exposing Canadian buyers to geopolitical supply interruptions and freight cost volatility.
- Interprovincial Privacy Fragmentation:Alberta's Personal Information Protection Act, Quebec's Law 25, and British Columbia's PIPA create conflicting encryption and breach-notification standards that complicate national deployments.
- Legacy Tape Archive Dependency:Cold-storage economics still favor magnetic tape for seven-year retention mandates, slowing all-flash penetration in archival tiers despite operational friction.
Strategic Opportunities
- Atlantic Canada Hyperscale Corridors:Newfoundland and Labrador's hydroelectric surplus and submarine cable landing points position St. John's and Halifax as emerging colocation destinations for latency-tolerant workloads.
- Indigenous Data Sovereignty Frameworks:First Nations broadband initiatives and self-governance agreements create demand for community-controlled storage infrastructure outside provincial jurisdiction.
- AI Training Cluster Expansion:Vector Institute partnerships and federal compute procurement programs drive petabyte-scale object storage deployments for machine learning pipelines.
Industry Challenges
- Specialized Storage Engineering Talent:Distributed systems expertise for Ceph and MinIO deployments remains scarce in Montreal and Calgary markets, forcing reliance on contractor networks.
- Hybrid Cloud Integration Complexity:Enterprises struggle to unify on-premises PowerScale clusters with AWS Outposts and Azure Stack HCI instances under single data governance policies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Data Center Storage Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Disk Drives, Solid State Drives, Tape Storage, Hybrid Storage Technology: Flash Storage, Optical Storage, Magnetic Storage, Cloud Storage End User: Telecommunications, Financial Services, Healthcare, Government Deployment Model: On-Premises, Colocation, Hybrid Deployment, Public Cloud |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, IBM, NetApp, Hitachi Vantara, Pure Storage, Infinidat, Lenovo Group, Cisco Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Data Center Storage Market Trends and Innovations
Computational storage, software-defined architectures, and consumption-based procurement models are restructuring how Canadian enterprises acquire and operate persistent storage infrastructure.
Computational storage drives with onboard processing capability are decentralizing analytics workloads away from centralized compute nodes. Energy sector firms in Calgary deploy these devices to execute reservoir simulations at the storage layer, reducing data movement across network fabrics. This compression of the compute-storage boundary is decentralizing architectural decisions traditionally reserved for infrastructure architects.
The Canadian Centre for Cyber Security's IT Security Guidance for Cloud Services is mandating encryption-at-rest with hardware security module integration for federal contractors. This regulatory pressure forces storage vendors to certify FIPS 140-2 Level 3 compliance across product lines before qualifying for Shared Services Canada procurement vehicles. Defense and critical infrastructure operators now disqualify uncertified arrays regardless of price-performance metrics.
Capacity-on-demand contracting is displacing traditional capital acquisition cycles among mid-market enterprises. Colocation providers in Toronto's 151 Front Street corridor now offer storage-as-a-service with committed use discounts that mirror hyperscale pricing without egress complexity. Manufacturing verticals in southwestern Ontario have embraced this model most aggressively, preferring operational expenditure treatment for unpredictable growth phases.
Canada Data Center Storage Market Segmentation
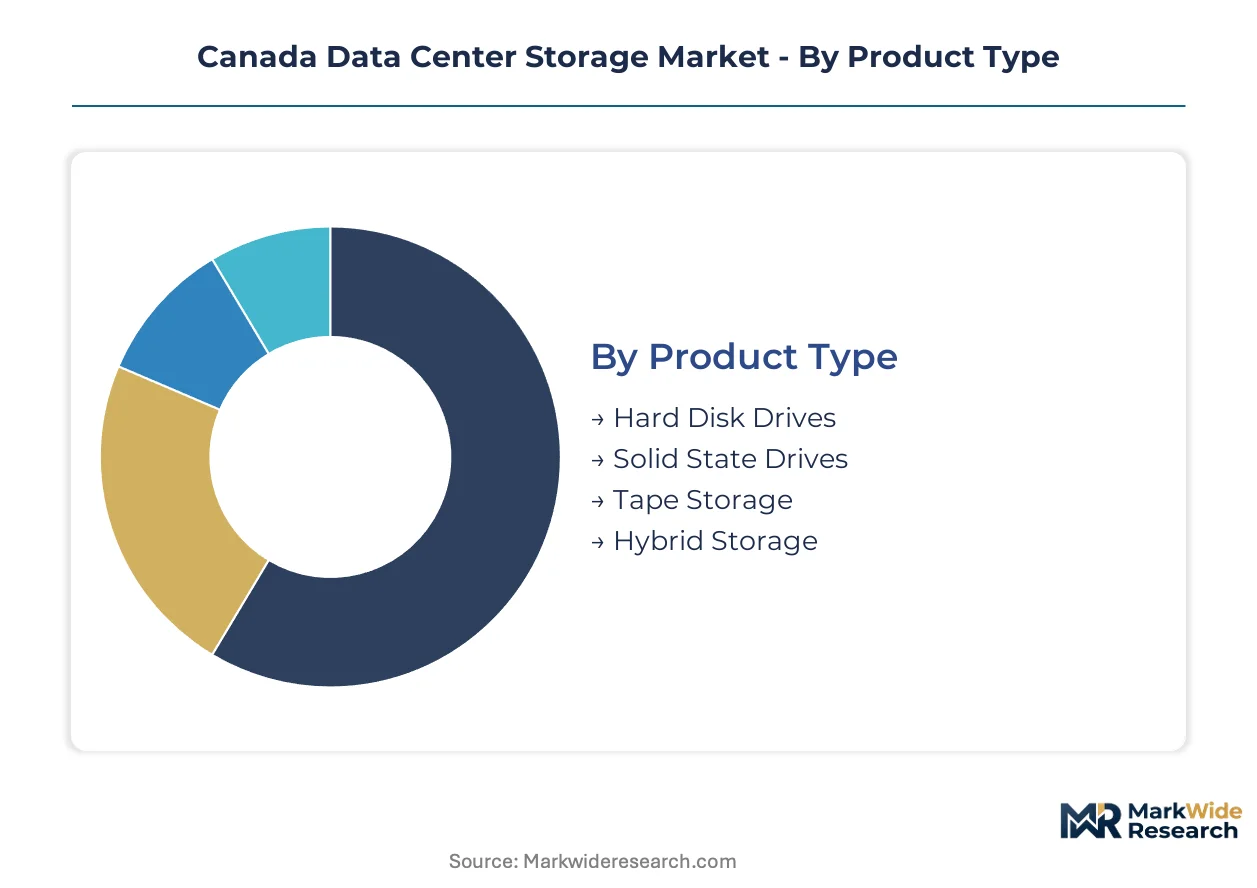
Storage procurement in Canada fragments across media technologies, deployment architectures, and compliance verticals. Each segment carries distinct certification burdens from federal regulators and divergent cost structures that reshape buyer behavior across Toronto financial corridors and provincial health networks.
Product Type:
FIPS 140-2 Level 3 certification applies to solid-state and hybrid arrays destined for Shared Services Canada contracts, while tape systems face less stringent cryptographic requirements under baseline federal guidelines.
- Solid State Drives:NAND-based persistent storage with sub-millisecond latency thresholds. Vector Institute AI partnerships in Toronto drive petabyte-scale NVMe deployments for machine learning pipelines, compressing procurement timelines for high-frequency workloads.
- Hard Disk Drives:Electromechanical magnetic storage dominating cost-per-gigabyte economics. Calgary energy firms maintain extensive HDD footprints for seismic data retention, though flash displacement accelerates in primary tiers.
- Tape Storage:Linear magnetic media for seven-year archival mandates under OSFI guidelines. Cold-storage economics retain dominance despite operational friction in retrieval workflows.
- Hybrid Storage:Tiered architectures combining flash and magnetic media with automated data placement. Mid-market enterprises in southwestern Ontario favor these arrays for unpredictable growth phases without full flash premiums.
Solid State Drives sits at the top of the volume ranking, with Hybrid Storage climbing the fastest.
Technology:
Cost stratification separates enterprise flash deployments from commodity magnetic tiers, with cloud storage commanding premium operational expenditure treatment.
- Flash Storage:NAND-based solid-state technologies including NVMe-oF fabrics. Financial institutions along Bay Street deploy these for OSFI-mandated resilience testing with geographic redundancy requirements.
- Cloud Storage:Distributed object and block services delivered via hybrid deployment models. Federal cloud-first directives accelerate procurement through Shared Services Canada vehicles, displacing traditional capital cycles.
- Magnetic Storage:Rotating media and tape systems for archival retention. Health Canada data residency mandates sustain demand for sovereign magnetic infrastructure in Ontario and Quebec health networks.
- Optical Storage:Write-once media for immutable compliance archives. Limited penetration outside specialized government and legal verticals requiring tamper-proof retention.
Flash Storage commands the highest capital allocation intensity, while Cloud Storage expands most quickly across federal procurement channels.
End User:
Application-specific workloads dictate performance requirements, with financial and healthcare verticals facing the strictest sovereign data controls.
- Financial Services:Tier-one banks and capital markets firms. OSFI B-13 guidelines force geographic redundancy expansions across Toronto and Vancouver metro corridors with compressed procurement timelines.
- Healthcare:Provincial health authorities and hospital networks. Law 25 in Quebec and comparable provincial statutes mandate patient record retention within Canadian borders, driving dedicated storage buildouts.
- Government:Federal agencies and crown corporations. Canadian Centre for Cyber Security baseline controls require hardware security module integration for encryption-at-rest specifications.
- Telecommunications:National carriers and regional ISPs. 5G infrastructure rollouts and subscriber data retention requirements sustain steady capacity demand.
Financial Services occupies the largest procurement volume position, with Healthcare gaining share fastest under data sovereignty enforcement.
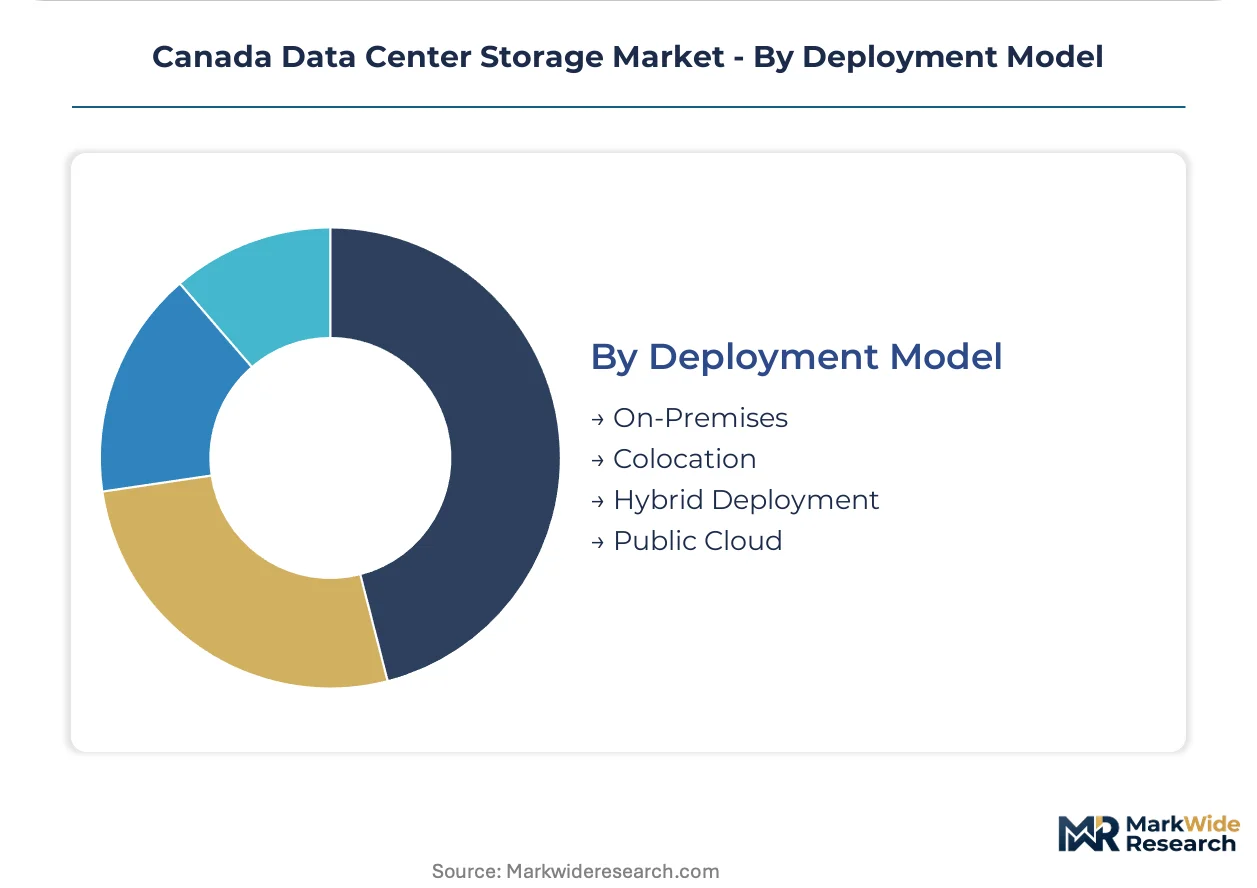
Deployment Model:
Customer type stratification separates hyperscale-ready enterprises from mid-market buyers seeking operational expenditure flexibility without egress complexity.
- Hybrid Deployment:Unified on-premises and cloud-connected architectures. Enterprises struggle to unify PowerScale clusters with AWS Outposts and Azure Stack HCI under single governance policies, creating integration service opportunities.
- Colocation:Third-party data center space with customer-owned or leased storage. 151 Front Street providers in Toronto offer storage-as-a-service with committed use discounts mirroring hyperscale economics.
- On-Premises:Fully captive data center infrastructure. Large manufacturers and resource sector firms maintain these deployments for latency-sensitive operational technology workloads.
- Public Cloud:Hyperscale provider-managed storage services. Federal procurement shifts toward hybrid models temper pure public cloud expansion despite operational simplicity.
Hybrid Deployment leads current infrastructure investment, with Colocation showing the steepest expansion trajectory among mid-market manufacturing verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized storage engineering talent clusters in Toronto and Vancouver anchor Canadian capacity expansion, with provincial data sovereignty mandates fragmenting procurement patterns across Ontario, Quebec, Alberta, and British Columbia corridors.
Ontario
Toronto's financial district drives petabyte-scale flash deployments for OSFI-mandated resilience testing. Health Canada data residency requirements force provincial health networks to maintain sovereign storage infrastructure within Ontario borders. The Vector Institute partnership ecosystem in downtown Toronto accelerates NVMe-oF fabric adoption for AI training clusters.
Quebec
Provincial health authorities execute dedicated storage buildouts under Law 25 patient record retention mandates. Montreal's gaming and visual effects studios demand high-throughput object storage for rendering pipelines. Hydro-Québec's surplus electricity attracts hyperscale colocation providers to Quebec City and Montreal metro corridors.
Alberta
Calgary energy firms maintain extensive HDD footprints for seismic data retention despite flash displacement in primary tiers. The Personal Information Protection Act creates encryption standards that diverge from federal baseline controls. Oilsands operational technology workloads sustain captive on-premises storage deployments.
British Columbia
Vancouver's film production and post-production verticals drive high-performance storage procurement for 4K/8K content workflows. British Columbia's PIPA statute generates breach-notification requirements distinct from Ontario and Quebec frameworks. Submarine cable landing points position Vancouver as a Pacific gateway for latency-tolerant cloud storage expansion.
Atlantic Canada
Newfoundland and Labrador's hydroelectric surplus positions St. John's as an emerging colocation destination for archival workloads. First Nations broadband initiatives create demand for community-controlled storage infrastructure outside provincial jurisdiction. Halifax's submarine cable connectivity supports latency-tolerant object storage deployments for federal government backup tiers.
Canada Data Center Storage Market Competitive Landscape
Capital-heavy array manufacturers compete with software-defined storage designers for enterprise procurement decisions, producing a tiered vendor structure where integrated infrastructure stacks dominate financial services verticals while disaggregated architectures gain traction in research and cloud-native environments. Three strategic archetypes anchor positioning: full-stack infrastructure vendors bundling compute-network-storage portfolios, cloud-connected fabric specialists bridging on-premises and colocation tiers, and consumption-model disruptors replacing capital cycles with subscription economics. Competitive moves concentrate on hybrid cloud integration partnerships and FIPS 140-2 Level 3 certification races for Shared Services Canada eligibility.
Within the full-stack infrastructure tier, Dell Technologies and Hewlett Packard Enterprise occupy positions defined by integrated PowerStore and Alletra portfolio breadth. NetApp represents the cloud-connected fabric archetype through unified data management across distributed environments. Pure Storage exemplifies consumption-model disruption with subscription-based Evergreen structures that compress refresh friction for mid-market buyers.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| IBM |
| NetApp |
| Hitachi Vantara |
| Pure Storage |
| Infinidat |
| Lenovo Group |
| Cisco Systems |
| Others |
Pricing and Supply Chain Analysis
Specialized storage engineering talent concentration in Toronto and Vancouver metro corridors widens labor-cost differentials between tier-one financial deployments and mid-market manufacturing installations, compressing pricing spreads for FIPS-certified arrays against commodity flash tiers.
Pricing Analysis
The bundled-versus-unbundled service split separates integrated infrastructure stacks with multi-year maintenance contracts from disaggregated software-defined deployments sold on consumption metrics. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and geographic redundancy specifications, with FIPS 140-2 Level 3 arrays commanding substantial premiums over baseline encrypted tiers. Pricing pressure stems from NAND supply volatility and hyperscale competitive benchmarking, forcing mid-market vendors toward storage-as-a-service models. Financial institutions along Bay Street exhibit lowest price sensitivity due to regulatory compliance mandates, while southwestern Ontario manufacturers prioritize operational expenditure treatment over capital efficiency.
Supply Chain Analysis
Domestic-content mandates under Shared Services Canada procurement vehicles reshape sourcing toward North American assembly for federal-qualified arrays, though NAND fabrication concentrates in South Korea and Taiwan with controller silicon anchored in the United States. Flash memory wafers, enterprise HDD mechanisms, and hardware security modules constitute critical input dependencies. Single-source vulnerability in advanced NAND nodes exposes Canadian buyers to geopolitical freight disruptions. Distribution runs through Toronto's 151 Front Street colocation corridor and direct OEM channels serving Vancouver financial districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada data center storage represents a late-cycle quality story as OSFI B-13 resilience mandates and Health Canada data residency enforcement shift procurement toward premium-certified configurations with sovereign redundancy architectures.
For Market Incumbents: Deploy consumption-model contracting to counter hyperscale pricing pressure. Dell Technologies and NetApp should expand FIPS 140-2 Level 3 certification races across mid-tier product lines before Shared Services Canada eligibility windows narrow. Channel control through Toronto colocation partnerships defends against software-defined storage entrants targeting hybrid integration complexity pain points. For New Entrants and Emerging Players: Enter via Atlantic Canada hyperscale corridors where Newfoundland hydroelectric surplus and Halifax submarine cable landing points create latency-tolerant archival whitespace. Indigenous data sovereignty frameworks outside provincial jurisdiction offer penetrable governance structures with community-controlled infrastructure mandates. Position around MinIO and Ceph distributed systems expertise to exploit specialized engineering talent scarcity in Montreal and Calgary markets. For Investors and Strategic Acquirers: Cloud-connected fabric specialists are the most active acquirer in this space, seeking unified data management capabilities bridging on-premises and colocation tiers. Long-term viability hinges on hybrid cloud integration moats and federal certification pipelines. Monitor Vector Institute AI partnership announcements as inflection indicators for petabyte-scale object storage demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FIPS 140-2 Level 3 Certification Expansion | Qualifies arrays for Shared Services Canada procurement vehicles and defense contractor eligibility. |
| NVMe-oF Fabric Deployment | Collapses latency between compute and storage layers for Vector Institute AI training clusters. |
| Consumption-Model Contracting | Mirrors hyperscale pricing without egress complexity for southwestern Ontario manufacturing verticals. |
| Atlantic Canada Colocation Buildout | Leverages Newfoundland hydroelectric surplus for latency-tolerant archival workload migration. |
| Indigenous Data Sovereignty Partnerships | Captures community-controlled infrastructure demand outside provincial privacy jurisdiction fragmentation. |
Research Methodology
Bottom-up enterprise workload modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with data center infrastructure architects, storage procurement officers at tier-one banks, Health Canada IT compliance leads, and colocation facility operators in Toronto and Vancouver were cross-validated against secondary sources including Shared Services Canada procurement disclosures, Canadian Centre for Cyber Security guidance documents, OSFI regulatory filings, and hyperscaler capex trajectory reports. Triangulation between demand-side capacity planning and supply-side product certification pipelines ensures segmentation integrity across deployment models and compliance verticals.
Input-output matrices map flash memory supply constraints, labor cost differentials across engineering talent clusters, and regulatory certification timelines to volume and value projections. Segmentation dimensions span media technology, deployment architecture, end-user vertical, and geographic compliance cluster. CAGRs derive from curve-fitting historical procurement cycles against federal cloud-first directive acceleration and provincial data sovereignty enforcement patterns. AI training cluster expansion timelines and OSFI B-13 implementation deadlines constitute industry-specific forecast anchors.
Inputs from federal procurement databases and vendor certification registries were available through the study window; gaps in real-time NAND spot pricing and interprovincial privacy statute harmonization progress introduce uncertainty bands around capacity planning assumptions. Forecasts reflect documented baseline scenarios with sensitivity testing against supply interruption and regulatory delay contingencies. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Life Cycle Services Market
Data Center Infrastructure
Germany Data Center Construction Market
Data Center Infrastructure
New York Data Center Market
Data Center Infrastructure
Malaysia Data Center Rack Market
Data Center Infrastructure
Malaysia Data Center Construction Market
Data Center Infrastructure
Global Data Center Rack Server Market
Data Center Infrastructure
Denmark Data Center Server Market
Data Center Infrastructure
Denmark Data Center Rack Market
Data Center Infrastructure
Global Telecommunication Equipment Cabinet and Racks Market
Data Center Infrastructure
Europe Containerized Data Center Market
Data Center Infrastructure
Converged Infrastructure Market
Data Center Infrastructure
United Arab Emirates Data Center Physical Security Market
Data Center Infrastructure
Nigeria Data Center Power Market
Data Center Infrastructure
Data Center in Japan Market
Data Center Infrastructure
Norway Data Center Networking Market
Data Center Infrastructure
Brazil Data Center Server Market