
 India Data Center Construction Market | 2026-2036
India Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
India Data Center Construction Market Insights
The capability gap between hyperscale-ready engineering firms and conventional contractors is collapsing as power density requirements exceed 50 kW per rack. AdaniConneX leverages its captive energy infrastructure to sustain cost advantages across Gujarat and Maharashtra. Larsen & Toubro anchors large-scale civil and mechanical execution for multiple operators. CtrlS Data Centers differentiates through Tier-IV certified facilities with integrated disaster recovery architecture.
India data center construction encompasses the design, engineering, and build-out of mission-critical facilities housing servers, storage, and networking equipment, typically requiring N+1 redundancy in power and precision cooling to maintain 99.999% uptime. Wholesale and hyperscale types command the dominant share of new capacity as cloud providers pursue single-tenant campuses exceeding 100 MW. Cooling systems and power distribution technologies absorb the largest capital allocations within the technology stack, driven by tropical climate stress and utility grid instability. Colocation and cloud services applications generate the steepest demand curves as enterprises exit captive infrastructure.
BIS standards for electrical safety, CEA regulations on power backup mandates, and state-level data center policies in Maharashtra and Tamil Nadu collectively shape permitting timelines and operational compliance costs. The PLI scheme administered by MeitY further tilts investment toward domestic manufacturing of servers and components. Stakeholders must weigh land acquisition risks against renewable energy procurement timelines when selecting sites.
Market Dynamics
Power density requirements exceeding 50 kW per rack are collapsing the capability gap between hyperscale-ready engineering firms and conventional contractors across India. This structural compression is redrawing competitive boundaries and reshaping capital allocation priorities.
Growth Catalysts
- PLI scheme for IT hardware:MeitY's incentive program redirects domestic capital flows toward server manufacturing and data center infrastructure buildouts.
- BFSI cloud migration:Banking and financial services institutions are accelerating hyperscale campus commitments to replace captive server rooms.
- Maharashtra and Tamil Nadu state policies:Subnational regulatory frameworks streamline permitting timelines and reduce operational compliance costs for new entrants.
Market Restraints
- Land acquisition volatility:Mumbai, Chennai, and Hyderabad face fragmented title records and prolonged negotiation cycles with agricultural landholders.
- Utility grid instability:Tropical climate stress and distribution network congestion force redundant substation investments that inflate project capex.
- Cooling equipment import dependence:Precision HVAC systems and chillers concentrate sourcing from European and East Asian suppliers, exposing timelines to freight bottlenecks.
Strategic Opportunities
- Gujarat renewable energy corridors:Captive solar and wind procurement under state green tariffs enables power cost arbitrage for hyperscale operators.
- Edge computing for manufacturing:Industrial IoT deployments across automotive and electronics clusters create distributed facility demand outside primary metros.
- CEA power backup mandates:Central Electricity Authority regulations on diesel generator phase-out accelerate battery energy storage system integration contracts.
Industry Challenges
- Tier-IV certification expertise scarcity:Uptime Institute accredited design review capacity concentrates in three domestic engineering consultancies, creating queue bottlenecks.
- Mechanical-electrical integration complexity:Tropical humidity specifications and seismic zone IV requirements force custom engineering that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Data Center Construction Market |
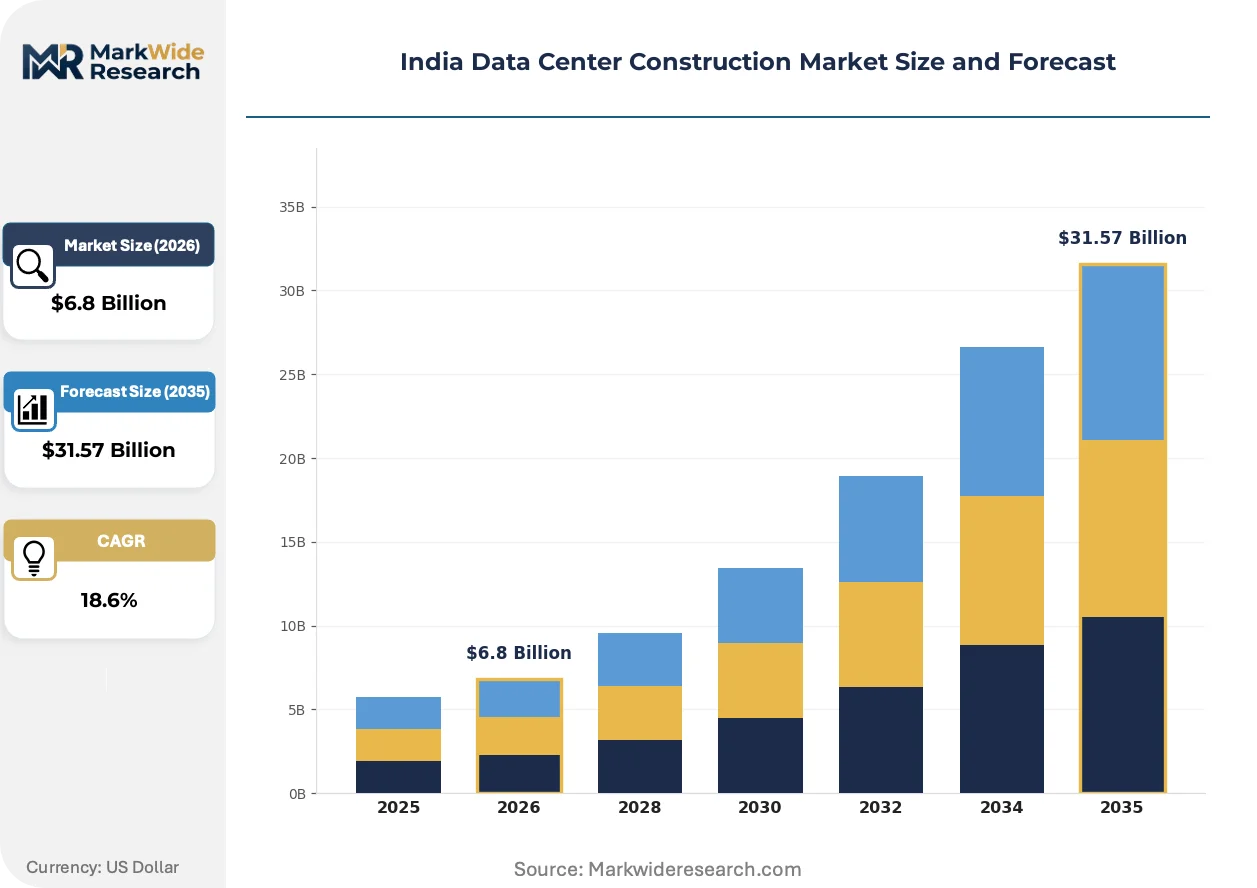
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.57 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Wholesale, Retail, Modular, Hyperscale Technology: Cooling Systems, Power Distribution, Physical Security, Network Infrastructure End User: IT & Telecom, BFSI, Healthcare, Government Application: Cloud Services, Colocation, Disaster Recovery, Managed Hosting |
| Companies Covered | AdaniConneX, STT Global Data Centers India, NTT Communications, CtrlS Data Centers, Equinix, Nxtra Data Limited, Sify Technologies, Larsen & Toubro, AECOM, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Data Center Construction Market Trends and Innovations
Liquid cooling architectures and renewable energy procurement models are actively compressing operating cost structures for Indian hyperscale operators. These shifts are reconfiguring vendor relationships and site selection criteria.
Direct-to-chip liquid cooling is displacing traditional air-cooled precision HVAC in new builds exceeding 30 MW capacity. Cloud providers and colocation operators are adopting this technology to manage rack densities above 50 kW without mechanical refrigeration penalties. This transition is displacing incumbent chiller manufacturers from the critical load path and elevating specialized fluid systems vendors.
CEA regulations on captive power plant emissions and renewable purchase obligations are tightening operational compliance thresholds. The rules mandate progressive diesel generator displacement through battery storage and grid-connected solar. Maharashtra-based hyperscale campuses are responding with behind-the-meter solar plus storage configurations that exceed 40% of facility load.
Enterprise procurement of wholesale data center space is consolidating toward long-term lease structures with embedded renewable energy certificates. Financial services and e-commerce verticals are displacing shorter-term colocation contracts with 10-15 year commitments tied to carbon neutrality milestones. This pattern is most visible in Mumbai's Navi Mumbai and Thane submarkets where land scarcity intensifies tenant competition.
India Data Center Construction Market Segmentation
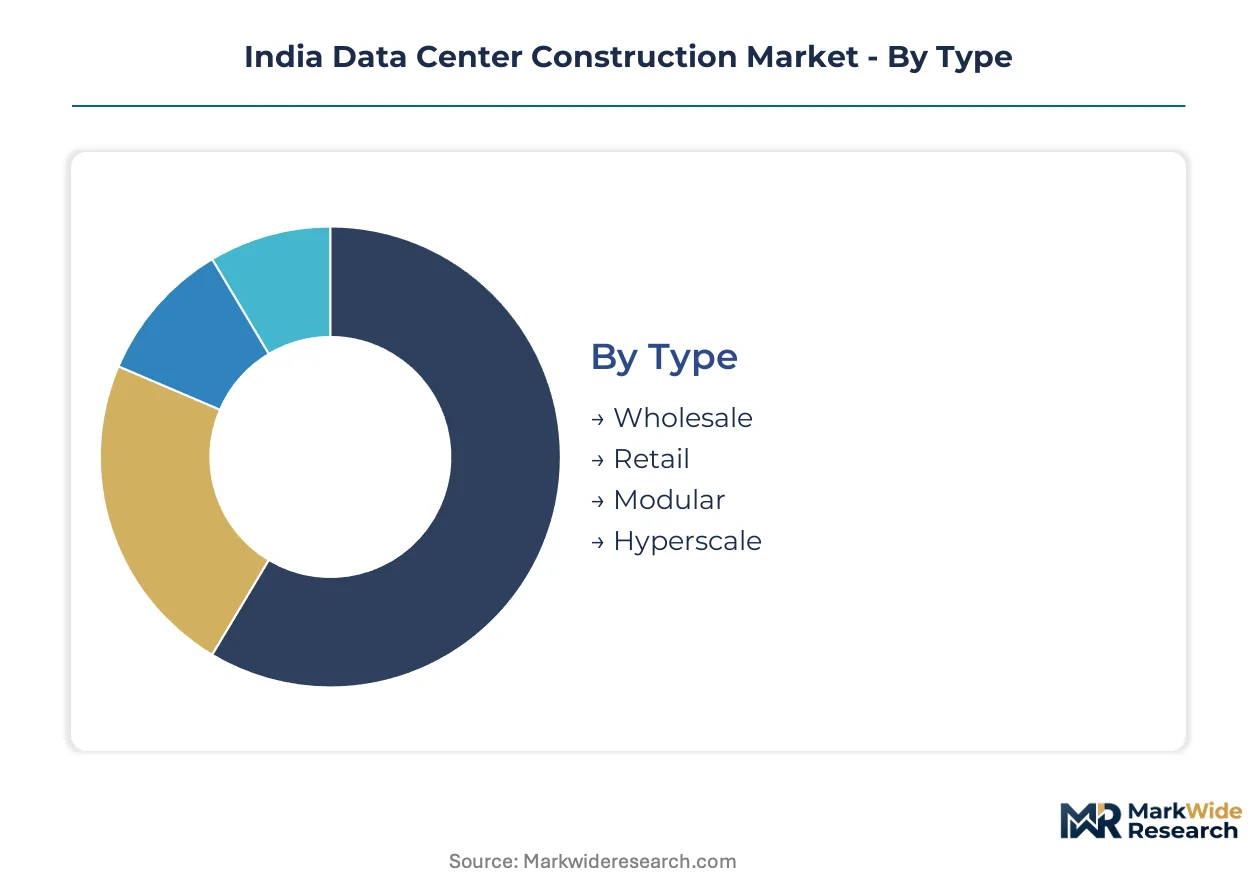
Facility type and technology stack determine capital deployment patterns across India's data center construction pipeline. End-user verticals and application workloads shape site selection, power density specifications, and compliance architecture.
Type:
Wholesale and hyperscale campuses flow through direct operator-developer relationships, while retail and modular deployments concentrate in channel partnerships with regional system integrators.
- Wholesale:Single-tenant facilities exceeding 10 MW with dedicated substations and custom mechanical infrastructure. Mumbai's Navi Mumbai corridor anchors demand from cloud providers seeking contiguous land parcels for 100+ MW campuses. State-level data center policies in Maharashtra compress permitting timelines for these anchor investments.
- Hyperscale:Purpose-built campuses designed for 50+ kW per rack densities with liquid cooling readiness and renewable energy procurement integration. Hyderabad and Chennai clusters concentrate commitments from international cloud operators under PLI scheme incentives.
- Retail:Multi-tenant facilities with standardized rack configurations and shared mechanical systems. Tier-II cities see rising demand from mid-market enterprises exiting captive server rooms.
- Modular:Prefabricated power and cooling modules enabling rapid deployment in edge locations. Manufacturing corridors in Gujarat and Tamil Nadu drive adoption for industrial IoT latency requirements.
Wholesale dominates installed base. Hyperscale is where expansion concentrates.
Technology:
Capital allocation across the technology stack tracks power density escalation and tropical climate stress, with cooling and power systems commanding priority spend.
- Cooling Systems:Precision HVAC, chillers, and emerging direct-to-chip liquid cooling architectures. Rack densities above 50 kW in Mumbai and Chennai campuses are displacing air-cooled designs and elevating specialized fluid systems vendors.
- Power Distribution:Medium-voltage switchgear, UPS systems, and busbar trunking with N+1 redundancy. CEA regulations on diesel generator phase-out accelerate battery energy storage integration across Maharashtra facilities.
- Physical Security:Biometric access control, perimeter detection, and blast-resistant architecture. BFSI tenants in Mumbai mandate Tier-IV compliant security layers with integrated disaster recovery protocols.
- Network Infrastructure:Fiber termination, cross-connects, and software-defined networking fabric. Cloud services applications in Hyderabad drive demand for diverse carrier connectivity and low-latency interconnection.
Cooling systems absorb the largest share of technology capex. Power distribution is climbing fastest as grid instability forces redundant substation investments.
End User:
Procurement patterns diverge sharply between regulated verticals requiring certified facilities and growth sectors prioritizing scale and cost arbitrage.
- IT & Telecom:Domestic cloud providers and telecommunications operators building captive infrastructure. TRAI policy frameworks on data localization accelerate server farm construction for content delivery networks.
- BFSI:Banking and financial services institutions migrating from captive server rooms to hyperscale colocation. RBI guidelines on business continuity and disaster recovery mandate Tier-III minimum certification for primary data centers.
- Healthcare:Hospital networks and health insurers deploying HIPAA-equivalent infrastructure for electronic medical records. CDSCO data integrity requirements shape validation protocols for facility commissioning.
- Government:Central and state agencies building sovereign cloud capacity under MeitY directives. State data center policies in Tamil Nadu streamline land acquisition for public-sector campuses.
IT & Telecom anchors current capacity. BFSI is expanding most quickly as cloud migration accelerates.
Application:
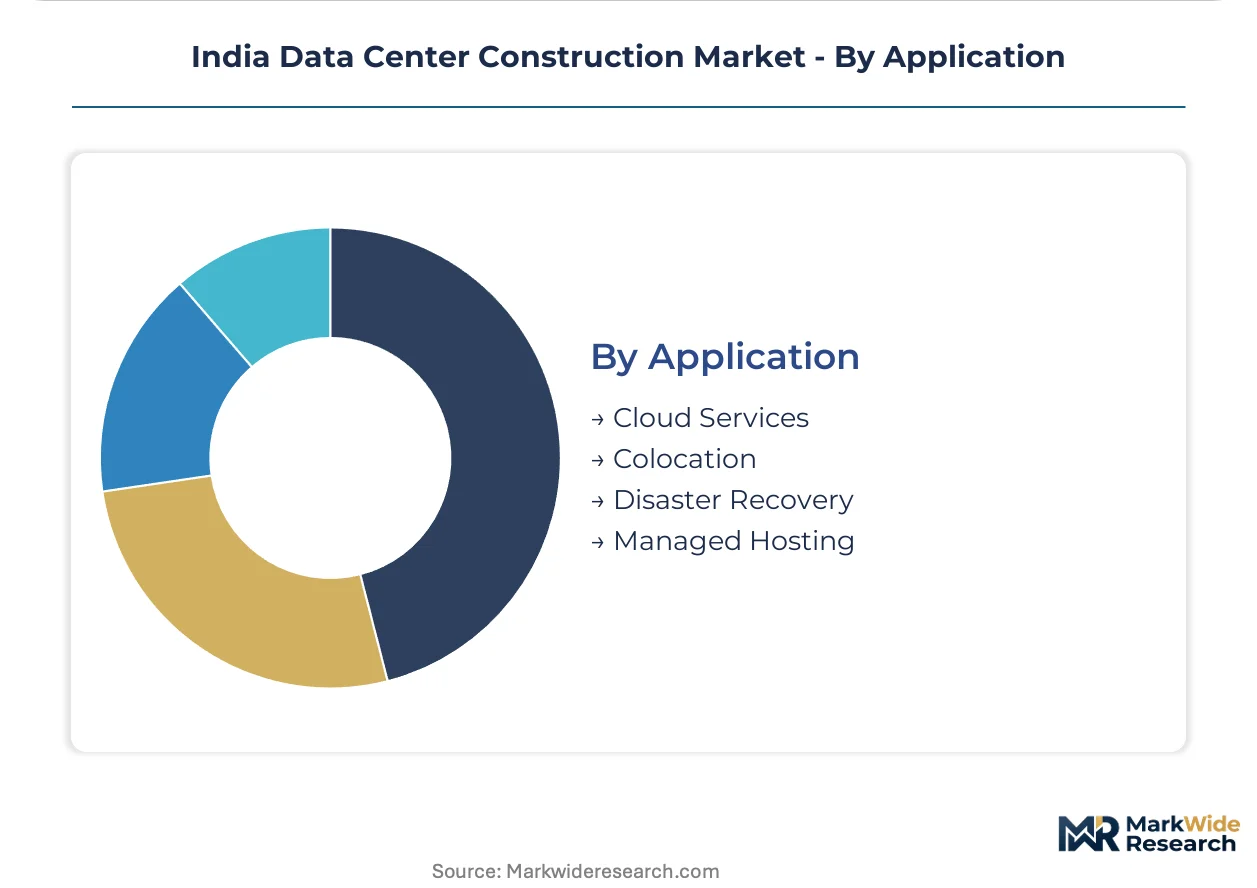
Workload characteristics determine facility design parameters, with cloud and colocation driving hyperscale specifications while disaster recovery mandates geographic diversity.
- Cloud Services:Public and private cloud infrastructure requiring elastic power and cooling scalability. Wholesale commitments from international operators concentrate in Mumbai, Chennai, and Hyderabad clusters.
- Colocation:Multi-tenant facilities where enterprises lease rack space and cross-connects. Long-term lease structures with embedded renewable energy certificates are displacing shorter-term contracts in Mumbai submarkets.
- Disaster Recovery:Secondary sites with synchronous replication capabilities and seismic zone separation. CtrlS Tier-IV certified facilities with integrated DR architecture capture premium positioning.
- Managed Hosting:Operator-managed infrastructure for enterprises lacking internal platform expertise. Mid-market demand in Pune and Bengaluru drives retail colocation expansion.
Cloud services command the dominant share of new capacity. Disaster recovery is gaining share fastest as BFSI compliance mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Land scarcity in Mumbai commands 40-60% construction cost premiums over Chennai and Hyderabad, redistributing hyperscale investment flows toward southern and western corridors. This pricing asymmetry is compressing development timelines in secondary clusters while extending permitting queues in the financial capital.
Maharashtra
Navi Mumbai and Thane submarkets anchor cloud provider demand for 100+ MW contiguous campuses. The state's data center policy streamlines single-window clearances and offers stamp duty exemptions for IT infrastructure investments. MMRDA's planned metro extensions are improving last-mile connectivity to emerging hyperscale zones.
Tamil Nadu
Chennai's submarine cable landing stations attract international cloud operators seeking low-latency Asia-Pacific connectivity. The state's data center policy mandates renewable energy procurement targets and fast-track environmental approvals. Sriperumbudur-Oragadam industrial corridor is emerging as a preferred location for disaster recovery facilities serving BFSI tenants.
Telangana
Hyderabad's HITEC City and upcoming Pharma City extensions concentrate hyperscale commitments under PLI scheme incentives. The state's data center policy offers 100% electricity duty exemption for captive power generation. Fab City and Genome Valley adjacencies are creating hybrid cloud-HPC facility demand from life sciences and semiconductor verticals.
Gujarat
GIFT City's international financial services zone drives Tier-III minimum certification requirements for trading infrastructure. The state's green tariff regime enables behind-the-meter solar procurement at 30-40% discount to grid tariffs. Dholera Special Investment Region is attracting edge computing deployments for manufacturing IoT across the Delhi-Mumbai Industrial Corridor.
Karnataka
Bengaluru's Whitefield and Electronic City clusters see retail colocation expansion serving mid-market SaaS enterprises. The state's EV and semiconductor policies are redirecting data center investment toward Mysuru and Hubli-Dharwad for land cost arbitrage. KIADB's industrial parks offer plug-and-play substation infrastructure reducing commissioning timelines.
India Data Center Construction Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across India's data center construction value chain. The market structures around three tiers: integrated infrastructure conglomerates with captive energy assets, specialized engineering contractors with hyperscale delivery track records, and global colocation operators importing standardized designs. Strategic moves concentrate on renewable energy procurement partnerships and mechanical-electrical design-build contracts for liquid cooling readiness.
Within the integrated infrastructure tier, AdaniConneX leverages captive solar and transmission assets across Gujarat and Maharashtra. Larsen & Toubro anchors large-scale civil and mechanical execution for multiple operators through its construction division. CtrlS Data Centers occupies a specialist position in Tier-IV certified facilities with integrated disaster recovery architecture.
| Leading Market Players |
|---|
| AdaniConneX |
| STT Global Data Centers India |
| NTT Communications |
| CtrlS Data Centers |
| Equinix |
| Nxtra Data Limited |
| Sify Technologies |
| Larsen & Toubro |
| AECOM |
| Others |
Pricing and Supply Chain Analysis
BIS electrical safety certification and Uptime Institute Tier-IV accreditation simultaneously gate supplier qualification and stratify price premiums across India's data center construction market. These dual compliance thresholds compress vendor pools while amplifying spreads between certified and uncertified engineering capacity.
Pricing Analysis
Configured-to-order hyperscale campuses command 35-50% premiums over standardized retail colocation builds. Pricing stratifies across Tier-IV certified, Tier-III compliant, and uncertified facility tiers, with certification level and captive renewable energy integration as primary differentiation drivers. Cost compression in retail colocation is intensifying because mid-market enterprises are consolidating procurement toward wholesale commitments. Hyperscale cloud providers exhibit lowest price sensitivity; mid-market SaaS enterprises show highest.
Supply Chain Analysis
Freight bottlenecks at Singapore and Jebel Ali ports choke precision HVAC and medium-voltage switchgear deliveries to Indian project sites. Supply draws from Germany, Japan, and South Korea for chillers, UPS systems, and specialized fluid cooling components. Single-source vulnerability concentrates in European chiller manufacturers serving tropical climate specifications. Distribution runs through EPC contractors with direct operator-developer relationships rather than open distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's data center construction market sits in early-cycle recovery as PLI scheme capital commitments accelerate buildout velocity. BFSI cloud migration and hyperscale campus commitments provide cyclical momentum through the projection horizon.
For Market Incumbents: Secure captive renewable energy procurement contracts ahead of CEA diesel generator phase-out deadlines. Anchor Tier-IV certification capacity with Uptime Institute-accredited engineering consultancies before queue bottlenecks extend commissioning timelines. Vertical integration into behind-the-meter solar plus storage configurations defends margin position against grid instability cost inflation.
For New Entrants and Emerging Players: Anchor in Gujarat's green tariff corridors where land cost arbitrage and renewable procurement discounts offset Mumbai's connectivity premiums. Target edge computing deployments in Dholera Special Investment Region and Tamil Nadu manufacturing corridors where industrial IoT latency requirements outpace hyperscale supply. Pursue channel partnerships with regional system integrators rather than direct operator competition.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed hyperscale developers holding Maharashtra and Telangana land banks but lacking integrated energy infrastructure. Five-to-ten year viability hinges on renewable procurement execution and liquid cooling readiness. Watch CEA regulatory tightening on captive power emissions as the inflection signal for battery storage integration mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Architecture Deployment | Direct-to-chip systems from specialized fluid vendors displace incumbent chiller manufacturers in 50+ kW rack densities. |
| Behind-the-Meter Solar Plus Storage Integration | Maharashtra hyperscale campuses exceed 40% facility load through CEA-mandated diesel displacement programs. |
| Tier-IV Certification Investment | Uptime Institute accreditation captures BFSI premium pricing under RBI business continuity mandates. |
| Edge Computing Facility Development | Modular prefabricated deployments in Gujarat and Tamil Nadu manufacturing corridors address industrial IoT latency requirements. |
| Long-Term Renewable Energy Procurement | 10-15 year lease structures with embedded certificates displace short-term colocation contracts in Mumbai submarkets. |
Research Methodology
A spread of perspectives from hyperscale facility operators, EPC contractors, Uptime Institute-accredited engineering consultants, and state nodal agency officials converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through MeitY PLI scheme disclosures, CEA regulatory filings, and state data center policy documents. Bottom-up project pipeline aggregation triangulated against top-down capital expenditure tracking across the analysis window.
Facility type, technology stack, end-user vertical, and application workload dimensions structured the analytical framework. CAGRs derived from weighted capacity addition curves and per-MW construction cost trajectories across the projection horizon. Hyperscale power density escalation and renewable procurement integration timelines served as industry-specific forecast inputs.
Material uncertainties — land acquisition volatility, utility grid instability, and cooling equipment import bottlenecks — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as CEA regulatory phase-out schedules and PLI scheme incentive revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Europe Data Center Rack Market
Data Center Infrastructure
Mumbai Data Center Market
Data Center Infrastructure
Malaysia Data Center Rack Market
Data Center Infrastructure
US Data Center Construction Market
Data Center Infrastructure
Taiwan Data Center Server Market
Data Center Infrastructure
Philippines Data Center Market
Data Center Infrastructure
Shanghai Data Center Market
Data Center Infrastructure
Germany Data Center Power Market
Data Center Infrastructure
Australia Data Center Physical Security Market
Data Center Infrastructure
Russia Data Center Rack Market
Data Center Infrastructure
Indonesia Enterprise Network Infrastructure Market
Data Center Infrastructure
Germany Data Center Physical Security Market
Data Center Infrastructure
Philippines Data Center Power Market
Data Center Infrastructure
Belgium Data Center Physical Security Market
Data Center Infrastructure
Data Center Blade Server Market
Data Center Infrastructure
Israel Data Center Rack Market