
 Middle East Commercial Vehicles Lubricants Market | 2026-2036
Middle East Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Commercial Vehicles Lubricants Market Foresight
Modular service bundling is pivoting how fleet operators procure lubricants across the Middle East. Royal Dutch Shell Plc leverages its integrated supply chain to offer predictive maintenance packages alongside bulk oil deliveries. Petromin Corporation anchors Saudi Arabia's aftermarket through its nationwide retail network and OEM partnerships. TotalEnergies differentiates via high-performance synthetic formulations tailored to desert operating conditions.
Middle East commercial vehicles lubricants encompass refined petroleum-based and synthetic formulations engineered to reduce friction, dissipate heat, and prevent wear in diesel and natural gas engines operating under extreme thermal loads, with viscosity grades typically ranging from SAE 15W-40 to SAE 5W-30 for heavy-duty applications. Engine Oil commands the largest revenue share due to mandatory drain intervals tied to OEM warranty requirements across heavy-duty truck fleets. Fleet Operators represent the fastest-growing end-user category as Saudi and UAE logistics companies consolidate vehicle pools under centralized maintenance contracts. Construction Equipment applications face margin pressure from intermittent utilization patterns that extend oil change cycles beyond standard intervals.
Saudi Arabia's SFDA and the UAE's MOHAP enforce product quality standards that align with API CK-4 and FA-4 specifications, while Gulf Standardization Organization harmonization pushes regional conformity assessment for lubricant imports. The transition to lower-sulfur diesel under Gulf environmental protocols is accelerating demand for compatible high-alkalinity reserve engine oils. Stakeholders must monitor how Saudi Vision 2030 infrastructure spending reshapes fleet composition and lubricant procurement centralization across state-linked transport entities.
Market Dynamics
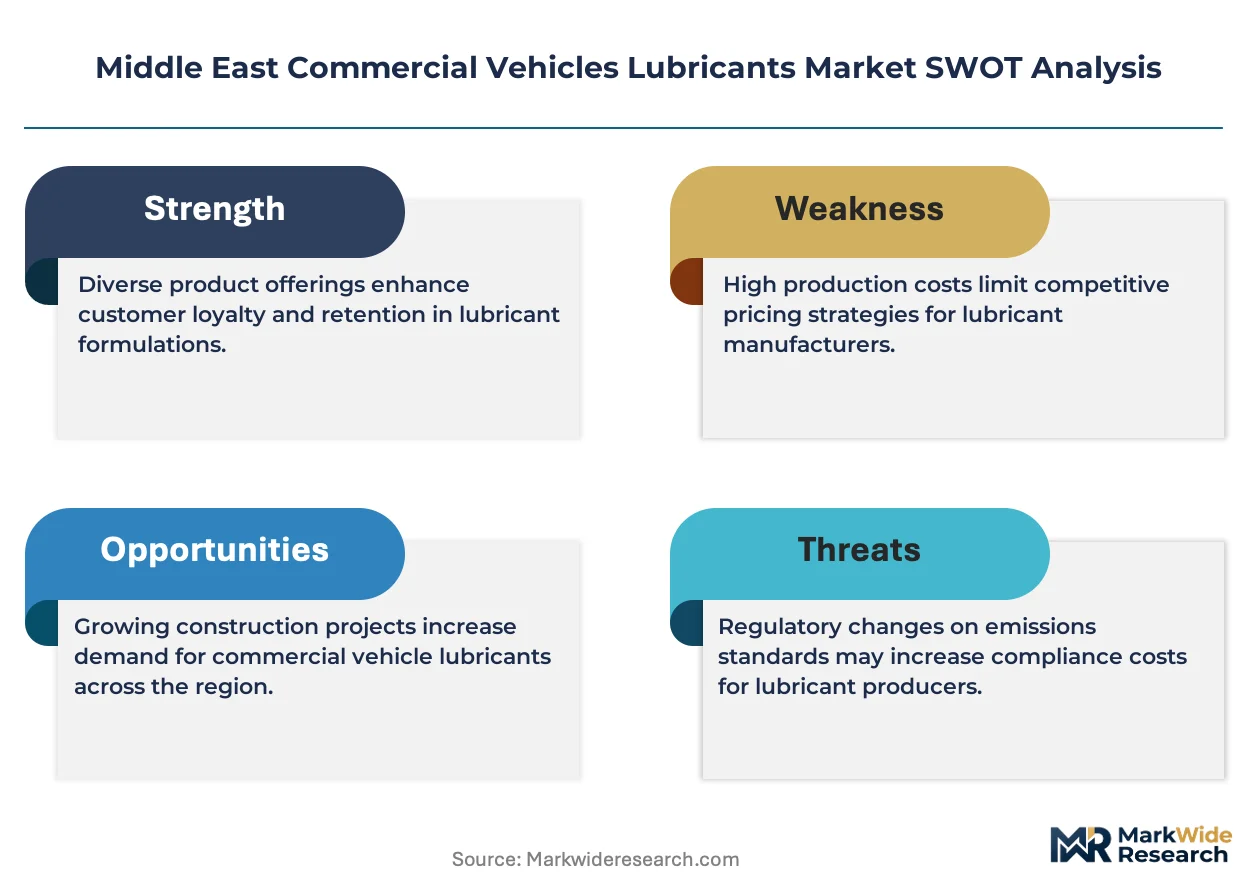
Gulf-wide sulfur reduction mandates are compressing engine oil specifications and forcing fleet operators to accelerate drain interval compliance across Saudi Arabia's logistics corridors and the UAE's commercial transport hubs.
Growth Catalysts
- API CK-4/FA-4 Alignment:Gulf Standardization Organization harmonization is pulling import conformity assessments toward unified heavy-duty diesel engine standards, reducing regulatory friction for cross-border lubricant trade.
- Fleet Consolidation:Saudi Vision 2030 infrastructure spending is centralizing vehicle pools under state-linked transport entities, aggregating procurement volumes and standardizing maintenance protocols.
- Desert Operating Conditions:Extreme thermal load requirements in the UAE's Jebel Ali corridor are driving specification upgrades toward high-alkalinity reserve formulations that extend equipment life under stress.
Market Restraints
- Base Oil Supply Concentration:Regional dependence on Group II/III base stock imports from Asian refiners exposes blenders to freight cost volatility and currency fluctuation risk.
- Intermittent Utilization Patterns:Construction equipment operators in Qatar and Kuwait extend oil change cycles beyond OEM warranty intervals, compressing aftermarket revenue per unit.
- SFDA Quality Enforcement:Saudi Arabia's pharmaceutical and food safety regulator applies stringent product registration timelines that delay new formulation launches by 8-14 months.
Strategic Opportunities
- Oman and Bahrain Penetration:Underdeveloped independent aftermarket networks in these markets offer first-mover positioning for integrated service-and-supply contracts.
- Predictive Maintenance Convergence:Telematics platforms and oil condition monitoring sensors are enabling usage-based pricing models that lock in multi-year fleet agreements.
- Natural Gas Engine Formulations:Compressed natural gas adoption in UAE municipal bus fleets is creating demand for specialized low-ash lubricants outside conventional diesel specifications.
Industry Challenges
- Technical Certification Bottlenecks:OEM approval processes for next-generation synthetic blends require 18-24 month field trials, delaying revenue recognition for R&D investments.
- Skills Gap in Condition Monitoring:Fleet maintenance departments lack trained technicians to interpret oil analysis data and optimize drain intervals, limiting value capture from premium products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Commercial Vehicles Lubricants Market |
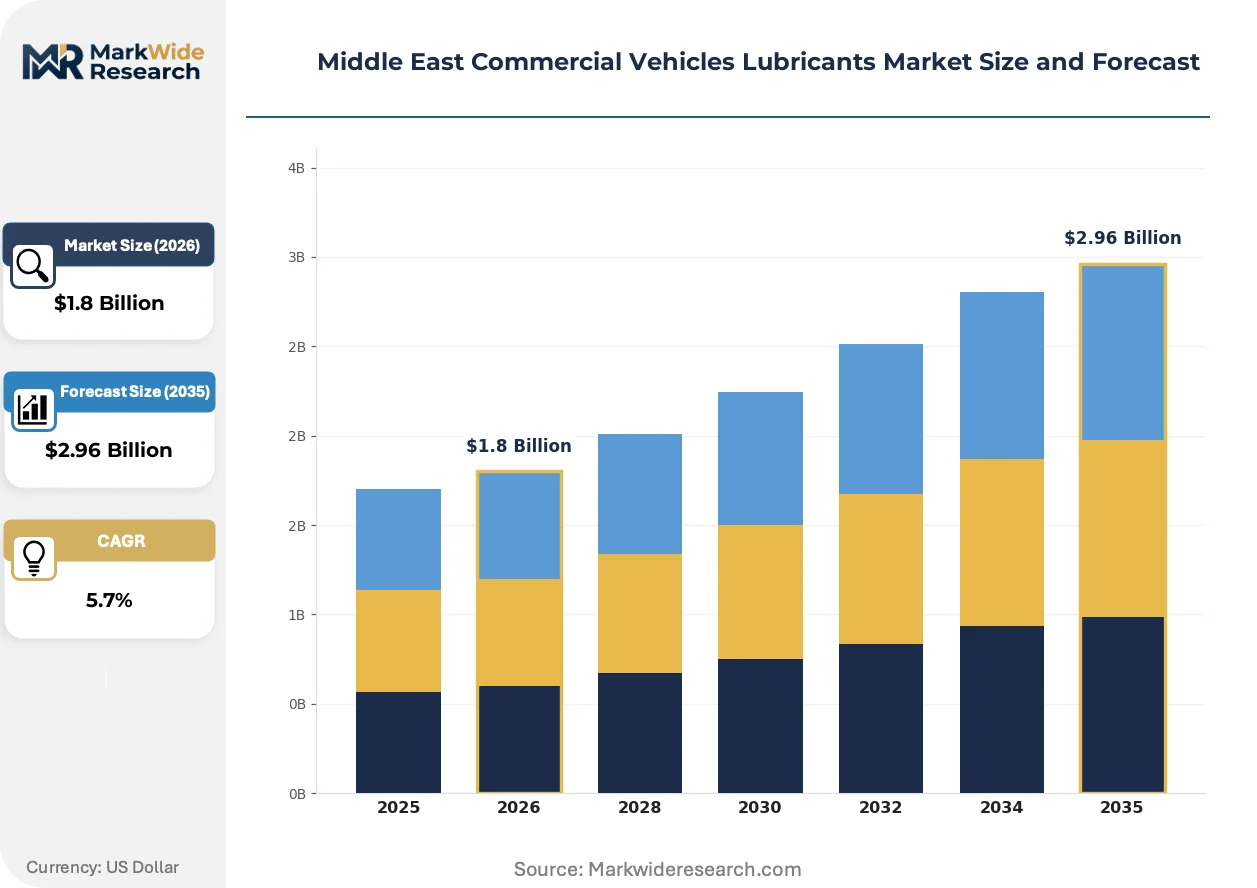
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Hydraulic Oil End User: Fleet Operators, Transport Companies, Construction Firms, Oil & Gas Application: Heavy-Duty Trucks, Buses, Construction Equipment, Agricultural Machinery Distribution Channel: Retail Outlets, Online Stores, Direct Sales, Wholesalers |
| Companies Covered | Petromin Corporation, Behran Oil Company, BP PLC (Castrol), Royal Dutch Shell Plc, TotalEnergies, ExxonMobil Corporation, FUCHS, Aljomaih & Shell Lubricating Oil Company, ENOC (Emirates National Oil Company), Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Commercial Vehicles Lubricants Market Shifts & Advancements
Service bundling architectures are displacing transactional bulk oil sales across Middle East commercial transport, with technology and regulatory forces converging to reshape how lubricant value is delivered and captured.
Synthetic base stock technology is modularizing lubricant formulation design, allowing blenders to customize viscosity-temperature performance for specific engine duty cycles. Heavy-duty fleet operators in Saudi Arabia's Riyadh-Jeddah corridor are adopting these configurable chemistries at accelerated pace. The technology is modularizing supplier-customer relationships into co-engineering partnerships rather than commodity transactions.
Gulf environmental protocols mandating ultra-low sulfur diesel are forcing lubricant alkalinity reserve upgrades to neutralize acidic combustion byproducts. SFDA and MOHAP enforcement of API CK-4 specifications is eliminating legacy CI-4 PLUS inventory from import channels. Engine oil suppliers serving UAE-based transport companies are reformulating high-TBN products to maintain warranty compliance under tightened sulfur caps.
Centralized procurement contracts are consolidating maintenance spend under single-source agreements that bundle lubricants, filters, and predictive diagnostics. Fleet operators across Dubai and Abu Dhabi are displacing spot-market purchasing with multi-year total cost of ownership frameworks. This concentration is most visible in Saudi Arabia's state-linked logistics entities, where procurement authority has shifted from depot managers to regional headquarters.
Middle East Commercial Vehicles Lubricants Market Segmentation
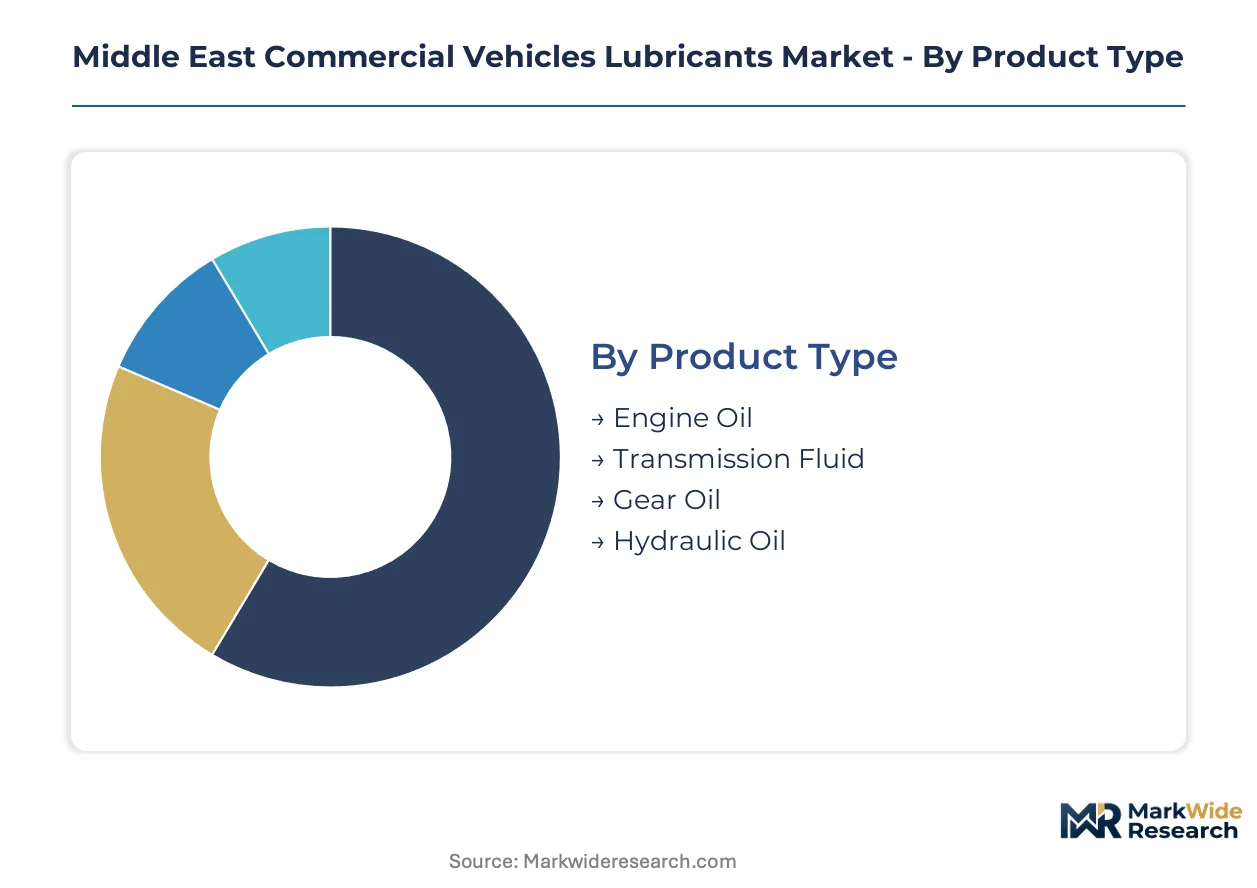
Commercial vehicle lubricant procurement across the Middle East fragments across four distinct dimensions, each reflecting different technical requirements, purchasing authority structures, and margin profiles. Fleet operators and blenders must navigate specification complexity, centralized procurement trends, and channel migration to optimize product-market fit.
Product Type:
Customization intensity varies sharply across this category, from commodity-grade hydraulic fluids to precision-engineered synthetic engine oils requiring OEM certification.
- Engine Oil:Refined petroleum-based and synthetic formulations engineered to reduce friction, dissipate heat, and prevent wear in diesel and natural gas engines. Demand concentrates in Saudi Arabia's logistics corridors where Gulf-wide sulfur reduction mandates tighten specifications toward API CK-4 and FA-4 compliance.
- Transmission Fluid:Specialized lubricants designed for automated manual and fully automatic transmissions in heavy-duty applications. Fleet operators across the UAE's Jebel Ali commercial hub specify these fluids for high-utilization truck fleets operating between Dubai and Abu Dhabi.
- Gear Oil:Extreme-pressure lubricants for differentials and final drives.
- Hydraulic Oil:Anti-wear formulations for construction and agricultural equipment.
Leading the category by volume: Engine Oil. Growing fastest: Transmission Fluid.
End User:
Purchasing sophistication separates this category, from centralized procurement departments to decentralized depot-level buying.
- Fleet Operators:Consolidated vehicle pools under centralized maintenance contracts across Saudi and UAE logistics companies. These entities aggregate procurement volumes and standardize maintenance protocols, displacing spot-market purchasing with multi-year total cost of ownership frameworks.
- Transport Companies:Regional and long-haul operators with mixed fleet ages and duty cycles. Procurement authority has shifted from depot managers to regional headquarters in state-linked entities, bundling lubricants with filters and predictive diagnostics.
- Construction Firms:Intermittent utilization patterns extend oil change cycles beyond OEM warranty intervals.
- Oil & Gas:Remote site operations with captive maintenance capabilities and bulk storage infrastructure.
Volume leadership: Fleet Operators. Steepest expansion trajectory: Transport Companies.
Application:
Operating environment severity drives specification divergence across this category.
- Heavy-Duty Trucks:High-mileage diesel engines operating under extreme thermal loads across desert corridors. SFDA and MOHAP enforcement of API CK-4 specifications is eliminating legacy CI-4 PLUS inventory from import channels serving this segment.
- Buses:Municipal and intercity fleets with frequent stop-start cycles. Compressed natural gas adoption in UAE municipal bus fleets is creating demand for specialized low-ash lubricants outside conventional diesel specifications.
- Construction Equipment:Intermittent utilization patterns that extend oil change cycles.
- Agricultural Machinery:Seasonal demand concentrated in Saudi Arabia's agricultural regions.
Heavy-Duty Trucks dominate category volume. Buses are gaining share fastest.
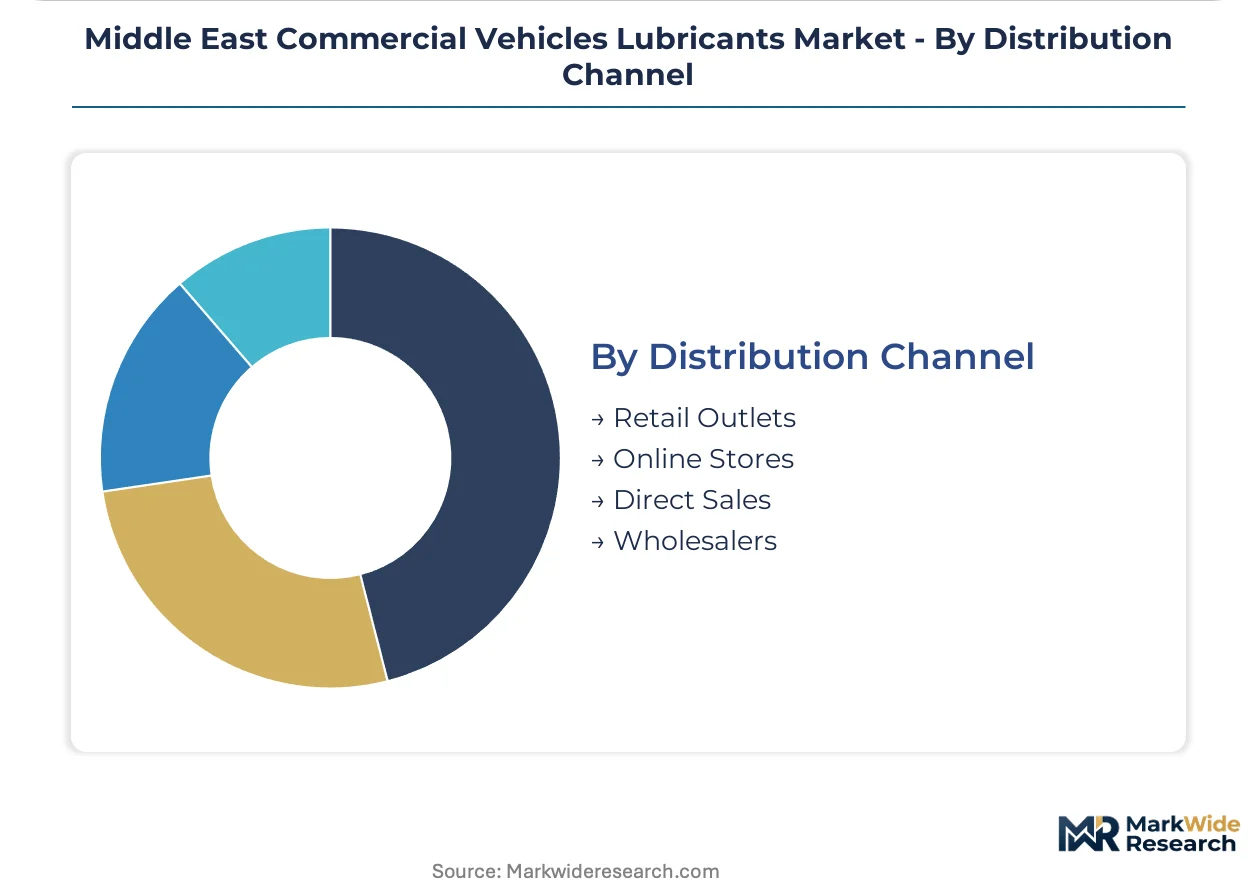
Distribution Channel:
Channel economics reflect customer scale and technical service requirements.
- Direct Sales:Integrated supply chain relationships where blenders offer predictive maintenance packages alongside bulk oil deliveries. Fleet operators across Dubai and Abu Dhabi are consolidating maintenance spend under single-source agreements through this channel.
- Retail Outlets:Nationwide networks anchoring Saudi Arabia's aftermarket through OEM partnerships and technical service capabilities.
- Online Stores:Emerging procurement channel for standardized products.
- Wholesalers:Traditional intermediaries serving fragmented customer bases.
Direct Sales leads category volume. Online Stores are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional lubricant production capacity concentrates in Saudi Arabia and the UAE, yet consumption spreads across Gulf logistics corridors where fleet operators source through centralized procurement contracts.
Saudi Arabia
Riyadh-Jeddah logistics corridors anchor heavy-duty truck fleet density. SFDA enforces API CK-4 and FA-4 specifications that eliminate legacy CI-4 PLUS inventory from import channels. The Eastern Province hosts Petromin Corporation's blending infrastructure serving state-linked transport entities.
United Arab Emirates
Jebel Ali commercial hub processes high-utilization truck fleets operating between Dubai and Abu Dhabi. MOHAP quality standards align with Gulf Standardization Organization harmonization protocols. Dubai's logistics free zones concentrate predictive maintenance service providers bundling lubricants with telematics.
Oman
Muscat-Sohar industrial corridor exhibits underdeveloped independent aftermarket networks. The country's national standards body applies conformity assessment procedures for lubricant imports. Port of Salalah serves as transshipment node for regional base oil flows.
Kuwait
Construction equipment operators extend oil change cycles beyond OEM warranty intervals, compressing aftermarket revenue. Kuwait's national petroleum company maintains captive blending capacity for domestic fleet requirements. Al Ahmadi industrial zone houses bulk storage infrastructure serving oil and gas remote site operations.
Qatar
Intermittent utilization patterns in construction applications delay lubricant consumption per unit. The country's national investment authority directs infrastructure spending through consolidated procurement frameworks. Ras Laffan industrial city concentrates heavy equipment deployed in energy sector logistics.
Middle East Commercial Vehicles Lubricants Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across lubricant formulation and distribution channels. The vendor base organizes around three strategic archetypes: integrated energy majors with captive base oil supply, national champions leveraging domestic retail networks, and independent blenders serving niche specification requirements. Competitive moves concentrate on predictive maintenance service bundling and geographic expansion into underdeveloped Gulf markets.
Among Saudi-based national champions, Petromin Corporation anchors the aftermarket through nationwide retail infrastructure. Royal Dutch Shell Plc exemplifies the integrated energy major archetype with supply chain control spanning base stock through finished lubricant distribution. TotalEnergies occupies a position emphasizing high-performance synthetic formulations engineered for desert thermal loads.
| Leading Market Players |
|---|
| Petromin Corporation |
| Behran Oil Company |
| BP PLC (Castrol) |
| Royal Dutch Shell Plc |
| TotalEnergies |
| ExxonMobil Corporation |
| FUCHS |
| Aljomaih & Shell Lubricating Oil Company |
| ENOC (Emirates National Oil Company) |
| Others |
Supply & Pricing Matrix
Blending technician concentrations in Saudi Arabia's Eastern Province and the UAE's Jebel Ali corridor create labor-cost differentials that widen pricing-tier spreads between premium synthetic formulations and commodity-grade mineral oils across the Middle East commercial vehicles lubricants market.
Pricing Analysis
Margin tightening in economy-grade engine oils reflects Asian Group II/III base stock import dependence and freight cost volatility. Three-tier pricing structure across premium synthetic, standard semi-synthetic, and economy mineral tiers separates buyers by fleet scale and warranty compliance requirements. Cost-down pressure on standard-tier products accelerates because construction equipment operators in Qatar and Kuwait extend drain intervals beyond OEM specifications. Fleet operators with centralized procurement contracts exhibit lowest price sensitivity; independent transport companies in fragmented aftermarket channels exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Singaporean refiners supplying Group II/III base stocks to regional blenders. Manufacturing concentrates in Saudi Arabia's Eastern Province, the UAE's Jebel Ali free zone, and Bahrain's Sitra refinery complex. Raw material dependencies include base oil feedstocks, viscosity index improvers, and detergent additive packages. Tariff exposure on Asian chemical imports creates margin compression risk for non-integrated blenders. Distribution runs through direct sales contracts for fleet operators, retail networks for aftermarket service, and wholesale intermediaries for fragmented construction and agricultural end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East commercial vehicles lubricants market functions as a cost-of-compliance story where SFDA and MOHAP enforcement of API CK-4 specifications creates a barrier-to-entry moat protecting formulation-certified incumbents from unregistered import competition.
For Market Incumbents: Acquire predictive maintenance technology platforms and oil condition monitoring sensor capabilities to defend against telematics-enabled new entrants. Secure backward integration into Group II/III base oil supply through long-term offtake agreements with Asian refiners, reducing currency fluctuation exposure. Certification investment in FA-4 low-viscosity formulations represents the critical lever for capturing Saudi Vision 2030 fleet procurement centralization. For New Entrants and Emerging Players: Begin with underdeveloped independent aftermarket networks in Oman and Bahrain where integrated service-and-supply contracts face minimal incumbent saturation. Target municipal bus fleet operators in the UAE transitioning to compressed natural gas and requiring specialized low-ash lubricants outside conventional diesel specifications. A telematics-partnership go-to-market angle enables usage-based pricing models that lock in multi-year agreements before established blenders adapt. For Investors and Strategic Acquirers: Re-rating potential sits with national champions possessing captive retail infrastructure given Gulf Standardization Organization harmonization accelerating cross-border volume consolidation. Long-term viability favors blenders with OEM approval pipelines and SFDA registration expertise over pure trading operations. Watch API FA-4 adoption rates in Saudi state-linked transport entities as the signal indicating inflection toward low-viscosity synthetic penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Long-term offtake agreements with South Korean refiners reduce freight cost volatility exposure for Saudi blenders. |
| Predictive Maintenance Platform Acquisition | Telematics bundling locks in multi-year fleet contracts across Dubai-Abu Dhabi commercial corridors. |
| API FA-4 Formulation Certification | Low-viscosity synthetic approval captures Saudi Vision 2030 centralized procurement volumes. |
| Geographic Expansion into Oman and Bahrain | First-mover positioning in underdeveloped aftermarket networks before incumbent retail saturation. |
| Natural Gas Engine Lubricant Development | Specialized low-ash formulations address UAE municipal bus fleet transition outside diesel specifications. |
Research Methodology
Multi-period observation of SFDA registration timelines, MOHAP quality enforcement actions, and fleet procurement contract awards anchored the trend analysis, supplemented by interviews with lubricant blending plant managers, fleet maintenance directors at Saudi logistics entities, aftermarket distribution channel partners, and technical R&D directors at additive suppliers. Secondary validation drew from Gulf Standardization Organization harmonization protocols, customs import data for base oil feedstocks, and SEC filings of integrated energy majors. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, application, and distribution channel dimensions.
Segment-weighting approaches applied differential growth assumptions to engine oils versus transmission fluids, fleet operators versus construction firms, and direct sales versus retail channels across the projection horizon. CAGRs derived from regression analysis of historical procurement volume trends, fleet expansion pipelines tied to Saudi Vision 2030 infrastructure spending, and sulfur reduction mandate implementation schedules. Industry-specific forecast inputs included OEM warranty drain interval specifications and Gulf environmental protocol adoption curves.
Underlying measurement precision varies by segment; fleet operator procurement data carries tighter precision than fragmented construction equipment consumption estimates. Forecasts reflect assumptions regarding regulatory enforcement consistency, base oil supply continuity, and fleet consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Neat Cutting Oil Market
Lubricants
Philippines Lubricants Market
Lubricants
Global Grease Cartridges Market
Lubricants
India Lubricants Market
Lubricants
Fire Resistant Fluids Market
Lubricants
Global Lubricant Antioxidants Market
Lubricants
Technical Fluids Market
Lubricants
Hydraulic Oil Additives Market
Lubricants
Global Friction Modifiers Market
Lubricants
Singapore Automotive Lubricants Market
Lubricants
Africa Lubricants Market
Lubricants
Middle East Lubricants Market
Lubricants
Automotive Suspension System Lubricants Market
Lubricants
Lubricated Tracks Market
Lubricants
Germany Lubricants Market
Lubricants
Specialty Lubricants Market