
 Fire Resistant Fluids Market | 2026-2036
Fire Resistant Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Resistant Fluids Market Analysis
REACH is expanding the cost-of-entry calculus for fluid blenders serving European metalworking and power generation customers. ExxonMobil Corporation leverages its integrated synthetic base stock position to supply phosphate ester formulations with certified fire performance. Shell plc anchors its portfolio through specialized water-glycol products engineered for steel mill hydraulics. FUCHS SE differentiates via application-specific technical service tied to rolling mill and foundry operations.
Fire resistant fluids are formulated lubricants engineered to resist ignition and self-extinguish when exposed to open flame or high-temperature metal surfaces, typically achieving flash points above 300°C through phosphate ester, water-glycol, or synthetic ester chemistry. Their primary commercial purpose is to eliminate fire hazards in hydraulic systems operating near molten metal, hot forging equipment, or turbine exhaust zones. Non-water-based fluids dominate margin pools in aerospace and power generation applications where equipment sensitivity limits aqueous alternatives. Water-soluble fluids occupy the fastest-expanding position in automotive stamping and general manufacturing as facilities prioritize lower-cost fire protection upgrades.
EPA oversight of industrial chemical safety in the United States shapes discharge and handling protocols for phosphate ester fluids deployed in steel and aluminum operations. ECHA enforces REACH registration requirements that restrict halogenated additives and mandate toxicity documentation across European supply chains. China's MEE implements dual carbon goals that pressure domestic metal processors toward lower-emission fire resistant formulations. Stakeholders must monitor how diverging chemical safety frameworks between North America, Europe, and Asia reshape formulation standards and sourcing qualifications.
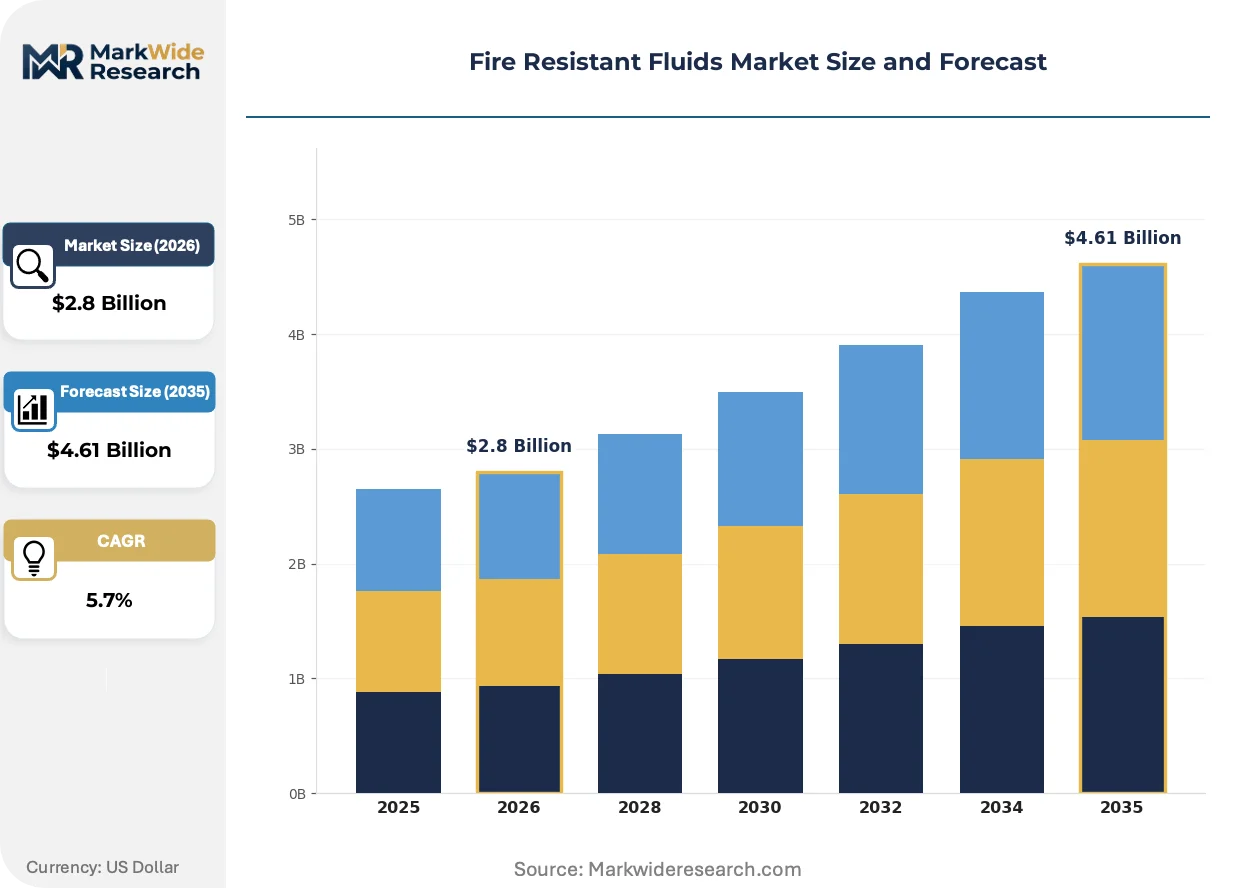
Market Dynamics
Steel mills and aluminum smelters are systematically replacing mineral oil hydraulics with fire-resistant formulations as molten metal proximity regulations tighten and insurance underwriters demand certified fire performance documentation.
Growth Catalysts
- REACH halogen restrictions:ECHA mandates are forcing European metal processors toward phosphate ester and synthetic ester bases, opening formulation contracts for compliant blenders.
- Water-glycol chemistry:Automotive stamping plants are adopting aqueous fire-resistant fluids for cost-effective hydraulic upgrades without full system replacement.
- China MEE dual carbon enforcement:Domestic smelters face emissions penalties that favor lower-carbon synthetic ester formulations over mineral oil basestocks.
Market Restraints
- Phosphate ester feedstock concentration:Synthetic base stock supply clusters among integrated petrochemical majors, limiting independent blender margin flexibility.
- Water-glycol performance ceiling:Aqueous formulations cannot operate above 65°C without vapor pressure complications, excluding high-temperature turbine applications.
- REACH registration cost burden:Small and mid-sized European compounders face documentation expenses that favor larger competitors with dedicated regulatory affairs teams.
Strategic Opportunities
- India metal processing expansion:BIS safety code updates at aluminum and steel facilities are creating first-mover advantage for fire-resistant fluid technical service providers.
- Synthetic ester-aerospace convergence:Next-generation turbine designs tolerate higher fluid temperatures, enabling synthetic ester penetration where phosphate esters previously dominated.
- Digital fluid monitoring integration:IoT sensor deployment at German steel mills is creating bundled service contracts combining fluid supply with real-time fire risk analytics.
Industry Challenges
- Fire safety certification timelines:Factory Mutual and UL testing protocols for new formulations extend 18-24 months, compressing product development cycles.
- Legacy hydraulic system incompatibility:Retrofitting water-glycol fluids into mineral oil-designed pumps requires seal replacement and reservoir modifications that delay facility conversions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Resistant Fluids Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous Film Forming Foam, Chemical Foams, Water-Soluble Fluids, Non-Water-Based Fluids Application: Industrial Processes, Firefighting, Transportation, Aerospace End User: Manufacturing, Oil & Gas, Automotive, Aviation Technology: Conventional Technology, Advanced Technology, Proprietary Systems, Emerging Solutions |
| Companies Covered | ExxonMobil Corporation, Shell plc, Quaker Chemical Corporation, FUCHS SE, TotalEnergies SE, BP plc, Chevron Corporation, BASF SE, Petrofer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Resistant Fluids Market Emerging Trajectories
Formulation chemistry is pivoting toward bio-based synthetic esters and smart fluid monitoring systems that embed fire resistance into broader predictive maintenance architectures.
Synthetic ester base stocks derived from vegetable oil feedstocks are expanding into steel mill hydraulics as drop-in replacements for phosphate esters. German rolling mills are piloting these formulations to satisfy supply chain sustainability audits. The technology is expanding into foundry applications where phosphate ester disposal costs have escalated.
EPA industrial chemical safety oversight is tightening discharge documentation for phosphate ester fluids in US steel and aluminum operations. Facilities must now report handling protocols and containment measures to regional offices. The regulation most affects Great Lakes region smelters where water discharge permits intersect with fire safety compliance.
Buyer consolidation among tier-one automotive stampers is compressing supplier qualification cycles and unbundling fluid supply from equipment maintenance contracts. Mid-sized blenders now compete on technical service attach rates rather than volume pricing alone. This pattern concentrates in Michigan and Ohio manufacturing corridors where stamping plant ownership has consolidated among three major vehicle assemblers.
Fire Resistant Fluids Market Segmentation
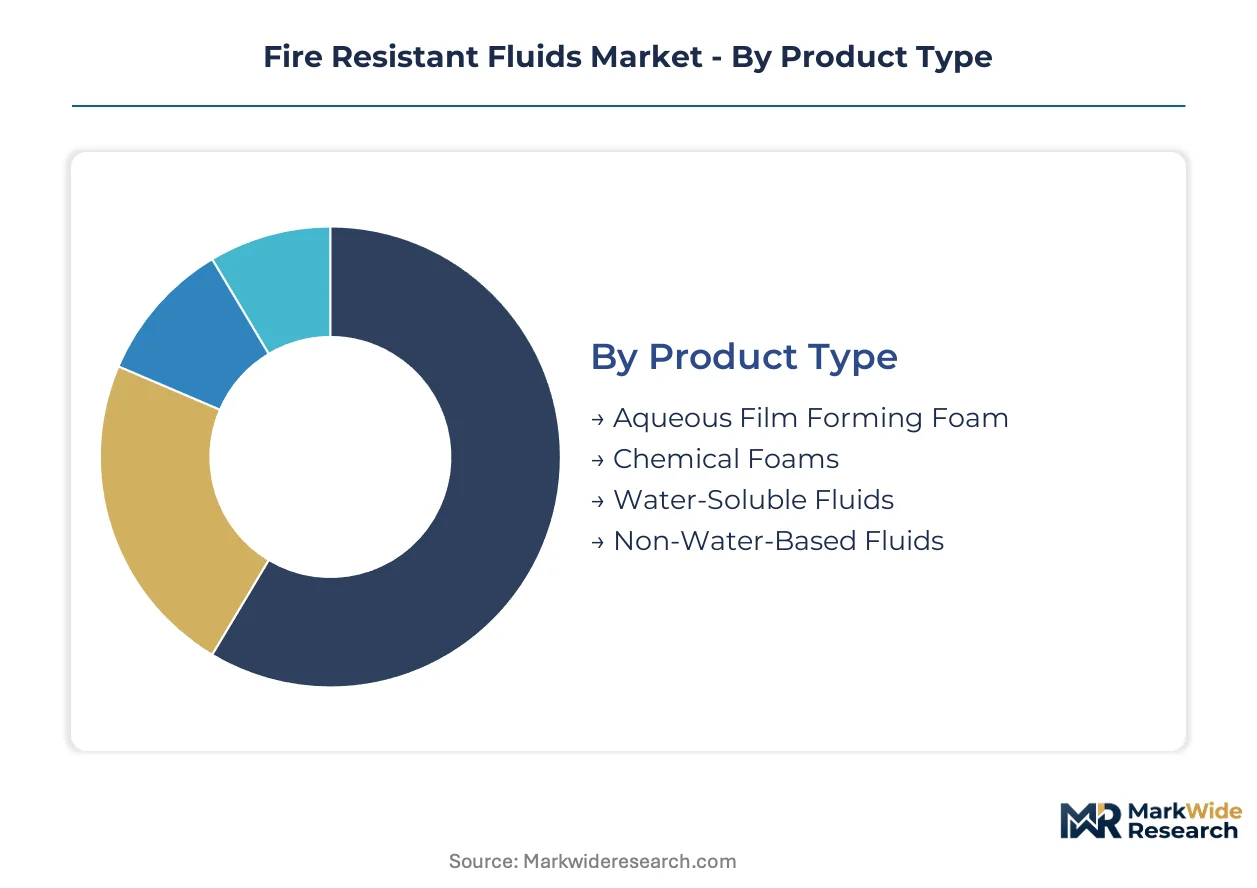
Fire resistant fluids serve radically different operational environments, from molten metal hydraulics to aircraft turbine systems. Segmentation reveals how formulation chemistry, application severity, and end-user compliance requirements fragment procurement patterns across industrial buyers.
Product Type:
Formulation chemistry determines thermal stability limits, disposal protocols, and retrofit compatibility with legacy hydraulic infrastructure.
- Non-Water-Based Fluids:Phosphate ester and synthetic ester formulations dominate high-temperature turbine and aerospace applications where flash points must exceed 300°C. Steel mills in Germany and aluminum smelters in China specify these for molten metal proximity zones where aqueous vaporization risks catastrophic pressure loss.
- Water-Soluble Fluids:Water-glycol blends deliver cost-effective fire protection for automotive stamping presses and general manufacturing hydraulics operating below 65°C. Michigan and Ohio automotive corridors are systematically adopting these for retrofit programs that avoid full pump replacement.
- Aqueous Film Forming Foam:Surfactant-based formulations extinguish pool fires through vapor suppression film formation. Petrochemical storage facilities and aviation fuel farms deploy these in fixed suppression systems.
- Chemical Foams:Protein-based and synthetic foam concentrates generate stable blankets for hydrocarbon fire scenarios. Marine terminals and bulk fuel handling operations specify these for dockside protection.
Mature deployment sits with non-water-based fluids in power generation and aerospace. Newer deployment is concentrated in water-soluble fluids as automotive stampers prioritize cost-contained fire safety upgrades.
Application:
Severity of thermal exposure and regulatory inspection frequency shape specification intensity across operational contexts.
- Industrial Processes:Rolling mills, foundries, and forging operations require continuous hydraulic fire protection adjacent to molten metal pours. EPA discharge documentation requirements in US Great Lakes steel regions are tightening handling protocols for phosphate ester fluids at these facilities.
- Aerospace:Aircraft turbine hydraulics and fuel system fire suppression demand certified formulations meeting SAE AS1241 and OEM qualification protocols. Next-generation engine designs tolerating higher fluid temperatures are enabling synthetic ester penetration where phosphate esters previously dominated.
- Firefighting:Municipal and industrial brigades stock foam concentrates and wetting agents for structural and wildland suppression. Urban interface zones in California and Australia are driving specification for environmentally degradable foam alternatives.
- Transportation:Rail, marine, and heavy vehicle hydraulic systems require portable fire protection without fixed infrastructure. LNG bunkering vessels and electric bus thermal management systems are emerging specification points.
Specification maturity clusters in aerospace with decades of OEM qualification precedent. Fastest specification evolution is occurring in industrial processes as REACH halogen restrictions and dual carbon enforcement reshape European and Chinese formulation requirements.
End User:
Procurement sophistication ranges from centralized technical buying at aviation OEMs to distributed maintenance purchasing at manufacturing plants.
- Manufacturing:Steel, aluminum, and automotive stampers specify fluids through integrated safety and procurement committees. Tier-one automotive ownership consolidation in Michigan and Ohio is compressing supplier qualification cycles and unbundling fluid supply from equipment maintenance contracts.
- Aviation:Airlines and MRO facilities purchase through OEM-approved supplier lists with mandatory batch certification. Boeing and Airbus hydraulic system specifications cascade through their supplier networks.
- Oil & Gas:Upstream platforms and downstream refineries specify foam systems and hydraulic fluids through project engineering contractors. Offshore North Sea and Gulf of Mexico facilities face intensified regulatory scrutiny of foam discharge environmental persistence.
- Automotive:Vehicle assembly plants and component manufacturers operate distinct from stamping operations, with lighter hydraulic loads and lower thermal exposure profiles.
Contract concentration sits with aviation through locked OEM approval systems. Procurement flexibility is expanding fastest in manufacturing as technical service attach rates displace volume pricing in supplier selection.
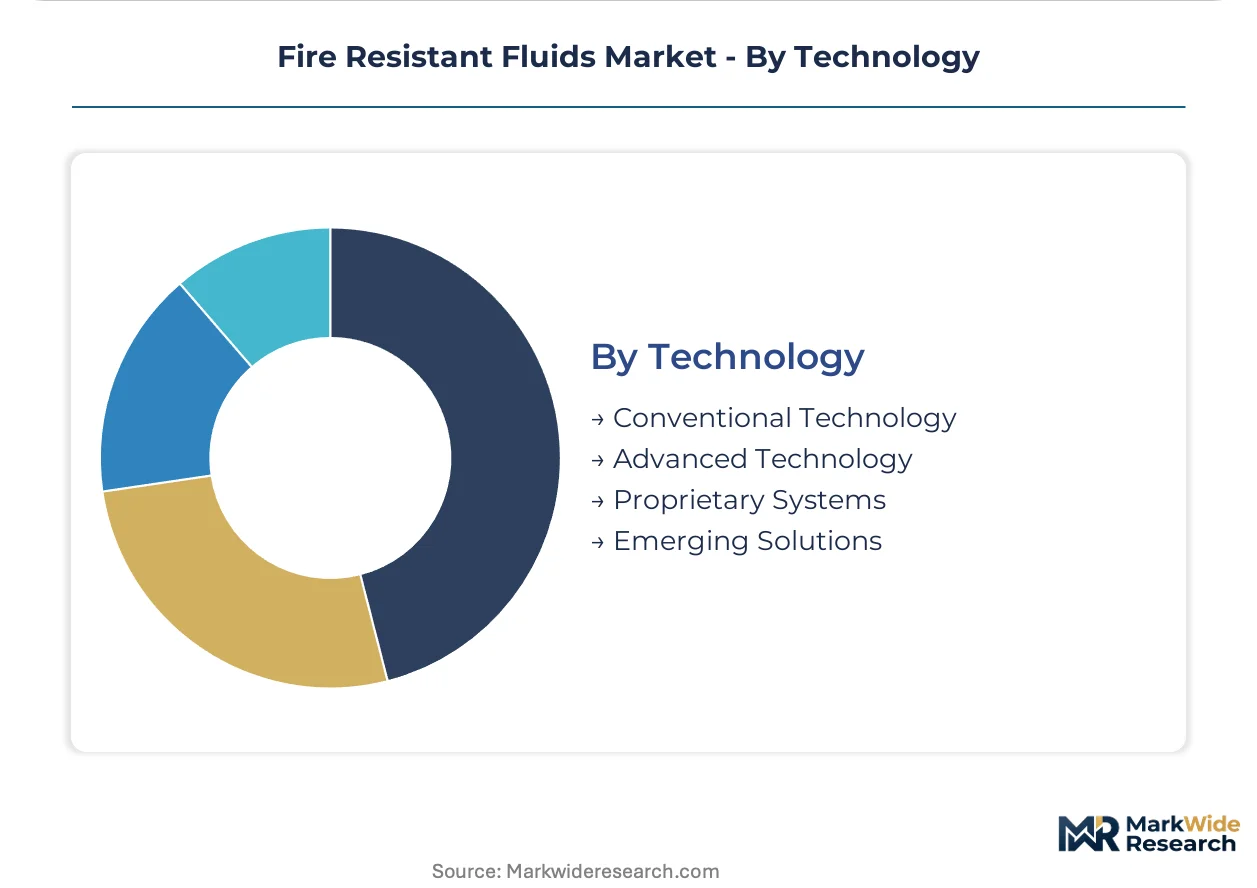
Technology:
Intellectual property protection and integration depth separate technology tiers in this market.
- Advanced Technology:Synthetic ester formulations with bio-based feedstocks and smart additive packages enable predictive maintenance integration. German rolling mills piloting these formulations connect fluid sensors to IoT fire risk analytics platforms.
- Proprietary Systems:Integrated fluid-and-hardware offerings bundle formulation supply with reservoir design, seal specification, and monitoring equipment. Major steel mill rebuild projects in India are specifying these turnkey packages.
- Conventional Technology:Standard phosphate ester and water-glycol formulations without digital integration or sustainability certification. Legacy facilities with minimal capital replacement budgets continue specifying these.
- Emerging Solutions:Experimental bio-fluids and nanofluid thermal management formulations remain in pilot validation. Chinese MEE dual carbon enforcement is accelerating domestic smelter trials of lower-emission alternatives.
Installed base dominance rests with conventional technology in mature industrial corridors. Technology transition is accelerating fastest in advanced technology as sustainability audits and predictive maintenance architectures converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ruhr industrial corridor tax incentives concentrate European fire-resistant fluid demand around German steel modernization clusters. Chinese free-trade zones in Jiangsu and Guangdong accelerate domestic formulation capacity. United States opportunity zones in Michigan and Ohio attract automotive stamper facility upgrades requiring aqueous fire protection systems.
United States
Great Lakes steel mills and Ohio automotive stampers drive phosphate ester and water-glycol procurement. EPA discharge documentation requirements tighten handling protocols for facilities operating near water permits. Michigan manufacturing corridors see supplier consolidation as tier-one automotive ownership compresses qualification cycles.
Germany
Ruhr Valley rolling mills and Bavarian foundries specify synthetic ester formulations for REACH halogen compliance. ECHA registration mandates favor larger blenders with dedicated regulatory affairs capacity. Stuttgart industrial clusters pilot bio-based synthetic esters for supply chain sustainability audits.
China
Jiangsu aluminum smelters and Guangdong metal processors face MEE dual carbon enforcement favoring lower-emission formulations. Domestic synthetic base stock capacity expands to reduce import dependence. Shanghai-Pudong specialty chemical zones attract joint ventures for phosphate ester production.
India
Maharashtra and Gujarat steel mills respond to BIS safety code updates with first-mover fire-resistant fluid adoption. Central government production-linked incentive schemes support domestic blending capacity. Mumbai-Pune industrial belt attracts technical service providers for rolling mill hydraulic conversions.
Japan
Chubu region turbine manufacturers and Kansai aerospace suppliers specify certified formulations meeting JIS thermal stability standards. METI industrial safety guidelines pressure facilities toward predictive maintenance integration. Nagoya manufacturing clusters test IoT-enabled fluid monitoring for fire risk analytics.
Fire Resistant Fluids Market Vendor Landscape
United States and European integrated petrochemical majors anchor one tier; Asian and regional specialists hold formulation and technical service positions. Market structure concentrates around synthetic base stock supply, with phosphate ester feedstock clustering among upstream-integrated players. Three archetypes dominate: integrated oil majors with captive base stock, independent compounders with application expertise, and regional distributors with maintenance bundling. Competitive moves center on sustainability certification acquisition and predictive maintenance service integration.
Within the integrated major tier, ExxonMobil Corporation and Shell plc occupy positions defined by synthetic base stock control and certified fire performance documentation. FUCHS SE exemplifies the independent compounder archetype through technical service attach rates at rolling mill and foundry operations. These three anchors illustrate how supply-side concentration in base stocks shapes competitive positioning across formulation and service layers.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| Quaker Chemical Corporation |
| FUCHS SE |
| TotalEnergies SE |
| BP plc |
| Chevron Corporation |
| BASF SE |
| Petrofer |
| Others |
Supply Flow & Price Mechanics
Phosphate ester feedstock costs cascade through formulation tiers as integrated petrochemical majors leverage captive synthetic base stock supply to command premium positioning for certified fire performance documentation, while independent compounders absorb margin compression from concentrated upstream supply.
Pricing Analysis
Short lead time premiums attach to phosphate ester formulations where Factory Mutual and UL certification documentation compresses supplier flexibility. Three-tier pricing structure across premium, standard, and economy levels separates OEM-qualified aerospace grades from industrial process fluids and unbundled water-glycol commodity supply. Pricing pressure stems from REACH registration cost burdens that favor larger blenders with dedicated regulatory affairs capacity. Tier-one automotive stampers in Michigan and Ohio exhibit highest price sensitivity as ownership consolidation unbundles fluid supply from equipment maintenance contracts, while aerospace OEM procurement through approved supplier lists shows lowest sensitivity to per-unit pricing.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the United States anchor hub-and-spoke patterns for fire-resistant fluid logistics. Synthetic base stock production clusters in Germany, China, and the United States, with phosphate ester feedstock concentrating among integrated petrochemical majors. Raw material dependencies center on phosphorus pentoxide, ethylene oxide derivatives, and vegetable oil feedstocks for bio-based synthetic esters. Single-source vulnerability runs through phosphate ester base stock where upstream integration limits independent blender sourcing alternatives. Distribution runs through authorized distributor networks bundling technical service with fluid supply for steel mill and foundry operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration mandates and ECHA halogen restrictions are forcing consolidation as smaller European compounders exit, leaving technical service capacity and certified formulation portfolios in fewer hands.
For Market Incumbents: Anchor market position through backward integration into synthetic ester base stock production and predictive maintenance service bundling. ExxonMobil Corporation and Shell plc demonstrate how captive phosphate ester supply defends margin structure against feedstock volatility. FUCHS SE's technical service attach rates at rolling mill operations illustrate how application expertise creates switching costs that resist price-only competition from commodity blenders. For New Entrants and Emerging Players: BIS safety code updates in India open a window for technical service providers targeting Maharashtra and Gujarat steel mill hydraulic conversions. White-space concentration sits with bio-based synthetic ester formulations for German sustainability audits and IoT-enabled fluid monitoring systems for Japanese METI predictive maintenance guidelines. Go-to-market execution should prioritize bundled fluid-and-hardware offerings for Indian steel mill rebuild projects where turnkey procurement patterns concentrate specification authority. For Investors and Strategic Acquirers: Factory Mutual and UL testing protocol completion is the leading indicator that formulation portfolios carry durable competitive moats. Long-term viability favors compounders with REACH-registered synthetic ester portfolios and established technical service density in metal processing corridors. Acquisition targets should display integrated regulatory affairs capacity and regional distributor relationships in Germany or China. Monitor ECHA substance evaluation timelines as signals for reformulation contract velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Base Stock | Captive phosphate ester supply insulates margin structure from feedstock concentration among petrochemical majors. |
| REACH Registration Investment | ECHA compliance documentation creates cost-of-entry barriers that eliminate smaller European compounder competition. |
| Predictive Maintenance Service Bundling | IoT sensor integration at German steel mills converts fluid supply into recurring revenue with higher switching costs. |
| Bio-Based Formulation Development | Vegetable oil-derived synthetic esters capture sustainability audit requirements from German rolling mill procurement committees. |
| Joint Venture in Chinese Free-Trade Zones | Shanghai-Pudong specialty chemical partnerships localize phosphate ester capacity for MEE dual carbon enforcement. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plant managers at steel and aluminum facilities, procurement leads at automotive stampers, technical R&D directors at fluid blenders, and distribution channel partners supplied operational validation. Secondary sources included ECHA REACH registration databases, EPA discharge documentation filings, SEC 10-K disclosures from integrated petrochemical majors, and customs import records for phosphate ester base stocks. Bottom-up demand modeling across end-use applications triangulated against top-down supply capacity assessments.
Granularity-level modeling operated at formulation chemistry, application severity, and end-user procurement sophistication dimensions across the analysis window. Segmentation dimensions included product type chemistry, industrial process application, manufacturing versus aviation end-user archetypes, and technology tier integration depth. CAGRs derived from annualized growth rate calculations applied to base year market sizing. Industry-specific forecast inputs incorporated MEE dual carbon enforcement timelines, BIS safety code implementation schedules, and Factory Mutual certification completion rates.
The model assumes a particular technology adoption path; alternative pathways for bio-based synthetic ester penetration would alter the outlook if feedstock cost curves shift or sustainability audit requirements accelerate. Forecasts reflect documented assumptions about regulatory enforcement intensity and metal processing capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Bulgaria Passenger Vehicles Lubricants Market
Lubricants
Global Commercial Vehicles Lubricants Market
Lubricants
Global Hydraulic Fluid Market
Lubricants
Global Grease Market
Lubricants
Indonesia Lubricants Market
Lubricants
Norway Automotive Lubricants Market
Lubricants
Global Lubricant Antioxidants Market
Lubricants
Mining Lubricants Market
Lubricants
Graphite Lubricant Market
Lubricants
Lubricated Tracks Market
Lubricants
Automotive Suspension System Lubricants Market
Lubricants
Norway Lubricants Market
Lubricants
Poland Lubricants Market
Lubricants
Cutting Fluid Market
Lubricants
Plastic Lubricants Market
Lubricants
Firearm Lubricants Market