
 Europe Lubricants Market | 2026-2036
Europe Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Lubricants Market Foresight
Poland's refining corridor is fragmenting as new blending capacity enters service alongside legacy assets in the Rhine-Ruhr region. Shell plc leverages its integrated supply chain from base oil production to retail distribution across Northwestern Europe. TotalEnergies SE anchors its position through specialized synthetic lubricant lines serving French aerospace and automotive OEMs. FUCHS SE competes by dominating the industrial grease segment for German precision machinery manufacturers.
Lubricants are formulated fluids comprising base oils—mineral, synthetic, or bio-derived—and performance-enhancing additives that reduce friction, dissipate heat, and prevent wear in mechanical systems. Viscosity grades, oxidation stability, and pour point specifications determine suitability for engines, transmissions, hydraulic circuits, and open gearing across temperature extremes. Motor oil retains the largest value pool within product type segmentation, though synthetic and bio-based oil categories command premium positioning as OEM drain intervals extend and sustainability metrics tighten. Hydraulic fluid draws structural support from automated manufacturing and construction equipment fleets, while grease occupies niche, high-margin applications in bearings and sealed components where relubrication access is limited.
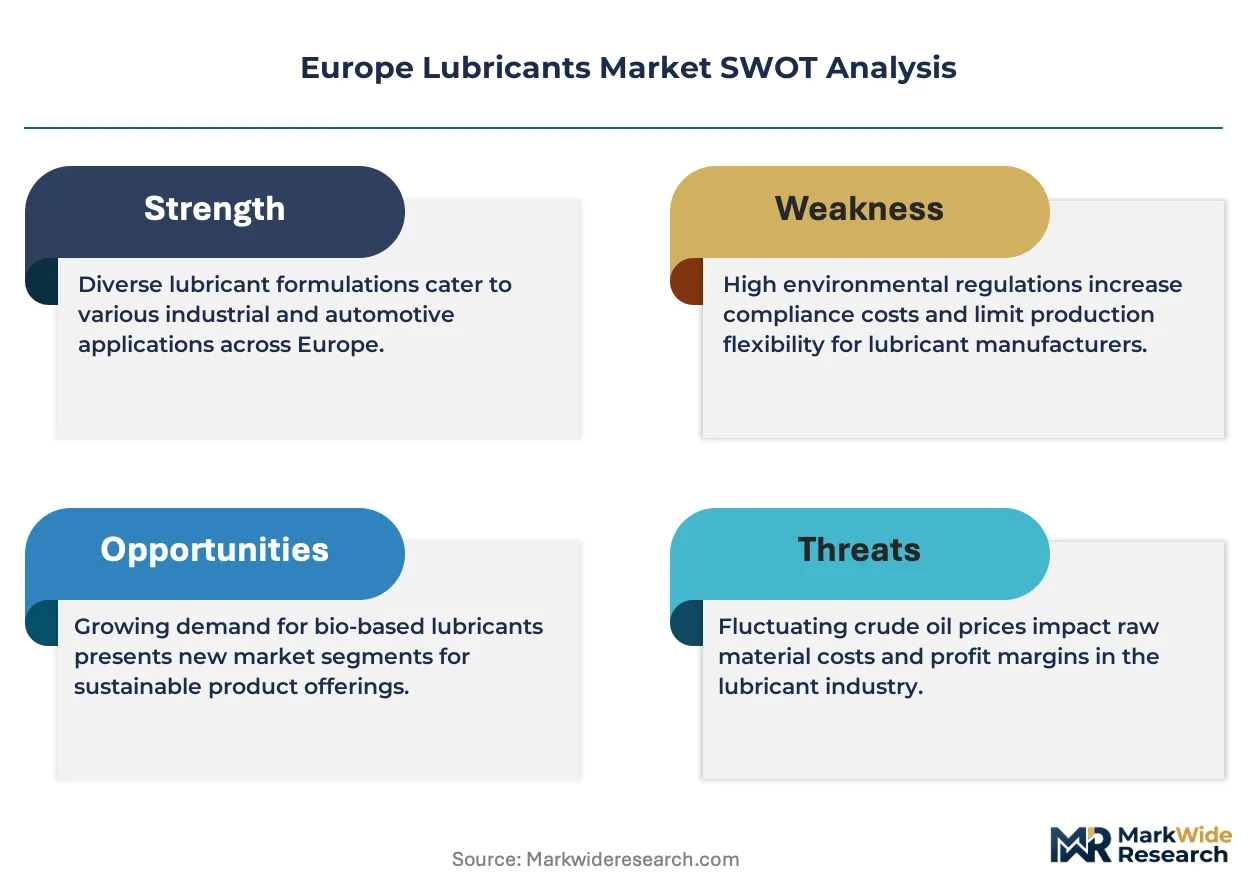
REACH registration requirements and the EU F-Gas Regulation constrain additive chemistries and base stock sourcing, compelling reformulation investments that favor larger blenders with dedicated regulatory affairs capacity. ECHA substance evaluation protocols extend compliance timelines for novel bio-based formulations, creating asymmetric barriers between incumbent mineral oil portfolios and emerging sustainable alternatives. Stakeholders must monitor the interaction between CE marking extensions for industrial lubricants and national eco-label schemes that increasingly influence public procurement specifications across European manufacturing hubs.
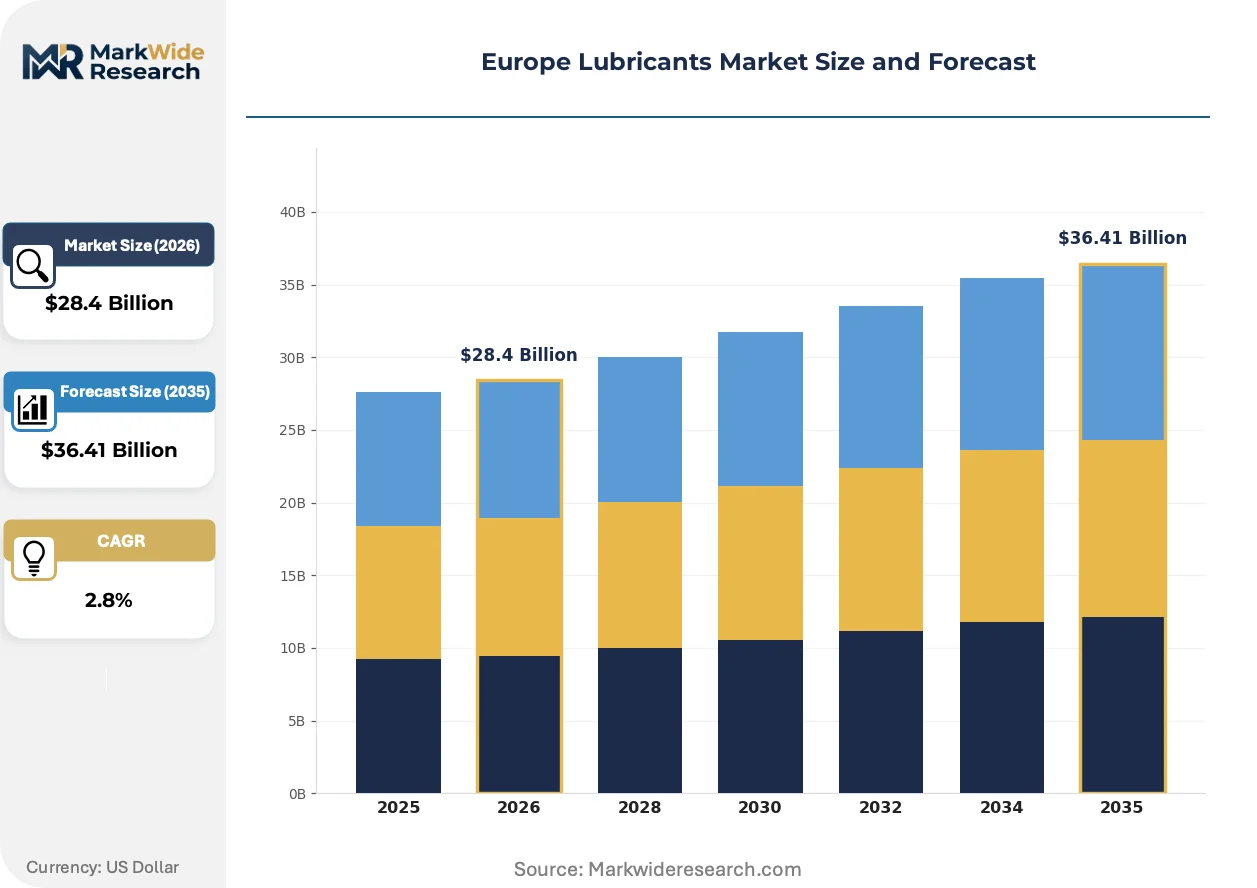
Market Dynamics
The EU Green Deal's decarbonization mandates are compressing mineral oil demand while accelerating synthetic and bio-based lubricant R&D cycles across European blenders.
Growth Catalysts
- REACH chemical registration:Tiered compliance timelines favor large-scale blenders with dedicated regulatory affairs teams, consolidating market access for reformulated bio-based portfolios.
- Extended OEM drain intervals:German and French automotive manufacturers specify synthetic motor oils to meet Euro 7 emissions protocols, pulling premium lubricant volumes.
- Industrial automation clusters:Manufacturing corridors in the Rhine-Ruhr region drive bulk hydraulic fluid procurement for precision machinery and robotics installations.
Market Restraints
- Base oil supply concentration:Northwest European refining capacity dominates Group II/III feedstock availability, exposing blenders to geographic concentration risk.
- ECHA substance evaluation timelines:Novel bio-based additive packages face extended approval protocols, delaying commercialization of sustainable formulations.
- Mineral oil substitution economics:Price-sensitive fleet operators in Southern Europe retain conventional lubricant purchasing patterns despite sustainability mandates.
Strategic Opportunities
- Polish blending capacity expansion:New production assets entering service alongside legacy Rhine-Ruhr infrastructure create geographic diversification options for pan-European distribution.
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases in industrial applications open formulation space for advanced synthetic greases in sealed bearing systems.
- Aerospace OEM specifications:French aviation manufacturers demand specialized synthetic lubricant lines with extreme-temperature performance credentials.
Industry Challenges
- Additive chemistry expertise scarcity:Formulation chemists with dual competency in bio-based stocks and REACH compliance command premium compensation, constraining mid-tier blender hiring.
- CE marking extension complexity:Industrial lubricant certification timelines vary across national eco-label schemes, fragmenting public procurement qualification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Lubricants Market |
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $36.41 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motor Oil, Gear Oil, Hydraulic Fluid, Grease End Use Industry: Automotive, Manufacturing, Marine, Aerospace Base Oil Type: Mineral Oil, Synthetic Oil, Bio-based Oil, Paraffin Sales Channel: Retail, Wholesale, Direct Sales, E-commerce |
| Companies Covered | Shell plc, TotalEnergies SE, BP plc, ExxonMobil Corporation, FUCHS SE, Chevron Corporation, LUKOIL, Eni S.p.A., Repsol, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Lubricants Market Shifts & Advancements
Synthetic base oil technology and regulatory chemistry constraints are actively restructuring European lubricant value chains, with sustainability credentials becoming a technical specification rather than a marketing overlay.
Group III and polyalphaolefin synthetic base oils deliver superior oxidation stability and extended drain intervals compared to mineral alternatives. German automotive OEMs specify these formulations to satisfy Euro 7 emissions testing protocols. The technology is migrating from premium passenger vehicle segments into commercial fleet and industrial hydraulic applications as total cost-of-ownership calculations reshape procurement criteria.
REACH registration requirements and the EU F-Gas Regulation constrain additive chemistries and halogenated base stock sourcing. Blenders must reformulate portfolios to maintain market access, with compliance investments favoring integrated producers over toll blenders. Industrial grease and sealed-system applications face the most acute substitution pressure as fluorinated performance additives phase down.
Fleet procurement departments now require documented carbon intensity metrics alongside traditional technical specifications. Long-term supply agreements with certified sustainable base oil producers are displacing spot-market purchasing for major automotive and manufacturing accounts. This pattern concentrates in Germany's industrial corridor, where Scope 3 emissions reporting obligations cascade through automotive supply tiers.
Europe Lubricants Market Segmentation
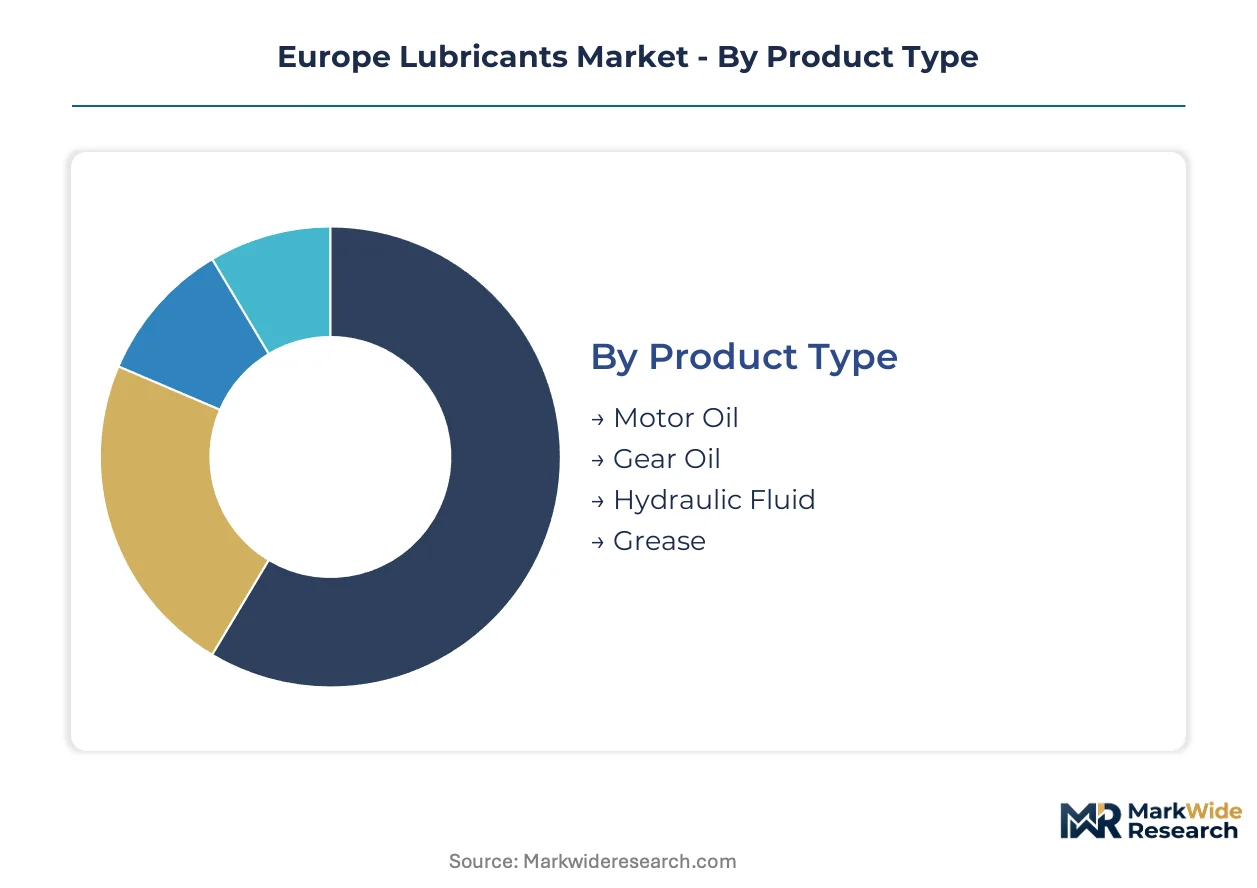
Product type, base oil chemistry, and end-use application create distinct value pools across the European lubricants landscape. Procurement specifications vary sharply between German automotive OEMs and Mediterranean fleet operators, while regulatory pressure on base stock sourcing is fragmenting competitive positions by formulation technology.
Product Type:
Application function determines additive complexity, drain interval specifications, and margin structure across the four product categories.
- Motor Oil:Formulated from Group II/III mineral or polyalphaolefin synthetic base stocks with detergent-dispersant additive packages for combustion engine protection. German and French automotive OEMs specify synthetic grades to satisfy Euro 7 emissions protocols, pulling premium volumes through extended drain intervals.
- Hydraulic Fluid:Anti-wear formulations with viscosity index improvers for power transmission in precision machinery. Demand concentrates in the Rhine-Ruhr manufacturing corridor where automated production lines and robotics installations require bulk procurement of ISO 32-68 grade fluids.
- Gear Oil:Extreme-pressure lubricants for transmission and differential systems with sulfur-phosphorus additive chemistry.
- Grease:Thickened base oil formulations for sealed bearing applications where relubrication access is limited.
Motor oil holds installed capacity. Grease is rotating up the share rankings.
End Use Industry:
Customer operational intensity and regulatory exposure shape formulation requirements and contract structures.
- Automotive:Passenger vehicle and commercial fleet maintenance drives the largest volume pool, with German OEMs mandating synthetic motor oils and French manufacturers extending drain intervals through advanced formulation specifications.
- Manufacturing:Industrial automation clusters across Germany's industrial corridor consume bulk hydraulic fluids and precision greases for machinery uptime optimization.
- Marine:Cylinder and system lubricants for two-stroke and four-stroke marine diesel engines operating under IMO sulfur regulations.
- Aerospace:Synthetic lubricant lines with extreme-temperature performance credentials for turbine engines and landing gear systems.
Automotive holds installed capacity. Manufacturing is rotating up the share rankings.
Base Oil Type:
Feedstock chemistry determines oxidation stability, cold-flow properties, and compliance positioning under REACH and EU Green Deal mandates.
- Synthetic Oil:Group III hydrocracked or polyalphaolefin base stocks deliver superior thermal stability and extended service intervals compared to mineral alternatives. German automotive OEM specifications and Euro 7 testing protocols are accelerating substitution away from conventional formulations.
- Bio-based Oil:Estolide or vegetable-derived base stocks with renewable carbon content credentials for Scope 3 emissions reporting. ECHA substance evaluation timelines delay commercialization, creating asymmetric barriers versus incumbent mineral portfolios.
- Mineral Oil:Solvent-refined or hydrocracked Group I/II base stocks from Northwest European refining capacity.
- Paraffin:Saturated hydrocarbon fractions for specialized industrial applications requiring low aromatic content.
Mineral oil holds installed capacity. Synthetic oil is rotating up the share rankings.
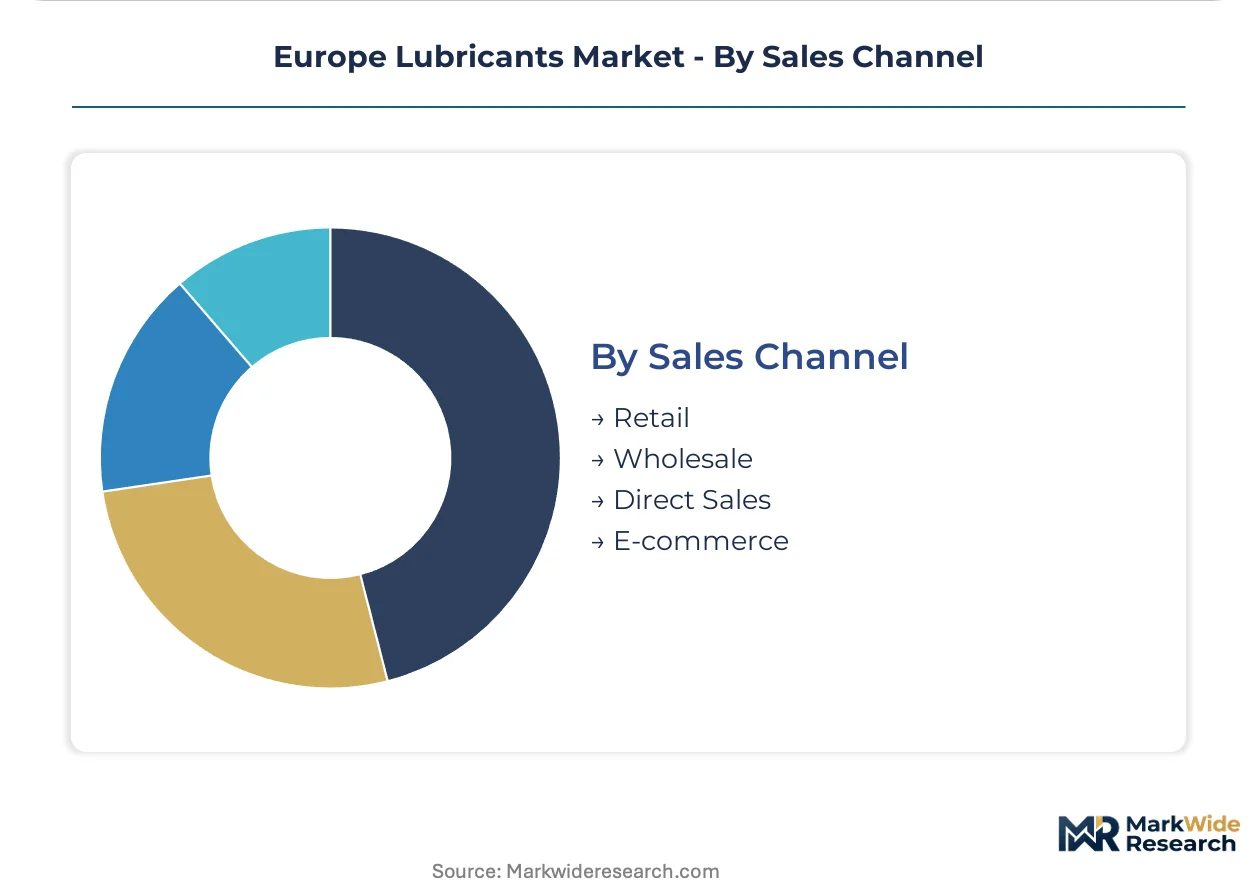
Sales Channel:
Channel structure reflects customer scale, technical service requirements, and inventory velocity patterns.
- Wholesale:Bulk supply agreements with manufacturing accounts and fleet operators in Germany's industrial corridor, where long-term contracts with certified sustainable base oil producers displace spot-market purchasing.
- Retail:Packaged lubricant sales through automotive service stations and parts distributors for passenger vehicle maintenance.
- Direct Sales:Technical field service relationships for aerospace OEMs and precision machinery manufacturers requiring formulation customization.
- E-commerce:Digital procurement platforms for small-to-mid fleet operators and independent repair shops.
Wholesale holds installed capacity. Direct sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr pipeline network and Rotterdam-Antwerp refining corridor anchor European lubricant supply chains, channeling base oil feedstocks from Northwest European crackers to blending facilities across the continent.
Germany
Automotive OEMs in Stuttgart and Munich mandate synthetic motor oils for Euro 7 compliance, pulling premium formulation volumes through extended drain intervals. The KBA enforces stringent emissions testing protocols that cascade into lubricant procurement specifications. Manufacturing clusters along the Rhine-Ruhr corridor consume bulk hydraulic fluids for precision machinery and robotics installations.
France
Aerospace manufacturers in Toulouse and Paris specify specialized synthetic lubricants with extreme-temperature credentials for turbine engine applications. ANSM oversees chemical substance registrations that constrain additive package approvals. The Île-de-France automotive belt drives demand for high-performance gear oils in transmission systems.
Italy
Industrial machinery producers in Lombardy and Emilia-Romagna source precision greases for automated production lines. CE marking extensions for industrial lubricants create compliance complexity across national eco-label schemes. The Port of Genoa handles marine lubricant volumes for Mediterranean shipping routes under IMO sulfur regulations.
Poland
New blending capacity near Gdańsk and Płock fragments the traditional Rhine-Ruhr supply concentration, offering geographic diversification for pan-European distribution. The country's national chemical regulator implements REACH-aligned substance evaluation timelines. Manufacturing investment in Lower Silesia drives hydraulic fluid procurement for automotive component suppliers.
Netherlands
Rotterdam's refining and storage infrastructure dominates Group II/III base oil availability for European blenders. The EU F-Gas Regulation constrains fluorinated additive chemistries in industrial grease formulations. Chemical processing clusters in the Randstad region sustain demand for specialized process oils in polymer and pharmaceutical manufacturing.
Europe Lubricants Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The European lubricants sector consolidates around integrated energy majors with captive base oil production, while mid-tier blenders compete on formulation specialization and regional service density. Three archetypes dominate: vertically integrated refiners with retail distribution networks, industrial specialists focused on grease and hydraulic fluids, and toll blenders serving private-label accounts. Competitive moves center on synthetic base oil capacity expansion and bio-based formulation partnerships to secure REACH-compliant additive supply.
Within the integrated energy major tier, Shell plc and TotalEnergies SE exemplify platform-scale positioning with upstream base oil production through retail channel control. BP plc occupies a position bridging system integration and geographic diversification across Northwest European markets. FUCHS SE represents the industrial specialist archetype, anchoring its competitive stance through precision grease formulation for German machinery manufacturers rather than commodity motor oil volumes.
| Leading Market Players |
|---|
| Shell plc |
| TotalEnergies SE |
| BP plc |
| ExxonMobil Corporation |
| FUCHS SE |
| Chevron Corporation |
| LUKOIL |
| Eni S.p.A. |
| Repsol |
| Others |
Supply & Pricing Matrix
Rotterdam's refining and storage infrastructure anchors European base oil availability, with Group II/III capacity concentration in the Netherlands and Germany translating directly into formulation cost leverage for integrated blenders serving automotive OEMs and industrial accounts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts, with synthetic Group III formulations commanding spreads over mineral alternatives due to Euro 7 compliance certification and extended drain interval guarantees. Price differentiation hinges on REACH registration status and volume scale, with bulk fleet operators extracting double-digit discounts unavailable to independent repair channels. Cost compression in economy-tier mineral oils is intensifying because Polish blending capacity expansion erodes legacy Rhine-Ruhr pricing power. Small fleet operators in Southern Europe exhibit highest price sensitivity, while German automotive OEMs prioritize technical specification adherence over unit cost.
Supply Chain Analysis
Upstream feedstock flows from Northwest European crackers in the Netherlands, Belgium, and Germany concentrate Group II/III base oil availability for continental blenders. Formulation chemistry draws from additive packages sourced through specialized chemical distributors, with bio-based estolide stocks emerging as alternative feedstocks constrained by ECHA evaluation timelines. Single-source vulnerability concentrates in fluorinated performance additives facing phase-down under EU F-Gas Regulation, forcing grease reformulation investments. Distribution runs through integrated refiner networks and independent toll blenders, with long-term supply agreements displacing spot purchasing for major manufacturing accounts in Germany's industrial corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as regulatory chemistry constraints and bio-based formulation complexity splinter procurement specifications, creating niche positions for specialized blenders alongside integrated energy majors.
For Market Incumbents: Pre-empt mid-tier blender consolidation by acquiring REACH-compliant additive technology portfolios before ECHA substance evaluation timelines extend competitive barriers. Secure backward integration into certified sustainable base oil production to defend margin position against bio-based feedstock scarcity. Anchor channel control through direct technical service relationships with aerospace OEMs and precision machinery manufacturers where formulation customization commands pricing power.
For New Entrants and Emerging Players: Pursue geographic white space in Polish blending capacity serving pan-European distribution networks, where new production assets fragment traditional Rhine-Ruhr supply concentration. Target industrial grease applications under EU F-Gas Regulation substitution pressure, where fluorinated additive phase-down creates formulation gaps for advanced synthetic alternatives. Establish go-to-market positioning through e-commerce platforms capturing small-to-mid fleet operators underserved by integrated refiner distribution.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors industrial specialists with captive formulation expertise over commodity motor oil blenders facing synthetic substitution margin compression. Long-term viability over the next decade rests on bio-based portfolio development and REACH compliance infrastructure rather than mineral oil volume scale. Acquisition target archetype: mid-tier blenders with established regulatory affairs capacity and aerospace or precision manufacturing customer concentration. Signal to watch: ECHA substance evaluation timeline acceleration for novel bio-based additive packages as inflection indicator for sustainable formulation commercialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Captive Group III supply secures margin control against Rotterdam-Antwerp feedstock concentration risk. |
| REACH-Compliant Bio-based Formulation Partnership | Estolide feedstock alliances preempt ECHA evaluation bottlenecks for sustainable lubricant portfolios. |
| Polish Blending Capacity Expansion | Gdańsk and Płock assets diversify geographic footprint beyond legacy Rhine-Ruhr infrastructure. |
| Aerospace OEM Technical Service Investment | Direct field relationships with Toulouse and Paris manufacturers capture extreme-temperature specification premiums. |
| E-commerce Platform Development | Digital procurement channels penetrate fragmented small fleet and independent repair shop segments. |
Research Methodology
A standing panel of lubricant formulation chemists, automotive OEM procurement directors, industrial maintenance engineers, and REACH regulatory affairs specialists provided ongoing calibration against primary fieldwork and secondary validation. Primary interviews combined with trade data from Eurostat customs records, Cefic chemical industry reports, SEC filings from integrated energy majors, and base oil production statistics from Northwest European refiners. Bottom-up volume modeling across product type, base oil chemistry, and end-use segments triangulated against top-down market sizing from macroeconomic industrial production indices.
Scenario-bracketing framed analytical approach across the projection horizon, with demand elasticity tested against Euro 7 implementation timing and EU Green Deal decarbonization trajectory. Segmentation dimensions modeled encompass product type, base oil chemistry tier, end-use industry vertical, and sales channel structure. CAGRs derived from regression analysis of historical volume patterns against industrial automation investment cycles and automotive production forecasts. Industry-specific inputs included OEM drain interval specification trends and ECHA substance evaluation pipeline status.
Macroeconomic conditions sit as an overlay; deviation in industrial production growth, base oil crack spreads, or euro-denominated energy costs would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation timelines and substitution elasticity. Cross-checking against Eurostat industrial production indices and automotive registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Europe Marine Lubricants Market
Lubricants
Sri Lanka Lubricants Market
Lubricants
Norway Automotive Lubricants Market
Lubricants
Firearm Lubricants Market
Lubricants
Friction Reducers Market
Lubricants
Europe Grease Market
Lubricants
Philippines Commercial Vehicles Lubricants Market
Lubricants
Russia Automotive Engine Oils Market
Lubricants
Mexico Automotive Engine Oils Market
Lubricants
Global Compressor Oil Market
Lubricants
China Lubricants Market
Lubricants
Perfluoropolyether Fluorinated Fluids Market
Lubricants
Singapore Lubricants Market
Lubricants
Brazil Commercial Vehicles Lubricants Market
Lubricants
Aluminum Extrusion Lubricants Market
Lubricants
Neat Cutting Oil Market