
 Asia-Pacific Camping and Caravanning Market | 2026-2036
Asia-Pacific Camping and Caravanning Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Camping and Caravanning Market Analytics
Market Context
Family outdoor recreation is shifting toward multi-day caravanning trips across the Asia-Pacific. Thor Industries Inc. leverages its international manufacturing footprint to serve Australian and Japanese dealers. SAIC Motor anchors its position through RV-specific platforms developed for Chinese domestic tourism. Great Wall Motor Co., Ltd. competes on cost-engineered motorhome chassis targeting Southeast Asian markets.
Technical Definition and Structural Segments
Camping and caravanning encompasses mobile temporary shelter systems including towable trailers, self-propelled motorhomes, and portable tents designed for recreational occupancy with sleeping, cooking, and sanitation functions. Motorhomes integrate automotive drivetrains with living modules, requiring compliance with both vehicle safety and habitation standards. Tents and caravans lead volume across the product type dimension, though motorhomes capture disproportionate margin pools in Japan and Australia due to premium pricing and longer replacement cycles. The customer type structure shows outdoor enthusiasts driving equipment upgrades, while families represent the fastest-growing application segment as multi-generational travel gains traction in South Korea and Taiwan.
Regulatory Frame and Outlook
Australia's caravan safety standards, Japan's Ministry of Land, Infrastructure, Transport and Tourism vehicle type approvals, and China's MIIT special-purpose vehicle regulations collectively shape product certification timelines and market access conditions. Australia's mandatory gas and electrical compliance for caravans adds cost but filters out low-grade imports. Stakeholders must monitor how Japan's METI decarbonization roadmaps and Australia's state-level campground licensing reforms alter capital allocation between motorhome manufacturing and fixed-site infrastructure development.
Market Dynamics
Domestic leisure travel across Australia, Japan, and South Korea is pivoting toward self-contained outdoor accommodation, compressing traditional hotel demand while accelerating campground infrastructure investment along Queensland and New South Wales coastal corridors.
Growth Catalysts
- MIIT Vehicle Classification Reforms:China's Ministry of Industry and Information Technology special-purpose vehicle regulations are streamlining motorhome type approvals, reducing certification timelines for domestic manufacturers.
- Multi-Generational Travel Patterns:South Korean and Taiwanese families are expanding caravanning trip durations, driving demand for larger towable units with expanded sleeping configurations.
- Coastal Infrastructure Investment:Queensland and New South Wales are accelerating campground licensing reforms, expanding powered site availability and wastewater hookup density.
Market Restraints
- Aluminum and Steel Input Volatility:Caravan chassis and body panel fabrication faces raw material cost swings that compress manufacturer margins without commensurate pricing power.
- Australia's Gas and Electrical Compliance:Mandatory certification requirements for caravan habitation systems add fixed compliance costs that filter out low-grade import competitors.
- Substitution from Glamping Fixed Structures:Permanent luxury tent installations at Japanese and Australian resorts capture price-sensitive outdoor enthusiasts seeking comfort without vehicle ownership.
Strategic Opportunities
- Southeast Asian Motorhome Penetration:Thailand and Vietnam present underdeveloped caravanning cultures where cost-engineered chassis platforms can establish first-mover retail networks.
- METI Decarbonization Roadmaps:Japan's Ministry of Economy, Trade and Industry carbon-neutral targets are creating incentive structures for electric drivetrain motorhome development.
- Direct-to-Consumer Digital Channels:Australian and Japanese manufacturers are bypassing dealer networks through configuration platforms, capturing margin and shortening order cycles.
Industry Challenges
- Dual Certification Complexity:Motorhome manufacturers must satisfy both automotive safety standards and habitation compliance, elongating product development timelines.
- Specialized Technician Scarcity:Combined automotive and residential system repair skills remain concentrated in urban Australian and Japanese service centers, limiting rural support coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Camping and Caravanning Market |
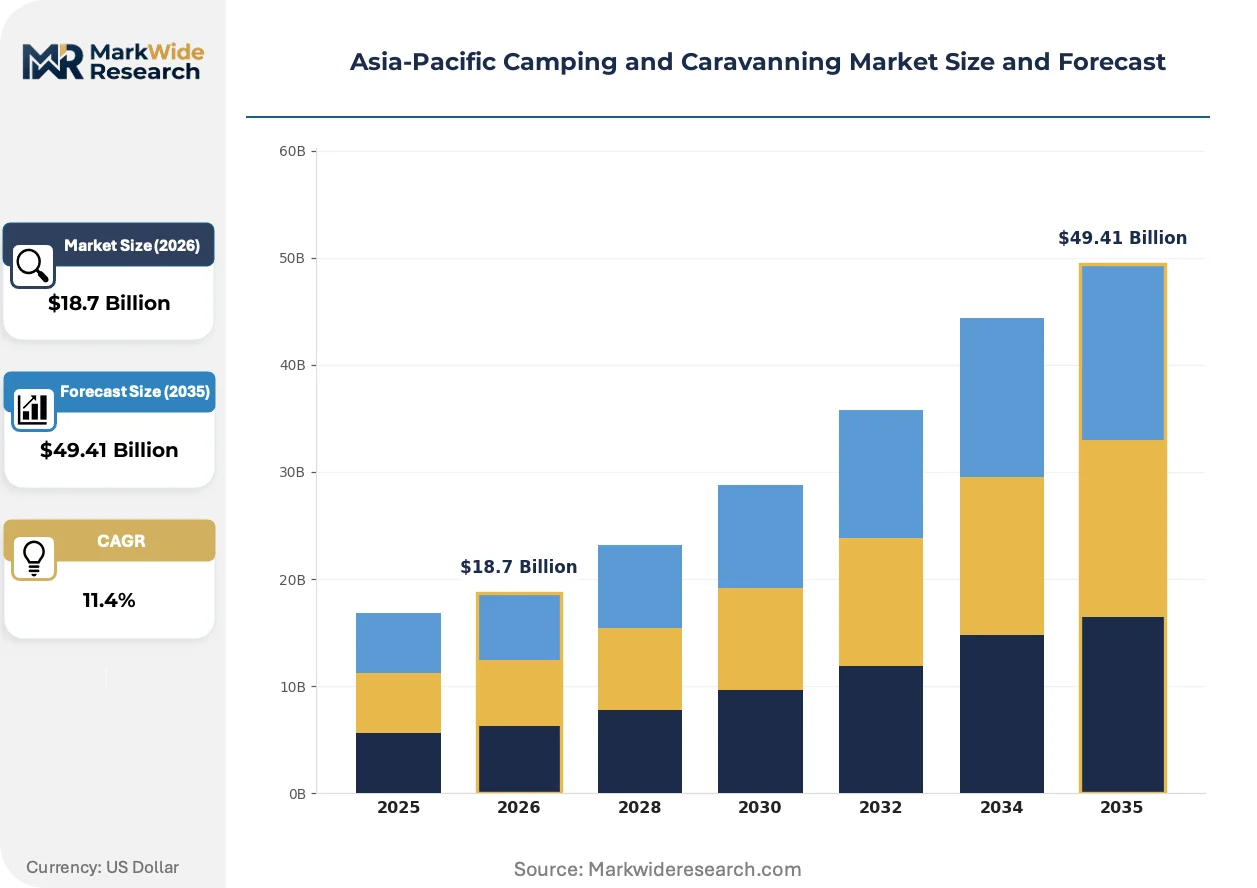
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tents, Caravans, Motorhomes, Trailers Application: Recreational, Adventure, Family, Solo Customer Type: Outdoor Enthusiasts, Tourists, Families, Groups Distribution Channel: Retail Stores, Online Platforms, Exhibitions, Dealers |
| Companies Covered | Thor Industries Inc., SAIC Motor, Great Wall Motor Co., Ltd., Forest River Inc., Winnebago Industries Inc., BYD Auto, REV Group, Hyundai Motor Company, JAC Motors, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Camping and Caravanning Market Evolving Landscape
Electrification of drivetrains and habitation systems is restructuring product architectures across the Asia-Pacific, while regulatory pressure on emissions and safety compliance accelerates R&D allocation toward integrated platform solutions.
Lithium-ion battery packs with integrated solar charge controllers are electrifying auxiliary power systems in Australian and Japanese motorhomes. Premium buyers are specifying 400Ah+ house battery configurations as standard equipment. This capability is electrifying off-grid camping viability, compressing generator sales and expanding remote site accessibility.
Australia's caravan safety standards are mandating enhanced structural integrity testing for towable units, including rollover simulation and coupling durability verification. Manufacturers are redesigning chassis architectures to meet these thresholds. Japanese and South Korean export-oriented suppliers are most affected, accelerating local production shifts to avoid compliance friction.
Subscription-based access models are disrupting traditional ownership patterns among urban Australian millennials. Fleet operators are offering seasonal membership programs with distributed pickup locations. Sydney and Melbourne metropolitan zones show the highest adoption density, with penetration expanding into Brisbane and Perth corridors.
Asia-Pacific Camping and Caravanning Market Segmentation
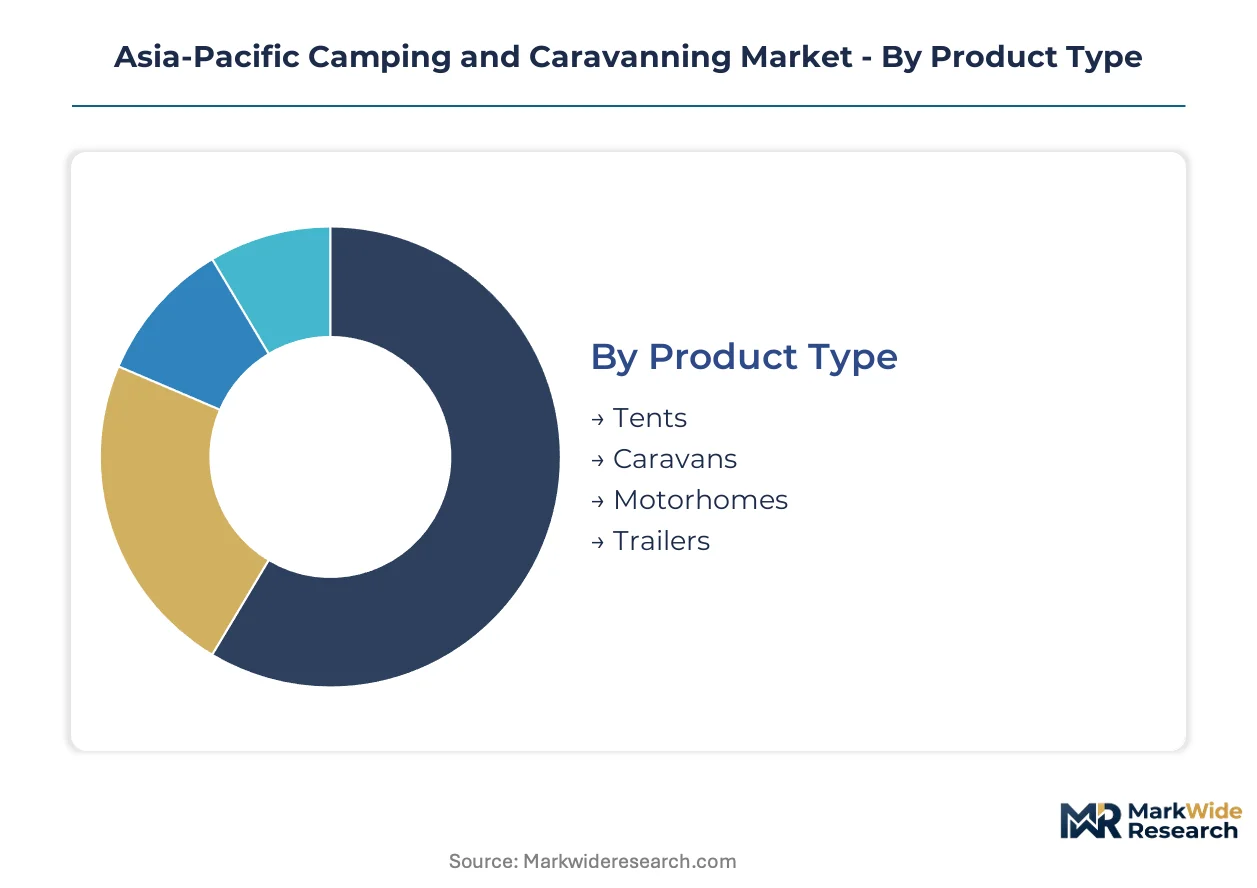
Equipment configuration and trip duration preferences diverge sharply across the Asia-Pacific camping landscape. Buyers in Australia prioritize towable chassis durability for extended coastal circuits, while Japanese purchasers emphasize compact motorhome maneuverability for mountain road access. South Korean family groups drive demand for multi-berth configurations with integrated sanitation systems.
Product Type:
Price elasticity and replacement cycle length determine how buyers allocate spending across mobile shelter categories.
- Motorhomes:Self-propelled units integrate automotive drivetrains with habitation modules requiring dual certification under Japan's Ministry of Land, Infrastructure, Transport and Tourism vehicle type approvals and Australia's caravan safety standards. Premium pricing concentrates demand among Japanese retirees and Australian empty-nesters undertaking months-long circumnavigation routes. Extended replacement cycles—often exceeding a decade—create lumpy revenue recognition for manufacturers.
- Caravans:Towable trailers dominate Australian volume through Queensland and New South Wales coastal corridors where campground infrastructure investment is accelerating powered site availability. Aluminum chassis fabrication faces raw material cost volatility that compresses manufacturer margins. Mandatory gas and electrical compliance adds fixed certification costs that filter low-grade imports.
- Tents:Portable fabric shelters serve price-sensitive entry segments and adventure-oriented buyers in South Korea and Taiwan seeking lightweight mobility for multi-day trekking circuits.
- Trailers:Utility-focused towable platforms support equipment hauling and minimalist overnighting among Australian rural property owners and Southeast Asian agricultural tourism operators.
Motorhomes lead on scale through premium pricing concentration; caravans lead on momentum through infrastructure-linked volume expansion.
Application:
Trip purpose shapes equipment specification priorities and service expectation thresholds.
- Family:Multi-generational travel patterns across South Korea and Taiwan are expanding caravanning trip durations, driving demand for larger towable units with expanded sleeping configurations and integrated kitchen sanitation. Queensland campground licensing reforms are expanding wastewater hookup density to accommodate these extended stays.
- Recreational:Weekend-oriented domestic leisure travel across Australia and Japan favors flexible booking patterns and equipment rental access over ownership commitment. Subscription-based fleet operators in Sydney and Melbourne metropolitan zones show highest adoption density.
- Adventure:Off-grid camping viability is electrifying through lithium-ion battery packs with integrated solar charge controllers, with premium buyers specifying 400Ah+ house battery configurations as standard equipment in Australian and Japanese markets.
- Solo:Individual travelers prioritize compact footprint and single-berth efficiency, particularly among Japanese urban millennials seeking escape from metropolitan density without vehicle ownership burden.
Family applications are climbing the fastest through multi-generational travel normalization; recreational applications maintain the broadest geographic penetration.
Customer Type:
Experience depth and group composition determine upgrade velocity and accessory spending intensity.
- Families:Australia's multi-day caravanning trip growth and South Korea's multi-generational travel expansion are converging on larger towable configurations with enhanced sleeping capacity and climate control systems.
- Outdoor Enthusiasts:Equipment upgrade cycles concentrate among experienced Australian and Japanese buyers replacing aging chassis to meet enhanced structural integrity testing mandates including rollover simulation requirements.
- Tourists:International visitors to Thailand and Vietnam present underdeveloped caravanning cultures where cost-engineered chassis platforms can establish first-mover retail networks.
- Groups:Organized touring clubs in Japan coordinate seasonal migration patterns that concentrate demand for standardized motorhome specifications enabling inter-fleet compatibility and shared service infrastructure.
Families are gaining share fastest through demographic tailwinds; outdoor enthusiasts sustain the steepest equipment replacement spending per capita.
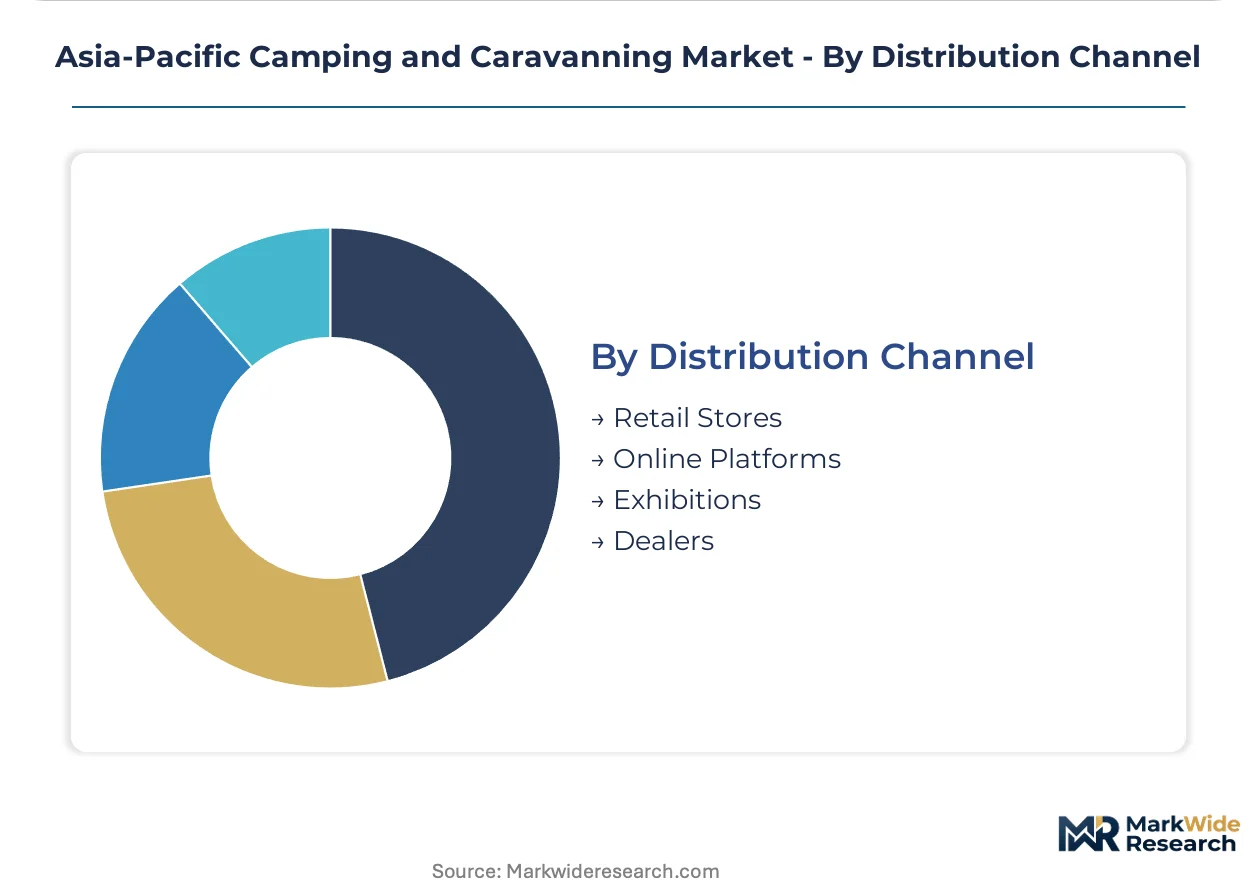
Distribution Channel:
Channel selection reflects buyer information-seeking behavior and configuration complexity tolerance.
- Online Platforms:Australian and Japanese manufacturers are bypassing dealer networks through configuration platforms, capturing margin and shortening order cycles. Sydney and Melbourne metropolitan zones show highest digital adoption density.
- Dealers:Physical retail networks remain essential for motorhome transactions requiring test drive validation and financing arrangement, particularly in Japan where Ministry of Land, Infrastructure, Transport and Tourism compliance documentation demands in-person verification.
- Retail Stores:Camping equipment specialists in Queensland and New South Wales coastal corridors stock tent and accessory inventory for impulse purchase alongside trip planning services.
- Exhibitions:Annual caravan shows in Australian state capitals and Tokyo generate concentrated lead generation for premium motorhome manufacturers with extended sales cycles.
Dealers lead on scale through high-value transaction concentration; online platforms lead on momentum through margin capture and geographic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Queensland and New South Wales coastal corridors anchor the Asia-Pacific camping infrastructure expansion, where powered site investment and wastewater hookup density are accelerating campground licensing reforms to accommodate extended multi-generational stays.
Australia
Domestic leisure travel is compressing traditional hotel demand across Queensland and New South Wales as families pivot toward self-contained outdoor accommodation. The country's caravan safety standards mandate enhanced structural integrity testing including rollover simulation, filtering low-grade imports while accelerating local chassis fabrication. Coastal infrastructure investment concentrates along the Gold Coast-to-Byron Bay corridor and the Mid North Coast, where powered site availability is expanding fastest.
China
Domestic tourism platforms are driving motorhome penetration through RV-specific vehicle architectures developed for self-drive vacation circuits. The Ministry of Industry and Information Technology special-purpose vehicle regulations are streamlining type approvals, reducing certification timelines for domestic manufacturers. Manufacturing clusters in Shanghai and Guangdong are scaling chassis production for both domestic deployment and Southeast Asian export.
Japan
Retiree demand for months-long circumnavigation routes is concentrating premium motorhome sales among empty-nesters seeking mountain road accessibility. The Ministry of Economy, Trade and Industry decarbonization roadmaps are creating incentive structures for electric drivetrain development. The Kanto and Kansai metropolitan zones maintain the densest dealership networks for Ministry of Land, Infrastructure, Transport and Tourism compliance documentation.
South Korea
Multi-generational travel normalization is expanding caravanning trip durations, driving specification demand for larger towable units with expanded sleeping configurations. National park access permits and seasonal migration coordination through organized touring clubs are standardizing fleet specifications. The Seoul Capital Area and Busan-Ulsan corridor show highest membership density for subscription-based access models.
Thailand
Agricultural tourism operators and international visitor segments present underdeveloped caravanning cultures where cost-engineered chassis platforms can establish first-mover retail networks. National tourism board infrastructure grants are piloting campground development in Chiang Mai and Phuket provinces. Bangkok-based distributors are testing fleet rental models before ownership commitment thresholds mature.
Asia-Pacific Camping and Caravanning Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers scale chassis fabrication to meet Australia's structural integrity mandates and China's streamlined type approvals. The vendor base stratifies across three tiers: multinational platform integrators with international manufacturing footprints, domestic automotive conglomerates leveraging RV-specific vehicle architectures, and regional specialists focused on cost-engineered chassis for emerging Southeast Asian markets. Strategic archetypes include automotive OEMs diversifying into recreational vehicle platforms, dedicated caravan fabricators defending coastal corridor market share, and electric drivetrain developers capturing METI incentive structures. Geographic expansion and portfolio diversification represent the dominant competitive moves, with players establishing distributed retail networks in underpenetrated markets while broadening product configurations across motorhome, caravan, and subscription-access segments.
Among multinational platform integrators, Thor Industries Inc. and Winnebago Industries Inc. occupy positions exemplifying the premium-tier motorhome archetype with extended replacement cycle revenue recognition. SAIC Motor and Great Wall Motor Co., Ltd. represent the automotive OEM diversification pattern, leveraging captive vehicle platforms to serve domestic tourism growth and Southeast Asian export corridors respectively. These three anchors illustrate how competitive positioning separates international footprint scale from domestic market capture and cost-engineered emerging market penetration.
| Leading Market Players |
|---|
| Thor Industries Inc. |
| SAIC Motor |
| Great Wall Motor Co., Ltd. |
| Forest River Inc. |
| Winnebago Industries Inc. |
| BYD Auto |
| REV Group |
| Hyundai Motor Company |
| JAC Motors |
| Others |
Value Network & Pricing Analysis
Aluminum chassis fabrication costs cascade through Australia's caravan manufacturing tiers, compressing margins for towable unit producers while elevating price premiums for MIIT-certified motorhome platforms in China.
Pricing Analysis
Distributor markups on Japanese motorhomes absorb Ministry of Land, Infrastructure, Transport and Tourism compliance documentation costs, widening spreads between dealer-channel and direct-to-consumer Australian configuration platforms. Three-tier pricing structure across premium lithium-equipped motorhomes, standard aluminum-body caravans, and economy tent segments reflects certification grade and after-sales bundling intensity. Pricing pressure stems from raw material input volatility in Queensland chassis fabricators. Fleet subscription operators in Sydney and Melbourne metropolitan zones exhibit lowest price sensitivity; Southeast Asian agricultural tourism buyers face highest budget constraints.
Supply Chain Analysis
Specialized welding technicians concentrate in Shanghai and Guangdong manufacturing clusters, constraining chassis production scaling for domestic Chinese deployment and Thai export corridors. Aluminum extrusion and steel coil feedstock draw from Australian bauxite processing and Chinese integrated mills. Single-source vulnerability sits with Japanese lithium-ion battery pack suppliers for 400Ah+ house battery configurations. Distribution runs through Queensland and New South Wales coastal dealer networks for towable units, while Japanese motorhome transactions require Kanto and Kansai metropolitan showroom verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific camping and caravanning market compounds steadily through multi-generational travel normalization across South Korea and Taiwan, embedding durable replacement cycles into family equipment upgrade patterns.
For Market Incumbents: Lock in coastal corridor dealership density across Queensland and New South Wales before campground licensing reforms mature. Deepen backward integration into aluminum chassis fabrication to offset raw material cost volatility threatening margin stability. Prioritize METI decarbonization roadmap alignment for electric drivetrain motorhome development in Japan. For New Entrants and Emerging Players: Launch via subscription-based fleet membership models in Bangkok and Chiang Mai before ownership commitment thresholds mature in Thailand. Target Vietnamese agricultural tourism operators with cost-engineered utility trailer platforms. Exploit direct-to-consumer digital configuration gaps left by incumbent dealer networks in Australian metropolitan zones. For Investors and Strategic Acquirers: Consolidation pressure builds where dual certification complexity elongates product development timelines beyond capital-efficient horizons. Position for platform integrators with captive vehicle architectures and distributed Southeast Asian retail footprints. Watch lithium-ion battery supply contract renegotiations as inflection signals for margin compression timing in premium motorhome tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Drivetrain Motorhome Development | Captures METI incentive structures while aligning with Japan's carbon-neutral vehicle roadmaps. |
| Direct-to-Consumer Configuration Platform Launch | Bypasses Queensland dealer markups and compresses order cycles for Australian manufacturers. |
| Coastal Campground Infrastructure Partnership | Secures powered site priority access for motorhome fleets along New South Wales corridors. |
| Lithium Battery Supply Agreement | Locks in 400Ah+ house battery configurations for off-grid camping viability in premium segments. |
| Southeast Asian Retail Network Establishment | Builds first-mover position in Thailand and Vietnam before domestic ownership culture matures. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with caravan manufacturer product managers, campground infrastructure investors, MIIT regulatory compliance officers, and Queensland dealer network operators with secondary validation. Customs trade data, vehicle registration databases, state-level campground licensing records, and Ministry of Economy, Trade and Industry policy filings anchored external verification. Bottom-up equipment shipment tallies and top-down tourism expenditure estimates achieved triangulation.
Comparable historical periods anchored the projection horizon, with segmentation modeling across product type, application purpose, customer experience depth, and distribution channel structure. CAGRs derived from regression analysis against domestic leisure travel expenditure trends and infrastructure investment pipelines. Motorhome replacement cycle length and caravan structural integrity testing compliance timelines fed industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum price spike scenarios or Australia's gas certification standard revisions. Forecasts reflect documented assumptions regarding multi-generational travel persistence and METI incentive continuity. Material deviation in lithium battery supply contract pricing or Queensland campground licensing reform pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Cloud Advertising Market
Others
India Foundry Market
Others
Global Electroshock Weapons Market
Others
8K Technology Market
Others
Augmented Reality (AR) in Manufacturing Market
Others
Security Envelopes Market
Others
Idaas Market
Others
Fiber to the X (Fttx) Tester Market
Others
Smart Home Service Market
Others
5G Devices Market
Others
Solar Animal Repeller Market
Others
Global Military Lighting Market
Others
North America Micro Market
Others
Aerospace Engineering Services Outsourcing Market
Others
Europe Legal Services Market
Others
France Automotive LED Lighting Market