
 North America Wireless Charging Market | 2026-2036
North America Wireless Charging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wireless Charging Market Intelligence
The EPA's tightened e-waste directives under the Resource Conservation and Recovery Act is realigning manufacturer priorities toward charger longevity and interoperability standards. Apple Inc. leverages its proprietary MagSafe ecosystem to sustain premium positioning across consumer electronics. Qualcomm Incorporated anchors automotive-grade wireless power transfer through its Halo technology platform for electric vehicle integration.
North America wireless charging encompasses contactless power transfer systems operating at frequencies between 110-205 kHz for inductive coupling and 6.78 MHz for resonant architectures, converting alternating magnetic fields into direct current without galvanic connections. The technology serves primarily to eliminate mechanical wear in high-cycle environments and enable sealed-device charging in medical and automotive applications. Inductive charging dominates current volume across smartphones and consumer wearables due to proven efficiency in tightly coupled coil arrangements. Resonant charging extends operational air gaps for automotive underbody and furniture-embedded installations, capturing margin pools in premium vehicle trims and hospitality infrastructure.
The FCC governs radio-frequency exposure limits and spectrum allocation for wireless power transmitters, while Underwriters Laboratories certifies thermal and electrical safety for retail charger deployment. Canada's Innovation, Science and Economic Development ministry coordinates spectrum harmonization with US bands, reducing cross-border product fragmentation. Stakeholders must monitor pending FCC proceedings on higher-power inductive allocations for heavy-duty vehicle classes.
Market Dynamics
Electric vehicle fleet operators are accelerating pad-based and in-road charging deployments, compressing payback periods through utility-backed infrastructure incentives and zero-emission vehicle mandates concentrated in California's metropolitan corridors.
Growth Catalysts
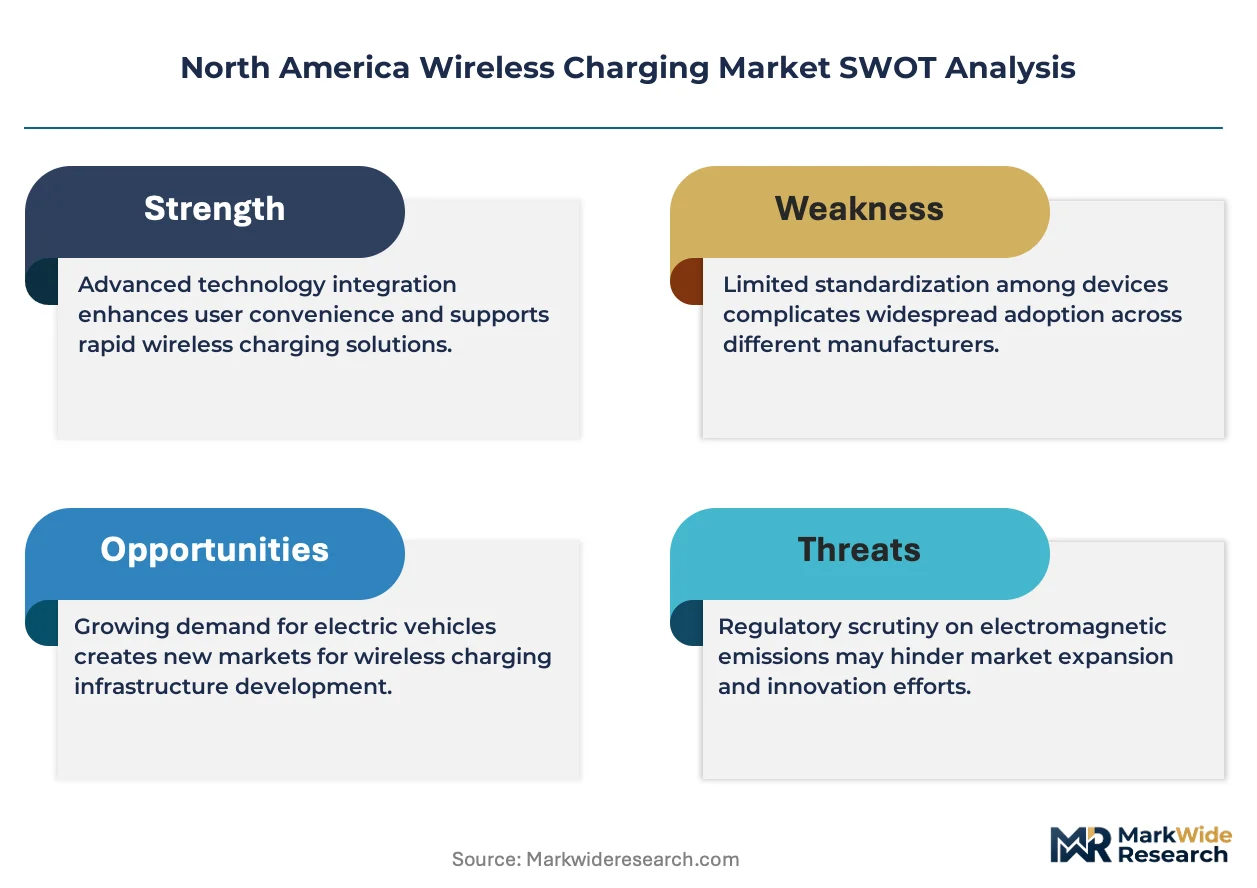
- California's ZEV Mandates:The state's Advanced Clean Cars II regulation compels automakers to integrate wireless charging compatibility into electric vehicle platforms, expanding addressable hardware volumes.
- FCC Part 18 Certification Pathway:Industrial, scientific, and medical equipment emissions rules provide transmitter manufacturers with streamlined market access for consumer and automotive-grade systems.
- Medical Device Sealing Requirements:Inductive architectures eliminate galvanic connections in implantable and wearable health monitors, satisfying FDA biocompatibility protocols for moisture-sensitive electronics.
Market Restraints
- Copper Coil Input Volatility:Litz wire and ferrite core costs fluctuate with commodity markets, squeezing margins on high-power automotive transmitters.
- Asian Component Concentration:Power semiconductor foundry capacity clusters in Taiwan and South Korea, creating supply vulnerability for North American transmitter assemblers.
- Air Gap Efficiency Limits:Resonant architectures sacrifice conversion efficiency above 15 centimeters, constraining furniture-embedded and public infrastructure deployments.
Strategic Opportunities
- Texas Utility Partnerships:ERCOT grid operators are piloting vehicle-to-building wireless bidirectional systems, opening fleet operator revenue streams beyond passenger automotive.
- Qi2 Magnetic Alignment Convergence:The Wireless Power Consortium's updated standard merges inductive reliability with resonant spatial freedom, enabling cross-device ecosystem lock-in.
- Canada's Clean Fuel Regulations:Federal credit mechanisms for zero-emission infrastructure reduce capital recovery timelines for Ontario and Quebec corridor charging networks.
Industry Challenges
- RF Exposure Compliance Timelines:FCC human safety testing for higher-power inductive allocations extends certification cycles by 8-14 months for heavy-duty vehicle classes.
- Legacy PHEV Integration Complexity:Retrofit hardware for existing plug-in hybrid fleets requires vehicle-specific coil positioning, fragmenting aftermarket service protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wireless Charging Market |
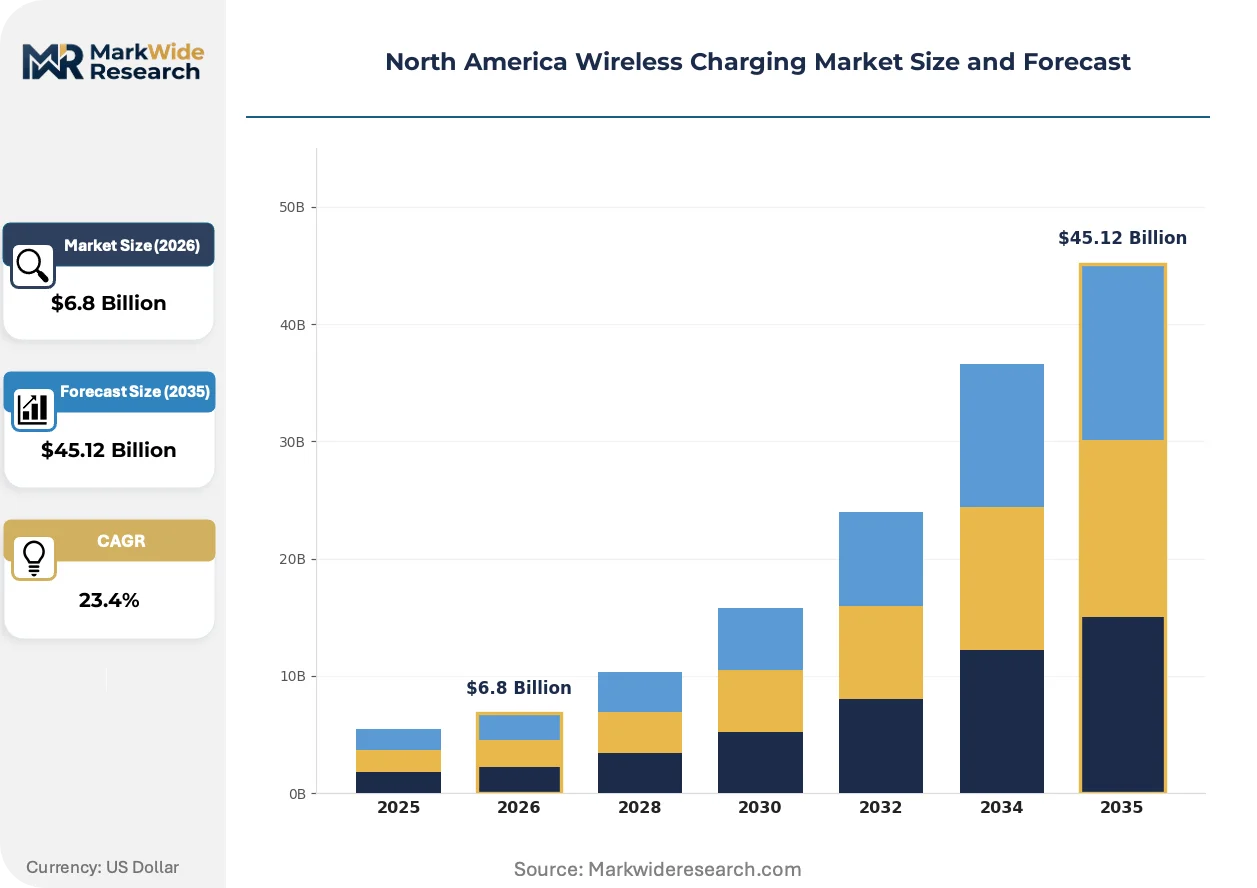
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $45.12 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Laptops, Wearables, Electric Vehicles Technology: Inductive Charging, Resonant Charging, Radio Frequency, Magnetic Resonance End User: Consumer Electronics, Automotive, Healthcare, Industrial Installation: Wall-Mounted, Surface-Mounted, Embedded, Portable |
| Companies Covered | WiTricity Corporation, Apple Inc., Samsung Electronics Co. Ltd., Qualcomm Incorporated, Texas Instruments Inc., Belkin International, Powermat Technologies Ltd., Continental AG, InductEV Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wireless Charging Market Strategic Shifts & Innovations
Magnetic alignment architectures are displacing positional tolerance limitations, while regulatory pressure on e-waste streams accelerates modular charger design. Demand concentration among fleet operators is compressing procurement cycles toward integrated infrastructure contracts.
GaN-based power conversion is consolidating transmitter efficiency profiles across 110-205 kHz inductive bands. Tier 1 automotive suppliers are adopting the semiconductor material for underbody charging modules, reducing thermal management overhead. The technology is consolidating mid-power consumer and high-power automotive segments into unified component supply bases.
The EPA's tightened e-waste directives under the Resource Conservation and Recovery Act mandate charger longevity standards and interoperability testing. Manufacturers must redesign thermal cycling resilience into coil assemblies to satisfy extended warranty obligations. Consumer electronics and medical device segments face the steepest compliance cost escalations.
Fleet procurement is aggregating around infrastructure-as-a-service contracts that bundle hardware, installation, and energy management. Traditional equipment distributors are losing position to vertically integrated charging network operators. California's metropolitan corridors exhibit the fastest contract structure migration, with Texas and Florida markets following 18-24 months behind.
North America Wireless Charging Market Segmentation
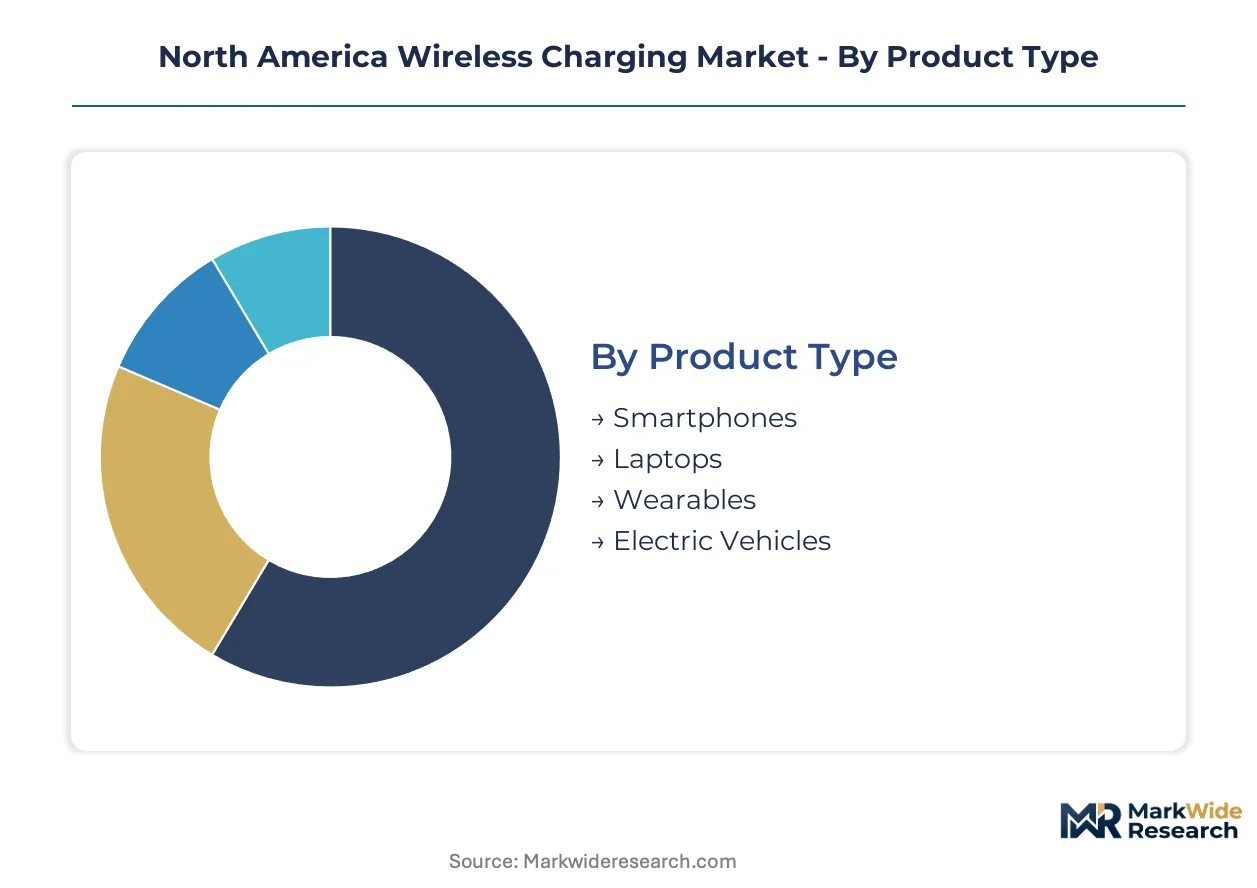
Segmentation in North American wireless charging reveals divergent technology maturities and regulatory exposure profiles. Each dimension carries distinct margin structures and certification burdens that reshape procurement priorities across automotive, medical, and consumer verticals.
Product Type:
Application durability requirements and power throughput specifications drive hardware selection, with automotive platforms demanding sealed assemblies and medical devices prioritizing biocompatibility.
- Smartphones:Tightly coupled inductive coils at 110-205 kHz dominate this segment, with MagSafe magnetic alignment architectures commanding premium positioning. California's metropolitan corridors concentrate replacement demand, where utility-backed infrastructure incentives accelerate public charging pad deployment.
- Electric Vehicles:Underbody pad systems and in-road dynamic charging installations operate at higher power thresholds. Fleet operators in Texas and California compress payback periods through vehicle-to-building bidirectional pilots and zero-emission mandates.
- Laptops:Mid-power resonant architectures extend spatial freedom for workspace furniture integration. Corporate procurement in Ontario and Quebec corridors favors embedded installations under Canada's Clean Fuel Regulations.
- Wearables:Miniaturized coil assemblies serve sealed health monitors and fitness trackers. FDA biocompatibility protocols for moisture-sensitive electronics elevate design complexity.
Volume sits with smartphones; growth tilts toward electric vehicles.
Technology:
Frequency band allocation and air gap tolerance determine regulatory pathway and thermal management overhead, with FCC Part 18 certification timelines varying by power class.
- Inductive Charging:Proven efficiency in tightly coupled arrangements at 110-205 kHz anchors consumer electronics volume. GaN-based power conversion is consolidating transmitter efficiency profiles and reducing thermal overhead.
- Resonant Charging:6.78 MHz architectures extend operational air gaps to 15 centimeters for automotive underbody and furniture-embedded installations. Efficiency constraints above this threshold limit public infrastructure scalability.
- Magnetic Resonance:Qi2 standard convergence merges inductive reliability with resonant spatial freedom, enabling cross-device ecosystem lock-in across premium automotive trims.
- Radio Frequency:Uncoupled power transfer at higher frequencies serves low-power sensor networks and IoT endpoints. FCC human safety testing extends certification cycles for emerging implementations.
Inductive architectures capture current volume; resonant and magnetic resonance platforms are climbing the fastest as automotive adoption accelerates.
End User:
Regulatory jurisdiction and procurement centralization create divergent sales cycle lengths, with healthcare and automotive requiring extended compliance documentation.
- Automotive:Tier 1 suppliers adopt GaN semiconductors for underbody modules, consolidating mid-power consumer and high-power automotive supply bases. California's Advanced Clean Cars II regulation compels wireless charging compatibility integration.
- Consumer Electronics:Modular charger design is accelerating under EPA e-waste directives mandating longevity standards and interoperability testing. Thermal cycling resilience requirements escalate compliance costs.
- Healthcare:Implantable and wearable health monitors demand inductive architectures that eliminate galvanic connections. FDA protocols for moisture-sensitive electronics dominate vendor qualification.
- Industrial:High-cycle environments leverage contactless power to eliminate mechanical wear. Sealed-device requirements in hazardous locations drive specification premiums.
Consumer electronics anchors volume; automotive and healthcare are gaining share fastest through fleet procurement and medical device sealing mandates.
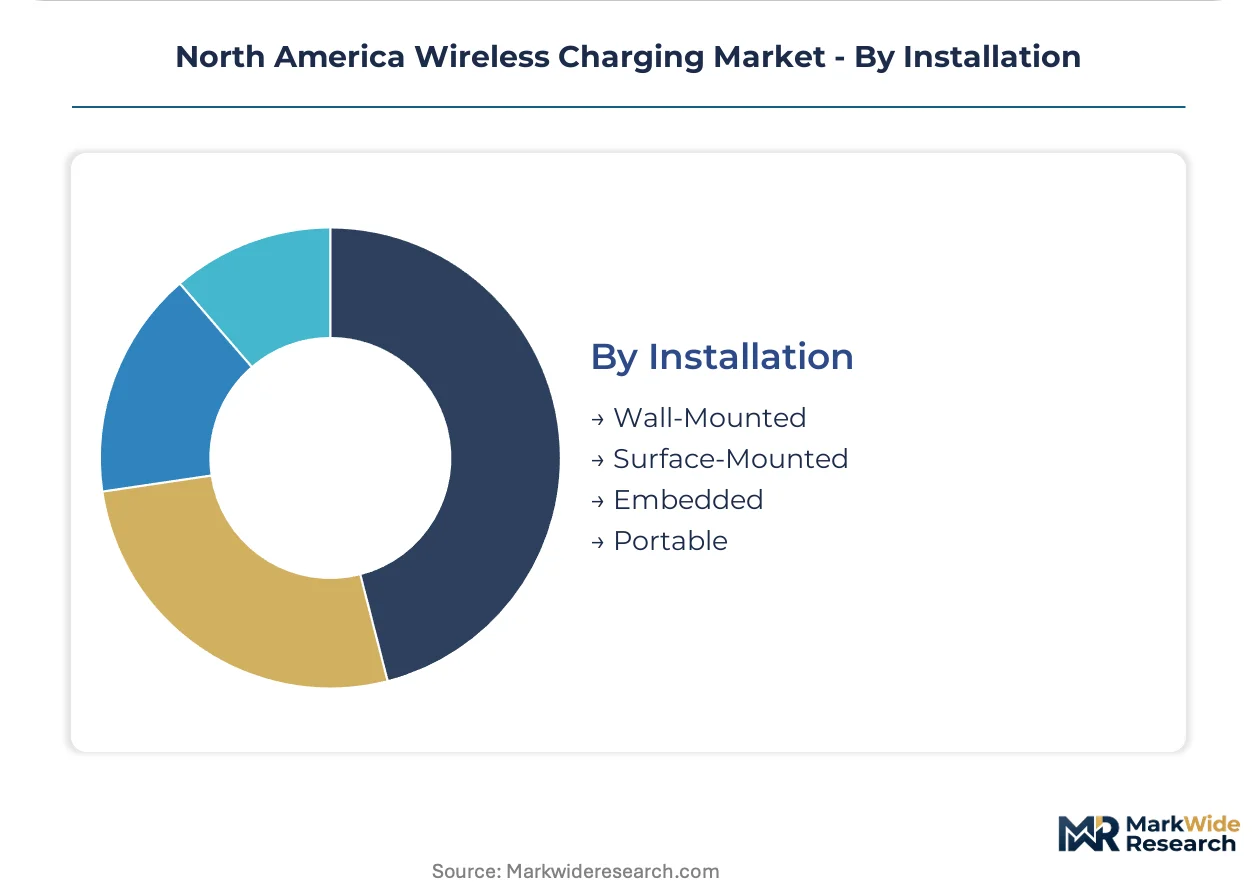
Installation:
Capital recovery timelines and infrastructure ownership models determine contract structure migration, with fleet operators favoring bundled service agreements over hardware-only procurement.
- Embedded:Furniture and roadway integration captures margin pools in premium vehicle trims and hospitality infrastructure. California's metropolitan corridors exhibit fastest contract structure migration toward infrastructure-as-a-service.
- Surface-Mounted:Pad-based systems for fleet depots and commercial garages dominate current automotive deployment. ERCOT grid operators in Texas pilot bidirectional systems opening revenue streams beyond passenger automotive.
- Wall-Mounted:Residential and small commercial installations serve smartphone and laptop charging. Retail channel distribution faces compression from vertically integrated network operators.
- Portable:Aftermarket accessories for travel and backup power operate outside utility incentive structures. Price pressure concentrates in undifferentiated coil assemblies.
Surface-mounted systems hold current volume; embedded installations show steepest expansion trajectory as infrastructure-as-a-service contracts aggregate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's metropolitan corridors dominate North American wireless charging deployment, where utility-backed infrastructure incentives and zero-emission vehicle mandates converge to compress capital recovery timelines for fleet operators.
United States
California's Advanced Clean Cars II regulation compels automakers to integrate wireless charging compatibility into electric vehicle platforms. The FCC's Part 18 rules govern industrial, scientific, and medical equipment emissions for transmitter certification. Texas ERCOT grid operators pilot vehicle-to-building bidirectional systems in Dallas-Fort Worth and Houston corridors.
Canada
Federal credit mechanisms under the Clean Fuel Regulations reduce capital recovery timelines for Ontario and Quebec corridor charging networks. Innovation, Science and Economic Development Canada coordinates spectrum harmonization with US bands to reduce cross-border product fragmentation. Corporate procurement in Toronto and Montreal favors embedded furniture installations.
Mexico
Automotive manufacturing clusters in Nuevo León and Baja California generate component sourcing demand for wireless power assemblies. The country's national telecommunications regulator aligns equipment certification with FCC Part 18 frameworks to facilitate export manufacturing. Guadalajara's electronics assembly sector supplies coil components to North American transmitter manufacturers.
North America Wireless Charging Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology licensing and automotive integration vectors. The market structures around three tiers: semiconductor IP licensors, Tier 1 automotive suppliers, and consumer electronics ecosystem owners. Two strategic archetypes dominate—patent-holding technology platforms and vertically integrated hardware manufacturers. Competitive moves concentrate on Qi2 standard convergence and utility partnership formations for fleet infrastructure.
Within the technology platform tier, WiTricity Corporation and Qualcomm Incorporated anchor patent licensing positions for automotive-grade magnetic resonance architectures. Apple Inc. occupies the consumer electronics ecosystem archetype through proprietary magnetic alignment systems. These three entities exemplify divergent margin capture strategies across inductive frequency bands and resonant air-gap specifications.
| Leading Market Players |
|---|
| WiTricity Corporation |
| Apple Inc. |
| Samsung Electronics Co. Ltd. |
| Qualcomm Incorporated |
| Texas Instruments Inc. |
| Belkin International |
| Powermat Technologies Ltd. |
| Continental AG |
| InductEV Inc. |
| Others |
Cost & Logistics Intelligence
Fleet operator procurement consolidation toward infrastructure-as-a-service contracts is compressing hardware margins and forcing transmitter manufacturers to absorb coil assembly costs upfront. This demand-side shift toward bundled energy management agreements concentrates pricing power with vertically integrated network operators capable of underwriting multi-year deployments.
Pricing Analysis
Value-based pricing anchored to vehicle uptime and energy throughput is displacing per-unit hardware transactions in automotive segments. Three-tier pricing structure across premium, standard, and economy levels separates FCC Part 18 certified systems from uncertified aftermarket alternatives, with thermal cycling resilience warranties commanding substantial premiums. Cost compression in surface-mounted fleet depot systems is intensifying because GaN semiconductor shortages constrain transmitter output capacity. Corporate procurement teams in California's metropolitan corridors exhibit lowest price sensitivity, while residential portable accessory buyers face acute margin pressure from undifferentiated coil imports.
Supply Chain Analysis
Certification gating through Underwriters Laboratories thermal testing and FCC human safety protocols fragments qualified supplier pools and extends component qualification timelines. Power semiconductor foundry capacity draws from Taiwan, South Korea, and Japan, while Litz wire and ferrite core sourcing rests on Chinese and Mexican manufacturing clusters. Single-source vulnerability in automotive-grade GaN wafer supply creates procurement risk for North American transmitter assemblers. Distribution runs through vertically integrated charging network operators that are displacing traditional equipment distributors in California and Texas corridor markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GaN foundry capacity constraints are propping transmitter pricing and extending order backlogs for automotive-grade systems. This supply bottleneck justifies sustained margin premiums for incumbents with captive semiconductor relationships.
For Market Incumbents: Lock in multi-year GaN supply agreements with Taiwanese and South Korean foundries before capacity expansion cycles complete. Secure FCC Part 18 pre-certification for higher-power inductive allocations targeting heavy-duty vehicle classes to outpace regulatory compliance timelines that threaten to extend competitor certification cycles. Defend against emerging Qi2 ecosystem owners by deepening magnetic alignment IP portfolios.
For New Entrants and Emerging Players: Begin with aftermarket retrofit hardware for legacy plug-in hybrid fleets in Texas and Florida corridors, where vehicle-specific coil positioning requirements have fragmented incumbent service protocols. Target embedded furniture installations in Ontario and Quebec corporate procurement markets, where Canada's Clean Fuel Regulations reduce capital recovery timelines and compress incumbent response windows. Pursue hospital system partnerships for sealed wearable health monitors, where FDA biocompatibility protocols create qualification barriers that favor specialized entrants.
For Investors and Strategic Acquirers: Re-rating potential sits with patent-holding technology platforms given Qi2 standard convergence and automotive magnetic resonance licensing expansion. Long-term viability in this market hinges on IP moats around multi-frequency coil architectures and utility partnership formations. Target acquisition archetypes include GaN power conversion specialists with automotive qualification pathways. Watch for ERCOT vehicle-to-building bidirectional pilot scale-up as the inflection signal for fleet infrastructure-as-a-service contract proliferation.
| Strategic Initiative | Industry Significance |
|---|---|
| Qi2 Magnetic Alignment Certification | Wireless Power Consortium standard convergence enables cross-device ecosystem lock-in across premium automotive trims. |
| GaN Semiconductor Supply Agreement | Taiwanese and South Korean foundry partnerships reduce thermal management overhead in underbody charging modules. |
| ERCOT Grid Integration Partnership | Texas utility collaboration opens vehicle-to-building revenue streams beyond passenger automotive applications. |
| FCC Part 18 Pre-Certification Investment | Early compliance with higher-power inductive allocations accelerates market access for heavy-duty vehicle transmitters. |
| Infrastructure-as-a-Service Contract Formation | Vertically integrated charging network operators displace traditional distributors in California metropolitan corridors. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with Tier 1 automotive supplier procurement teams, OEM platform engineers, FCC certification consultants, and utility fleet electrification managers combined with secondary validation from Wireless Power Consortium technical specifications, EPA Resource Conservation and Recovery Act filings, and vehicle production databases. Bottom-up transmitter shipment modeling and top-down infrastructure investment triangulation converged on segment-level estimates.
Granularity-level modeling deployed technology-by-power-class matrices across inductive, resonant, and radio frequency architectures, with installation type and end-user vertical dimensions layered throughout the projection horizon. CAGRs were derived from utility incentive program trajectories, zero-emission vehicle mandate compliance schedules, and fleet operator procurement cycle compression patterns. Automotive content-per-vehicle assumptions and medical device sealing requirement adoption curves fed sector-specific growth calibration.
Copper commodity volatility, foundry capacity expansion delays, and FCC proceeding outcomes on heavy-duty vehicle spectrum allocation are the dominant revision risks to modeled forecasts. A model refresh is warranted upon material change in GaN semiconductor supply availability or Qi2 ecosystem adoption velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Charging Pile Cables Market
Electric Vehicle Charging
Copper in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charging Facilities Market
Electric Vehicle Charging
United States Electric Vehicle Charging Systems and Equipment Market
Electric Vehicle Charging
EV DC Fast Charger Market
Electric Vehicle Charging
Two Wheel Electric Vehicle Charger Market
Electric Vehicle Charging
EV Charging Kiosk Market
Electric Vehicle Charging
Global EV Charging Adapter Market
Electric Vehicle Charging
Electric Vehicle (EV) Public Charging Station Market
Electric Vehicle Charging
Portable Charging Units Market
Electric Vehicle Charging
Japan Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Infrastructure Market
Electric Vehicle Charging
Denmark Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Integrated EV Chargers Market
Electric Vehicle Charging
Oman EV Charging Station Market
Electric Vehicle Charging
Solar-Based Electronic Vehicle Market