
 Integrated EV Chargers Market | 2026-2036
Integrated EV Chargers Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated EV Chargers Market Insights
Certified EV charging technician availability is collapsing across major manufacturing hubs, forcing OEMs to internalize training pipelines. ABB leverages its robotics heritage to automate assembly lines and reduce labor dependency. Tesla sustains vertical control over charger design and deployment through its Supercharger network. Wallbox competes by specializing in compact residential units with embedded load-management software.
An integrated EV charger combines power conversion electronics, communication modules, and safety systems into a single enclosure rated for outdoor operation, typically delivering between 7 kW and 350 kW depending on configuration. These units convert AC grid power to DC for battery replenishment while managing authentication, metering, and grid communication protocols. DC Fast Charging occupies the highest-margin tier as fleet operators and highway corridor developers prioritize throughput over unit cost. Home Chargers lead volume shipments but face commoditization as utilities subsidize mass deployment. Wireless Charging remains nascent, constrained by efficiency gaps and infrastructure retrofit requirements.
NHTSA and the EU Green Deal collectively mandate interoperability standards and minimum efficiency thresholds that shape product roadmaps on both sides of the Atlantic. China's GB standards and SAMR certification requirements create a parallel compliance track for manufacturers serving that supply base. Stakeholders must monitor how evolving grid codes in California, Germany, and China's coastal provinces redefine power-quality specifications before committing to platform architectures.
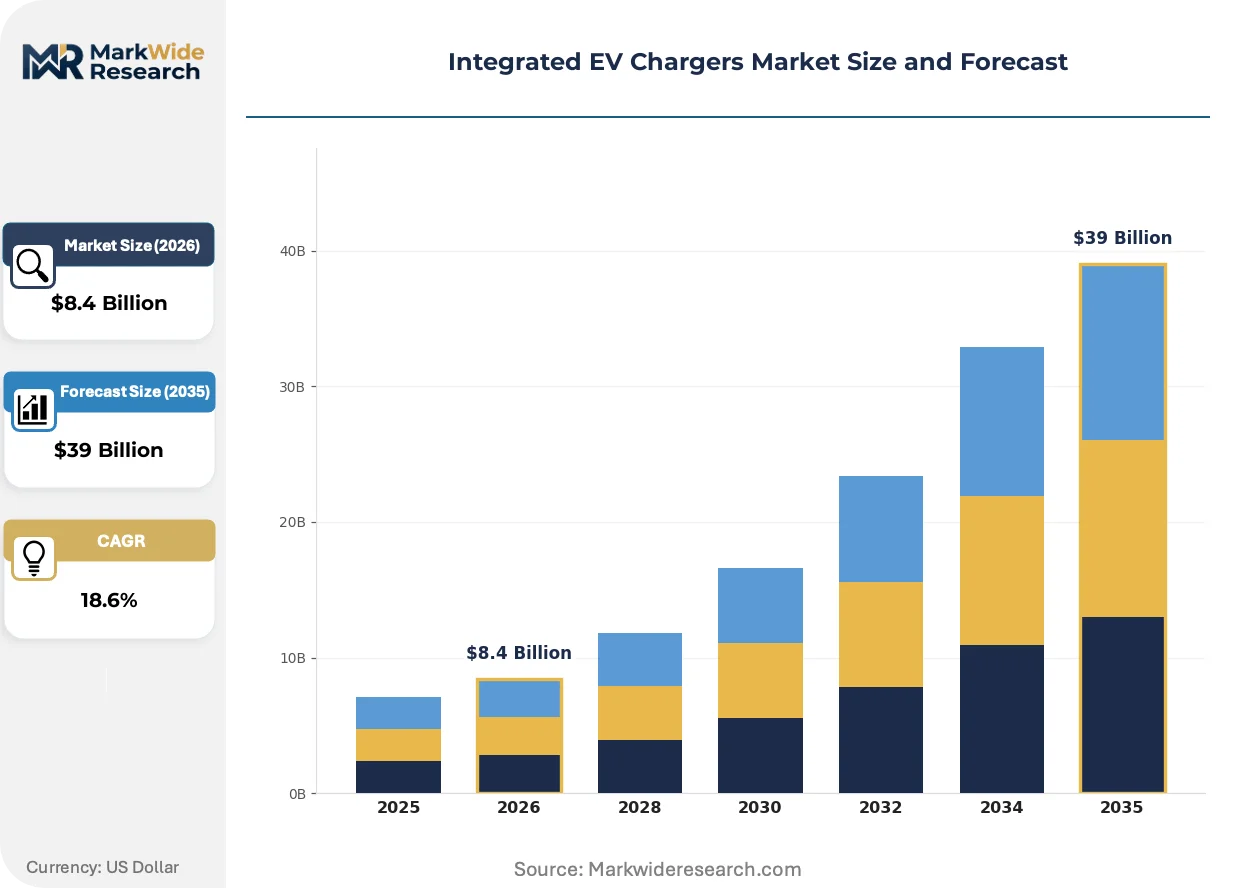
Market Dynamics
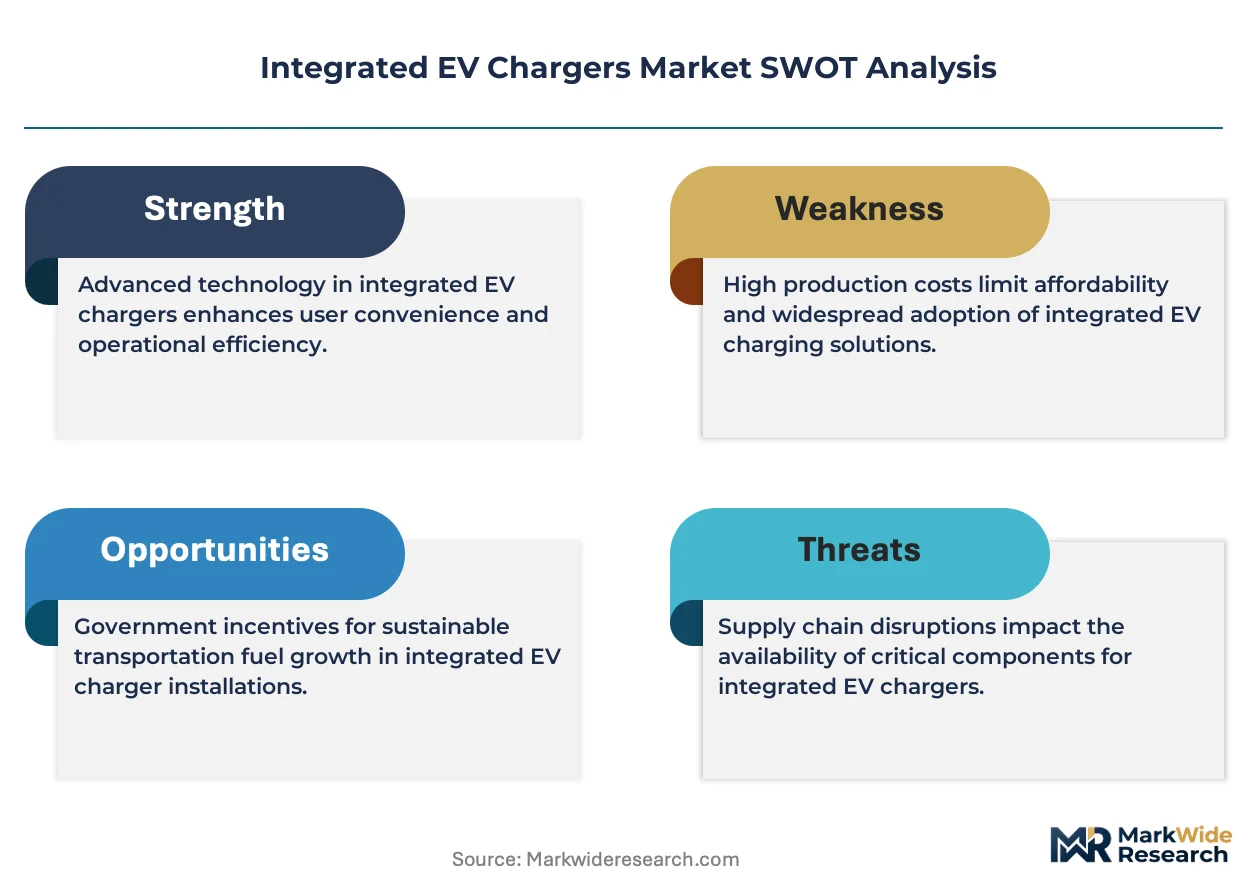
Fleet electrification mandates and grid-interoperability requirements are compressing product development cycles while forcing manufacturers to absorb certification costs previously borne by installers.
Growth Catalysts
- NHTSA Charging Standards:Updated interoperability mandates in the United States eliminate proprietary connector fragmentation, reducing buyer hesitation among multi-brand fleet operators.
- EU Green Deal Infrastructure Mandates:Binding deployment targets for highway corridor charging create guaranteed offtake for DC fast charging manufacturers across member states.
- Load Management Software:Embedded intelligence in residential units enables peak-shaving capabilities that unlock utility partnership programs and subsidized installation channels.
Market Restraints
- Semiconductor Supply Concentration:Power module dependence on East Asian foundries exposes lead times to geopolitical friction and export control volatility.
- Copper and Rare Earth Input Costs:Magnet and winding material price swings compress hardware margins faster than software value-adds can offset.
- Wireless Efficiency Gap:Inductive charging systems face 10-15 percentage point energy losses that disqualify them from fleet applications where throughput economics dominate.
Strategic Opportunities
- India PLI Scheme for ACC Batteries:Domestic cell manufacturing incentives will create parallel demand for compatible charging infrastructure as OEMs localize supply chains.
- V2G Bidirectional Integration:Convergence of onboard inverters with grid-tie electronics opens revenue streams from frequency regulation services in deregulated power markets.
- Subscription-Based Hardware Models:Hardware-as-a-service distribution removes upfront capital barriers for small commercial fleets and multi-unit residential developers.
Industry Challenges
- Certified Technician Scarcity:High-voltage installation and commissioning expertise pools are depleted faster than vocational programs can replenish them across manufacturing hubs.
- Multi-Jurisdiction Certification Timelines:UL, CE, and GB standard testing sequences add 8-14 months to product launches for manufacturers pursuing simultaneous market entry.
- Legacy Grid Integration Complexity:Distribution transformer capacity constraints in dense urban districts require site-specific electrical upgrades that fragment deployment economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated EV Chargers Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Chargers, Public Chargers, Fleet Chargers, Portable Chargers Technology: Level 1, Level 2, DC Fast Charging, Wireless Charging End User: Residential Users, Commercial Users, Municipalities, Charging Networks Installation Type: Wall-Mounted, Standalone, Embedded, Mobile Solutions |
| Companies Covered | ChargePoint, ABB, Tesla, EVBox, Wallbox, Eaton, Delta Electronics, Star Charge, TELD New Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated EV Chargers Market Trends and Innovations
Silicon carbide power electronics and dynamic load balancing algorithms are compressing charger footprints while expanding operating temperature ranges, enabling deployment in previously inaccessible environments.
Silicon carbide MOSFETs are fragmenting the insulated-gate bipolar transistor supplier base by offering 30% switching efficiency gains at equivalent cost curves. Tier 1 automotive suppliers are adopting these devices for 350 kW highway corridor units where thermal management constraints previously limited duty cycles. The technology is fragmenting procurement patterns as OEMs bypass legacy power semiconductor distributors to secure direct foundry allocations.
EU Green Deal efficiency thresholds are mandating 97% minimum power conversion ratings for publicly subsidized installations, rendering transformer-based architectures economically obsolete. Manufacturers serving the European market are accelerating resonant converter designs that were previously niche. German highway corridor developers are responding by specifying liquid-cooled architectures that maintain rated output across ambient temperature swings.
Fleet procurement departments are consolidating vendor relationships around full-lifecycle service agreements that bundle hardware, installation, and predictive maintenance. Traditional equipment distributors are losing relevance as charge point operators establish direct manufacturer relationships. California fleet electrification programs exhibit this pattern most acutely, where megawatt-scale depot installations bypass regional electrical wholesalers entirely.
Integrated EV Chargers Market Segmentation
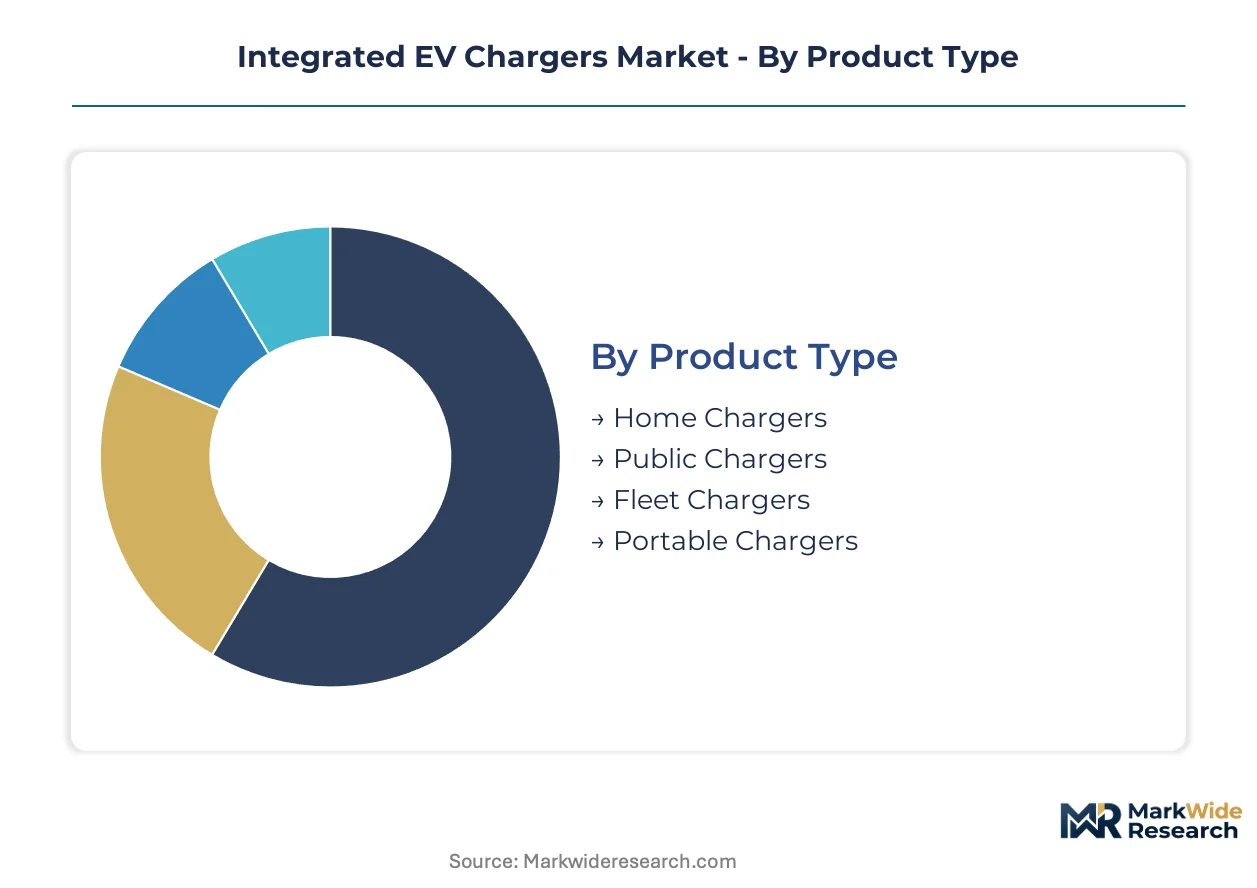
Integrated EV charger segmentation reveals divergent margin structures across product tiers and installation contexts. Fleet procurement patterns and residential utility partnerships create distinct demand profiles that reshape manufacturer portfolio priorities.
Product Type:
Fleet chargers and public infrastructure units dominate export-led manufacturing volumes, while home chargers anchor domestic aftermarket channels across North American and European markets.
- Fleet Chargers:High-capacity depot installations delivering 150-350 kW simultaneous multi-vehicle charging with integrated energy management. Demand concentrates in California and Germany where municipal electrification mandates and highway corridor subsidies compress procurement timelines for logistics operators.
- Home Chargers:Wall-mounted 7-22 kW units with embedded load-balancing software and utility communication modules. North American utilities subsidize mass deployment through demand-response programs, while European markets favor smart-grid integration features mandated by EU Green Deal efficiency thresholds.
- Public Chargers:Highway corridor and urban curbside units requiring NHTSA interoperability certification and payment authentication systems.
- Portable Chargers:Mobile emergency units with lower power output serving roadside assistance networks and rental fleet contingencies.
Home chargers command the established base. The steepest expansion runs through fleet chargers.
Technology:
Power conversion architectures stratify by duty cycle intensity and thermal management requirements, with silicon carbide adoption accelerating most rapidly in high-throughput applications.
- DC Fast Charging:Direct current systems bypassing onboard vehicle inverters to deliver 50-350 kW with liquid-cooled power modules. Highway corridor developers in Germany prioritize these units for EU Green Deal infrastructure targets, while California fleet operators specify them for depot electrification timelines.
- Level 2:240V alternating current systems with 7-19 kW output dominating residential and workplace installations. North American utility rebate programs channel volume through certified contractor networks, creating procurement concentration among regional electrical distributors.
- Level 1:Standard 120V residential outlets providing trickle charging for overnight residential use.
- Wireless Charging:Inductive pad systems constrained by 10-15 percentage point efficiency losses that disqualify fleet applications.
Level 2 retains volume leadership. DC fast charging gains share fastest through fleet procurement consolidation.
End User:
Customer procurement sophistication determines service bundling requirements, with charging networks and municipalities demanding full-lifecycle agreements that bypass traditional equipment distribution.
- Charging Networks:Multi-site operators requiring centralized fleet management software, predictive maintenance contracts, and interoperability certification across jurisdictions. California-based operators exhibit the most acute vendor consolidation, sourcing directly from manufacturers for megawatt-scale installations.
- Municipalities:Public transit agencies and city governments procuring through funded electrification programs with stringent local content requirements. German municipal utilities leverage EU Green Deal subsidies to specify liquid-cooled architectures for bus depot conversions.
- Residential Users:Individual homeowners accessing subsidized installation channels through utility partnership programs.
- Commercial Users:Workplace and retail location operators prioritizing customer dwell-time optimization over charging speed.
Residential users anchor unit shipments. Charging networks drive margin expansion through service bundling.
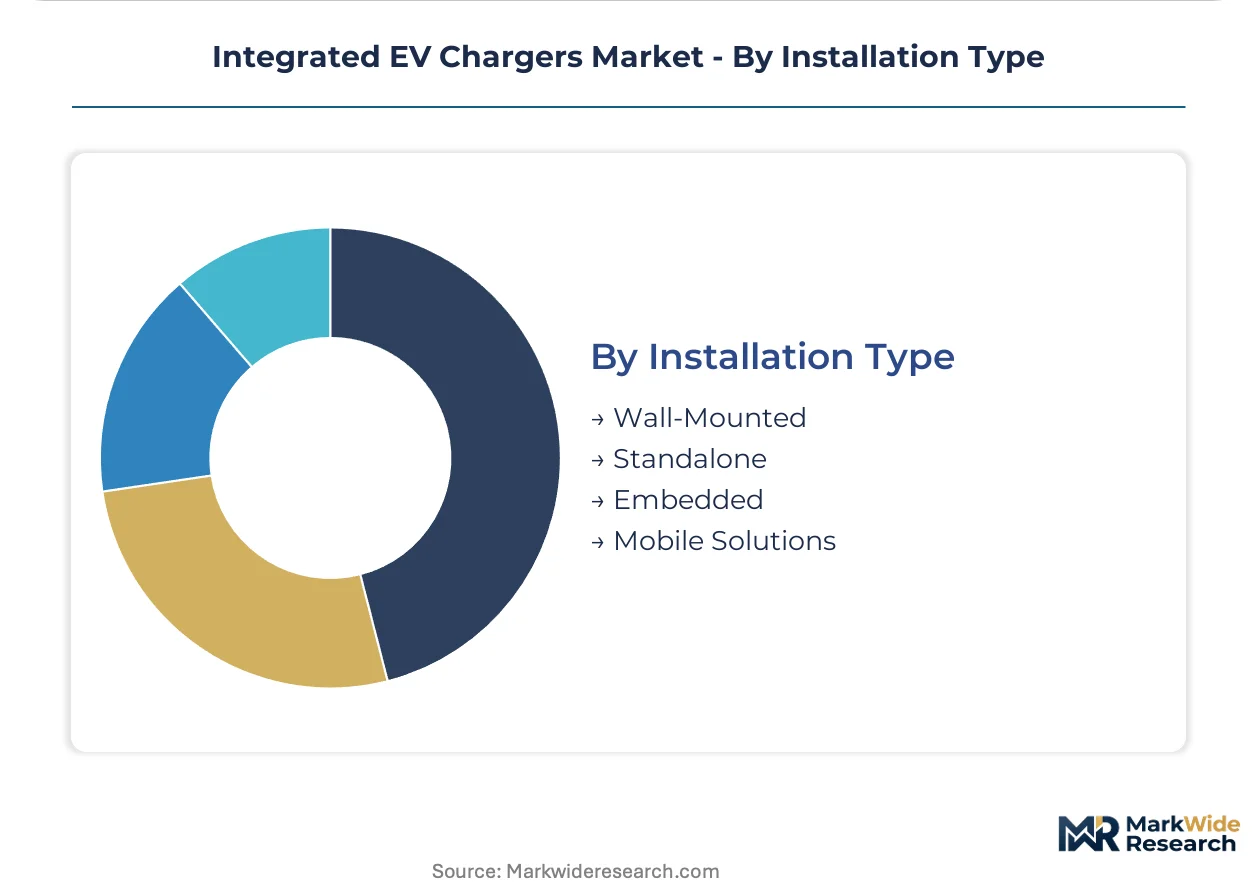
Installation Type:
Physical mounting configurations correlate with grid interconnection complexity and site-specific electrical upgrade requirements.
- Wall-Mounted:Compact residential and light commercial units minimizing footprint through integrated power electronics. North American suburban markets favor these for garage installations, while European apartment blocks require load-management coordination with building infrastructure.
- Standalone:Pedestal and canopy-mounted highway corridor units with transformer integration and payment terminal enclosures. German autobahn service areas specify these for EU-mandated corridor coverage targets.
- Embedded:Structural integration with parking infrastructure and building electrical systems.
- Mobile Solutions:Trailer-mounted and temporary deployment units for event charging and construction site electrification.
Wall-mounted units dominate residential penetration. Standalone installations climb fastest through highway corridor mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA charging standards anchor United States demand, while the EU Green Deal infrastructure mandates and China's GB certification requirements create parallel compliance tracks that fragment manufacturer platform strategies across three regulatory spheres.
United States
Fleet electrification timelines and highway corridor subsidies drive procurement concentration among California logistics operators and Texas energy-sector fleets. NHTSA interoperability mandates eliminate proprietary connector fragmentation, accelerating multi-brand fleet standardization. Los Angeles and Houston anchor megawatt-scale depot installations that bypass regional electrical distributors entirely.
Germany
Autobahn service area coverage targets and municipal bus depot conversions compress deployment schedules for liquid-cooled architectures. EU Green Deal efficiency thresholds mandate 97% minimum power conversion ratings, rendering transformer-based designs economically obsolete. Bavarian highway corridor developers specify resonant converter units for temperature-stable output across ambient swings.
China
Domestic cell manufacturing scale and coastal province grid codes reshape power-quality specifications for export-bound manufacturers. SAMR certification requirements and GB standards create compliance barriers for foreign entrants seeking utility partnership channels. Yangtze River Delta clusters concentrate silicon carbide foundry allocations that bypass legacy semiconductor distributors.
India
PLI scheme incentives for ACC battery manufacturing create parallel infrastructure demand as OEMs localize supply chains. Central Electricity Authority grid codes and state-level EV policies fragment procurement standards across Maharashtra and Gujarat manufacturing hubs. Delhi-NCR transit agencies pilot depot electrification through centrally funded programs with stringent local content requirements.
Japan
Automotive OEM captive demand and METI efficiency roadmaps prioritize bidirectional V2G integration for frequency regulation services. JIS standards and utility deregulation experiments in Kansai and Chubu regions shape product specifications for residential and commercial segments. Nagoya-area industrial electronics suppliers consolidate around silicon carbide module architectures for next-generation highway units.
Integrated EV Chargers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure consolidating around full-lifecycle service bundling rather than hardware differentiation alone. Tier 1 automotive suppliers and electrical equipment conglomerates occupy premium positions through captive semiconductor sourcing and direct utility relationships. Strategic archetypes include vertical integrators controlling foundry-to-deployment value chains, software-specialized residential players, and scale-driven charge point operators consolidating vendor relationships. Dominant competitive moves encompass direct foundry allocations bypassing legacy distributors, and predictive maintenance contracts that displace traditional equipment wholesalers.
Among North American charge point operators, ChargePoint occupies a position exemplifying network-scale procurement consolidation, while Tesla anchors vertical integration from power module design through Supercharger deployment. ABB represents the industrial-electronics conglomerate archetype with robotics heritage informing automated assembly approaches. These three entities illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| ChargePoint |
| ABB |
| Tesla |
| EVBox |
| Wallbox |
| Eaton |
| Delta Electronics |
| Star Charge |
| TELD New Energy |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with silicon carbide foundries lock in both semiconductor supply access and hardware cost visibility for manufacturers serving NHTSA-certified and EU Green Deal-mandated installations. These arrangements insulate procurement departments from spot-market volatility in power electronics while compressing margins for competitors without similar upstream commitments.
Pricing Analysis
California fleet operators pay premiums of 15-20 percent above German highway corridor equivalents for identically specced 350 kW units, reflecting divergent certification burdens and site-specific electrical upgrade costs. The dominant structure stratifies across premium liquid-cooled architectures, standard air-cooled depot systems, and economy residential wall-mounted units differentiated by load-management software sophistication and UL certification tier. Pricing pressure stems from copper and rare earth magnet cost swings that outpace software value-add offsets. Residential utility partnership channels exhibit acute price sensitivity, while charging networks prioritize throughput reliability over unit economics.
Supply Chain Analysis
Strait of Malacca transit routes underpin 70 percent of global silicon carbide wafer shipments from Taiwanese and South Korean foundries to power module assemblers in Germany and China. Magnet winding copper concentrates in Chilean and Peruvian mining output, while rare earth processing clusters in China's Jiangxi and Inner Mongolia provinces. Single-source vulnerability in 200mm silicon carbide substrate supply exposes lead times to export control friction. Distribution runs through direct manufacturer relationships with charge point operators, displacing legacy electrical equipment wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance contracts and software subscription layers are expanding at triple the rate of hardware shipments, converting capital expenditure barriers into recurring revenue streams for charging network operators and fleet managers.
For Market Incumbents: Secure direct foundry allocations for silicon carbide MOSFETs before tier-two automotive suppliers exhaust available 2025-2026 capacity reservations. Consolidate around full-lifecycle service bundling that displaces traditional equipment distributors, as California megawatt-scale depot installations already bypass regional electrical wholesalers entirely. Vertical integration into automated assembly reduces labor dependency where certified technician availability is collapsing. For New Entrants and Emerging Players: Anchor in India's PLI scheme corridors where ACC battery manufacturing incentives create parallel charging infrastructure demand without entrenched incumbent relationships. Target Maharashtra and Gujarat state-level procurement programs with locally compliant hardware before national standardization consolidates vendor pools. Pursue hardware-as-a-service distribution models that remove upfront capital barriers for small commercial fleets. For Investors and Strategic Acquirers: The market sits at a standardization phase that favors charge point operators with captive software platforms and direct utility relationships over pure-play hardware manufacturers. Five-to-ten year viability hinges on V2G bidirectional integration capabilities and frequency regulation service revenue streams in deregulated power markets. Monitor NHTSA interoperability mandate enforcement as the inflection signal determining which connector architectures achieve de facto standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Partnership | Direct wafer allocations from Taiwanese foundries bypass legacy semiconductor distributors and secure power module supply. |
| Predictive Maintenance Platform Launch | Software subscriptions convert hardware margins into recurring revenue streams with charging network operators. |
| V2G Bidirectional Certification | Grid-tie electronics integration unlocks frequency regulation revenues in California and German deregulated markets. |
| EU Green Deal Efficiency Compliance | Resonant converter designs meeting 97% conversion thresholds render transformer architectures obsolete in European procurement. |
| Hardware-as-a-Service Distribution | Subscription models remove capital barriers for India PLI-linked fleet operators and multi-unit residential developers. |
Research Methodology
The analysis maps DC fast charging, Level 2 residential, and fleet depot sub-sectors, each validated through charge point operator procurement directors, utility demand-side management officers, and Tier 1 automotive supplier power electronics engineers. Primary fieldwork combined with secondary validation against NHTSA regulatory filings, EU Green Deal infrastructure deployment databases, and SAMR certification registries. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across the analysis window.
Consistency checks validated volume and value outputs against IEA EV charging infrastructure databases, California Energy Commission rebate program disclosures, and German autobahn service area deployment records. The analytical framework modeled technology architecture, installation type, and end-user procurement sophistication across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with policy-mandated deployment timelines and fleet electrification schedules. Forecast inputs incorporated silicon carbide adoption curves and certified technician pipeline constraints.
Material uncertainties — semiconductor export control expansion, copper price volatility, and multi-jurisdiction certification timeline extensions — sit outside the modeled envelope. Forecasts reflect assumptions about NHTSA interoperability enforcement and EU Green Deal subsidy continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Netherlands Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Spain Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Italy Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Connector Market
Electric Vehicle Charging
EV Charging Facilities Market
Electric Vehicle Charging
EV Charging Management Software Platform Market
Electric Vehicle Charging
US Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
AC Electric Vehicle Charging Station Market
Electric Vehicle Charging
Public EV Charger Market
Electric Vehicle Charging
North America EV Charging Stations Market
Electric Vehicle Charging
Smart EV Charger Market
Electric Vehicle Charging
EV Solar Charging Wallbox Market
Electric Vehicle Charging
Electric Vehicle 800-Volt Charging Pile Market
Electric Vehicle Charging
Electric Vehicle Charging Plugs Market