
 Graphene Nanoplatelets Market | 2026-2036
Graphene Nanoplatelets Market Size, Share, and Industry Trends Forecast 2026-2036
Graphene Nanoplatelets Market Intelligence
REACH is repositioning European manufacturers toward certified supply chains with full material traceability. NanoXplore Inc. leverages vertically integrated production from graphite feedstock to functionalized dispersions. XG Sciences, Inc. anchors its position through proprietary xGnP manufacturing platforms that control flake dimensions. Global Graphene Group differentiates via multi-layer patent portfolios spanning synthesis and surface modification chemistries.
Graphene nanoplatelets consist of stacked graphene sheets with lateral dimensions of one to tens of micrometers and thicknesses between one and fifteen nanometers, typically produced through liquid-phase exfoliation or chemical vapor deposition for thermal and electrical conductivity enhancement. The powder form dominates current shipment volumes due to compatibility with existing polymer compounding infrastructure, while dispersions capture expanding margin pools in conductive ink formulations. Battery additives represent the fastest-growing application segment as cell manufacturers seek silicon-anode stabilization, though reinforcement applications in aerospace retain the highest per-kilogram pricing.
The EPA governs occupational exposure limits for nanomaterial handling in US manufacturing facilities, while REACH mandates registration and hazard communication for graphene substances imported into the European Economic Area. BIS in India has initiated framework development for graphene material standards to support domestic electronics manufacturing incentives. Stakeholders must monitor how evolving nanomaterial classification protocols across these jurisdictions reshape import documentation and downstream liability structures.
Market Dynamics
REACH registration requirements and EU Green Deal material mandates are forcing manufacturers to rebuild supply chains around certified feedstock traceability, compressing procurement timelines for automotive and battery-grade material qualification.
Growth Catalysts
- EV Battery Stabilization:Silicon-anode chemistries in lithium-ion cells require graphene nanoplatelet conductive networks to manage volume expansion during charge cycling, pulling volume from Korean and Chinese cell manufacturers.
- REACH Compliance:European Economic Area registration mandates for nanomaterials above one tonne annually are creating first-mover advantages for pre-registered suppliers with documented hazard communication protocols.
- Thermal Interface Materials:Data center cooling infrastructure is absorbing high-aspect-ratio nanoplatelets for gap-filling compounds, driven by rack density increases in hyperscale facilities across Germany and the Netherlands.
Market Restraints
- Graphite Feedstock Concentration:Spherical graphite precursor supply concentrates in Chinese processing facilities, exposing European and North American dispersion manufacturers to export licensing volatility and carbon border adjustment exposure.
- Exfoliation Yield Limits:Liquid-phase exfoliation methods achieve sub-ten-percent monolayer conversion rates, constraining cost-competitive production of thin-flake grades required for transparent conductive film applications.
- Carbon Fiber Substitution:Mature carbon fiber supply chains in aerospace structural applications resist displacement despite graphene-enhanced thermoplastic promises, due to qualified material databases and repair infrastructure lock-in.
Strategic Opportunities
- Indian Electronics Manufacturing:BIS framework development for graphene material standards aligns with production-linked incentive schemes for semiconductor packaging, opening qualification pathways for thermal management compounds.
- Construction Cement Reinforcement:Mechanical property enhancement in low-carbon concrete formulations represents an unpenetrated volume channel, with pilot projects active in Spanish and Italian infrastructure programs.
- Recyclable Polymer Integration:Compatibility advances with post-consumer recycled polypropylene streams are unifying circular economy mandates from the EU Green Deal with automotive interior panel specifications.
Industry Challenges
- Metrology Standardization:Absence of harmonized flake thickness measurement protocols between Raman spectroscopy and atomic force microscopy methods delays batch release decisions and customer qualification timelines.
- Functionalization Scale-Up:Surface chemistry modifications required for polymer matrix compatibility demand reactor investments with long depreciation horizons, straining mid-cap producers seeking automotive Tier-2 supplier status.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphene Nanoplatelets Market |
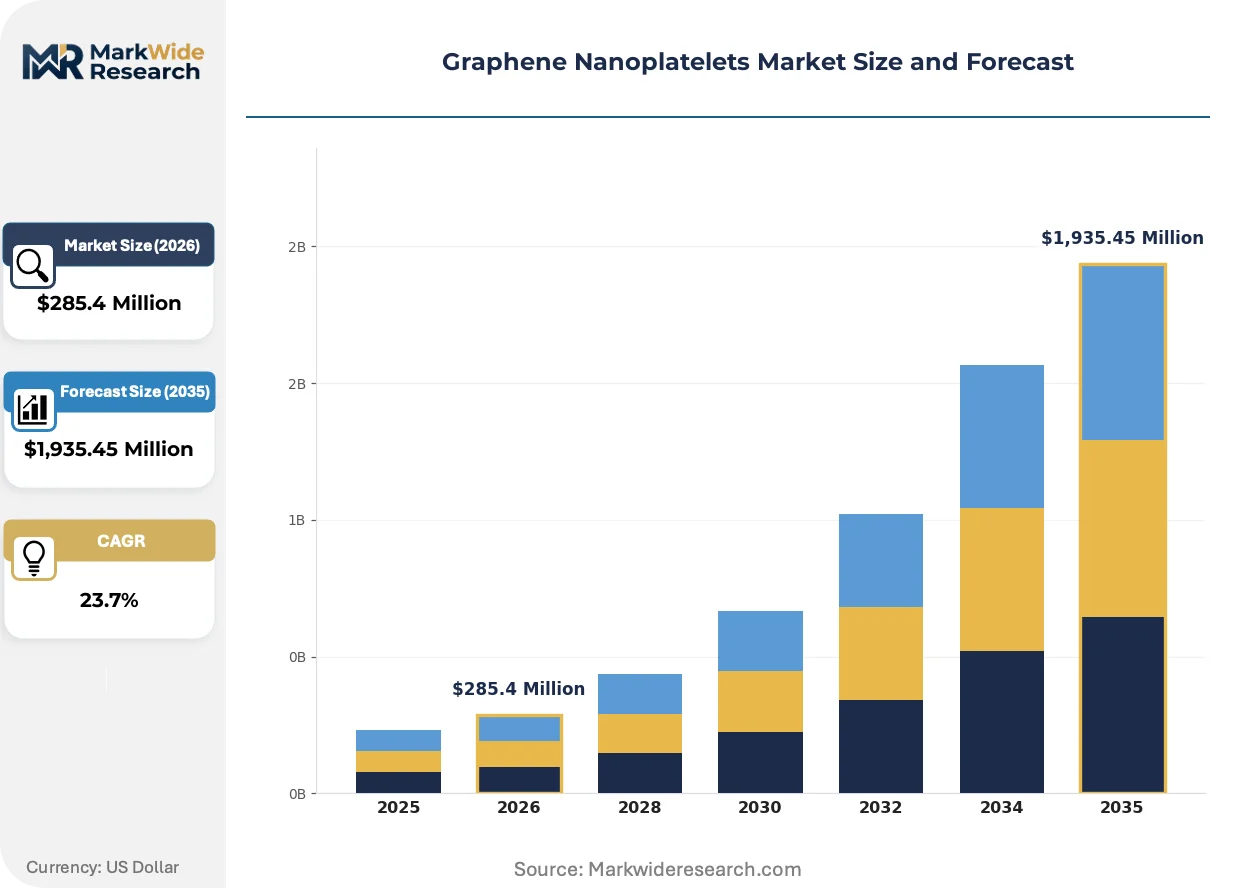
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,935.45 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Grade, High Purity, Functionalized, Composite End User: Electronics, Aerospace, Energy, Coatings Application: Conductive Inks, Battery Additives, Reinforcement, Sensors Form: Powder, Dispersions, Sheets, Films |
| Companies Covered | NanoXplore Inc., XG Sciences, Inc., Global Graphene Group, ACS Material, Haydale Graphene Industries, Graphenea, CVD Equipment Corporation, Directa Plus, Thomas Swan & Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphene Nanoplatelets Market Strategic Shifts & Innovations
Process intensification in exfoliation methods and regulatory harmonization efforts are compressing the gap between laboratory-grade material and industrial-scale qualification, reshaping how buyers evaluate supplier technical capabilities.
Electrochemical exfoliation using bipolar electrode configurations is unifying high-throughput production with controlled defect engineering, enabling battery manufacturers to specify consistent surface area metrics across hundred-kilogram batches. Korean cathode material suppliers are adopting these protocols ahead of European cell factory ramp-ups. The structural consequence is compressing qualification cycles from thirty-six months toward eighteen months for automotive supply chain entry.
ECHA substance evaluation under REACH is tightening information requirements for graphene oxide and reduced graphene oxide classifications, forcing importers to commission extended one-generation reproductive toxicity studies. Industrial coating formulators in the Netherlands and Belgium are absorbing these costs into premium product lines. The segment most affected is construction-sector anti-corrosion primers, where downstream liability concerns are accelerating substitution toward pre-registered dispersion suppliers.
Automotive OEMs are consolidating qualified material suppliers from dozens toward three-to-five strategic partnerships per component category, compressing vendor management overhead but intensifying price negotiation leverage. This concentration pattern is displacing spot-market purchasing for structural composite prepregs. German industrial corridors exhibit the most visible consolidation, with Bavarian and Baden-Württemberg automotive clusters issuing unified material specifications across multiple Tier-1 suppliers.
Graphene Nanoplatelets Market Segmentation
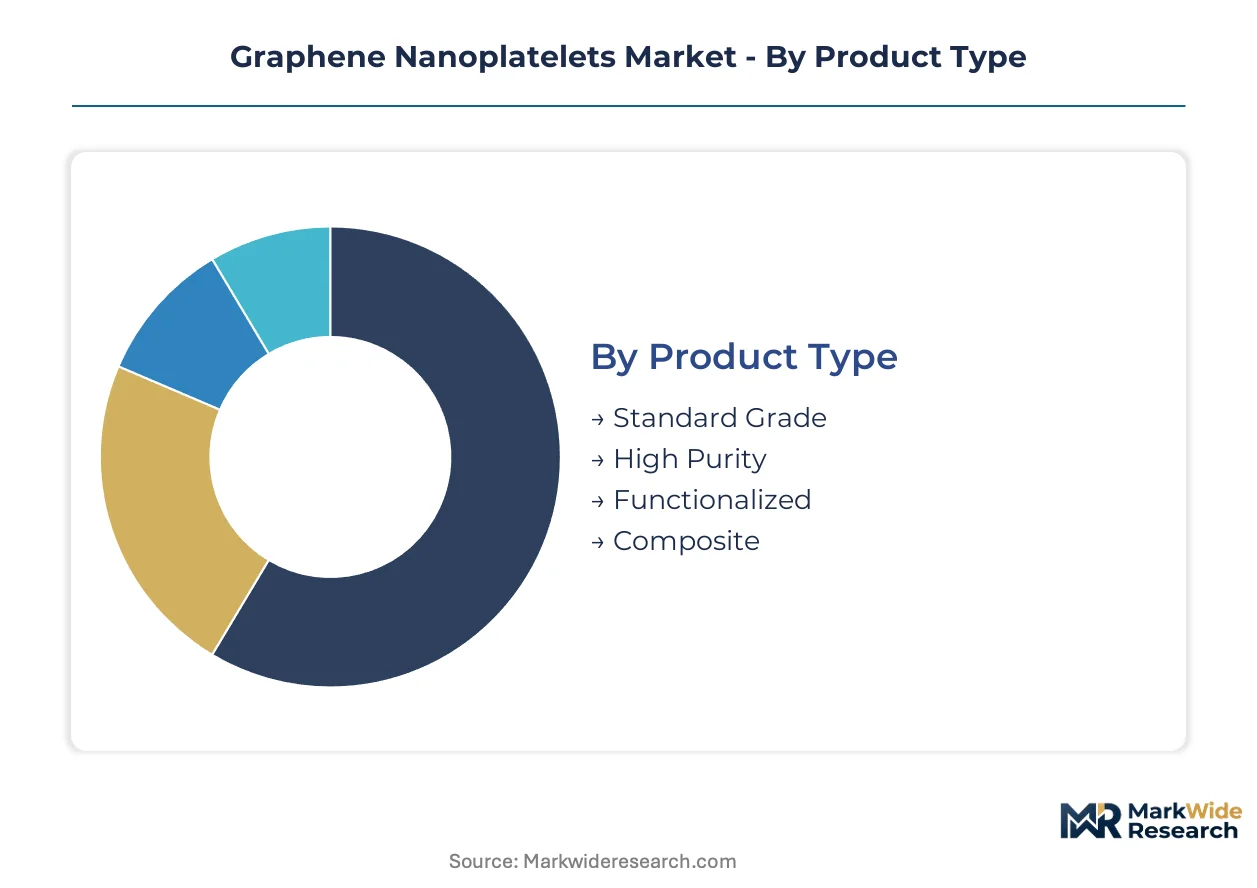
Segmentation in graphene nanoplatelets reveals how specification hierarchies separate commodity volume plays from premium qualification pathways. Buyers navigate trade-offs between flake thickness control, surface chemistry modification, and downstream processing compatibility.
Product Type:
Thickness distribution and surface chemistry modification define the specification ladder that separates industrial-grade volume from automotive-qualified premium tiers.
- Standard Grade:Multi-layer flake structures with 5-15 nanometer thickness dominate polymer compounding volumes. Korean battery manufacturers absorb standard-grade powder for silicon-anode conductive networks in cylindrical cell formats.
- High Purity:Reduced metallic impurity profiles below 100 ppm enable semiconductor thermal interface applications. German data center operators specify high-purity dispersions for direct-chip cooling compounds in Frankfurt and Munich hyperscale facilities.
- Functionalized:Surface-modified variants with carboxyl or amine terminations improve polymer matrix adhesion.
- Composite:Pre-dispersed masterbatch formats accelerate compounding throughput for automotive Tier-2 suppliers.
Standard Grade leads on scale; Functionalized leads on momentum.
End User:
Customer sophistication and qualification burden create distinct service models across terminal demand channels.
- Electronics:Thermal management and EMI shielding specifications drive thickness uniformity requirements. Indian semiconductor packaging facilities under PLI schemes are qualifying nanoplatelet compounds for flip-chip interconnects.
- Aerospace:Qualified material databases and repair infrastructure lock-in sustain carbon fiber dominance despite graphene-enhanced thermoplastic promises. French and Italian airframe suppliers pilot lightning strike protection films on regional jet programs.
- Energy:Cell manufacturers specify consistent surface area metrics across hundred-kilogram batches.
- Coatings:Anti-corrosion primers face ECHA substance evaluation tightening under REACH.
Energy leads on scale; Electronics leads on momentum.
Application:
Performance requirements and margin structures diverge sharply between formulation-intensive and reinforcement-dominated use cases.
- Conductive Inks:Flexographic and inkjet formulations demand sub-5 nanometer thickness for transparent electrode conductivity. Dutch industrial coating formulators are absorbing REACH registration costs into premium product lines for construction-sector anti-corrosion primers.
- Battery Additives:Silicon-anode stabilization networks require controlled defect engineering for cycle life management. Korean cathode material suppliers are adopting electrochemical exfoliation protocols ahead of European cell factory ramp-ups.
- Reinforcement:Mechanical property enhancement in low-carbon concrete represents unpenetrated volume channels.
- Sensors:Surface area-dependent chemiresistive response enables gas detection applications.
Battery Additives leads on scale; Conductive Inks leads on momentum.
Form:
Physical presentation determines compatibility with incumbent processing infrastructure and logistics economics.
- Powder:Dry flake formats integrate with twin-screw extrusion and ball milling equipment prevalent in polymer compounding. Powder dominates current shipment volumes due to compatibility with existing infrastructure.
- Dispersions:Solvent-based and aqueous suspensions capture expanding margin pools in conductive ink formulations. REACH-compliant dispersion suppliers with documented hazard communication protocols are gaining first-mover advantages in European Economic Area markets.
- Sheets:Self-supporting formats enable lamination processes for thermal interface assembly.
- Films:Cast or deposited layers target transparent electrode and barrier coating applications.
Powder leads on scale; Dispersions leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Materials scientists and polymer engineers cluster around automotive battery corridors and semiconductor packaging zones, anchoring demand geography to established manufacturing ecosystems rather than raw material sources.
Germany
Bavarian automotive clusters specify graphene-enhanced thermoplastic prepregs for structural EV components. REACH registration mandates force importers to document full material traceability through ECHA portals. Baden-Württemberg OEMs consolidate qualified suppliers from dozens toward three-to-five strategic partnerships per component category.
United States
EPA occupational exposure limits govern nanomaterial handling in Texas and Michigan battery manufacturing facilities. The Inflation Reduction Act's domestic content incentives pull Korean cell manufacturers toward Arizona and Georgia factory sites. Research Triangle Park in North Carolina hosts pilot-scale dispersion facilities serving semiconductor thermal management applications.
South Korea
Cathode material suppliers adopt electrochemical exfoliation protocols ahead of European cell factory qualification cycles. MFDS frameworks for nanomaterial safety documentation align with export requirements for EU-bound battery additives. Busan-Ulsan industrial corridors concentrate graphene dispersion capacity serving LG Energy Solution and Samsung SDI supply chains.
China
Spherical graphite precursor processing dominates feedstock supply for global nanoplatelet production. MIIT standards for graphene material classification support domestic electronics manufacturing incentives. Yangtze River Delta dispersion manufacturers face carbon border adjustment exposure on European exports.
India
BIS framework development for graphene material standards aligns with PLI schemes for semiconductor packaging. Karnataka's Electronics City hosts qualification programs for thermal management compounds in flip-chip interconnects. Tamil Nadu battery assembly plants pilot silicon-anode stabilization networks for two-wheeler EV platforms.
Graphene Nanoplatelets Market Key Industry Players
The competitive structure tilts toward vertically integrated specialists with captive graphite feedstock control. Tier-1 automotive qualification barriers compress the vendor base into three functional tiers: pre-registered REACH suppliers with documented hazard protocols, mid-cap dispersion manufacturers seeking Tier-2 supplier status, and laboratory-scale producers locked in thirty-six-month qualification cycles. Consolidation pressures intensify as OEMs reduce vendor management overhead through strategic partnership reduction.
Among North American-registered entities, NanoXplore Inc. and XG Sciences, Inc. occupy positions within the integrated production archetype, while Global Graphene Group exemplifies multi-layer patent portfolio strategies. These three anchors represent divergent paths to automotive supply chain entry: backward integration into graphite feedstock, proprietary manufacturing platform control, and synthesis-to-surface-modification patent coverage. European-originated players including Haydale Graphene Industries and Directa Plus sit within the dispersion-specialist tier, competing on REACH pre-registration status and documented batch consistency. The structural consequence compresses price negotiation leverage toward OEMs while raising capital barriers for mid-cap qualification attempts.
| Leading Market Players |
|---|
| NanoXplore Inc. |
| XG Sciences, Inc. |
| Global Graphene Group |
| ACS Material |
| Haydale Graphene Industries |
| Graphenea |
| CVD Equipment Corporation |
| Directa Plus |
| Thomas Swan & Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Automotive OEM consolidation of qualified suppliers toward three-to-five strategic partnerships per component category is compressing procurement timelines and forcing dispersion manufacturers to absorb REACH registration costs into premium product lines. This buyer-driven concentration is reshaping how suppliers price functionalized grades and allocate capacity across battery additive versus thermal management applications.
Pricing Analysis
Unbundled powder shipments for polymer compounding command lower per-kilogram rates than dispersion formats with documented hazard communication protocols. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered functionalized grades from standard multi-layer flake and high-purity variants. Cost compression in standard-grade powder is intensifying because Korean and Chinese cell manufacturers are consolidating cylindrical cell procurement volumes. Battery additive buyers exhibit highest price sensitivity due to silicon-anode cost targets, while semiconductor thermal interface specifications tolerate premium dispersion pricing.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for automotive-qualified masterbatch formats, while spot-market purchasing for construction-sector primers flows through distribution intermediaries. Spherical graphite precursor processing concentrates in China, with dispersion manufacturing clustering in South Korea and Germany. The supply chain draws from liquid-phase exfoliation equipment, surface modification reactor capacity, and polymer compounding infrastructure. Single-source vulnerability in Chinese feedstock exposes European formulators to carbon border adjustment exposure and export licensing volatility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH pre-registration status in Europe commands premium pricing against emerging BIS qualification pathways in India with lower compliance overhead.
For Market Incumbents: Cement automotive Tier-2 supplier status through captive reactor investments for surface chemistry modifications that polymer matrix compatibility demands. Lock in spherical graphite offtake agreements to defend against Chinese export licensing volatility. Prioritize documented batch consistency metrics that compress eighteen-month qualification cycles toward twelve-month windows for Korean cathode material suppliers. For New Entrants and Emerging Players: Construction-sector anti-corrosion primer formulators represent an underserved buyer archetype displaced by ECHA substance evaluation tightening. Capture share in Spanish and Italian low-carbon concrete pilot programs where mechanical property enhancement specifications remain undefined. Lead with aqueous dispersion formats that bypass solvent-handling infrastructure requirements at mid-scale coating operations. For Investors and Strategic Acquirers: Asymmetric upside sits with dispersion-specialist tier players holding REACH pre-registration status and documented hazard protocols. Five-to-ten year viability hinges on electrochemical exfoliation scale-up capabilities that unify high-throughput production with controlled defect engineering. Watch Korean cathode material supplier adoption rates of bipolar electrode configurations as inflection indicator for qualification cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Graphite Feedstock | Captive spherical graphite supply insulates NanoXplore and XG Sciences from Chinese export licensing volatility. |
| REACH Pre-Registration Investment | Documented hazard communication protocols create first-mover advantages in European Economic Area battery additive procurement. |
| Electrochemical Exfoliation Scale-Up | Bipolar electrode configurations enable Korean cathode suppliers to specify consistent surface area metrics across hundred-kilogram batches. |
| Functionalized Dispersion Capacity Addition | Surface-modified variants with carboxyl terminations improve polymer matrix adhesion for automotive interior panel specifications. |
| Indian BIS Qualification Pathway | Production-linked incentive alignment opens thermal management compound opportunities at Karnataka Electronics City facilities. |
Research Approach
Multiple input streams — primary interviews with plant managers and procurement leads at downstream OEMs, technical R&D directors at dispersion manufacturers, and distribution channel partners — were reconciled against customs and trade data, SEC filings from North American-registered entities, and ECHA registration databases. Bottom-up volume modeling across powder, dispersion, sheet, and film formats was cross-validated through top-down triangulation against polymer compounding throughput estimates and battery cell production forecasts.
Historical capacity utilization patterns were cross-referenced against panel input from materials scientists and polymer engineers to generate projection trajectories across the analysis window. Segmentation dimensions modeled include product grade tier, end-use industry channel, physical form factor, and regional production hub clustering. CAGRs were derived through slope-intercept analysis of normalized adoption curves, with specific inputs from silicon-anode penetration rates in cylindrical cell formats and data center rack density expansion in German hyperscale facilities.
Inputs from ECHA substance evaluation timelines and BIS framework development proceedings were available through the study window; gaps in harmonized flake thickness measurement protocol adoption introduce uncertainty bands around batch release timing assumptions. Forecasts reflect documented assumptions regarding exfoliation yield improvements and automotive supplier consolidation trajectories. Periodic stress-testing of base assumptions against Korean cathode material supplier qualification cycle compression is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Spintronics Market
Emerging and Next Generation Technologies
Nanoelectronics Market
Emerging and Next Generation Technologies
Ultra-Thin Solar Cells Market
Emerging and Next Generation Technologies
Nanopatterning Market
Emerging and Next Generation Technologies
Asia-Pacific MPU Market
Emerging and Next Generation Technologies
Laser Technology Market
Emerging and Next Generation Technologies
Mexico Cleanroom Technology Market
Emerging and Next Generation Technologies
Asia Pacific Quantum Computing Market
Emerging and Next Generation Technologies
Programmable Semiconductor Technologies Market
Emerging and Next Generation Technologies
Ultra-Fine Ath Market
Emerging and Next Generation Technologies
Flexible Hybrid Electronics (FHE) Market
Emerging and Next Generation Technologies
Next Generation Processors Market
Emerging and Next Generation Technologies
Global Hybrid Intelligence Market
Emerging and Next Generation Technologies
Global Next Generation Computing Market
Emerging and Next Generation Technologies
Swarm Computing Market
Emerging and Next Generation Technologies
Next Gen TV (ATSC TV) Market