
 Swarm Intelligence Market | 2026-2036
Swarm Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
Swarm Intelligence Market Analysis
ISO/IEC 23053 for AI system trustworthiness is bifurcating the competitive landscape between certified enterprise suppliers and uncertified niche developers. Unanimous A.I. leverages its human-swarm hybrid platform to dominate commercial forecasting applications. Hydromea anchors its position in underwater swarm robotics for offshore infrastructure inspection. Sentien Robotics specializes in autonomous ground swarms for warehouse logistics, competing on deployment speed rather than algorithmic sophistication.
Swarm intelligence denotes decentralized coordination architectures where multiple agents interact through local rules to produce emergent collective behavior, typically operating with sub-second communication latency and fault-tolerant topologies that maintain mission continuity when individual nodes fail. The approach serves industrial purposes ranging from predictive maintenance routing to distributed environmental monitoring. Robotics applications within the application dimension command the largest installed base, while optimization solutions extract premium pricing from supply-chain clients. Agent-based systems within the technology dimension show the steepest capability curve, though artificial neural networks retain the broadest interoperability with legacy enterprise stacks.
The U.S. FAA regulates beyond-visual-line-of-sight drone operations under Part 107 waivers, constraining commercial swarm deployment timelines and forcing vendors to maintain dual development tracks for restricted and unrestricted airspace. The EU AI Act's high-risk system classification triggers conformity assessment obligations for defense and transportation end users, redirecting procurement toward auditable algorithmic architectures. Stakeholders must monitor whether emerging military export controls on swarm coordination software fragment vendor addressable markets or create protected domestic supply bases.
Market Dynamics
Decentralized coordination architectures are displacing centralized command systems across defense and industrial robotics, as sub-second latency requirements and fault-tolerant topologies become non-negotiable performance benchmarks for mission-critical deployments.
Growth Catalysts
- DARPA OFFSET program:Autonomous swarm prototyping contracts accelerate algorithmic maturation for urban warfare scenarios, pulling venture capital into adjacent commercial applications.
- EU AI Act high-risk classification:Conformity assessment obligations redirect procurement toward auditable architectures, creating first-mover advantages for certified vendors.
- Predictive maintenance routing:Oil and gas operators deploy underwater swarm inspection systems to reduce platform downtime, generating recurring service revenue for robotics integrators.
Market Restraints
- Lithium-polymer battery supply:Energy density limitations constrain flight endurance for aerial swarms below 45 minutes, tethering commercial use cases to short-range missions.
- Dual-use export controls:Coordination software restrictions fragment vendor addressable markets, forcing redundant development tracks for domestic and international product variants.
- Beyond-visual-line-of-sight waivers:FAA Part 107 constraints delay commercial deployment timelines, compressing revenue recognition for U.S.-focused operators.
Strategic Opportunities
- Offshore wind inspection:North Sea operators lack scalable turbine maintenance solutions, creating white space for underwater swarm service providers.
- ISO/IEC 23053 certification:Trustworthiness frameworks enable premium positioning for enterprise suppliers against uncertified niche developers.
- 5G network slicing:Ultra-reliable low-latency communication converges with edge computing to enable real-time swarm coordination in dense urban environments.
Industry Challenges
- Distributed systems engineering talent:Shortage of specialists in emergent behavior modeling and fault-tolerant topology design constrains R&D velocity for mid-tier vendors.
- Algorithmic audit trails:EU AI Act documentation requirements extend certification timelines by 12-18 months, delaying product launches for architecture redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swarm Intelligence Market |
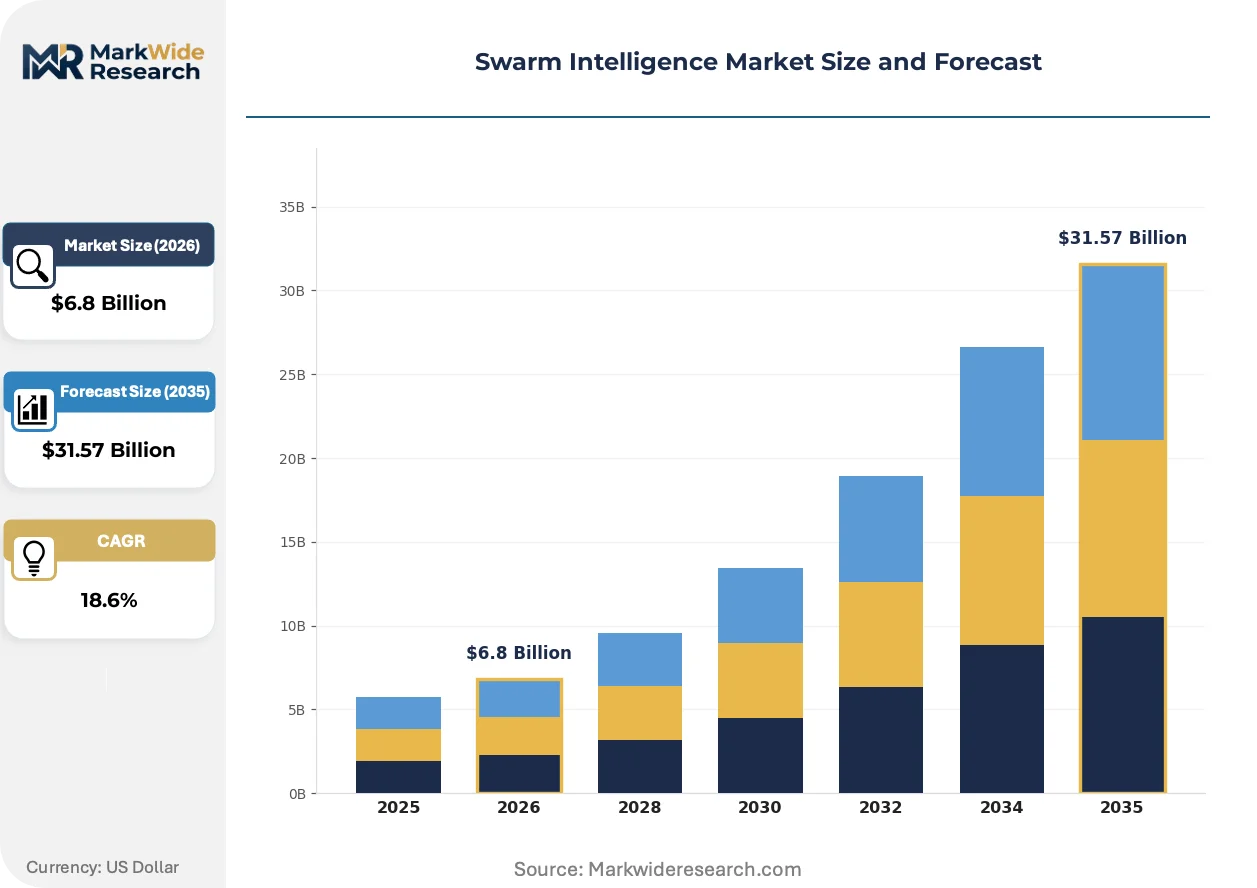
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.57 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Robotics, Optimization, Network Routing, Data Analysis Technology: Artificial Neural Networks, Agent-Based Systems, Bio-Inspired Algorithms, Distributed Computing End User: Defense, Healthcare, Agriculture, Transportation Solution: Simulation Tools, Decision Support Systems, Collaborative Platforms, Risk Management Solutions |
| Companies Covered | Unanimous A.I., Hydromea, Kim Technologies, DoBots, Swarm Technology, Sentien Robotics, Valutico, ConvergentAI, Inc, Power-Blox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swarm Intelligence Market Emerging Trajectories
Edge-native processing architectures and regulatory pressure for algorithmic transparency are compressing development cycles while fragmenting competitive positioning between certified enterprise suppliers and agile niche developers.
Onboard neuromorphic computing chips are miniaturizing swarm node power consumption below 500 milliwatts while maintaining inference throughput for obstacle avoidance. Warehouse logistics operators in Germany and Japan pilot these systems for 24-hour autonomous ground fleet operation. The technology is miniaturizing previously rack-mounted compute into palm-sized payloads, collapsing the cost barrier for sub-50-agent commercial deployments.
EU AI Act risk-classification mandates now require high-risk autonomous systems to maintain human oversight loops and decision logging. Defense procurement offices across NATO member states rewrite technical specifications to embed conformity assessment deliverables. Transportation and critical infrastructure end users accelerate vendor qualification processes, favoring suppliers with pre-submitted audit documentation.
Buyers increasingly unbundle hardware acquisition from algorithm licensing, treating swarm coordination software as renewable subscription revenue. Agricultural drone operators in California and Queensland negotiate per-acre service fees rather than capital expenditure contracts. This consumption-pattern shift pressures hardware margins while elevating recurring revenue multiples for platform vendors with established flight-hour datasets.
Swarm Intelligence Market Segmentation
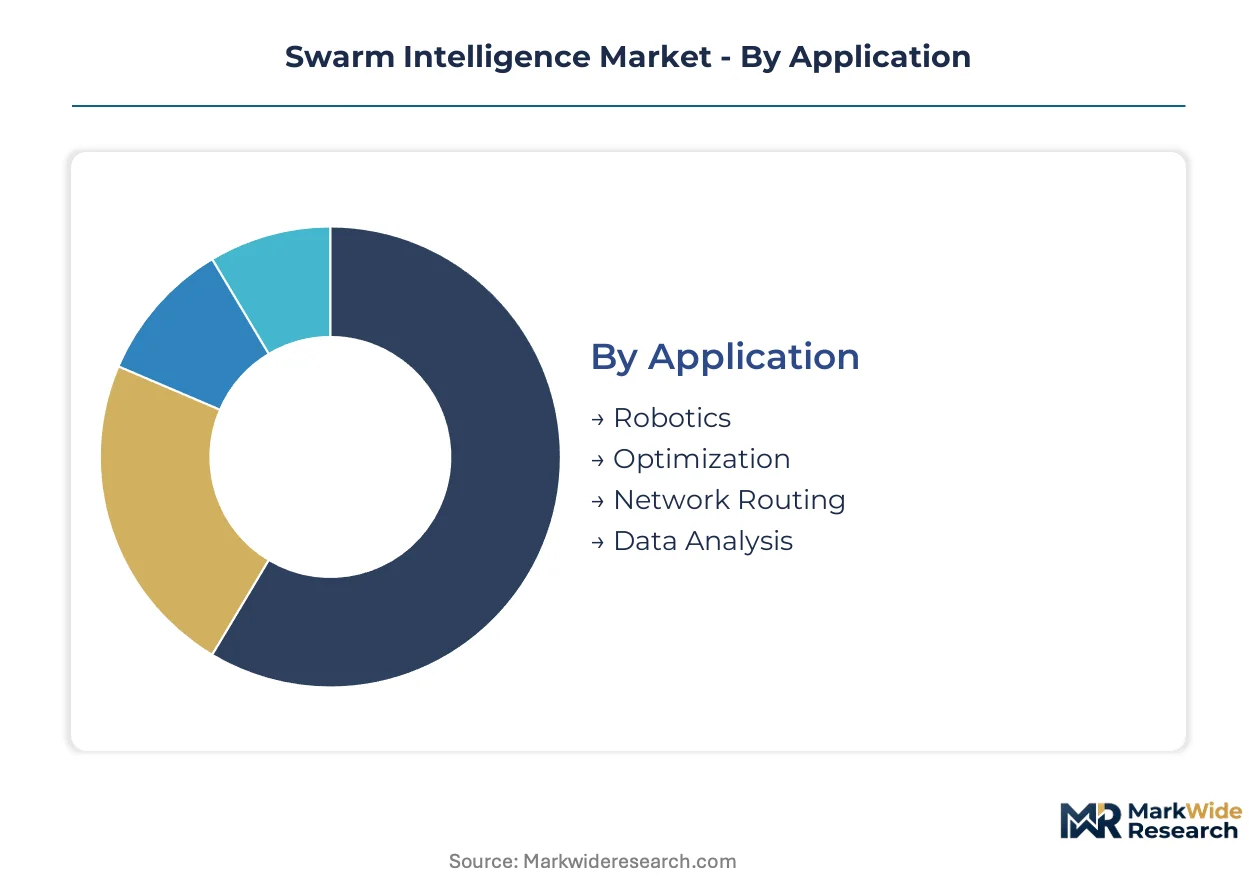
Segmentation in swarm intelligence separates architectures by compliance burden, latency tolerance, and mission criticality. Defense procurement offices weight fault-tolerant topologies above cost efficiency, while commercial operators prioritize deployment speed over algorithmic sophistication.
Application:
EU AI Act high-risk classification splits this category between auditable mission-critical systems and lighter-touch commercial deployments.
- Robotics:Physical agent coordination dominates installed base with sub-second latency requirements for collision avoidance and formation maintenance. NATO defense agencies in Germany, France, and the United Kingdom drive procurement of autonomous aerial and ground swarms for surveillance and logistics missions, prioritizing fault-tolerant topologies that sustain operation when individual nodes fail.
- Optimization:Algorithmic routing for supply chain and resource allocation extracts premium pricing from enterprise clients. Oil and gas operators in the North Sea and Gulf of Mexico deploy predictive maintenance routing to reduce platform downtime, generating recurring service revenue for integrators with established flight-hour datasets.
- Network Routing:Distributed pathfinding protocols enable resilient data transmission across dynamic topologies. Telecommunications infrastructure in urban Japan and South Korea pilots these systems for 5G network slicing applications.
- Data Analysis:Collective intelligence frameworks aggregate dispersed sensor inputs for pattern recognition. Agricultural cooperatives in California and Queensland apply human-swarm hybrid platforms to crop yield forecasting.
Established volume favors Robotics; emerging adoption favors Optimization.
Technology:
Cost tier differentiation separates enterprise-grade certified stacks from agile experimental architectures.
- Agent-Based Systems:Emergent behavior modeling through localized interaction rules shows the steepest capability curve in current development. DARPA OFFSET program contracts accelerate algorithmic maturation for urban warfare scenarios, pulling venture capital into adjacent commercial applications with proven military heritage.
- Artificial Neural Networks:Deep learning integration retains broadest interoperability with legacy enterprise stacks and existing data infrastructure. Warehouse logistics operators in Germany and Japan pilot onboard neuromorphic implementations for 24-hour autonomous ground fleet operation, collapsing power consumption below 500 milliwatts.
- Bio-Inspired Algorithms:Mechanisms derived from ant colony optimization and particle swarm methods address specific combinatorial problems. Academic research clusters in Boston and Pittsburgh commercialize these approaches for niche routing applications.
- Distributed Computing:Edge-native processing architectures minimize communication latency through decentralized computation. ISO/IEC 23053 certification requirements bifurcate competitive positioning between auditable enterprise suppliers and uncertified developers.
Enterprise procurement favors Artificial Neural Networks; capability expansion favors Agent-Based Systems.
End User:
Customer type determines funding stability, procurement cycle length, and tolerance for pre-commercial technology risk.
- Defense:Sovereign procurement offices across NATO member states rewrite technical specifications to embed EU AI Act conformity assessment deliverables. Multi-year development contracts sustain algorithmic maturation through extended testing cycles unavailable to commercial operators.
- Transportation:Beyond-visual-line-of-sight regulatory constraints under FAA Part 107 compress revenue recognition timelines for U.S.-focused operators. Autonomous ground swarms for warehouse logistics compete on deployment speed rather than coordination sophistication.
- Agriculture:Per-acre service fee models replace capital expenditure contracts, shifting consumption patterns toward renewable subscription revenue. Drone operators in California and Queensland negotiate flight-hour-based pricing with established dataset providers.
- Healthcare:Patient safety requirements impose documentation burdens extending certification timelines. Distributed environmental monitoring applications in hospital logistics remain pre-commercial pending regulatory clarity.
Funding stability favors Defense; consumption model innovation favors Agriculture.
Solution:
Margin structure separates high-touch integration services from scalable software licensing.
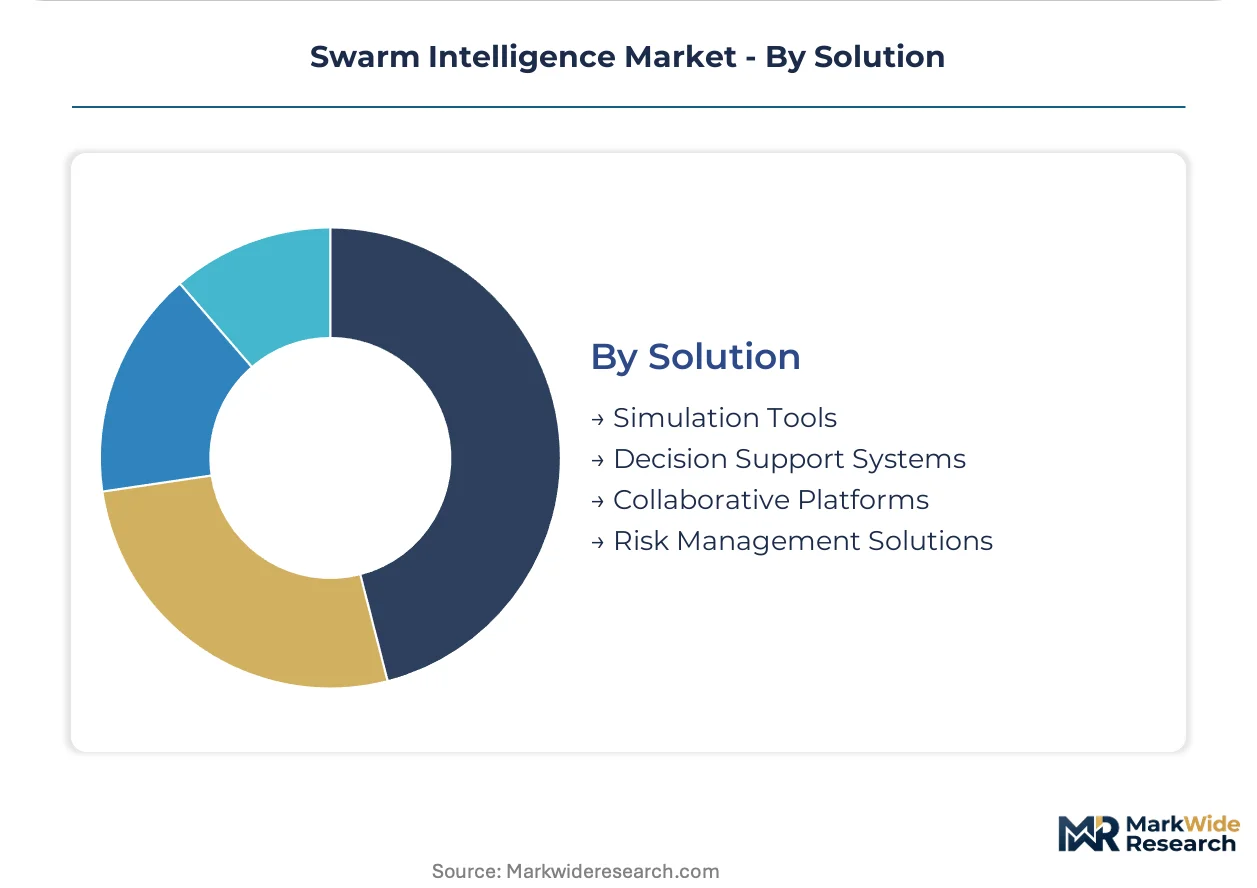
- Simulation Tools:Digital twin environments for swarm behavior validation reduce physical prototyping costs. Defense contractors in the United States and United Kingdom require these capabilities for mission rehearsal and operator training.
- Collaborative Platforms:Multi-stakeholder coordination interfaces enable shared control across heterogeneous agent fleets. Offshore wind operators in the North Sea lack scalable turbine maintenance solutions, creating white space for underwater swarm service providers.
- Decision Support Systems:Human-in-the-loop oversight interfaces satisfy EU AI Act high-risk system classification requirements. Transportation and critical infrastructure end users accelerate vendor qualification processes for suppliers with pre-submitted audit documentation.
- Risk Management Solutions:Fault-tolerant topology design and failure-mode analysis address mission continuity requirements. Lithium-polymer battery supply constraints tether commercial aerial applications to short-range missions below 45 minutes endurance.
Integration margins favor Simulation Tools; recurring revenue scalability favors Collaborative Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices and commercial robotics clusters concentrate demand in the United States, Germany, Japan, United Kingdom, and Australia, with each geography shaping distinct compliance and deployment pathways for swarm coordination systems.
United States
DARPA OFFSET program contracts accelerate algorithmic maturation for urban warfare scenarios, pulling venture capital into adjacent commercial applications. The FAA regulates beyond-visual-line-of-sight drone operations under Part 107 waivers, constraining commercial deployment timelines. Robotics clusters in Boston and Pittsburgh accelerate deployment of autonomous ground swarms for warehouse logistics.
Germany
Offshore wind operators in the North Sea lack scalable turbine maintenance solutions, creating white space for underwater swarm service providers. The EU AI Act's high-risk system classification triggers conformity assessment obligations for defense and transportation end users. Warehouse logistics operators in Bavaria pilot onboard neuromorphic implementations for 24-hour autonomous ground fleet operation.
Japan
Telecommunications infrastructure pilots distributed pathfinding protocols for 5G network slicing applications in dense urban environments. METI standards frameworks shape vendor compliance roadmaps for autonomous systems deployment. Robotics integrators in the Kansai region commercialize bio-inspired algorithms for niche routing applications.
United Kingdom
Defense contractors require digital twin environments for swarm behavior validation and mission rehearsal. NATO procurement offices rewrite technical specifications to embed EU AI Act conformity assessment deliverables. Academic research clusters in Cambridge and Oxford commercialize emergent behavior modeling approaches.
Australia
Agricultural cooperatives in Queensland apply human-swarm hybrid platforms to crop yield forecasting and negotiate per-acre service fees. The country's national aviation regulator constrains beyond-visual-line-of-sight operations pending safety case demonstrations. Robotics clusters in Sydney and Melbourne develop underwater swarm inspection systems for offshore infrastructure.
Swarm Intelligence Market Vendor Landscape
Player mix skews toward specialized developers with military heritage and certified enterprise suppliers, creating a bifurcated structure where auditable architectures command premium positioning against agile niche operators. The vendor base separates into three strategic archetypes: human-swarm hybrid platforms, underwater swarm specialists, and autonomous ground fleet operators. Competitive moves concentrate on ISO/IEC 23053 certification acquisition and 5G network slicing partnerships for ultra-reliable low-latency coordination.
Within the certified enterprise tier, Unanimous A.I. and Sentien Robotics exemplify divergent positioning strategies, with the former anchoring commercial forecasting applications and the latter occupying warehouse logistics deployment. Hydromea represents the underwater specialization archetype, serving offshore infrastructure inspection demand in the North Sea and Gulf of Mexico. These three entities collectively illustrate how compliance burden and latency tolerance segment addressable market access.
| Leading Market Players |
|---|
| Unanimous A.I. |
| Hydromea |
| Kim Technologies |
| DoBots |
| Swarm Technology |
| Sentien Robotics |
| Valutico |
| ConvergentAI, Inc |
| Power-Blox |
| Others |
Supply Flow & Price Mechanics
Project-based capacity reservation contracts with NATO defense procurement offices lock in multi-year algorithm development commitments and provide visibility into unit pricing for swarm coordination software licensing. These structures tether commercial pricing benchmarks to sovereign-funded R&D amortization schedules while insulating certified vendors from spot-market volatility in lithium-polymer battery inputs.
Pricing Analysis
Cost-plus contracts with lithium-polymer indexation dominate hardware procurement for aerial swarm deployments, while software licensing migrates toward per-agent subscription tiers anchored to flight-hour datasets. Three-tier pricing structure across certified enterprise, provisional compliance, and uncertified developer levels reflects ISO/IEC 23053 audit burden differentiation. Pricing pressure stems from agricultural drone operators in California and Queensland negotiating per-acre service fees rather than capital expenditure contracts. Warehouse logistics buyers in Germany exhibit highest price sensitivity due to compressed deployment timelines, while NATO defense agencies absorb premium positioning for fault-tolerant topology guarantees.
Supply Chain Analysis
China and South Korea anchor neuromorphic chip fabrication for onboard swarm processing, while Japan and Taiwan concentrate lithography capacity for sub-500-milliwatt payload miniaturization. The supply chain draws from lithium-polymer cell production in Shenzhen and Busan, rare-earth magnet sourcing for drone motors, and epoxy resin feedstocks for underwater hull encapsulation. Single-source vulnerability concentrates in advanced semiconductor lithography equipment subject to dual-use export control restrictions. Distribution runs through robotics systems integrators in Boston and Pittsburgh for North American defense contracts, and through Kansai-region engineering houses for Japanese telecommunications pilots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Swarm intelligence is approaching a platform-economics inflection where interoperability standards and flight-hour data network effects will consolidate vendor positioning around certified coordination stacks, much as cloud infrastructure concentrated around hyperscale API ecosystems.
For Market Incumbents: Compound ISO/IEC 23053 certification advantages by embedding conformity assessment deliverables into standard contract templates, forcing uncertified niche developers into costly architecture redesigns. Acquire underwater swarm specialists in the North Sea corridor to preempt offshore wind inspection white-space capture by agile entrants. Vertical integration into lithium-polymer battery pack assembly mitigates energy density constraints compressing aerial mission endurance below operational thresholds for commercial buyers. For New Entrants and Emerging Players: Per-acre agricultural service fee models in Queensland and California represent the most penetrable entry vector, as incumbent hardware vendors lack established flight-hour datasets for crop yield forecasting applications. Target collaborative platform licensing for offshore wind operators lacking scalable turbine maintenance solutions in the North Sea. Pursue 5G network slicing partnerships with Japanese telecommunications infrastructure pilots as a go-to-market angle bypassing FAA Part 107 waiver constraints that entrench U.S.-focused competitors. For Investors and Strategic Acquirers: Capital is best deployed toward human-swarm hybrid platform vendors with proven military heritage and renewable subscription revenue conversion capability. Long-term viability hinges on algorithmic audit trail architectures satisfying EU AI Act documentation requirements. Watch for 5G ultra-reliable low-latency communication deployment milestones in dense urban Japanese environments as the inflection indicator for real-time coordination scalability.| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 23053 Certification Acquisition | Enables premium positioning against uncertified developers in EU AI Act-regulated procurement. |
| 5G Network Slicing Partnership | Unlocks real-time swarm coordination in dense urban environments for Japanese telecommunications pilots. |
| Underwater Swarm Specialist Acquisition | Captures offshore wind inspection white space in the North Sea where scalable maintenance solutions remain absent. |
| Per-Acre Service Model Launch | Converts agricultural drone operators in California and Queensland from capital expenditure to renewable subscription revenue. |
| Neuromorphic Chip Integration | Collapses power consumption below 500 milliwatts for 24-hour autonomous ground fleet operation in German warehouses. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with robotics systems integrators, NATO defense procurement officers, warehouse logistics deployment leads, offshore wind maintenance planners, and agricultural drone service operators. Secondary validation incorporated DARPA OFFSET program contract disclosures, FAA Part 107 waiver filings, EU AI Act conformity assessment documentation, METI standards frameworks, and hyperscaler edge computing capex disclosures. Bottom-up unit economics for swarm node production and top-down addressable market sizing for coordination software licensing were triangulated against deployment velocity metrics from pilot programs in Boston, Pittsburgh, and the Kansai region.
Across the analysis window, the forecast framework modeled segmentation dimensions spanning application type, technology architecture, end-user funding stability, and solution margin structure alongside regional regulatory cluster differentiation. CAGRs were derived from deployment timeline compression rates and procurement cycle acceleration patterns specific to defense versus commercial buyer archetypes. Industry-specific inputs included beyond-visual-line-of-sight waiver approval velocities, lithium-polymer energy density improvement curves, and algorithmic audit trail implementation lag times for EU AI Act compliance.
Forecasts assume regulatory continuity in FAA Part 107 administration, EU AI Act risk classification enforcement, and METI autonomous systems standards; material policy shifts in any regime would require re-modeling deployment timeline assumptions and procurement redirection patterns. Recalibration cycles align with material shifts in dual-use export control scope, 5G network slicing commercial availability, and sovereign defense R&D budget appropriations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Global High-Performance Computing (HPC) Market
Emerging and Next Generation Technologies
Multi-Touch Technology Market
Emerging and Next Generation Technologies
Graphene Nanoplatelets Market
Emerging and Next Generation Technologies
Stretchable Electronics Market
Emerging and Next Generation Technologies
Global WI SUN Technology Market
Emerging and Next Generation Technologies
MLDW Technology Market
Emerging and Next Generation Technologies
3D Electronics Market
Emerging and Next Generation Technologies
Printed Electronics Market
Emerging and Next Generation Technologies
Metamaterial Medium Market
Emerging and Next Generation Technologies
Internet of Nano Things Market
Emerging and Next Generation Technologies
In-Mold Electronics (IME) Market
Emerging and Next Generation Technologies
Ultra-Thin Solar Cells Market
Emerging and Next Generation Technologies
Lab on Chips Market
Emerging and Next Generation Technologies
Hyperscale Computing Market
Emerging and Next Generation Technologies
Global Smart Window Market
Emerging and Next Generation Technologies
Global Ultrafast Lasers Market