
 Gut Modifiers Market | 2026-2036
Gut Modifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Gut Modifiers Market Outlook
Clinical nutrition programs is repositioning gut modifiers from wellness aisles into hospital discharge protocols and chronic disease management plans. Nestlé S.A. leverages its pharmaceutical nutrition division to anchor institutional contracts across European healthcare systems. Chr. Hansen Holding A/S dominates strain library depth, while BioGaia AB specializes in single-strain L. reuteri formulations for pediatric applications.
Gut modifiers comprise live microbial cultures, fermentable fibers, and their metabolic byproducts formulated to modulate intestinal microbiota composition and host immune response, typically requiring minimum colony-forming unit counts and gastric acid resistance for therapeutic efficacy. Probiotics occupies the largest revenue share due to established consumer recognition and clinical trial infrastructure, though postbiotics is accelerating fastest as heat-killed formulations bypass cold-chain constraints and extend shelf stability. Synbiotics captures concentrated margin pools where co-formulated prebiotic substrates enhance strain colonization rates in premium positioning.
The FDA scrutinizes structure-function claims under DSHEA enforcement discretion, while EMA's Nutrition and Health Claims Regulation demands substantiated human intervention data for probiotic marketing in the European Union. Japan's FOSHU system creates a parallel compliance pathway that rewards clinically validated gut health products with premium channel access. Stakeholders must monitor evolving strain-specific qualification criteria as regulators shift from genus-level to species- and strain-level efficacy requirements.
Market Dynamics
Strain-level regulatory qualification is compressing genus-level product lines while hospital formulary committees demand species-specific clinical evidence for microbiome interventions. Live-culture supply chains face mounting cold-chain cost pressure as stability windows narrow under tightened FDA and EMA enforcement.
Growth Catalysts
- DSHEA enforcement discretion:The FDA's evolving guidance on structure-function claims creates pathways for substantiated probiotic health positioning in US dietary supplements, accelerating clinical trial investment by domestic manufacturers.
- Japan FOSHU premium channel access:Clinically validated gut health products secure preferential retail placement and consumer price premiums under this designated health foods framework, concentrating R&D expenditure on Japanese market entry.
- Postbiotic heat-killed formulations:Elimination of cold-chain requirements extends shelf stability and reduces distribution costs, enabling penetration into ambient retail channels previously inaccessible to live cultures.
Market Restraints
- Strain library concentration:Deep proprietary culture collections reside with a limited set of European suppliers, creating dependency risk for North American and Asian formulators seeking clinically documented species.
- Human intervention data costs:EMA's Nutrition and Health Claims Regulation mandates substantiated efficacy trials that strain mid-cap R&D budgets and extend product development timelines substantially.
- Prebiotic fiber input volatility:Inulin and galactooligosaccharide sourcing faces agricultural yield fluctuation tied to chicory root and lactose feedstock availability, compressing synbiotic margin pools.
Strategic Opportunities
- Pediatric single-strain specialization:L. reuteri and B. infantis formulations for infant colic and atopic dermatitis represent underpenetrated therapeutic niches with premium pricing potential and limited generic competition.
- Hospital discharge protocol integration:Clinical nutrition programs in Germany, France, and the United Kingdom are embedding microbiome-targeted interventions into post-surgical and antibiotic recovery pathways.
- Metabolic byproduct standardization:Postbiotic short-chain fatty acid concentrates and exopolysaccharide isolates enable pharmaceutical-grade ingredient positioning with distinct regulatory pathways from live cultures.
Industry Challenges
- Strain-specific qualification expertise:Regulatory affairs professionals capable of navigating species- and strain-level efficacy requirements remain scarce, elongating compliance timelines for product line extensions.
- Colony-forming unit stability validation:Gastric acid resistance testing and shelf-life verification demand specialized laboratory infrastructure that smaller formulators must outsource at significant cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gut Modifiers Market |
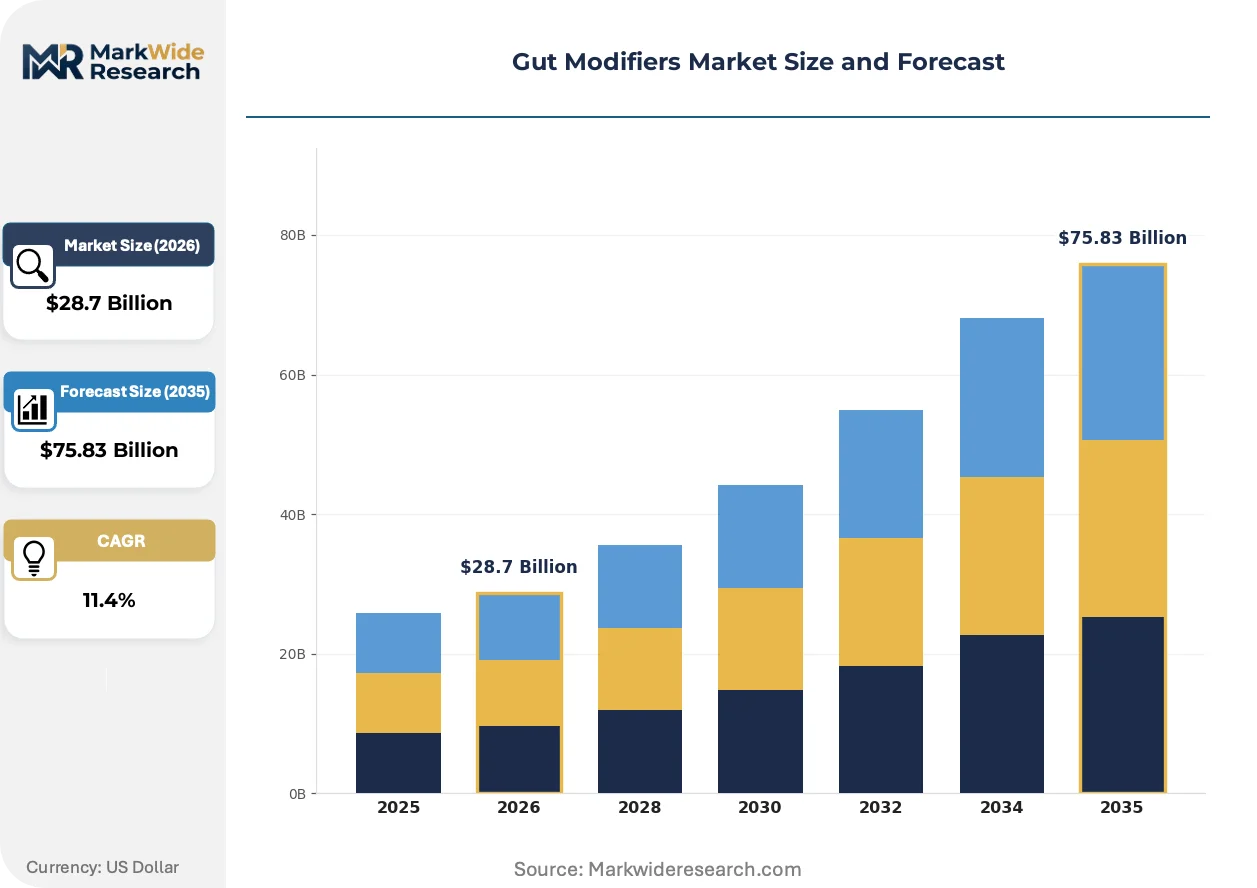
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $75.83 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Synbiotics, Postbiotics Application: Digestive Health, Immune Support, Weight Management, Mood Regulation End User: Retail Consumers, Healthcare Professionals, Fitness Enthusiasts, Dietary Supplement Users Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Food Stores |
| Companies Covered | Nestlé S.A, Groupe Danone S.A, Yakult Honsha Co. Ltd., Chr. Hansen Holding A/S, International Flavors & Fragrances Inc., DSM-Firmenich, Archer-Daniels-Midland, BioGaia AB, Lallemand Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gut Modifiers Market Strategic Shifts
Formulation science is pivoting from live-cell dependency toward bioactive metabolite isolation, while regulatory frameworks fragment across strain-level qualification requirements. Digital health integration and personalized microbiome profiling are beginning to reshape prescriber and consumer engagement models.
Postbiotic heat-killed formulations is overtaking traditional live-culture probiotics in ambient retail channels and pharmaceutical ingredient supply. Major CPG manufacturers are adopting these stabilized preparations for functional food integration at accelerated pace. The technology is compressing cold-chain infrastructure requirements and enabling shelf-stable product formats previously technically unfeasible.
EMA's strain-level efficacy requirements under the Nutrition and Health Claims Regulation are reshaping European competitive positioning. Genus-level marketing claims face systematic rejection without species- and strain-specific human intervention data. Premium synbiotic and postbiotic categories absorb disproportionate compliance investment as manufacturers retreat from undifferentiated multi-strain live culture lines.
Hospital formulary procurement is consolidating around single-strain, indication-specific microbiome interventions with documented clinical outcomes. Traditional wellness-channel probiotics face displacement by pharmaceutical nutrition divisions with institutional contracting capabilities. This concentration is most visible in German, Swiss, and Dutch healthcare systems where reimbursement pathways for medical foods are most developed.
Gut Modifiers Market Segmentation
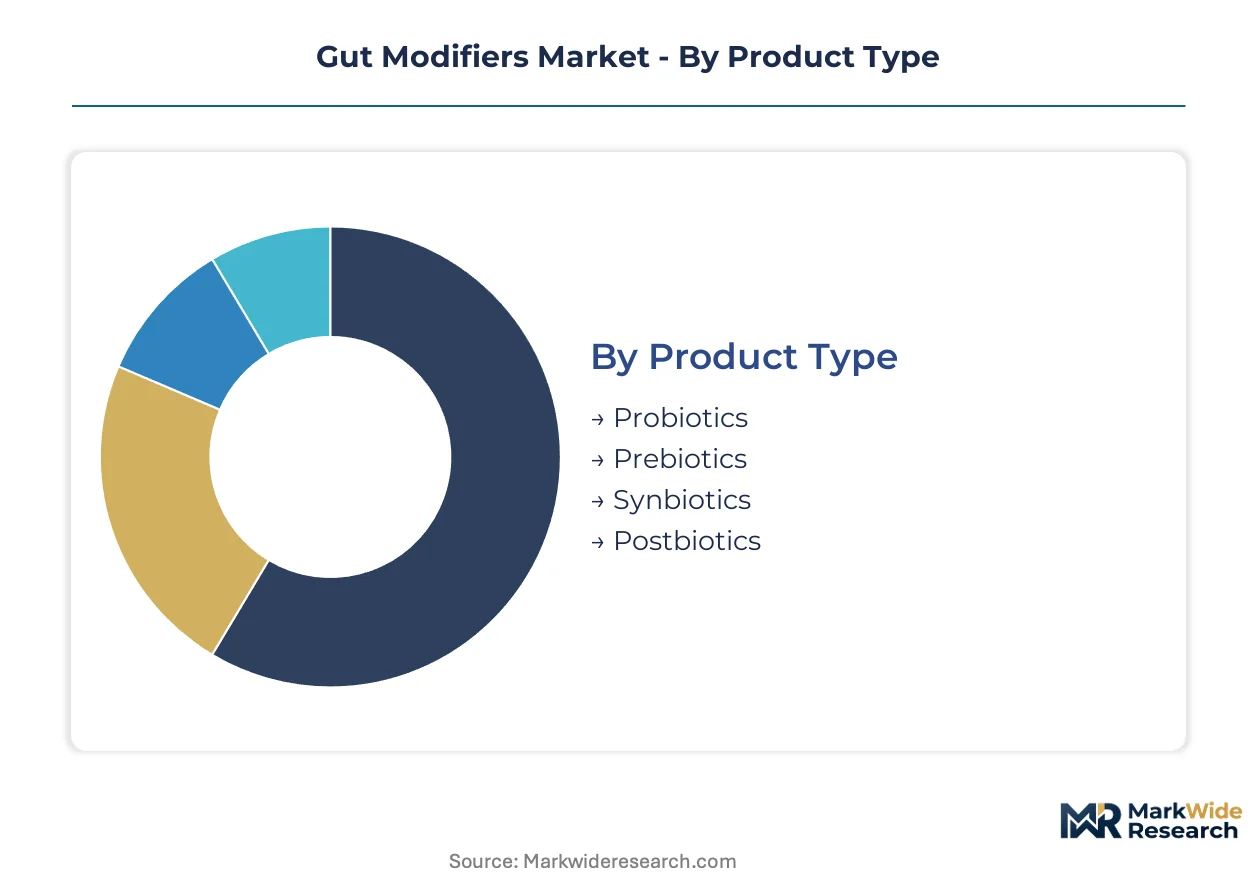
Gut modifiers segment along four intersecting dimensions that determine formulation requirements, regulatory pathways, and margin structures. Product type classifications dictate stability standards and clinical substantiation burdens, while application focus shapes strain selection and dosing protocols.
Product Type:
Standalone live-culture formulations dominate hospital procurement, whereas heat-stabilized and co-formulated systems penetrate ambient retail and functional food channels.
- Probiotics:Live microbial cultures requiring minimum colony-forming unit counts and gastric acid resistance for therapeutic efficacy. Demand concentrates in hospital discharge protocols across Germany, France, and the United States, where formulary committees mandate species-specific clinical documentation.
- Postbiotics:Heat-killed formulations and metabolic byproducts that bypass cold-chain constraints entirely. Expansion accelerates in Japanese FOSHU-authorized channels and North American ambient retail, where shelf stability enables functional food integration at reduced distribution cost.
- Prebiotics:Fermentable fibers including inulin and galactooligosaccharides that selectively nourish beneficial microbiota.
- Synbiotics:Co-formulated live cultures with prebiotic substrates designed to enhance colonization rates.
Volume placements concentrate in probiotics; the faster expansion belongs to postbiotics.
Application:
Pediatric and geriatric indications command premium positioning, while metabolic and cognitive applications attract pharmaceutical-grade investment.
- Digestive Health:Irritable bowel syndrome, antibiotic-associated diarrhea, and post-surgical recovery protocols. German and Swiss healthcare systems embed these interventions into reimbursement pathways for medical foods.
- Immune Support:Respiratory infection prophylaxis and vaccine adjuvant applications. Japanese consumers pay substantial premiums for clinically validated immune positioning under FOSHU designation.
- Weight Management:Metabolic modulation through short-chain fatty acid stimulation and appetite regulation.
- Mood Regulation:Gut-brain axis targeting for anxiety and depressive symptom management.
Digestive health captures institutional procurement volume; mood regulation climbs the fastest as psychobiotic research matures.
End User:
Professional prescribing channels outperform direct-to-consumer growth as clinical evidence standards tighten.
- Healthcare Professionals:Hospital formulary committees and clinical nutrition programs driving institutional contracting. European pharmaceutical nutrition divisions anchor multi-year supply agreements with documented outcome metrics.
- Retail Consumers:Mass-market wellness purchasers with lower clinical substantiation tolerance. United States functional food integration accelerates through mainstream retail channel expansion.
- Fitness Enthusiasts:Performance-oriented consumers seeking recovery and metabolic optimization.
- Dietary Supplement Users:Established supplement adopters with structure-function claim familiarity.
Healthcare professionals drive value concentration; retail consumers provide volume scale.
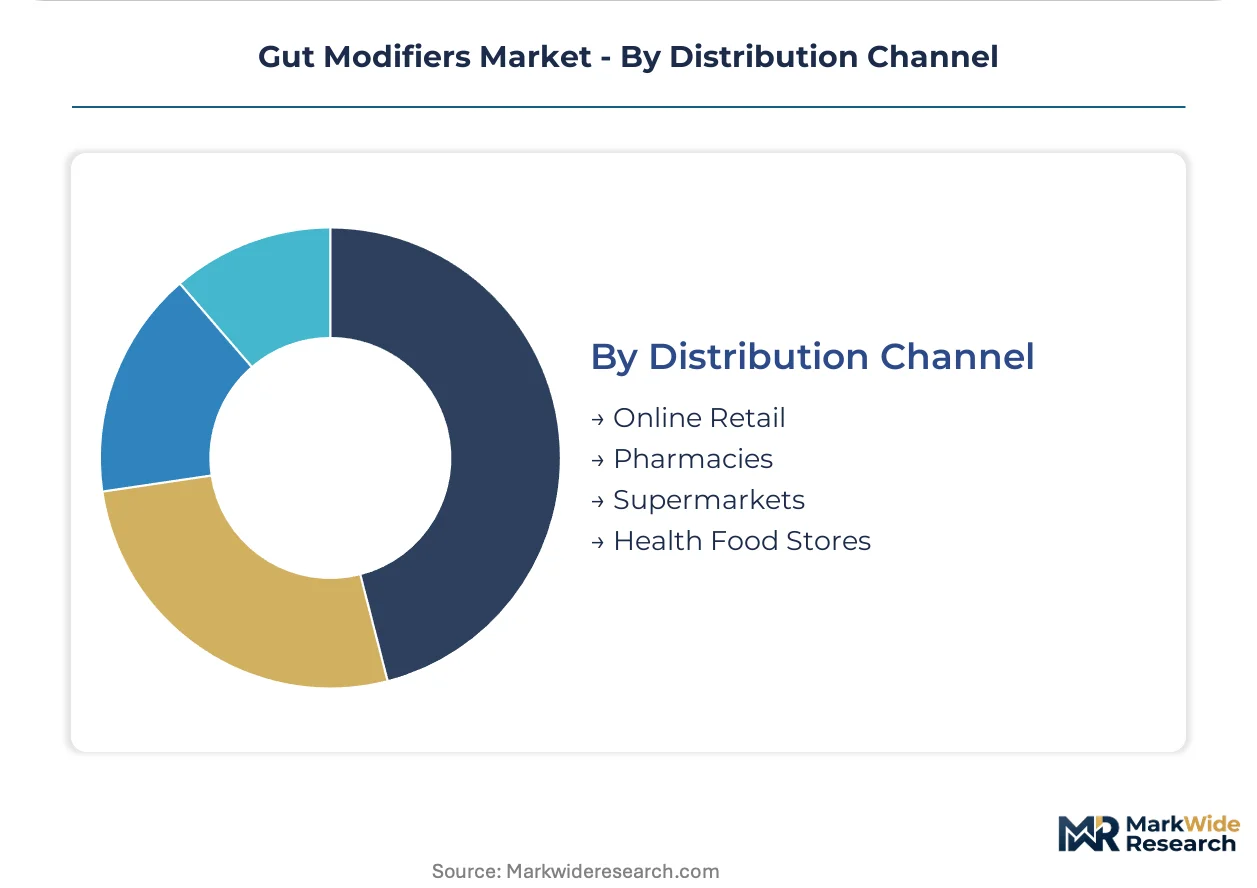
Distribution Channel:
Cold-chain capabilities and regulatory compliance depth determine channel access tiering.
- Pharmacies:Professional recommendation environments with pharmacist counseling infrastructure. German and French pharmacy networks concentrate prescription-strength probiotic distribution.
- Online Retail:Direct-to-consumer platforms enabling strain-specific education and subscription models. Japanese e-commerce channels leverage FOSHU authorization badges for premium positioning.
- Supermarkets:Mass-market ambient placement for stabilized postbiotic and synbiotic formats.
- Health Food Stores:Specialty retail with educated consumer base and practitioner referral relationships.
Pharmacies dominate professional-grade volume; online retail gains share fastest through personalization algorithms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Singapore and Shenzhen anchor Asia-Pacific supply chain concentration for fermentable fiber inputs and strain library logistics. Tax incentives for biotechnology R&D in Basel and Boston drive pharmaceutical nutrition division expansion. Special economic zones in Dubai and Jebel Ali facilitate Gulf distribution hub development for ambient-stable postbiotic formats.
United States
Hospital discharge protocol expansion and mainstream retail functional food integration concentrate demand along the Interstate 95 corridor. FDA structure-function claim enforcement under DSHEA creates compliance pathways for substantiated probiotic positioning. The Greater Boston biotech cluster houses pharmaceutical nutrition divisions developing single-strain clinical documentation for formulary committees.
Germany
Medical foods reimbursement pathways and hospital formulary procurement centralize institutional volume in Baden-Württemberg and Bavaria. EMA Nutrition and Health Claims Regulation mandates strain-specific human intervention data for market access. The Frankfurt-Rhine-Main logistics hub anchors cold-chain distribution networks serving Swiss and Dutch healthcare systems.
Japan
FOSHU-authorized premium channel access and consumer price tolerance for clinically validated immune positioning drive R&D concentration in Kanto. METI and PMDA coordination on designated health foods frameworks rewards substantiated gut health claims. Tokyo-based pharmaceutical divisions leverage FOSHU badges for preferential retail placement and export qualification.
Switzerland
Pharmaceutical nutrition contracting capabilities and institutional outcome metrics anchor European healthcare system supply agreements. Swissmedic medical foods oversight aligns with EMA strain-level efficacy requirements. The Basel biotech cluster concentrates proprietary culture collection depth and species-specific clinical trial infrastructure.
China
Domestic fermentation capacity expansion and dual carbon goals drive local manufacturing of heat-killed postbiotic formats. NMPA and SAMR coordination on dietary supplement claims creates parallel compliance pathways to Western frameworks. The Yangtze River Delta biotech corridor concentrates synbiotic co-formulation capacity for Asia-Pacific export markets.
Gut Modifiers Market Competitive Environment
Top-tier vendors anchor pharmaceutical nutrition and strain library depth, while mid-tier formulators compete on ambient stability and pediatric specialization. The competitive structure stratifies across three tiers: integrated pharmaceutical nutrition divisions with institutional contracting capabilities, specialized strain library custodians with regulatory affairs expertise, and functional food ingredient suppliers with CPG manufacturing relationships. Dominant competitive moves include backward integration into proprietary culture collections and strategic partnerships with hospital formulary committees for outcome-based procurement contracts.
Within the pharmaceutical nutrition tier, Nestlé S.A. and Groupe Danone S.A. represent integrated food-healthcare conglomerates with institutional contracting infrastructure across European healthcare systems. Chr. Hansen Holding A/S occupies a position as a specialized strain library custodian with deep species-specific documentation capabilities. BioGaia AB exemplifies the pediatric single-strain specialization archetype, anchoring premium positioning in infant colic and atopic dermatitis therapeutic niches with limited generic competition.
| Leading Market Players |
|---|
| Nestlé S.A |
| Groupe Danone S.A |
| Yakult Honsha Co. Ltd. |
| Chr. Hansen Holding A/S |
| International Flavors & Fragrances Inc. |
| DSM-Firmenich |
| Archer-Daniels-Midland |
| BioGaia AB |
| Lallemand Inc. |
| Others |
Value Chain & Pricing Dynamics
Strain-level certification tiers bifurcate pricing power between pharmaceutical-grade suppliers and commodity live-culture merchants, with EMA species-specific documentation requirements forcing supply chain reconfiguration toward Basel and Boston biotech clusters. Cold-chain cost differentials amplify this divergence as ambient-stable postbiotic formats bypass refrigerated logistics entirely.
Pricing Analysis
Short lead-time premiums concentrate around FOSHU-authorized Japanese channels where METI-designated health foods command immediate shelf placement. Three-tier pricing structure across pharmaceutical-grade, clinical nutrition, and mass-market wellness levels tracks certification depth and gastric acid resistance validation. Pricing pressure stems from agricultural yield fluctuation in chicory root and lactose feedstocks compressing synbiotic margin pools. Retail consumers exhibit highest price sensitivity, while hospital formulary committees absorb premium positioning for documented single-strain outcomes.
Supply Chain Analysis
Strain library qualification gates concentrate upstream supply among Danish, Swiss, and German culture collection custodians with proprietary species documentation. Live-culture production draws from chicory root cultivation in Belgium and the Netherlands, lactose refining in New Zealand and Ireland, and specialized fermentation infrastructure in the United States. Single-source vulnerability pervades proprietary L. reuteri and B. infantis strains controlled by limited European suppliers. Distribution runs through pharmaceutical nutrition divisions with institutional contracting capabilities anchoring hospital procurement, while ambient-stable postbiotics penetrate mass retail through CPG manufacturing partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
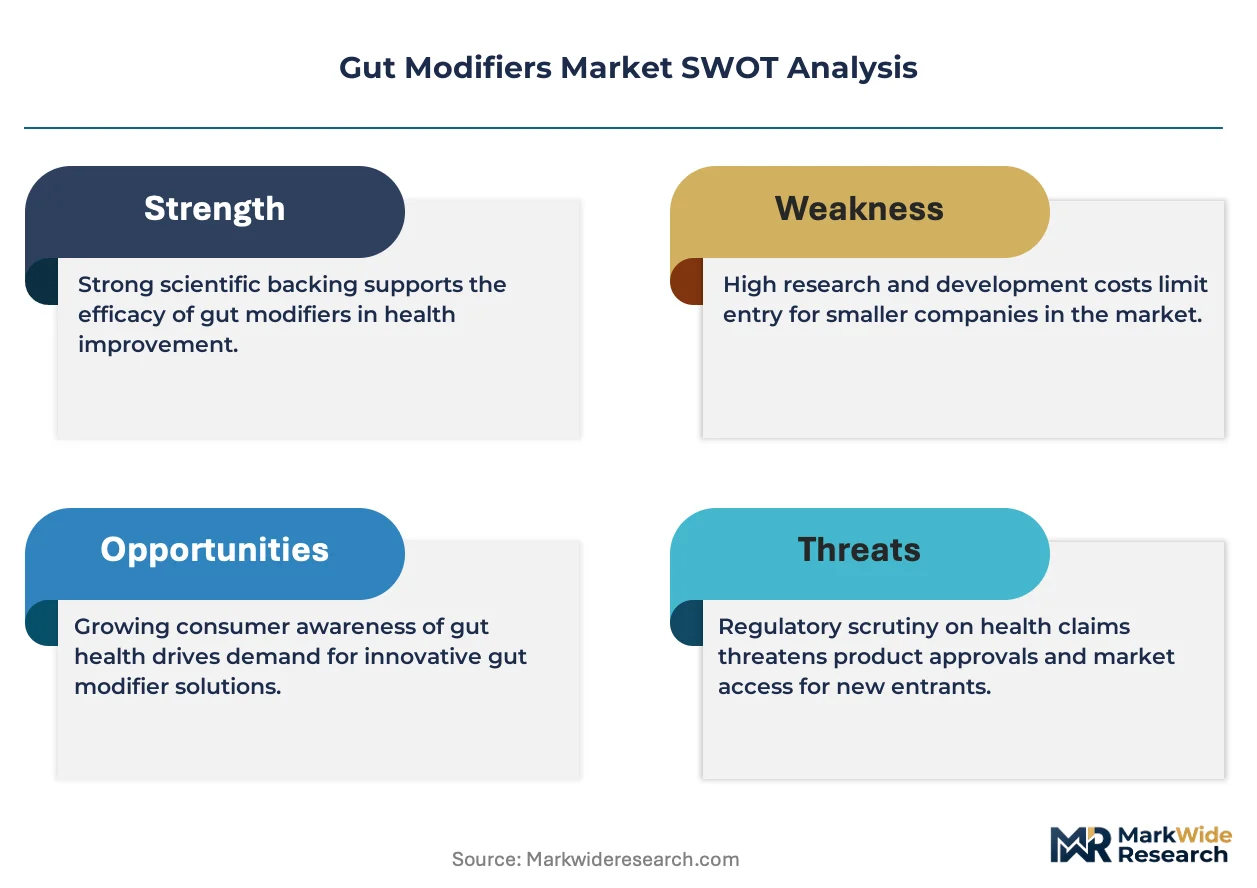
The gut modifiers market operates as a cost-of-compliance story where EMA's strain-level efficacy requirements under the Nutrition and Health Claims Regulation erect substantial barrier-to-entry moats favoring incumbents with documented human intervention data.
For Market Incumbents: Acquire proprietary culture collections with species-specific clinical documentation to consolidate strain library depth against generic multi-strain displacement. Nestlé S.A. and Chr. Hansen Holding A/S demonstrate this defensive pattern through institutional contracting infrastructure and regulatory affairs expertise. Hospital formulary consolidation threatens undifferentiated live-culture lines, making backward integration into heat-killed postbiotic production capacity a critical capacity lever. For New Entrants and Emerging Players: Begin with pediatric single-strain specialization in L. reuteri formulations for infant colic and atopic dermatitis, where BioGaia AB's premium positioning reveals limited generic competition and reimbursement pathway development. Japanese FOSHU authorization offers the most penetrable regulatory channel for clinically validated immune positioning. Direct-to-consumer subscription models with microbiome profiling integration provide the optimal go-to-market angle for bypassing entrenched pharmaceutical nutrition distribution. For Investors and Strategic Acquirers: Re-rating potential sits with specialized strain library custodians given EMA's shift from genus-level to species- and strain-level qualification requirements. Long-term viability across the analysis window favors assets with documented human intervention data and hospital formulary relationships. The signal to watch is FDA enforcement discretion tightening under DSHEA, which would accelerate consolidation toward compliant players with structure-function claim substantiation infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Library Acquisition | Proprietary culture collections with species-specific documentation anchor EMA compliance and hospital formulary access. |
| Postbiotic Manufacturing Scale-Up | Heat-killed formulation capacity eliminates cold-chain dependency and enables ambient retail channel penetration. |
| Hospital System Partnership | German and Swiss medical foods reimbursement pathways reward outcome-based procurement with multi-year supply agreements. |
| FOSHU Authorization Pathway | METI-designated health foods status unlocks premium Japanese retail placement and consumer price tolerance. |
| Pediatric Indication Expansion | Single-strain L. reuteri and B. infantis formulations target underpenetrated therapeutic niches with limited competition. |
Study Parameters
Document review covered FDA structure-function claim guidance, EMA Nutrition and Health Claims Regulation submissions, and Japanese FOSHU authorization databases, complemented by interviews with regulatory affairs directors at pharmaceutical nutrition divisions, hospital formulary committee members in Germany and Switzerland, and strain library curators at European culture collection institutions. Secondary validation drew from clinical trial registries, medical foods reimbursement pathway documentation, and proprietary fermentation capacity disclosures. Bottom-up demand modeling across product type, application, and end-user segments was triangulated against top-down healthcare expenditure allocation analysis.
Segment-level revenue estimates and volume projections across the analysis window were generated through hierarchical modeling of probiotics, postbiotics, prebiotics, and synbiotics demand trajectories. The analytical framework incorporated strain-specific qualification timelines, cold-chain infrastructure cost curves, and FOSHU authorization success rates as industry-specific forecast inputs. CAGRs were derived from convergence of historical growth patterns and forward-looking regulatory enforcement intensity assumptions.
Underlying measurement precision varies by segment; postbiotic and synbiotic categories carry tighter precision than undifferentiated multi-strain probiotics given standardization advantages. Forecasts reflect assumptions regarding EMA strain-level enforcement timing and FDA DSHEA discretion evolution. A model refresh is warranted upon material change in medical foods reimbursement pathway expansion or ambient-stable formulation technology breakthrough.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Europe Food Flavor and Enhancer Market
Food Enhancers and Additives
Australia Food Flavor and Enhancer Market
Food Enhancers and Additives
Dough Conditioners Market
Food Enhancers and Additives
Dysphagia Diet Thickening Market
Food Enhancers and Additives
Liquid Water Enhancers Market
Food Enhancers and Additives
Europe Feed Palatability Enhancers Market
Food Enhancers and Additives
Food Thickeners Market
Food Enhancers and Additives
South Korea Fat Replacers Market
Food Enhancers and Additives
Fortified Salts Market
Food Enhancers and Additives
Canada Food Flavor and Enhancer Market
Food Enhancers and Additives
Browning Enhancers Market
Food Enhancers and Additives
India Food Flavor and Enhancer Market
Food Enhancers and Additives
Africa Water Enhancer Market
Food Enhancers and Additives
Used Cooking Oil Market
Food Enhancers and Additives
Mexico Food Flavor and Enhancer Market
Food Enhancers and Additives
Crumb Softener Market