
 Food Thickening Agents Market | 2026-2036
Food Thickening Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Food Thickening Agents Market Analysis
European hydrocolloid refiners is repositioning capacity toward plant-derived alternatives as clean-label pressure mounts across Western retail channels. Cargill, Incorporated leverages its integrated corn and tapioca supply chains to control starch-based thickener costs. Kerry Group plc sustains formulation partnerships with major dairy processors, embedding its pectin and gum systems into private-label portfolios. Ingredion Incorporated anchors North American beverage and sauce applications through modified starch specialization.
Food thickening agents comprise hydrocolloids, starches, and proteins that increase viscosity in aqueous systems through hydration, gelation, or entanglement mechanisms, typically functioning at concentrations between 0.1% and 5.0% by weight. Their primary commercial purpose centers on texture modification, suspension stability, and mouthfeel engineering across processed food matrices. Starch dominates volume flows in sauces and soups where cost efficiency outweighs premium positioning, while xanthan gum commands margin pools in salad dressings requiring shear-thinning behavior and freeze-thaw stability. Pectin exhibits the fastest structural growth among plant-derived options as food manufacturers reformulate around recognizable ingredient declarations.
The FDA governs thickener safety under GRAS self-determination and food additive petition pathways, while EFSA mandates novel food assessments for non-traditional hydrocolloids entering European commerce. FSSAI in India enforces BIS standards on imported gum and starch specifications, creating compliance friction for suppliers targeting institutional food manufacturers. Stakeholders must monitor evolving clean-label definitions across jurisdictions, as regulatory divergence between permissive self-affirmation regimes and pre-market authorization systems directly determines product development timelines and geographic launch sequencing.
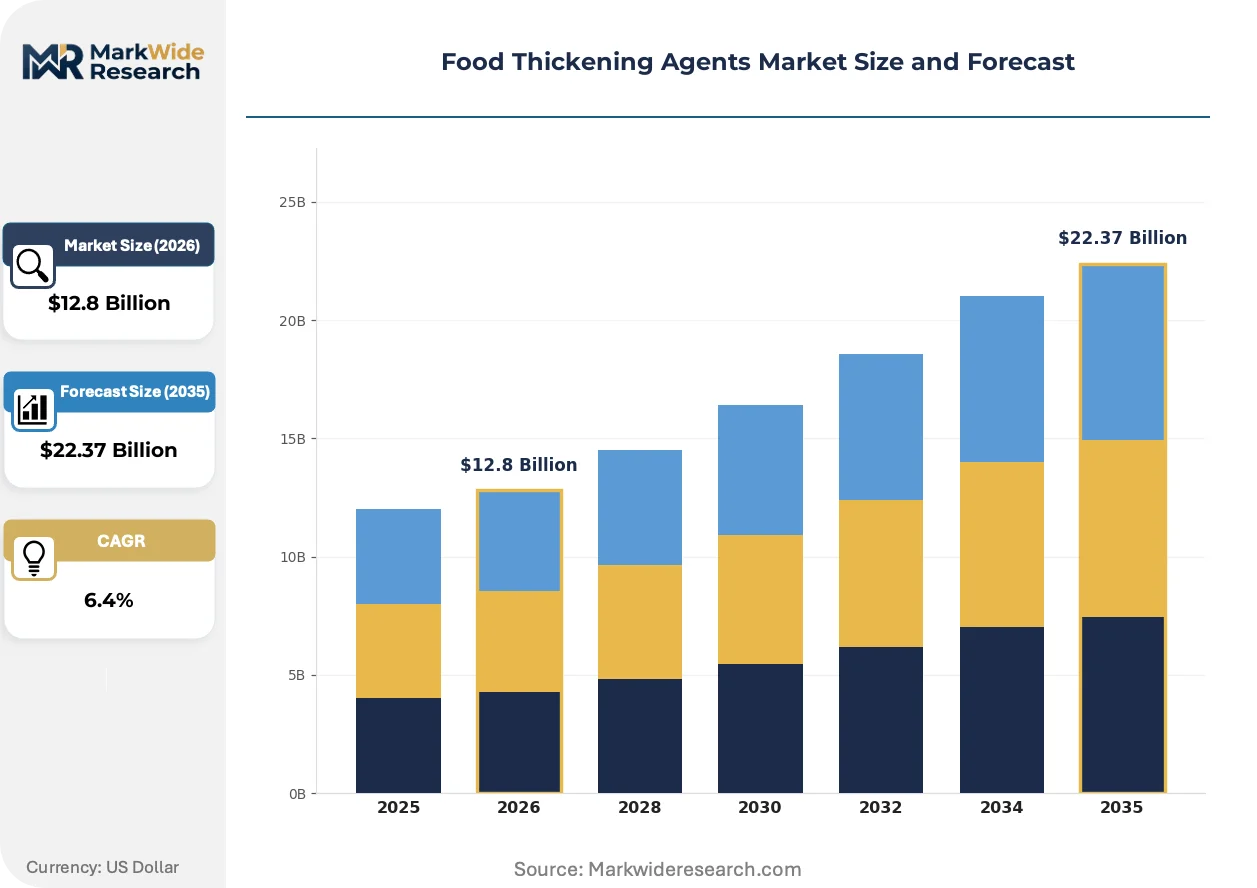
Market Dynamics
Clean-label regulatory pressure from FDA and EFSA is forcing simultaneous reformulation across dairy, sauce, and beverage categories, compressing development timelines while opening premium positioning for plant-derived hydrocolloids.
Growth Catalysts
- EFSA Novel Food Assessments:Pre-market authorization requirements for non-traditional hydrocolloids are accelerating investment in clinically validated plant extracts with established consumption histories.
- Freeze-thaw stability demand:Prepared meal manufacturers are specifying xanthan gum and modified starch systems for distribution through extended cold-chain networks.
- Japan processed food consumption:METI-supported food innovation programs sustain institutional demand for texture-engineered products in aging-population nutrition segments.
Market Restraints
- Tapioca starch supply volatility:Southeast Asian weather patterns and cassava harvest variability create input cost instability for modified starch producers.
- GRAS self-determination complexity:FDA's lack of affirmative approval for novel hydrocolloid sources generates liability exposure deterring smaller suppliers from US market entry.
- Protein thickener performance ceiling:Egg and dairy protein systems fail to match hydrocolloid viscosity stability across pH and temperature ranges, limiting clean-label substitution potential.
Strategic Opportunities
- FSSAI BIS compliance services:Indian institutional food manufacturers require imported gum and starch certification support, creating advisory and testing revenue streams.
- Cell-cultured meat suspension systems:Emerging scaffolding and texture requirements in alternative protein applications demand novel hydrocolloid functionality.
- EU Green Deal bioeconomy incentives:Agricultural residue valorization programs subsidize pectin and cellulose extraction from fruit processing waste streams.
Industry Challenges
- Clean-label definition divergence:Retailers, regulators, and consumer panels apply inconsistent "natural" and "recognizable ingredient" standards across jurisdictions, forcing multiple formulation tracks.
- Legacy equipment retrofit costs:Transitioning from traditional starch hydration to cold-soluble gum systems requires capital expenditure in mixing and dispersion infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Thickening Agents Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch, Gelatin, Pectin, Xanthan Gum Application: Dairy Products, Sauces, Soups, Salad Dressings Form: Powder, Liquid, Granules, Tablets End User: Food Manufacturers, Restaurants, Catering Services, Bakeries |
| Companies Covered | Tate & Lyle PLC, Kerry Group plc, Cargill, Incorporated, Ashland, DuPont de Nemours, Inc., Archer Daniels Midland Company, CP Kelco, International Flavors & Fragrances, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Thickening Agents Market Emerging Trajectories
Formulation science is pivoting from single-ingredient functionality to synergistic hydrocolloid blends that deliver clean-label declarations while maintaining process tolerance.
Fermentation-derived hydrocolloids are expanding into mainstream dairy alternatives. Precision fermentation platforms now yield gellan gum and curdlan at commercial scale. Oat milk and coconut yogurt manufacturers are adopting these systems for suspension stability without "chemical-sounding" additives. This technology is expanding into cost-competitive positioning against extraction-based alternatives.
REACH registration requirements for polymer additives are tightening purity specifications for xanthan gum imports into European commerce. ECHA substance evaluation protocols now demand residual solvent and protein allergen documentation. Salad dressing and sauce manufacturers sourcing Asian fermentation capacity are restructuring supplier qualification programs to preempt authorization delays.
Direct supplier relationships are displacing distributor intermediaries among mid-sized food manufacturers. Purchasing departments now engage hydrocolloid refiners for technical service and custom blending. Germany and the United States exhibit the most advanced procurement transformation, with dairy processors embedding formulation scientists at supplier technical centers.
Food Thickening Agents Market Segmentation
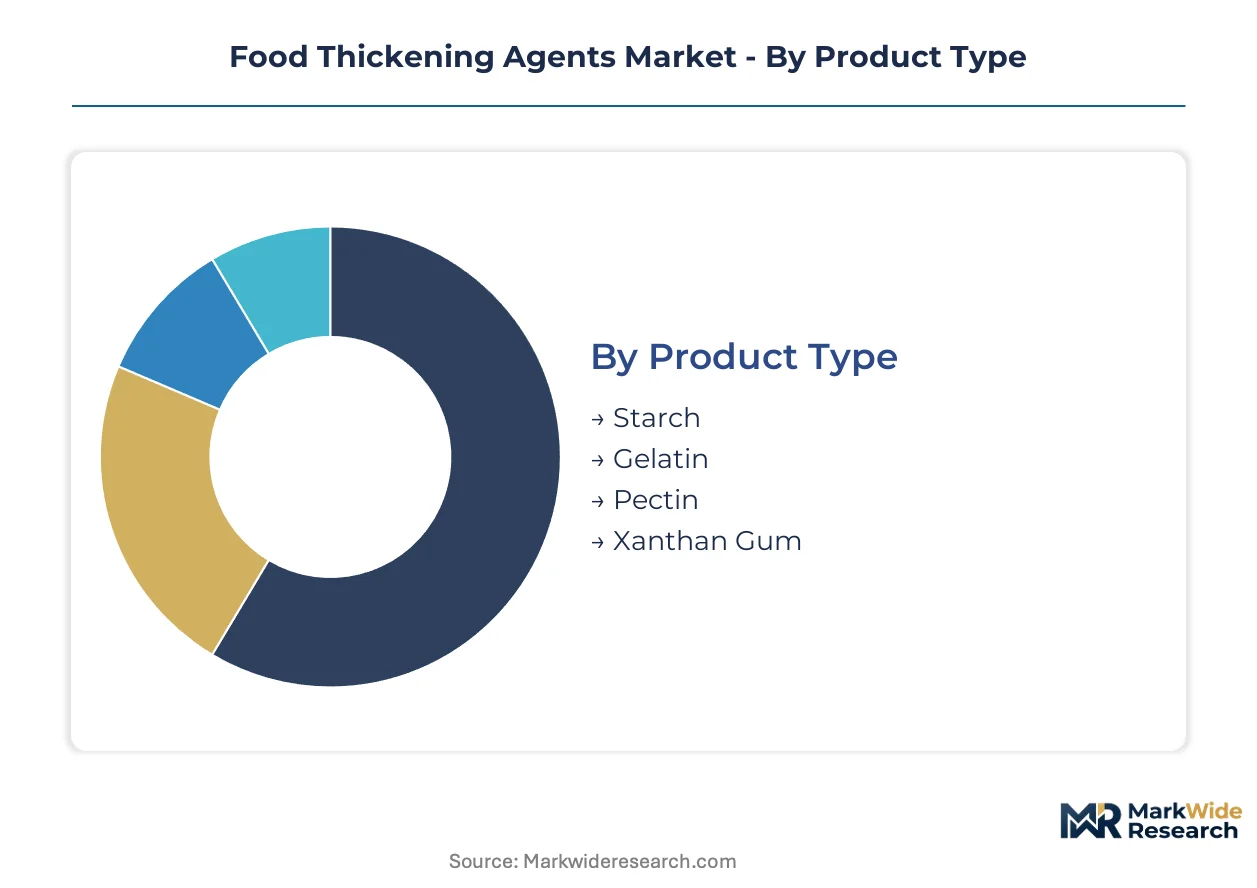
Thickening agent selection determines formulation architecture across processed food matrices. Manufacturers balance standalone hydrocolloid performance against integrated multi-ingredient systems based on process equipment, label requirements, and cost targets.
Product Type:
Starch dominates standalone applications where simple hydration suffices; gums and pectins embed into complex stabilizer blends for demanding rheology profiles.
- Starch:Modified and native corn, tapioca, and potato starches deliver cost-efficient viscosity through granular swelling and amylose leaching. Sauces and soups in the United States and Germany absorb the largest volumes where price sensitivity outweighs premium positioning. FDA GRAS status and EFSA food additive approvals accelerate procurement cycles for standard grades.
- Xanthan Gum:Fermentation-derived extracellular polysaccharide exhibits pronounced shear-thinning and freeze-thaw stability. Salad dressing manufacturers in Japan specify xanthan for cold-chain distribution networks where viscosity recovery after pouring is essential. ECHA REACH registration requirements now demand residual solvent documentation for European imports.
- Pectin:Citrus and apple-derived galacturonan extracted under acidic conditions. Clean-label dairy alternatives favor high-methoxyl grades.
- Gelatin:Collagen hydrolysate from bovine and porcine sources provides thermoreversible gelation. Confectionery and dairy desserts remain primary outlets.
Starch leads volumes today; pectin is gaining share fastest.
Application:
Cost tier stratification separates commodity texture modification from premium mouthfeel engineering.
- Dairy Products:Yogurt, ice cream, and plant-based milk alternatives require suspension stability and creaminess modulation. Pectin and starch blends dominate European clean-label reformulations as EFSA novel food assessments push manufacturers toward established hydrocolloid sources. German dairy processors embed formulation scientists at supplier technical centers.
- Sauces:Tomato, cream, and ethnic sauce categories prioritize pour viscosity and cling. Modified starches anchor mid-tier positioning; xanthan-guar synergies command premium segments.
- Soups:Canned and retorted applications demand thermal stability across sterilization cycles. Cross-linked starches prevent breakdown.
- Salad Dressings:Emulsion stability and shelf-life consistency drive hydrocolloid selection. Pourable and spoonable textures require distinct rheology profiles.
Dairy Products anchor revenue concentration; Salad Dressings show steepest expansion trajectory.
Form:
Supply concentration in powder processing creates margin pressure for liquid and tablet specialists.
- Powder:Spray-dried and agglomerated grades dominate bulk ingredient flows. Standardized particle size distributions ensure dispersion uniformity in high-shear mixing environments.
- Liquid:Pre-hydrated gum dispersions eliminate dusting and reduce batch cycle times. United States beverage manufacturers adopt liquid pectin for streamlined continuous processing.
- Granules:Intermediate particle size bridges powder flowability and liquid handling efficiency. Intermediate moisture content reduces caking susceptibility.
- Tablets:Unit-dose formats serve institutional catering and small-batch restaurant applications. Precise weighing elimination reduces operator error.
Powder leads volumes today; Liquid is gaining share fastest.
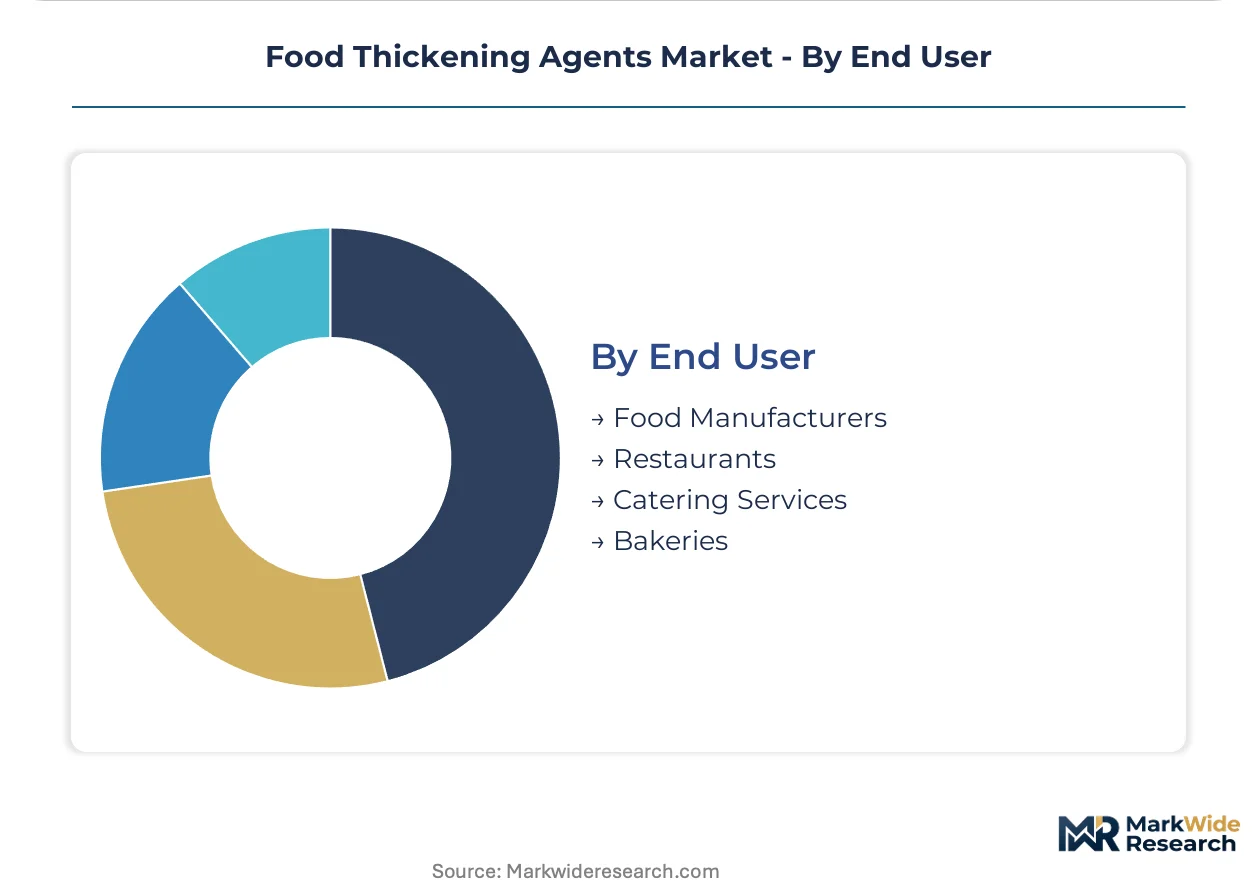
End User:
Customer type determines technical service intensity and contract structure.
- Food Manufacturers:Large-scale processors specify custom hydrocolloid blends with embedded formulation support. Direct supplier relationships displace distributor channels as procurement departments engage refiners for technical collaboration.
- Restaurants:Chain operators standardize texture profiles across locations through pre-mixed thickening systems. Consistency requirements override ingredient cost minimization.
- Catering Services:Volume volatility and menu diversity favor flexible procurement arrangements. Powder concentrates enable on-site reconstitution.
- Bakeries:Fillings, glazes, and cream systems require specific gelation temperatures. Pectin and modified starch combinations predominate in fruit preparations.
Food Manufacturers lead volumes today; Restaurants are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hydrocolloid refiners command premium positioning through clean-label partnerships, while the United States absorbs larger starch volumes in cost-sensitive sauce applications. Japan sustains specialized demand for freeze-thaw stable systems in prepared meals. India and Brazil represent emerging procurement complexity as regulatory frameworks mature.
United States
Salad dressing manufacturers specify xanthan gum for cold-chain distribution networks requiring viscosity recovery after pouring. FDA GRAS self-determination pathways accelerate standard hydrocolloid procurement cycles. Chicago and Minneapolis processing clusters embed formulation scientists at supplier technical centers for custom blending collaboration.
Germany
Dairy processors reformulate around high-methoxyl pectin for clean-label yogurt and plant-based milk alternatives. EFSA novel food assessments push manufacturers toward established hydrocolloid sources with consumption histories. Bavarian and North Rhine-Westphalia food innovation hubs sustain direct supplier relationships displacing traditional distributor channels.
Japan
METI-supported food innovation programs sustain institutional demand for texture-engineered products targeting aging-population nutrition segments. Prepared meal manufacturers specify modified starch systems for extended cold-chain distribution. Kanto and Kansai metropolitan clusters concentrate hydrocolloid technical service capabilities.
India
FSSAI BIS standards on imported gum and starch specifications create compliance friction for suppliers targeting institutional food manufacturers. Domestic dairy processors expand pectin adoption in clean-label formulations. Maharashtra and Gujarat industrial corridors attract certification advisory and testing service providers.
Brazil
ANVISA regulatory alignment with international food additive standards accelerates hydrocolloid import qualification timelines. Processed sauce and soup manufacturers balance cost efficiency against label recognition requirements. São Paulo state anchors South American formulation technical service concentration.
Food Thickening Agents Market Vendor Landscape
North American producers anchor one tier through integrated corn and tapioca supply chains; European specialists hold premium positioning via clean-label hydrocolloid purification capabilities. The vendor base organizes around three archetypes: agricultural commodity processors controlling upstream starch flows, fermentation-platform operators yielding consistent biopolymer grades, and formulation-service integrators embedding technical scientists at customer R&D centers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with direct supplier relationships displacing distributor intermediaries among mid-scale food manufacturers.
Within the integrated agricultural processor tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify supply chain control strategies. Kerry Group plc occupies a position among formulation-service specialists embedding technical collaboration capabilities. These entities represent divergent competitive vectors: upstream raw material security versus downstream application expertise.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Kerry Group plc |
| Cargill, Incorporated |
| Ashland |
| DuPont de Nemours, Inc. |
| Archer Daniels Midland Company |
| CP Kelco |
| International Flavors & Fragrances |
| Ingredion Incorporated |
| Others |
Supply Flow & Price Mechanics
Fermentation scientists concentrated in the Kanto region of Japan command wage premiums that propagate through xanthan gum cost structures, widening spreads between commodity starch grades and precision-fermentation hydrocolloids across global procurement tiers.
Pricing Analysis
Capacity additions in Thailand and Vietnam are reshaping price floors for tapioca-derived modified starches as Southeast Asian processors expand wet-milling infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates cold-soluble gum systems from cross-linked starches and native granular grades. Price differentiation hinges on EFSA novel food certification status and minimum order volumes. Cost compression in standard starch tiers is intensifying because Brazilian corn ethanol diversion tightens feedstock availability. Quick-service restaurant chains exhibit highest price sensitivity; pharmaceutical texture applications show least.
Supply Chain Analysis
Cassava root supply rests on Thai, Vietnamese, and Indonesian agricultural harvest cycles with monsoon-dependent yield variability. Key inputs include corn and tapioca starch feedstocks, fermentation nutrients for biopolymer platforms, and citrus peel waste streams for pectin extraction. Single-source vulnerability concentrates in xanthan gum fermentation capacity anchored in Chinese and Japanese bioreactor networks. Distribution runs through direct supplier relationships displacing traditional distributor channels among mid-scale dairy and sauce manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
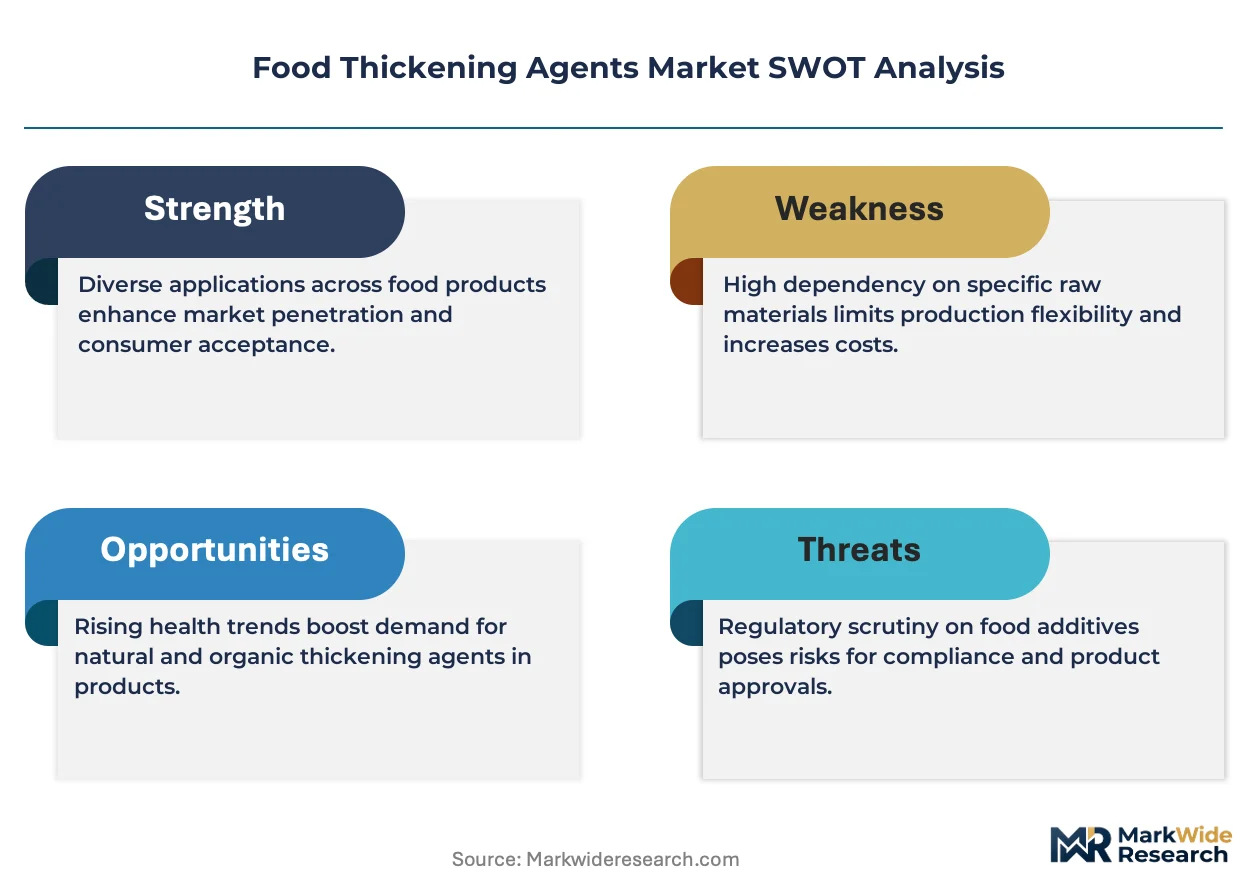
Food Thickening Agents Market functions as a stable compounder where clean-label regulatory pressure sustains steady reformulation demand across dairy, beverage, and prepared meal categories.
For Market Incumbents: Acquire fermentation-platform operators to secure consistent biopolymer supply as EFSA novel food assessments accelerate preference for clinically validated hydrocolloid sources. Build captive pectin extraction capacity in Southern European citrus processing zones to control clean-label input costs. Threat substitution from protein-based thickeners with inferior pH stability demands defensive patent positioning in synergistic gum-starch blends.
For New Entrants and Emerging Players: Small-batch craft sauce manufacturers in the United States represent an underserved buyer archetype requiring flexible minimum order quantities and embedded formulation support. White-space concentration sits in FSSAI BIS compliance advisory services for Indian institutional food manufacturers navigating imported gum certification friction. Precision-fermentation curdlan for oat milk suspension systems offers the most penetrable application entry point. Go-to-market execution should leverage liquid pre-hydrated gum dispersions eliminating customer capital expenditure in mixing infrastructure.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional starch processors lacking clean-label hydrocolloid purification capabilities. Five-to-ten year viability framing favors fermentation-platform operators with established pharmaceutical-grade certification and multi-jurisdictional regulatory dossiers. Acquisition target archetype: European pectin refiners with EU Green Deal bioeconomy subsidy access and fruit processing waste stream partnerships. Signal to watch: FSSAI enforcement intensity on imported gum specifications as proxy for Indian market formalization pace.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cassava Cultivation | Cargill and ADM secure Thai and Vietnamese acreage to buffer tapioca starch cost volatility from monsoon disruption. |
| Precision Fermentation Scale-Up | CP Kelco expands Kanto bioreactor capacity for gellan gum yielding cost parity with extraction-based alternatives. |
| Clean-Label Certification Investment | Kerry Group secures EFSA novel food pre-approvals for citrus pectin accelerating European dairy processor procurement cycles. |
| Direct Supplier Relationship Programs | Ingredion embeds formulation scientists at Minneapolis dairy technical centers displacing distributor intermediaries. |
| Agricultural Residue Valorization Partnership | Tate & Lyle leverages EU Green Deal subsidies for cellulose extraction from European fruit processing waste streams. |
Methodological Framework
Direct dialogue with hydrocolloid refinery technical directors, dairy processor formulation scientists, FSSAI compliance consultants, and salad dressing procurement managers grounded qualitative assessment. Secondary validation drew from FDA GRAS notices, EFSA novel food opinions, BIS starch specifications, and SEC 10-K disclosures from agricultural processors. Bottom-up volume modeling triangulated against top-down category expenditure analysis.
Top-down market sizing anchored in processed food production indices across the analysis window, segmented by hydrocolloid type, application matrix, and end-user procurement archetype. Modeled dimensions included starch versus gum versus protein thickener classes; dairy, sauce, soup, and dressing applications; and food manufacturer versus foodservice channel splits. CAGRs derived from regression against historical price-volume elasticities and regulatory event timelines. Forecast inputs incorporated EFSA assessment queue depths and METI food innovation program funding trajectories.
Underlying measurement precision varies by segment; established GRAS-affirmed starch categories carry tighter precision than novel fermentation-derived hydrocolloids pending regulatory authorization. Forecasts reflect assumptions on clean-label definition convergence and cassava harvest stability. Supply disruption from Southeast Asian weather volatility, FDA enforcement shifts on self-affirmed GRAS, and EU Green Deal subsidy modifications warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Gut Modifiers Market
Food Enhancers and Additives
Natural Taste Enhancers and Modifiers Market
Food Enhancers and Additives
Kaempferol Market
Food Enhancers and Additives
Germany Food Flavor and Enhancer Market
Food Enhancers and Additives
North America Vinegar Market
Food Enhancers and Additives
Asia-Pacific Food Flavor and Enhancer Market
Food Enhancers and Additives
Europe Feed Palatability Enhancers Market
Food Enhancers and Additives
Dysphagia Diet Thickening Agents Market
Food Enhancers and Additives
Italy Anti-Caking Market
Food Enhancers and Additives
Fortified Salts Market
Food Enhancers and Additives
Flour Improvers Market
Food Enhancers and Additives
Dough Conditioners Market
Food Enhancers and Additives
Germany Water Enhancer Market
Food Enhancers and Additives
Asia-Pacific Flavor Enhancer Market
Food Enhancers and Additives
High Ratio Shortening Market
Food Enhancers and Additives
North America Food Flavor and Enhancer Market